
 Helideck Monitoring System Market | 2026-2036
Helideck Monitoring System Market Size, Share, and Industry Trends Forecast 2026-2036
Helideck Monitoring System Market Analysis
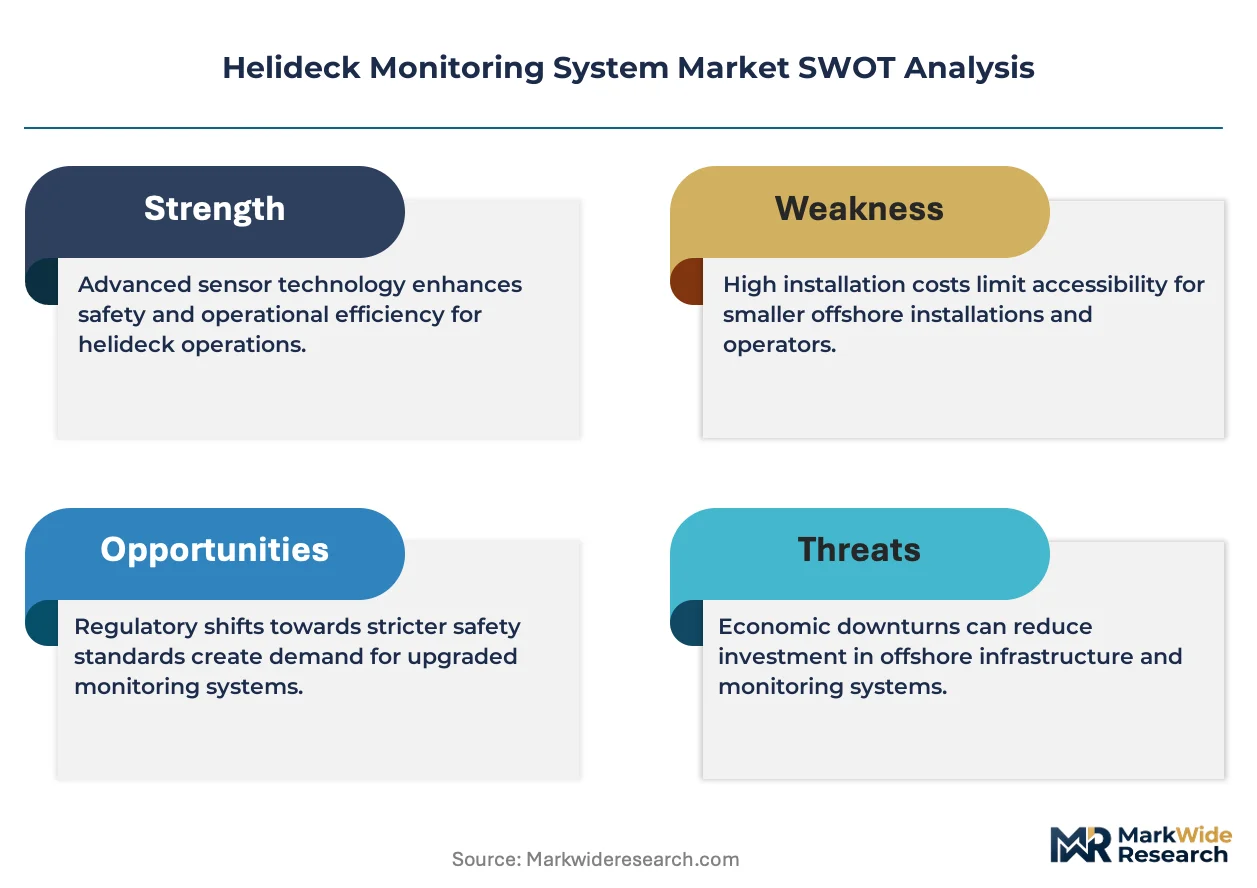
CAP 437 is shifting compliance thresholds for offshore helideck operations across the North Sea, forcing operators to upgrade legacy visual-only systems to integrated meteorological and motion-monitoring suites. Kongsberg Gruppen anchors its position through captive supply of wave radar and helideck motion sensors purpose-built for harsh-environment platforms. Fugro differentiates by combining helideck monitoring with its broader offshore survey and positioning services, creating bundled procurement appeal for integrated energy clients. ABB leverages its power and automation installed base to cross-sell monitoring systems into existing offshore electrical infrastructure contracts.
A helideck monitoring system comprises integrated sensor arrays, processing units, and display interfaces that measure wind velocity, air temperature, barometric pressure, helideck motion, and obstacle proximity to determine safe helicopter landing conditions on marine structures. These systems typically incorporate radar-based wave height sensors, high-resolution cameras with automated object detection, and networked anemometers sampling at one-second intervals to deliver real-time go/no-go recommendations to pilots and platform managers. Sensor Network deployments dominate retrofit opportunities on aging offshore platforms where fiber backbone infrastructure already exists, while Data Analytics capabilities represent the fastest-expanding margin pool as operators seek predictive maintenance integration and automated reporting for regulatory audits. Permanent Installation configurations sustain the largest revenue base across greenfield oil rig developments, though Modular Systems are gaining traction in research vessel applications where deck configurations change between scientific missions.
The UK Civil Aviation Authority enforces CAP 437 helideck standards that mandate continuous meteorological monitoring and periodic friction testing, directly shaping product specifications and certification requirements for equipment suppliers. Norway's Petroleum Safety Authority and Brazil's national civil aviation regulator apply parallel but non-identical standards, creating fragmented compliance landscapes that favor suppliers with multi-certification capabilities. Stakeholders must monitor evolving unmanned aerial vehicle integration rules and their potential convergence with manned helicopter safety frameworks, as this intersection could redefine sensor requirements and data architecture for marine landing platforms.
Market Dynamics
Offshore platform operators face simultaneous pressure from regulatory tightening and sensor-network obsolescence, forcing wholesale replacement of legacy visual monitoring with integrated meteorological-motion suites.
Growth Catalysts
- CAP 437 Revision:The UK Civil Aviation Authority's updated standard mandates continuous meteorological monitoring and real-time helideck motion reporting, compelling North Sea operators to upgrade installed bases.
- Sensor Network Retrofits:Aging platforms in Norway and Brazil leverage existing fiber backbone infrastructure to deploy networked anemometer and wave radar arrays without full platform shutdown.
- Offshore Wind Expansion:Floating wind installation vessels require modular helideck monitoring systems that reconfigure between construction and maintenance phases.
Market Restraints
- Certification Fragmentation:Parallel but non-identical standards from Norway's Petroleum Safety Authority, Brazil's ANAC, and the UK CAA force suppliers to maintain multiple certification streams, inflating development overhead.
- Specialized Component Supply:Harsh-environment wave radar and motion sensors rely on concentrated supply from Nordic marine electronics specialists, creating single-source vulnerability.
- Platform Lifecycle Mismatch:Twenty-year platform design horizons clash with seven-year sensor obsolescence cycles, straining capital allocation for mid-life monitoring upgrades.
Strategic Opportunities
- Predictive Maintenance Integration:Data analytics capabilities that correlate helideck motion patterns with structural fatigue offer new recurring revenue streams for monitoring system vendors.
- Unmanned Platform Convergence:Evolving UAV integration rules at the UK CAA and EASA may converge with manned helicopter frameworks, expanding sensor requirements for hybrid landing zones.
- Research Vessel Modularization:Scientific fleet operators in Germany and Japan seek rapidly reconfigurable monitoring systems that adapt to changing deck geometries between oceanographic missions.
Industry Challenges
- Marine Electronics Integration:Platform control systems built on proprietary 1990s architectures resist seamless integration with IP-based sensor networks, requiring costly middleware development.
- Calibration Specialist Scarcity:One-second-interval anemometer certification and wave radar validation demand technicians with combined aviation and offshore survival qualifications, tightening field service capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Helideck Monitoring System Market |
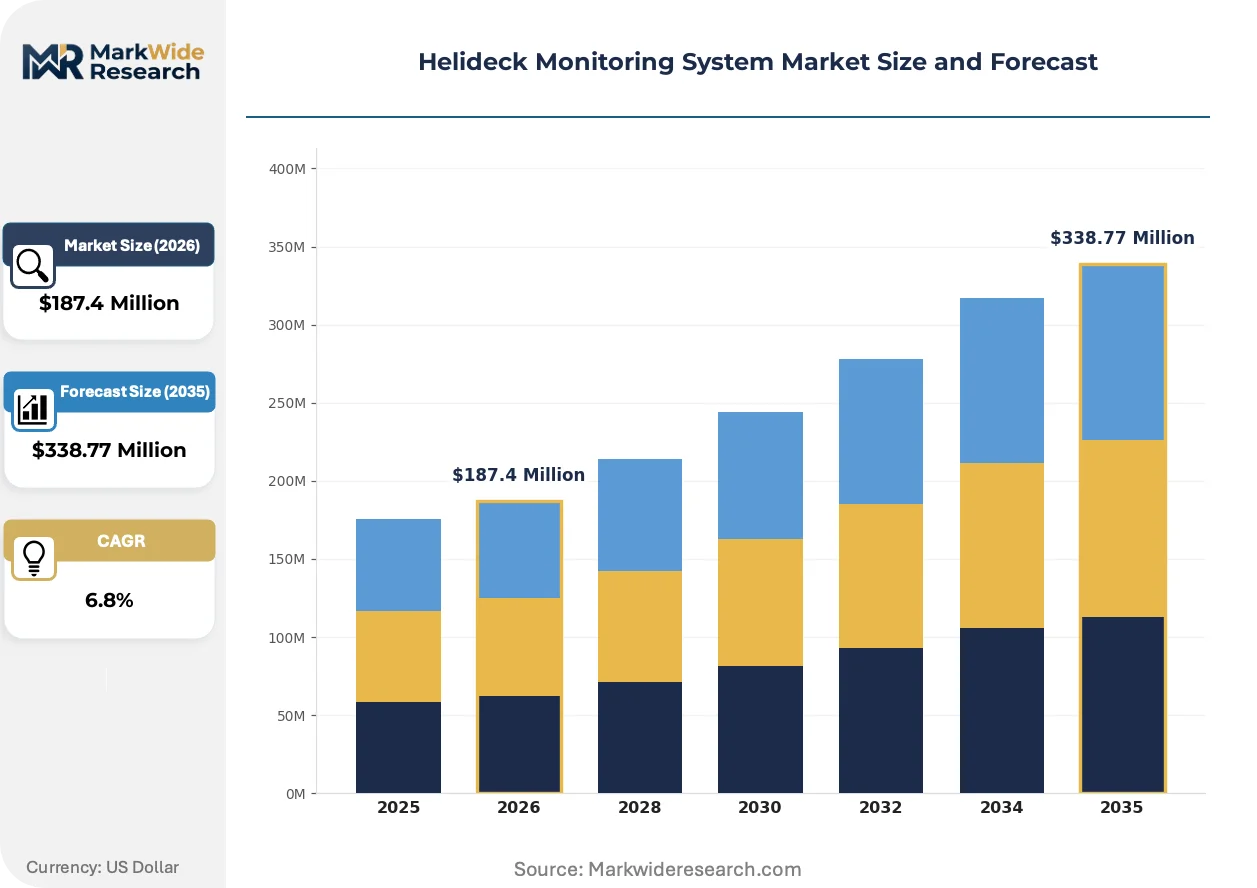
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Radar System, Camera System, Sensor Network, Data Analytics Application: Offshore Platforms, Oil Rigs, Research Vessels, Cargo Ships End User: Energy Sector, Shipping Industry, Government Agencies, Private Operators Installation Type: Permanent Installation, Temporary Installation, Retrofit Solutions, Modular Systems |
| Companies Covered | ABB, Fugro, Kongsberg Gruppen, ASB Systems, AWA Marine, Monitor Systems, Observator Group, Automasjon og Data AS, Miros Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Helideck Monitoring System Market Emerging Trajectories
Edge computing architectures are redistributing processing load from centralized platform servers to sensor-mounted units, cutting latency for pilot go/no-go decisions while complicating cybersecurity protocols.
Millimeter-wave radar is decentralizing wave height measurement by embedding processing directly into marine-rated sensor housings, eliminating dependency on platform server rooms. Offshore operators in the UK and Norway are retrofitting these units onto aging platforms where fiber runs to central processing bays would require shutdown windows. This topology compresses installation timelines from weeks to days while fragmenting vendor service relationships across multiple edge device suppliers.
REACH restrictions on perfluorinated compounds are forcing redesign of marine sensor housings and cable insulation, accelerating material substitution programs across European supply chains. Equipment suppliers must reformulate IP67-rated enclosures without legacy waterproofing chemistries, extending certification timelines by twelve to eighteen months. The F-Gas Regulation's parallel phase-down of high-GWP refrigerants in climate-controlled electronics shelters adds secondary compliance pressure for North Sea deployments.
Integrated service contracts are displacing discrete equipment procurement as major offshore operators bundle helideck monitoring with broader marine assurance packages. Energy majors in Brazil and Norway now specify outcome-based availability guarantees rather than capital equipment purchases, transferring operational risk to monitoring vendors. This compression of vendor-customer relationships favors suppliers with captive maintenance networks over pure equipment manufacturers.
Helideck Monitoring System Market Segmentation
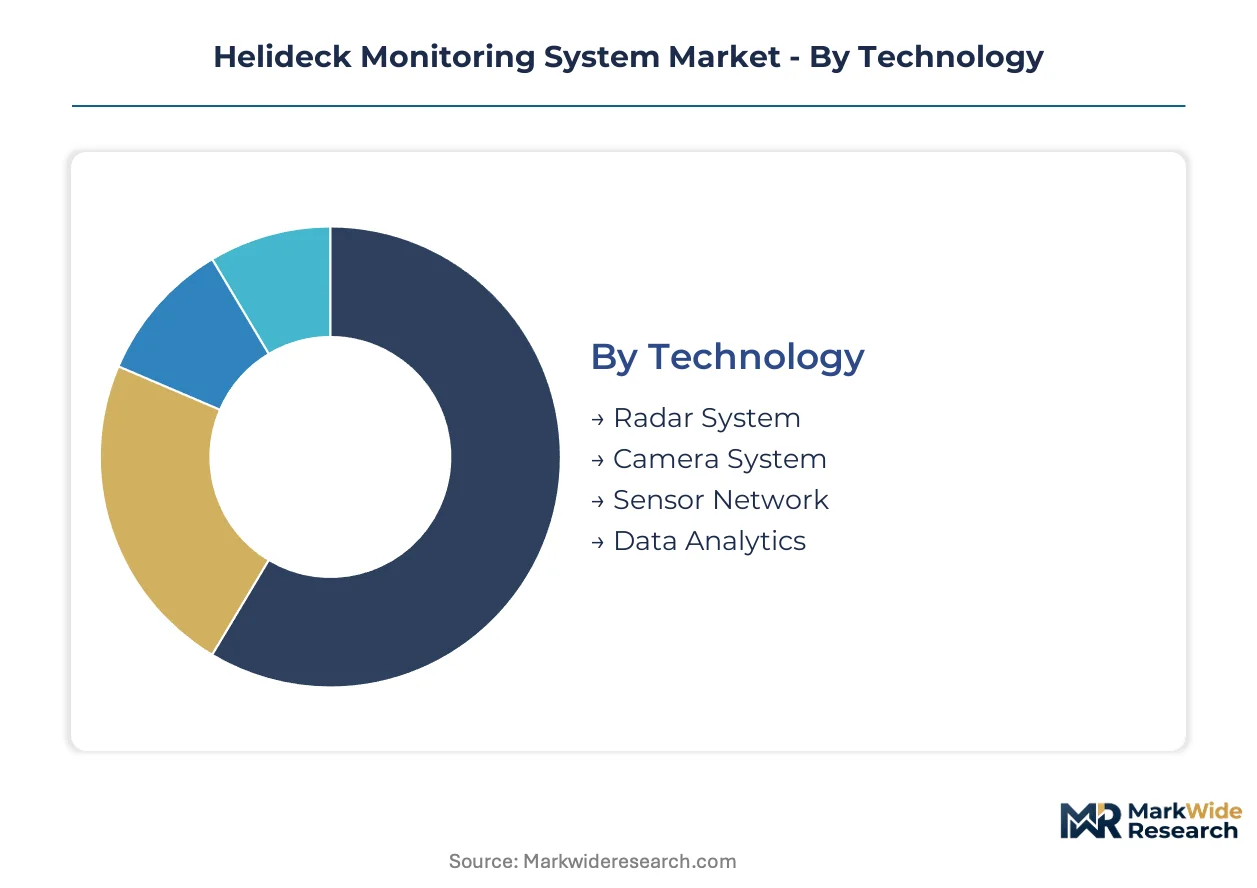
Helideck monitoring procurement splits sharply between integrated platform-wide suites and standalone sensor deployments. Technology choices determine installation complexity, while end-user sector dictates compliance stringency and service contract structures.
Technology:
Integration depth varies from standalone perimeter devices to platform-embedded processing architectures.
- Radar System:Millimeter-wave units embed wave height processing directly into marine-rated housings, eliminating fiber runs to central servers. Norwegian operators retrofit these onto aging North Sea platforms where shutdown windows are prohibitively expensive.
- Sensor Network:Networked anemometer arrays sampling at one-second intervals dominate retrofit opportunities where fiber backbone infrastructure already exists. Brazil's pre-salt basin operators leverage existing cabling to deploy frictionless friction-monitoring nodes without platform shutdown.
- Camera System:High-resolution units with automated object detection provide visual confirmation for pilot go/no-go decisions.
- Data Analytics:Predictive maintenance modules correlate helideck motion patterns with structural fatigue indicators.
Volume placements concentrate in Sensor Network deployments; the faster expansion belongs to Data Analytics capabilities as operators seek automated regulatory audit trails.
Application:
Cost tier separation runs from capital-intensive permanent infrastructure to reconfigurable vessel-mounted systems.
- Offshore Platforms:Fixed installations require continuous meteorological and motion monitoring under CAP 437 mandates. UK North Sea operators face wholesale replacement cycles as legacy visual-only systems fail compliance thresholds.
- Research Vessels:Modular configurations adapt to changing deck geometries between oceanographic missions. German and Japanese scientific fleet operators specify rapid reconfiguration protocols for multi-mission vessels.
- Oil Rigs:Greenfield developments specify integrated suites from construction phase.
- Cargo Ships:Limited helideck utilization drives minimal sensor deployment.
Revenue concentration sits with Offshore Platforms; Research Vessels are climbing the fastest as floating wind installation fleets expand.
End User:
Customer type determines procurement modality, from outcome-based service contracts to discrete capital equipment purchases.
- Energy Sector:Oil majors and offshore wind developers specify availability guarantees rather than equipment purchases, transferring operational risk to monitoring vendors. Norway and Brazil energy majors now bundle helideck monitoring with broader marine assurance packages.
- Government Agencies:National civil aviation regulators and coast guard operators mandate certified systems for search-and-rescue infrastructure.
- Shipping Industry:Container and tanker operators deploy minimal compliant configurations for occasional helicopter logistics.
- Private Operators:Independent platform owners face capital constraints on mid-life monitoring upgrades.
Contract value concentrates in Energy Sector accounts; Government Agencies show steepest expansion trajectory as coastal surveillance programs modernize.
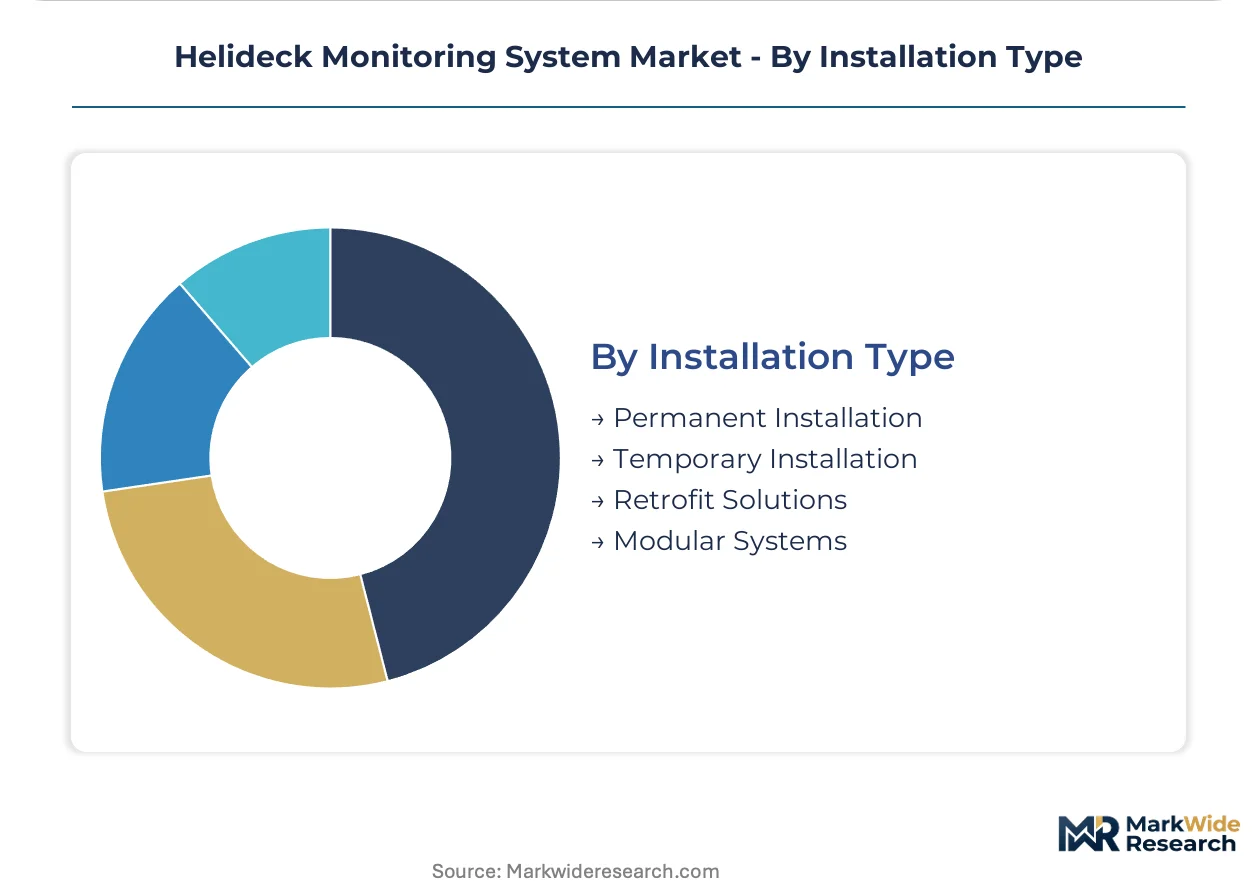
Installation Type:
Maturity gradients separate legacy retrofit demand from greenfield permanent specifications.
- Permanent Installation:Hardwired configurations sustain the largest revenue base across new-build oil rig developments. Integrated processing bays and dedicated server rooms characterize these capital-intensive deployments.
- Modular Systems:Rapidly deployable units gain traction where deck configurations change between operational phases. Floating wind installation vessels require systems that reconfigure between construction and maintenance cycles.
- Retrofit Solutions:Sensor overlays on aging platforms leverage existing infrastructure where possible.
- Temporary Installation:Short-term deployments serve exploration campaigns and emergency response.
Installed base volume sits with Permanent Installation; Modular Systems are gaining share fastest as vessel specialization intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
North Sea special economic zones for offshore energy development concentrate procurement of integrated helideck monitoring suites, with regulatory harmonization efforts across maritime boundaries creating cross-border installation demand.
United Kingdom
North Sea oil and gas operators face wholesale replacement cycles as legacy visual-only systems fail CAP 437 compliance thresholds. The UK Civil Aviation Authority mandates continuous meteorological monitoring and real-time helideck motion reporting. Aberdeen's offshore engineering cluster anchors retrofit demand as aging platforms upgrade sensor networks.
Norway
Pre-salt basin developments and mature North Sea fields drive sensor-network retrofit installations on aging platforms. The Petroleum Safety Authority applies parallel but non-identical standards to UK CAP 437, creating multi-certification requirements. Stavanger's marine electronics specialists concentrate supply of harsh-environment wave radar units.
Brazil
Deepwater pre-salt expansion accelerates demand for networked anemometer arrays on floating production platforms. ANAC helideck certification rules shape local procurement specifications for equipment suppliers. Rio de Janeiro's offshore engineering hub coordinates installation of friction-monitoring nodes without platform shutdown.
Germany
Research vessel operators in the scientific fleet specify rapidly reconfigurable monitoring systems for multi-mission oceanographic operations. REACH restrictions on perfluorinated compounds force redesign of marine sensor housings across European supply chains. Hamburg's maritime technology cluster develops modular configurations adapting to changing deck geometries.
Japan
Floating wind installation vessels require modular helideck monitoring systems reconfiguring between construction and maintenance phases. METI offshore renewable energy programs shape procurement standards for hybrid marine platforms. Yokohama's shipbuilding district integrates monitoring suites into specialized construction vessel newbuilds.
Helideck Monitoring System Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across procurement modalities from capital equipment sales to outcome-based service contracts. Market structure tilts toward consolidation as energy majors bundle helideck monitoring with broader marine assurance packages. Three archetypes dominate: diversified industrial groups leveraging installed base cross-selling, marine survey specialists integrating monitoring with positioning services, and pure-play sensor manufacturers with captive harsh-environment expertise. Dominant competitive moves include backward integration into specialized component supply and geographic expansion through certification stacking.
Within the diversified industrial tier, ABB leverages its power and automation installed base to cross-sell monitoring systems into existing offshore electrical infrastructure contracts. Kongsberg Gruppen anchors the marine electronics specialist segment through captive supply of wave radar and helideck motion sensors purpose-built for harsh-environment platforms. Fugro occupies a position exemplifying the integrated service model by combining helideck monitoring with broader offshore survey and positioning capabilities.
| Leading Market Players |
|---|
| ABB |
| Fugro |
| Kongsberg Gruppen |
| ASB Systems |
| AWA Marine |
| Monitor Systems |
| Observator Group |
| Automasjon og Data AS |
| Miros Group |
| Others |
Supply Flow & Price Mechanics
Millimeter-wave radar decentralization is compressing installation timelines from weeks to days while fragmenting vendor service relationships, simultaneously reducing upfront capital costs and dispersing pricing power across multiple edge device suppliers. This topology shift rewards suppliers with captive calibration networks while squeezing margins for pure hardware manufacturers.
Pricing Analysis
Short lead-time premiums command substantial markups as North Sea operators face CAP 437 compliance deadlines with limited shutdown windows. Pricing stratifies across certification tiers, with multi-standard systems carrying material premiums over UK-only configurations. Cost compression in economy-tier sensor networks is intensifying because Brazilian and Norwegian operators leverage existing fiber infrastructure for frictionless retrofits. Private platform operators exhibit acute price sensitivity, while energy majors prioritize availability guarantees over capital expenditure minimization.
Supply Chain Analysis
Refurbishment flows for wave radar units and motion sensors extend component lifecycles on aging North Sea platforms where new procurement faces extended certification timelines. Supply concentrates in Norway, the United Kingdom, and Germany, with Stavanger's marine electronics specialists and Hamburg's maritime technology cluster anchoring harsh-environment component production. Harsh-environment sensor housings draw from Nordic specialty polymer suppliers facing REACH restriction pressures. Single-source vulnerability concentrates in millimeter-wave radar modules. Distribution runs through integrated service contractors bundling monitoring with broader marine assurance packages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Calibration specialist scarcity props pricing across all tiers, as technicians combining aviation and offshore survival qualifications remain capacity-constrained relative to retrofit demand.
For Market Incumbents: Anticipate certification stacking requirements as Norway's Petroleum Safety Authority and Brazil's ANAC diverge from UK CAP 437 standards. Defensive consolidation should prioritize captive supply of wave radar modules and motion sensors to offset Nordic component concentration risk. Backward integration into edge computing architectures protects margin pools as processing load decentralizes from platform servers.
For New Entrants and Emerging Players: The premium-to-economy price gap in research vessel modular systems offers white-space entry, as German and Japanese scientific fleet operators seek rapidly reconfigurable configurations. Target floating wind installation vessels requiring systems that adapt between construction and maintenance phases. Partner with established marine electronics distributors to bypass direct certification burden.
For Investors and Strategic Acquirers: Re-rating potential sits with integrated service providers given outcome-based contract displacement of discrete equipment procurement. Long-term viability favors vendors with captive maintenance networks over pure manufacturers. Watch UAV integration rule convergence at EASA and UK CAA as inflection signal for expanded sensor requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Certification Stacking Investment | Multi-standard capabilities unlock Norway and Brazil procurement alongside UK CAP 437 compliance. |
| Edge Computing Architecture Deployment | Sensor-mounted processing units cut latency while complicating cybersecurity protocols for platform operators. |
| Calibration Network Expansion | Technician capacity constraints in combined aviation-offshore qualifications tighten field service availability. |
| Modular System Development | Rapid reconfiguration protocols capture research vessel and floating wind installation vessel demand. |
| Predictive Maintenance Integration | Data analytics correlating helideck motion with structural fatigue creates recurring revenue streams. |
Methodological Framework
Multi-period observation of CAP 437 compliance timelines, sensor obsolescence cycles, and retrofit installation rates anchored the trend analysis, supplemented by interviews with offshore platform managers, marine electronics procurement leads, aviation safety regulators, and helideck calibration technicians. Secondary validation drew from UK CAA regulatory filings, Norway Petroleum Safety Authority standards documentation, ANAC certification records, and offshore engineering project databases. Bottom-up platform inventory analysis triangulated against top-down energy sector capital expenditure tracking.
Input-output matrix modeling connected sensor deployment volumes to platform age profiles, regulatory enforcement intensity, and fiber infrastructure availability across the projection horizon. Segmentation dimensions included technology integration depth, installation type maturity, and end-user procurement modality. CAGRs derived from fitted growth curves applied to disclosed retrofit timelines and greenfield development pipelines, with wave radar unit shipments and anemometer array installations serving as primary volume indicators.
Inputs from regulatory filing databases and offshore project tracking services were available through the study window; gaps in real-time platform operator budget allocation introduce uncertainty bands around near-term retrofit timing assumptions. Forecasts reflect documented enforcement schedules and disclosed platform decommissioning timelines. Material deviation in CAP 437 inspection intensity or REACH restriction implementation pace warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Technologies
Airport Smart Lighting Market
Airport Technologies
Airport Information Systems Market
Airport Technologies
North America Airport Baggage Handling Systems Market
Airport Technologies
Bird Detection System for Airports Market
Airport Technologies
Global Airport Baggage Handling System Market
Airport Technologies
Asia-Pacific Smart Airport Market
Airport Technologies
Airport Information Display System Market
Airport Technologies
Smart Baggage Handling System Market
Airport Technologies
Middle-East and Africa Airport Baggage Handling Systems Market
Airport Technologies
America Airport Ground Handling Systems Market
Airport Technologies
Europe Airport Ground Handling Systems Market
Airport Technologies
Airport Cargo Community Digital Collaboration Platforms Market
Airport Technologies
Airport Runway Foreign Object Debris (FOD) Detection Systems Market
Airport Technologies
Air Traffic Smart Tower Solutions Market
Airport Technologies
Commercial Airport Baggage Handling Systems Market
Airport Technologies
Europe Smart Airport Market