
 Satellite Antenna Market | 2026-2036
Satellite Antenna Market Size, Share, and Industry Trends Forecast 2026-2036
Satellite Antenna Market Intelligence
Software-defined beamforming is recalibrating how satellite antenna value gets captured, shifting revenue from hardware sales to recurring capability upgrades. Mitsubishi Electric Corporation leverages its precision manufacturing heritage to dominate high-frequency Ka-band ground segments. Kymeta competes through flat-panel form factors that eliminate mechanical steering. Cobham Limited anchors its position in military mobility applications where ruggedization standards exceed commercial thresholds.
A satellite antenna converts electromagnetic signals between free-space propagation and guided transmission, typically operating across C, Ku, Ka, or X-band frequencies with gains ranging from 20 dBi to over 60 dBi depending on aperture diameter and feed configuration. These devices enable bidirectional communication links for broadcasting, broadband internet, remote sensing data downlink, and command-and-control networks. Phased array and flat panel architectures are capturing share from parabolic reflectors in low-Earth orbit applications where rapid beam agility and low profile matter more than peak gain. Defense and maritime end users sustain premium pricing for multi-band terminals that operate across contested spectrum environments. Ground station installations retain the largest volume footprint, though mobile platforms represent the fastest-expanding margin pool as connected vehicle and airborne relay programs multiply.
FCC spectrum allocation proceedings, ITU coordination frameworks, and DoD MIL-STD-188 compliance requirements collectively shape product roadmaps and market access timelines for antenna suppliers serving North American customers. EAR and ITAR export controls further segment addressable markets between allied defense programs and unrestricted commercial deployments. Stakeholders must track LEO constellation deployment cadence against terrestrial 5G spectrum claims to anticipate capacity pricing and terminal demand inflections.
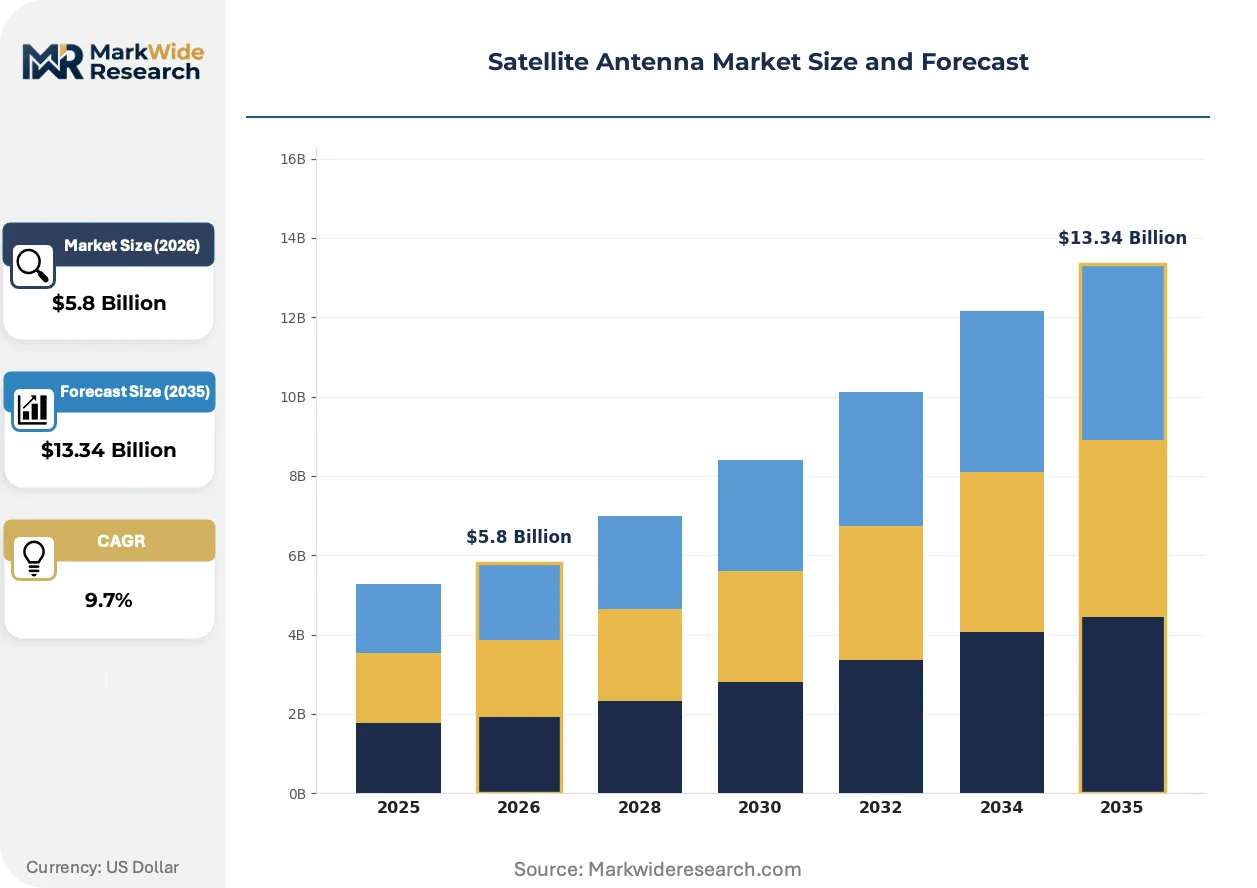
Market Dynamics
Phased array architectures are compressing the traditional hardware replacement cycle while shifting margin capture toward software-defined capability layers. This structural transition favors suppliers with embedded firmware competencies over legacy dish manufacturers.
Growth Catalysts
- LEO Constellation Deployment:Commercial low-Earth orbit networks are pulling demand for flat-panel terminals that track multiple satellites simultaneously without mechanical steering.
- Space Force Modernization:United States defense procurement programs are expanding resilient satellite uplink capacity across contested spectrum environments.
- Software-Defined Beamforming:Digital signal processing advances enable antenna pattern reconfiguration through firmware updates, creating recurring revenue streams.
Market Restraints
- Gallium Nitride Supply Concentration:High-frequency power amplifier substrates depend on limited foundry capacity concentrated in East Asian manufacturing clusters.
- ITAR Export Controls:United States defense technology restrictions segment addressable markets between allied military programs and unrestricted commercial deployments.
- Ka-band Rain Fade:Higher frequency operation suffers signal attenuation in heavy precipitation, limiting reliable throughput in tropical and maritime zones.
Strategic Opportunities
- Connected Vehicle Integration:Automotive OEMs are sourcing low-profile roof-mounted terminals for over-the-air software updates and passenger broadband.
- India's Spacecom Liberalization:Revised satellite communication policies permit private ground station ownership, opening terminal deployment for regional ISPs.
- Hybrid RF-Optical Links:Convergence of radio frequency and free-space optical technologies enables terabit-class feeder links for next-generation constellations.
Industry Challenges
- Electromagnetic Interference Certification:Multi-band terminals face extended FCC and ITU coordination timelines for spectrum coexistence validation.
- Thermal Management Expertise:Compact flat-panel designs require scarce RF thermal engineering talent to dissipate power in sealed enclosures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Satellite Antenna Market |
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $13.34 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Parabolic, Phased Array, Flat Panel, Cassegrain End User: Aerospace, Defense, Maritime, Telecommunication Installation: Ground Station, Mobile, Portable, Fixed Technology: Active, Passive, Dual-Band, Multi-Band |
| Companies Covered | Mitsubishi Electric Corporation, CPI Satcom & Antenna Technologies, Maxar Technologies, Kymeta, Cobham Limited, Viasat, L3Harris, Gilat Satellite Networks, Honeywell International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Satellite Antenna Market Strategic Shifts & Innovations
Beam agility requirements are forcing architectural choices that trade peak gain for scan speed and form factor flexibility. These pressures are accelerating investment in solid-state electronics and digital beamforming ASICs.
Electronically steered arrays are automating satellite acquisition and handoff sequences that previously required manual operator intervention or mechanical repositioning. Maritime and aviation end users are adopting these systems fastest where crew size constraints eliminate dedicated antenna operators. This automation is compressing the addressable market for traditional servo motor and positioner suppliers while expanding margins for semiconductor and software providers.
United States FCC spectrum allocation proceedings are reallocating C-band spectrum for 5G terrestrial use, forcing satellite operators to migrate services to higher frequencies or compressed orbital slots. This industrial consequence accelerates Ka-band terminal refresh cycles among broadcast and enterprise customers. Ground segment suppliers serving North American broadcasters are responding with multi-band capable infrastructure that maintains legacy Ku-band operation while adding Ka-band paths.
Antenna-as-a-service contracting is displacing capital purchase models among constellation operators managing rapid technology obsolescence risk. Fleet operators and regional airlines are adopting monthly terminal lease arrangements that bundle hardware, maintenance, and bandwidth. This pattern is most visible in United States and European markets where managed connectivity providers aggregate demand across dispersed vehicle and vessel populations.
Satellite Antenna Market Segmentation
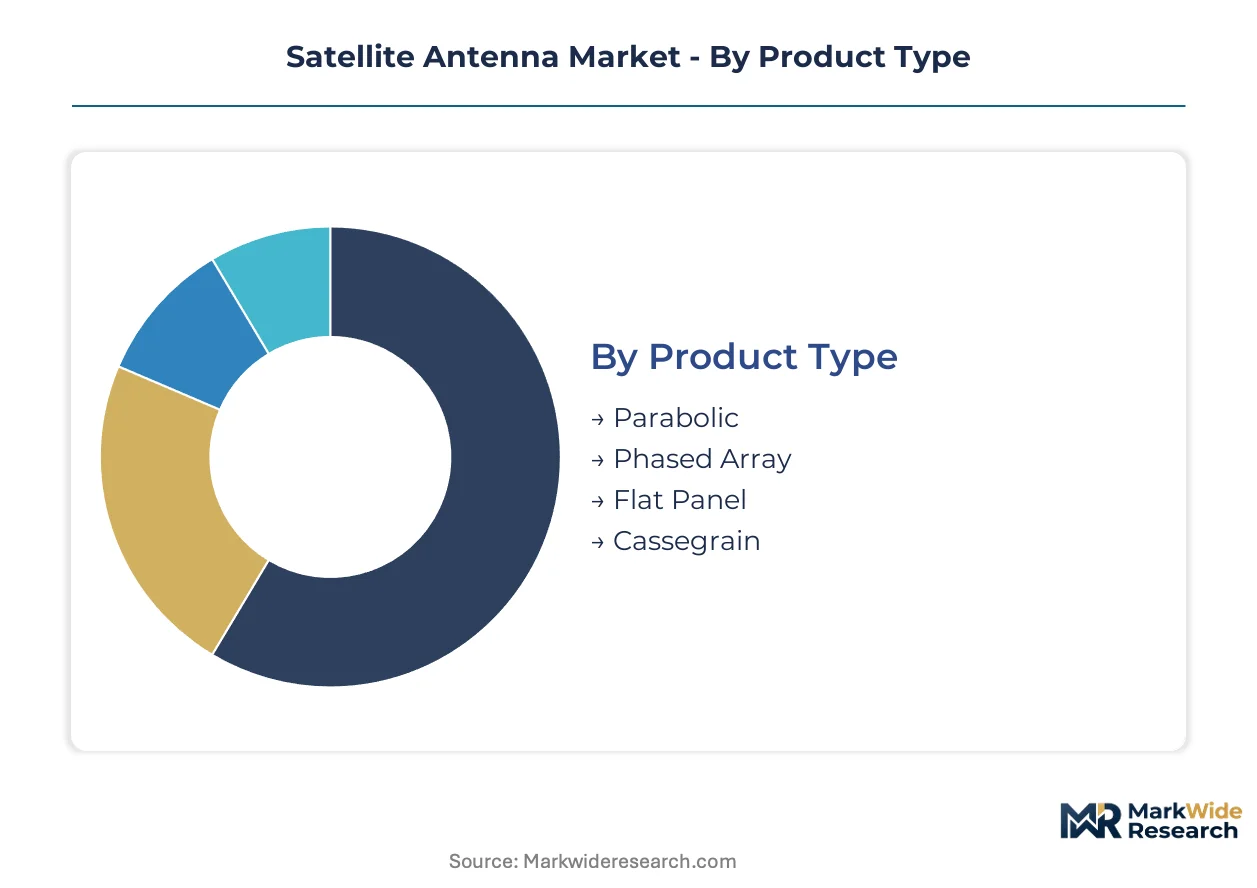
Satellite antenna architectures diverge sharply between legacy ground infrastructure and next-generation mobility platforms. Phased array and flat-panel technologies are compressing the addressable market for mechanically steered dishes while expanding margin pools for semiconductor-integrated suppliers.
Product Type:
The customization-to-standardization spectrum runs from bespoke parabolic installations for deep-space missions to mass-produced flat panels for consumer broadband terminals.
- Parabolic:Large-aperture reflector designs achieve peak gain through precision-machined aluminum or composite surfaces, typically exceeding 3 meters diameter for geostationary links. Broadcasters in the United States and legacy teleport operators sustain procurement for high-throughput video distribution where beam agility matters less than signal-to-noise ratio.
- Phased Array:Electronically steered architectures eliminate mechanical wear through solid-state phase shifters and radiating element matrices. Defense procurement programs across NATO members are standardizing on these systems for resilient satellite uplinks in contested spectrum environments where rapid beam nulling defeats jamming.
- Flat Panel:Low-profile form factors integrate RF electronics directly into weather-sealed enclosures for vehicle and maritime mounting. Starlink and OneWeb terminal suppliers are driving volume manufacturing scale.
- Cassegrain:Dual-reflector configurations fold optical paths into compact mechanical packages for high-frequency Ka-band operation. Scientific research stations and specialized military ground segments maintain limited procurement.
Leading the category by volume: Flat Panel. Expanding most quickly: Phased Array.
End User:
Cost tiers separate mission-critical defense specifications from price-sensitive consumer broadband deployments.
- Aerospace:Airborne terminals must satisfy DO-160G environmental standards for altitude, vibration, and temperature cycling. Commercial airlines and business aviation operators are retrofitting fleets for passenger connectivity and cockpit data links.
- Defense:MIL-STD-188 compliance and NSA Type-1 encryption certification create procurement barriers that sustain premium pricing. Space Force modernization programs are expanding resilient uplink capacity across United States strategic command networks.
- Maritime:Stabilized antenna platforms compensate for vessel motion through gyroscopic reference systems and rapid electronic beam steering. Cruise lines and container shipping operators are standardizing on flat-panel terminals that eliminate below-deck mechanical tracking equipment.
- Telecommunication:Ground station operators and cellular backhaul providers source multi-band infrastructure for flexible capacity leasing. Tower companies in India are deploying terminals to extend 4G coverage into rural zones where fiber deployment is uneconomical.
Highest margin concentration: Defense. Steepest volume expansion: Telecommunication.
Installation:
Geographic mobility requirements dictate thermal management complexity and environmental sealing specifications.
- Ground Station:Fixed installations leverage concrete foundations and climate-controlled equipment shelters to maximize aperture diameter and minimize maintenance cycles. Teleport operators in the United States, Germany, and Australia are upgrading C-band infrastructure for Ka-band migration.
- Mobile:Vehicle-mounted terminals integrate shock isolation and aerodynamic enclosures for highway and railway speeds. Connected truck programs across North American freight corridors are pulling demand for low-profile roof-mounted systems.
- Portable:Man-packable terminals collapse into transport cases for rapid deployment by expeditionary units and emergency response teams. Military special operations and disaster relief agencies sustain procurement for beyond-line-of-sight communications.
- Fixed:Building-mounted consumer terminals prioritize aesthetic integration and simplified homeowner installation. Starlink's residential subscriber base in the United States and Canada is driving manufacturing scale for self-aligning phased array dishes.
Dominant revenue share: Ground Station. Gaining share fastest: Mobile.
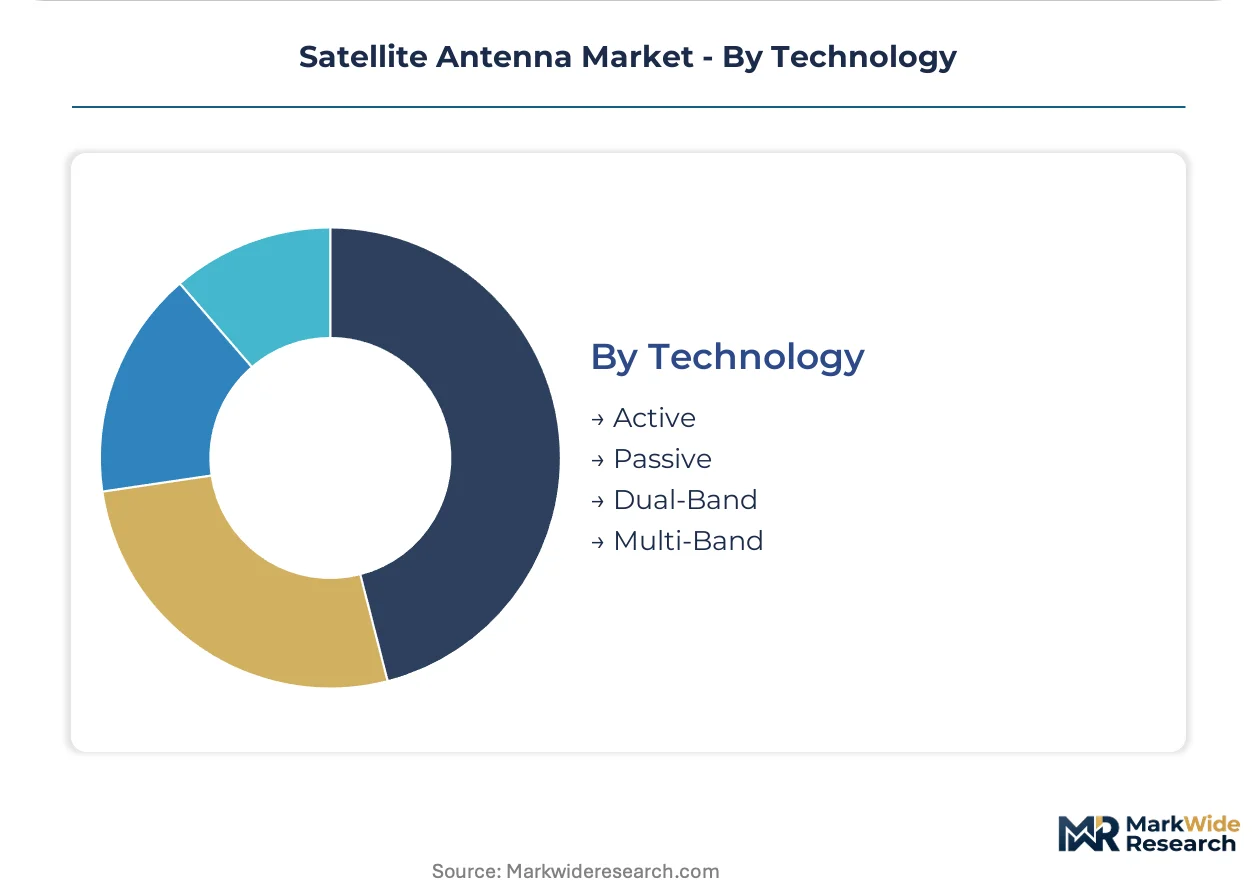
Technology:
Supply concentration in GaN foundry capacity and digital beamforming ASICs favors integrated suppliers over discrete component assemblers.
- Active:Transmit-receive modules with integrated power amplification enable electronic beam steering without external RF chains. Phased array suppliers in the United States and Japan are securing captive GaN-on-SiC foundry capacity.
- Passive:Receive-only architectures eliminate power amplifiers and thermal management systems for cost-constrained applications. Direct-to-home satellite television markets in Latin America and Southeast Asia sustain demand for simple parabolic dishes.
- Dual-Band:Simultaneous Ku and Ka-band operation enables service continuity during spectrum migration. Broadcasters facing FCC C-band reallocation are prioritizing these terminals for operational flexibility.
- Multi-Band:C, X, Ku, and Ka-band coverage supports military users operating across contested and cooperative spectrum environments. NATO interoperability standards are mandating these capabilities for coalition force communications.
Widest deployment base: Passive. Climbing the fastest: Active.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
El Segundo, California anchors North American satellite antenna engineering talent density, with Space Force procurement programs and commercial LEO constellation operators co-located along the aerospace corridor.
United States
Space Force modernization and Starlink terminal manufacturing pull demand for flat-panel and phased array architectures. FCC spectrum reallocation proceedings force C-band migration toward Ka-band infrastructure. El Segundo and Redondo Beach concentrate defense prime contractors and commercial constellation operators.
Germany
Broadcast teleport operators and maritime terminal integrators sustain procurement for multi-band ground infrastructure. REACH chemical compliance and CE marking requirements shape thermal management material selection. Munich and Stuttgart host precision manufacturing clusters serving European space agencies.
Japan
METI industrial policy directs public-private investment toward next-generation satellite communication terminals. Ka-band ground segment suppliers leverage precision machining heritage from consumer electronics manufacturing. Tokyo and Nagoya concentrate RF component foundries and antenna test facilities.
India
Spacecom liberalization permits private ground station ownership, opening terminal deployment for regional ISPs and tower companies. TRAI spectrum allocation frameworks govern Ku and Ka-band commercial use. Bengaluru and Hyderabad host ISRO-adjacent engineering clusters developing indigenous antenna capabilities.
United Kingdom
Defense procurement through the Ministry of Defence sustains demand for ruggedized maritime and airborne terminals. ITAR-aligned export control regimes segment allied military programs from commercial deployments. Portsmouth and Bristol harbor satellite integration facilities serving NATO interoperability standards.
Satellite Antenna Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the satellite antenna value chain, with integrated foundry operators capturing margin from semiconductor-integrated architectures while specialized engineering houses retain position in bespoke reflector applications. The vendor base stratifies across three tiers: defense primes with captive certification capabilities, commercial flat-panel specialists scaling manufacturing velocity, and regional teleport integrators assembling multi-vendor ground segments. Dominant competitive moves include GaN-on-SiC foundry capacity pre-commitments and firmware-centric service contracting that displaces hardware-only revenue models.
Within the defense prime tier, L3Harris and Honeywell International exemplify integrated suppliers with embedded NSA Type-1 encryption certification and MIL-STD-188 compliance capabilities. Mitsubishi Electric Corporation occupies a position bridging precision manufacturing heritage with high-frequency ground segment supply. Kymeta represents the flat-panel specialist archetype, competing through electronically steered architectures that eliminate mechanical steering subsystems.
| Leading Market Players |
|---|
| Mitsubishi Electric Corporation |
| CPI Satcom & Antenna Technologies |
| Maxar Technologies |
| Kymeta |
| Cobham Limited |
| Viasat |
| L3Harris |
| Gilat Satellite Networks |
| Honeywell International |
| Others |
Cost & Logistics Intelligence
Gallium Nitride substrate costs cascade through three distinct pricing tiers, with defense-certified active phased arrays commanding premiums over commercial flat panels and passive parabolic dishes absorbing commodity-level margin compression. Ka-band power amplifier foundry capacity in Japan and the United States concentrates pricing power among integrated suppliers, while downstream buyers in maritime and telecommunication segments face divergent total-cost-of-ownership calculations based on firmware upgrade pathways.
Pricing Analysis
Throughput-guaranteed service contracting anchors value-based pricing for constellation operators managing rapid technology obsolescence risk. Three-tier pricing structure across defense-certified, enterprise-grade, and consumer broadband levels separates MIL-STD-188 compliant terminals from commercial flat panels and passive receiver dishes. Pricing pressure stems from Starlink manufacturing scale driving consumer terminal cost compression, with telecommunication ground station operators exhibiting highest price sensitivity and Space Force procurement programs remaining least elastic due to encryption certification requirements.
Supply Chain Analysis
Refurbishment flows for phased array transmit-receive modules create secondary supply streams that moderate raw material demand volatility for gallium nitride and silicon carbide substrates. Manufacturing concentrates in Japan, the United States, and Taiwan, with GaN-on-SiC foundry capacity drawing from limited substrate suppliers in North Carolina and Aichi Prefecture. Single-source vulnerability in high-frequency power amplifier substrates persists, while distribution runs through defense prime integrators, commercial constellation operators, and regional teleport service providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ITAR export controls erect a cost-of-compliance moat that protects incumbent defense primes while fragmenting addressable markets between allied military programs and unrestricted commercial deployments. This regulatory barrier sustains premium pricing for NSA Type-1 encryption certification holders.
For Market Incumbents: Anchor defense prime positions through captive GaN-on-SiC foundry pre-commitments and firmware-centric service contracting that displaces hardware-only revenue models. Threat substitution from commercial flat-panel specialists like Kymeta demands accelerated software-defined beamforming R&D investment. Vertical integration into thermal management engineering talent pools represents the critical lever for margin defense in compact active array architectures. For New Entrants and Emerging Players: Enter via India's liberalized Spacecom ground station ownership rules, where regional ISP terminal deployment remains underpenetrated relative to United States and European markets. White-space targets include connected vehicle integration programs across North American freight corridors and hybrid RF-optical feeder link development for next-generation constellations. Direct sales to automotive OEMs bypass established defense prime distribution channels. For Investors and Strategic Acquirers: LEO constellation deployment cadence announcements from SpaceX and OneWeb are the leading indicator that terminal manufacturing scale economics will consolidate around integrated semiconductor-assembly suppliers. Long-term viability favors asset-light designers with embedded firmware competencies over capital-heavy parabolic reflector manufacturers. Acquisition targets should display GaN foundry partnerships or digital beamforming ASIC development capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| GaN-on-SiC Foundry Pre-commitment | Captive substrate supply secures pricing power for active phased array production against East Asian capacity constraints. |
| Firmware-as-a-Service Transition | Recurring capability upgrades shift revenue from hardware sales to software-defined antenna pattern reconfiguration contracts. |
| ITAR-Compliant Manufacturing Footprint | Segregated production lines preserve defense program access while commercial units serve unrestricted export markets. |
| Multi-band Terminal Development | Simultaneous Ku and Ka-band coverage addresses FCC C-band reallocation migration requirements for broadcast customers. |
| Connected Vehicle Integration Partnership | Automotive OEM roof-mounted terminal programs pull demand for low-profile form factors with aerodynamic enclosures. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, triangulated against primary interviews with RF systems engineers, defense procurement officers, constellation program managers, and teleport operations directors. FCC spectrum allocation dockets, ITU coordination filings, and DoD MIL-STD-188 compliance documentation provided regulatory boundary conditions. Bottom-up manufacturing capacity assessments and top-down demand modeling from LEO constellation deployment schedules converged on volume estimates.
Granularity-level modeling tracked product type, end user, installation, and technology dimensions across the projection horizon, with additional segmentation by frequency band and certification tier. CAGRs derived from installed base replacement cycles and new deployment ramps, incorporating GaN foundry capacity expansion timelines and Space Force budget authorization trajectories as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under gallium nitride supply disruption or accelerated 5G spectrum reallocation scenarios. Practitioners should monitor LEO constellation launch cadence and ITAR regulatory amendments for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Satellite Communication Equipment Market
Satellite
Satellite Attitude and Orbit Control System Market
Satellite
Satellite Photography Service Market
Satellite
Europe Military Satellite Market
Satellite
Global Satellite Modem Market
Satellite
Medium and Large Satellite Market
Satellite
Commercial LEO Satellite Market
Satellite
Asia-Pacific Satellite Launch Vehicle Market
Satellite
Sudan Satellite Transponder Market
Satellite
4K Satellite Broadcasting Market
Satellite
Satellite Signal Meter Market
Satellite
Asia-Pacific Satellite Manufacturing and Launch Systems Market
Satellite
Latin America Satellite Connectivity Market
Satellite
US Satellite-Based Earth Observation Market
Satellite
Satellite Based Augmentation Systems (SBAS) Market
Satellite
Germany Satellite Imagery Services Market