
 Satellite Signal Meter Market | 2026-2036
Satellite Signal Meter Market Size, Share, and Industry Trends Forecast 2026-2036
Satellite Signal Meter Market Analytics
The FCC's updated signal integrity requirements for satellite broadcast transmissions is expanding the addressable market for precision measurement equipment. SATLINK leverages its specialization in handheld field meters to capture installer demand across Latin America. L3Harris Technologies sustains technology leadership through defense-grade signal analyzer platforms. Viasat competes by anchoring its product line to consumer satellite internet installation workflows.
A satellite signal meter is an electronic test instrument that measures radio frequency power levels, signal-to-noise ratios, and modulation quality parameters such as MER and BER across Ku-band and Ka-band frequencies. The device enables technicians to align antennas, verify transponder performance, and certify compliance with carrier specifications during satellite ground segment deployment. Handheld meters occupy the highest volume tier due to technician mobility requirements, while signal analyzers command premium pricing from broadcast engineering departments. Desktop meters serve the maintenance application segment where stationary monitoring stations predominate.
The FCC enforces emission mask compliance and out-of-band radiation limits that mandate calibrated measurement tools for licensed earth stations. ETSI standards in Europe and ARIB specifications in Japan create parallel certification requirements that shape product design cycles and market entry costs. Stakeholders must monitor evolving spectrum reallocation proceedings and next-generation DVB-S2X standardization timelines to align R&D commitments with regulatory trajectories.
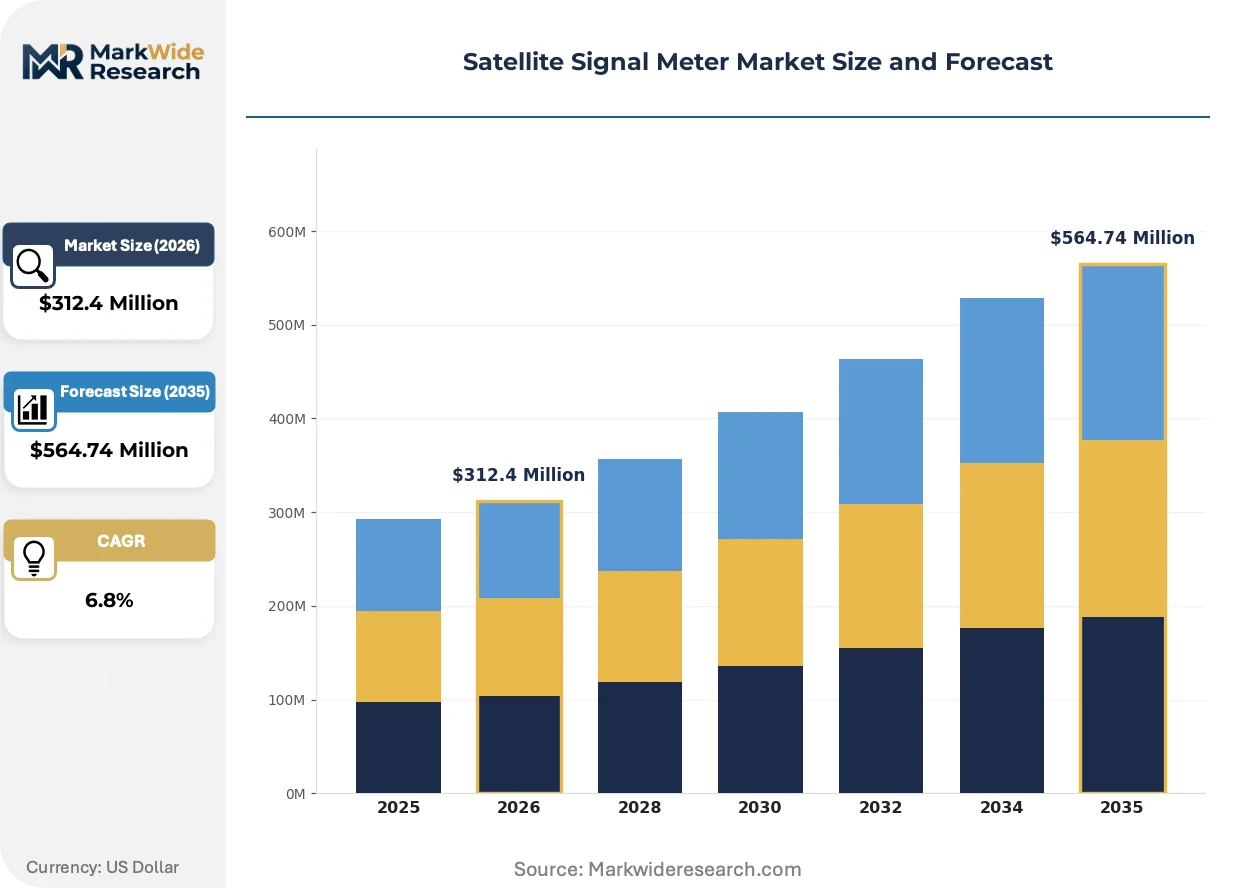
Market Dynamics
Broadcast infrastructure modernization is compressing replacement cycles for field measurement equipment as terrestrial-to-satellite migration accelerates across network operators. Regulatory mandates for signal integrity verification are embedding calibrated meters into standard deployment workflows rather than treating them as discretionary tools.
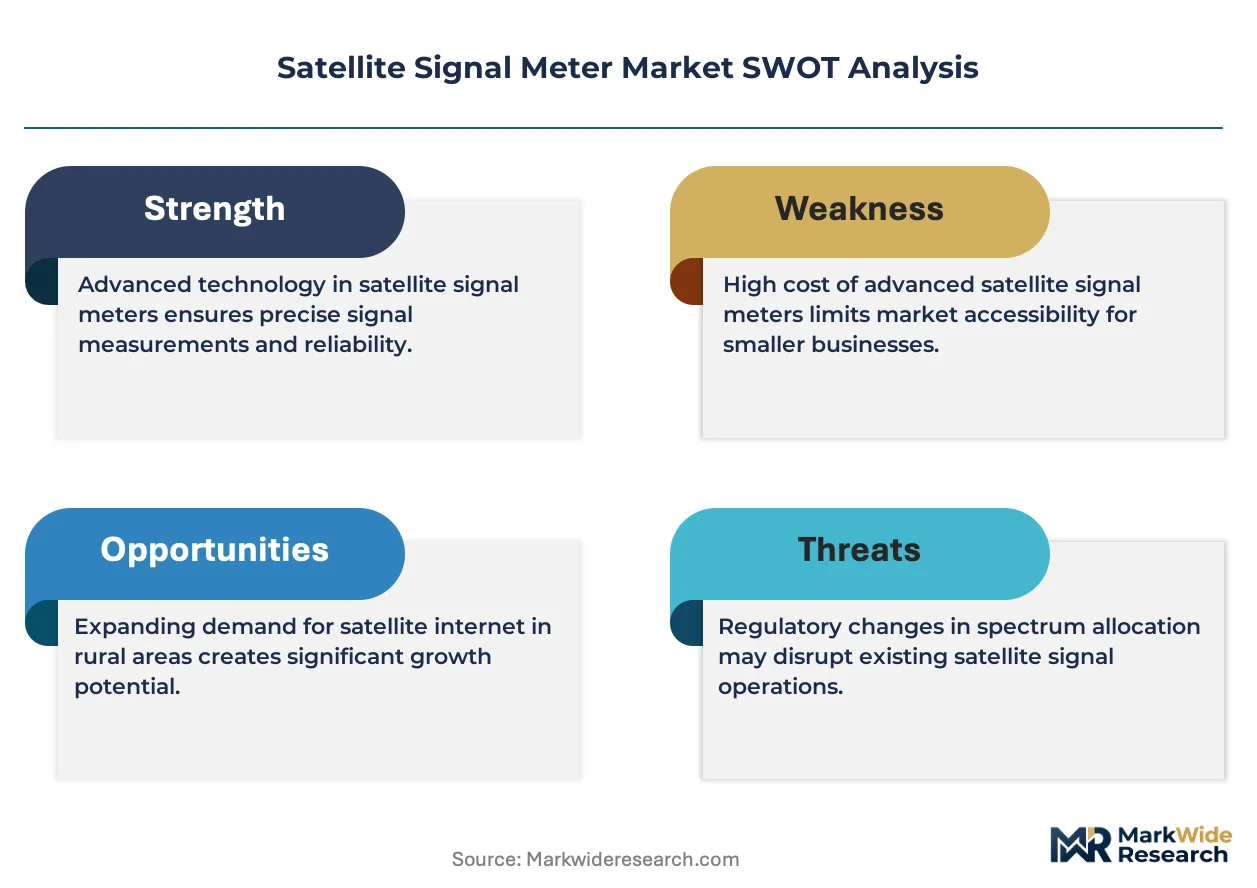
Growth Catalysts
- FCC emission mask enforcement:Licensed earth stations in the United States must deploy calibrated measurement tools to verify out-of-band radiation limits, expanding mandatory procurement beyond voluntary upgrade cycles.
- Ku-band to Ka-band migration:Higher frequency operations demand precision alignment capabilities that legacy analog meters cannot deliver, forcing hardware refresh across installer networks.
- Consumer satellite internet rollout:Low-earth orbit constellation deployment is creating technician workforce scale requirements that handheld field meters must satisfy.
Market Restraints
- RF component supply concentration:Specialized mixer and detector module production clusters in East Asian foundries expose meter manufacturers to single-source vulnerability and extended lead times.
- Calibration infrastructure scarcity:National metrology institutes maintain limited satellite signal reference standards, creating bottlenecks for manufacturer certification and recertification services.
- Software-defined radio substitution:General-purpose SDR platforms with open-source signal analysis stacks threaten dedicated hardware demand among technically sophisticated users.
Strategic Opportunities
- India broadcast digitization:TRAI-mandated satellite television infrastructure expansion is creating first-time meter demand among regional cable operators and direct-to-home installers.
- DVB-S2X standardization:Next-generation modulation schemes require updated measurement algorithms that create upgrade revenue streams from installed base replacement.
- Cloud-connected diagnostics:Cellular-enabled meters transmitting alignment data to central engineering desks enable subscription-based fleet management services.
Industry Challenges
- RF engineering talent scarcity:Specialized microwave measurement expertise required for product development concentrates in defense and telecommunications sectors, constraining hiring pipelines.
- Multi-standard certification complexity:Simultaneous compliance with FCC, ETSI, and ARIB specifications extends product development timelines and testing expenditure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Satellite Signal Meter Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Meters, Desktop Meters, Signal Analyzers, Advanced Meters End User: Telecommunication Companies, Installers, Broadcasters, Consumers Technology: DVB-S2, DVB-S, DSS, FSS Application: Satellite Installation, Maintenance, Signal Analysis, Troubleshooting |
| Companies Covered | SATLINK, Findsat, GTMEDIA, SANKYSAT, Twinkler, L3Harris Technologies, Honeywell International, Viasat, EchoStar Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Satellite Signal Meter Market Evolving Landscape
Measurement hardware is converging with software analytics platforms, transforming standalone instruments into networked diagnostic nodes. This integration is compressing the boundary between field installation tools and centralized network operations centers.
Vector signal analysis capability is absorbing into handheld meter form factors previously limited to scalar power measurement. Broadcast engineering departments are adopting these units for remote site troubleshooting without dispatching spectrum analyzer equipment. This capability migration is absorbing service contract value from centralized test labs into distributed field assets.
ETSI harmonized standards for satellite earth station equipment are mandating interoperability testing protocols that shape product architecture decisions. Manufacturers must embed standardized remote monitoring interfaces to achieve CE marking for European market entry. Broadcast network operators in Germany and France are prioritizing certified equipment to streamline cross-border fleet procurement.
Technical buyers are consolidating vendor relationships around full-lifecycle service agreements rather than transactional hardware purchases. System integrators and network operators are bundling meter procurement with training and calibration services under multi-year contracts. This preference consolidation is most pronounced in United States cable and satellite television markets where procurement departments seek single-source accountability.
Satellite Signal Meter Market Segmentation
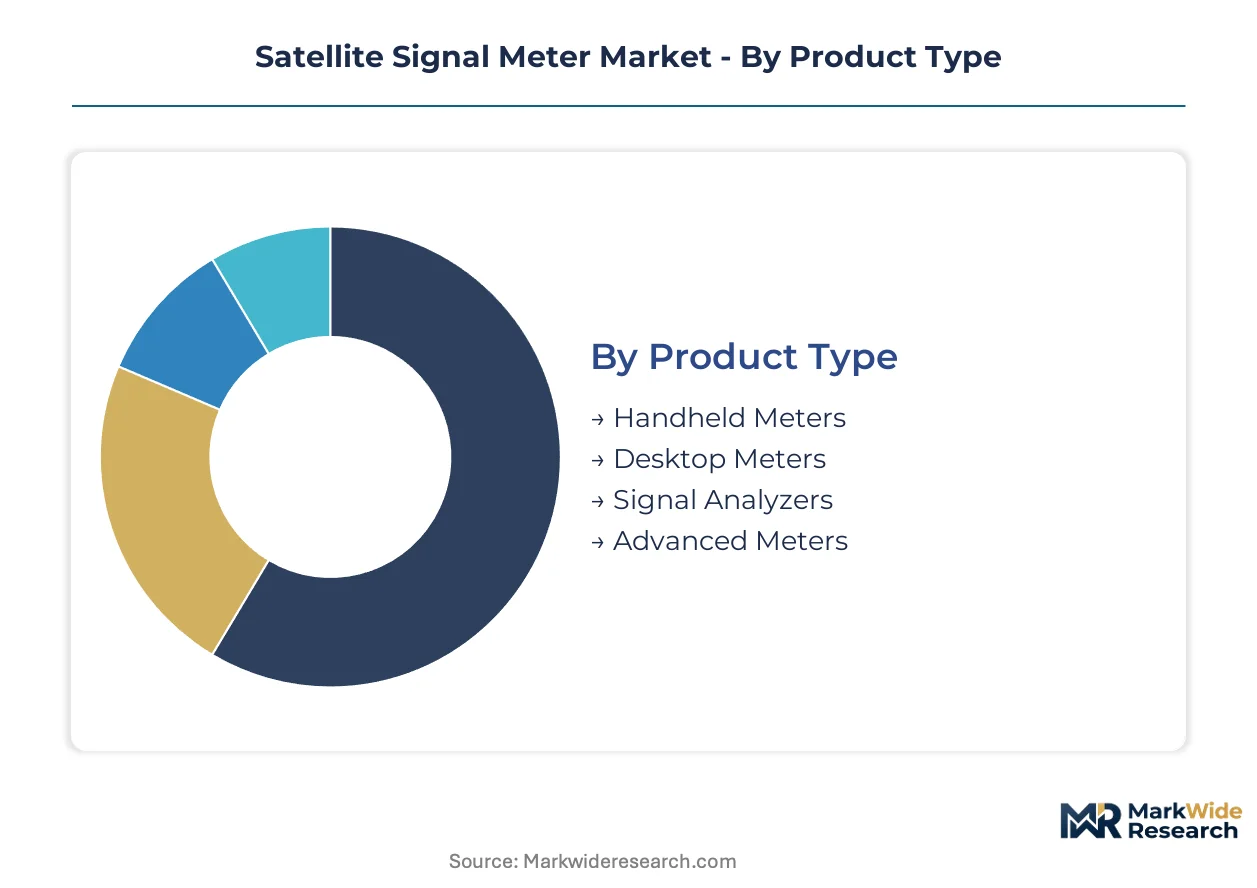
Satellite signal meter segmentation reflects divergent capital requirements across deployment scenarios. Installer mobility demands shape hardware form factors, while broadcast engineering workflows dictate precision specifications and calibration protocols.
Product Type:
Capital intensity varies sharply across this category, with laboratory-grade analyzers requiring tenfold higher upfront investment than field-portable units.
- Handheld Meters:Battery-powered units integrate scalar power detection with basic modulation analysis for antenna alignment tasks. United States direct-to-home installers drive volume procurement as LEO constellation deployment scales technician workforces.
- Signal Analyzers:Vector-capable platforms perform deep modulation quality analysis including MER and BER characterization across Ku-band and Ka-band frequencies. Broadcast engineering departments in Germany and France absorb premium pricing for remote site troubleshooting without spectrum analyzer dispatch.
- Desktop Meters:Stationary monitoring stations predominate in earth station maintenance facilities where continuous transponder verification is required.
- Advanced Meters:Cellular-enabled units transmit alignment telemetry to centralized network operations centers under subscription fleet management contracts.
Handheld meters absorb the bulk of installed capacity; advanced meters are expanding most quickly.
End User:
Procurement authority concentrates with technically sophisticated buyers who specify calibration certificates and multi-standard compliance.
- Telecommunication Companies:Backbone network operators mandate certified measurement tools for licensed earth station commissioning under FCC emission mask enforcement. Procurement departments bundle hardware with training and recalibration services under multi-year agreements.
- Broadcasters:Terrestrial-to-satellite migration accelerates equipment refresh cycles as network operators modernize transmission infrastructure.
- Installers:Independent technicians prioritize portability and battery endurance for residential satellite internet antenna deployment.
- Consumers:Hobbyist astronomers and recreational vehicle owners purchase entry-level units for occasional self-installation.
Telecommunication companies anchor procurement volume; broadcasters are climbing the fastest as infrastructure modernization accelerates.
Technology:
Standardization timelines shape product development roadmaps and installed base replacement cycles.
- DVB-S2:Dominant modulation standard for commercial satellite broadcasting supports adaptive coding and modulation with superior spectral efficiency.
- DVB-S2X:Next-generation extension enables higher-order modulation schemes and narrower carrier spacing for bandwidth-constrained applications.
- DVB-S:Legacy standard persists in established broadcast networks with slower upgrade trajectories.
- DSS:Proprietary direct broadcast satellite format maintains installed base in specific regional markets.
- FSS:Fixed satellite service applications require precision alignment verification for transponder leasing compliance.
DVB-S2 retains the dominant installed footprint; DVB-S2X is gaining share fastest as broadcasters prepare for ultra-HD payload requirements.
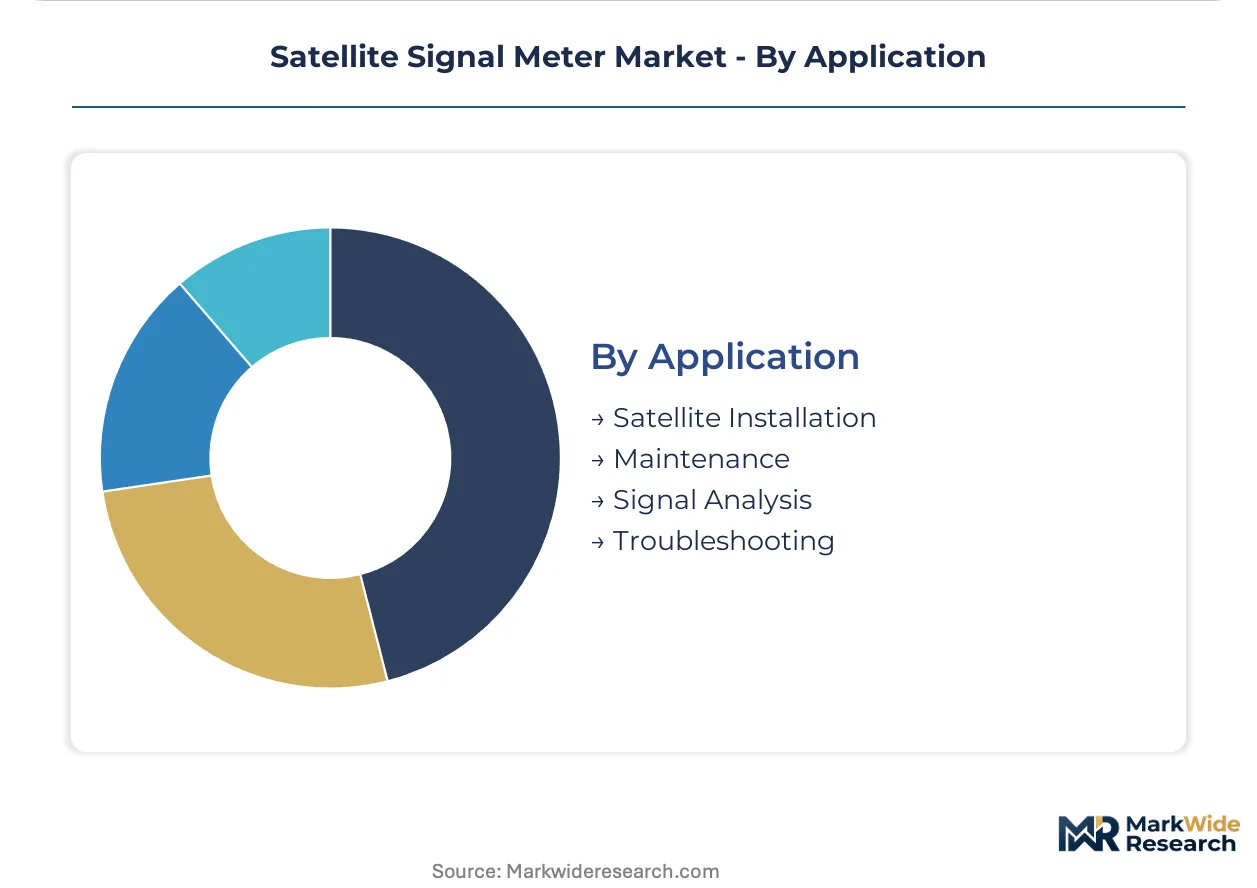
Application:
Workflow integration determines whether meters function as discrete tools or networked diagnostic nodes.
- Satellite Installation:Initial antenna alignment and line-of-sight verification for consumer and enterprise ground segments.
- Signal Analysis:Deep modulation quality assessment for broadcast engineering departments verifying carrier specifications.
- Maintenance:Continuous monitoring at earth station facilities where drift detection triggers proactive intervention.
- Troubleshooting:Rapid fault isolation during service degradation events requiring field dispatch or remote diagnosis.
Installation tasks consume the highest meter deployment volume; signal analysis applications are expanding most quickly as vector capability migrates to handheld form factors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in East Asian electronics manufacturing clusters while consumption tilts toward North American and European broadcast infrastructure markets. Meter manufacturers source specialized RF components from Taiwan and South Korean foundries. End-user demand clusters around licensed earth station operators facing tightening emission compliance mandates.
United States
FCC emission mask enforcement and LEO constellation deployment are expanding procurement of calibrated handheld meters among direct-to-home installers. The FCC mandates out-of-band radiation verification for licensed earth stations under Part 25 rules. Engineering departments in Los Angeles and New York broadcast clusters are refreshing legacy analog equipment for Ka-band precision alignment.
Germany
ETSI harmonized standards for earth station interoperability are embedding certified remote monitoring interfaces into procurement specifications. CE marking requirements under the Radio Equipment Directive shape product architecture decisions for European market entry. Broadcast network operators in Munich and Cologne prioritize certified equipment to streamline cross-border fleet standardization.
India
TRAI-mandated satellite television infrastructure expansion is generating first-time meter demand among regional cable operators and DTH installers. The Telecom Regulatory Authority of India enforces digitization timelines that accelerate ground equipment deployment. Installer networks in Maharashtra and Karnataka are scaling technician workforces to meet payload verification requirements.
Japan
ARIB specifications for satellite broadcasting equipment create parallel certification requirements that extend product development timelines. METI oversight of spectrum reallocation proceedings shapes R&D commitments for next-generation DVB-S2X compatibility. Precision manufacturing clusters in Nagoya supply mixer and detector modules to meter assembly operations.
Brazil
Satellite internet rollout for remote connectivity is driving technician workforce scale requirements across the Amazon region. ANATEL technical requirements for earth station licensing mandate calibrated measurement tools for transponder leasing compliance. Installers in São Paulo and Rio de Janeiro are upgrading from legacy analog meters to vector-capable handheld units.
Satellite Signal Meter Market Competitive Landscape
The competitive structure tilts toward defense-electronics conglomerates with captive RF engineering expertise. Tiered specialization separates handheld field specialists from laboratory-grade analyzer platforms. Three archetypes dominate: broadcast-focused instrument manufacturers, aerospace-defense contractors leveraging signal intelligence heritage, and consumer satellite equipment suppliers bundling meters with installation workflows. Capacity expansion and strategic technology licensing represent the dominant competitive moves as players address Ka-band precision requirements.
Among defense-electronics conglomerates, L3Harris Technologies and Honeywell International exemplify the aerospace-contractor archetype with heritage in signal intelligence and avionics measurement. SATLINK and Viasat occupy distinct positioning tiers—SATLINK representing handheld field specialists with Latin American installer network penetration, Viasat anchoring consumer satellite internet ecosystem integration. These named entities illustrate how competitive positioning fragments across precision-grade, portable, and ecosystem-embedded measurement solutions rather than consolidating around unified product architectures.
| Leading Market Players |
|---|
| SATLINK |
| Findsat |
| GTMEDIA |
| SANKYSAT |
| Twinkler |
| L3Harris Technologies |
| Honeywell International |
| Viasat |
| EchoStar Corporation |
| Others |
Value Network & Pricing Analysis
RF engineering talent concentration in Taiwan and South Korea generates labor-cost differentials that widen pricing-tier spreads between economy handheld units and precision laboratory analyzers. Technician wage arbitrage across these manufacturing clusters feeds directly into landed cost structures for field-portable versus rack-mounted instrumentation.
Pricing Analysis
Margin tightening in economy handheld meters reflects Ka-band precision requirements that obsolete legacy analog architectures. Three-tier pricing structure across premium vector-analyzer, standard scalar-meter, and economy power-detector levels separates certification-grade calibration from basic alignment functionality. Price differentiation traces to FCC Part 25 compliance certification and multi-standard ETSI/ARIB testing expenditure. Installer networks exhibit highest price sensitivity; defense-electronics procurement departments absorb premium positioning for signal intelligence-grade specifications.
Supply Chain Analysis
Specialized mixer and detector module supply rests on Taiwanese and South Korean foundry operations with limited alternative sourcing. Critical RF component dependencies include GaAs MMICs, precision attenuators, and calibrated reference oscillators. Single-source vulnerability concentrates around East Asian semiconductor packaging facilities exposed to geopolitical logistics chokepoints. Distribution runs through authorized instrumentation distributors serving broadcast engineering departments and direct-to-installer e-commerce channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into captive RF component fabrication represents the decisive competitive race as Ka-band precision requirements intensify. Players securing in-house MMIC production capacity gain procurement flexibility unavailable to assembly-only competitors.
For Market Incumbents: Hedge against software-defined radio substitution by embedding cloud-connected telemetry into handheld form factors. Defense heritage players like L3Harris Technologies should deepen backward integration into GaAs foundry partnerships. Certification investment in DVB-S2X measurement algorithms protects installed base replacement revenue against open-source analysis stacks. For New Entrants and Emerging Players: Launch via direct-to-installer digital channels targeting India's TRAI-mandated digitization surge. White-space concentration sits with regional cable operators in Maharashtra and Karnataka requiring first-time meter procurement. Cloud-enabled fleet management subscriptions offer recurring revenue differentiation against transactional hardware competitors. For Investors and Strategic Acquirers: Re-rating potential sits with handheld specialists possessing Latin American installer network density given LEO constellation deployment scaling. Broadcast infrastructure modernization extends replacement cycles across a multi-year viability window. Monitor DVB-S2X standardization timeline acceleration as inflection signal for algorithm-upgrade revenue recognition.| Strategic Initiative | Industry Significance |
|---|---|
| Ka-Band Precision R&D Investment | Defense contractors anchor technology leadership through signal intelligence heritage migration. |
| Cloud-Connected Diagnostics Launch | Cellular-enabled telemetry transforms standalone instruments into subscription fleet management nodes. |
| India Distribution Partnership | TRAI-mandated infrastructure expansion creates first-time demand among regional cable operators. |
| Backward Integration into RF Components | Captive MMIC fabrication insulates against East Asian foundry concentration risk. |
| Multi-Standard Certification Acceleration | Simultaneous FCC, ETSI, and ARIB compliance streamlines cross-border procurement for broadcast networks. |
Research Methodology
Regulatory filings, customs trade databases, and broadcast engineering procurement records formed the secondary backbone for this analysis. Primary interviews with RF test equipment product managers, satellite installer network supervisors, broadcast engineering department heads, and national metrology institute calibration specialists validated demand assumptions. Bottom-up unit shipment estimates triangulated against top-down addressable market calculations across handheld, analyzer, and desktop meter categories.
Historical trendline analysis of replacement cycle compression and technology migration patterns informed projection framework construction. Segmentation modeling spanned product form factor, end-user procurement authority, modulation standard generation, and application workflow integration. CAGRs derived from unit-volume trajectory analysis adjusted for regulatory mandate acceleration effects and LEO constellation deployment scaling assumptions.
Spectrum reallocation proceedings, RF component supply disruption, and DVB-S2X standardization delays are the dominant revision risks warranting ongoing watch. Forecasts reflect documented assumptions regarding technician workforce scaling and emission compliance enforcement intensity. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
North America Mobile Satellite Services Market
Satellite
North America Satellite Bus Market
Satellite
Asia-Pacific Satellite Bus Market
Satellite
Satellite Gateway Market
Satellite
Satellite Bus Market
Satellite
Satellite Communications Service Market
Satellite
Asia-Pacific Satellite Manufacturing and Launch Systems Market
Satellite
Spain Satellite Imagery Services Market
Satellite
Electric Propulsion Satellite Market
Satellite
ASEAN Satellite-Based Earth Observation Market
Satellite
China Satellite Imagery Services Market
Satellite
China Satellite-Based Earth Observation Market
Satellite
India Satellite Connectivity Market
Satellite
UAE Satellite Imagery Services Market
Satellite
Europe Satellite IoT Market
Satellite
Optical Satellite Communication Market