
 Computer Vision in Aerospace and Defense Market | 2026-2036
Computer Vision in Aerospace and Defense Market Size, Share, and Industry Trends Forecast 2026-2036
Computer Vision in Aerospace and Defense Market Insights
Software-defined targeting and analytics subscription layers is broadening what defense primes sell beyond hardware-delivery contracts. NVIDIA leverages its GPU-accelerated inference stack to anchor high-performance edge deployments for unmanned systems. Boeing sustains long-term service agreements that integrate computer vision modules into existing fleet modernization cycles. Shield AI competes through proprietary autonomy software that extends hardware utility across multiple aerial platforms.
Computer vision in aerospace and defense encompasses algorithms and sensor systems that extract actionable intelligence from electro-optical, infrared, and synthetic aperture radar inputs, typically processing imagery at frame rates exceeding 30 Hz for real-time decision support. Its primary purpose centers on enabling autonomous or semi-autonomous perception in contested environments where human operator bandwidth is constrained. Image processing and sensor fusion technologies dominate current deployment architectures, while machine learning segments exhibit the fastest capability iteration cycles as defense agencies fund adaptive threat recognition. Edge computing deployments capture concentrated margin pools due to latency requirements in denied-communication scenarios.
The United States Department of Defense imposes stringent AI ethics and testing protocols through the Responsible Artificial Intelligence Strategy, directly shaping vendor qualification requirements and procurement timelines. FAA regulations for beyond-visual-line-of-sight unmanned operations intersect with defense airspace management standards, creating dual-compliance burdens for contractors serving both military and civilian agencies. ISO 9001 and AS9100 quality frameworks govern supplier certification pathways, filtering market access for subsystem integrators. Stakeholders must monitor evolving export control classifications for dual-use computer vision software as sovereignty concerns harden technology transfer policies.
Market Dynamics
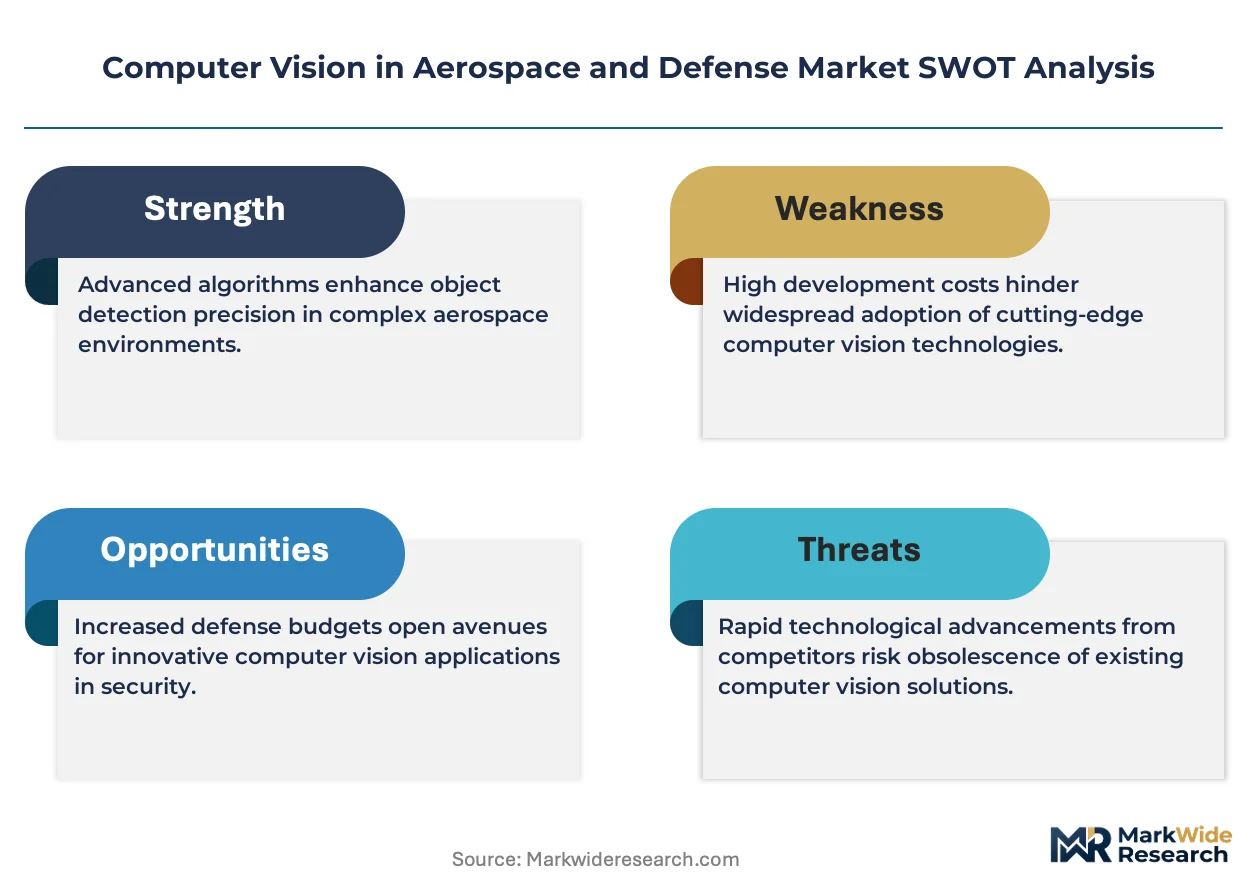
Defense procurement standards in the United States are compressing vendor qualification timelines while mandating sovereign AI capabilities, forcing subsystem integrators to restructure development pipelines around Responsible Artificial Intelligence Strategy compliance checkpoints.
Growth Catalysts
- Responsible Artificial Intelligence Strategy:The United States Department of Defense mandates rigorous testing protocols that filter qualified vendors and accelerate budget allocation toward compliant autonomy stacks.
- Autonomous surveillance systems:Military end users in Israel and China are expanding procurement volumes for unmanned perimeter monitoring following border security escalations.
- Edge computing architectures:Latency requirements in denied-communication scenarios are driving hardware-software integration contracts for GPU-accelerated inference at the tactical edge.
Market Restraints
- Export control classifications:Dual-use computer vision software faces hardening technology transfer policies from the United States Bureau of Industry and Security, elongating sales cycles for foreign military customers.
- GPU supply concentration:High-performance inference chip fabrication concentrates in Taiwan and South Korea, exposing defense primes to geopolitical supply disruption risks.
- Algorithmic interpretability limitations:Black-box neural network decisions fail to satisfy military chain-of-custody requirements for lethal autonomous system engagements.
Strategic Opportunities
- Underpenetrated aerial platforms:Rotary-wing unmanned systems in India lack mature computer vision payloads, creating first-mover advantages for modular autonomy software providers.
- Sensor fusion convergence:Electro-optical and synthetic aperture radar data streams are merging into unified perception pipelines for all-weather target recognition.
- AS9100 certification pathways:Quality framework compliance opens supplier tiers to prime contractor subcontracting networks previously closed to non-aerospace software vendors.
Industry Challenges
- Embedded systems talent scarcity:Defense contractors compete with commercial autonomous vehicle firms for firmware engineers capable of optimizing neural network inference on power-constrained edge devices.
- Dual FAA-military compliance:Contractors serving both civilian beyond-visual-line-of-sight operations and defense airspace management must maintain parallel certification tracks, doubling documentation overhead.
- Legacy fleet integration friction:Computer vision modules require physical retrofit of aging fixed-wing platforms with incompatible power and data bus architectures, complicating modernization contract scoping.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Computer Vision in Aerospace and Defense Market |
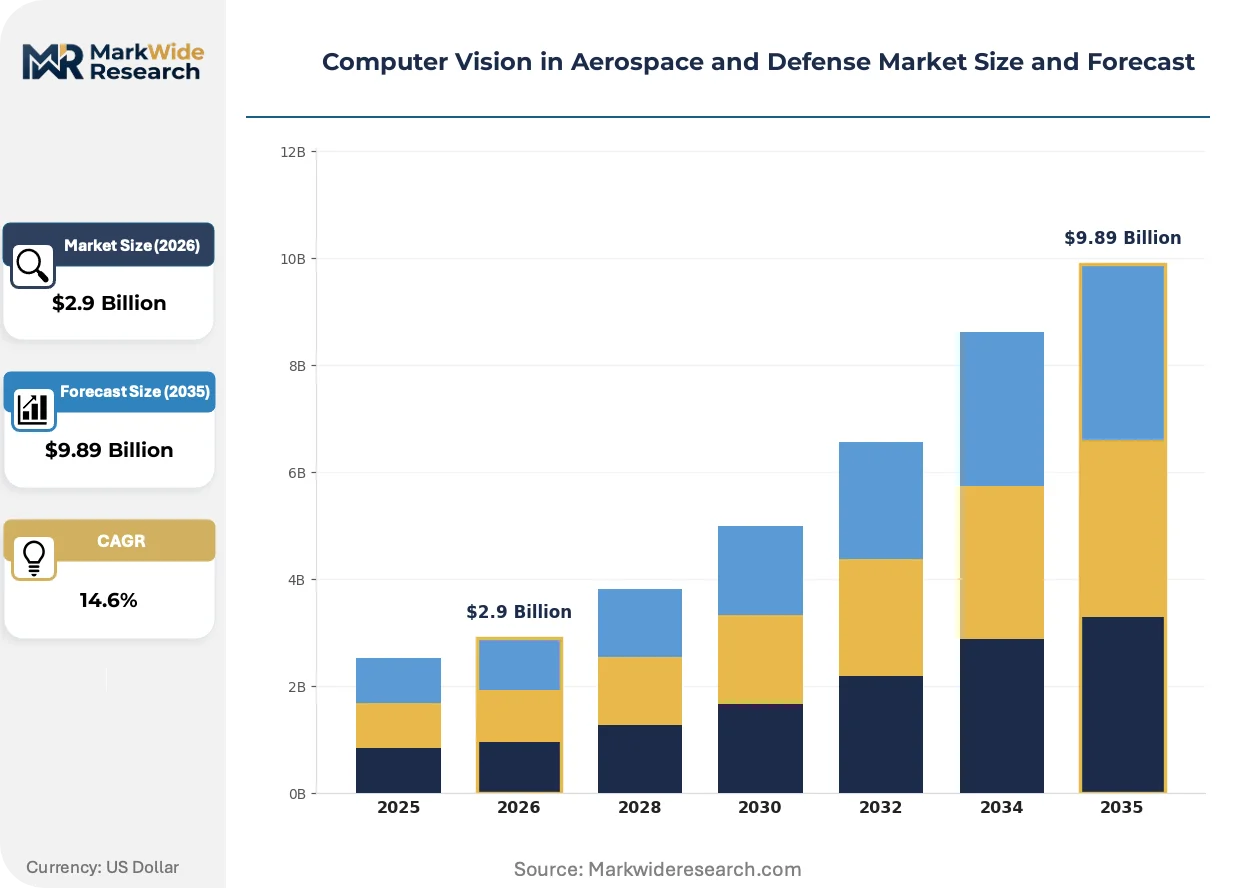
| Market Size in 2026 | $2.9 Billion |
| Market Size in 2035 | $9.89 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Surveillance, Target Recognition, Navigation Assistance, Maintenance Automation Technology: Machine Learning, Neural Networks, Image Processing, Sensor Fusion End User: Military, Government, Contractors, Research Institutions Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing |
| Companies Covered | Anduril Industries, HRL Laboratories, NVIDIA, Iris Automation, Adarga, Boeing, Shield AI, Echodyne, Cognex Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Computer Vision in Aerospace and Defense Market Trends and Innovations
Federated learning architectures are redistributing model training across dispersed tactical nodes, eliminating centralized data aggregation risks while preserving operational security in contested electromagnetic environments.
Neuromorphic processing chips are decentralizing inference workloads from centralized server racks to individual unmanned vehicle payloads. Naval Research Laboratory programs are piloting event-based vision sensors that reduce power consumption by three orders of magnitude versus frame-based cameras. This shift is compressing the minimum viable platform size for autonomous target tracking below ten kilograms.
EU AI Act risk classification tiers are mandating conformity assessments for high-risk autonomous systems deployed in member state defense cooperation frameworks. German and French procurement agencies now require documented human oversight protocols for computer vision-enabled strike recommendation systems. Dual-use vendors are restructuring product lines to isolate military-grade autonomy stacks from civilian commercial offerings.
Defense primes are unbundling hardware delivery from perpetual software licenses, replacing capital expenditure contracts with subscription-based analytics services. Israeli and Australian military customers now procure computer vision capabilities as operational expenditure line items tied to flight-hour utilization. This reconfiguration is compressing vendor cash conversion cycles while extending customer lifetime value through continuous model retraining services.
Computer Vision in Aerospace and Defense Market Segmentation
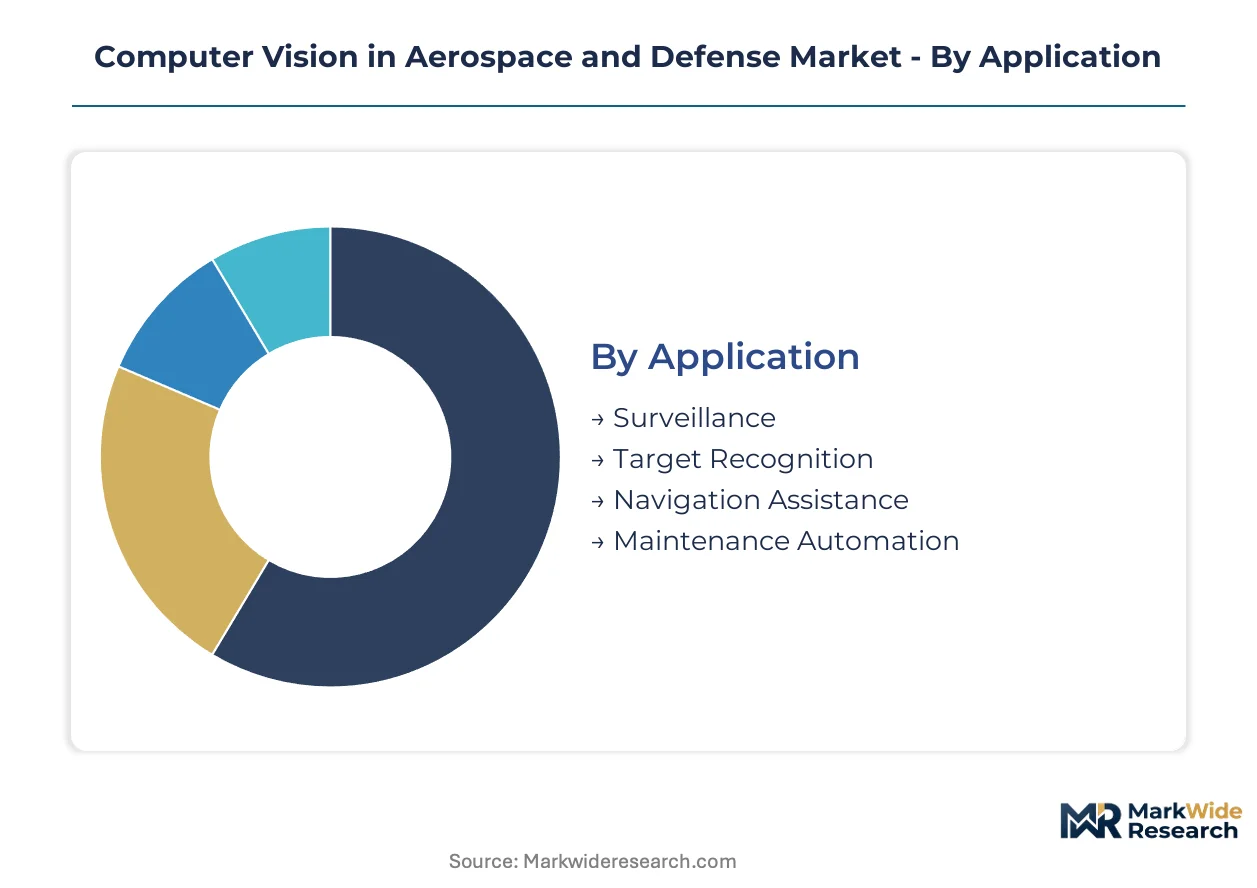
Computer vision in aerospace and defense fragments across multiple technical and operational axes, each commanding distinct procurement workflows and capability requirements. Military buyers prioritize deployment architecture and algorithm maturity over cost optimization, while dual-use contractors navigate divergent compliance pathways across application domains.
Application:
Image processing algorithms extract actionable intelligence from electro-optical, infrared, and synthetic aperture radar inputs across mission-critical scenarios.
- Surveillance:Perimeter monitoring systems process imagery exceeding 30 Hz frame rates for real-time threat detection in contested electromagnetic environments. Israel Defense Forces and United States Customs and Border Protection expand procurement of autonomous unmanned perimeter systems following border security escalations.
- Target Recognition:Machine learning classifiers identify and track objects across multiple spectral bands under degraded visibility conditions. Strike recommendation systems face EU AI Act conformity assessments requiring documented human oversight protocols in European defense cooperation frameworks.
- Navigation Assistance:Visual-inertial odometry enables GPS-denied positioning for unmanned aerial platforms operating in jammed airspace.
- Maintenance Automation:Defect detection algorithms inspect airframe structures and engine components during scheduled depot cycles.
Surveillance leads on scale; target recognition leads on momentum.
Technology:
Algorithmic approaches diverge sharply in computational requirements, interpretability standards, and military qualification burdens.
- Machine Learning:Adaptive statistical models iteratively improve threat recognition accuracy from operational data feedback loops. Defense agencies fund capability iteration cycles most aggressively in this segment, compressing model deployment timelines from laboratory to tactical edge.
- Neural Networks:Deep learning architectures achieve superior performance in cluttered visual environments but fail military chain-of-custody requirements for lethal autonomous engagements due to black-box decision opacity.
- Image Processing:Traditional computer vision techniques using edge detection, feature extraction, and geometric transforms require lower computational overhead.
- Sensor Fusion:Unified perception pipelines merge electro-optical and synthetic aperture radar streams for all-weather target recognition.
Image processing dominates current deployment architectures; machine learning expands most quickly.
End User:
Procurement authority and compliance obligations vary substantially across institutional categories.
- Military:Service branches mandate sovereign AI capabilities and Responsible Artificial Intelligence Strategy compliance checkpoints, filtering vendor qualification timelines. United States Department of Defense procurement standards compress development pipelines around rigorous testing protocols.
- Government:Civilian agencies including homeland security and intelligence community elements procure dual-use systems subject to FAA beyond-visual-line-of-sight regulations intersecting with defense airspace management standards.
- Contractors:Prime contractors and subsystem integrators serve as intermediaries, with AS9100 quality framework certification opening supplier tiers previously closed to non-aerospace software vendors.
- Research Institutions:Naval Research Laboratory programs pilot neuromorphic processing chips and event-based vision sensors, reducing power consumption by orders of magnitude versus conventional frame-based cameras.
Military commands the largest procurement volumes; research institutions drive the steepest technology advancement trajectory.
Deployment:
Latency requirements and communication availability dictate architectural trade-offs between centralized and distributed processing.
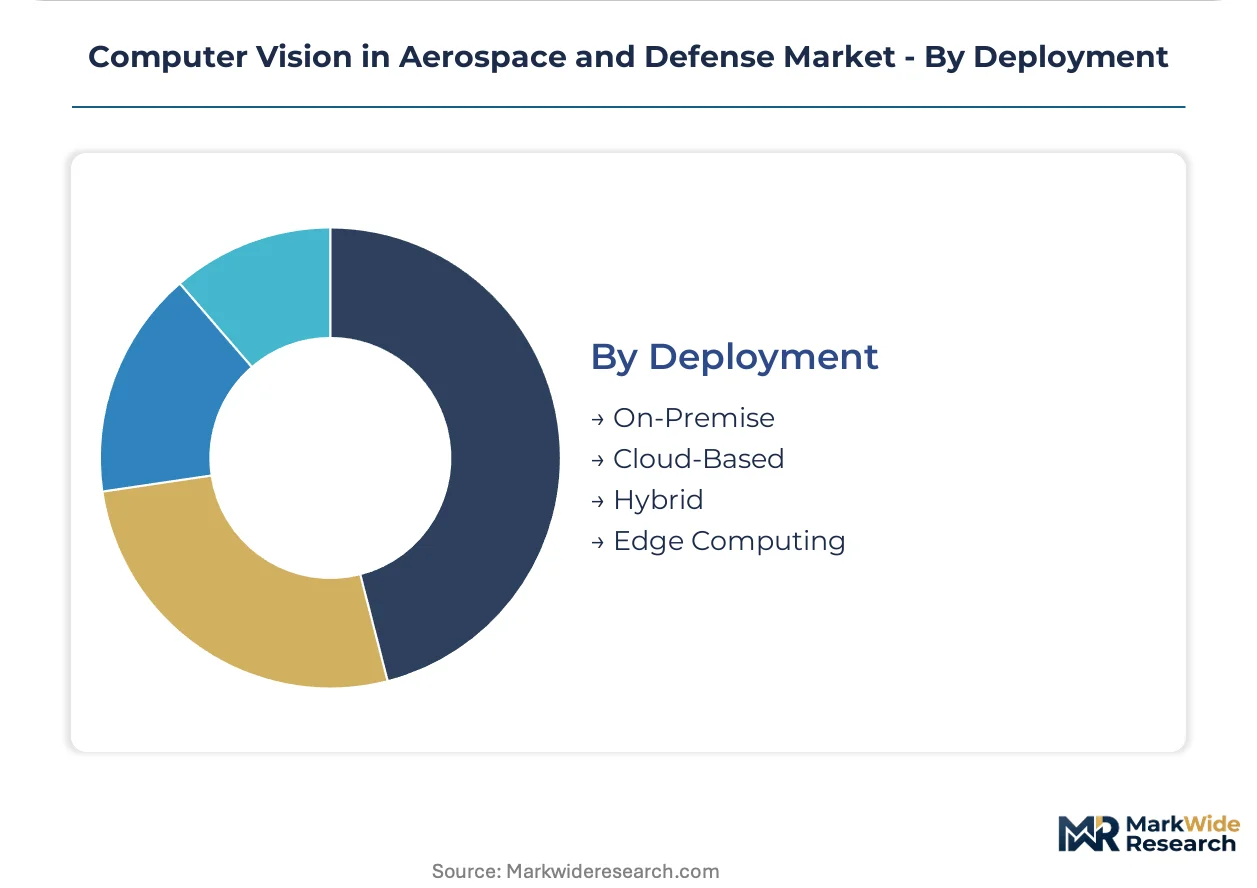
- Edge Computing:GPU-accelerated inference on power-constrained tactical devices enables real-time decision support in denied-communication scenarios. NVIDIA anchors high-performance edge deployments for unmanned systems, capturing concentrated margin pools from latency-sensitive contracts.
- Cloud-Based:Centralized model training and analytics services support non-time-critical applications including fleet-wide maintenance data aggregation and pattern-of-life analysis.
- On-Premise:Classified processing within secure facility air gaps satisfies operational security requirements for sensitive intelligence exploitation workflows.
- Hybrid:Federated learning architectures redistribute model training across dispersed tactical nodes, eliminating centralized data aggregation risks while preserving operational security.
Edge computing captures premium contract values; hybrid architectures gain share fastest as federated learning matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Israel channels more sovereign AI investment per capita into defense applications than any peer nation, while China concentrates procurement authority within state-owned defense conglomerates that internalize computer vision development.
United States
The Department of Defense compresses vendor qualification timelines through Responsible Artificial Intelligence Strategy compliance checkpoints. FAA beyond-visual-line-of-sight regulations intersect with defense airspace standards, creating dual-compliance burdens for contractors. Boston and Washington DC metro areas cluster autonomy software specialists serving prime contractor subcontracting networks.
China
State-owned aviation conglomerates internalize computer vision development for unmanned combat aerial platforms. MIIT standards for autonomous systems guide defense-adjacent technology transfer within controlled supply chains. Chengdu and Shenyang host integrated development facilities linking airframe manufacturing with embedded perception systems.
Israel
Border security escalations drive procurement of autonomous perimeter monitoring systems across military and homeland security agencies. The national cyber directorate imposes algorithmic testing protocols for AI-enabled strike recommendation systems. Tel Aviv and Haifa anchor dense ecosystems of autonomy software vendors spun from military research units.
Germany
Bundeswehr modernization programs fund sovereign AI capabilities for reconnaissance and target recognition payloads. EU AI Act conformity assessments mandate documented human oversight protocols for computer vision-enabled systems. Munich and Stuttgart concentrate defense electronics specialists integrating sensor fusion architectures for all-weather operations.
Australia
AUKUS defense technology sharing agreements accelerate access to allied autonomy stacks for maritime surveillance applications. The national defense strategy prioritizes sovereign AI capabilities for unmanned underwater and aerial platforms. Adelaide and Canberra host integration facilities linking foreign subsystem procurement with domestic airframe modification programs.
Computer Vision in Aerospace and Defense Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with software-defined autonomy stacks capturing recurring revenue streams while hardware integrators compete on program execution timelines. The vendor base concentrates around three strategic archetypes: GPU-accelerated inference platform providers, full-system prime contractors with embedded software divisions, and pure-play autonomy software specialists licensing across multiple airframes. Dominant competitive moves include hardware-software unbundling toward subscription analytics services and strategic partnerships bridging commercial semiconductor supply with defense qualification pathways.
Within the GPU-accelerated platform tier, NVIDIA anchors high-performance edge deployments for unmanned systems. Boeing exemplifies the integrated prime contractor model, sustaining long-term service agreements that fold computer vision modules into fleet modernization cycles. Shield AI occupies a specialist position, competing through proprietary autonomy software that extends hardware utility across aerial platforms.
| Leading Market Players |
|---|
| Anduril Industries |
| HRL Laboratories |
| NVIDIA |
| Iris Automation |
| Adarga |
| Boeing |
| Shield AI |
| Echodyne |
| Cognex Corporation |
| Others |
Pricing and Supply Chain Analysis
Performance-tier divergence between GPU-accelerated edge inference stacks and commodity image processing modules manifests in both contract values and supplier qualification burdens across defense procurement channels. Subscription-based analytics services for sovereign AI capabilities command premium pricing from military end users, while hardware-delivery contracts face cost compression from compressed vendor qualification timelines.
Pricing Analysis
Capacity additions in Taiwan and South Korea are reshaping price floors for high-performance inference chips while defense primes absorb geopolitical risk premiums through long-term service agreements. Three-tier pricing structure across mission-critical, dual-use, and commercial-grade autonomy stacks differentiates by Responsible Artificial Intelligence Strategy compliance depth and AS9100 certification status. Cost compression in commodity image processing hardware intensifies as Chinese state-owned aviation conglomerates internalize development. Government contractors exhibit highest price sensitivity due to dual FAA-military compliance documentation overhead; military service branches show lowest sensitivity where latency requirements in denied-communication scenarios dictate specification.
Supply Chain Analysis
Direct-to-prime contractor channels handle hyperscale military procurement volumes while research institution partnerships feed early-stage neuromorphic chip development. GPU fabrication concentrates in Taiwan, South Korea, and the United States; event-based vision sensor production anchors in Israel and Germany. Raw material dependencies span advanced semiconductor substrates, rare earth elements for electro-optical components, and synthetic aperture radar substrates. Single-source vulnerability in high-performance inference chip supply exposes defense primes to Taiwan Strait disruption scenarios. Distribution runs through AS9100-certified subsystem integrators into prime contractor subcontracting networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Responsible Artificial Intelligence Strategy functions as a regulatory compounder, accelerating budget allocation toward compliant autonomy stacks while filtering vendor qualification timelines through rigorous testing protocols.
For Market Incumbents: Extend software-defined targeting offerings through subscription analytics layers that convert capital expenditure contracts into recurring operational expenditure line items. Shield proprietary autonomy software across multiple aerial platforms to counter pure-play specialists licensing modular stacks. Invest in AS9100 certification pathways for non-aerospace software divisions to defend prime contractor subcontracting access against emerging subsystem integrators. For New Entrants and Emerging Players: Launch via research institution partnerships targeting Naval Research Laboratory neuromorphic processing programs and federated learning architecture pilots. Penetrate rotary-wing unmanned systems in India where mature computer vision payloads remain underdeveloped. Target sensor fusion convergence opportunities merging electro-optical and synthetic aperture radar streams for all-weather target recognition. For Investors and Strategic Acquirers: Consolidation pressure builds where embedded systems talent scarcity concentrates competitive advantage among firms with firmware optimization capabilities for power-constrained edge devices. Five-to-ten year viability favors pure-play autonomy software specialists with cross-platform licensing models over hardware-dependent integrators. Monitor GPU supply concentration disruptions as inflection indicator for prime contractor margin compression and alternative inference architecture adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Responsible AI Compliance Investment | Accelerates vendor qualification through United States Department of Defense testing protocol alignment. |
| Neuromorphic Chip Development Partnership | Reduces power consumption three orders of magnitude for sub-ten-kilogram autonomous platforms. |
| AS9100 Certification Pathway Completion | Opens prime contractor subcontracting tiers previously closed to non-aerospace software vendors. |
| Federated Learning Architecture Deployment | Eliminates centralized data aggregation risks while preserving operational security in contested environments. |
| Subscription Analytics Service Launch | Compresses vendor cash conversion cycles while extending customer lifetime value through continuous retraining. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with autonomy software engineers, defense procurement officers, prime contractor subsystem integrators, and FAA certification specialists with secondary validation against SEC filings of GPU platform providers, United States Department of Defense budget justification documents, EU AI Act regulatory texts, and customs trade data for semiconductor components. Bottom-up segment sizing triangulated against top-down defense expenditure allocation models.
Historical reference periods anchored the projection horizon through verified deployment data for unmanned systems and computer vision module integration timelines across military modernization cycles. Segmentation dimensions modeled encompass application type, technology maturity tier, end-user institutional category, and deployment architecture with sovereign AI capability requirements. CAGRs derived from defense procurement velocity indicators and capability iteration funding trajectories, incorporating edge computing contract value concentration and federated learning adoption curves as industry-specific inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under export control classification hardening and Taiwan Strait supply disruption scenarios. Periodic stress-testing of base assumptions is recommended given algorithmic interpretability limitations affecting lethal autonomous system engagement protocols and evolving dual-use technology transfer policies.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace & Defense
Aircraft Refueling Hose Market
Aerospace & Defense
Aircraft Oxygen System Market
Aerospace & Defense
Germany Satellite-Based Earth Observation Market
Aerospace & Defense
Single-Seat Gyrocopter Market
Aerospace & Defense
Global Commercial Avionics Systems Market
Aerospace & Defense
Aviation High Speed Motor Market
Aerospace & Defense
Military Radar Market
Aerospace & Defense
Howitzer Artillery System Market
Aerospace & Defense
Armored Personnel Carrier Market
Aerospace & Defense
Aircraft Generators Market
Aerospace & Defense
Manned Anti-Tank Guided Missile System Market
Aerospace & Defense
Carrier Rocket Market
Aerospace & Defense
Rocket Launchpad Market
Aerospace & Defense
Small Satellite Market
Aerospace & Defense
US Space Launch Services Market
Aerospace & Defense
Aerospace Turbojet Market