
 Satellite Attitude and Orbit Control System Market | 2026-2036
Satellite Attitude and Orbit Control System Market Size, Share, and Industry Trends Forecast 2026-2036
Satellite Attitude and Orbit Control System Market Analytics
Modular subsystem packaging is shifting buyer choice as satellite prime contractors unbundle attitude determination from orbit maneuvering functions. Northrop Grumman Corporation leverages its heritage in integrated space vehicle electronics to sustain bundled offerings for large government platforms. Blue Canyon Technologies LLC competes through standardized reaction wheel modules that occupy the smallsat tier with rapid-delivery configurations.
Satellite attitude and orbit control systems comprise sensors, actuators, and control algorithms that maintain spacecraft orientation and orbital position using reaction wheels generating momentum exchange torques up to several Newton-meters, thrusters providing delta-v for station-keeping, and gyroscopes measuring angular rates with arcsecond precision. The primary industrial purpose spans geostationary communications satellite pointing, Earth observation payload stability, and interplanetary trajectory correction. Reaction wheels dominate hardware value pools in geostationary platforms where continuous momentum management extends operational life, while hybrid systems integrating magnetic control with momentum wheels represent the fastest-expanding technology segment for low-Earth orbit constellations demanding mass-optimized solutions. Commercial satellites anchor end-user demand as Starlink-type deployments multiply unit volumes, though defense applications sustain premium pricing through radiation-hardened specifications.
FAA licensing requirements for commercial launch vehicles indirectly shape AOCS reliability standards through payload qualification protocols, while NASA's orbital debris mitigation guidelines mandate tighter pointing accuracy to prevent collision risks. The European Space Agency's Clean Space initiative extends similar constraints for member-state procurements, creating dual-certification burdens for suppliers serving transatlantic programs. Stakeholders must monitor evolving debris-tracking mandates that could force hardware redundancy upgrades before mid-decade fleet refreshes.
Market Dynamics
Constellation-scale deployment timelines are compressing supplier qualification cycles and forcing modular AOCS architectures that separate attitude sensing from propulsion functions. Prime contractors now source reaction wheel clusters and star tracker units through parallel procurement streams rather than integrated subsystem awards.
Growth Catalysts
- Space Force procurement acceleration:The US Space Force's rapid satellite replenishment mandates are refreshing legacy military platforms with precision pointing systems. Defense specifications sustain premium hardware volumes independent of commercial pricing pressure.
- Orbital debris mitigation frameworks:NASA's updated collision avoidance protocols mandate tighter pointing accuracy for new spacecraft. Operators must demonstrate active maneuvering capability to receive launch licenses.
- Reaction wheel miniaturization:Advances in ceramic bearing technology and hollow rotor designs are shrinking momentum wheel mass for smallsat form factors. This enables AOCS functionality on spacecraft below 50 kilograms.
Market Restraints
- Rare earth magnet supply concentration:Neodymium and dysprosium for torque rods and magnetic torquers source predominantly from Chinese processing facilities. Western satellite builders face input cost volatility and export control exposure.
- Radiation-hardening certification bottlenecks:Total ionizing dose qualification for space-grade electronics requires 18-24 month test cycles at specialized facilities. This timeline mismatch blocks rapid constellation iteration.
- Thruster propellant toxicity constraints:Hydrazine storage and handling regulations under REACH and OSHA impose ground infrastructure burdens. Green propellant alternatives remain unproven for high-impulse station-keeping maneuvers.
Strategic Opportunities
- On-orbit servicing integration:Refueling and life extension missions require cooperative rendezvous sensors and docking-optimized control algorithms. This creates hardware pull-through from emerging servicing operators.
- India's commercial launch access:ISRO's SSLV and private launch vehicle development is lowering orbital insertion costs for domestic constellation builders. Local AOCS suppliers can embed with vertically integrated satellite programs.
- Magnetorquer-cold gas hybridization:Combining electromagnetic attitude control with micro-thruster precision enables mass-optimized solutions for Earth observation swarms. Convergence of these technologies opens new smallsat tier pricing.
Industry Challenges
- Gyroscope assembly technician scarcity:Hemispherical resonator gyro and fiber optic gyro manufacturing requires specialized optical polishing and vacuum packaging skills. Training pipelines lag constellation workforce demands.
- ITAR compliance fragmentation:US export control classification for attitude determination units creates licensing friction for multinational satellite programs. Dual-use technology determinations delay contract execution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Satellite Attitude and Orbit Control System Market |
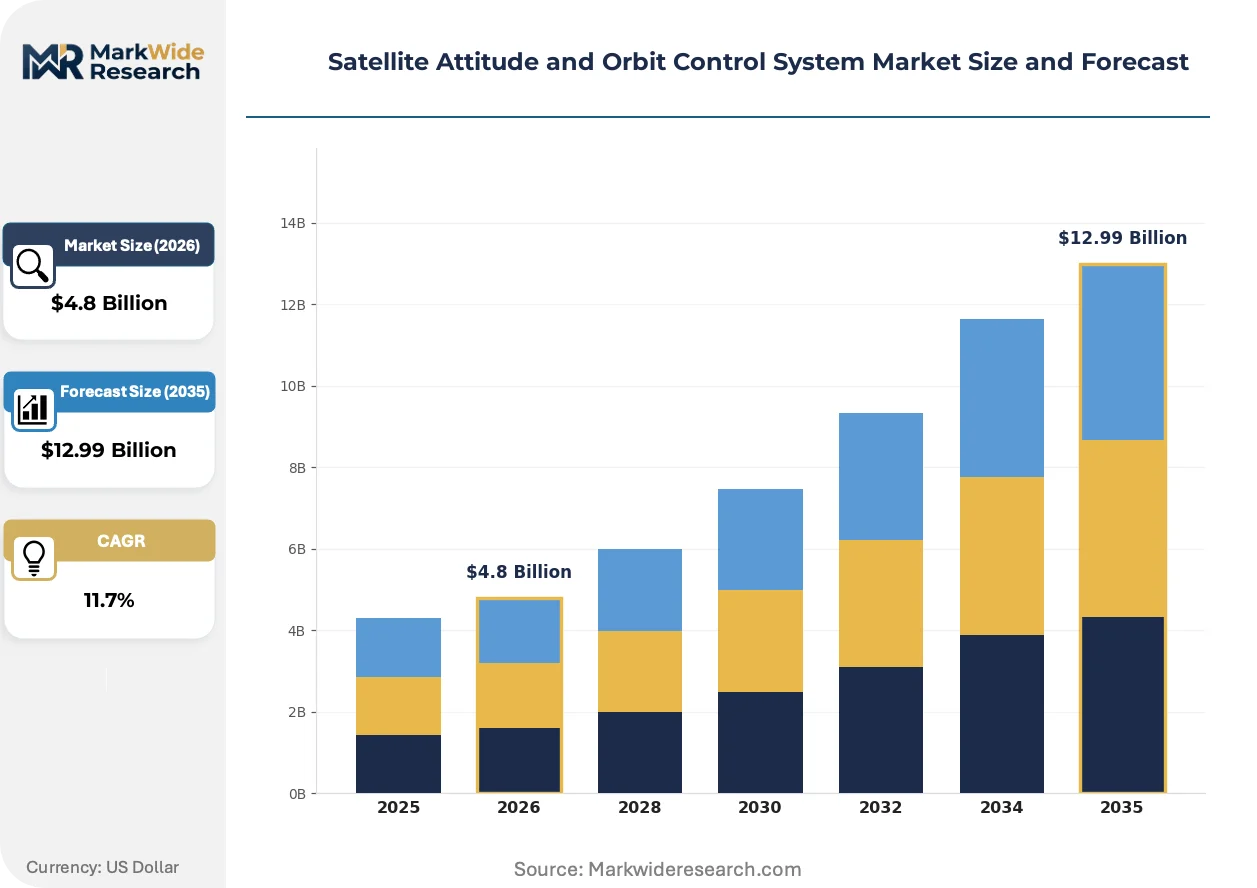
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reaction Wheels, Thrusters, Magnetometers, Gyroscopes End User: Commercial Satellites, Government Agencies, Research Institutions, Defense Technology: Magnetic Control, Momentum Wheels, Control Moment Gyroscopes, Hybrid Systems Application: Aerospace, Communication, Earth Observation, Scientific Exploration |
| Companies Covered | Northrop Grumman Corporation, Thales Group, Lockheed Martin Corporation, OHB System AG, Moog Inc., Airbus SE, BAE Systems PLC, Blue Canyon Technologies LLC, Honeywell International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Satellite Attitude and Orbit Control System Market Evolving Landscape
Software-defined control architectures are displacing hardware-fixed processing pipelines across satellite bus designs. Algorithmic momentum management now enables mission profile adaptation without physical actuator replacement.
Magnetic bearing reaction wheels are decentralizing momentum storage architectures previously centralized on large geostationary platforms. Smallsat constellation operators adopt distributed wheel arrays that tolerate single-unit failures without mission degradation. This topology is compressing supplier concentration in heritage momentum control vendors.
ESA's Clean Space initiative and NASA's orbital debris mitigation guidelines are tightening end-of-life disposal mandates for spacecraft. Operators must now demonstrate passivation and de-orbit capability during initial design reviews. Low-Earth orbit constellations face the steepest compliance ramps given their unit volumes and shorter orbital lifetimes.
Buyer consolidation among mega-constellation operators is compressing supplier negotiation leverage. SpaceX and Amazon's Kuiper now account for dominant procurement volumes, forcing AOCS vendors into long-term frame contracts with price-down schedules. European and Japanese satellite builders retain fragmented sourcing patterns with shorter commitment horizons.
Satellite Attitude and Orbit Control System Market Segmentation
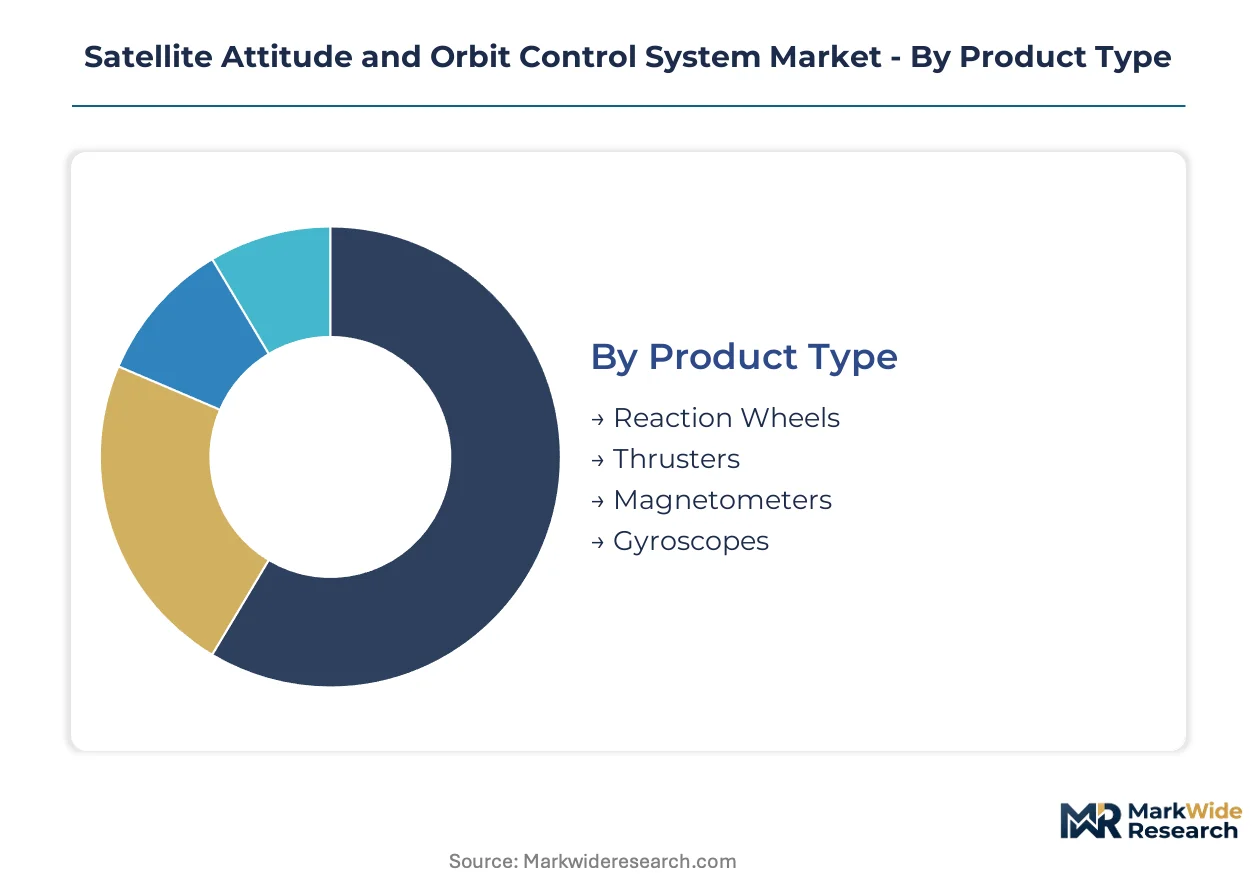
AOCS procurement patterns diverge sharply across hardware categories, end-use missions, and control architectures. Satellite prime contractors now unbundle subsystem sourcing, creating distinct competitive arenas for momentum storage versus sensing technologies.
Product Type:
Capital intensity peaks in momentum storage hardware, where precision machining and vacuum packaging drive unit economics.
- Reaction Wheels:Ceramic bearing assemblies and hollow rotor designs generate momentum exchange torques for continuous attitude adjustment. Geostationary communications platforms in the United States absorb dominant procurement volumes as Space Force refresh cycles extend operational life requirements.
- Thrusters:Chemical and electric propulsion systems deliver delta-v for station-keeping and orbital maneuvers. Earth observation constellations prioritize miniaturized cold gas units to satisfy mass constraints on smallsat buses.
- Magnetometers:Fluxgate and Hall-effect sensors measure local magnetic field vectors for attitude reference.
- Gyroscopes:Hemispherical resonator and fiber optic designs measure angular rates with arcsecond precision.
Reaction wheels absorb the bulk of installed capacity; thrusters are expanding most quickly as constellation operators prioritize maneuverability for collision avoidance.
End User:
Procurement scale concentrates in operators deploying multi-hundred-unit fleets, while specification stringency clusters in national security applications.
- Commercial Satellites:Starlink-type mega-constellations drive volume demand for standardized, radiation-tolerant components. Frame contracts with price-down schedules compress supplier margins as SpaceX and Amazon's Kuiper consolidate procurement leverage.
- Government Agencies:NASA and ESA science missions sustain premium pricing for custom pointing systems. Mars sample return and deep space observatories require fault-tolerant architectures with extended operational lifetimes.
- Research Institutions:University-led CubeSat programs source commercial off-the-shelf AOCS modules.
- Defense:US Space Force and allied military programs mandate ITAR-controlled components with proven flight heritage.
Commercial satellites command the greatest unit volumes; defense applications sustain the steepest pricing premiums through hardened specifications.
Technology:
Control architecture selection hinges on mission duration, pointing accuracy requirements, and permissible mass allocation.
- Momentum Wheels:Conventional brushed or brushless DC motor designs dominate geostationary platforms where continuous momentum management extends service life. FAA payload qualification protocols indirectly enforce reliability standards through launch licensing.
- Hybrid Systems:Integrated magnetic torquer and reaction wheel configurations optimize mass for low-Earth orbit swarms. European constellation builders under ESA Clean Space mandates favor these architectures for end-of-life passivation compliance.
- Magnetic Control:Electromagnetic torque rods provide coarse attitude adjustment without consumables.
- Control Moment Gyroscopes:High-torque momentum exchange devices enable rapid slew maneuvers for agile imaging.
Momentum wheels retain the largest installed base; hybrid systems are gaining share fastest as smallsat operators seek mass-optimized solutions.
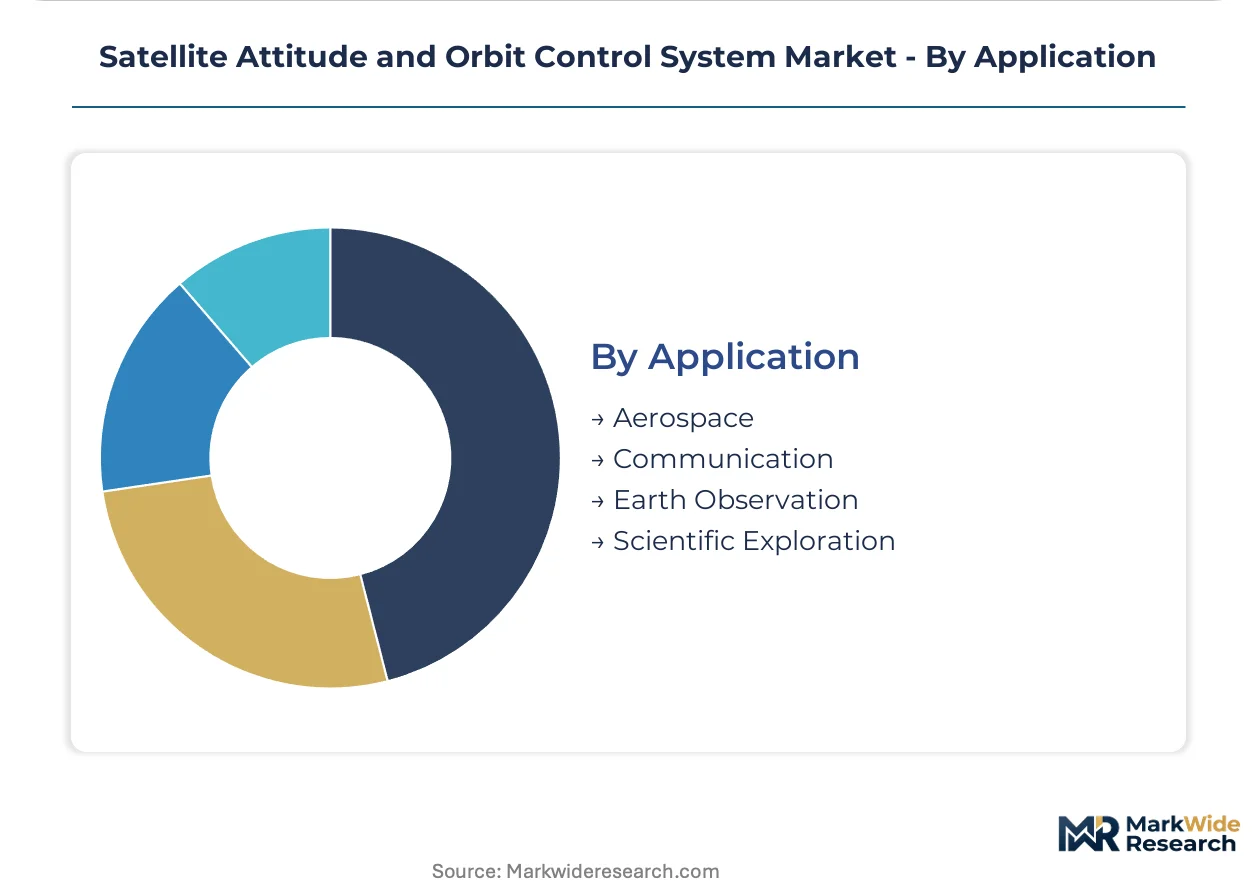
Application:
Mission-criticality varies across orbital regimes, with geostationary assets demanding highest reliability and low-Earth orbit platforms prioritizing cost minimization.
- Communication:Geostationary relay satellites require sub-arcminute pointing stability to maintain link budgets. US-based operators face NASA orbital debris mitigation mandates tightening maneuvering capability demonstrations.
- Earth Observation:Synthetic aperture radar and optical imaging platforms need precise attitude knowledge for geolocation accuracy. Japanese and European builders source star tracker and gyroscope clusters through fragmented procurement patterns.
- Aerospace:Crewed spacecraft and cargo vehicles employ redundant control channels for safety-critical operations.
- Scientific Exploration:Interplanetary probes and space telescopes demand ultra-stable pointing for long-exposure observations.
Communication applications anchor revenue concentration; Earth observation is climbing the fastest as commercial remote sensing constellations proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in established aerospace clusters while consumption spreads across emerging launch markets. The United States dominates hardware manufacturing through Space Force procurement and commercial constellation buildouts. European and Asian markets are expanding ground infrastructure and indigenous satellite programs.
United States
Space Force rapid replenishment mandates and Starlink-scale constellation deployments drive precision pointing system demand. FAA licensing requirements for commercial launch vehicles enforce payload qualification protocols that cascade into AOCS reliability standards. Colorado and California aerospace clusters host prime contractors unbundling attitude determination from propulsion functions.
Germany
OHB System AG anchors European momentum wheel manufacturing for institutional science missions. ESA Clean Space initiative debris mitigation guidelines mandate tighter end-of-life disposal capabilities for member-state procurements. Bavaria's satellite manufacturing corridor supplies hybrid magnetic control systems for Earth observation swarms.
France
Thales Group and Airbus SE sustain premium pricing for geostationary platform pointing systems through flight heritage advantages. ANSM export control classifications create licensing friction for attitude determination units in multinational programs. Toulouse space cluster concentrates integrated AOCS development for telecommunications satellites.
Japan
METI-funded smallsat programs expand domestic reaction wheel demand as constellation operators proliferate. JAXA orbital debris guidelines align with NASA protocols, tightening maneuvering capability demonstrations for launch authorization. Kyushu manufacturing bases produce ceramic bearing assemblies for miniaturized momentum wheels.
India
ISRO SSLV and private launch vehicle development lower orbital insertion costs for domestic constellation builders. BIS certification requirements for space-grade electronics create qualification pathways for local AOCS suppliers. Bengaluru satellite manufacturing hub embeds attitude control modules with vertically integrated smallsat programs.
Satellite Attitude and Orbit Control System Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across distinct technology tiers. Market structure fragments between heritage defense primes sustaining bundled subsystem offerings and modular component vendors capturing constellation-scale volumes. Strategic archetypes include integrated space vehicle electronics providers, standardized reaction wheel specialists, and radiation-hardened sensing technology developers. Competitive moves center on unbundling procurement streams and compressing qualification cycles for rapid-delivery configurations.
Within the heritage prime tier, Northrop Grumman Corporation and Lockheed Martin Corporation exemplify bundled platform integration strategies for large government satellites. Blue Canyon Technologies LLC occupies the standardized module position for smallsat rapid-delivery configurations. European institutional fabricants Thales Group and Airbus SE anchor geostationary precision pointing markets through accumulated flight heritage.
| Leading Market Players |
|---|
| Northrop Grumman Corporation |
| Thales Group |
| Lockheed Martin Corporation |
| OHB System AG |
| Moog Inc. |
| Airbus SE |
| BAE Systems PLC |
| Blue Canyon Technologies LLC |
| Honeywell International Inc. |
| Others |
Value Network & Pricing Analysis
ESA's Clean Space initiative gates qualified supply and premium-tier pricing access for AOCS vendors, as debris mitigation compliance separates certified suppliers from commodity competitors while constellation operators demand volume discounts that compress margins across reaction wheel and sensor categories.
Pricing Analysis
Margin tightening in the smallsat tier reflects SpaceX and Amazon Kuiper's consolidated procurement leverage. Three-tier pricing structure across radiation-hardened premium, ITAR-controlled standard, and commercial off-the-shelf economy levels dominates contract architecture. Price differentiation rests on flight heritage certification and volume scale, with mega-constellation frame contracts forcing annual price-down schedules. Research institutions and university CubeSat programs exhibit highest price sensitivity, while defense applications sustain premium tolerance through hardened specification requirements.
Supply Chain Analysis
Dual-sourcing mandates from prime contractors require AOCS vendors to qualify backup suppliers for ceramic bearing assemblies and hollow rotor components. Manufacturing concentrates in the United States, Germany, and Japan, with rare earth magnet processing anchored in Chinese facilities. Raw material dependencies include neodymium and dysprosium for torque rods, high-purity ceramics for bearings, and radiation-hardened semiconductors. Single-source vulnerability in rare earth supply chains creates tariff exposure and export control risk. Distribution runs through prime contractor integration facilities and direct constellation operator procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where reaction wheel manufacturers pursue captive supply of ceramic bearing assemblies to secure margin control and qualification timeline compression.
For Market Incumbents: Deepen backward integration into ceramic bearing production to offset rare earth supply volatility and capture value from hollow rotor machining. Lockheed Martin Corporation and Northrop Grumman Corporation should accelerate in-house production of radiation-hardened control electronics before ITAR compliance fragmentation worsens. Consolidate supplier relationships with constellation operators through multi-year frame contracts that embed price-down schedules defensible through manufacturing scale. For New Entrants and Emerging Players: University-led CubeSat programs represent an underserved buyer archetype with fragmented sourcing patterns and limited flight heritage requirements. India's domestic constellation builders under ISRO's SSLV access expansion offer the most penetrable geography for modular AOCS module suppliers. Establish go-to-market partnerships with Bengaluru satellite manufacturing hubs to embed attitude control units with vertically integrated smallsat programs before local certification pathways mature. For Investors and Strategic Acquirers: First-mover qualification under NASA's updated orbital debris mitigation guidelines is the leading indicator that vendor positioning will crystallize before mid-decade fleet refreshes. Acquisition targets should feature hybrid magnetic control IP and existing ESA Clean Space certification. Watch for gyroscope assembly technician scarcity signals in Colorado and California aerospace clusters as the inflection point for automated manufacturing investment.| Strategic Initiative | Industry Significance |
|---|---|
| Reaction Wheel Miniaturization | Ceramic bearing advances enable AOCS functionality on spacecraft below 50 kilograms. |
| Software-Defined Control Architecture | Algorithmic momentum management displaces hardware-fixed processing pipelines across satellite bus designs. |
| Magnetorquer-Cold Gas Hybridization | Mass-optimized solutions for Earth observation swarms open new smallsat tier pricing. |
| On-Orbit Servicing Integration | Cooperative rendezvous sensors create hardware pull-through from emerging servicing operators. |
| Radiation-Hardening Certification Investment | Total ionizing dose qualification timelines determine constellation iteration speed. |
Research Methodology
SEC filings, ESA procurement databases, and FAA commercial launch licensing records formed the secondary backbone for this analysis. Primary interviews with satellite prime contractor procurement officers, AOCS subsystem engineering directors, constellation operator mission planners, and radiation-hardened electronics certification specialists combined with secondary validation. Bottom-up and top-down triangulation reconciled unit volume assumptions from reaction wheel shipment data with top-down constellation deployment schedules.
Bottom-up modeling aggregated segment-level unit economics across momentum storage, sensing, and propulsion hardware categories. Segmentation dimensions included product type, end-user mission profile, control architecture technology, and orbital application regime. CAGRs were derived from fitted growth curves calibrated against historical qualification cycle compression and constellation deployment acceleration. Industry-specific forecast inputs incorporated Space Force replenishment mandates and ESA Clean Space compliance ramps.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to rare earth export control escalations and gyroscope technician pipeline constraints. Deviation in NASA debris mitigation guideline enforcement timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Healthcare Satellite Connectivity Market
Satellite
North America Remote Sensing Services Market
Satellite
US Satellite Connectivity Market
Satellite
Italy Satellite Imagery Services Market
Satellite
Russia Satellite Connectivity Market
Satellite
North America Military Satellite Market
Satellite
Nanosatellite Market
Satellite
Asia-Pacific Satellite Bus Market
Satellite
Canada Satellite Connectivity Market
Satellite
Satellite Antenna Market
Satellite
Latin America Satellite Connectivity Market
Satellite
Reusable Satellite Launch Vehicle (RSLV) Market
Satellite
Medium and Large Satellite Market
Satellite
Communication Satellite Launch Services Market
Satellite
High Altitude Pseudo Satellites Market
Satellite
United Kingdom Satellite Communications Market