
 Military Tank Container Market | 2026-2036
Military Tank Container Market Size, Share, and Industry Trends Forecast 2026-2036
Military Tank Container Market Foresight
European steel fabricators and German pressure vessel specialists is expanding output of MIL-STD-certified tank modules to address NATO's consolidated fuel distribution requirements. WEW Container System GmbH leverages decades of Bundeswehr contracting experience to sustain long-term platform supply relationships. Klinge Corporation dominates refrigerated and hazardous-material container engineering for US military logistics. Krampitz Tanksystem GmbH specializes in custom tank configurations for expeditionary force support across varied terrain conditions.
A military tank container is a rigid, pressure-rated intermodal vessel engineered to ISO frame dimensions, typically constructed from corten steel or aluminum alloy with multi-layer insulation and baffling systems, designed for the transport of liquids, fuels, or sensitive cargo across road, rail, sea, and air modalities without intermediate handling. Fuel tank configurations anchor current procurement volumes due to persistent operational energy requirements in theater logistics, while composite material segments are gaining traction where weight reduction directly impacts airlift payload economics. Road and rail delivery modes occupy the majority of existing fleet deployments, though naval transport modules command premium engineering margins due to saltwater corrosion resistance and stack stability specifications.
The US Defense Logistics Agency enforces MIL-STD-810 environmental testing and MIL-STD-461 electromagnetic compatibility standards that filter non-compliant suppliers from defense procurement channels. Germany's KBA and the EU Pressure Equipment Directive jointly govern transportable tank certification, creating a dual-compliance burden for cross-border NATO supply contracts. Stakeholders must monitor evolving interoperability mandates between US DoD specifications and emerging EU defense procurement harmonization frameworks.
Market Dynamics
Defense procurement consolidation across NATO member states is compressing supplier qualification timelines while elevating MIL-STD and ISO intermodal compliance thresholds as non-negotiable gatekeepers for contract participation.
Growth Catalysts
- Allied Interoperability Mandates:NATO's consolidated fuel distribution frameworks require standardized tank modules that bridge US DoD specifications with EU Pressure Equipment Directive compliance, forcing cross-certification investments that lock in long-term supplier relationships.
- Forward Deployment Infrastructure:Poland's eastern flank positioning and Germany's logistics hub role generate replacement cycles for expeditionary-capable tank systems designed for rapid rail-to-road transfer without intermediate pumping.
- Composite Material Adoption:Aluminum alloy and advanced polymer insulation layers reduce airlift payload penalties, enabling strategic mobility planners to prioritize weight-optimized modules for rapid reaction force deployments.
Market Restraints
- Corten Steel Price Volatility:Specialty corrosion-resistant steel inputs face supply concentration from limited European mill capacity, squeezing fabrication margins for pressure-rated vessel construction.
- Dual-Certification Burden:Germany's KBA transportable tank requirements叠加 US MIL-STD-810 environmental testing create parallel compliance tracks that extend qualification periods and raise fixed compliance costs.
- Rigid ISO Dimension Constraints:Fixed frame specifications limit design innovation for non-standard cargo profiles, capping premium pricing potential for specialized expeditionary configurations.
Strategic Opportunities
- Multi-Modal Naval Modules:Saltwater corrosion-resistant stack-stable tank systems command premium engineering margins as Pacific theater maritime logistics requirements expand beyond traditional Atlantic-centric supply patterns.
- Hazardous Material Integration:Refrigerated and chemical-agent-rated container platforms address emerging NATO CBRN logistics protocols that extend tank container utility beyond hydrocarbon transport.
- EU Defense Procurement Harmonization:Emerging EU-wide defense procurement frameworks promise to collapse bilateral certification requirements into single-market approvals, reducing cross-border supply friction for certified fabricators.
Industry Challenges
- Electromagnetic Compatibility Testing:MIL-STD-461 certification for shielded tank control systems requires specialized anechoic chamber investments that smaller fabricators struggle to amortize across limited defense contract volumes.
- Skilled Pressure Vessel Welding Shortage:Bundeswehr-contracted suppliers face recruitment constraints for ASME Section IX-certified welders capable of multi-pass corten steel fabrication under military quality assurance protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Tank Container Market |
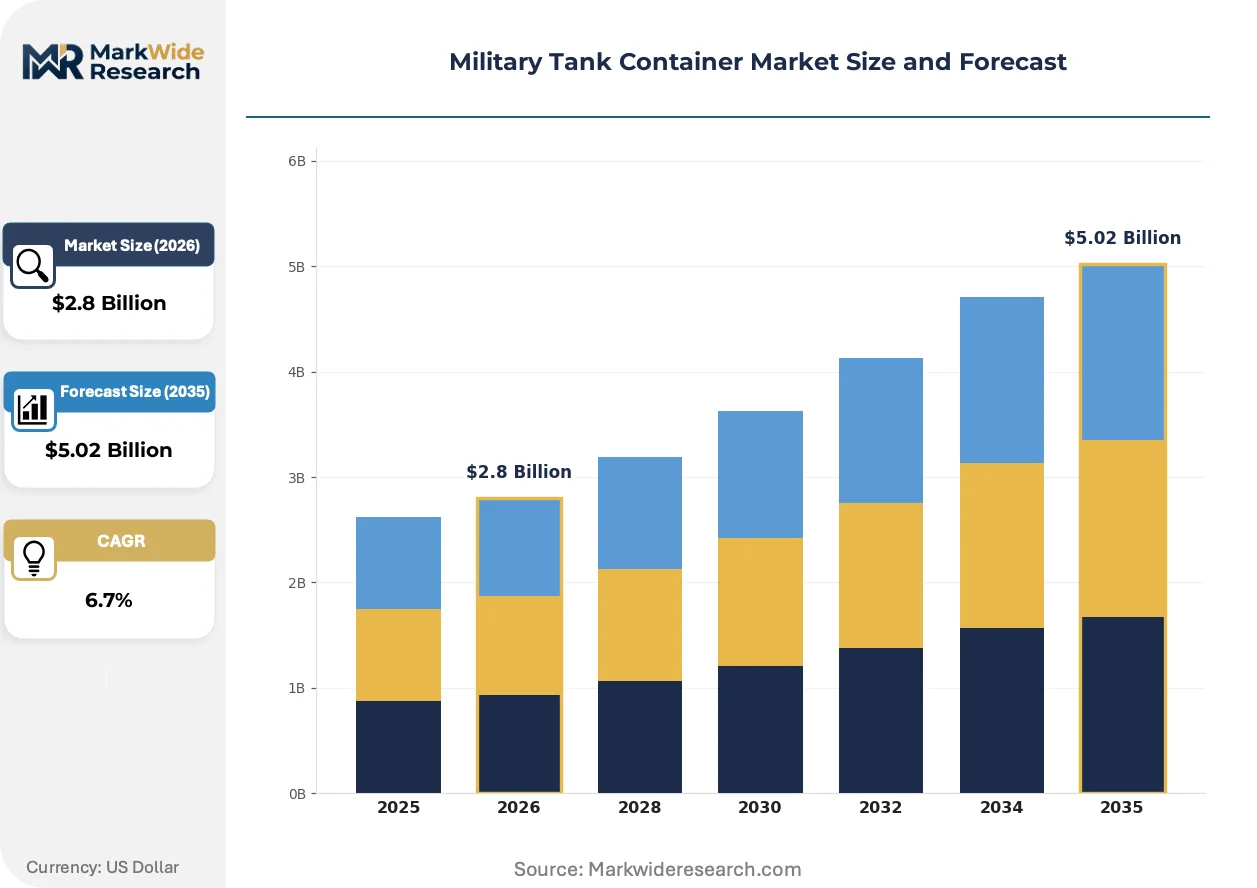
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fuel Tank, Water Tank, Ammunition Tank, Oil Tank Material: Steel, Aluminum, Composite, Plastic Delivery Mode: Road Transport, Rail Transport, Air Transport, Naval Transport End User: Military Organizations, Defense Contractors, Logistics Providers, Government Agencies |
| Companies Covered | WEW Container System GmbH, Klinge Corporation, Krampitz Tanksystem GmbH, SEA BOX, Inc., AMA S.p.A, ANCORA Sp. Z o. o., VARIEL, a. s., Eurotainer SA, LAVA Engineering Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Tank Container Market Shifts & Advancements
Active standardization of intermodal interfaces is compressing the gap between commercial ISO container economics and military-specific ruggedization requirements, enabling dual-use procurement strategies that dilute pure defense premium pricing.
Smart telemetry integration is unifying tank condition monitoring with automated logistics management systems. US Defense Logistics Agency procurement officers now specify embedded pressure, temperature, and location sensors as baseline requirements for new fuel tank contracts. This convergence is unifying previously separate container hardware and information system procurement budgets, reshaping vendor qualification criteria toward dual-competency suppliers.
Germany's KBA has tightened transportable tank inspection intervals for cross-border NATO supply movements, mandating enhanced documentation trails that extend from fabrication through operational deployment. German pressure vessel specialists have responded by embedding blockchain-traceable material certification into production workflows, shifting competitive advantage toward fabricators with integrated quality assurance digitization.
Expeditionary force commanders now specify rapid-deployment tank modules that collapse setup time from hours to minutes, displacing legacy fixed-site fuel farms in forward operating base planning. Polish and Baltic state defense ministries have accelerated procurement of self-contained pump-and-filter systems that integrate directly with tank container frames, compressing vendor selection criteria toward turnkey subsystem providers rather than pure vessel fabricators.
Military Tank Container Market Segmentation
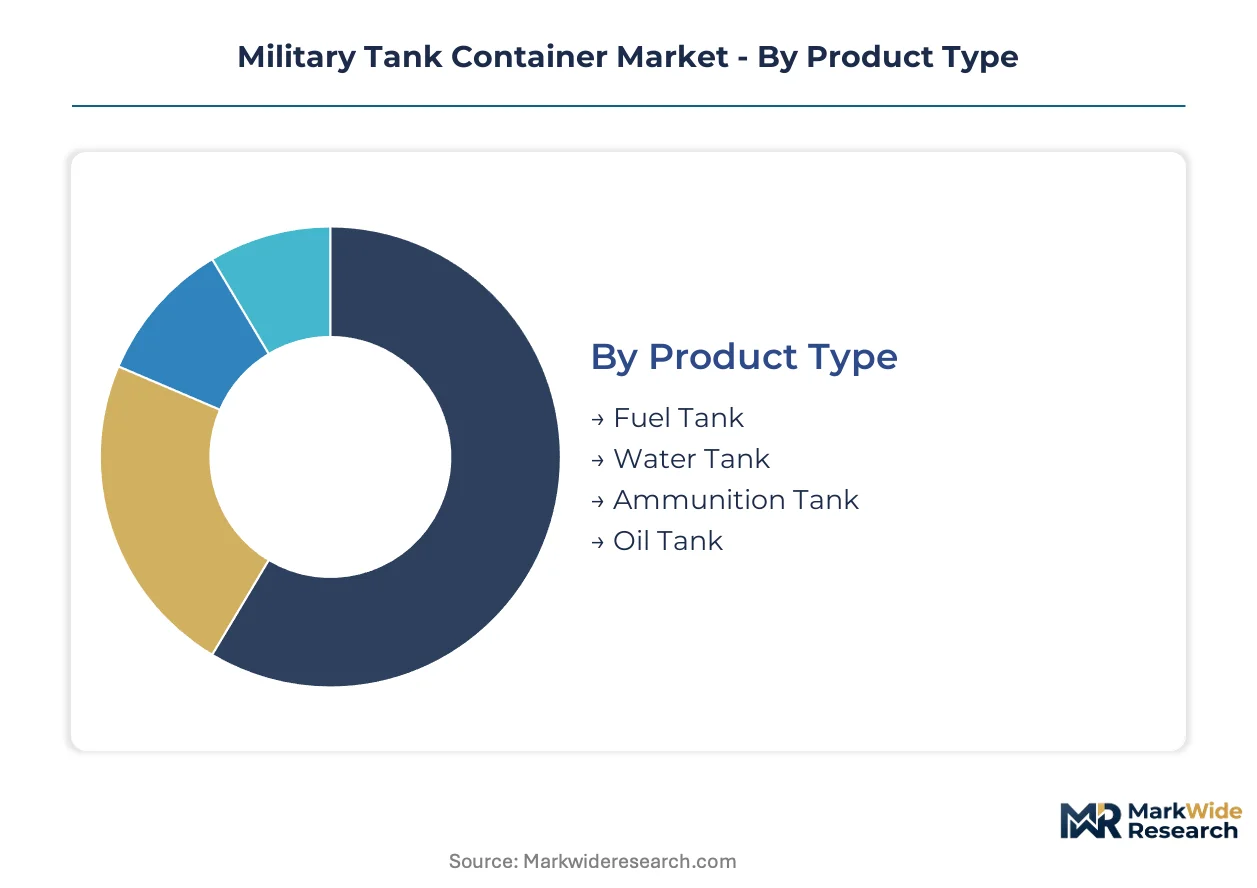
Military tank container procurement splits along four intersecting dimensions that determine capital allocation, compliance burden, and operational deployment profiles. Each segmentation layer carries distinct engineering specifications and certification requirements that filter supplier participation.
Product Type:
Fuel tank configurations demand the heaviest upfront capital investment due to pressure-rated vessel construction, multi-layer baffling systems, and MIL-STD-810 environmental testing protocols.
- Fuel Tank:Corten steel or aluminum alloy vessels engineered for hydrocarbon transport with integrated pump-and-filter subsystems. Polish and Baltic defense ministries are accelerating procurement of self-contained expeditionary modules that compress setup time from hours to minutes at forward operating bases.
- Water Tank:Stainless steel or polymer-lined containers with potable-grade certification and temperature insulation layers. German KBA transportable tank requirements叠加 enhanced documentation trails for cross-border NATO supply movements, embedding blockchain-traceable material certification into production workflows.
- Ammunition Tank:Blast-resistant configurations with specialized baffling to prevent cargo shift during multi-modal transfer.
- Oil Tank:Lubricant and hydraulic fluid variants with viscosity-optimized discharge systems for arctic to desert temperature ranges.
Fuel tank configurations absorb the bulk of installed capacity; water tank segments are expanding most quickly as expeditionary force planners prioritize potable logistics independence.
Material:
Material selection pivots on the weight-versus-durability trade-off that shapes airlift economics and corrosion resistance in saltwater environments.
- Steel:Corten and carbon steel grades dominate pressure-rated vessel fabrication for fuel and hazardous cargo applications. European mill capacity constraints squeeze fabrication margins, with specialty corrosion-resistant inputs concentrated among limited German and Polish suppliers.
- Aluminum:Alloy configurations reduce airlift payload penalties by 30-40% compared to steel equivalents, enabling strategic mobility planners to prioritize weight-optimized modules for rapid reaction force deployments across Pacific theater requirements.
- Composite:Advanced polymer insulation layers with embedded sensor arrays for smart telemetry integration.
- Plastic:Rotationally molded polyethylene for water and non-hazardous liquid transport in low-threat environments.
Steel retains the dominant share of active fleet composition; aluminum is climbing the fastest as composite material adoption accelerates under airlift payload optimization mandates.
Delivery Mode:
Delivery modality determines stack stability specifications, corrosion resistance requirements, and intermodal transfer interface standards.
- Road Transport:ISO frame dimensions with twist-lock corner castings for truck chassis mounting and rapid rail-to-road transfer without intermediate pumping. Road and rail modalities occupy the majority of existing NATO fleet deployments across Germany's logistics hub infrastructure.
- Rail Transport:Enhanced stack-load ratings and buffer coupling compatibility for European and North American gauge networks.
- Air Transport:Weight-optimized aluminum and composite modules certified for military cargo aircraft pallet constraints. US Defense Logistics Agency procurement officers now specify embedded pressure, temperature, and location sensors as baseline requirements for strategic airlift tank contracts.
- Naval Transport:Saltwater corrosion-resistant coatings and stack-stable engineering for maritime logistics requirements expanding beyond traditional Atlantic-centric supply patterns.
Road transport anchors current procurement volumes; naval transport modules command the steepest expansion trajectory as Pacific theater maritime logistics requirements reshape NATO supply patterns.
End User:
End-user segmentation reflects divergent procurement authority structures, budget cycles, and technical specification authority across defense organizations.
- Military Organizations:National armed forces with direct platform ownership and theater logistics responsibility. US DoD and Bundeswehr contracting channels enforce MIL-STD and KBA dual-compliance thresholds that lock in long-term supplier relationships.
- Defense Contractors:Prime systems integrators procuring tank modules as subsystems for larger vehicle or base infrastructure programs.
- Logistics Providers:Third-party defense logistics operators managing NATO consolidated fuel distribution frameworks.
- Government Agencies:Civil defense, emergency response, and humanitarian aid organizations with modified civilian-adjacent certification requirements.
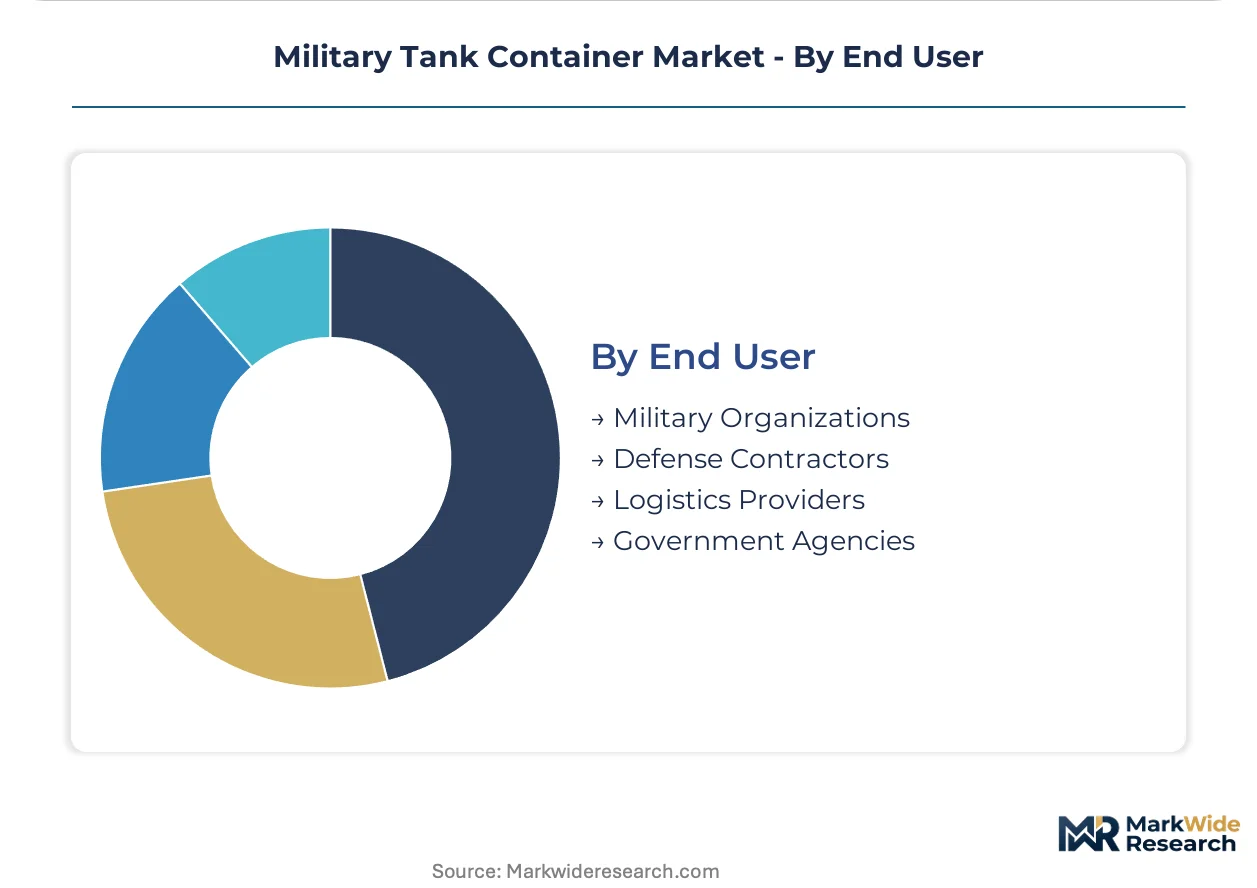
Military organizations control the dominant procurement volume; defense contractors are gaining share fastest as prime integrators consolidate subsystem sourcing under turnkey platform contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European corten steel mills in Germany and Poland supply the specialty corrosion-resistant alloys that anchor NATO-compliant pressure vessel fabrication. Defense logistics procurement concentrates where forward deployment infrastructure intersects with established fabrication clusters.
United States
The US Defense Logistics Agency drives procurement through MIL-STD-810 and MIL-STD-461 certification requirements that filter supplier participation. The Pentagon's ISO-standard intermodal platform mandates reshape contracting channels toward dual-competency vendors. Klinge Corporation anchors the refrigerated and hazardous-material container engineering segment from its US base.
Germany
Bundeswehr fuel distribution frameworks and KBA transportable tank certification create dual-compliance burdens for cross-border NATO contracts. The EU Pressure Equipment Directive叠加 German national requirements extend qualification timelines. WEW Container System GmbH and Krampitz Tanksystem GmbH leverage decades of defense contracting relationships from fabrication clusters in North Rhine-Westphalia and Lower Saxony.
Poland
Eastern flank positioning generates replacement cycles for expeditionary-capable tank systems with rapid rail-to-road transfer capability. ANCORA Sp. Z o. o. represents Polish pressure vessel specialists responding to accelerated procurement timelines. Baltic state interoperability exercises drive demand for self-contained pump-and-filter modules.
United Kingdom
Strategic airlift payload optimization mandates from RAF Brize Norton logistics planners favor aluminum alloy configurations. SEA BOX, Inc. maintains UK market presence through ISO-frame modular systems. The Ministry of Defence's emphasis on multi-modal deployability compresses vendor selection toward integrated subsystem providers.
Czech Republic
VARIEL, a. s. exemplifies Central European fabricators serving NATO consolidated fuel distribution requirements. The country's industrial base supports ASME Section IX-certified welding capacity for corten steel pressure vessels. Cross-border supply movements into Germany face KBA-mandated inspection intervals that favor fabricators with digitized quality assurance workflows.
Military Tank Container Market Competitive Landscape
Global majors compete with regional champions across certification competency, with German and US specialists dominating MIL-STD and KBA dual-compliance channels while Central European fabricators capture NATO interoperability-driven replacement cycles. The vendor structure tiers into pressure vessel specialists with Bundeswehr heritage, refrigerated container engineers with US DoD relationships, and expeditionary subsystem integrators responding to Polish and Baltic procurement acceleration. Strategic moves concentrate on blockchain-traceable material certification adoption and smart telemetry integration that unifies hardware with automated logistics management systems.
Within the German pressure vessel specialist tier, WEW Container System GmbH and Krampitz Tanksystem GmbH occupy positions sustained by long-term Bundeswehr contracting relationships. Klinge Corporation represents the US-based refrigerated and hazardous-material engineering archetype. These three anchors illustrate how defense procurement consolidation compresses qualification timelines toward fabricators with integrated quality assurance digitization and multi-modal certification portfolios spanning both sides of the Atlantic.
| Leading Market Players |
|---|
| WEW Container System GmbH |
| Klinge Corporation |
| Krampitz Tanksystem GmbH |
| SEA BOX, Inc. |
| AMA S.p.A |
| ANCORA Sp. Z o. o. |
| VARIEL, a. s. |
| Eurotainer SA |
| LAVA Engineering Company |
| Others |
Supply & Pricing Matrix
Smart telemetry integration is compressing cost economics for tank module fabricators while concentrating supply relationships around dual-competency vendors capable of unifying hardware with automated logistics systems. This technology shift simultaneously elevates fixed certification investments and locks in long-term procurement channels for integrated quality assurance providers.
Pricing Analysis
Warranty and field-service bundling separates premium-tier suppliers from unbundled transactional vendors in defense tank container procurement. Three-tier pricing structure across premium, standard, and economy levels reflects MIL-STD-810 certification grade and embedded sensor array sophistication. Cost compression in standard-tier steel configurations is intensifying because European corten mill capacity constraints squeeze fabrication margins. Third-party logistics providers exhibit the highest price sensitivity due to thin operating margins on NATO fuel distribution contracts.
Supply Chain Analysis
Dual-sourcing requirements mandated by the US Defense Logistics Agency and Germany's KBA compel prime contractors to qualify multiple pressure vessel fabricators across Germany, Poland, and the Czech Republic. Raw material supply draws from specialty European corten steel mills, aluminum alloy producers, and advanced polymer insulation layer manufacturers. Single-source vulnerability concentrates around limited ASME Section IX-certified welding capacity for multi-pass corten fabrication. Distribution runs through defense prime integrators and NATO consolidated fuel distribution frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into specialty steel supply and captive sensor subsystem production defines the vertical-integration race among military tank container specialists. Control over ASME-certified welding capacity and blockchain-traceable material certification workflows represents the decisive upstream lever.
For Market Incumbents: Deploy blockchain-traceable material certification workflows to defend Bundeswehr and US DoD contracting positions against emerging Central European fabricators. Add pressure vessel welding capacity in Poland's emerging industrial clusters to offset recruitment constraints for ASME Section IX-certified labor in Germany. Lock in long-term corten steel offtake agreements before European mill capacity tightens further. For New Entrants and Emerging Players: Enter via hazardous-material-rated container platforms addressing NATO CBRN logistics protocols, the most penetrable segment outside incumbent hydrocarbon transport dominance. Target Polish and Baltic defense ministries accelerating procurement of self-contained expeditionary modules with rapid deployment specifications. Pursue joint development agreements with prime systems integrators rather than direct military contracting channels. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by defense primes consolidating subsystem sourcing under turnkey platform contracts. Five-to-ten year viability hinges on dual-compliance competency spanning MIL-STD and KBA certification channels. Monitor EU defense procurement harmonization frameworks as the critical inflection signal for cross-border supply friction reduction.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Telemetry Integration | Embedded sensor arrays unify tank hardware with US Defense Logistics Agency automated logistics management systems. |
| Blockchain-Traceable Certification | German KBA-mandated documentation trails shift competitive advantage toward digitized quality assurance fabricators. |
| Composite Material Adoption | Aluminum alloy configurations reduce airlift payload penalties for Pacific theater rapid reaction force deployments. |
| Multi-Modal Naval Module Development | Saltwater corrosion-resistant engineering captures premium margins from Pacific maritime logistics expansion. |
| ASME Welding Capacity Expansion | Captive ASME Section IX-certified labor pools address Bundeswehr contractor recruitment constraints. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this military tank container market assessment. Primary interviews with defense procurement officers, pressure vessel fabrication executives, NATO logistics coordinators, and ASME-certified welding specialists combined with secondary validation from US DoD contract announcements, KBA transportable tank registries, EU Pressure Equipment Directive submissions, and Bundeswehr equipment procurement databases. Bottom-up tank module shipment tallies and top-down defense logistics budget allocations underwent rigorous triangulation.
Data-stream reconciliation across product type, material grade, delivery modality, and end-user segmentation dimensions shaped the analytical framework across the projection horizon. CAGRs derived from weighted average of historical replacement cycle analysis and forward deployment infrastructure investment trajectories. Forecast inputs incorporated NATO interoperability exercise frequency and Pacific theater maritime logistics requirement shifts.
Forecast precision tightens around the base case; tail outcomes carry wider variance under corten steel supply disruption or accelerated EU defense procurement harmonization scenarios. Deviation in German KBA inspection interval tightening would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Vehicles
Middle East Military Vehicles Market
Military Vehicles
Main Battle Tank Market
Military Vehicles
Destroyers Market
Military Vehicles
India Combat Vehicle Systems Market
Military Vehicles
Japan Defense Market
Military Vehicles
Indonesia Defense Market
Military Vehicles
Iran Defense Market
Military Vehicles
Global Offshore Patrol Vessel (OPV) Market
Military Vehicles
Amphibious Land Craft Market
Military Vehicles
Military Land Vehicles Market
Military Vehicles
Southeast Asia Defense Market
Military Vehicles
Military Vehicle & Aircraft Protection Systems Market
Military Vehicles
Robotic Combat Vehicle (RCV) Market
Military Vehicles
Russia Defense Market
Military Vehicles
Taiwan Defense Market
Military Vehicles
Military Ground Vehicle Actuators Market