
 Global Connected Aircraft Solutions Market | 2026-2036
Global Connected Aircraft Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Global Connected Aircraft Solutions Market Analysis
Commercial airline investment in passenger-facing connectivity is consolidating as the dominant demand vector, displacing earlier military-aviation-led procurement cycles. Honeywell International Inc. leverages its integrated flight-deck heritage to bundle connectivity with avionics suites. Thales Group anchors European supply chains through its Galileo-compatible terminals and ground infrastructure partnerships. Gogo Inc. competes aggressively in the North American air-to-ground segment with proprietary tower networks.
Connected aircraft solutions encompass satellite, air-to-ground, and cellular-linked systems that transmit flight data, passenger internet, and maintenance telemetry between airborne platforms and ground stations, typically operating across L-band through Ka-band frequencies with latency targets under 500 milliseconds for operational applications. Satellite communication currently captures the largest revenue pool due to coverage over oceanic routes where terrestrial alternatives fail, while 5G-based systems represent the fastest-expanding category as aviation-specific spectrum allocations mature in major jurisdictions. Flight operations applications command premium pricing relative to passenger Wi-Fi because carriers prioritize fuel optimization and route analytics over entertainment monetization.
FAA airworthiness certification timelines directly shape hardware vendor entry costs and retrofit scheduling for US-registered fleets. EASA's cybersecurity directives for connected cockpits are forcing European operators to segment passenger and operational data streams through isolated architectures. China's CAAC and its GB standards for airborne telecommunications equipment create parallel compliance obligations for suppliers serving Chinese carriers. Stakeholders must weigh spectrum auction outcomes against satellite constellation deployment schedules when committing to multi-year fleet upgrade programs.
Market Dynamics
Retrofit cycles for narrow-body fleets are compressing installation windows as carriers race to match competitor connectivity offerings before contract renewal seasons. Satellite constellation deployment schedules now dictate hardware procurement timelines more than traditional avionics upgrade programs.
Growth Catalysts
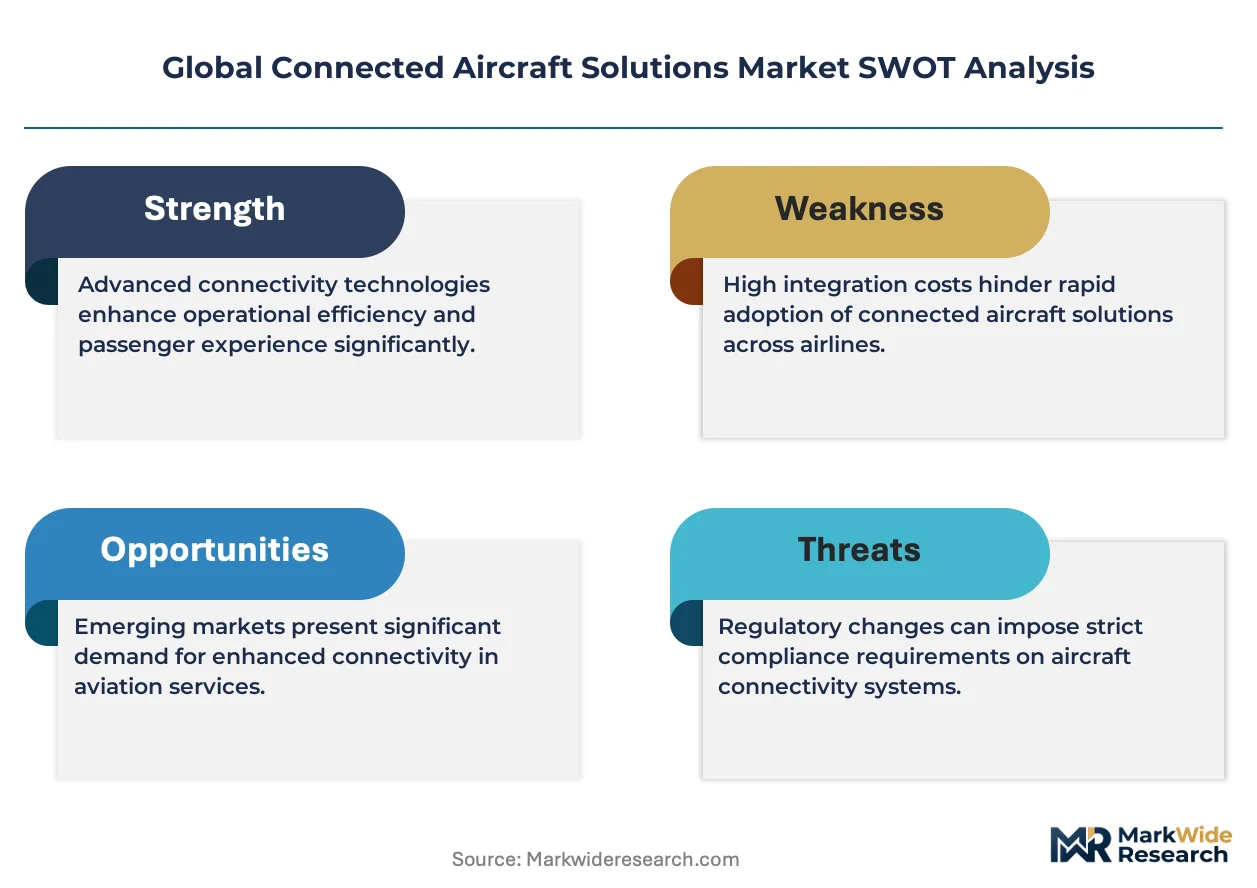
- FAA Airworthiness Directives:Tightening certification pathways for connectivity hardware installation are accelerating fleet-wide upgrade mandates for US-registered aircraft, pulling forward replacement demand.
- Passenger Retention Economics:Commercial airlines now treat inflight broadband as a competitive necessity rather than amenity, with route-specific deployment decisions tied directly to loyalty program metrics.
- Ka-band Terminal Miniaturization:Reduced antenna footprint and weight are enabling retrofit viability on regional jets previously excluded from satellite connectivity programs due to aerodynamic constraints.
Market Restraints
- Certification Cost Burden:FAA supplemental type certificate expenses for connectivity hardware frequently exceed hardware unit costs, creating diseconomies for smaller fleet operators.
- Spectrum Auction Uncertainty:Pending FCC decisions on C-band reallocation threaten interference mitigation costs for existing Ku-band installations across North American routes.
- Terrestrial Infrastructure Gaps:Air-to-ground tower density limitations over mountainous terrain in the western United States force dual-mode satellite-cellular architectures that inflate system complexity.
Strategic Opportunities
- Chinese Domestic Fleet Expansion:CAAC GB standards for airborne telecommunications equipment create dedicated compliance pathways for suppliers establishing localized production partnerships.
- Maintenance Telemetry Monetization:Engine health monitoring data streams represent underexploited revenue channels distinct from passenger-facing connectivity subscriptions.
- 5G-ATG Spectrum Allocations:Aviation-specific frequency designations in major jurisdictions enable next-generation air-to-ground networks with latency performance matching operational flight deck requirements.
Industry Challenges
- Cybersecurity Architecture Segmentation:EASA directives mandating isolated data streams between passenger Wi-Fi and operational systems require hardware redesigns that extend development cycles.
- Installation Slot Scarcity:MRO facility capacity constraints during peak retrofit seasons create scheduling bottlenecks that delay revenue service entry for upgraded aircraft.
- Interoperability Protocol Fragmentation:Competing satellite operator standards prevent seamless roaming between constellations, forcing carriers into single-source dependencies or redundant hardware configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Connected Aircraft Solutions Market |
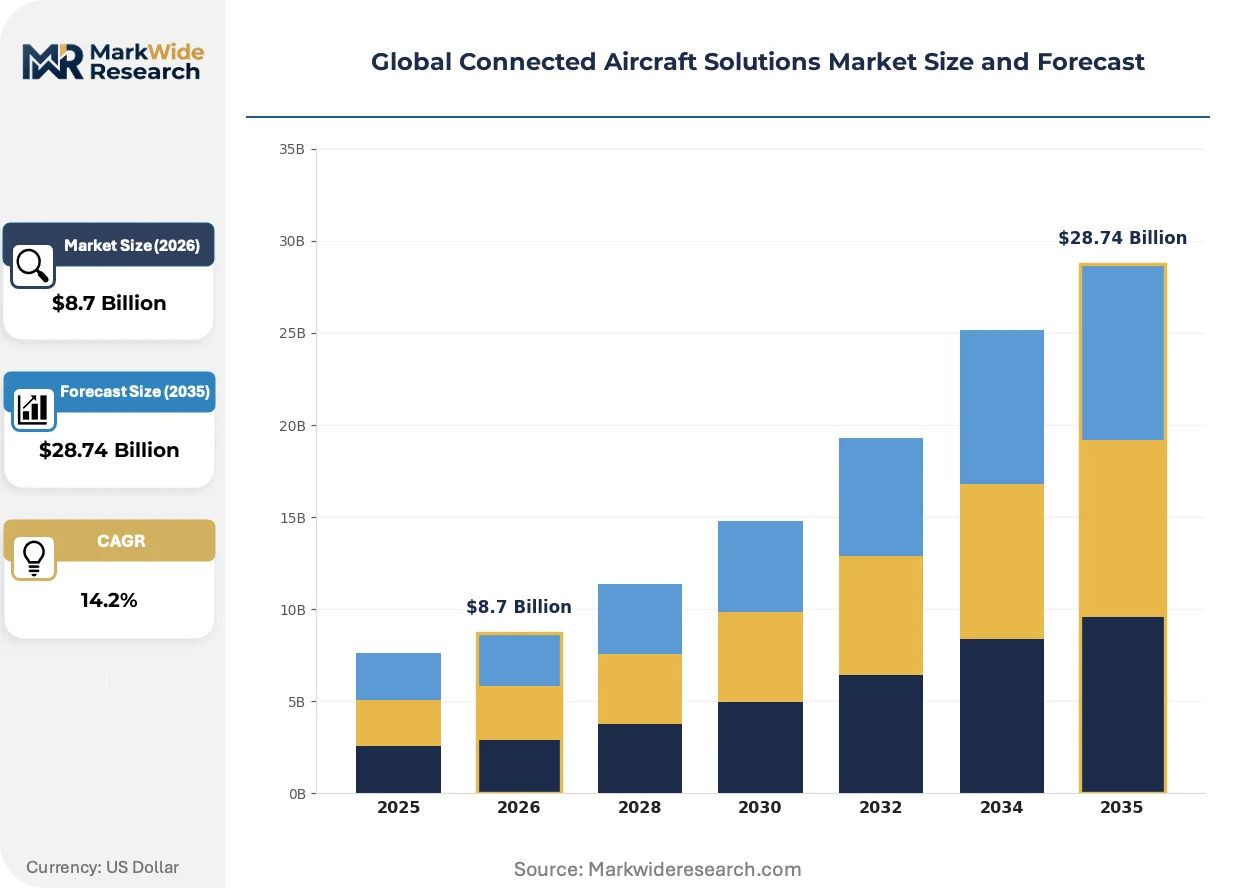
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Wi-Fi, Satellite Communication, Air-to-Ground, 5G Application: Passenger Connectivity, Fleet Management, Flight Operations, Maintenance Tracking End User: Commercial Airlines, Cargo Operators, Private Jets, Military Aviation Service Type: Data Integration, Cybersecurity, Real-Time Monitoring, Analytics |
| Companies Covered | Honeywell International Inc., Thales Group, Gogo Inc., Viasat Inc., Panasonic Avionics Corporation, Raytheon Technologies, Inmarsat Global Limited, Collins Aerospace, SITA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Connected Aircraft Solutions Market Emerging Trajectories
Software-defined radio architectures are dissolving traditional hardware boundaries between connectivity bands, allowing post-installation reconfiguration without physical antenna replacement. This flexibility is altering how carriers structure long-term supplier relationships and technology roadmaps.
Phased-array antenna systems are modularizing across the commercial aviation supply chain. Regional carriers previously locked out of satellite connectivity programs are adopting electronically steered flat-panel terminals that eliminate mechanical gimbal maintenance. The technology is modularizing procurement decisions, allowing fleet managers to standardize on single hardware platforms while selecting service providers through software configuration rather than physical equipment swaps.
EU cybersecurity certification schemes for connected cockpits are mandating formal incident response protocols and supply chain transparency disclosures from hardware vendors. EASA's implementing regulations require documented vulnerability management programs as a condition of European type acceptance. European network operators are responding by segmenting ground infrastructure architectures, isolating passenger data processing from safety-critical flight information systems through physically separated routing paths.
Airline technical procurement teams are consolidating vendor evaluation criteria around total lifecycle cost models rather than upfront hardware pricing. Maintenance burden, firmware update frequency, and mean-time-between-failure metrics now dominate supplier selection processes for fleet-wide connectivity deployments. This behavioral shift is most pronounced among US legacy carriers managing mixed fleets of owned and leased aircraft with divergent residual value considerations.
Global Connected Aircraft Solutions Market Segmentation
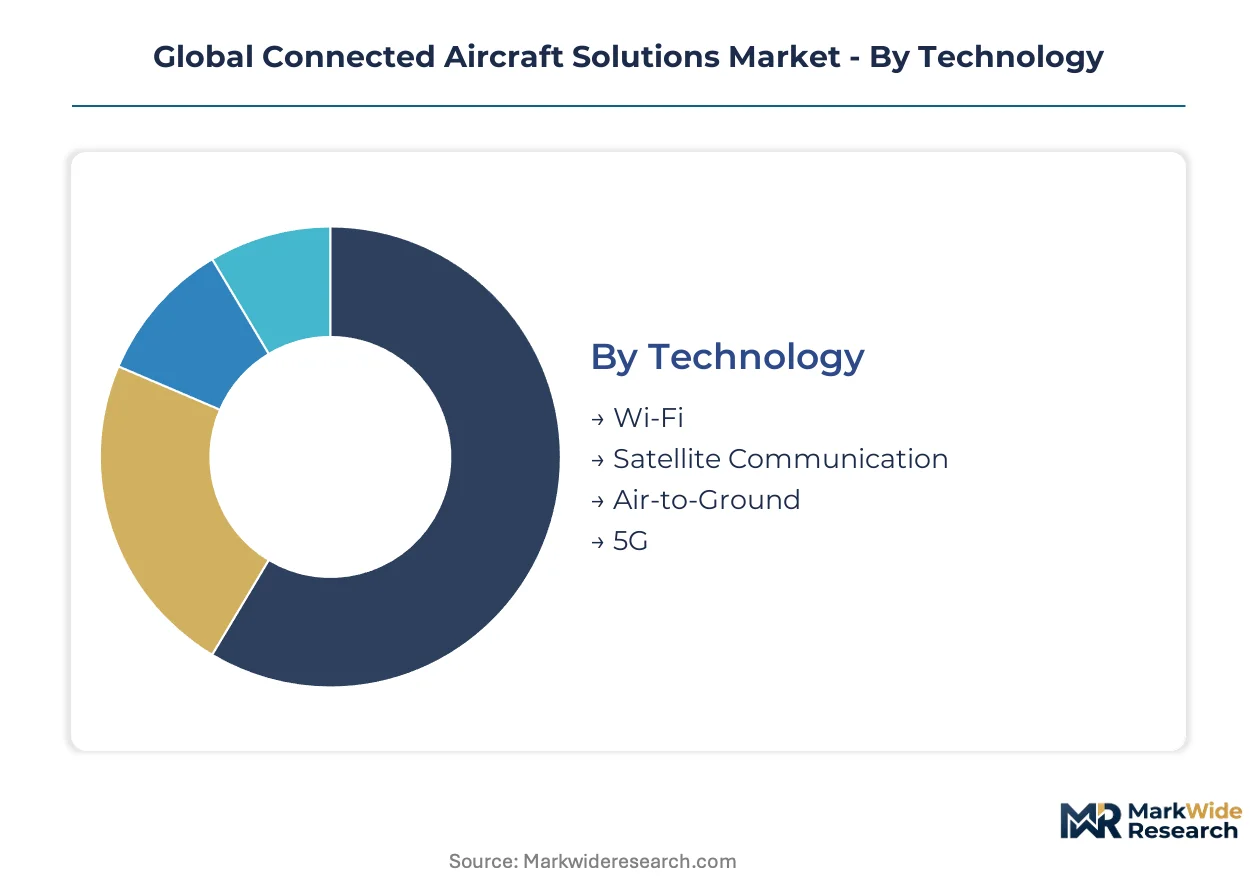
Technology choices in connected aircraft solutions lock carriers into decade-long supplier relationships and determine retrofit feasibility across fleet types. Application priorities diverge sharply between passenger-facing monetization and operational cost reduction. End-user economics vary enormously, from high-volume narrow-body programs to bespoke military platforms with classified security requirements.
Technology:
Satellite communication terminals demand the heaviest capital outlay due to phased-array antenna hardware and certification complexity, while 5G infrastructure requires spectrum licensing investments before aircraft installation.
- Satellite Communication:Ka-band and Ku-band systems provide uninterrupted coverage over oceanic routes where terrestrial networks fail. Demand concentrates among United States legacy carriers retrofitting narrow-body fleets for transcontinental passenger Wi-Fi, driven by FAA supplemental type certificate mandates accelerating replacement cycles.
- Air-to-Ground:Cellular tower-linked architectures deliver lower latency than satellite alternatives over landmasses. Deployment concentrates in the continental United States where proprietary tower networks achieve sufficient density, constrained by terrain gaps in mountainous western regions forcing hybrid satellite backups.
- Wi-Fi:Cabin distribution systems extend connectivity to passenger devices without standalone wide-area transmission capability.
- 5G:Aviation-specific spectrum allocations enable next-generation networks with latency under 100 milliseconds for flight deck applications.
Most installed capacity flows through Satellite Communication. Expansion is steepest in 5G as aviation frequency designations mature in major jurisdictions.
Application:
Operational applications command pricing premiums over passenger entertainment because carriers prioritize fuel burn optimization and predictive maintenance ROI.
- Flight Operations:Real-time weather routing and fuel analytics integrate directly with flight management systems. Adoption concentrates among European network carriers subject to EASA cybersecurity directives mandating isolated data architectures, forcing hardware redesigns that extend procurement cycles.
- Passenger Connectivity:Inflight broadband serves as a competitive retention tool tied to loyalty program metrics. Investment surges among United States ultra-low-cost carriers matching legacy competitor offerings before contract renewal seasons.
- Fleet Management:Aircraft positioning and scheduling optimization across hub-and-spoke networks.
- Maintenance Tracking:Engine health monitoring and component lifecycle telemetry for predictive intervention.
Flight Operations captures the highest per-aircraft contract values. Passenger Connectivity is gaining share fastest as monetization models shift from flat-rate to usage-based pricing.
End User:
Commercial airline procurement volumes dwarf other segments, though military platforms sustain premium pricing through security-hardened requirements.
- Commercial Airlines:Scheduled passenger carriers drive fleet-wide connectivity mandates across owned and leased aircraft. Retrofit demand concentrates in the United States where major carriers compress installation windows to match competitor offerings, constrained by MRO slot scarcity during peak seasons.
- Military Aviation:Classified communication requirements and jam-resistant waveforms sustain dedicated supply chains. Procurement flows through national defense ministries with multi-year program timelines distinct from commercial aviation cycles.
- Cargo Operators:Package carriers prioritizing route optimization over passenger amenities.
- Private Jets:Owner-operated aircraft with bespoke connectivity configurations.
Commercial Airlines account for the dominant installed base. Military Aviation shows the steepest expansion trajectory as allied defense departments modernize aerial command networks.
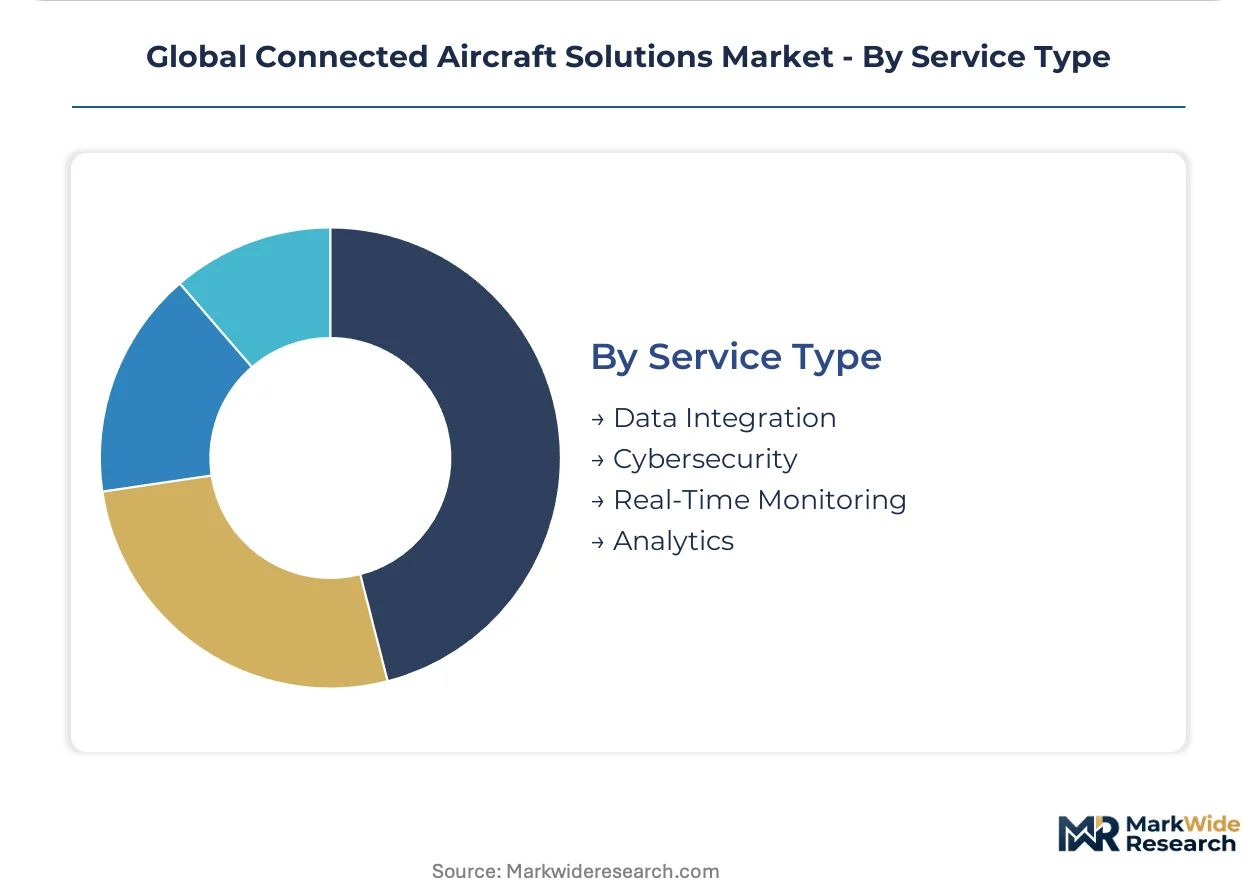
Service Type:
Cybersecurity investments are accelerating fastest as regulators mandate formal incident response protocols and supply chain transparency disclosures.
- Cybersecurity:Network segmentation and threat monitoring services isolate passenger data from operational systems. Demand surges among European operators complying with EASA implementing regulations requiring documented vulnerability management programs as a condition of type acceptance.
- Real-Time Monitoring:Continuous data stream validation and anomaly detection for flight-critical applications. Procurement concentrates among United States regional carriers seeking operational parity with mainline competitors through satellite-linked telemetry.
- Data Integration:Middleware platforms unifying disparate aircraft sensors with ground systems.
- Analytics:Predictive models converting raw telemetry into maintenance and routing recommendations.
Cybersecurity services command the fastest-growing share of service contracts. Real-Time Monitoring retains the largest revenue pool among established fleet management programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping supplier footprints as hardware vendors relocate final assembly to jurisdictions with streamlined airworthiness certification pathways. Cost-of-compliance gaps between the FAA's supplemental type certificate process and alternative national frameworks are pulling manufacturing investment toward specific regulatory environments.
United States
Major carriers including American Airlines and Delta Air Lines are compressing narrow-body retrofit schedules to match competitor connectivity offerings ahead of loyalty program renewal seasons. FAA supplemental type certificate mandates for Ka-band hardware installation are accelerating fleet-wide upgrade cycles. Dallas-Fort Worth and Seattle-Tacoma aerospace clusters concentrate MRO facility capacity where installation slot scarcity creates peak-season bottlenecks.
China
Domestic fleet expansion by COMAC and state-owned airlines is generating dedicated demand for GB-standard airborne telecommunications equipment. CAAC certification requirements create parallel compliance obligations distinct from Western airworthiness frameworks. Shanghai and Tianjin manufacturing corridors host localized production partnerships as foreign suppliers establish captive assembly operations.
Germany
Lufthansa Group's operational data analytics procurement prioritizes fuel optimization over passenger entertainment monetization. EASA cybersecurity directives mandating isolated passenger-operational data architectures are forcing hardware redesigns that extend development cycles. Munich and Hamburg aerospace engineering centers concentrate avionics integration expertise for Galileo-compatible terminal systems.
United Kingdom
British Airways and Virgin Atlantic are retrofitting long-haul fleets with dual-mode satellite-cellular architectures for transatlantic route coverage. CAA alignment with EASA implementing regulations requires documented vulnerability management programs as conditions of type acceptance. London Gatwick and Manchester maintenance bases are expanding hangar capacity to accommodate phased-array antenna installation programs.
Japan
ANA and JAL are deploying connectivity upgrades across domestic narrow-body fleets as competitive response to rail network improvements. METI aviation-specific spectrum allocations for 5G-ATG networks are enabling next-generation air-to-ground infrastructure. Nagoya and Kobe industrial zones concentrate precision antenna manufacturing for electronically steered flat-panel terminal production.
Global Connected Aircraft Solutions Market Vendor Landscape
Strategic partnerships dominate the current landscape as hardware vendors align with satellite constellation operators to lock in decade-long fleet supply agreements. The market structures around three tiers: integrated avionics conglomerates with flight-deck heritage, pure-play connectivity specialists with proprietary infrastructure, and aerospace-tier suppliers leveraging manufacturing scale. Two archetypes command premium positioning: bundled-suite providers embedding connectivity within broader flight-management ecosystems, and spectrum-asset holders controlling dedicated aviation frequency allocations. Competitive moves concentrate on vertical integration into antenna manufacturing and exclusive service-provider arrangements with major carrier groups.
Within the integrated-systems tier, Honeywell International Inc. and Thales Group exemplify bundled-suite strategies that leverage established flight-deck relationships to embed connectivity within avionics procurement cycles. Gogo Inc. occupies a distinct position as a pure-play specialist with captive air-to-ground infrastructure. These three entities represent contrasting archetypes: the diversified conglomerate anchoring European supply chains through Galileo-compatible ground partnerships, the North American connectivity pure-play competing on proprietary tower density, and the avionics incumbent bundling satellite terminals with existing flight-management suite contracts.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Thales Group |
| Gogo Inc. |
| Viasat Inc. |
| Panasonic Avionics Corporation |
| Raytheon Technologies |
| Inmarsat Global Limited |
| Collins Aerospace |
| SITA |
| Others |
Supply Flow & Price Mechanics
Carrier procurement teams consolidating around total lifecycle cost models are compressing hardware margins and forcing suppliers to absorb certification and firmware update burdens. This demand-side shift toward operational expenditure frameworks restructures how vendors price connectivity suites and where they locate final assembly.
Pricing Analysis
Direct-to-OEM discount structures dominate hardware procurement, with satellite terminal manufacturers offering volume-scaled pricing tied to fleet-wide retrofit commitments. Price differentiation hinges on FAA supplemental type certificate tier and mean-time-between-failure guarantees, with premium tiers commanding substantial uplifts for isolated cybersecurity architectures. Cost compression in regional jet installations intensifies as Ka-band miniaturization expands addressable fleet segments. Ultra-low-cost carriers exhibit acute price sensitivity, while legacy network carriers prioritize reliability metrics over upfront hardware expenditure.
Supply Chain Analysis
Regional distribution centers in Dallas-Fort Worth and Seattle-Tacoma concentrate MRO facility capacity where installation slot scarcity creates peak-season bottlenecks. Manufacturing draws from United States, Germany, and China, with phased-array antenna components resting on gallium nitride semiconductor substrates and precision-machined waveguide assemblies. Single-source vulnerability in satellite constellation operator partnerships exposes hardware vendors to service discontinuation risk. Distribution runs through captive OEM logistics networks and third-party aerospace parts distributors serving leased fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through software-defined radio architectures that reduce physical hardware refresh cycles and enable post-installation service tier upgrades.
For Market Incumbents: Anchor fleet-wide connectivity suite contracts by bundling satellite terminals with existing flight-management system relationships, insulating against pure-play connectivity specialists. Deepen backward integration into phased-array antenna manufacturing to capture value migrating from hardware to software-defined service layers. Prioritize EASA cybersecurity certification investments to maintain European carrier access as regulatory requirements stiffen. For New Entrants and Emerging Players: Regional carriers operating mixed leased-owned fleets represent an underserved buyer archetype with unconsolidated procurement and limited technical integration resources. White-space targets include maintenance telemetry monetization platforms and 5G-ATG infrastructure partnerships in Japan and China. A direct-to-fleet-manager technical sales model bypasses incumbent OEM channel control. For Investors and Strategic Acquirers: Asymmetric upside sits with software-defined radio platform developers with aviation-specific spectrum relationships and firmware-over-the-air update capabilities. Long-term viability favors suppliers with demonstrated FAA supplemental type certificate track records and established MRO installation partnerships. Watch for inflection signals in CAAC GB standard adoption rates indicating Chinese domestic fleet procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Radio Platform Development | Enables post-installation band reconfiguration without antenna replacement, extending hardware lifecycle. |
| Galileo-Compatible Terminal Certification | Secures European carrier procurement pipelines under EASA navigation mandate alignment. |
| Phased-Array Antenna Manufacturing Scale-Up | Captures value migrating from mechanical gimbal systems to electronically steered flat-panel architectures. |
| 5G-ATG Spectrum Licensing Partnership | Establishes aviation-specific frequency control for next-generation air-to-ground latency performance. |
| Maintenance Telemetry Data Platform | Monetizes engine health streams distinct from passenger-facing connectivity subscription models. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Primary fieldwork encompassed airline fleet procurement directors, MRO facility operations managers, satellite constellation commercial leads, and avionics integration engineers. Secondary sources included FAA supplemental type certificate filings, EASA implementing regulation documentation, CAAC GB standard publications, and satellite operator service coverage disclosures. Bottom-up fleet installation forecasts triangulated against top-down connectivity service revenue estimates.
Rate-of-change decomposition across the analysis window separates retrofit cycle compression effects from satellite constellation deployment timing and regulatory mandate acceleration. Segmentation dimensions encompassed technology band, application priority, end-user category, and service type tier. CAGRs derived from installed base growth curves weighted by per-aircraft contract value trajectories. Industry-specific inputs included narrow-body fleet age profiles and loyalty program contract renewal seasonality.
Underlying measurement precision varies by segment; commercial airline retrofit forecasts carry tighter precision than military aviation procurement projections due to classified program opacity. Forecasts reflect documented assumptions regarding satellite constellation deployment schedules and spectrum auction outcomes. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Data and Diagnostics
Flight Data Monitoring Market
Aircraft Data and Diagnostics
Attitude and Heading Reference System (AHRS) Market
Aircraft Data and Diagnostics
Airplane Machmeter Market
Aircraft Data and Diagnostics
Helicopter Aeronautical Software Market
Aircraft Data and Diagnostics
Automated Composite Structure Inspection Systems for Aerospace Market
Aircraft Data and Diagnostics
Air Data Systems Market
Aircraft Data and Diagnostics
Europe Aircraft Health Monitoring System Market
Aircraft Data and Diagnostics
Air Data Testers Market
Aircraft Data and Diagnostics
Aviation Compliance Monitoring Tools Market
Aircraft Data and Diagnostics
Flight Data Recorder (FDR) Market
Aircraft Data and Diagnostics
NDT in the Aerospace and Defense Market
Aircraft Data and Diagnostics
Embedded Structural Health Monitoring Networks for Aircraft Skins Market
Aircraft Data and Diagnostics
Global Flight Inspection Market
Aircraft Data and Diagnostics
Commercial Aircraft Health Monitoring Systems Market
Aircraft Data and Diagnostics
Aerospace and Defense Telemetry Market
Aircraft Data and Diagnostics
Aircraft Control Software Market