
 Sudan Satellite Transponder Market | 2026-2036
Sudan Satellite Transponder Market Size, Share, and Industry Trends Forecast 2026-2036
Sudan Satellite Transponder Market Insights
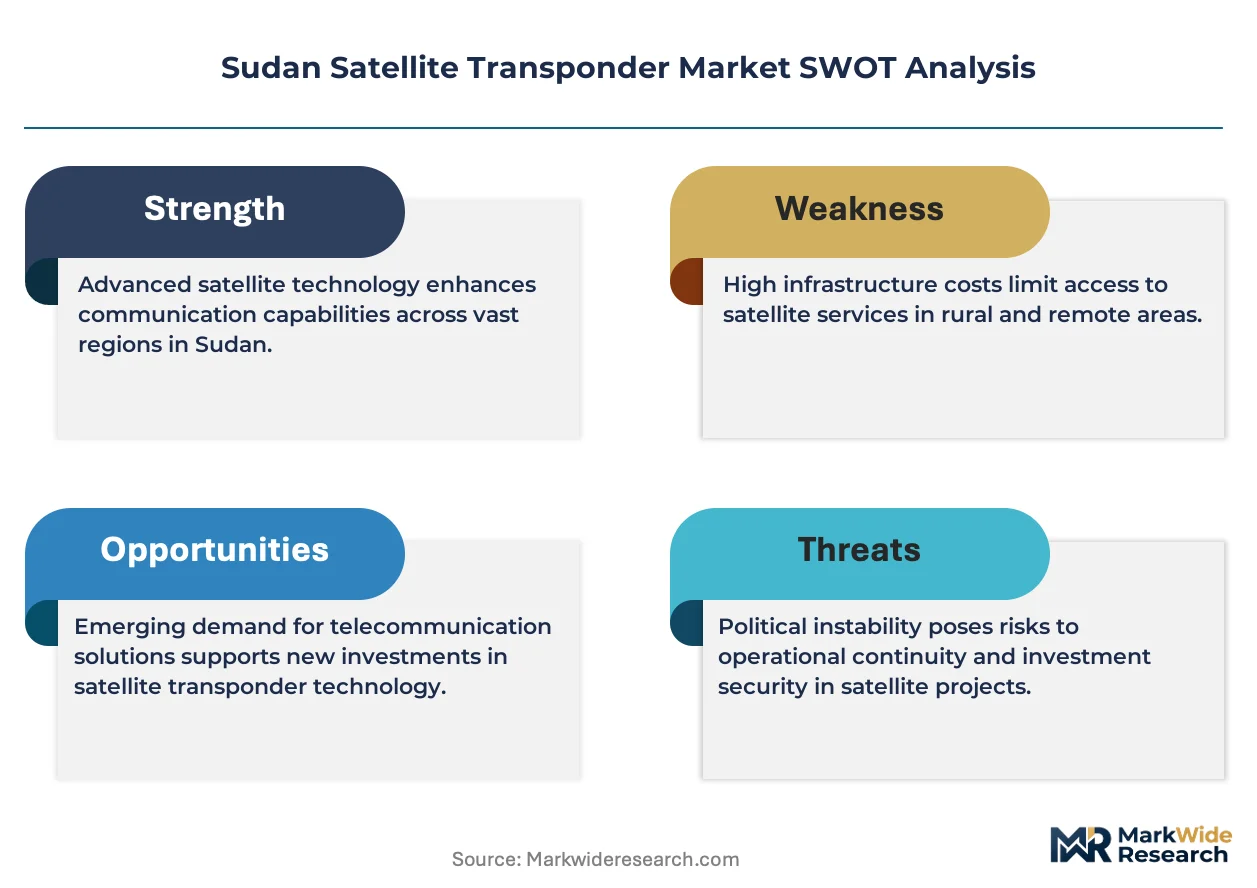
ITU satellite coordination frameworks is expanding bandwidth allocation discipline across East African orbital corridors. Intelsat leverages its Africa-wide beam architecture to sustain long-haul connectivity contracts into Sudan. SES S.A. anchors C-band and Ku-band capacity for broadcast redistribution across the Horn of Africa. Yah Satellite Communications Company competes on Ka-band density for enterprise and government backhaul.
A satellite transponder is a receiver-transmitter subsystem aboard a communications satellite that receives an uplink signal, translates its frequency, amplifies it, and retransmits it to a designated coverage area; typical Ku-band transponders operate with 36 to 72 MHz bandwidth and output 50 to 150 watts per channel, serving television broadcast, telecom trunking, and broadband internet relay functions. C-band capacity dominates Sudan's current leasing mix due to superior rain-fade resilience across the Sahel climate zone, while Ka-band segments attract the fastest capacity additions as enterprise and government agencies pursue higher throughput per transponder. Broadcasting applications command the largest share of leased bandwidth, though Internet Services segments are deepening faster as terrestrial fiber gaps persist in South Kordofan and Darfur states.
Sudan's National Telecommunications Corporation enforces licensing and orbital usage compliance for all satellite service providers, while ITU Radio Regulations bind frequency coordination across neighboring Ethiopian and Egyptian orbital arcs. The country's central bank and ministry of finance shape foreign currency availability for transponder lease payments, directly constraining procurement timelines for government agencies and telecom operators. Stakeholders must monitor spectrum re-farming decisions and regional orbital congestion before committing to multi-year transponder capacity agreements.
Market Dynamics
Orbital slot scarcity under ITU coordination frameworks is compressing lease negotiation timelines for Sudanese broadcasters and government agencies seeking Ku-band and Ka-band capacity. Foreign currency rationing by the central bank further constrains multi-year transponder procurement cycles.
Growth Catalysts
- South Kordofan fiber gaps:Terrestrial infrastructure deficits in conflict-affected states are forcing telecom operators and aid organizations toward satellite backhaul as the sole reliable connectivity option.
- ITU Radio Regulations:Mandatory frequency coordination across Ethiopian and Egyptian orbital arcs is formalizing spectrum access protocols, reducing interference disputes and stabilizing lease terms for Sudanese uplink facilities.
- Ka-band density migration:Enterprise and government agencies are upgrading from C-band to higher-throughput Ka-band transponders for data-intensive applications, expanding addressable bandwidth per orbital slot.
Market Restraints
- Foreign exchange controls:The ministry of finance and central bank restrict hard currency availability for transponder lease payments denominated in USD or EUR, delaying procurement for government agencies and private operators.
- Rain-fade technical limitation:Ka-band signals suffer attenuation during Sudan's July-September rainy season, requiring costly site diversity configurations or forcing retention of C-band capacity for mission-critical links.
- Regional orbital congestion:Beam overlap from Egyptian and Ethiopian satellite fleets reduces available downlink power margins for Khartoum-based earth stations, degrading link budgets.
Strategic Opportunities
- Darfur humanitarian connectivity:UN agencies and international NGOs require dedicated transponder capacity for coordination networks in camps and field offices underserved by terrestrial infrastructure.
- National Telecommunications Corporation licensing reform:Potential streamlining of satellite service provider authorization processes could accelerate market entry for regional operators seeking orbital capacity leases.
- Hybrid C/Ka-band architectures:Converged transponder configurations allowing dynamic bandwidth allocation between rain-resilient C-band and high-capacity Ka-band are attracting broadcasters seeking operational flexibility.
Industry Challenges
- Satellite engineering skill scarcity:Khartoum's technical institutes produce limited RF engineering and earth station maintenance specialists, forcing operators to rely on expensive expatriate technicians or regional training partnerships.
- Legacy C-band infrastructure integration:Broadcast redistribution networks built on analog C-band receivers require phased replacement to capture Ka-band throughput gains, straining capital deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sudan Satellite Transponder Market |
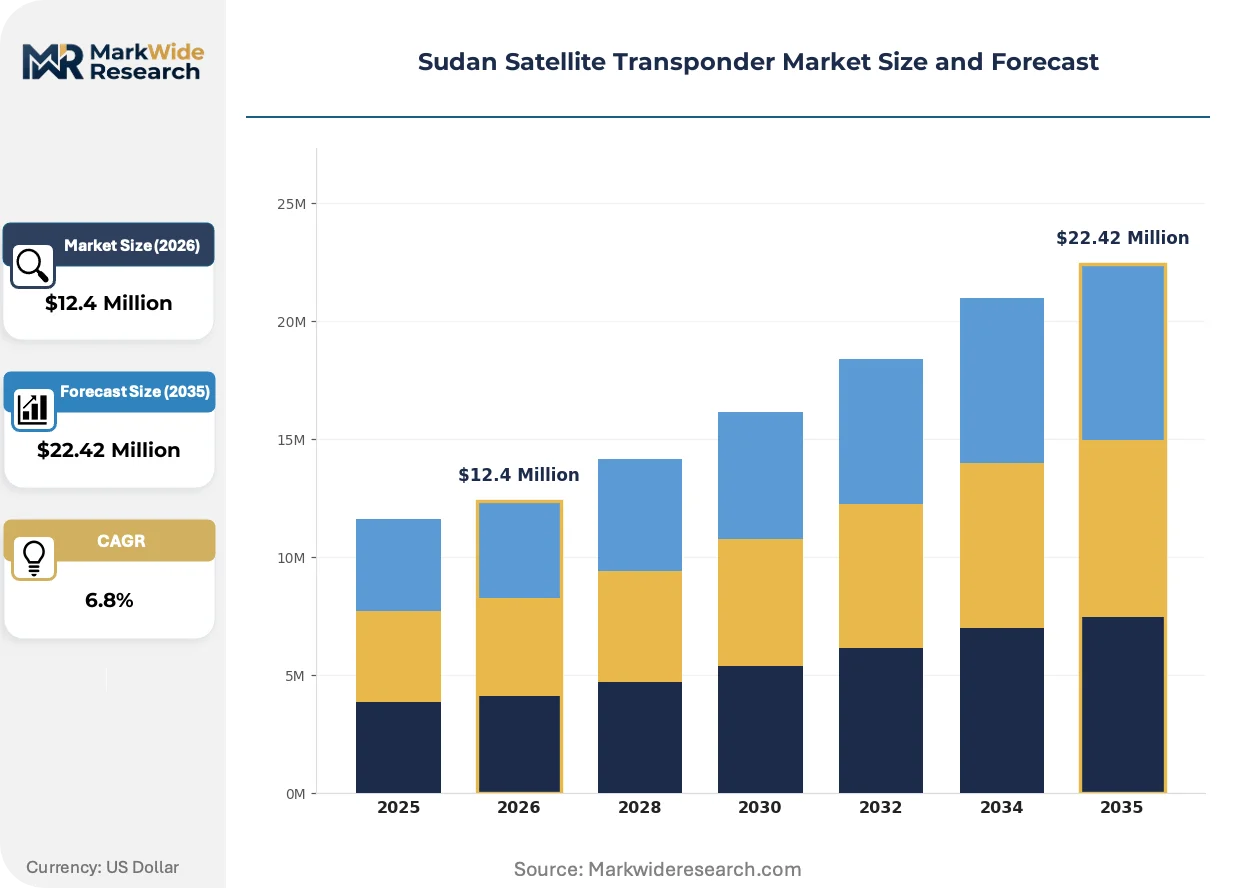
| Market Size in 2026 | $12.4 Million |
| Market Size in 2035 | $22.42 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: C-band, Ku-band, Ka-band, Q-band Application: Broadcasting, Communications, Internet Services, Government Services End User: Telecom Operators, Broadcasters, Government Agencies, Enterprises Deployment: Fixed Satellite, Mobile Satellite, Hybrid Satellite, Others |
| Companies Covered | Intelsat, SES S.A., Eutelsat S.A., Yah Satellite Communications Company, Telesat Corporation, Hispasat SA, EchoStar Corporation, China Satellite Communications Co Ltd, Thuraya Telecommunications Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sudan Satellite Transponder Market Trends and Innovations
Frequency re-farming and digital compression standards are reshaping how Sudanese broadcasters and government agencies allocate transponder bandwidth across orbital arcs. Technical migration toward higher-frequency bands is accelerating alongside regulatory pressure for spectrum efficiency.
High-throughput satellite (HTS) spot-beam architecture is modularizing capacity allocation across Sudan's coverage footprint. The National Telecommunications Corporation and private broadcasters are adopting HTS platforms to partition bandwidth into geographically concentrated cells. This modularizing approach allows precise matching of transponder power to demand density in Khartoum versus peripheral states, reducing wasted wide-beam coverage.
ITU Radio Regulations enforcement across East African orbital corridors is tightening coordination requirements for Sudanese uplink operators. The framework mandates cross-border interference studies with Ethiopian and Egyptian satellite networks before new frequency assignments. Broadcasters and government agencies now face extended licensing timelines but gain improved signal integrity through formalized spectrum discipline.
Service unbundling is fragmenting traditional transponder lease structures in Sudan's media sector. Broadcasters are separating content delivery from earth station management and conditional access systems, sourcing each component from specialized providers. This decomposition is most visible among Khartoum-based private television networks seeking operational flexibility without capital-intensive ground infrastructure ownership.
Sudan Satellite Transponder Market Segmentation
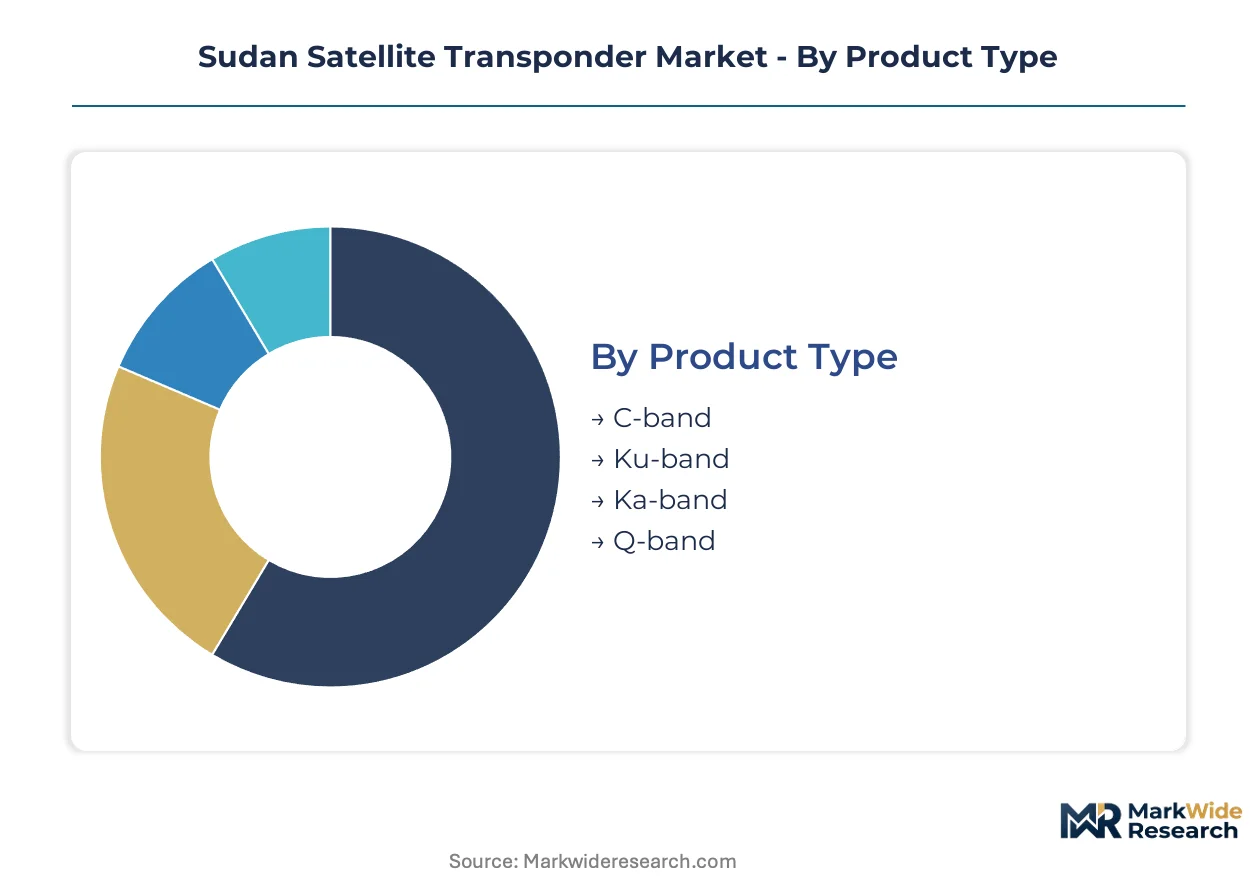
Satellite transponder segmentation in Sudan reflects technical trade-offs between rain resilience and spectral efficiency, with procurement patterns shaped by foreign currency constraints and regional orbital coordination. Band selection, application priority, and deployment architecture each determine lease economics and operational reliability for Khartoum-based uplink facilities.
Product Type:
C-band dominates leased volume for its superior rain-fade resilience across Sudan's Sahel climate zone, while Ka-band commands premium pricing for high-throughput enterprise applications.
- C-band:Operating in the 4-8 GHz range with 36-72 MHz channel bandwidths, C-band transponders deliver 50-150 watts per channel with minimal signal attenuation during Sudan's July-September rainy season. Demand concentrates in Khartoum's government broadcast redistribution networks and national television uplink facilities where link reliability outweighs spectral efficiency considerations. The National Telecommunications Corporation prioritizes C-band licensing for mission-critical national infrastructure.
- Ka-band:High-frequency 26.5-40 GHz operation enables 500+ MHz channel bandwidths and spot-beam architectures that multiply throughput per orbital slot. Enterprise data centers and government ministry networks in Khartoum are migrating to Ka-band for bandwidth-intensive cloud connectivity, though site diversity configurations add 30-40% to ground infrastructure costs.
- Ku-band:The 12-18 GHz middle band balances rain resilience with spectral efficiency for private broadcasters and regional telecom operators seeking cost-optimized capacity.
- Q-band:Emerging 33-50 GHz spectrum attracts experimental deployments for specialized military and research applications with limited commercial leasing activity.
Today's leader: C-band. Tomorrow's challenger: Ka-band.
Application:
Broadcasting generates the highest transponder lease volume through Sudan's state television redistribution requirements, while Internet Services segments expand fastest where terrestrial fiber gaps persist.
- Broadcasting:National television networks, religious programming redistribution, and pan-Arab channel backhaul consume the majority of C-band and Ku-band capacity leased by Sudanese operators. The country's state broadcaster maintains long-term contracts with regional satellite operators for Nile Basin coverage beams.
- Internet Services:VSAT networks and community internet hubs in South Kordofan and Darfur states rely exclusively on satellite backhaul where fiber deployment remains economically unviable due to security constraints and terrain challenges.
- Communications:Corporate voice trunking and banking network redundancy applications favor Ku-band transponders for cost-balanced reliability.
- Government Services:Military, diplomatic, and emergency coordination networks require dedicated transponder capacity with encrypted uplink capabilities and priority restoration protocols.
Broadcasting anchors current revenue. Internet Services climbs the fastest as aid organizations and mobile operators extend coverage to underserved states.
End User:
Telecom operators drive volume procurement through multi-transponder contracts, while government agencies face payment delays from central bank foreign currency rationing.
- Telecom Operators:Zain Sudan, MTN Sudan, and Sudatel lease C-band and Ku-band capacity for rural network backhaul and international voice gateway redundancy. These operators negotiate multi-year contracts denominated in USD, exposing procurement timelines to foreign exchange availability fluctuations.
- Government Agencies:The Ministry of Information, National Telecommunications Corporation, and military communications directorates require dedicated transponder segments with sovereign control over encryption and priority access protocols.
- Broadcasters:Private television networks and radio redistribution operators source unbundled transponder capacity separate from earth station management services.
- Enterprises:Banking consortia, petroleum exploration companies, and agricultural commodity traders lease Ka-band capacity for secure data transmission between Khartoum headquarters and field operations.
Telecom operators maintain procurement scale leadership. Enterprises gain share fastest as digital transformation accelerates across extractive industries.
Deployment:
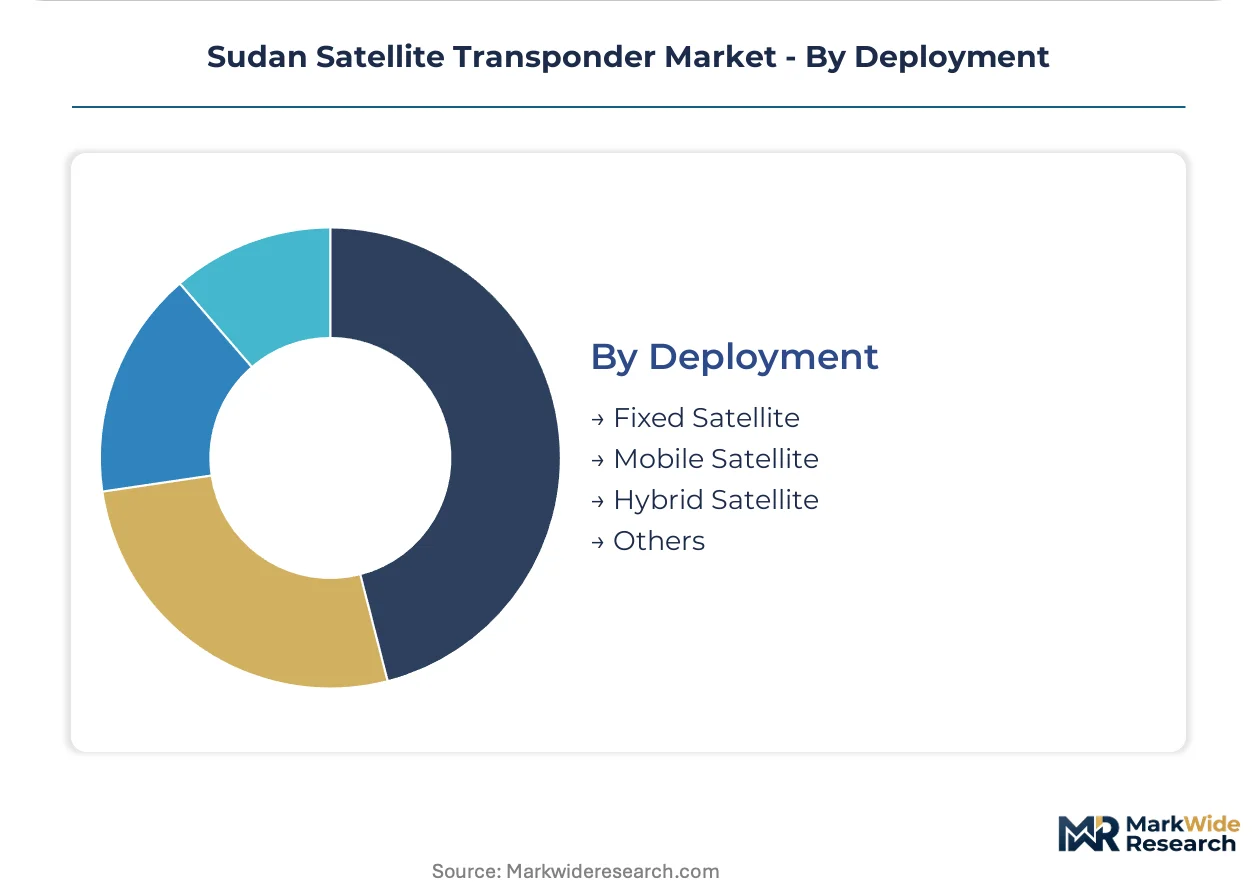
Fixed satellite installations dominate Khartoum's established earth station infrastructure, while hybrid configurations emerge for broadcasters seeking operational flexibility.
- Fixed Satellite:Permanent earth stations with 9-meter or larger antennas at Khartoum's government and telecom operator facilities provide primary transponder access with 99.95% availability service level agreements. These installations represent sunk capital with 15-20 year depreciation schedules.
- Hybrid Satellite:Converged C/Ka-band ground systems allow dynamic bandwidth allocation between rain-resilient and high-throughput transponders based on weather conditions and traffic priority. Private broadcasters pilot these configurations to reduce redundant capacity leasing.
- Mobile Satellite:Transportable VSAT terminals and vehicle-mounted antennas serve humanitarian field operations, election monitoring, and temporary event coverage in peripheral states.
- Others:Maritime and aeronautical applications remain nascent segments with limited transponder demand from Sudan-based operators.
Fixed Satellite retains infrastructure dominance. Hybrid Satellite shows steepest expansion trajectory as broadcasters optimize capital deployment across dual-band architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sudan's satellite transponder capacity procurement concentrates around Khartoum's technical workforce and uplink engineering clusters, with demand radiating toward conflict-affected peripheries where terrestrial alternatives fail.
Khartoum State
Government broadcast redistribution and enterprise data centers drive transponder leasing in Sudan's capital. The National Telecommunications Corporation enforces orbital usage compliance and licensing protocols for all satellite service providers. Khartoum's earth station infrastructure hosts the majority of C-band and Ku-band capacity serving national television networks and international voice gateways.
Darfur Region
Humanitarian connectivity requirements from UN agencies and international NGOs sustain dedicated transponder demand across camps and field offices. Foreign currency rationing by the central bank constrains lease procurement timelines for aid organizations operating in the region. Mobile satellite deployments serve temporary event coverage and election monitoring where fixed infrastructure remains impractical.
South Kordofan
Terrestrial fiber gaps force telecom operators toward satellite backhaul as the sole reliable connectivity option in this conflict-affected state. The ministry of finance shapes foreign currency availability for transponder payments, directly impacting procurement cycles. VSAT networks and community internet hubs rely exclusively on leased capacity where security constraints block ground infrastructure deployment.
Red Sea State
Port Sudan's maritime and logistics corridors generate specialized transponder requirements for shipping coordination and petroleum exploration data transmission. ITU Radio Regulations bind frequency coordination with neighboring Egyptian and Ethiopian orbital arcs, formalizing spectrum access protocols. Enterprise Ka-band leasing accelerates among extractive industry operators seeking secure headquarters-to-field connectivity.
Sudan Satellite Transponder Market Competitive Landscape
Capital-heavy satellite fleet operators compete with asset-light capacity resellers and managed service providers across Sudan's transponder procurement channels. The market structure consolidates around three to four dominant orbital slot holders with Africa-wide beam architectures, while regional specialists capture niche government and humanitarian segments. Strategic archetypes include pan-African fleet operators with legacy C-band dominance, Middle Eastern Ka-band specialists, and emerging Asian constellation providers. Competitive moves center on multi-year capacity pre-commitments and hybrid C/Ka-band service bundling.
Among Africa-based fleet operators, Intelsat and SES S.A. anchor the competitive landscape through long-haul connectivity contracts and broadcast redistribution capacity. Yah Satellite Communications Company represents the Middle Eastern Ka-band specialist archetype, competing on high-throughput density for enterprise and government backhaul. These three operators exemplify the tier of providers with sovereign-grade orbital assets and established Sudanese regulatory relationships.
| Leading Market Players |
|---|
| Intelsat |
| SES S.A. |
| Eutelsat S.A. |
| Yah Satellite Communications Company |
| Telesat Corporation |
| Hispasat SA |
| EchoStar Corporation |
| China Satellite Communications Co Ltd |
| Thuraya Telecommunications Company |
| Others |
Pricing and Supply Chain Analysis
C-band-to-Ka-band performance divergence splits Sudan's transponder market into rain-resilient legacy leasing and premium high-throughput segments, with that bifurcation driving divergent procurement cycles and orbital slot dependencies across Khartoum's government uplink facilities and enterprise data centers. Foreign currency rationing by Sudan's central bank compresses payment timelines for Ka-band capacity while C-band contracts retain priority clearance, embedding supply chain rigidity into pricing negotiations.
Pricing Analysis
Bundled earth-station-plus-transponder contracts dominate government and telecom operator procurement, while unbundled capacity-only leases attract private broadcasters seeking operational flexibility. Three-tier pricing structure across premium Ka-band spot-beam, standard Ku-band regional beam, and economy C-band wide-beam levels reflects bandwidth density and rain-fade resilience differentials. Pricing pressure stems from foreign exchange controls delaying USD-denominated payments to regional satellite operators. Government agencies show lowest price sensitivity due to sovereign priority access protocols, while humanitarian organizations face highest sensitivity due to donor funding cycles.
Supply Chain Analysis
Transponder manufacturing rests on European and American satellite bus producers, with payload integration concentrated in France, USA, and Luxembourg. Solar panel arrays, traveling-wave tube amplifiers, and antenna reflectors constitute critical component dependencies. Single-source vulnerability runs through specialized traveling-wave tube suppliers in USA and France, with ITU coordination timelines adding regulatory chokepoint risk. Distribution runs through regional satellite operators with Africa-wide beam architectures, who lease orbital capacity to Sudanese broadcasters and government agencies via long-term contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sudan's satellite transponder market functions as a geographic-arbitrage play where Khartoum's orbital slot scarcity and foreign currency controls create pricing premiums unavailable in Egyptian or Ethiopian orbital corridors with deeper hard currency reserves.
For Market Incumbents: To counter emerging Asian constellation providers with LEO broadband offerings, incumbents should anchor multi-year C-band pre-commitments with Sudan's National Telecommunications Corporation and deepen backward integration into earth station management services. Hybrid C/Ka-band service bundling preserves margin position against unbundled competitors. For New Entrants and Emerging Players: Humanitarian connectivity coordinators in Darfur represent the most penetrable buyer archetype, with UN agencies and international NGOs requiring dedicated transponder capacity for camp coordination networks underserved by terrestrial infrastructure. Ka-band spot-beam density for enterprise backhaul in South Kordofan offers secondary white-space opportunity. Go-to-market positioning should emphasize rapid deployment timelines and donor-compliant billing structures. For Investors and Strategic Acquirers: Consolidation pressure builds where foreign currency rationing strands smaller capacity resellers unable to secure hard currency for orbital lease payments. Long-term viability favors operators with sovereign-grade regulatory relationships and diversified Africa-wide beam footprints. Acquisition targets include regional managed service providers with established National Telecommunications Corporation licensing. The signal to watch is central bank foreign exchange allocation policy shifts affecting multi-year contract security.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid C/Ka-band Architecture Deployment | Enables dynamic bandwidth allocation between rain-resilient and high-throughput transponders for Khartoum broadcasters. |
| Long-term Orbital Capacity Pre-commitment | Secures priority slot access with Intelsat and SES S.A. ahead of ITU coordination queue congestion. |
| Earth Station Management Service Expansion | Captures unbundled procurement demand from private broadcasters seeking operational flexibility without capital ownership. |
| Humanitarian Connectivity Partnership | Positions operators for UN agency transponder tenders in Darfur and South Kordofan fiber-gap regions. |
| National Telecommunications Corporation Licensing Streamlining | Accelerates market entry authorization for regional operators seeking Sudanese orbital capacity access. |
Research Methodology
Coverage spans Sudan's Khartoum State, Darfur Region, South Kordofan, and Red Sea State, with primary inputs from each sub-region's distinct demand profile. Primary interviews with satellite service provider executives, earth station engineering directors, National Telecommunications Corporation licensing officers, and humanitarian organization ICT coordinators combined with secondary validation from ITU Radio Regulations filings, central bank foreign exchange policy circulars, and regional satellite operator capacity disclosure statements. Bottom-up transponder lease volume estimates triangulated against top-down orbital slot capacity allocations.
Granularity-level modeling deployed band-specific transponder counts by C-band, Ku-band, and Ka-band segments, crossed with application categories spanning broadcasting, internet services, communications, and government services. End-user splits modeled telecom operators, government agencies, broadcasters, and enterprises separately. CAGRs derived from lease volume trajectory analysis across the projection horizon, with foreign exchange availability and ITU coordination timelines as satellite industry-specific forecast inputs.
Underlying measurement precision varies by segment; C-band broadcasting leases carry tighter precision due to state television contract transparency, while Ka-band enterprise demand carries wider variance due to procurement sensitivity. Forecasts reflect documented assumptions regarding central bank currency rationing continuity and regional orbital coordination stability. A small set of triggers—foreign exchange policy shifts, ITU slot reallocation decisions, and fiber infrastructure deployment in conflict-affected states—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Europe Satellite Attitude and Orbit Control System Market
Satellite
North America Satellite Bus Market
Satellite
South Korea Satellite Communication Market
Satellite
Asia-Pacific Small Satellite Market
Satellite
Satellite Based Augmentation Systems (SBAS) Market
Satellite
Middle East Satellite Communications Market
Satellite
Global Maritime Satellite Communication Market
Satellite
France Satellite-Based Earth Observation Market
Satellite
Satellite Sensor Market
Satellite
Asia-Pacific Satellite Attitude and Orbit Control System Market
Satellite
M2M Satellite Communication Market
Satellite
Satellite Communication System Market
Satellite
Global LEO Satellite Market
Satellite
Asia-Pacific Satellite Manufacturing and Launch Systems Market
Satellite
France Satellite Imagery Services Market
Satellite
Asia-Pacific Satellite IoT Market