
 Satellite Photography Service Market | 2026-2036
Satellite Photography Service Market Size, Share, and Industry Trends Forecast 2026-2036
Satellite Photography Service Market Insights
Geospatial analytics licensing is reshaping margin distribution across the satellite photography value chain. Maxar Technologies leverages its legacy orbital constellation and government relationships to sustain premium positioning in defense and intelligence contracts. Planet Labs PBC operates the largest commercial CubeSat fleet, enabling daily Earth coverage that anchors its subscription-based data products. ICEYE specializes in synthetic aperture radar microsatellites, differentiating through all-weather, day-night imaging capabilities that competitors cannot match.
Satellite photography service encompasses the capture, processing, and delivery of Earth imagery from orbiting platforms operating at altitudes from 300 to 36,000 kilometers, utilizing sensors with spatial resolutions ranging from sub-meter to 30-meter ground sample distances for mapping, monitoring, and decision-support applications. Optical imaging dominates commercial revenue due to mature supply chains and intuitive interpretation, while synthetic aperture radar represents the fastest-expanding technology segment as climate volatility and defense requirements drive demand for reliable coverage through cloud and darkness. Geospatial analytics commands the highest margin pool within service types, reflecting customer willingness to pay for actionable intelligence rather than raw pixels.
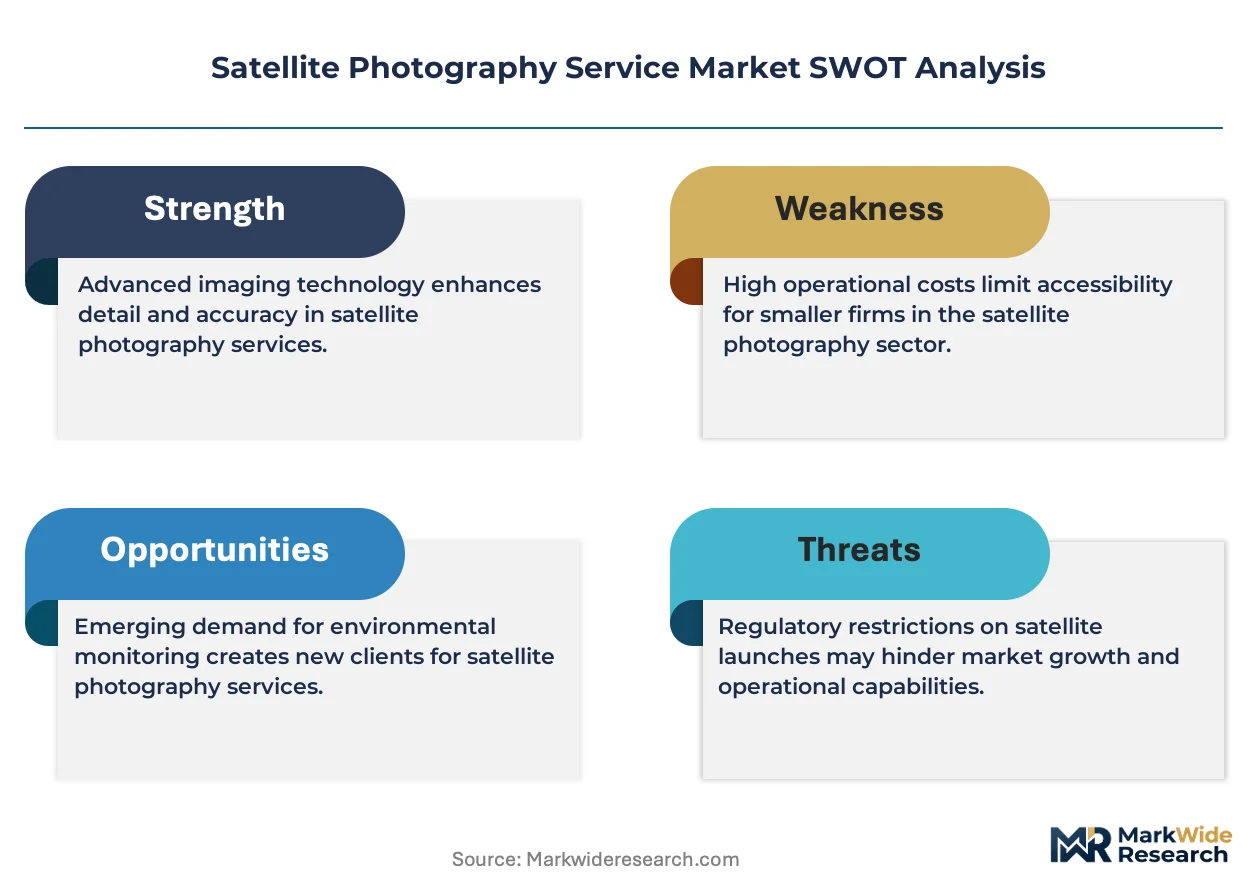
The Federal Aviation Administration governs commercial launch licensing and orbital slot coordination in the United States, while the National Oceanic and Atmospheric Administration regulates remote sensing spacecraft under the Land Remote Sensing Policy Act, creating compliance thresholds that filter market entrants by capital intensity and technical capability. European operators face additional layers under the EU Space Programme and GDPR-linked geospatial data restrictions. Stakeholders must monitor evolving debris mitigation mandates and spectrum allocation rulings that could constrain constellation expansion plans or force costly spacecraft redesigns.
Market Dynamics
Synthetic aperture radar is displacing optical imaging as the default procurement specification for defense and climate-monitoring contracts, compressing the addressable market for traditional electro-optical operators while expanding all-weather service premiums.
Growth Catalysts
- Defense procurement mandates:Federal agencies in the United States prioritize orbital imagery for border surveillance and asset tracking under classified program budgets.
- Climate volatility coverage gaps:Persistent cloud cover in tropical and maritime zones accelerates adoption of radar-based monitoring for agriculture and disaster response.
- Launch cost compression:Reusable rocket platforms reduce per-kilogram payload expenses, enabling denser constellation deployments by capital-constrained operators.
Market Restraints
- Orbital debris mitigation compliance:The Federal Aviation Administration imposes end-of-life disposal requirements that extend mission planning timelines and raise insurance premiums.
- Sensor component concentration:High-precision optics and radar transmitter modules source predominantly from German and Japanese specialty manufacturers, creating single-supplier vulnerability.
- Spectrum allocation contention:Radio frequency licensing disputes between commercial operators and military users constrain downlink capacity in crowded orbital slots.
Strategic Opportunities
- Emerging maritime surveillance demand:Port authorities in Indonesia and Vietnam seek persistent vessel tracking for illegal fishing enforcement and supply chain security.
- Carbon credit verification services:Forest carbon offset registries require standardized biomass measurement, opening subscription-based analytics to project developers.
- AI-assisted change detection:Machine learning models trained on historical imagery archives enable automated infrastructure monitoring for insurance underwriters.
Industry Challenges
- Geospatial data science talent scarcity:Competitors for PhD-level remote sensing specialists include autonomous vehicle mapping divisions and agricultural drone platforms.
- Cross-border imagery licensing complexity:National security classifications in multiple jurisdictions restrict resale of certain resolution grades to commercial customers.
- Legacy ground station integration:Established defense clients maintain proprietary data formats that require custom interface development for new satellite operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Satellite Photography Service Market |
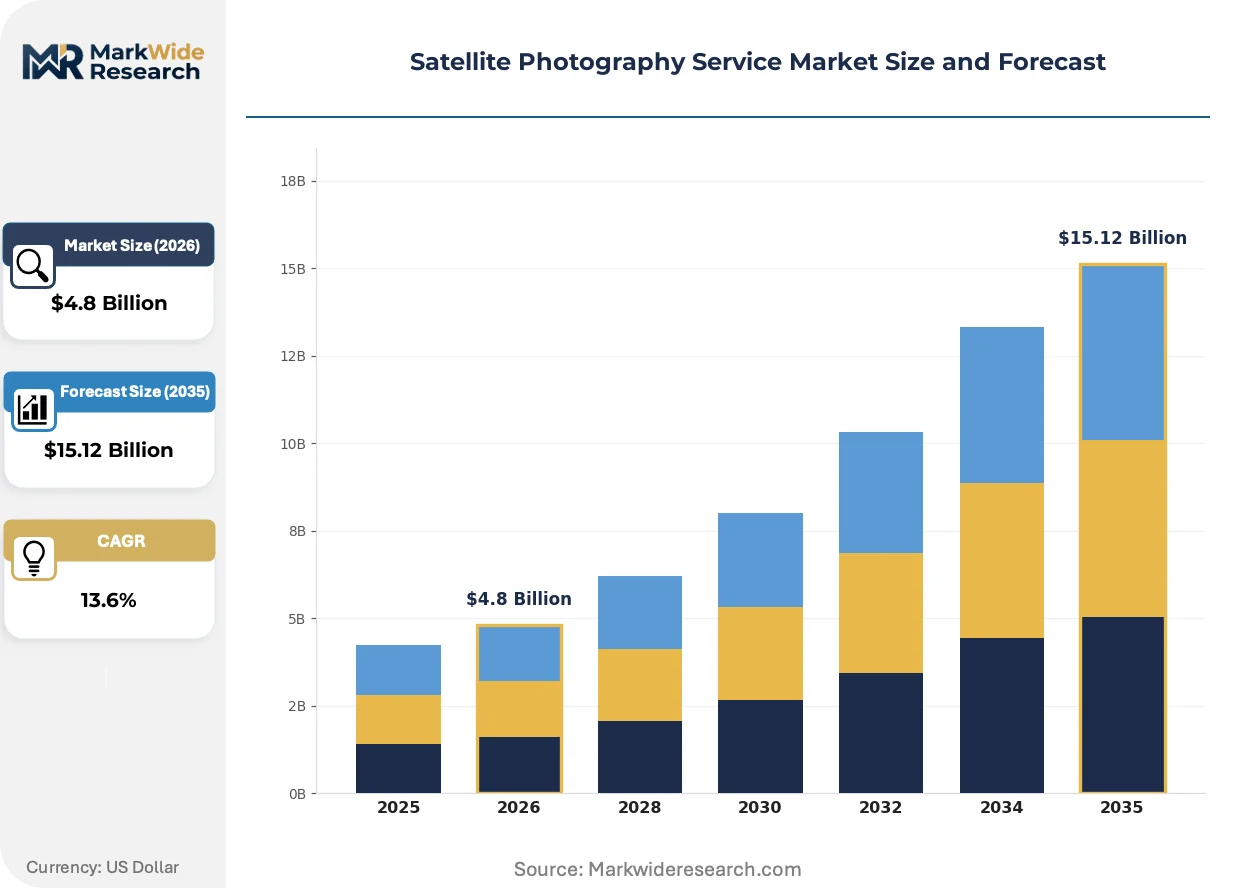
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.12 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Image Acquisition, Data Processing, Image Analysis, Cloud Storage, Geospatial Analytics Technology: Optical Imaging, Synthetic Aperture Radar, Multispectral Sensors, Hyperspectral Sensors, Thermal Imaging Application: Environmental Monitoring, Precision Agriculture, Urban Planning, Disaster Management, Maritime Surveillance End User: Government Agencies, Research Institutions, Energy Companies, Defense Contractors, Environmental Organizations |
| Companies Covered | Maxar Technologies, Airbus Defence and Space, Planet Labs PBC, L3Harris Technologies, ICEYE, Capella Space, Satellogic, BlackSky Technology, ImageSat International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Satellite Photography Service Market Trends and Innovations
Orbital sensor technology is converging with on-board edge computing, enabling real-time feature extraction before downlink. This compression of the analytics pipeline is restructuring competitive advantage toward software-defined payload architectures.
Very high-resolution optical systems are migrating from government-exclusive procurement to commercial subscription tiers. Agricultural cooperatives and commodity traders now access sub-meter imagery previously restricted to intelligence agencies. This democratization is compressing pricing power for legacy defense contractors while expanding total addressable volume across precision agriculture and infrastructure monitoring verticals.
The European Union's Space Programme is mandating open data policies for publicly funded Earth observation missions. This regulatory shift floods downstream markets with standardized imagery archives, forcing commercial operators to differentiate through proprietary analytics layers rather than raw data exclusivity. Smaller constellation operators face margin compression as Copernicus program outputs substitute for paid alternatives in environmental monitoring applications.
Insurance underwriters now specify satellite-derived property condition assessments as a condition of commercial policy renewal. This behavioral shift displaces traditional on-site inspection schedules with automated change-detection subscriptions. The transformation is most visible in catastrophe-prone coastal zones of Florida and the Gulf Coast, where carriers demand pre-event baseline imagery and post-disaster damage verification within 24-hour windows.
Satellite Photography Service Market Segmentation
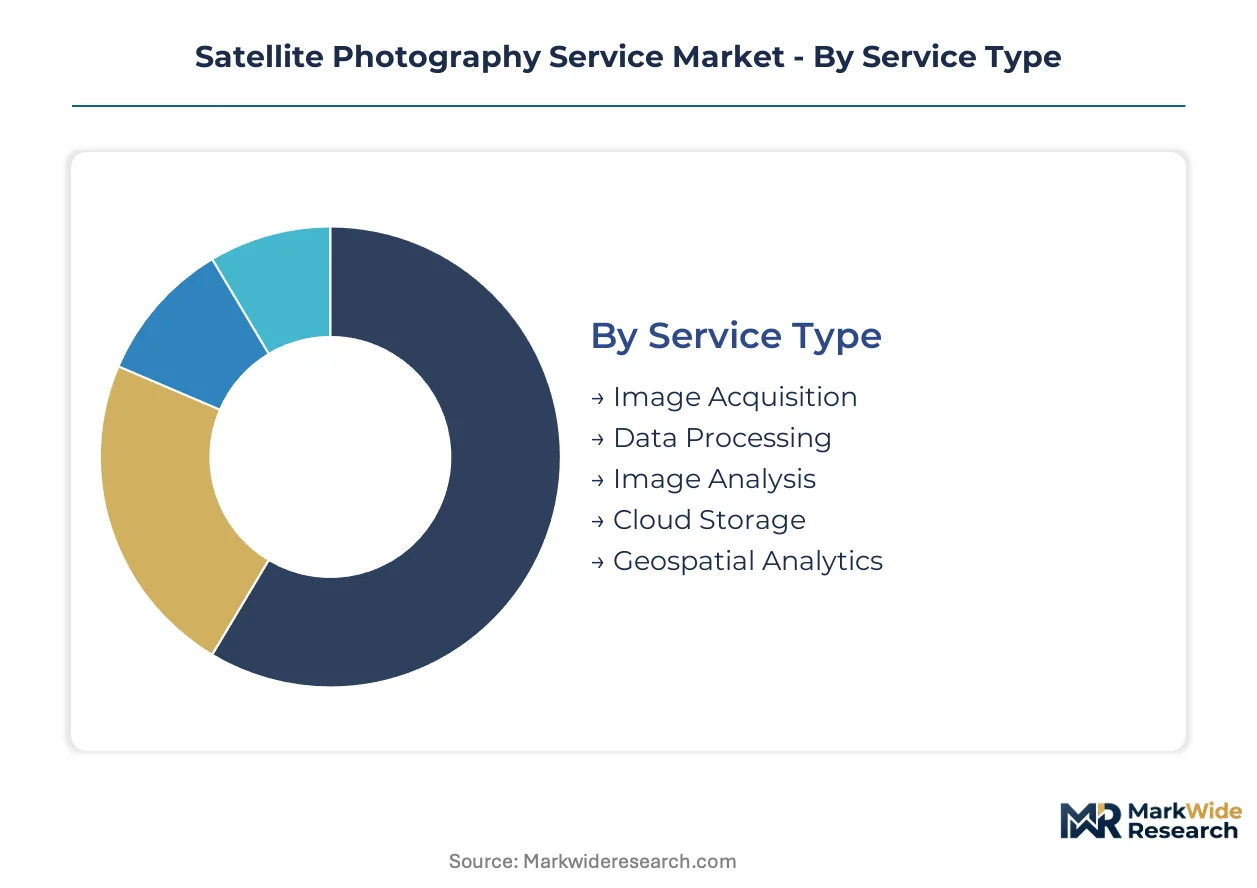
Service bundling intensity varies dramatically across satellite photography segments, with raw imagery commanding minimal recurring revenue while analytics layers generate multi-year subscription lock-in. Procurement patterns diverge sharply between defense classified programs and commercial self-service platforms, forcing operators to maintain dual delivery architectures.
Service Type:
After-sales engagement intensity peaks in analytics-heavy segments where customer success teams drive renewal rates through embedded workflow integration.
- Image Acquisition:Raw orbital capture services deliver unprocessed pixels at standardized resolution grades. Defense agencies in the United States dominate procurement through multi-year indefinite-delivery contracts with strict custody chain requirements.
- Geospatial Analytics:Value-added intelligence layers transform imagery into actionable decision support through automated feature extraction and predictive modeling. Agricultural commodity traders and catastrophe insurers now specify these outputs as mandatory inputs to underwriting workflows, compressing sales cycles and expanding annual contract values.
- Data Processing:Radiometric correction and orthorectification pipelines standardize raw sensor outputs for downstream consumption.
- Image Analysis:Human-in-the-loop interpretation services for change detection and object identification.
- Cloud Storage:Archive retention and rapid retrieval infrastructure for historical imagery libraries.
By volume, Image Acquisition leads. By growth pace, Geospatial Analytics is ahead.
Technology:
Cost tier stratification separates mature optical supply chains from capital-intensive radar development programs with extended payback horizons.
- Optical Imaging:Electro-optical sensors capture reflected visible and near-infrared radiation at sub-meter to 30-meter ground sample distances. Precision agriculture cooperatives in the United States Midwest and commodity crop traders drive commercial demand through growing season monitoring subscriptions.
- Synthetic Aperture Radar:Active microwave systems enable all-weather, day-night data collection independent of solar illumination or atmospheric conditions. Maritime surveillance authorities in Indonesia and Vietnam specify SAR for persistent vessel tracking through persistent tropical cloud cover, accelerating procurement outside traditional defense channels.
- Multispectral Sensors:Discrete band capture for vegetation health indices and mineral surface mapping.
- Hyperspectral Sensors:Continuous narrow-band spectral sampling for material identification and biochemical property estimation.
- Thermal Imaging:Long-wave infrared detection for heat signature monitoring and industrial facility assessment.
By maturity, Optical Imaging dominates. By expansion trajectory, Synthetic Aperture Radar climbs fastest.
Application:
Customer type concentration shapes service packaging, with government end-users requiring security-cleared personnel and commercial buyers demanding API-first integration.
- Environmental Monitoring:Ecosystem health assessment and land cover classification services support regulatory compliance and conservation finance. European Union Copernicus program open data policies flood this segment with subsidized alternatives, forcing commercial operators to differentiate through proprietary change-detection algorithms.
- Maritime Surveillance:Persistent ocean monitoring for illegal fishing enforcement, port security, and supply chain integrity. Southeast Asian port authorities and coast guard services are expanding procurement specifications to include real-time anomaly detection with sub-hourly revisit frequencies.
- Precision Agriculture:Variable rate input optimization and yield forecasting for commercial farming operations.
- Urban Planning:Infrastructure development tracking and informal settlement monitoring for municipal governments.
- Disaster Management:Rapid damage assessment and recovery coordination for humanitarian response agencies.
By contract value, Maritime Surveillance leads. By addressable expansion, Environmental Monitoring is broadening fastest.
End User:
Supply concentration clusters around defense and intelligence agencies with classified procurement thresholds that filter out capital-constrained entrants.
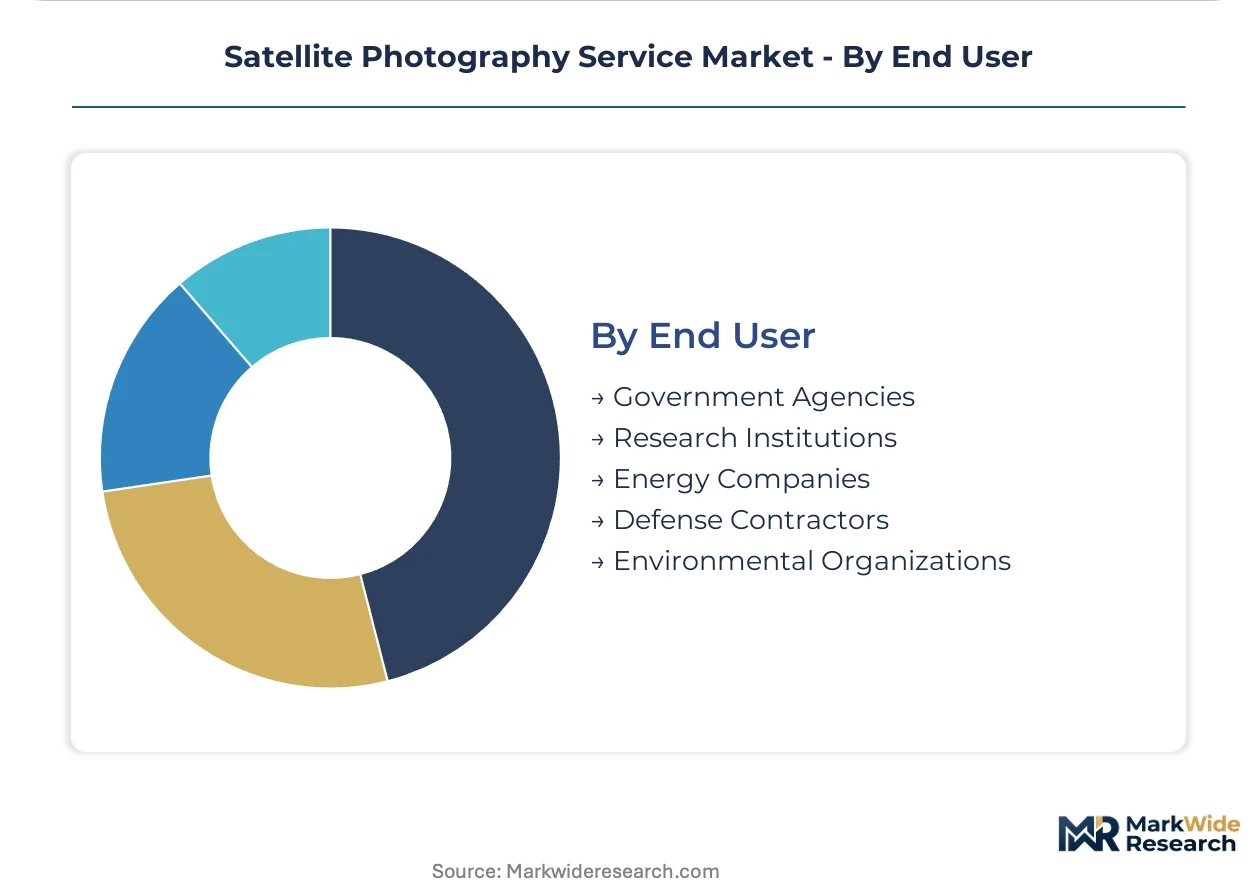
- Government Agencies:Civilian remote sensing programs and regulatory compliance monitoring drive sustained budget allocation. The National Oceanic and Atmospheric Administration and Federal Aviation Administration jointly govern licensing and operational compliance, creating multi-layer approval pathways that extend vendor qualification timelines.
- Defense Contractors:Prime systems integrators and classified program offices procure high-resolution imagery under restricted distribution protocols. Border surveillance and asset tracking mandates in the United States sustain premium pricing tiers unavailable to commercial counterparts.
- Research Institutions:Academic and non-commercial scientific access programs with publication-oriented data licensing.
- Energy Companies:Pipeline monitoring, exploration site assessment, and renewable energy resource mapping.
- Environmental Organizations:Conservation monitoring and advocacy-oriented transparency initiatives.
By spending scale, Defense Contractors lead. By procurement velocity, Government Agencies are accelerating.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense buyers in the United States accept premium pricing for classified orbital imagery, while agricultural cooperatives in Brazil and Indonesia drive hard volume negotiations for seasonal monitoring subscriptions. This elasticity split shapes regional go-to-market strategies across the value chain.
United States
Federal agencies sustain the highest contract values through classified border surveillance and asset tracking programs. The Federal Aviation Administration and National Oceanic and Atmospheric Administration jointly regulate launch licensing and remote sensing spacecraft compliance, filtering entrants by capital intensity. Denver and the Colorado Front Range host dense clusters of geospatial analytics firms serving defense primes.
Germany
Industrial automation conglomerates and automotive OEMs procure high-resolution imagery for supply chain facility monitoring. The EU Space Programme mandates open data policies that flood environmental monitoring segments with subsidized alternatives. Munich and Bavaria concentrate specialized sensor component manufacturers supplying precision optics to constellation operators.
China
State-owned aerospace groups deploy dual-use constellations for domestic resource mapping and maritime domain awareness. The Ministry of Industry and Information Technology governs satellite manufacturing standards and spectrum allocation. Beijing-Tianjin-Hebei anchors government-funded Earth observation research institutes and downstream analytics development.
Indonesia
Maritime surveillance authorities specify synthetic aperture radar for persistent vessel tracking through tropical cloud cover. Port authorities in Jakarta and Surabaya seek real-time anomaly detection for illegal fishing enforcement. The archipelago geography drives demand for sub-hourly revisit frequencies unavailable from traditional optical operators.
United Arab Emirates
Sovereign wealth vehicles and smart city developers commission high-resolution urban planning datasets for coastal infrastructure projects. The Mohammed bin Rashid Space Centre governs national space policy and international partnership frameworks. Dubai hosts regional headquarters for commercial satellite operators targeting Middle East and African markets.
Satellite Photography Service Market Competitive Landscape
Capability concentration sits with legacy defense contractors possessing government security clearances and orbital heritage; scale advantage sits with commercial CubeSat operators deploying dense constellations for daily Earth coverage. The market structures around three archetypes: premium-tier defense integrators, high-frequency commercial data providers, and specialized radar operators. Consolidation pressure runs through strategic partnerships between launch providers and constellation developers, plus vertical integration into proprietary analytics software.
Within the premium-tier defense segment, Maxar Technologies and L3Harris Technologies occupy positions anchored by classified program relationships and legacy orbital assets. Planet Labs PBC exemplifies the scale-driven commercial archetype through its extensive CubeSat fleet and subscription-based delivery models. ICEYE represents the specialized radar tier, differentiating through all-weather imaging capabilities that penetrate cloud cover and darkness.
| Leading Market Players |
|---|
| Maxar Technologies |
| Airbus Defence and Space |
| Planet Labs PBC |
| L3Harris Technologies |
| ICEYE |
| Capella Space |
| Satellogic |
| BlackSky Technology |
| ImageSat International |
| Others |
Pricing and Supply Chain Analysis
German and Japanese specialty manufacturers dominate high-precision optics and radar transmitter modules, anchoring margin capture in the sensor tier while downstream service providers compete on analytics bundling intensity. This upstream concentration forces constellation operators to absorb component cost volatility or push pricing pressure toward raw imagery commoditization.
Pricing Analysis
Multi-year subscription contracts for geospatial analytics generate the highest lifetime value, with agricultural commodity traders and catastrophe insurers specifying automated change-detection as mandatory workflow inputs. Three-tier pricing structure across premium, standard, and economy levels separates classified defense procurement from commercial self-service platforms and research access programs. Price differentiation hinges on resolution grade and security-cleared delivery personnel. Margins are tightening in raw imagery acquisition as Copernicus open data policies flood environmental monitoring segments with subsidized alternatives. Defense contractors show least price sensitivity; precision agriculture cooperatives negotiate hardest on seasonal volume.
Supply Chain Analysis
Extended payment terms from prime defense integrators cascade through Tier 2 payload integrators, compressing working capital for emerging constellation developers. Manufacturing concentrates in the United States for spacecraft final assembly, Germany for precision optics, and Japan for radar transmitter modules. Supply chains draw from gallium arsenide substrates, specialized optical glass, and radiation-hardened electronics. Single-source vulnerability in German and Japanese sensor component suppliers poses structural risk. Distribution runs through direct government indefinite-delivery contracts and API-first commercial platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The satellite photography service market functions as a defensive-moat industry where regulatory entrenchment through FAA launch licensing and NOAA remote sensing compliance creates durable barriers against capital-constrained entrants.
For Market Incumbents: Harden classified program relationships through security-cleared personnel retention and legacy ground station protocol compatibility. Deepen proprietary analytics layers to differentiate against Copernicus open data substitution. Prioritize synthetic aperture radar capacity additions in tropical maritime zones where persistent cloud cover eliminates optical competitors. For New Entrants and Emerging Players: Southeast Asian port authorities in Indonesia and Vietnam represent the most penetrable demand pocket, with sub-hourly revisit frequency requirements unmet by established operators. Carbon credit verification services for forest offset registries offer second white-space target with subscription-based recurring revenue potential. Lead with maritime surveillance specialization rather than competing head-to-head on daily Earth coverage. For Investors and Strategic Acquirers: Capital is best deployed toward specialized radar operators with all-weather technical differentiation and software-defined payload architectures enabling real-time edge analytics. Long-term viability rests on analytics revenue mix expansion rather than raw data volume scaling. Watch for FAA debris mitigation mandate tightening as inflection indicator forcing costly spacecraft redesigns or constellation contraction.| Strategic Initiative | Industry Significance |
|---|---|
| Synthetic Aperture Radar Capacity Expansion | All-weather imaging capabilities penetrate tropical cloud cover where optical systems fail. |
| Geospatial Analytics Platform Integration | Automated feature extraction embeds satellite data directly into insurance underwriting workflows. |
| Maritime Surveillance Partnership | Indonesian coast guard contracts specify real-time vessel tracking for illegal fishing enforcement. |
| AI-Assisted Change Detection Development | Machine learning models trained on historical archives enable infrastructure monitoring subscriptions. |
| Regulatory Compliance Certification Investment | FAA launch licensing and NOAA spacecraft compliance filter entrants by capital intensity thresholds. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with constellation program managers, geospatial analytics product leads, defense procurement officers, maritime surveillance authorities, and agricultural commodity trading desks. Secondary validation drew from FAA licensing databases, NOAA regulatory filings, EU Space Programme policy documents, customs trade records for sensor components, and SEC disclosures from publicly traded operators. Bottom-up segment sizing triangulated against top-down market envelope checks.
Calibration against historical contract award patterns and announced constellation deployment schedules anchored the analytical framework across the analysis window. Segmentation dimensions modeled include service type, sensor technology, application vertical, and end-user procurement channel. CAGRs derived from fitted growth curves applied to disclosed fleet expansion plans and subscription revenue recognition patterns. Forecast inputs incorporated launch cost compression trajectories from reusable rocket platforms and radar payload miniaturization curves.
The forecast holds incumbent behavior within observed patterns; aggressive moves by state-backed aerospace groups or well-capitalized software platforms would shift outcomes beyond modeled ranges. Macroeconomic contraction affecting defense discretionary budgets, tightening debris mitigation mandates, or breakthroughs in alternative aerial sensing platforms would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Asia-Pacific Remote Sensing Satellites Market
Satellite
Flat Panel Satellite Antenna Market
Satellite
France Satellite-Based Earth Observation Market
Satellite
Global Nanosatellite and Microsatellite Market
Satellite
Germany Satellite Imagery Services Market
Satellite
Aviation Satellite Antenna Systems Market
Satellite
Satellite Backhaul Market
Satellite
Global Satellite Based Earth Observation Market
Satellite
LEO Satellite Constellation Market
Satellite
Satellite Transponder Market
Satellite
North America Remote Sensing Services Market
Satellite
Cubesat Market
Satellite
Military Satellite Market
Satellite
United Kingdom Satellite Communications Market
Satellite
Nano and Microsatellite Market
Satellite
Communication Satellite Launch Services Market