
 Global Satellite Modem Market | 2026-2036
Global Satellite Modem Market Size, Share, and Industry Trends Forecast 2026-2036
Global Satellite Modem Market Intelligence
Maritime fleet connectivity is decoupling from legacy L-band dependency as shipping operators adopt high-throughput Ku-band and Ka-band VSAT systems. Gilat Satellite Networks leverages its vertically integrated hub infrastructure to capture terminal-to-cloud contracts with major container lines. Viasat competes through Ka-band capacity over the ViaSat-3 constellation, offering bandwidth economics that challenge fiber in offshore corridors. Hughes Network Systems anchors the North American enterprise segment with managed SD-WAN over satellite, sustaining subscriber density in rural broadband deserts.
A satellite modem is a specialized communications device that modulates baseband digital signals onto radio frequency carriers for transmission through geostationary, medium Earth orbit, or low Earth orbit satellite transponders, typically supporting symbol rates from 64 kbps to over 500 Mbps and incorporating forward error correction via LDPC or Turbo coding to maintain link integrity under atmospheric fading conditions. Its primary commercial purpose is to enable IP connectivity in locations where terrestrial fiber or cellular infrastructure is economically or physically impractical, spanning offshore platforms, military forward operating bases, and rural subscriber premises. VSAT modem shipments dominate volume due to proliferating two-way consumer broadband terminals, while Ka-band frequency segments attract the fastest equipment refresh cycles as operators migrate from wide-beam to high-throughput spot-beam architectures. Defense and government end users concentrate margin pools through ruggedized, NSA-certified modems with anti-jam waveforms and frequency-hopping capabilities.
The Federal Communications Commission governs orbital slot coordination and spectrum auctions in the United States, directly conditioning market access for non-geostationary constellation operators and their associated ground equipment vendors. The European Space Agency and national regulators in France, Germany, and Italy enforce CE marking and RED compliance for satellite terminals, creating certification barriers that favor established suppliers with in-house testing laboratories. ITU Radio Regulations mandate cross-border interference coordination, extending product development timelines but embedding incumbent relationships with national spectrum authorities. Stakeholders must monitor spectrum reallocation proceedings in C-band and emerging rules for direct-to-device satellite services, as these determinations will redirect R&D investment toward either legacy waveform optimization or next-generation 3GPP-NTN modem architectures.
Market Dynamics
Defense procurement cycles and software-defined radio migration are compressing hardware refresh timelines while fragmenting vendor lock-in across NATO satellite communication programs.
Growth Catalysts
- Space Force Modernization Budgets:United States Department of Defense allocations for protected tactical waveform terminals are accelerating ruggedized modem deployments across military forward operating bases.
- ITU Frequency Coordination Protocols:Harmonized cross-border interference standards are enabling multi-national constellation operators to certify single-modem designs across multiple regulatory domains simultaneously.
- Commercial LEO Constellation Deployments:Low Earth orbit broadband ventures in the United States are generating volume demand for flat-panel user terminals with integrated modem chipsets.
Market Restraints
- GaN and GaAs Semiconductor Supply Concentration:Gallium nitride and gallium arsenide substrate production concentrates in East Asian foundries, creating single-source vulnerability for high-power amplifier modules.
- NSA Certification Timeline Friction:Type-1 encryption validation requirements extend product development cycles by 18-24 months for defense-grade modems.
- Fiber Backhaul Substitution:Subsea cable capacity expansion along transoceanic corridors is displacing satellite links for fixed offshore platform connectivity.
Strategic Opportunities
- Direct-to-Device Satellite Services:3GPP NTN standardization is opening unmodified smartphone connectivity markets previously unreachable by VSAT terminals.
- India Rural Broadband Initiative:The country's universal service obligation fund is subsidizing satellite backhaul for village-level Wi-Fi hotspots.
- Software-Defined Waveform Convergence:Integration of 5G NR and DVB-S2X protocols onto common FPGA architectures is collapsing separate modem product lines into unified platforms.
Industry Challenges
- RF Engineering Talent Scarcity:Specialized microwave design expertise pools concentrate in defense contractor hubs, constraining commercial vendor hiring pipelines.
- Legacy MIL-STD-188 Integration Complexity:Backward compatibility requirements with obsolete satellite control protocols inflate firmware architecture costs.
- CE Marking Test Queue Congestion:European Space Agency notified body capacity constraints extend RED compliance timelines for new terminal introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Satellite Modem Market |
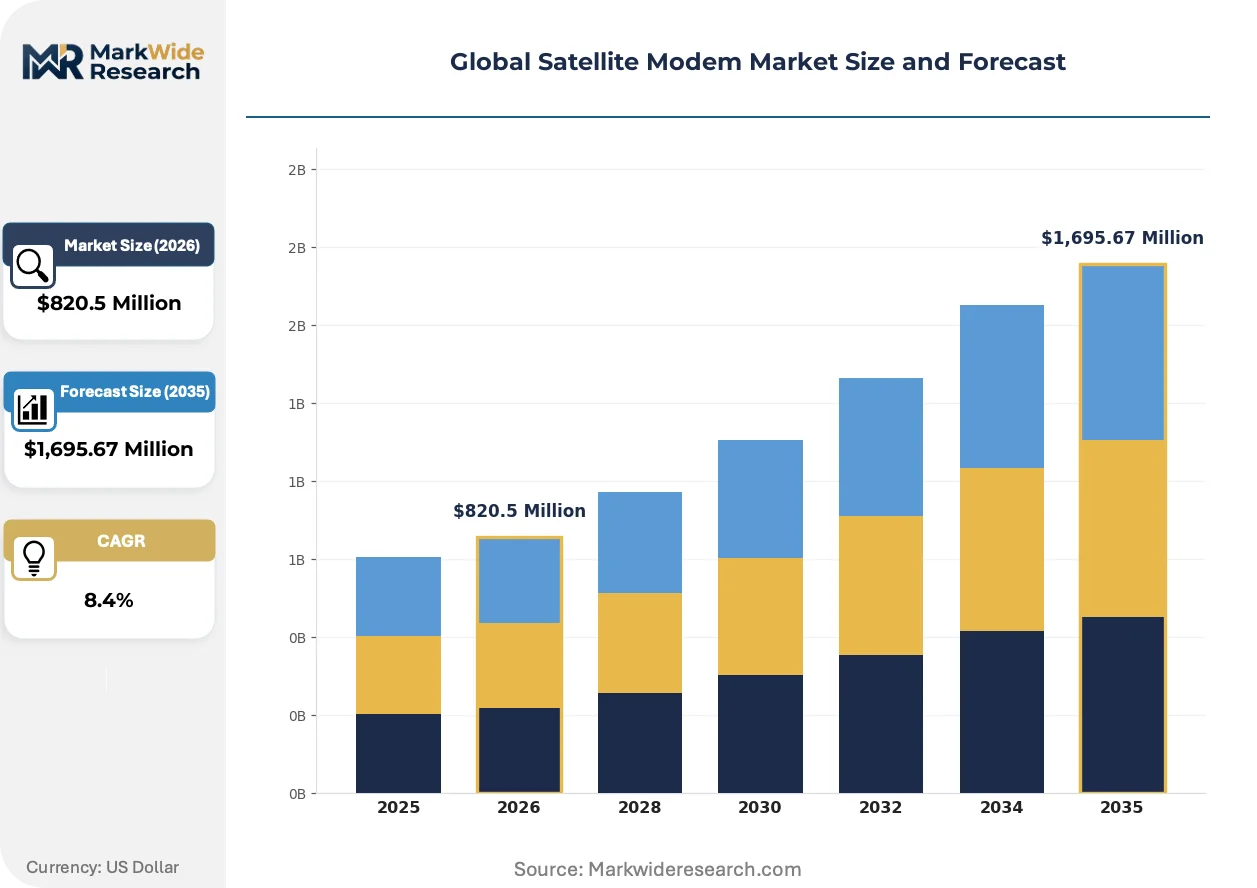
| Market Size in 2026 | $820.5 Million |
| Market Size in 2035 | $1,695.67 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Modem Type: VSAT, SCPC, TDMA, FDMA Application: Broadcasting, Defense, Remote Sensing, Maritime End User: Telecommunication, Government, Aerospace, Oil & Gas Frequency Band: C Band, Ku Band, Ka Band, X Band |
| Companies Covered | Gilat Satellite Networks Ltd., Datum Systems Inc., Viasat, Inc., Teledyne Technologies, ORBCOMM Inc., Hughes Network Systems, ST Engineering iDirect Inc., NovelSat, Comtech Telecommunications Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Satellite Modem Market Strategic Shifts & Innovations
Waveform virtualization and open-architecture modem platforms are dissolving proprietary hardware boundaries that historically protected incumbent supplier margins.
Artificial intelligence-driven link optimization is automating real-time modulation and coding adjustments that previously required manual engineering intervention. Maritime operators adopting autonomous vessel architectures are demanding self-healing satellite connectivity without shore-side technician oversight. This compression of operational human-in-the-loop functions is automating service delivery economics previously dependent on specialized VSAT engineering teams.
REACH substance restrictions and the EU F-Gas Regulation are phasing out hydrofluorocarbon-based thermal management fluids in outdoor modem enclosures. European terminal manufacturers are redesigning heat dissipation architectures to accommodate forced-air and liquid-cooling alternatives. Ka-band gateway equipment destined for France, Germany, and Italy faces accelerated compliance deadlines that compress product redesign windows ahead of standard technology refresh cycles.
Container lines are unbundling connectivity procurement from vessel management contracts, creating direct relationships between shipping operators and satellite service providers. This disintermediation of systems integrators concentrates purchasing power with fleet technical departments that prioritize bandwidth economics over bundled maintenance packages. The North Atlantic and Asia-Europe trade corridors exhibit the most pronounced shift toward standalone modem procurement with multi-orbit roaming capabilities.
Global Satellite Modem Market Segmentation
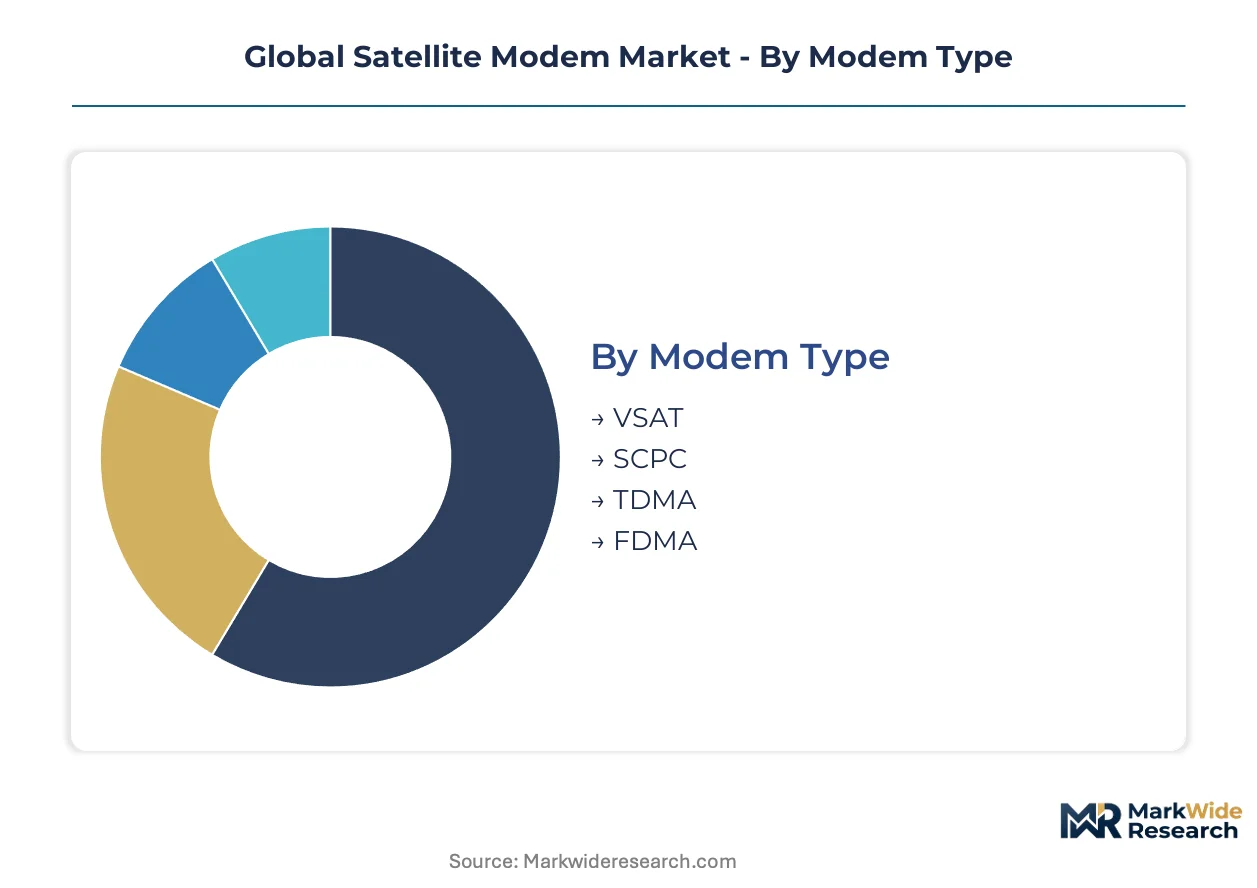
Satellite modem segmentation reveals divergent margin profiles across waveform architectures and frequency allocations. Equipment specifications fragment sharply between commercial volume terminals and defense-grade hardened platforms, with procurement channels and certification requirements creating distinct competitive arenas.
Modem Type:
Volume concentrates in standardized VSAT terminals while premium margins attach to specialized military waveforms.
- VSAT:Two-way consumer and enterprise terminals dominate shipment volumes through flat-panel and parabolic antenna integration. Rural broadband deployments in the United States and maritime connectivity contracts with Mediterranean shipping operators concentrate procurement.
- SCPC:Single channel per carrier architectures deliver dedicated bandwidth for broadcast backhaul and oil platform telemetry. Energy majors operating North Sea and Gulf of Mexico assets favor SCPC for guaranteed throughput to unmanned offshore installations.
- TDMA:Time division multiple access enables efficient bandwidth pooling across dispersed enterprise networks.
- FDMA:Frequency division multiple access persists in legacy government satellite control networks requiring protocol backward compatibility.
Today's leader: VSAT. Tomorrow's challenger: SCPC.
Application:
Defense procurement concentrates margin pools while maritime fleet refresh drives volume acceleration.
- Broadcasting:Contribution and distribution networks for live event transmission require low-latency, high-availability links. Sports rights holders across Latin America and Southeast Asia are upgrading SNG vehicles to Ka-band mobility terminals.
- Defense:Protected tactical waveforms with anti-jam and frequency-hopping capabilities command equipment premiums. NATO member states are standardizing on NSA-certified modems for interoperable forward operating base connectivity.
- Remote Sensing:Earth observation ground stations demand high-data-rate downlink reception for synthetic aperture radar and multispectral payloads.
- Maritime:Container line fleet operators are decoupling connectivity procurement from vessel management contracts.
Defense commands pricing power. Maritime expands most quickly.
End User:
Telecommunication service providers anchor commercial volumes while aerospace integrators specify custom form factors.
- Telecommunication:Mobile network operators deploy satellite backhaul for rural cell site connectivity. India's universal service obligation fund is subsidizing village-level Wi-Fi hotspot infrastructure with satellite modem termination.
- Government:Civilian agencies require Type-2 encryption for disaster response and diplomatic communications. The European Space Agency and national regulators in France, Germany, and Italy enforce CE marking and RED compliance.
- Aerospace:Satellite manufacturers integrate proprietary modem chipsets into payload data handling units.
- Oil & Gas:Exploration and production companies specify explosion-proof enclosures for upstream platform deployment.
Telecommunication scales volume. Government captures margin.
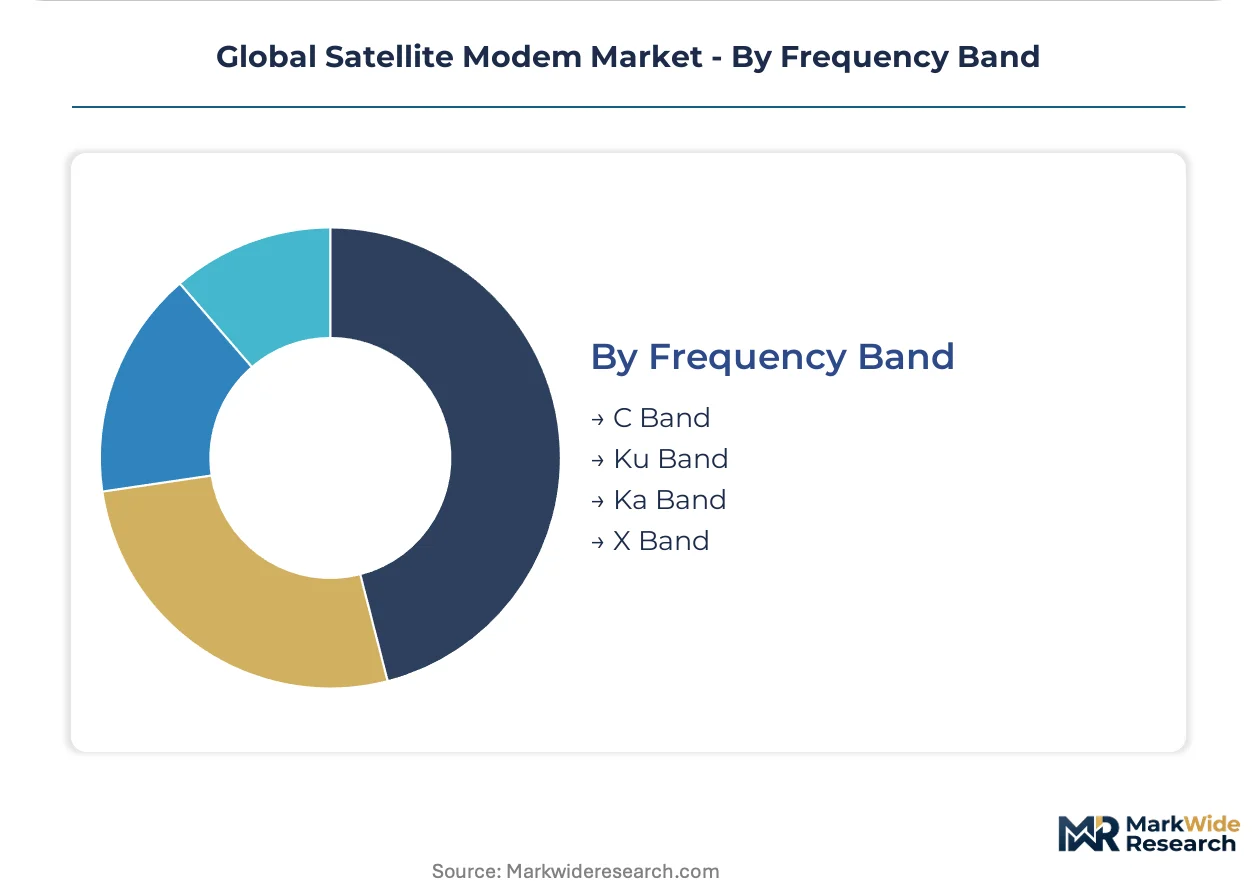
Frequency Band:
Ka-band attracts equipment refresh investment while C-band faces spectrum reallocation pressure.
- Ku Band:Mature high-throughput satellite capacity supports mainstream enterprise VSAT and maritime mobility services. Shipping operators across Asia-Europe trade corridors are migrating from legacy L-band to Ku-band VSAT for crew welfare and operational connectivity.
- Ka Band:Spot-beam high-throughput architectures enable bandwidth economics challenging fiber in offshore corridors. The ViaSat-3 constellation and competing systems are stimulating terminal demand with gigabit-class service offerings.
- C Band:Incumbent broadcast and government links face ITU-mandated spectrum clearing timelines.
- X Band:Military-exclusive allocation supports protected tactical communications with dedicated satellite constellations.
Ku Band holds installed base. Ka Band gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States Space Coast corridor in Florida anchors satellite modem manufacturing and ground systems integration, with Cape Canaveral serving as the primary launch coordination hub for commercial constellation operators.
United States
Space Force modernization budgets and commercial LEO constellation deployments drive procurement volume. The FCC governs orbital slot coordination and spectrum auctions, conditioning market access for non-geostationary operators. California's Silicon Valley hosts flat-panel terminal developers integrating modem chipsets for broadband ventures.
France
European Space Agency programs and national defense procurement sustain demand for ruggedized terminals. ANSM and national regulators enforce CE marking and RED compliance, creating certification barriers favoring established suppliers. Toulouse's aerospace cluster concentrates satellite manufacturer headquarters specifying custom modem form factors.
Germany
Broadcast contribution networks and maritime fleet operators upgrade to Ka-band mobility terminals. The KBA and federal spectrum authorities coordinate ITU-mandated interference standards for cross-border constellation operations. Munich's engineering corridor hosts ground station equipment vendors serving NATO satellite communication programs.
India
The universal service obligation fund subsidizes satellite backhaul for village-level Wi-Fi hotspots in rural broadband initiatives. TRAI regulates spectrum allocation for commercial satellite services, extending product development timelines through multi-agency coordination. Bengaluru's technology corridor attracts terminal manufacturers establishing regional assembly operations.
United Kingdom
Defense procurement for protected tactical waveforms and maritime connectivity contracts concentrate demand. National regulators align with ESA frameworks for RED compliance and spectrum coordination. Harwell's space cluster hosts satellite operators specifying ground segment equipment for Earth observation downlink reception.
Global Satellite Modem Market Key Industry Players
Strategic partnerships dominate the current landscape as vendors align with constellation operators and systems integrators. The vendor base fragments across defense contractors, commercial terminal manufacturers, and semiconductor suppliers, with tiered positioning separating NSA-certified suppliers from volume consumer equipment makers. Three archetypes occupy distinct positions: vertically integrated hub infrastructure operators, specialized waveform developers, and managed service providers bundling connectivity with hardware. M&A activity and technology licensing agreements represent the primary competitive moves reshaping supplier relationships.
Within the integrated infrastructure tier, Gilat Satellite Networks Ltd. and Viasat, Inc. exemplify operators capturing terminal-to-cloud contracts through captive hub assets. Hughes Network Systems anchors the North American managed services segment, representing the service-provider archetype that bundles SD-WAN delivery with subscriber premises equipment. These three companies occupy positions that illustrate the market's divergence between hardware-centric and service-anchored competitive strategies.
| Leading Market Players |
|---|
| Gilat Satellite Networks Ltd. |
| Datum Systems Inc. |
| Viasat, Inc. |
| Teledyne Technologies |
| ORBCOMM Inc. |
| Hughes Network Systems |
| ST Engineering iDirect Inc. |
| NovelSat |
| Comtech Telecommunications Corp. |
| Others |
Cost & Logistics Intelligence
Defense procurement standardization across NATO member states is compressing supplier qualification timelines and forcing foundries to absorb certification costs that ultimately flow through to terminal pricing. This buyer-driven specification convergence is reshaping how modem manufacturers negotiate component sourcing and where they locate final assembly.
Pricing Analysis
Input-cost pass-through from gallium nitride and gallium arsenide substrate shortages is compressing margins on high-power amplifier modules. Three-tier pricing structure across NSA-certified defense, ruggedized industrial, and commercial consumer levels separates procurement channels. Pricing pressure stems from fiber backhaul substitution along subsea cable corridors. Commercial volume buyers exhibit highest price sensitivity; defense agencies prioritize waveform interoperability over unit cost.
Supply Chain Analysis
India's PLI scheme for telecom equipment and local-content mandates in the United States Space Force procurement programs are reshaping sourcing footprints for final assembly operations. GaN and GaAs semiconductor fabrication concentrates in Taiwan, South Korea, and Japan. Raw material dependencies span rare-earth substrates, high-frequency laminates, and precision RF connectors. Single-source vulnerability in East Asian foundries threatens amplifier module availability. Distribution runs through authorized defense integrators and commercial service provider channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
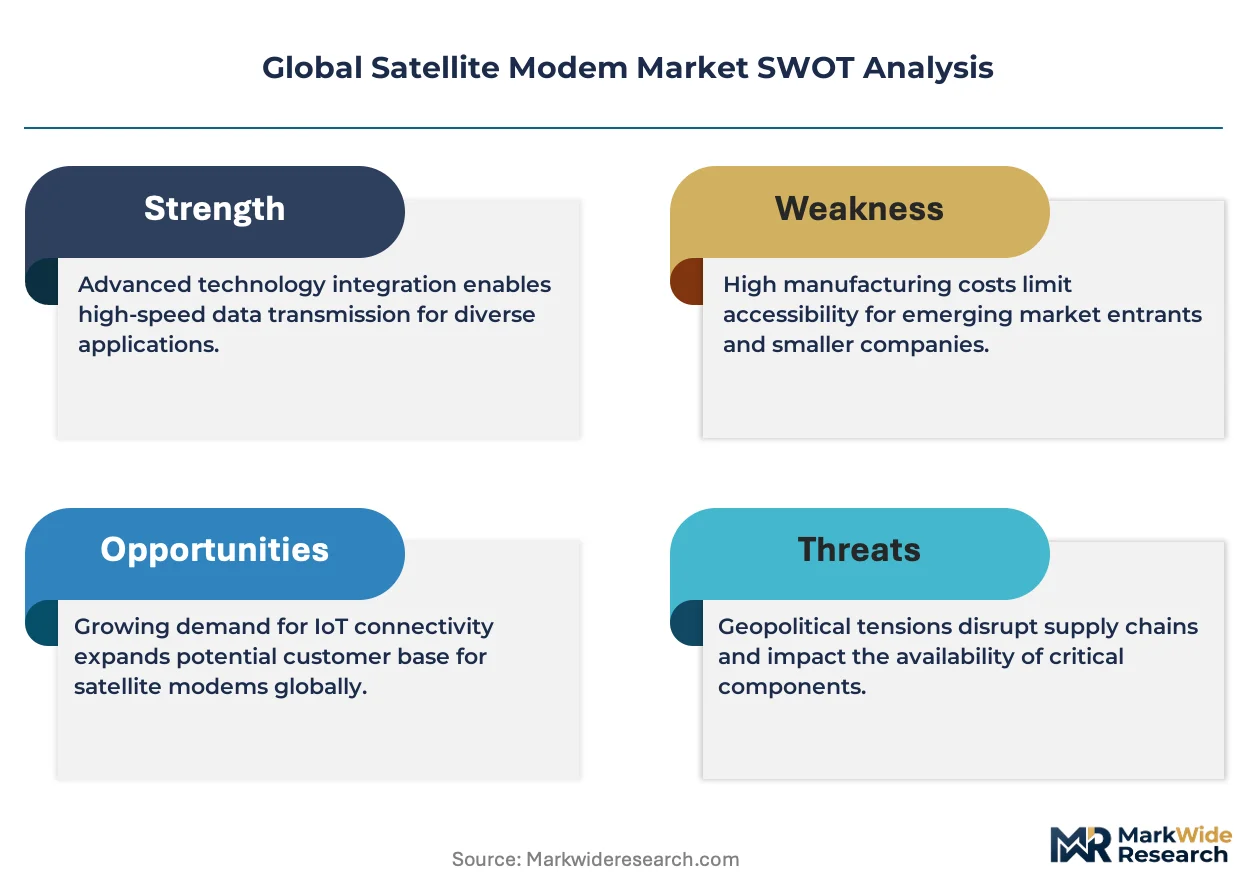
The satellite modem market functions as a stable compounder anchored by defense procurement cycles that refresh on predictable multi-year horizons regardless of commercial demand volatility.
For Market Incumbents: Hedge against GaN foundry concentration by qualifying secondary substrate suppliers in Japan and Israel. Secure captive hub infrastructure through long-term terminal-to-cloud contracts with container lines before maritime procurement fully disintermediates systems integrators. NSA certification investment remains the critical defensive moat against commercial entrants. For New Entrants and Emerging Players: Enter via India's rural broadband subsidy program where universal service obligation fund disbursements create immediate addressable demand for low-cost VSAT terminals. Target village-level Wi-Fi hotspot deployments as the most penetrable segment. Pursue white-label partnerships with regional mobile network operators lacking satellite engineering capabilities. For Investors and Strategic Acquirers: Asymmetric upside sits with software-defined waveform developers possessing FPGA architectures that collapse separate modem product lines into unified platforms. The five-to-ten-year viability window favors acquisition targets with 3GPP NTN standardization roadmaps and existing relationships with national spectrum authorities. Monitor ITU spectrum reallocation proceedings in C-band as the inflection signal for R&D investment redirection.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Waveform Convergence | Integration of 5G NR and DVB-S2X protocols onto common FPGA architectures collapses separate product lines. |
| Backward Integration into GaN Foundry Capacity | Captive substrate production mitigates single-source vulnerability in East Asian semiconductor supply. |
| Direct-to-Device Satellite Service Development | 3GPP NTN standardization opens unmodified smartphone connectivity markets previously unreachable by VSAT. |
| Multi-Orbit Roaming Certification | ITU frequency coordination protocols enable single-modem designs across geostationary and low Earth orbit constellations. |
| CE Marking and RED Compliance Investment | European Space Agency laboratory capacity accelerates terminal introductions for France, Germany, and Italy markets. |
Research Approach
Multiple input streams — primary interviews with satellite modem engineering directors, defense procurement officers, and maritime fleet technical managers, alongside secondary validation through FCC spectrum auction records, ITU Radio Regulations filings, and ESA program documentation — were reconciled to construct demand and supply estimates. Bottom-up terminal shipment tallies by frequency band and application were cross-checked against top-down service provider capacity deployment announcements.
Data-stream reconciliation across the projection horizon employed segmentation by modem type, frequency allocation, end-user vertical, and regional regulatory cluster. CAGRs were derived from fitted growth curves anchored to disclosed procurement budgets and constellation deployment timelines. Forecast inputs incorporated Space Force modernization appropriations, commercial low Earth orbit constellation launch manifests, and fiber backhaul expansion along transoceanic corridors.
The model holds under stable defense procurement continuity and uninterrupted gallium nitride substrate supply; deviation in NATO interoperability requirements or East Asian foundry export restrictions would shift volume and value trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Satellite Communication Subsystem Market
Satellite
Mexico Satellite Connectivity Market
Satellite
M2M Satellite Communication Market
Satellite
Satellite Data Analytics Services Market
Satellite
Europe Satellite Manufacturing and Launch Systems Market
Satellite
Asia-Pacific Military Satellite Market
Satellite
France Satellite Connectivity Market
Satellite
Sudan Satellite Transponder Market
Satellite
Saudi Arabia Satellite Imagery Services Market
Satellite
Satellite Payload Market
Satellite
South Korea Satellite Imagery Services Market
Satellite
GEO Satellite Market
Satellite
Satellite Parts and Components Market
Satellite
Europe Satellite Manufacturing Market
Satellite
South Korea Satellite-Based Earth Observation Market
Satellite
Commercial Satellite Launch Service Market