
 Asia-Pacific Satellite Launch Vehicle Market | 2026-2036
Asia-Pacific Satellite Launch Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Satellite Launch Vehicle Market Insights
Japan's METI clean-space initiative is broadening procurement criteria for domestic launch services, requiring methane-oxygen propulsion trials and stage reusability roadmaps. Mitsubishi Heavy Industries anchors Japan's orbital capacity through the H3 launch system and its Tanegashima Space Center operations. China Aerospace Science and Technology Corporation dominates China's state-backed manifest with Long March series production at its Tianjin manufacturing complex. ISRO competes on cost discipline through its Polar Satellite Launch Vehicle program and the upcoming Small Satellite Launch Vehicle for dedicated rideshare missions.
Asia-Pacific satellite launch vehicles are rocket systems engineered to deliver payloads between 150 kg and 25,000 kg into low-Earth, medium-Earth, or geostationary transfer orbits, utilizing solid and liquid propulsion stages with thrust vectoring and payload fairing separation mechanisms. Their primary purpose is to place commercial communications satellites, Earth observation platforms, and navigation constellations into precise orbital trajectories. Small Satellite Launchers represent the fastest-expanding vehicle category as operators in Australia, South Korea, and Singapore pursue dedicated access for synthetic aperture radar and IoT relay networks. Heavy-Lift Launchers concentrate margin pools around geostationary communications satellites and lunar trajectory missions, while Government Agencies remain the anchor end-user segment through national space programs and defense signaling payloads.
India's CEA and ISRO coordinate launch range safety and spectrum allocation under the Indian Space Policy framework, while China's SAMR and MIIT enforce GB standards for propellant handling and launch site environmental compliance. Japan's METI and JAXA administer launch licensing through the Space Activities Act, with particular scrutiny of debris mitigation plans for sun-synchronous missions. Stakeholders must monitor how Australia's emerging Space Agency licensing regime and South Korea's KARI commercialization directives reshape competitive access across the region's launch ranges.
Market Dynamics
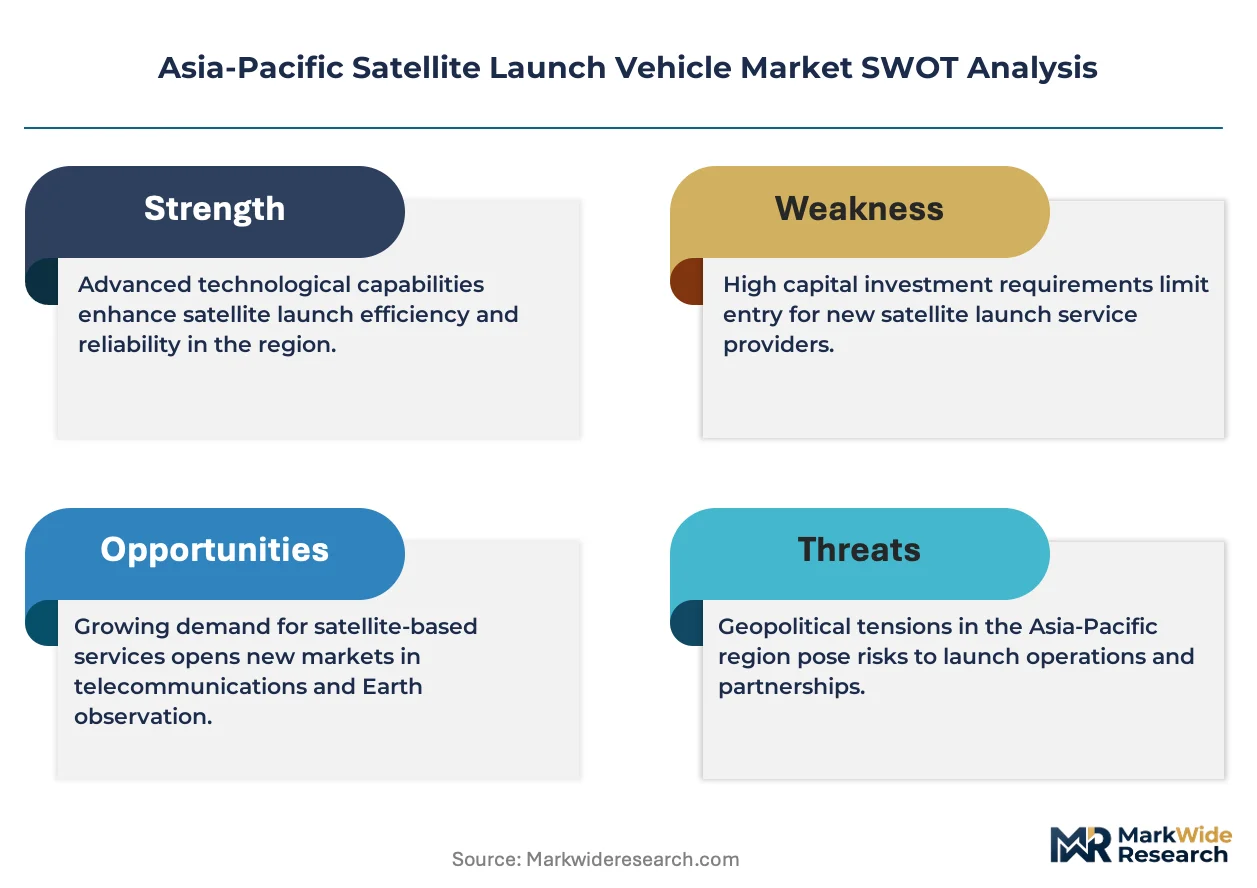
Reusable stage recovery programs across China and Japan are compressing per-launch costs and forcing established providers to accelerate propulsion modernization roadmaps or cede rideshare contracts to agile entrants.
Growth Catalysts
- India's Space Policy framework:The CEA-ISRO coordination mechanism streamlines launch range safety approvals and spectrum allocation, cutting time-to-launch for commercial Earth observation constellations.
- Synthetic aperture radar demand:Australian and Singaporean operators are procuring dedicated small-launcher slots for maritime surveillance and disaster monitoring payloads.
- Methane-oxygen propulsion trials:Japan's METI clean-space initiative mandates domestic providers demonstrate reusable stage recovery capabilities to qualify for government manifest priority.
Market Restraints
- Propellant supply concentration:High-purity liquid oxygen and kerosene sourcing clusters around Tianjin and Tanegashima, exposing launch schedules to regional logistics bottlenecks.
- GB standards compliance costs:China's SAMR and MIIT enforcement of propellant handling and environmental protocols at coastal launch sites adds fixed certification overhead for foreign payload integrators.
- Geostationary slot scarcity:ITU orbital filing backlogs and physical congestion at 36,000 km are extending mission lead times beyond heavy-launcher production cycles.
Strategic Opportunities
- South Korea's KARI commercialization directives:Naro Space Center infrastructure upgrades and private launch licensing pathways are opening dedicated access for regional IoT relay networks.
- Dual carbon goals alignment:China's MEE incentives for cleaner propellant formulations create procurement preference for domestic providers with demonstrated carbon intensity reductions.
- Lunar trajectory missions:Heavy-lift capacity demand for cislunar logistics and sample return programs is outpacing current Long March and H3 manifest availability.
Industry Challenges
- Turbopump manufacturing skills gap:Precision machining and cryogenic sealing expertise for staged-combustion engines remains concentrated at legacy state enterprises, constraining workforce mobility.
- Debris mitigation certification timelines:JAXA's sun-synchronous mission licensing requires exhaustive end-of-life disposal plans, extending pre-launch documentation cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Satellite Launch Vehicle Market |
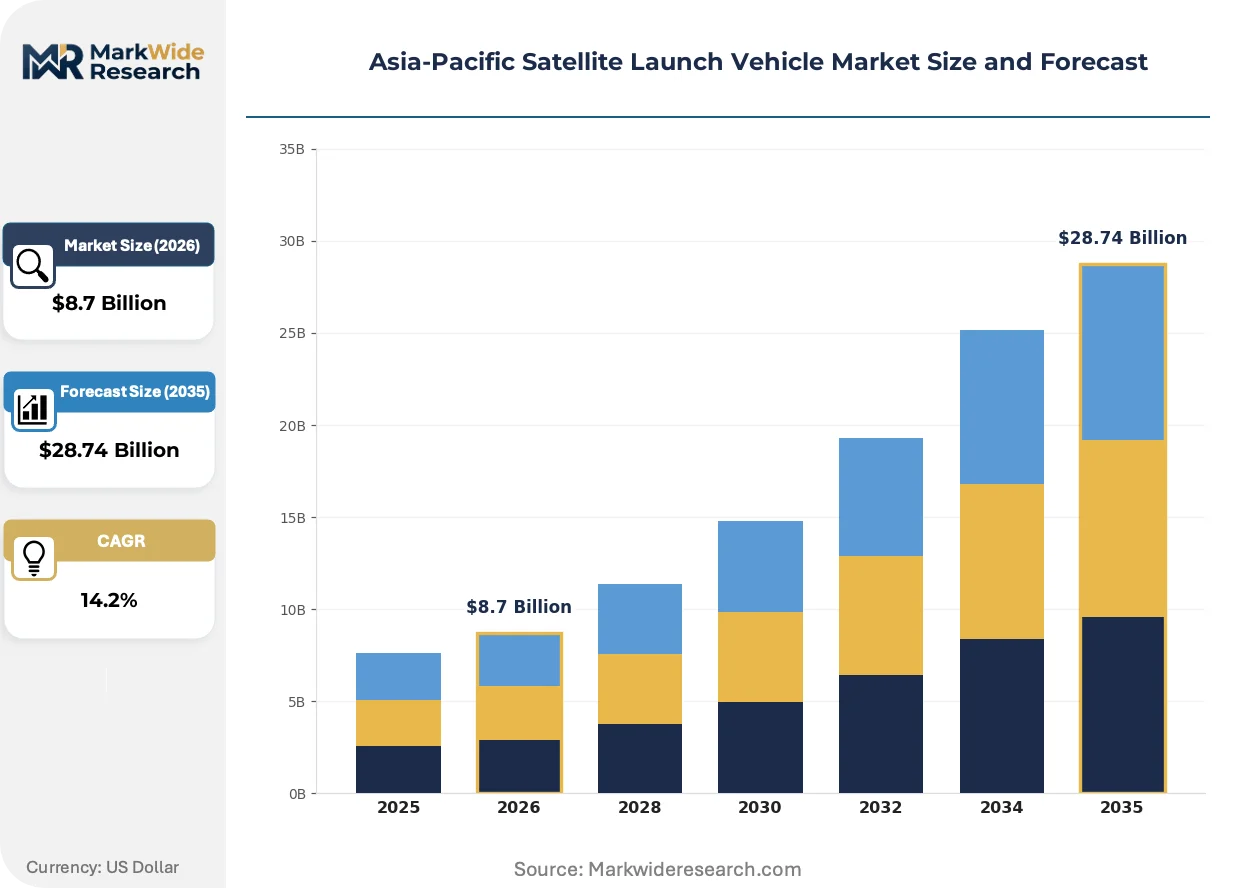
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Orbital Launch Vehicles, Suborbital Launch Vehicles, Small Satellite Launchers, Heavy-Lift Launchers Payload Capacity: Under 500 kg, 500-1000 kg, 1000-2500 kg, Over 2500 kg Launch Frequency: Monthly, Quarterly, Biannually, Annually End User: Government Agencies, Commercial Enterprises, Research Institutions, Defense Organizations |
| Companies Covered | Mitsubishi Heavy Industries, Rocket Lab USA, China Aerospace Science and Technology Corporation (CASC), The Boeing Company, Space Exploration Technologies Corp, China Great Wall Industry Corporation (CGWIC), Japan Aerospace Exploration Agency (JAXA), Ariane Group, Indian Space Research Organisation (ISRO), Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Satellite Launch Vehicle Market Trends and Innovations
Propulsion architecture choices and procurement contracting models are diverging sharply between state-backed heavy-lift programs and commercial small-launcher ecosystems.
Staged-combustion methane engines are consolidating technical roadmaps across Asia-Pacific launch providers. These powerplants offer superior specific impulse and throttle range for reusable first stages. ISRO and private Indian entrants are bench-testing full-flow staged combustion ahead of SSLV block upgrades. The technology is consolidating competitive positioning around rapid turnaround and propellant cost efficiency versus legacy kerolox systems.
Japan's Space Activities Act amendments are tightening debris mitigation enforcement for all sun-synchronous launches from Tanegashima. Operators must now demonstrate active deorbit capability or graveyard orbit placement with 99% reliability. Domestic Earth observation constellations and foreign rideshare customers face extended pre-mission review cycles as JAXA implements enhanced tracking and collision avoidance protocols.
Fixed-price launch service contracts are displacing cost-plus arrangements for commercial satellite operators in India and Australia. Constellation developers are negotiating multi-launch block buys with performance guarantees and on-orbit insurance bundling. This shift is most visible among synthetic aperture radar and broadband providers seeking predictable unit economics across 12-24 month deployment windows.
Asia-Pacific Satellite Launch Vehicle Market Segmentation
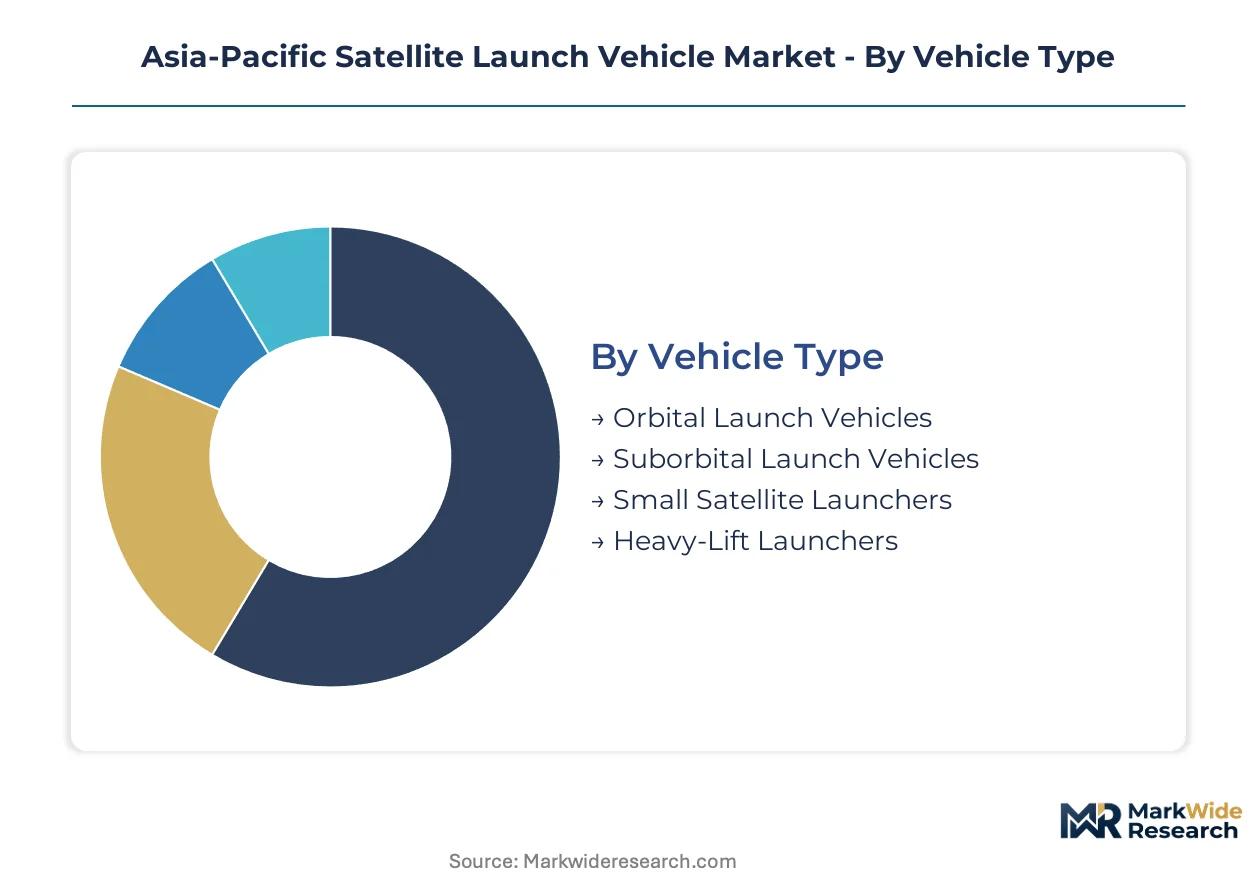
Launch vehicle segmentation in the Asia-Pacific region reveals how propulsion scale and payload economics fragment procurement patterns. Vehicle classification determines range access, insurance premiums, and manifest priority at Tanegashima, Satish Dhawan, and Jiuquan launch complexes.
Vehicle Type:
Production capabilities cluster around state-backed heavy-lift infrastructure and emerging private small-launcher foundries.
- Orbital Launch Vehicles:Multi-stage systems achieving stable Earth orbit insertion through liquid propulsion stages with restartable upper engines. ISRO's PSLV program and CASC's Long March series anchor regional capacity for medium-Earth and geostationary missions, constrained by turbopump manufacturing bottlenecks at legacy state enterprises.
- Small Satellite Launchers:Dedicated single-core or air-launched systems optimized for 150-500 kg payloads to sun-synchronous orbits. Australian and Singaporean operators are procuring slots for synthetic aperture radar constellations, driving demand for rapid turnaround and dedicated rideshare alternatives to piggyback arrangements.
- Suborbital Launch Vehicles:Sounding rockets and testbed platforms for microgravity research and propulsion qualification.
- Heavy-Lift Launchers:Staged-combustion systems exceeding 10,000 kg to geostationary transfer orbit, concentrated at CASC's Tianjin production complex and Mitsubishi Heavy Industries' Nagoya facilities.
Heavy-Lift Launchers absorb the bulk of installed capacity; Small Satellite Launchers are expanding most quickly.
Payload Capacity:
Mass thresholds determine launch site compatibility and propellant loading protocols across the region's coastal ranges.
- Under 500 kg:CubeSat and microsatellite form factors requiring minimal fairing volume and simplified payload adapters. Research Institutions in South Korea and Australia dominate procurement for technology demonstration missions, pressured by JAXA's debris mitigation certification timelines.
- 500-1000 kg:Smallsat constellations and dedicated Earth observation platforms. Commercial Enterprises in India negotiate fixed-price block buys for broadband relay networks, displacing cost-plus contracting as unit economics stabilize.
- 1000-2500 kg:Medium-class communications and navigation satellites.
- Over 2500 kg:Geostationary communications platforms and lunar trajectory payloads.
Over 2500 kg payloads command premium manifest slots; Under 500 kg volumes are climbing the fastest.
Launch Frequency:
Cadence requirements separate national program schedules from commercial constellation deployment economics.
- Monthly:Rapid-response launch services for reconnaissance and emergency communications replenishment. Defense Organizations in Japan and India sustain this cadence through dedicated range reservations, though propellant supply concentration at Tianjin and Tanegashima exposes schedules to logistics interruptions.
- Quarterly:Synthetic aperture radar constellation refresh and navigation satellite replenishment. Commercial Enterprises align procurement with insurance renewal cycles and on-orbit spare positioning.
- Biannually:Heavy geostationary satellite replacement and interplanetary mission windows.
- Annually:Flagship scientific payloads and technology demonstration missions.
Quarterly cadence captures the majority of commercial contracts; Monthly services are gaining share fastest.
End User:
Customer type dictates funding stability, technical specification stringency, and debris mitigation documentation depth.
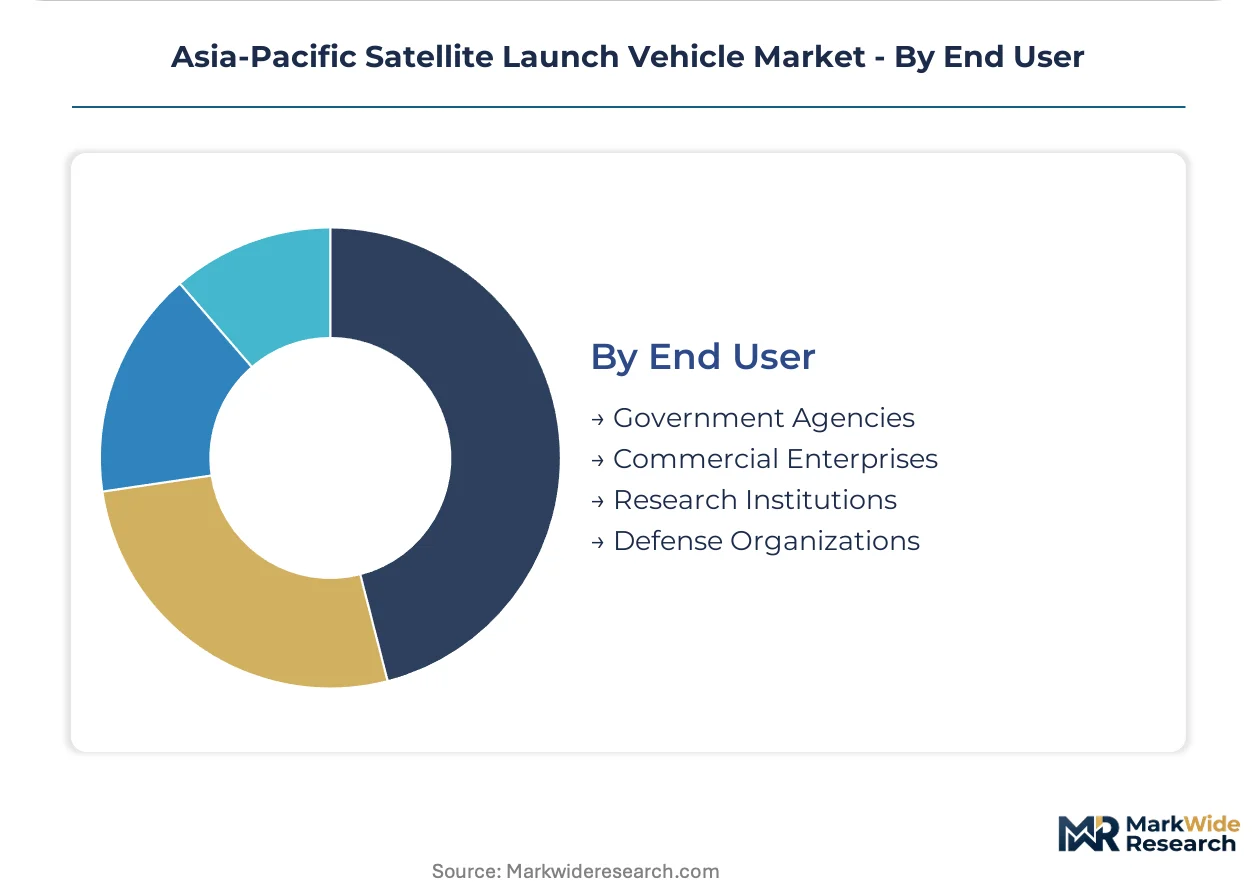
- Government Agencies:National space programs and meteorological services with sovereign payload requirements. India's ISRO and Japan's JAXA anchor demand through institutional budgets, though METI's clean-space initiative is tightening procurement criteria for domestic providers.
- Commercial Enterprises:Satellite operators and constellation developers pursuing predictable unit economics. Australian synthetic aperture radar ventures and Indian broadband providers negotiate performance-guaranteed block buys spanning 12-24 month deployment windows.
- Research Institutions:University consortia and technology demonstrators.
- Defense Organizations:Military communications and signals intelligence payloads.
Government Agencies anchor manifest priority; Commercial Enterprises are expanding their share of annual launches most steeply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in China's Tianjin manufacturing complex and Japan's Nagoya facilities, while consumption spreads across constellation operators in Australia, India, and Singapore seeking dedicated small-launcher access. This divergence shapes procurement patterns and range reservation strategies.
China
Heavy-lift demand from lunar trajectory missions and geostationary communications satellites drives CASC's Long March production at the Tianjin complex. SAMR and MIIT enforce GB standards for propellant handling and environmental compliance at coastal launch sites, adding certification overhead for foreign payload integrators. The Jiuquan and Wenchang launch centers anchor state-backed manifest priority for domestic operators.
Japan
METI's clean-space initiative mandates methane-oxygen propulsion trials and reusable stage recovery roadmaps for government contract eligibility. The Space Activities Act tightens debris mitigation enforcement through JAXA licensing, extending pre-mission review cycles for sun-synchronous launches. Mitsubishi Heavy Industries operates the H3 system from Tanegashima Space Center, serving domestic and rideshare customers.
India
ISRO's Polar Satellite Launch Vehicle program competes on cost discipline for Earth observation constellations, while the upcoming Small Satellite Launch Vehicle targets dedicated rideshare missions. CEA-ISRO coordination under the Indian Space Policy framework streamlines launch range safety approvals and spectrum allocation. Satish Dhawan Space Centre in Andhra Pradesh hosts commercial Earth observation deployments for regional operators.
South Korea
KARI commercialization directives are opening Naro Space Center infrastructure for private launch licensing and regional IoT relay networks. The national space agency's technology transfer programs support domestic propulsion development. Government and commercial customers in Seoul and Daejeon are procuring quarterly launch cadence for navigation satellite replenishment.
Australia
Synthetic aperture radar operators in Sydney and Perth are procuring dedicated small-launcher slots for maritime surveillance and disaster monitoring payloads. The emerging Space Agency licensing regime is reshaping competitive access for domestic and foreign launch providers. Arnhem Space Centre in the Northern Territory is positioning for suborbital and small orbital missions.
Asia-Pacific Satellite Launch Vehicle Market Competitive Landscape
The competitive structure tilts toward state-backed heavy-lift incumbents with captive manufacturing infrastructure and emerging private small-launcher specialists. Two strategic archetypes dominate: sovereign program anchors with institutional funding stability, and agile commercial entrants targeting dedicated rideshare economics. Consolidation pressure is accelerating through propulsion modernization roadmaps and reusable stage recovery programs. Competitive moves center on multi-launch block buy contracting and debris mitigation certification pre-positioning.
Among state-backed anchors, China Aerospace Science and Technology Corporation and Indian Space Research Organisation exemplify sovereign program incumbents with integrated production and range control. Mitsubishi Heavy Industries occupies a position within the heavy-lift tier, representing Japanese industrial capacity through the H3 launch system. These entities anchor regional manifest priority through institutional customer relationships and manufacturing scale.
| Leading Market Players |
|---|
| Mitsubishi Heavy Industries |
| Rocket Lab USA |
| China Aerospace Science and Technology Corporation (CASC) |
| The Boeing Company |
| Space Exploration Technologies Corp |
| China Great Wall Industry Corporation (CGWIC) |
| Japan Aerospace Exploration Agency (JAXA) |
| Ariane Group |
| Indian Space Research Organisation (ISRO) |
| Others |
Pricing and Supply Chain Analysis
Staged-combustion methane engine adoption across Asia-Pacific launch providers simultaneously compresses manufacturing cost curves and concentrates precision turbopump production at legacy state enterprises in China and Japan. This technology transition rewards providers with captive propulsion development while squeezing margin pools for integrators dependent on external sourcing.
Pricing Analysis
Margin tightening in heavy-lift geostationary missions reflects fixed-price contract displacement of cost-plus arrangements as Indian and Australian constellation operators negotiate performance-guaranteed block buys. Three-tier pricing structure across premium, standard, and economy levels separates dedicated small-launcher slots from rideshare piggyback arrangements and suborbital testbed services. Cost-down pressure on small satellite launchers accelerates because Australian synthetic aperture radar operators prioritize dedicated access over schedule flexibility. Commercial Earth observation developers in India and Singapore exhibit highest price sensitivity, while defense organizations in Japan sustain premium tolerance for monthly cadence guarantees.
Supply Chain Analysis
Precision machining and cryogenic sealing expertise for staged-combustion turbopumps concentrates in China's Tianjin manufacturing complex and Japan's Nagoya facilities, constraining workforce mobility across the region. High-purity liquid oxygen and kerosene sourcing draws from coastal clusters at Tianjin and Tanegashima, exposing launch schedules to regional logistics bottlenecks. Single-source vulnerability in turbopump manufacturing skills creates manifest allocation bottlenecks for commercial customers. Distribution runs through state-backed procurement channels for heavy-lift missions and emerging private launch service brokers for dedicated small-satellite access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific satellite launch vehicle competition has become a vertical-integration race where propulsion manufacturing control and reusable stage recovery capabilities determine contract eligibility under Japan's METI clean-space initiative and China's dual carbon procurement preferences.
For Market Incumbents: Anchor manifest priority through accelerated methane-oxygen propulsion trials and demonstrated reusable stage recovery roadmaps to satisfy METI government contract eligibility. Deepen captive turbopump manufacturing capacity at Tianjin and Nagoya facilities to defend against agile small-launcher entrants procuring slots for Australian synthetic aperture radar constellations. Lock in multi-launch block buy contracts with performance guarantees and on-orbit insurance bundling before fixed-price contracting fully displaces cost-plus arrangements. For New Entrants and Emerging Players: The price-point gap between premium dedicated small-launcher slots and economy rideshare piggyback arrangements opens white-space targeting for rapid-turnaround synthetic aperture radar operators in Sydney and Perth. South Korea's KARI commercialization directives at Naro Space Center offer the most penetrable geography for private launch licensing and regional IoT relay network access. Pursue debris mitigation certification pre-positioning ahead of JAXA's extended review cycles to accelerate time-to-first-contract. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition of staged-combustion engine specialists with demonstrated full-flow bench testing and reusable stage recovery prototypes. Long-term viability over the coming decade hinges on propulsion modernization roadmaps aligned with METI clean-space criteria and China's MEE carbon intensity incentives. Watch for inflection in quarterly launch cadence contracting volumes as the signal that fixed-price performance-guaranteed arrangements have achieved market dominance over legacy cost-plus structures.| Strategic Initiative | Industry Significance |
|---|---|
| Reusable Stage Recovery Program | METI clean-space initiative mandates demonstration roadmaps for government manifest priority eligibility. |
| Methane-Oxygen Propulsion Trials | Dual carbon goals alignment creates procurement preference through MEE carbon intensity reduction verification. |
| Multi-Launch Block Buy Contracting | Fixed-price performance guarantees displace cost-plus arrangements for Indian broadband constellation operators. |
| Debris Mitigation Certification Pre-Positioning | JAXA licensing requirements extend pre-mission review cycles by 8-14 months for sun-synchronous launches. |
| Turbopump Manufacturing Capacity Expansion | Precision machining skills concentration at Tianjin and Nagoya constrains workforce mobility and manifest allocation. |
Research Methodology
Document review covered launch manifest databases, regulatory filings with Japan's METI and China's SAMR, and propulsion development disclosures, complemented by interviews with launch vehicle program directors, satellite constellation procurement leads, range safety officers at Tanegashima and Satish Dhawan, and debris mitigation compliance specialists. Secondary validation drew from ISRO annual reports, CASC production disclosures, JAXA licensing bulletins, and KARI commercialization directives. Bottom-up segmentation modeling and top-down market sizing triangulated demand across vehicle type, payload capacity, and end-user categories.
Cross-referencing historical launch cadence patterns against panel input from commercial satellite operators and defense procurement officers shaped the analytical framework across the projection horizon. Segmentation dimensions modeled included vehicle classification, payload mass thresholds, launch frequency tiers, and customer type. CAGRs were derived from trajectory analysis of constellation deployment schedules and national program budget allocations. Industry-specific forecast inputs incorporated METI clean-space initiative compliance timelines and ITU geostationary slot filing backlogs.
Inputs from JAXA licensing records and CEA-ISRO coordination mechanisms were available through the study window; gaps in private small-launcher production cost disclosures introduce uncertainty bands around dedicated rideshare pricing trajectories. Forecasts reflect assumptions regarding propellant supply chain stability at Tianjin and Tanegashima and debris mitigation certification processing rates. Material deviation in METI procurement criteria enforcement or KARI commercialization directive implementation warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Satellite Based Augmentation Systems (SBAS) Market
Satellite
Global Satellite Based Earth Observation Market
Satellite
Global Broadband Satellite Services Market
Satellite
Europe Remote Sensing Satellites Market
Satellite
Europe Military Satellite Market
Satellite
Saudi Arabia Satellite-Based Earth Observation Market
Satellite
Global Commercial Satellite Imagery Market
Satellite
Asia-Pacific Satellite Manufacturing Market
Satellite
Israel Satellite Communications Market
Satellite
China Satellite Connectivity Market
Satellite
South Korea Satellite Imagery Services Market
Satellite
Satellite Payload Market
Satellite
Russia Satellite Connectivity Market
Satellite
North America Remote Sensing Services Market
Satellite
Flat Panel Satellite Antenna Market
Satellite
South Korea Satellite Communication Market