
 Cable Connectors and Adapters Market | 2026-2036
Cable Connectors and Adapters Market Size, Share, and Industry Trends Forecast 2026-2036
Cable Connectors and Adapters Market Analysis
Automotive electrification is realigning connector demand toward high-voltage, shielded assemblies. TE Connectivity leverages its automotive cable portfolio to anchor contracts with tier-one EV suppliers across Germany and the US. Amphenol Corporation specializes in harsh-environment interconnects for electric powertrains, sustaining premium positioning as OEMs raise amperage ratings. Molex competes aggressively in miniaturized board-to-board connectors for advanced driver-assistance systems, extending its footprint in vehicle sensor architectures.
Cable connectors and adapters are electromechanical devices engineered to establish signal or power pathways between cable assemblies and equipment interfaces, typically specifying contact resistance below 10 milliohms and dielectric withstanding voltages exceeding 500 VAC depending on application class. Their primary purpose is to ensure reliable, repeatable electrical continuity across systems subject to vibration, thermal cycling, and electromagnetic interference. Optical fiber connectors command outsized margins in telecommunications backbones where single-mode ferrule alignment tolerances reach sub-micron precision. USB-C form factors dominate consumer electronics procurement volumes, though custom configurations generate superior unit economics in medical and aerospace niches. Passive technology segments retain volume leadership while active cable assemblies with embedded signal conditioning chips capture fastest growth in data center interconnects exceeding 25 Gbps.
FCC equipment authorization rules govern electromagnetic compatibility for connectors deployed in US telecommunications infrastructure, while REACH and RoHS restrictions from ECHA constrain cadmium and lead content in European-sold contact platings. China's GB standards through SAMR mandate flame-retardant ratings for internal wiring connectors in consumer products, creating divergent certification burdens for multinational suppliers. Stakeholders must monitor evolving USB-IF and HDMI Forum specification releases that obsolete prior connector generations and force inventory repositioning across distribution channels.
Market Dynamics
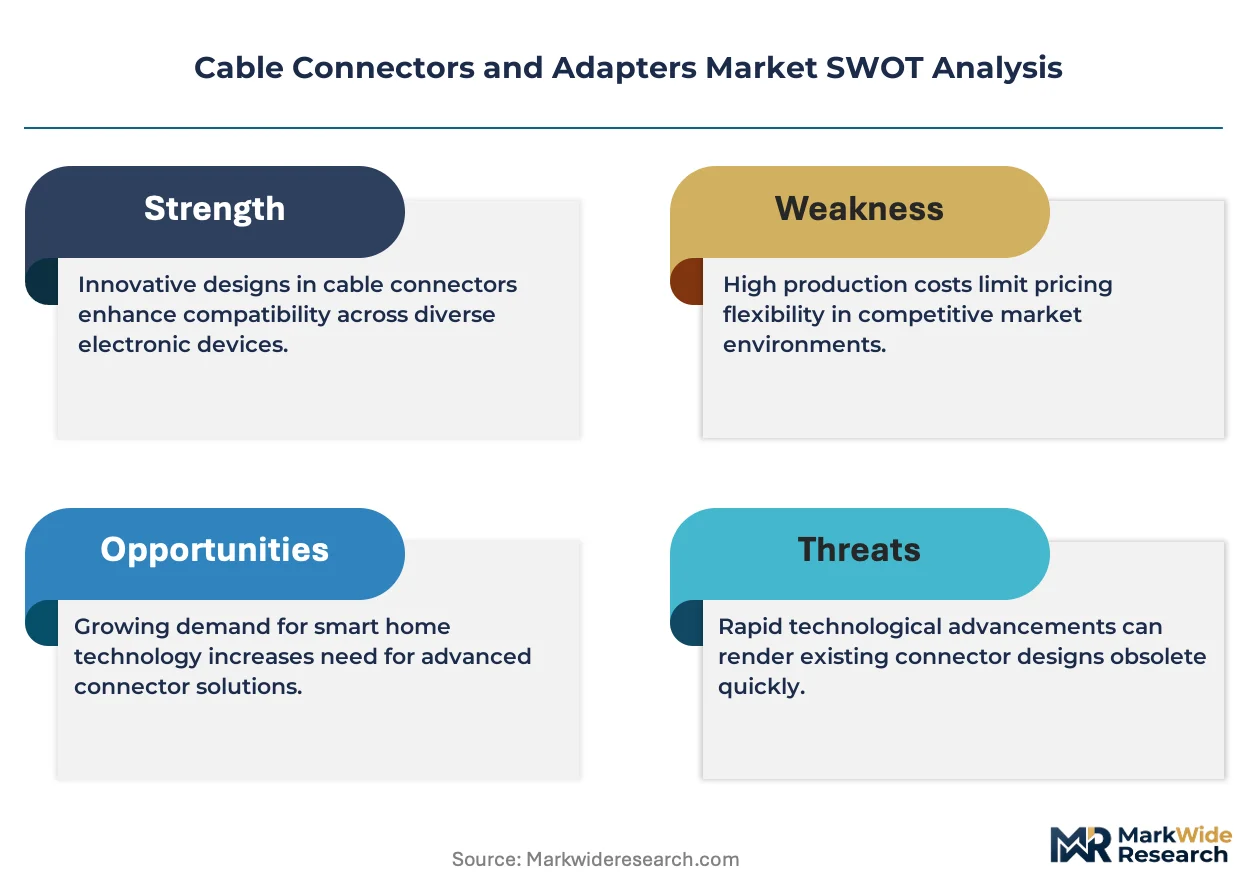
Hyperscaler data center buildouts are compressing procurement cycles for high-density interconnects while EU F-Gas Regulation and REACH compliance force simultaneous material transitions across European supply chains.
Growth Catalysts
- Data center densification:Hyperscalers in Northern Virginia and Frankfurt are procuring 400G/800G active optical cable assemblies to minimize rack space and power draw per bit transmitted.
- REACH material mandates:ECHA restrictions on cadmium and lead in contact platings are accelerating nickel-palladium-gold substitution across automotive and industrial connector portfolios.
- EV powertrain voltage escalation:800V architectures in premium electric vehicles are demanding shielded high-voltage interconnects rated above 500A continuous current.
Market Restraints
- Copper price volatility:LME copper futures above $9,000 per metric ton are compressing margins on high-conductor-count cable assemblies used in industrial automation.
- Guangdong supply concentration:Foxconn and TE Connectivity facilities in Shenzhen and Dongguan account for disproportionate share of global fiber connector output, creating geographic risk exposure.
- Single-mode alignment precision:Sub-micron ferrule tolerances in telecommunications backbones require capital-intensive polishing and interferometric inspection equipment.
Strategic Opportunities
- India data center buildout:Mumbai and Chennai hyperscaler campuses are creating demand for pre-terminated fiber trunk cables and modular patch panel systems.
- USB-IF specification velocity:Biennial updates to USB Power Delivery and DisplayPort Alt Mode are obsoleting legacy inventories and opening upgrade cycles in enterprise docking stations.
- Medical imaging miniaturization:Custom micro-coaxial connectors for portable ultrasound and endoscopic systems command premium pricing above standard consumer-grade equivalents.
Industry Challenges
- Signal integrity engineering scarcity:Designers capable of modeling 56G PAM4 channels through connector transitions command compensation premiums that inflate R&D overhead.
- Multi-jurisdiction certification backlog:Simultaneous FCC Part 15, CE marking, and China SRRC approvals for wireless-enabled smart connectors extend time-to-revenue by 4-6 months.
- Legacy MIL-SPEC integration:Defense platform refresh programs require backward-compatible interfaces that constrain adoption of denser commercial-off-the-shelf form factors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cable Connectors and Adapters Market |
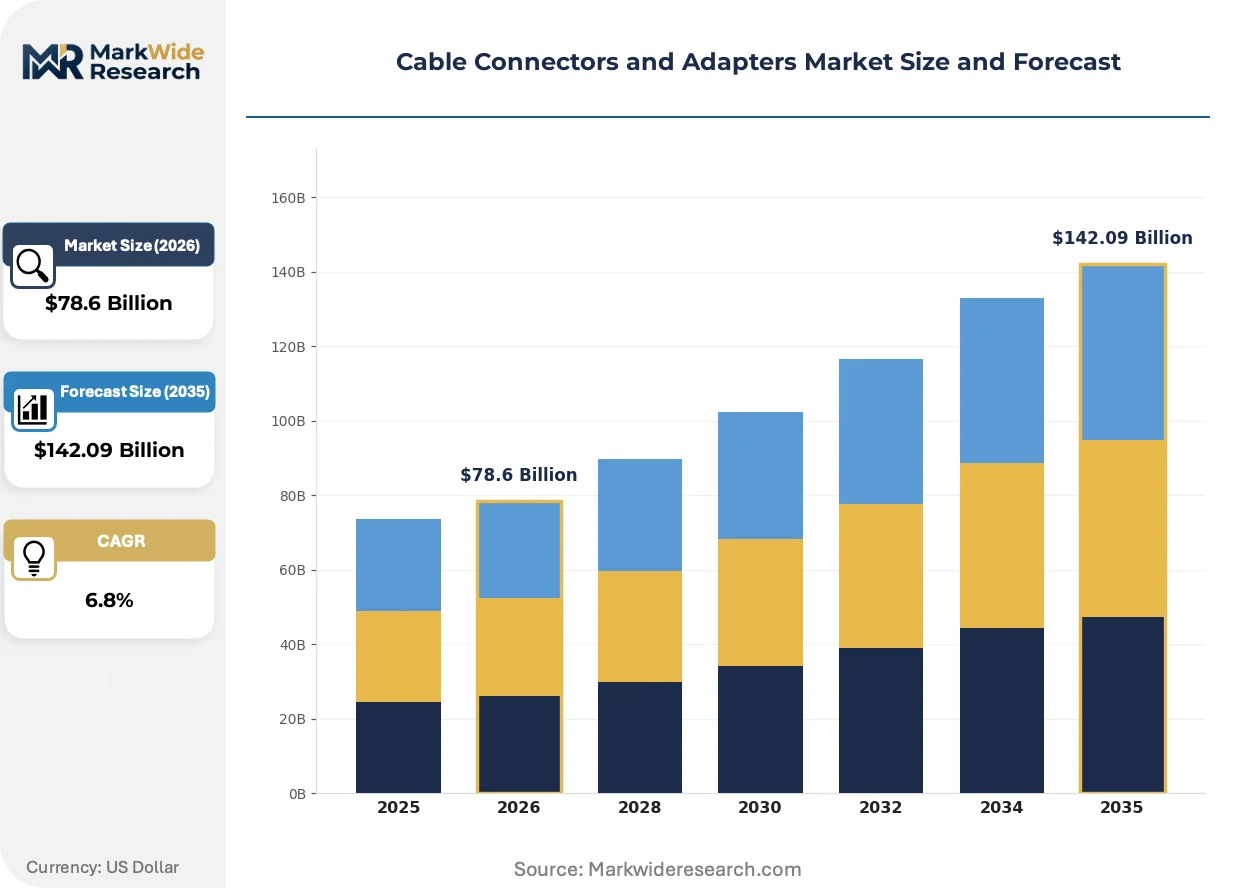
| Market Size in 2026 | $78.6 Billion |
| Market Size in 2035 | $142.09 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: USB, HDMI, Ethernet, Optical Fiber End User: Consumer Electronics, Telecommunications, Automotive, IT Services Technology: Active, Passive, Analog, Digital Form Factor: Standard, Mini, Micro, Custom |
| Companies Covered | Amphenol Corporation, TE Connectivity, Molex, Hirose Electric, Foxconn, Phoenix Contact, Harting Technology Group, Belden, Delta Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cable Connectors and Adapters Market Emerging Trajectories
Silicon photonics co-packaging and liquid cooling integration are forcing connector architectures to accommodate thermal and optical convergence within the same mechanical envelope.
Embedded optical engines within pluggable transceivers is decentralizing signal conditioning from switch ASICs to cable assemblies, enabling hyperscalers in Ashburn and Singapore to extend reach without active retimers in the data path. This topology reduces switch port complexity while elevating connector cleanliness specifications to Class 1000 cleanroom standards during field installation.
EU F-Gas Regulation phase-down schedules are banning sulfur hexafluoride in medium-voltage switchgear, compelling manufacturers in Germany and Poland to redesign high-voltage cable terminations for alternative insulation gases. The transition is accelerating qualification of dry-type terminations and vacuum interrupter interfaces that eliminate gas-dependent sealing systems entirely.
Consolidation of purchasing authority among cloud infrastructure procurement teams is compressing supplier qualification cycles and unbundling after-sales technical support from hardware pricing. Tier-one distributors in the Netherlands and Texas are responding with value-added assembly services that pre-configure cable harnesses to customer pinout specifications, capturing margin that previously accrued to original equipment manufacturers.
Cable Connectors and Adapters Market Segmentation
Connector procurement patterns diverge sharply across voltage ratings, signal integrity requirements, and environmental sealing specifications. Understanding these fault lines enables suppliers to align R&D pipelines with where purchasing authority is concentrating.
Product Type:
Buyers in this category separate by bandwidth headroom needs versus legacy compatibility obligations.
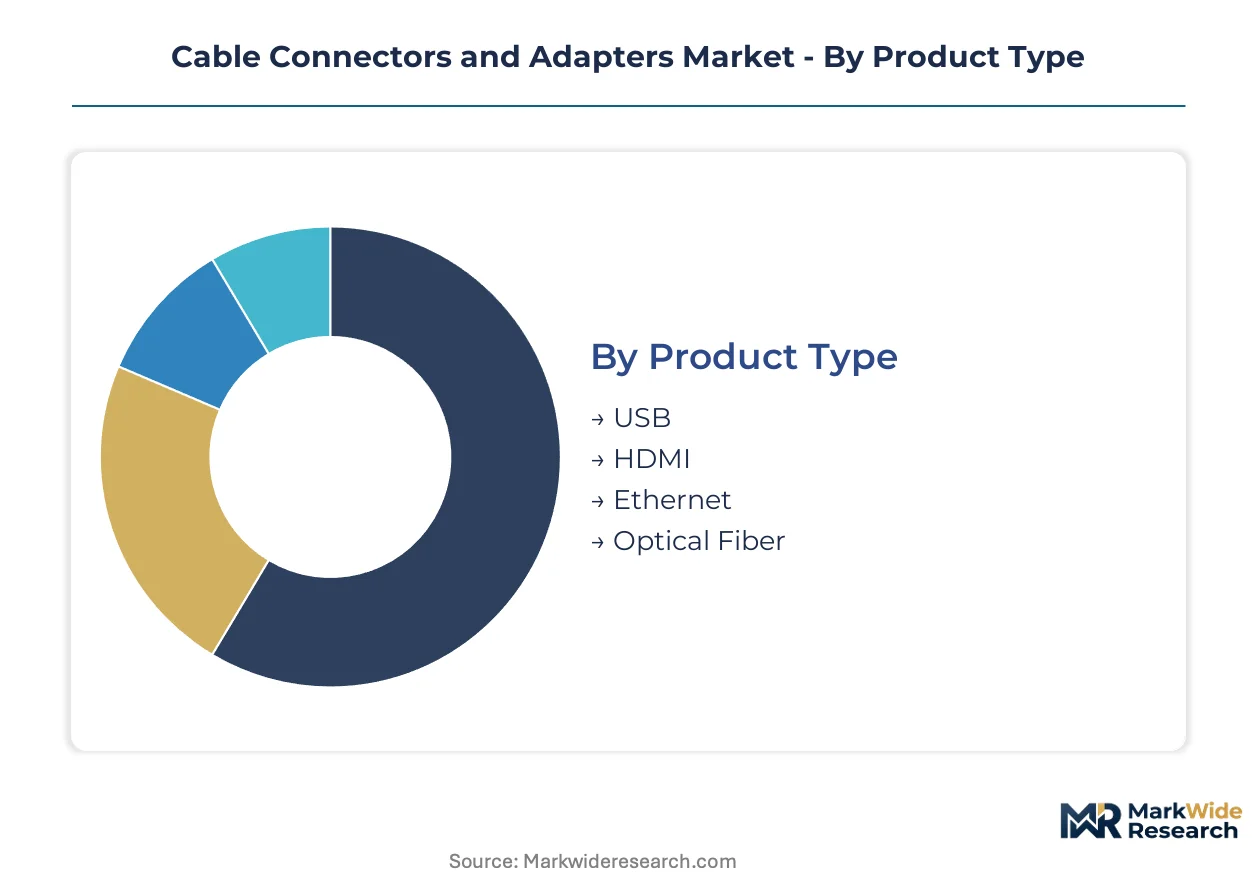
- USB:USB-C form factors with Power Delivery 3.1 support 240W charging and 40Gbps data throughput through differential signaling pairs. Procurement from Shenzhen and Dongguan contract manufacturers dominates consumer electronics and enterprise docking stations as USB-IF specification velocity accelerates upgrade cycles.
- HDMI:High-Definition Multimedia Interface connectors carry uncompressed 4K/8K video with HDCP 2.3 content protection across 19-pin configurations. Demand concentrates in home entertainment systems and commercial digital signage installations where DisplayPort Alt Mode competition is forcing connector consolidation decisions.
- Ethernet:RJ45 and industrial M12 variants handle 10Mbps to 10Gbps copper signaling with PoE++ power injection capabilities.
- Optical Fiber:Single-mode ferrule assemblies achieve sub-micron alignment precision for telecommunications backbones and hyperscale data center interconnects.
USB leads volumes today; optical fiber is gaining share fastest.
End User:
Application environments dictate insertion force tolerances, vibration resistance, and electromagnetic shielding investments.
- Consumer Electronics:Miniaturized board-to-board and cable-to-board connectors for smartphones, laptops, and wearables prioritize space efficiency over field serviceability. TE Connectivity and Foxconn manufacturing facilities in Guangdong province anchor global supply for this segment.
- Automotive:High-voltage shielded interconnects rated above 500A continuous current serve 800V EV powertrain architectures with IP67 sealing and vibration resistance per LV 214 specifications. Amphenol Corporation and TE Connectivity compete for tier-one supplier contracts across Germany and the US.
- Telecommunications:Dense fiber patch panel systems and active optical cable assemblies serve central office and 5G fronthaul deployments.
- IT Services:Pre-terminated copper trunk cables and modular patch panel systems support enterprise LAN refresh cycles and Mumbai hyperscaler campus buildouts.
Consumer electronics commands the largest procurement volumes; automotive exhibits the steepest expansion trajectory.
Technology:
Signal conditioning location—embedded versus external—determines cost structure and interoperability requirements.
- Passive:Unpowered connectors rely on conductor geometry and dielectric materials for signal integrity without active compensation. Volume leadership persists in legacy industrial automation and building infrastructure where cost sensitivity outweighs bandwidth demands.
- Active:Embedded signal conditioning chips within cable assemblies enable 25Gbps+ data center interconnects without switch-side retimers. Hyperscalers in Northern Virginia and Frankfurt are compressing procurement cycles for these assemblies.
- Analog:Continuous signal connectors for audio, video, and sensor applications with minimal digital processing overhead.
- Digital:Protocol-aware connectors with embedded logic for error correction and link training in high-speed serial interfaces.
Passive technology retains volume leadership; active assemblies are expanding most quickly.
Form Factor:
Mechanical envelope constraints and mating cycle durability separate specification tiers.
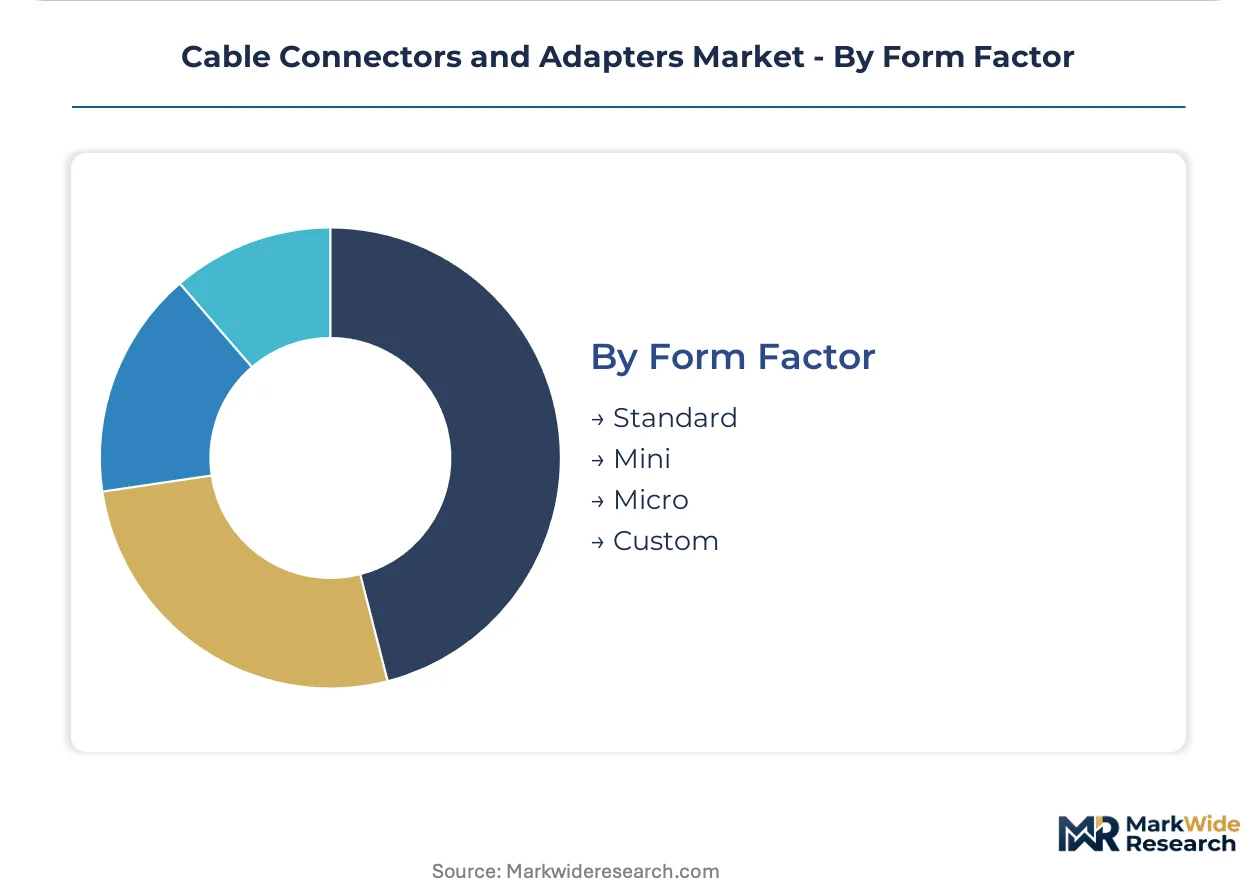
- Standard:Full-size connectors with robust latching mechanisms and field-replaceable contacts serve industrial machinery and telecommunications infrastructure. Procurement emphasizes longevity over density.
- Mini:Reduced-footprint variants for space-constrained equipment including tablets, portable medical devices, and compact industrial controllers.
- Micro:Sub-miniature connectors for wearables, hearing aids, and endoscopic systems where custom micro-coaxial configurations command premium pricing.
- Custom:Application-specific geometries for aerospace, defense, and medical imaging with MIL-SPEC or proprietary mating interfaces.
Standard form factors dominate installed base; custom configurations capture superior unit economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting connector manufacturing toward jurisdictions with streamlined environmental compliance, as EU REACH and F-Gas restrictions elevate European production costs relative to Asian alternatives.
United States
Hyperscaler data center buildouts in Northern Virginia and Dallas-Fort Worth are compressing procurement cycles for 400G/800G active optical cable assemblies. FCC equipment authorization rules govern electromagnetic compatibility for telecommunications infrastructure deployments. TE Connectivity operates major manufacturing facilities serving both domestic and export markets from its US base.
Germany
Automotive electrification is realigning connector demand toward high-voltage shielded assemblies for 800V EV powertrain architectures. EU F-Gas Regulation and REACH compliance through ECHA are reshaping material selection for jacketing and contact plating across European supply chains. Industrial clusters in Baden-Württemberg and Bavaria anchor premium automotive connector development for tier-one EV suppliers.
China
Guangdong province concentrates disproportionate global fiber connector output through Foxconn and TE Connectivity facilities in Shenzhen and Dongguan. GB standards through SAMR mandate flame-retardant ratings for internal wiring connectors in consumer products. The Pearl River Delta manufacturing corridor serves both domestic procurement and export markets with high-volume USB-C and board-to-board connector production.
India
Mumbai and Chennai hyperscaler campuses are creating demand for pre-terminated fiber trunk cables and modular patch panel systems. BIS certification requirements and PLI scheme incentives are encouraging domestic assembly capacity for telecommunications infrastructure. Karnataka and Telangana emerging as secondary clusters for IT services and data center interconnect procurement.
Japan
Miniaturized board-to-board connectors for advanced driver-assistance systems are extending supplier footprints in vehicle sensor architectures. METI industrial policy and JIS standards govern quality benchmarks for automotive and industrial interconnect applications. Kanto region manufacturers specialize in precision ferrule alignment equipment for sub-micron telecommunications backbone deployments.
Cable Connectors and Adapters Market Vendor Landscape
Portfolio diversification dominates the current landscape as incumbent suppliers reposition around data center and automotive electrification vectors. The vendor base separates into three tiers: diversified electromechanical conglomerates with cross-industry connector portfolios, specialized harsh-environment interconnect fabricators, and high-volume contract manufacturers serving consumer electronics procurement. Strategic archetypes include vertically integrated component suppliers controlling materials through finished assemblies, technology licensors monetizing connector interface standards, and regional champions capturing domestic infrastructure buildouts. M&A activity and capacity expansion in India and Southeast Asia represent the dominant competitive moves as suppliers seek geographic risk mitigation.
Among diversified electromechanical suppliers, Amphenol Corporation and TE Connectivity occupy positions exemplifying the premium-tier archetype, while Molex represents the miniaturization-specialist vector. These three anchors demonstrate how scale and specialization separate competitive positioning: Amphenol Corporation and TE Connectivity through breadth across automotive, aerospace, and industrial verticals, Molex through density in consumer electronics and vehicle sensor architectures. Foxconn, by contrast, sits within the contract-manufacturing tier where volume throughput and Guangdong province supply chain integration define competitive economics. The resulting structure rewards either scope-driven diversification or focused execution in high-mix, low-volume custom configurations.
| Leading Market Players |
|---|
| Amphenol Corporation |
| TE Connectivity |
| Molex |
| Hirose Electric |
| Foxconn |
| Phoenix Contact |
| Harting Technology Group |
| Belden |
| Delta Electronics |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up specialty connector distributors in North America and Europe are compressing channel margins while consolidating purchasing authority, tightening pricing discipline across copper-intensive cable assemblies and optical fiber interconnects alike.
Pricing Analysis
Distributor margin layers in the 15-25% range dominate pricing architecture for standard interconnects, while direct-to-OEM contracts on high-voltage automotive assemblies command steeper volume discounts. Three-tier pricing structure across MIL-SPEC certified, industrial-grade, and consumer-grade tiers separates Amphenol Corporation and TE Connectivity premium positioning from Shenzhen contract manufacturer spot pricing. Cost compression in copper conductor assemblies is intensifying because LME futures volatility above historical baselines erodes fixed-price contract profitability. Automotive tier-one suppliers exhibit lowest price sensitivity due to qualification lock-in, while consumer electronics procurement teams at Foxconn anchor volume drive the hardest bargain.
Supply Chain Analysis
High-purity copper cathode supply rests on Chilean mining output and Chinese smelter capacity, with palladium for contact plating drawing from Russian and South African precious metals streams. Guangdong province in China, Baden-Württemberg in Germany, and Texas in the United States anchor finished connector manufacturing, though sub-micron ferrule polishing equipment concentrates in Japan's Kanto region. Single-source vulnerability in rare earth magnet supply for shielded automotive interconnects creates tariff exposure risk given concentrated Chinese processing dominance. Distribution runs through Arrow Electronics and Avnet in North America, Rutronik in Europe, and WPG Holdings in Asia-Pacific for volume fulfillment, with value-added assembly services capturing margin migration from OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where EU F-Gas Regulation phase-down schedules and REACH material mandates are forcing simultaneous redesign cycles across European automotive and industrial connector portfolios, accelerating demand for compliant nickel-palladium-gold plating substitutions.
For Market Incumbents: Deepen backward integration into high-purity copper refining and captive palladium plating capacity to defend margin position against LME volatility and ECHA supply chain audits. Lock in multi-year qualification cycles with Munich and Detroit OEMs before 800V EV architectures standardize, while expanding Class 1000 cleanroom assembly capacity in India to offset Guangdong geographic risk. For New Entrants and Emerging Players: Capture modular patch panel system demand in Mumbai and Chennai hyperscaler campuses where BIS certification requirements create qualification moats against unlicensed Chinese imports. Target medical imaging miniaturization niches for portable ultrasound micro-coaxial connectors, leveraging FDA 510(k) pathway complexity as barrier to commodity competition. For Investors and Strategic Acquirers: Diversified electromechanical conglomerates with automotive-aerospace cross-selling capability are the most active acquirer in this space, consolidating harsh-environment specialists to fill portfolio gaps. Five-to-ten year viability hinges on silicon photonics co-packaging readiness and liquid cooling interface patent estates. Watch USB-IF specification release velocity as inflection indicator for inventory obsolescence risk and upgrade cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copper Refining | Captures margin from LME volatility while securing ECHA-compliant supply for European automotive contracts. |
| India Manufacturing Footprint Expansion | Mitigates Guangdong concentration risk while capturing PLI scheme incentives for telecommunications infrastructure. |
| Silicon Photonics Co-Packaging Investment | Positions for thermal-optical convergence in 800G data center interconnects at Ashburn and Frankfurt campuses. |
| REACH-Compliant Plating Qualification | Locks in nickel-palladium-gold substitution ahead of cadmium ban enforcement across German automotive supply chains. |
| Value-Added Assembly Service Launch | Captures margin migration from OEMs through pre-configured harnesses with customer-specific pinout specifications. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with connector procurement managers at hyperscaler facilities, Tier 1 automotive supplier platform engineers, and distribution channel partners at Arrow Electronics and Rutronik with secondary validation through SEC 10-K filings, ECHA REACH substance restriction updates, and USB-IF specification release archives. Bottom-up demand modeling across voltage ratings, signal integrity tiers, and environmental sealing specifications triangulated against top-down macroeconomic indicators.
Comparable-period anchoring linked the projection horizon to historical procurement cycle data across data center buildout waves and automotive platform refresh timelines. Segmentation dimensions modeled included product type, end-user vertical, passive versus active technology, and form factor envelope constraints. CAGRs were derived from installed base replacement velocity and new architecture adoption curves, with hyperscaler capex disclosures and EV production ramp schedules serving as primary demand inputs.
Copper price volatility, regulatory enforcement timing on F-Gas phase-down schedules, and USB-IF specification obsolescence velocity are the dominant revision risks that could compress or extend forecast intervals. Forecasts reflect documented assumptions on qualification cycle duration and geographic supply chain stability. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Connectors
Middle East and Africa Hazardous Location Connectors Market
Connectors
Japan Connector Market
Connectors
Mexico Connector Market
Connectors
India Connector Market
Connectors
PCI-E Connectors Market
Connectors
Global Wired Interface Market
Connectors
Connector Market
Connectors
Australia Connector Market
Connectors
Connector for PV System Market
Connectors
Relay Sockets Market
Connectors
Latin America Connector Market
Connectors
Press Fit Connector Market
Connectors
Circular Waterproof Connector Market
Connectors
Circular Connectors Market
Connectors
Automotive Data Connectors Market
Connectors
3C Electronics Precision Connectors Market