
 LCP Connectors Market | 2026-2036
LCP Connectors Market Size, Share, and Industry Trends Forecast 2026-2036
LCP Connectors Market Outlook
China's Guangdong province is narrowing the gap with established LCP connector manufacturing bases through dedicated polymer compounding facilities and precision molding investments. TE Connectivity Ltd. leverages its vertical polymer-to-connector pipeline to sustain cost advantages in high-volume automotive programs. Amphenol Corporation anchors North American supply security through captive resin qualification labs and domestic molding capacity. Sumitomo Chemical Company dominates upstream Vectra-type LCP resin supply, controlling material access for competitors across Asia.
Liquid crystal polymer connectors are injection-molded thermoplastic interconnects characterized by dimensional stability below 0.05% moisture absorption and dielectric constants near 2.9 at gigahertz frequencies, serving applications where miniaturization and signal integrity converge under thermal stress. High-speed connectors lead product type margins as data center and 5G infrastructure deployments require controlled impedance across dense pin arrays. Custom connectors represent the fastest-growing application category, with aerospace and defense buyers specifying hybrid material constructions that blend LCP housings with metal contact systems for electromagnetic shielding.
REACH compliance in Europe and RoHS substance restrictions constrain halogenated flame retardant formulations, compelling compounders like RTP Company to certify phosphorus-based alternatives for connector grades. Japan's METI enacts domestic content incentives through revised industrial standards that favor JIS-qualified LCP connector sources for critical telecommunications infrastructure. Stakeholders must monitor evolving F-Gas Regulation thresholds in Europe, as connector sealing applications face scrutiny over perfluorinated material content that could disrupt established supply qualifications.
Market Dynamics
Automotive electrification programs in Germany and Japan are compressing qualification cycles for high-speed LCP connectors, forcing resin compounders and molders to synchronize capacity expansions with battery platform launches rather than traditional consumer electronics cadences.
Growth Catalysts
- Automotive electrification mandates:Battery management systems in Germany and Japan require LCP connectors rated for 150°C continuous operation and 10Gbps signal integrity, pulling material qualification timelines forward by 18-24 months versus historical norms.
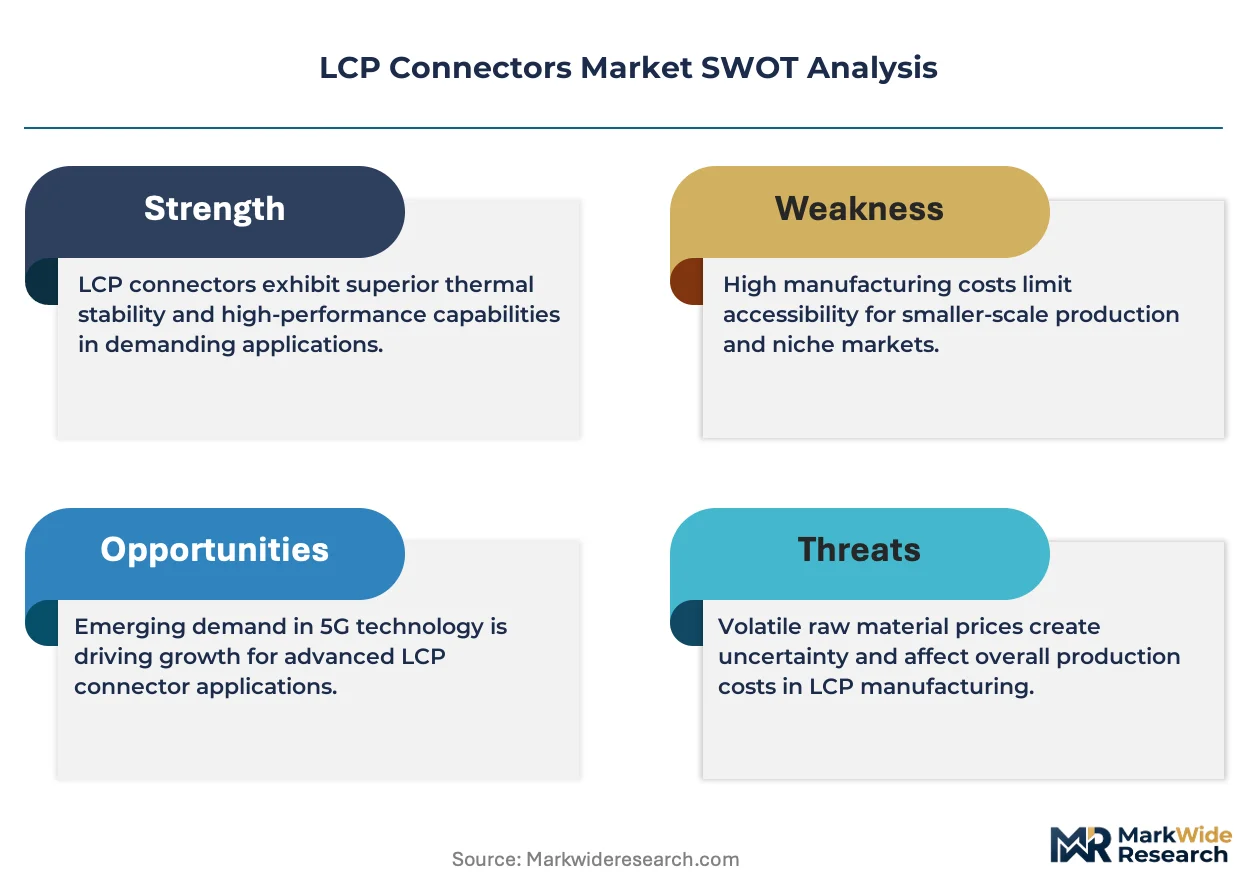
- REACH and RoHS substance restrictions:ECHA's tightening thresholds on halogenated flame retardants compel compounders to certify phosphorus-based LCP grades, creating first-mover advantages for suppliers with pre-qualified alternative formulations.
- Semiconductor packaging densification:South Korea's substrate-to-board interconnect cluster demands sub-0.4mm pitch LCP connectors with sub-0.05% moisture absorption, concentrating procurement among molders with micro-molding capability.
Market Restraints
- Vectra-type resin supply concentration:Sumitomo Chemical Company's dominance over upstream LCP resin production in Asia creates material access bottlenecks for competing connector manufacturers during demand surges.
- F-Gas Regulation compliance costs:EU thresholds on perfluorinated materials in connector sealing applications force reformulation of established grades, disrupting multi-year supply qualifications without guaranteed technical equivalence.
- Polymer compounding capex intensity:Precision LCP compounding requires twin-screw extrusion lines with nitrogen blanketing and laser gauging, locking out mid-tier molders from automotive-grade material development.
Strategic Opportunities
- Guangdong manufacturing base maturation:China's dedicated polymer compounding facilities and precision molding investments in Guangdong province offer captive supply alternatives to established Japanese and German supply nodes.
- Hybrid material aerospace specifications:Defense and satellite buyers are specifying LCP housings with integrated metal contact systems for electromagnetic shielding, opening premium-margin custom connector categories.
- METI domestic content incentives:Japan's revised industrial standards favoring JIS-qualified LCP connector sources create protected demand pools for certified domestic suppliers in critical telecommunications infrastructure.
Industry Challenges
- Micro-molding talent scarcity:The intersection of polymer rheology, mold flow simulation, and sub-micron tolerance metrology requires skill sets concentrated among aging specialists in Japan and Germany, constraining capacity expansion.
- Dual carbon alignment complexity:China's MEE enforcement of carbon intensity benchmarks across polymer production forces simultaneous retooling of compounding and molding operations, compressing margin recovery timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LCP Connectors Market |
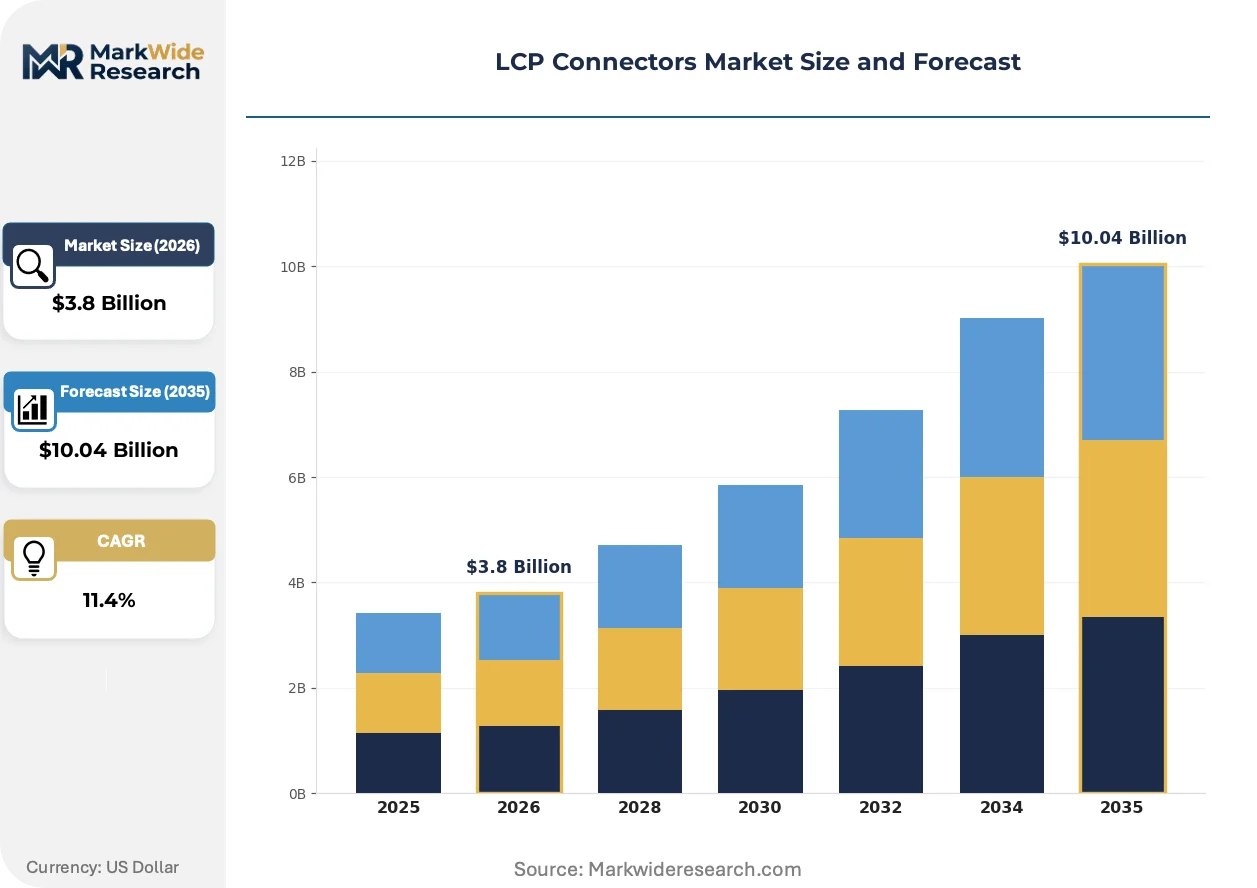
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
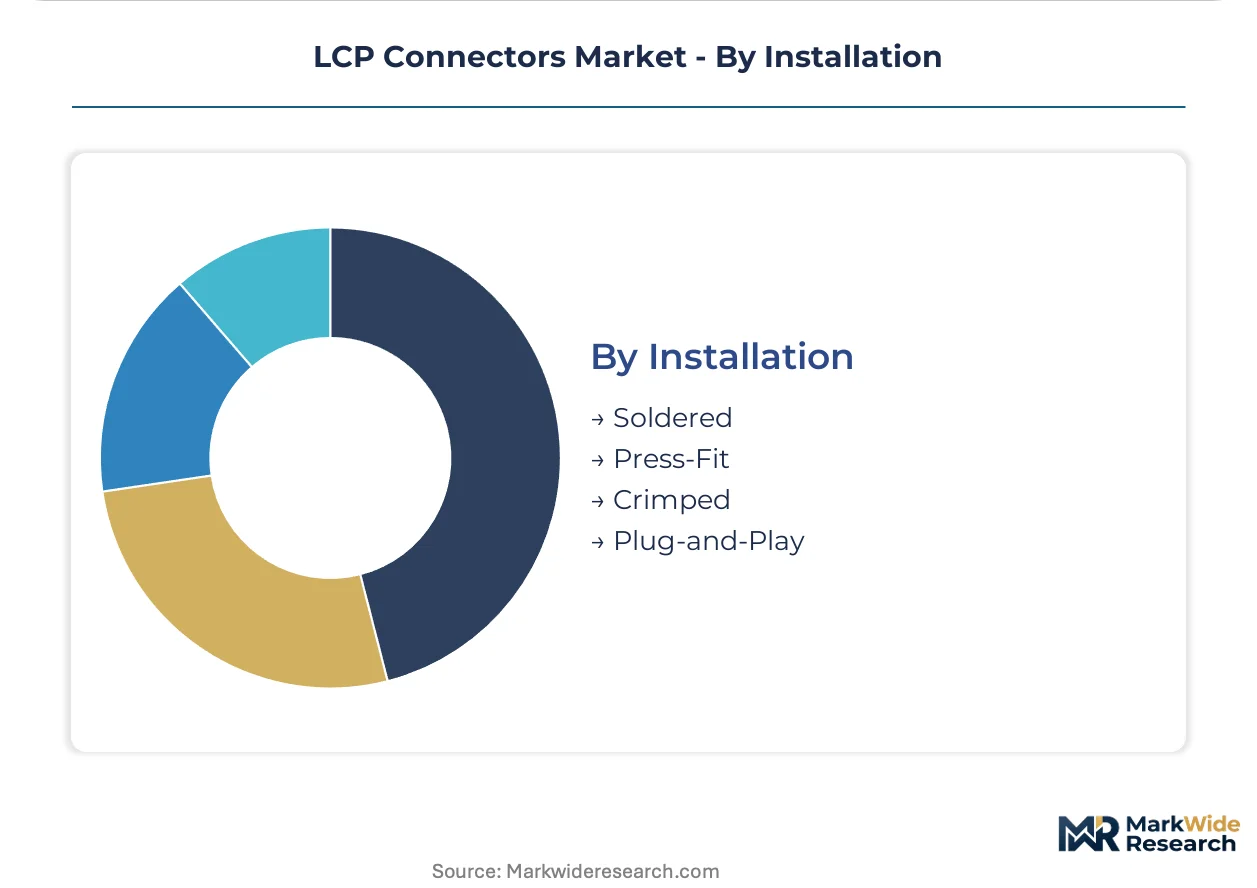
| Segmentation | Product Type: Standard Connectors, High-Speed Connectors, Power Connectors, Custom Connectors Application: Telecommunication, Aerospace, Automotive, Consumer Electronics Material: Plastic, Metal, Composite, Hybrid Installation: Soldered, Press-Fit, Crimped, Plug-and-Play |
| Companies Covered | Amphenol Corporation, Sumitomo Chemical Company, TE Connectivity Ltd., HARTING Technology Group, 3M Company, Hirose Electric Co., Ltd., Japan Aviation Electronics Industry, Ltd., Würth Elektronik GmbH & Co. KG, RTP Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LCP Connectors Market Strategic Shifts
Signal integrity requirements at millimeter-wave frequencies are collapsing traditional connector design paradigms, forcing convergence between material science and electromagnetic simulation capabilities.
Multi-layer LCP substrates with embedded passive components are collapsing the boundary between connector and substrate functions. 5G base station manufacturers in South Korea and Japan are adopting these integrated modules to reduce board stack height by 40-60%. The technology is collapsing procurement categories as buyers shift from discrete connector sourcing to substrate-connector hybrid specifications.
Europe's F-Gas Regulation is tightening thresholds on perfluorinated sealing materials used in hermetic LCP connectors. ECHA's 2024 guidance documents require reformulation of gas-tight grades for aerospace and medical applications, compressing supplier qualification windows. Connector manufacturers with captive resin development labs are responding faster than those dependent on external compounders.
Data center hyperscalers are consolidating connector procurement through direct material qualification partnerships rather than distributor channels. Buyers in Virginia, Frankfurt, and Singapore now require molders to submit resin batch certificates and dimensional Cpk data with every lot, bypassing traditional component distributors. This pattern concentrates volume with vertically integrated suppliers capable of polymer-to-connector traceability.
LCP Connectors Market Segmentation
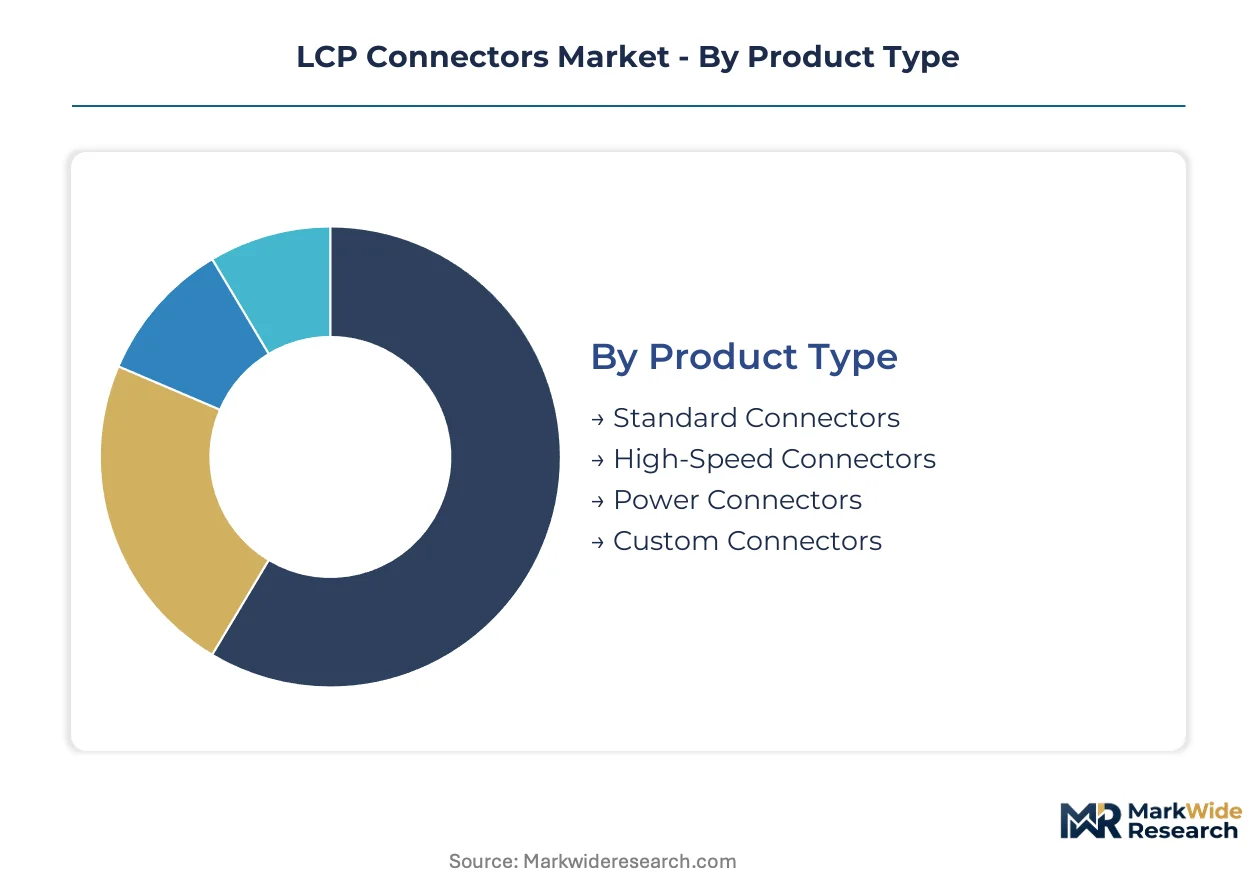
LCP connector procurement patterns diverge sharply across technical specifications and end-use environments. Material purity requirements, signal integrity thresholds, and regulatory compliance burdens reshape competitive positioning differently within each segment boundary.
Product Type:
Cost tier stratification separates commodity-grade interconnects from precision-engineered solutions commanding material science premiums.
- High-Speed Connectors:These interconnects maintain controlled impedance across dense pin arrays with dielectric constants near 2.9 at gigahertz frequencies. Data center hyperscalers in Virginia and Singapore mandate sub-0.4mm pitch specifications with full polymer-to-connector traceability, compressing supplier qualification windows.
- Custom Connectors:Hybrid constructions blend LCP housings with integrated metal contact systems for electromagnetic shielding. Defense and satellite buyers in Germany and Japan specify these for aerospace applications, opening premium-margin categories with extended development cycles.
- Standard Connectors:Injection-molded thermoplastic interconnects serve cost-sensitive consumer electronics with dimensional stability below 0.05% moisture absorption.
- Power Connectors:Continuous operation ratings at 150°C serve battery management systems in automotive electrification programs.
High-Speed Connectors command the established base. The steepest expansion runs through Custom Connectors.
Application:
End-use environment dictates material formulation, with thermal stress and signal density requirements varying dramatically across sectors.
- Automotive:Battery management systems in Germany and Japan require LCP connectors rated for 150°C continuous operation and 10Gbps signal integrity. MIIT's revised GB protocols in China push domestic OEMs toward certified suppliers, pulling material qualification timelines forward.
- Telecommunication:5G base station manufacturers in South Korea adopt multi-layer LCP substrates with embedded passive components, collapsing procurement categories toward substrate-connector hybrid specifications.
- Aerospace:Hermetic grades face ECHA's F-Gas Regulation thresholds on perfluorinated sealing materials, forcing reformulation without guaranteed technical equivalence.
- Consumer Electronics:Miniaturization imperatives converge with signal integrity requirements under thermal stress for handheld device interconnects.
Telecommunication anchors volume demand. Automotive generates the steepest specification escalation.
Material:
Supply concentration upstream determines access economics, with resin qualification capabilities separating tier-one molders from mid-tier competitors.
- Plastic:Vectra-type LCP resin from Sumitomo Chemical Company dominates upstream supply in Asia, creating material access bottlenecks during demand surges for competing connector manufacturers.
- Hybrid:LCP housings with metal contact systems serve aerospace electromagnetic shielding requirements, blending polymer dimensional stability with conductive performance.
- Metal:Contact systems integrated into LCP substrates provide signal path integrity for high-frequency applications.
- Composite:Reinforced formulations address mechanical stress in automotive underhood environments.
Plastic formulations dominate unit economics. Hybrid constructions expand most quickly on specification premiums.
Installation:
Assembly method selection correlates with field serviceability requirements and manufacturing automation levels.
- Soldered:Permanent attachment for high-reliability aerospace and medical applications requiring hermetic sealing under ECHA's tightened F-Gas thresholds.
- Press-Fit:Compliant pin interfaces serve automotive and telecommunications infrastructure with rework capability and reduced thermal processing.
- Crimped:Wire-to-board termination for power distribution in battery management systems.
- Plug-and-Play:Field-replaceable modules for data center and 5G infrastructure maintenance cycles.
Press-Fit commands automotive volume. Plug-and-Play gains share fastest in hyperscale data center procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Resin compounding capacity clusters in Japan and Germany, while precision molding investments concentrate in South Korea and China's Guangdong province. These four countries anchor LCP connector supply chains through distinct specializations in material science, automotive electrification, semiconductor packaging, and manufacturing scale.
Germany
Automotive electrification programs from BMW, Volkswagen, and Mercedes-Benz compress qualification cycles for 150°C-rated battery management connectors. KBA enforcement of EV safety protocols pulls material qualification timelines forward by 18-24 months versus consumer electronics norms. Bavaria's automotive supplier corridor around Munich hosts molders synchronizing capacity with battery platform launches.
Japan
METI domestic content incentives through revised JIS standards favor certified suppliers for critical telecommunications infrastructure. Sumitomo Chemical Company's Vectra-type resin production dominates upstream material access across Asia. The Chubu region around Nagoya concentrates aging micro-molding specialists whose skill scarcity constrains industry-wide capacity expansion.
South Korea
Semiconductor packaging densification drives demand for sub-0.4mm pitch connectors with sub-0.05% moisture absorption. MFDS-aligned reliability standards govern medical-grade interconnect specifications. The Suwon-Yongin corridor hosts substrate-to-board interconnect clusters where advanced packaging buyers dominate procurement.
China
MIIT's revised GB protocols tighten connector reliability standards, pushing domestic OEMs toward certified suppliers. Guangdong province narrows the gap with established manufacturing bases through dedicated polymer compounding facilities and precision molding investments. MEE enforcement of carbon intensity benchmarks forces simultaneous retooling of compounding and molding operations.
United States
Data center hyperscalers in Virginia consolidate procurement through direct material qualification partnerships requiring polymer-to-connector traceability. FCC electromagnetic compatibility standards shape signal integrity specifications for 5G infrastructure deployments. The Dallas-Austin corridor anchors domestic molding capacity serving aerospace and defense custom connector programs.
LCP Connectors Market Competitive Environment
Resin compounders and precision molders split the market along upstream-downstream boundaries. Three strategic archetypes dominate: chemical conglomerates with captive resin production, diversified interconnect specialists with backward polymer development capabilities, and regional precision molders serving automotive qualification programs. Competitive moves concentrate on capacity synchronization with battery platform launches and captive resin qualification labs to bypass external compounder dependencies.
Within the chemical conglomerate tier, Sumitomo Chemical Company exemplifies upstream dominance through Vectra-type resin supply control. Among diversified interconnect specialists, TE Connectivity Ltd. and Amphenol Corporation occupy positions defined by vertical polymer-to-connector pipelines. These three anchors represent distinct strategic postures: material access bottlenecks, cost advantages in high-volume programs, and supply security through captive resin qualification.
| Leading Market Players |
|---|
| Amphenol Corporation |
| Sumitomo Chemical Company |
| TE Connectivity Ltd. |
| HARTING Technology Group |
| 3M Company |
| Hirose Electric Co., Ltd. |
| Japan Aviation Electronics Industry, Ltd. |
| Würth Elektronik GmbH & Co. KG |
| RTP Company |
| Others |
Value Chain & Pricing Dynamics
The Yokohama-Long Beach transpacific corridor carries Vectra-type LCP resin shipments from Sumitomo Chemical's Nagoya facilities to North American molders, with freight cost volatility amplifying the pricing power of resin-integrated suppliers while compressing margins for compounder-dependent competitors serving automotive electrification programs.
Pricing Analysis
REACH and RoHS substance restrictions dictate the pricing tier structure across the LCP connector market, separating phosphorus-based certified grades from legacy halogenated formulations. Three-tier pricing stratifies across automotive-qualified, telecommunications-grade, and consumer electronics tiers, with JIS certification and MIIT GB protocol compliance commanding material science premiums. Cost compression in standard connector grades intensifies as Guangdong molders expand precision capacity, while hyperscale data center buyers with direct qualification partnerships exhibit lowest price sensitivity due to traceability requirements.
Supply Chain Analysis
Extended payment terms from automotive OEMs in Germany and Japan strain working capital for mid-tier molders without supply-chain finance facilities, concentrating procurement leverage with vertically integrated suppliers. Raw material sourcing draws from Sumitomo Chemical's Vectra-type resin production in Japan, RTP Company's phosphorus-based compounding in North America, and emerging Guangdong polymer facilities. Single-source vulnerability around upstream LCP resin creates material access bottlenecks during demand surges. Distribution runs through direct qualification partnerships with data center hyperscalers and Tier 1 automotive suppliers, bypassing traditional component distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
LCP connector procurement is shifting from discrete component sourcing to substrate-connector hybrid platforms, with 5G base station manufacturers in South Korea and Japan collapsing procurement categories through multi-layer LCP substrate adoption that embeds passive components and eliminates traditional board-stack boundaries.
For Market Incumbents: Harden resin qualification capabilities through captive compounding labs or exclusive RTP Company partnerships to bypass Sumitomo Chemical supply bottlenecks during automotive platform launch windows. Secure JIS certification under METI domestic content incentives to protect telecommunications infrastructure share from emerging Guangdong competitors. Prioritize micro-molding talent retention in Japan's Chubu region where aging specialist scarcity constrains industry-wide capacity expansion. For New Entrants and Emerging Players: Build out precision molding capacity in Guangdong province to exploit MIIT's GB protocol tightening, which pushes Chinese domestic OEMs toward certified alternative suppliers. Target aerospace custom connector specifications where hybrid LCP-metal constructions for electromagnetic shielding carry premium margins and extended development cycles insulate from price competition. Pursue direct qualification partnerships with Virginia-based data center hyperscalers requiring polymer-to-connector traceability that distributor-dependent incumbents cannot match. For Investors and Strategic Acquirers: Regional precision molders with automotive qualification pipelines and backward polymer development capabilities represent the most defensible acquisition targets as battery platform launches compress synchronization requirements. Long-term viability hinges on exposure to electrification mandates rather than consumer electronics cyclicality. Monitor F-Gas Regulation threshold evolution as an inflection indicator, since hermetic connector reformulation without technical equivalence guarantees will separate resin-integrated suppliers from compounder-dependent competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Resin Qualification Lab Investment | Eliminates Sumitomo Chemical supply bottlenecks during German and Japanese automotive platform surges. |
| Guangdong Precision Molding Capacity Expansion | Captures MIIT GB protocol-driven procurement shifts among domestic Chinese OEMs. |
| JIS Certification Pathway Completion | Secures protected demand pools under METI domestic content incentives for telecommunications infrastructure. |
| Multi-Layer LCP Substrate Development | Collapses procurement categories for South Korean 5G base station manufacturers seeking 40-60% board stack reduction. |
| Phosphorus-Based Flame Retardant Pre-Qualification | Creates first-mover advantage as ECHA REACH thresholds tighten on halogenated formulations. |
Study Parameters
Operator-level perspectives from polymer compounding plant managers, Tier 1 automotive supplier procurement leads, data center hyperscaler hardware engineers, and telecommunications infrastructure project developers anchored the qualitative base. Primary interview findings triangulated against secondary validation from MIIT GB standard filings, ECHA REACH guidance documents, METI JIS revision notices, and SEC 10-K disclosures from diversified interconnect specialists. Bottom-up volume modeling across high-speed, custom, standard, and power connector product types combined with top-down macroeconomic anchoring to ensure segmentation consistency.
Scenario-bracketing around automotive electrification cadence, semiconductor packaging densification rates, and regulatory compliance timeline compression shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application environment, material formulation, and installation method, with CAGRs derived from elasticity-adjusted demand curves and capacity-constrained supply responses. Industry-specific forecast inputs incorporated battery platform launch schedules from BMW, Volkswagen, and Mercedes-Benz, plus 5G base station deployment data from South Korean network operators.
Practitioners should monitor automotive platform launch delays, F-Gas Regulation threshold revisions, and Sumitomo Chemical capacity expansion announcements for early signals of forecast deviation. The analysis reflects assumptions about qualification timeline compression and resin supply concentration persistence. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Connectors
Australia Connector Market
Connectors
Micro-Miniature Co-Axial Adapter Market
Connectors
5G Connector Market
Connectors
IC Socket Market
Connectors
Smart Crimper Market
Connectors
Hazardous Location Connectors Market
Connectors
Wire-To-Board Connector Market
Connectors
High-Reliability Connectors Market
Connectors
Circular Waterproof Connector Market
Connectors
Connector and Terminal Systems for Harsh Environment Wiring Market
Connectors
Connector Market
Connectors
Telecom Mounting Hardware Market
Connectors
Press Fit Connector Market
Connectors
Asia-Pacific Connector Market
Connectors
Hybrid Fiber Optic Connectors Market
Connectors
Space Grade Connectors Market