
 USB Type-C Market | 2026-2036
USB Type-C Market Size, Share, and Industry Trends Forecast 2026-2036
USB Type-C Market Outlook
Modular bundling of USB Type-C cables with power adapters and device housings is realigning procurement patterns across consumer electronics supply chains. Texas Instruments leverages its analog semiconductor portfolio to anchor power delivery controller shipments for premium laptop OEMs. STMicroelectronics sustains competitive positioning through integrated MCU and protection IC designs that reduce board space in compact charger architectures.
USB Type-C denotes a 24-pin reversible connector system supporting USB Power Delivery up to 240 watts and data rates up to 80 Gbps under USB4 Version 2.0 specifications, engineered to unify charging, data, and display interfaces across consumer and enterprise hardware. The cable segment dominates volume shipments due to replacement cycles and in-box bundling, while power delivery technology commands disproportionate margin pools as wattage ratings escalate for laptop and workstation applications. Multi-function hubs represent the fastest-growing product category as hybrid work patterns sustain dock and peripheral attachment demand.
The European Union's Radio Equipment Directive mandates USB Type-C as the universal charging interface, compelling hardware redesigns across smartphone and tablet portfolios, while the USB Implementers Forum certification program governs interoperability testing and trademark licensing for connector and cable assemblies. China's SAMR enforces national standard GB/T 32638 for cable safety and electromagnetic compatibility, shaping export qualification requirements for Shenzhen and Dongguan manufacturing clusters. Stakeholders must monitor evolving wattage tiers and regional certification reciprocity to align product roadmaps with fragmented compliance landscapes.
Market Dynamics
The European Union's Radio Equipment Directive mandating USB Type-C as the universal charging interface is forcing hardware redesigns across smartphone, tablet, and peripheral portfolios, compressing connector diversity into a single standard while amplifying volume concentration for certified component suppliers.
Growth Catalysts
- EU Regulatory Mandate:The Radio Equipment Directive compels OEMs to standardize charging ports, eliminating proprietary connectors and consolidating procurement volumes toward USB Type-C certified suppliers.
- Power Delivery Escalation:USB Power Delivery 3.1 specifications supporting 240W output enable laptop and workstation charging through unified cables, displacing barrel-jack adapters in enterprise fleets.
- Electronics Manufacturing Concentration:Shenzhen and Dongguan clusters in China anchor global cable and connector production, achieving scale economies that reduce per-unit costs for export markets.
Market Restraints
- Copper Price Volatility:Raw material fluctuations in copper and gold plating for connector contacts compress margin stability for cable assemblers operating on fixed-price contracts.
- Certification Cost Burden:USB-IF trademark licensing and interoperability testing fees create fixed cost barriers for small-scale cable manufacturers seeking premium tier positioning.
- Legacy Device Persistence:Micro-USB and Lightning connector installed bases in emerging markets delay full Type-C penetration, fragmenting accessory demand across multiple standards.
Strategic Opportunities
- Automotive Infotainment Integration:In-cabin charging and data ports in electric vehicles represent an underpenetrated application, with Tier 1 suppliers redesigning center consoles around USB4 hubs.
- India Manufacturing Incentives:PLI scheme subsidies for electronics assembly attract cable and connector producers to diversify beyond China-centric supply chains.
- DisplayPort Alt Mode Convergence:Single-cable docking solutions combining power, data, and video output are displacing proprietary dock architectures in hybrid work deployments.
Industry Challenges
- Signal Integrity Engineering Talent:Shortage of high-speed PCB designers capable of managing 80 Gbps USB4 routing constraints delays product qualification timelines for premium cable manufacturers.
- Recertification Complexity:Wattage tier upgrades and regional electromagnetic compatibility variations force repeated testing cycles, extending time-to-revenue for new product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | USB Type-C Market |
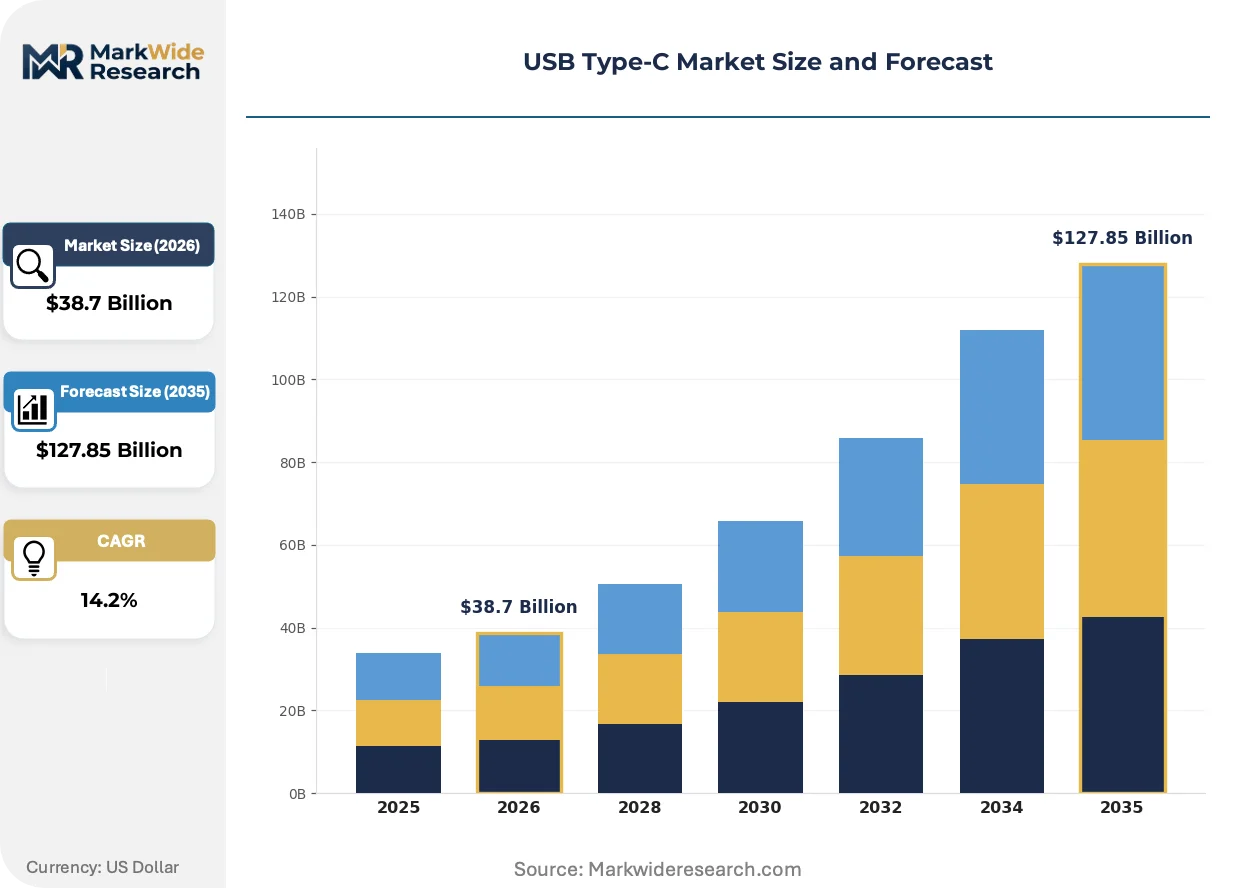
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $127.85 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cables, Adapters, Hubs, Chargers Application: Smartphones, Laptops, Tablets, Accessories End User: Consumers, Enterprises, OEMs, Retailers Technology: Power Delivery, Data Transfer, Audio/Video, Multi-Function |
| Companies Covered | Texas Instruments, STMicroelectronics, Belkin International, Anker Innovations, NXP Semiconductors, Infineon Technologies, Microchip Technology, Samsung Electronics, Apple, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
USB Type-C Market Strategic Shifts
Active cable architectures and intelligent power negotiation protocols are redefining performance thresholds across consumer and enterprise segments. These advances compress replacement cycles while elevating technical barriers for commodity producers.
USB4 Version 2.0 active cable technology is converging with silicon-based signal conditioning to maintain 80 Gbps throughput across extended lengths. Laptop OEMs are adopting these cables for workstation docking configurations. The technology is converging with premium pricing tiers, separating certified active-cable suppliers from passive copper assemblers.
China's SAMR enforcement of GB/T 32638 cable safety standards is tightening electromagnetic compatibility requirements for export qualification. Dongguan manufacturing clusters are upgrading shielding and insulation processes to meet these specifications. High-wattage laptop charging cables face the most stringent testing protocols, compressing supplier qualification timelines.
Enterprise procurement teams are consolidating vendor relationships around certified USB-IF suppliers with integrated power delivery and data hub portfolios. Direct OEM partnerships are displacing distributor-centric purchasing for volume cable and adapter procurement. This concentration is most visible in North American and European enterprise technology refresh cycles.
USB Type-C Market Segmentation
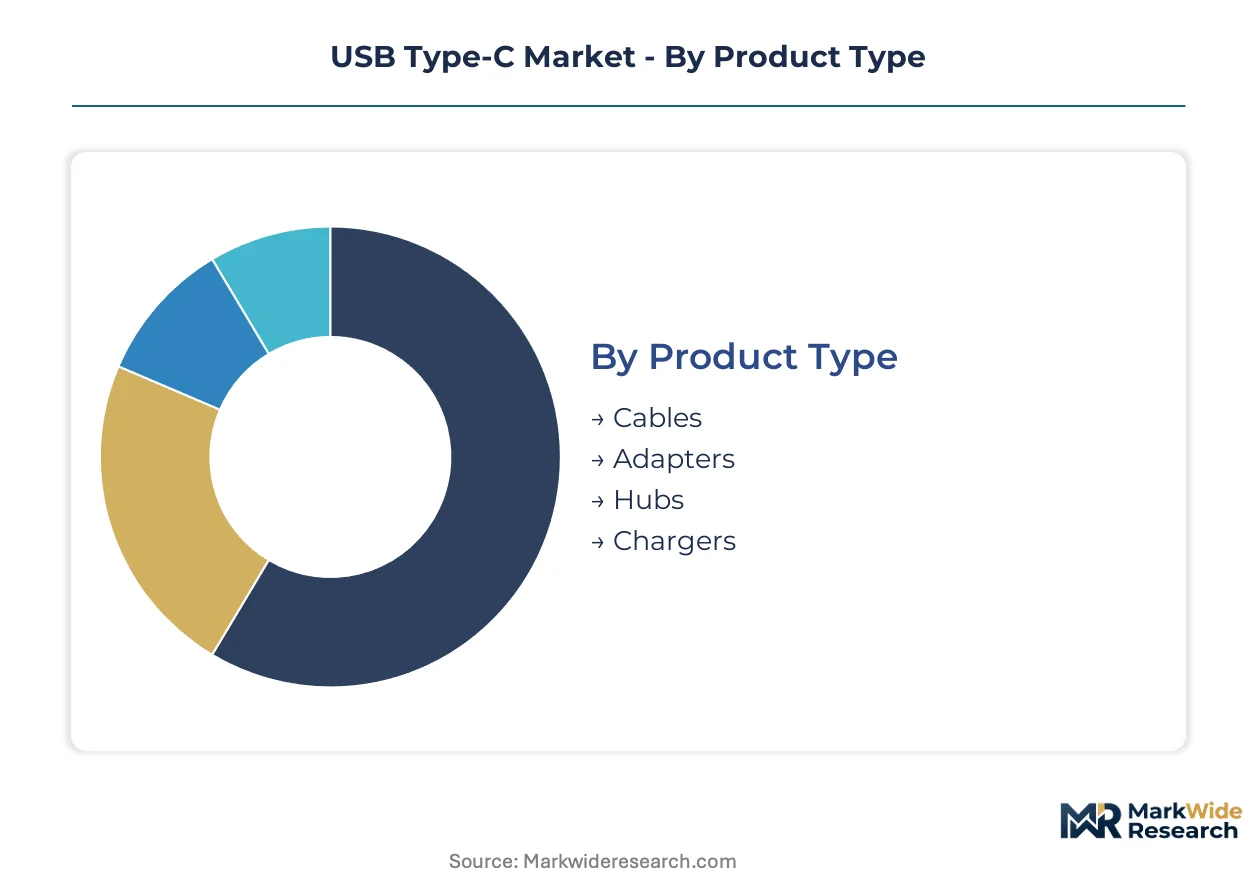
USB Type-C market segmentation reveals divergent margin structures across hardware categories and customer channels. Volume shipment economics favor cable producers while power delivery technology captures premium value pools in enterprise and OEM procurement.
Product Type:
Cables dominate absolute shipment volumes through replacement cycles and in-box bundling, while power delivery controllers and active cable architectures command disproportionate margin concentration.
- Cables:Passive copper assemblies anchor entry-level pricing tiers through Shenzhen and Dongguan manufacturing scale. Consumer electronics OEMs bundle these as standard accessories, compressing per-unit margins while sustaining massive throughput for certified suppliers.
- Chargers:GaN semiconductor integration and USB Power Delivery 3.1 protocol support enable 240W output for laptop and workstation applications. Enterprise fleet refresh cycles and EU regulatory mandates are accelerating displacement of proprietary barrel-jack adapters.
- Adapters:Legacy connector transition bridges for Micro-USB and Lightning installed bases.
- Hubs:Multi-function docking architectures consolidating power, data, and DisplayPort Alt Mode video output for hybrid work deployments.
Today's leader: Cables. Tomorrow's challenger: Chargers.
Application:
Smartphone penetration approaches saturation in developed markets, redirecting growth vectors toward laptop power delivery escalation and automotive infotainment integration.
- Smartphones:EU Radio Equipment Directive mandates have eliminated proprietary connector diversity, consolidating procurement volumes. Dongguan cable assemblers now serve standardized port requirements across Android OEM portfolios.
- Laptops:USB4 Version 2.0 active cable specifications supporting 80 Gbps throughput enable single-cable docking. IT procurement teams in North America and Europe are standardizing on 100W-240W power delivery tiers for workstation fleets.
- Tablets:Hybrid positioning between mobile and computing use cases drives mid-tier power delivery requirements.
- Accessories:Peripheral attachment demand spanning external storage, audio interfaces, and input devices.
Smartphones hold installed base dominance. Laptops are climbing the fastest on power delivery wattage escalation.
End User:
Procurement pattern fragmentation separates high-volume OEM bundling contracts from enterprise direct purchasing and retail replacement demand.
- OEMs:Consumer electronics manufacturers negotiate multi-year cable and adapter supply agreements with integrated power delivery portfolio suppliers. Texas Instruments and STMicroelectronics anchor controller silicon sourcing for premium laptop portfolios.
- Enterprises:IT asset management teams consolidate vendor relationships around USB-IF certified suppliers with interoperability documentation. Direct procurement is displacing distributor channels for volume adapter and hub deployment.
- Consumers:Individual replacement purchases through retail and e-commerce channels.
- Retailers:Private-label cable and accessory sourcing for aftermarket positioning.
OEMs drive volume concentration. Enterprises are expanding most quickly on hybrid work infrastructure investment.
Technology:
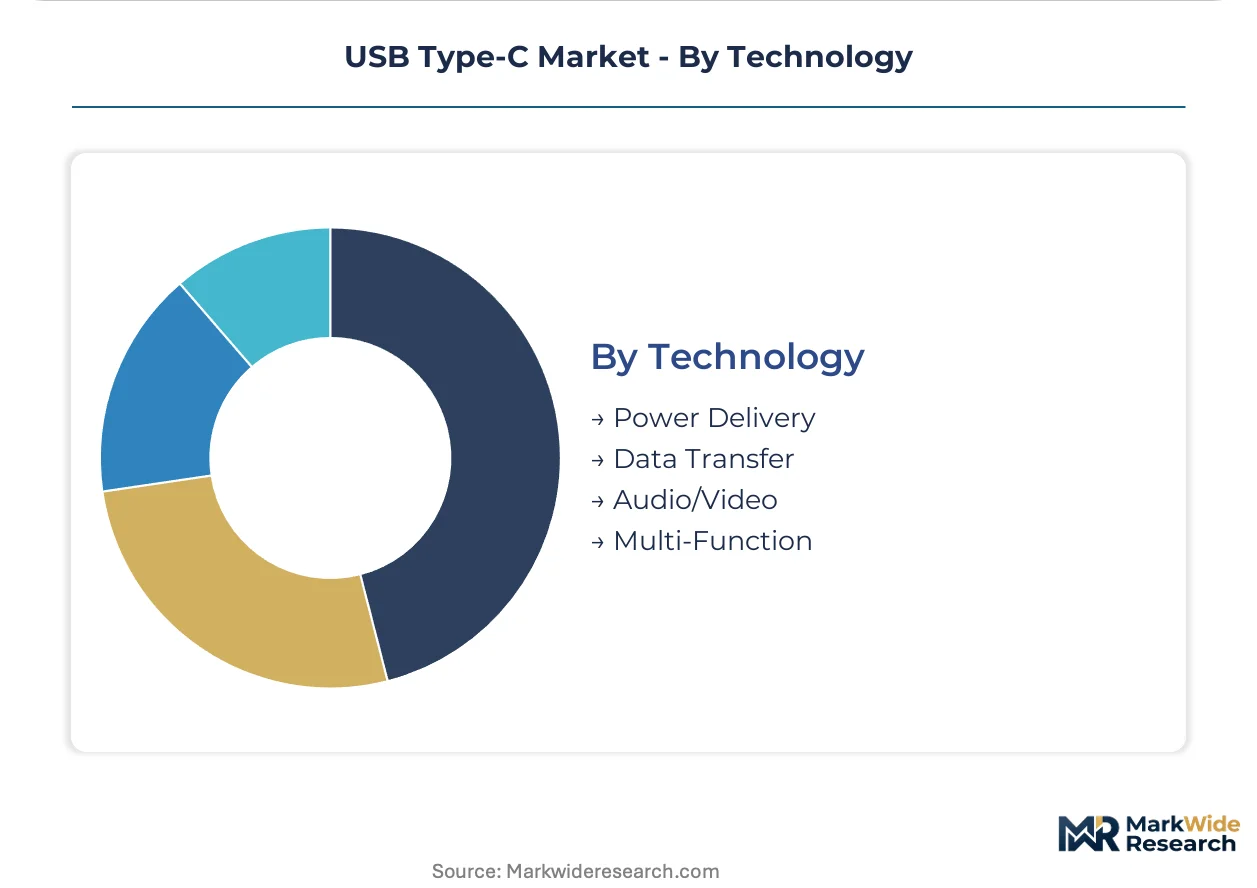
Functional convergence toward multi-purpose architectures is compressing single-use technology segments while elevating certification and signal integrity requirements.
- Multi-Function:Integrated power, data, and video delivery through single connector architectures. Active cable signal conditioning and intelligent power negotiation protocols separate certified suppliers from commodity assemblers.
- Power Delivery:USB PD 3.1 specification implementation with Extended Power Range enabling 48V/5A configurations. China's SAMR GB/T 32638 enforcement imposes stringent electromagnetic compatibility testing for high-wattage laptop charging cables.
- Data Transfer:USB4 80 Gbps symmetrical throughput specifications.
- Audio/Video:DisplayPort Alt Mode and analog audio accessory support.
Multi-Function integration leads roadmap investment. Power Delivery commands steepest expansion trajectory on wattage tier escalation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
USB Type-C connector standardization traces its commercial lineage to Intel's 2014 specification release in the United States, though mass manufacturing scale emerged subsequently in China's Pearl River Delta electronics clusters. Regional adoption patterns now diverge between regulatory-mandated standardization in Europe and supply-chain-driven integration across Asia-Pacific manufacturing hubs.
China
Dongguan and Shenzhen cable assemblers supply the majority of global USB Type-C volume through vertically integrated connector molding and copper wire drawing operations. SAMR enforcement of GB/T 32638 electromagnetic compatibility standards tightens export qualification protocols for high-wattage laptop charging assemblies. The Pearl River Delta manufacturing corridor is upgrading active cable shielding processes to meet these specifications.
United States
Enterprise IT procurement teams in North America are consolidating vendor relationships around USB-IF certified suppliers for workstation fleet refresh cycles. FCC equipment authorization requirements govern connector emissions testing for commercial hardware deployments. Texas Instruments anchors power delivery controller design activity in Dallas-Fort Worth semiconductor corridors.
Germany
Automotive Tier 1 suppliers in Baden-Württemberg are redesigning electric vehicle center consoles around USB4 hub architectures for in-cabin charging and data connectivity. KBA type-approval processes incorporate electromagnetic compatibility validation for integrated infotainment systems. Stuttgart engineering clusters are qualifying active cable assemblies for extended-temperature automotive specifications.
India
Electronics manufacturing services providers in Karnataka and Tamil Nadu are expanding USB Type-C cable assembly capacity under PLI scheme subsidies for mobile phone and accessory production. BIS certification mandates IS 13252 safety testing for power adapter and cable imports. Chennai and Sriperumbudur industrial zones are attracting connector producers diversifying beyond China-centric supply chains.
Japan
Precision connector manufacturers in Nagoya and Osaka industrial corridors supply high-reliability USB Type-C assemblies for industrial automation and medical equipment applications. METI technical standards JIS C 1010 govern safety requirements for information technology equipment. Aichi Prefecture fabrication facilities are qualifying 80 Gbps active cable architectures for factory automation deployments.
USB Type-C Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification tier and power delivery specification depth. The vendor base stratifies between USB-IF trademark licensees with full interoperability documentation and uncertified assemblers competing on price. Three archetypes dominate: integrated semiconductor-controller suppliers, branded cable and accessory specialists, and contract manufacturing aggregators serving OEM bundling programs. Competitive moves center on GaN semiconductor integration for thermal efficiency and strategic partnerships with laptop OEMs for power delivery controller socket wins.
Within the semiconductor-controller tier, Texas Instruments and STMicroelectronics exemplify the analog-integration archetype, anchoring power delivery IC sourcing for premium laptop portfolios. Among branded accessory specialists, Anker Innovations occupies a position representing the direct-to-consumer engineering-focused archetype. These named entities sit within a broader competitive set where certification depth and wattage tier coverage determine procurement access to enterprise and OEM channels.
| Leading Market Players |
|---|
| Texas Instruments |
| STMicroelectronics |
| Belkin International |
| Anker Innovations |
| NXP Semiconductors |
| Infineon Technologies |
| Microchip Technology |
| Samsung Electronics |
| Apple |
| Others |
Value Chain & Pricing Dynamics
Certification-grade bifurcation between USB-IF trademark licensees and uncertified assemblers manifests in parallel pricing power and procurement channel access. Premium-tier suppliers command socket wins with laptop OEMs through interoperability documentation, while commodity producers in Dongguan compete on spot-market copper pricing and thin assembly margins.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates active-cable architectures with signal conditioning silicon from passive copper assemblies and unbranded imports. Price differentiation hinges on USB-IF certification depth and GaN semiconductor integration for thermal efficiency. Cost compression in economy-tier passive cables is intensifying because Shenzhen manufacturers absorb copper volatility through fixed-price export contracts. Enterprise IT procurement teams exhibit lowest price sensitivity, prioritizing interoperability documentation over per-unit cost.
Supply Chain Analysis
Freight cost fluctuations between Pearl River Delta ports and North American distribution centers compress margin stability for cable assemblers operating on delivered-duty-paid terms. Manufacturing concentrates in China, Vietnam, and India, with Dongguan and Shenzhen anchoring global connector molding and copper wire drawing. Raw material dependencies span copper cathode, gold plating for contact surfaces, and GaN-on-silicon wafers for power delivery controllers. Single-source vulnerability concentrates in China's SAMR-certified shielding material suppliers. Distribution runs through direct OEM partnerships for volume procurement, displacing distributor-centric purchasing in enterprise channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where India's PLI scheme subsidies for electronics assembly create a 15-20% landed cost advantage versus China-centric sourcing for North American buyers navigating tariff exposure.
For Market Incumbents: Anticipate margin compression from GaN semiconductor commoditization by locking multi-year controller supply agreements with Texas Instruments and STMicroelectronics. Prioritize backward integration into connector molding operations to defend against Dongguan assemblers upgrading certification tiers. Channel control through direct OEM partnerships remains the critical lever for volume retention.
For New Entrants and Emerging Players: Launch via private-label supply contracts with Indian EMS providers under PLI scheme coverage to bypass China's SAMR export qualification bottlenecks. Target automotive infotainment integration as the most penetrable white space, where Tier 1 suppliers redesign electric vehicle center consoles around USB4 hubs. Pursue USB-IF certification investment as the primary go-to-market angle for enterprise procurement access.
For Investors and Strategic Acquirers: Consolidation pressure builds where certification cost burdens and repeated recertification cycles strand sub-scale cable manufacturers without active-cable engineering capabilities. Long-term viability favors integrated semiconductor-controller suppliers with power delivery and data hub portfolios. Acquisition target archetype: mid-cap USB-IF licensees with 80 Gbps signal integrity talent and automotive qualification pipelines. Watch laptop OEM power delivery wattage tier escalations as the inflection indicator for controller silicon demand.
| Strategic Initiative | Industry Significance |
|---|---|
| GaN Semiconductor Integration | Thermal efficiency gains enable 240W laptop charging through compact adapter form factors. |
| USB-IF Certification Investment | Interoperability documentation unlocks direct procurement contracts with enterprise IT asset managers. |
| Active Cable Architecture Development | Signal conditioning silicon maintains 80 Gbps throughput across extended cable lengths for workstation docking. |
| Automotive Infotainment Partnership | Tier 1 suppliers qualify USB4 hubs for electric vehicle center console integration under KBA type-approval. |
| India Manufacturing Footprint Expansion | PLI scheme subsidies attract cable assembly capacity to Karnataka and Tamil Nadu industrial zones. |
Study Parameters
Bottom-up OEM bundling and enterprise procurement modeling reconciled against top-down semiconductor controller shipment tracking forms the analytical core of this study. Primary interviews with consumer electronics supply chain managers, power delivery IC design engineers, USB-IF certification program administrators, and automotive Tier 1 procurement directors combined with secondary validation from SEC semiconductor filings, USB Implementers Forum trademark licensee directories, and China's SAMR GB/T 32638 enforcement notices. Triangulation across these sources anchors volume and value estimates.
Input-output matrices map connector and cable assembly throughput from Dongguan and Shenzhen manufacturing clusters against power delivery controller silicon sourcing from Texas Instruments and STMicroelectronics. Segmentation dimensions span product type, application, end user, and technology tiers across the analysis window. CAGRs derive from regression analysis of historical shipment correlations with laptop refresh cycles and EU regulatory mandate implementation timelines. Forecast inputs incorporate copper price volatility assumptions and certification reciprocity evolution between China's SAMR and regional electromagnetic compatibility regimes.
Several conditions sit outside the modeled scope, including speculative USB5 specification releases, unilateral trade barrier escalations, and automotive platform standardization delays. Forecasts reflect documented assumptions about regulatory enforcement consistency and semiconductor foundry capacity allocation. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Connectors
LCP Connectors Market
Connectors
Global Cables and Connector Market
Connectors
Connector Adapter Kits Market
Connectors
Heavy-Duty Connector Market
Connectors
Hazardous Location Connectors Market
Connectors
Underwater Connectors Market
Connectors
5G Connector Market
Connectors
Space Grade Connectors Market
Connectors
Middle East and Africa Hazardous Location Connectors Market
Connectors
Magnetic Connector Market
Connectors
Wire-To-Board Connector Market
Connectors
Automotive Data Connectors Market
Connectors
Filtered Connectors Market
Connectors
India Connector Market
Connectors
Global Wired Interface Market
Connectors
Line Clamp Market