
 Asia-Pacific Connector Market | 2026-2036
Asia-Pacific Connector Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Connector Market Insights
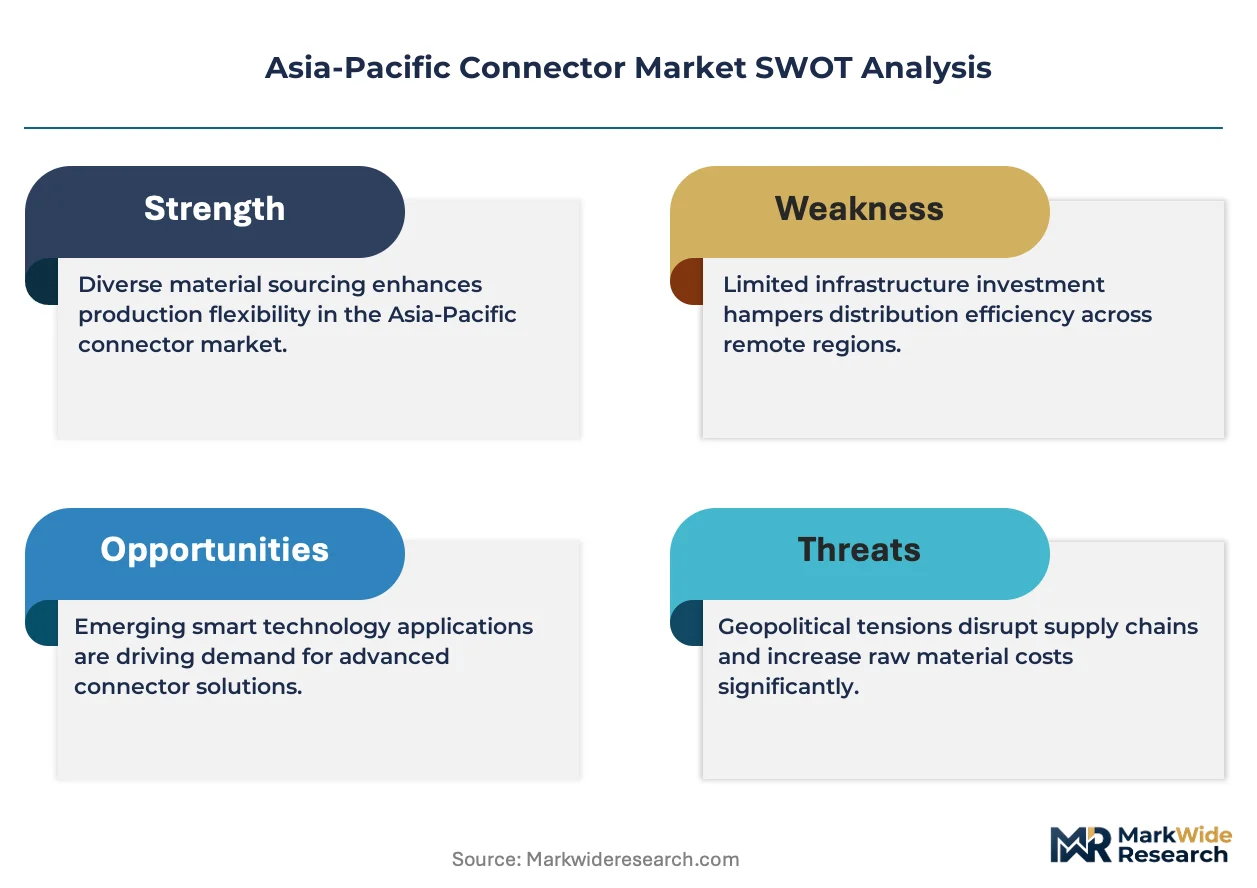
A capital-intensity divergence between integrated manufacturers and assembly-only suppliers is reorganizing competitive tiers in the Asia-Pacific connector industry. TE Connectivity Ltd leverages captive die-casting and plating operations across Thailand and China to sustain margin control on high-pin-count automotive harness connectors. Hirose Electric Co Ltd anchors its position through microminiature board-to-board specialization for Japanese consumer electronics OEMs. Sumitomo Electric Industries, Ltd. competes on fiber optic connector verticality, drawing polymer and optical fiber resources from its materials divisions.
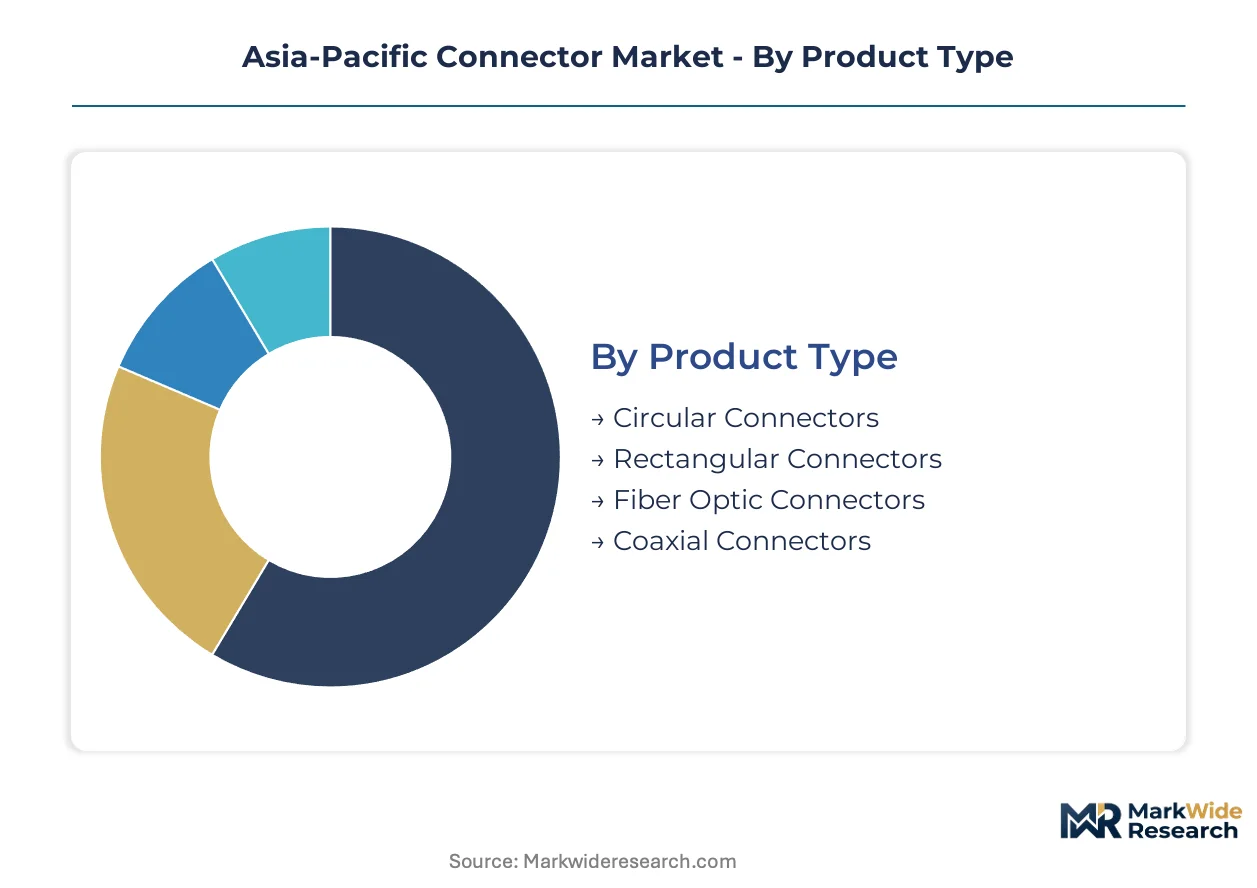
Asia-Pacific connectors are electromechanical devices engineered to join electrical terminations for signal transmission or power distribution, typically rated for specific current loads, mating cycles, and environmental sealing against dust or moisture ingress. Their primary purpose is to enable modular system architecture while maintaining signal integrity across vibration, thermal cycling, and electromagnetic interference conditions. Rectangular connectors dominate industrial equipment applications where multi-circuit density and panel-mount reliability command premium positioning. Fiber optic connectors represent the fastest-expanding product category as 5G backhaul and data center builds in South Korea and Australia strain copper bandwidth limits. Circular connectors retain mature, stable demand from defense and heavy machinery sectors where MIL-spec durability standards preserve incumbent supplier relationships.
China's MIIT enforces GB/T national connector standards for new energy vehicles, while Japan's METI administers JIS certification for industrial automation interoperability. South Korea's MFDS and KTL testing protocols shape medical and telecommunications connector approval pathways, respectively. REACH-compliant material declarations from European-exporting Asian manufacturers are becoming de facto prerequisites for supply chain qualification. Stakeholders must monitor evolving Chinese dual carbon goals for their impact on connector plating chemistry restrictions and regional factory energy audits.
Market Dynamics
Automotive electrification programs across China, Japan, and South Korea are restructuring procurement criteria for high-reliability interconnect systems, compressing qualification timelines while elevating performance thresholds for thermal cycling and vibration resistance.
Growth Catalysts
- MIIT GB/T Standards:China's mandatory new energy vehicle charging connector specifications are forcing domestic and foreign suppliers to retool production lines for high-voltage, high-current compatibility.
- 5G Backhaul Builds:South Korean and Australian telecommunications infrastructure expansion is accelerating fiber optic connector deployment as copper bandwidth limits strain under data center loads.
- Industrial Automation:Japan's METI push for smart factory interoperability is generating sustained demand for JIS-certified rectangular connectors in precision machinery applications.
Market Restraints
- Raw Material Concentration:Copper and high-performance polymer supply chains concentrate in specific Chinese provinces, exposing manufacturers to localized logistics disruptions and input cost volatility.
- Plating Chemistry Restrictions:REACH-compliant material declarations from European-exporting Asian manufacturers are becoming de facto prerequisites, eliminating cadmium and certain hexavalent chromium processes from qualified supplier lists.
- Optical Fiber Substitution:Fiber optic interconnects are progressively displacing copper in high-bandwidth applications, constraining growth potential for traditional signal connectors in telecommunications backbones.
Strategic Opportunities
- Medical Device Interconnects:South Korea's MFDS testing protocols for implantable and diagnostic equipment create a protected niche for sterilization-resistant microminiature connectors with extended mating cycle ratings.
- Dual Carbon Alignment:China's evolving factory energy audit requirements and plating chemistry restrictions favor suppliers with captive renewable energy and closed-loop wastewater systems in the Yangtze River Delta.
- Edge Computing Hardware:Convergence of 5G small-cell infrastructure and industrial IoT gateways in Japanese and Australian markets is opening demand for hybrid power-and-signal connectors with integrated EMI shielding.
Industry Challenges
- Precision Machining Talent:The Asia-Pacific connector industry faces acute shortages of technicians skilled in micro-molding and sub-micron stamping operations required for board-to-board miniaturization.
- Qualification Timeline Compression:Automotive OEMs are collapsing traditional 18-month validation cycles into 8-10 months, straining testing laboratory capacity and forcing parallel rather than sequential certification tracks.
- Legacy System Integration:Industrial automation retrofits in Japan and South Korea require backward-compatible connector footprints that constrain design freedom and prolong obsolete product support obligations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Connector Market |
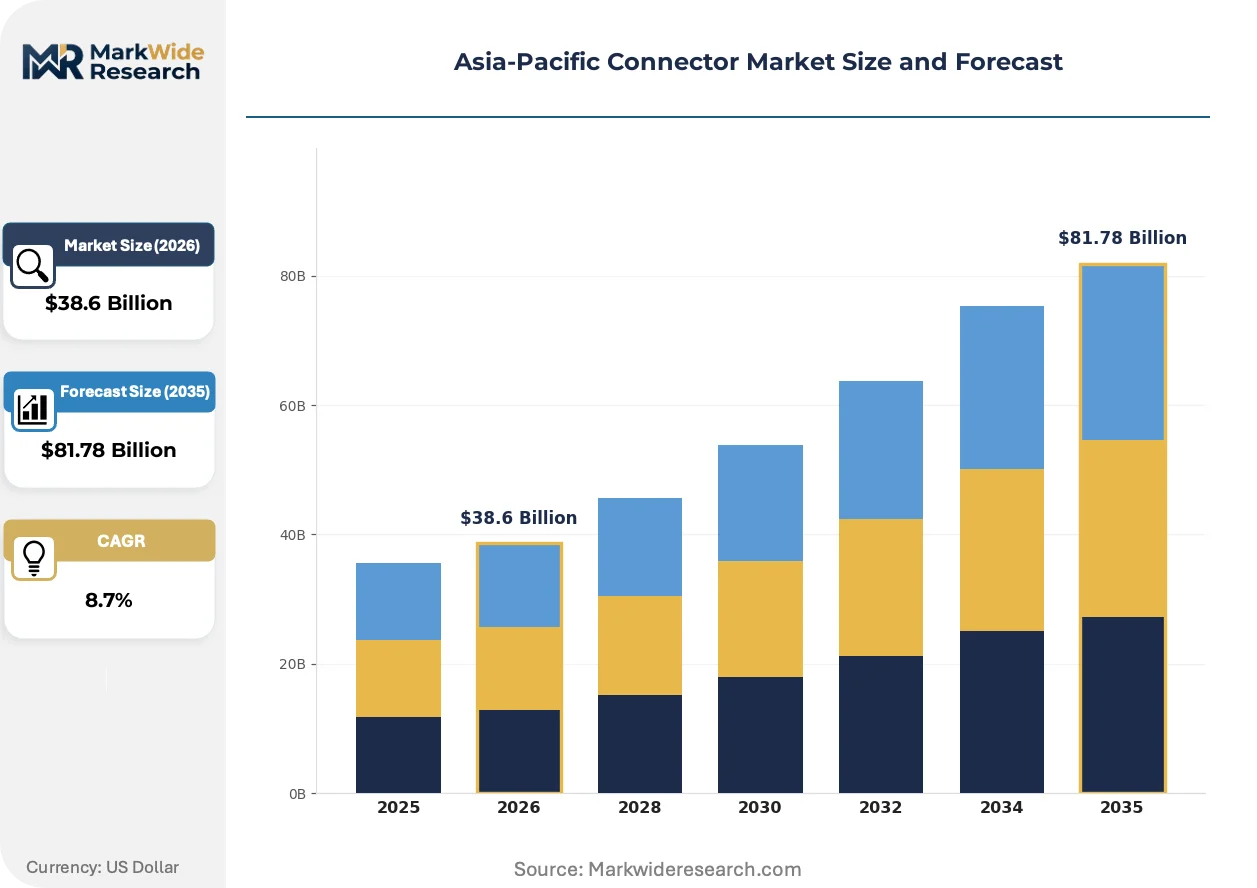
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $81.78 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Circular Connectors, Rectangular Connectors, Fiber Optic Connectors, Coaxial Connectors End User: Telecommunications, Automotive, Industrial Equipment, Consumer Electronics Connection Method: Wireless, Hardwired, Hybrid, Blow-Molded Application: Data Transmission, Power Distribution, Signal Processing, Automation |
| Companies Covered | TE Connectivity Ltd, Amphenol Corporation, Molex LLC, 3M Company, Aptiv PLC, Sumitomo Electric Industries, Ltd., Hirose Electric Co Ltd, Japan Aviation Electronics Industry, Ltd., Yazaki Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Connector Market Trends and Innovations
Active materials substitution, regulatory chemistry restrictions, and procurement model rationalization are concurrently reshaping how connector manufacturers configure product portfolios and supply relationships across the Asia-Pacific region.
High-temperature liquid crystal polymer housings are decomposing traditional thermoplastic dominance in automotive underhood applications. Chinese EV battery pack manufacturers are specifying these materials for 150°C continuous operation zones. This substitution is compressing the addressable market for standard nylon and PBT compounds in powertrain interconnects.
METI-administered JIS certification for industrial automation interoperability is mandating standardized pin assignments and mechanical keying across Japanese machinery OEMs. The regulation forces connector suppliers to maintain dual inventory streams for Japan-bound versus export-configured products. Precision equipment builders in the Nagoya manufacturing corridor are responding by consolidating supplier lists to vendors with dedicated JIS-compliant production cells.
Automotive tier-1 suppliers are unbundling connector procurement from full harness assembly contracts, creating direct purchasing relationships with specialized interconnect manufacturers. This disintermediation bypasses traditional wiring harness assemblers in China's Yangtze River Delta and South Korea's Gyeonggi-do province. The pattern is most pronounced among battery electric vehicle programs where high-voltage connector performance requirements exceed standard harness supplier technical capabilities.
Asia-Pacific Connector Market Segmentation
Connector procurement in the Asia-Pacific region flows through distinct channel architectures shaped by end-use certification requirements and manufacturing cluster proximity. Segment-specific qualification protocols in automotive and medical applications create divergent distribution pathways that suppliers must navigate simultaneously.
Product Type:
Circular connectors move through defense and heavy machinery OEM direct channels, while rectangular and fiber optic variants split between telecom infrastructure contractors and industrial automation distributors.
- Circular Connectors:MIL-spec durability ratings with threaded coupling mechanisms define this category. Demand concentrates in Japan's defense procurement and Australia's mining equipment rebuild programs, where incumbent supplier relationships and extended qualification cycles protect established vendors.
- Rectangular Connectors:Multi-circuit density configurations with panel-mount reliability dominate industrial equipment applications. China's Yangtze River Delta manufacturing corridor consumes the majority of regional volume for factory automation and EV battery pack integration, driven by MIIT-mandated charging standard compliance.
- Fiber Optic Connectors:South Korean 5G backhaul builds and Australian data center expansions are straining copper bandwidth limits, accelerating deployment of LC and MPO interfaces for high-density optical interconnects.
- Coaxial Connectors:RF signal transmission applications in telecommunications infrastructure and broadcast equipment sustain steady demand through specialized RF component distributors.
By volume, rectangular connectors lead. By growth pace, fiber optic variants are climbing the fastest.
End User:
Cost tier differentiation separates premium-certified automotive and medical segments from price-sensitive consumer electronics procurement.
- Automotive:High-voltage interconnect systems for battery electric vehicles require thermal cycling resistance beyond standard specifications. China's MIIT GB/T charging connector mandates and South Korean OEM electrification programs are compressing supplier qualification timelines to 8-10 months.
- Telecommunications:5G infrastructure deployment across South Korea and Australia demands fiber optic and high-speed copper interconnects with signal integrity guarantees for small-cell and macro-cell base stations.
- Industrial Equipment:Japan's METI smart factory initiative generates sustained demand for JIS-certified rectangular connectors in precision machinery and robotics applications across the Nagoya manufacturing corridor.
- Consumer Electronics:Japanese microminiature board-to-board specifications for smartphones and wearables command premium positioning through specialized distribution serving Osaka and Tokyo design houses.
Automotive applications command the highest unit margins. Consumer electronics delivers the largest shipment volumes.
Connection Method:
Maturity gradients separate established hardwired architectures from emerging wireless and hybrid configurations in industrial IoT deployments.
- Hardwired:Soldered and crimped terminations remain dominant in automotive powertrain and industrial automation applications where vibration resistance and environmental sealing are non-negotiable.
- Wireless:Industrial IoT sensor networks in Japanese and Australian manufacturing facilities are adopting contactless power and data transmission for rotating equipment and hazardous environment applications.
- Hybrid:Combined power-and-signal configurations with integrated EMI shielding address edge computing hardware requirements at 5G small-cell and industrial gateway convergence points.
- Blow-Molded:Overmolded cable assemblies with integrated strain relief serve consumer electronics and medical device applications requiring sterilization resistance and extended flex life.
Hardwired methods retain the installed base. Hybrid configurations are gaining share fastest in new installations.
Application:
Supply concentration in China's polymer and copper processing clusters shapes regional fulfillment patterns for power distribution versus signal processing applications.
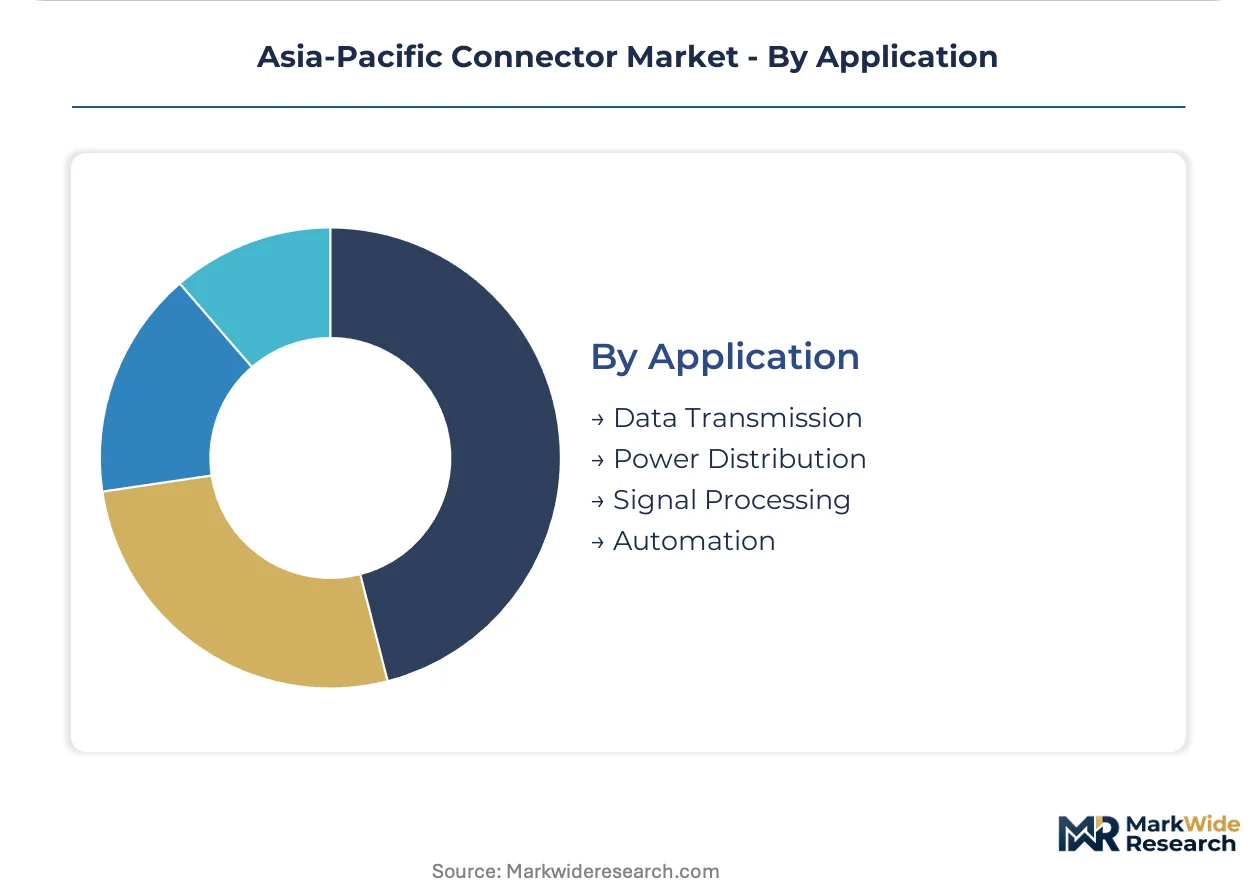
- Data Transmission:High-speed differential signaling for 5G fronthaul and data center interconnects demands controlled impedance and crosstalk suppression, with South Korean and Australian deployments driving fiber optic substitution.
- Power Distribution:High-current busbar and battery pack connectors for electric vehicles require liquid crystal polymer housings rated for 150°C continuous operation in Chinese EV manufacturing.
- Signal Processing:Analog and digital sensor interfaces in industrial automation rely on shielded coaxial and twisted-pair configurations with JIS-compliant pin assignments.
- Automation:Programmable logic controller I/O modules and robotic arm interconnects combine power, signal, and communication in hybrid rectangular formats across Japanese smart factory installations.
Power distribution applications anchor supplier revenue. Data transmission is expanding most quickly as bandwidth requirements escalate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Connector buyers in China's Yangtze River Delta manufacturing corridor exhibit the lowest price elasticity, absorbing premium pricing for MIIT-certified high-voltage interconnects. Australian mining equipment purchasers and South Korean consumer electronics OEMs operate at opposite ends of the sensitivity spectrum.
China
Electric vehicle battery pack integration and 5G telecommunications infrastructure anchor connector demand across the Yangtze River Delta. MIIT-administered GB/T national standards for new energy vehicle charging connectors mandate specific high-voltage, high-current compatibility requirements. Production clusters in Shanghai, Suzhou, and Ningbo serve domestic EV manufacturers and telecom equipment makers with captive die-casting and plating operations.
Japan
Industrial automation retrofits and precision machinery applications sustain demand for JIS-certified rectangular connectors. METI-administered certification for smart factory interoperability mandates standardized pin assignments and mechanical keying across machinery OEMs. The Nagoya manufacturing corridor concentrates procurement for robotics and programmable logic controller applications, with precision equipment builders consolidating supplier lists to vendors with dedicated JIS-compliant production cells.
South Korea
5G backhaul infrastructure and data center expansions accelerate fiber optic connector deployment as copper bandwidth limits strain under escalating loads. MFDS testing protocols for implantable and diagnostic medical equipment create protected niches for sterilization-resistant microminiature connectors. The Gyeonggi-do province hosts manufacturing operations serving both telecommunications infrastructure contractors and medical device OEMs with extended mating cycle requirements.
Australia
Mining equipment rebuild programs and data center construction sustain demand for MIL-spec circular connectors and high-density optical interconnects respectively. National broadband infrastructure initiatives and renewable energy grid expansions reshape procurement criteria for outdoor-rated power distribution connectors. Sydney and Melbourne metropolitan areas concentrate telecommunications and data center investment, while Western Australia mining corridors drive heavy machinery interconnect replacement cycles.
Thailand
Automotive harness assembly operations and electronics manufacturing services anchor connector consumption for regional export markets. Board of Investment incentives for electric vehicle supply chain localization attract tier-1 supplier investments in high-voltage interconnect production. The Eastern Economic Corridor development zone concentrates foreign direct investment in automotive and electronics manufacturing, with connector procurement increasingly unbundled from full harness assembly contracts.
Asia-Pacific Connector Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the Asia-Pacific connector industry. Captive die-casting, plating, and polymer compounding operations distinguish the upper tier from assembly-dependent competitors. Three archetypes define competitive positioning: diversified industrial conglomerates with materials science verticality, microminiature specialists serving consumer electronics design houses, and automotive-focused suppliers with high-voltage certification capabilities. Capacity expansion in China's Yangtze River Delta and strategic partnerships for JIS-compliant production cells represent the dominant competitive moves.
Among diversified industrial conglomerates, Sumitomo Electric Industries, Ltd. and TE Connectivity Ltd occupy positions defined by captive materials and process control. Hirose Electric Co Ltd exemplifies the microminiature specialist archetype serving Japanese consumer electronics OEMs. These three companies represent the tiered structure: integrated materials-backed diversification, precision miniaturization expertise, and automotive electrification readiness.
| Leading Market Players |
|---|
| TE Connectivity Ltd |
| Amphenol Corporation |
| Molex LLC |
| 3M Company |
| Aptiv PLC |
| Sumitomo Electric Industries, Ltd. |
| Hirose Electric Co Ltd |
| Japan Aviation Electronics Industry, Ltd. |
| Yazaki Corporation |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization gaps between captive plating operations and outsourced assembly tiers compress margin structures for connector suppliers serving China's Yangtze River Delta EV manufacturers. Scale economies in high-volume die-casting favor integrated producers, forcing price discipline on smaller competitors dependent on toll processing for connector housings.
Pricing Analysis
After-sales service contracts and extended mating cycle warranties anchor lifetime value for automotive tier-1 procurement teams. Three-tier pricing structure across premium, standard, and economy levels separates MIIT-certified high-voltage interconnects from uncertified commodity alternatives. Cost compression in standard-grade rectangular connectors intensifies as Chinese EV OEMs consolidate supplier lists around proven thermal cycling performers. Battery electric vehicle programs exhibit the lowest price sensitivity, while consumer electronics distributors in South Korea's Gyeonggi-do province demand aggressive unit economics.
Supply Chain Analysis
Strait of Malacca transit routes and Shanghai-Ningbo port congestion expose connector manufacturers to logistics chokepoints when sourcing liquid crystal polymer compounds from Japanese chemical suppliers. Copper rod drawing and high-performance thermoplastic compounding concentrate in China's Jiangsu and Zhejiang provinces, with precision stamping equipment anchored in Japan's Nagoya corridor. Single-source vulnerability in specialized plating chemistry for REACH-compliant finishes threatens qualification timelines for European-exporting Asian manufacturers. Distribution runs through direct OEM channels for automotive and defense applications, while industrial automation procurement flows via authorized distributors with JIS certification capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive OEM electrification programs are consolidating connector procurement authority from harness assemblers to platform engineering teams, shifting buyer power toward direct specification control. Tier-1 unbundling of interconnect purchasing from full assembly contracts fragments traditional supplier relationships.
For Market Incumbents: Secure captive renewable energy capacity in the Yangtze River Delta to satisfy China's dual carbon factory audit requirements and plating chemistry restrictions. Defend against fiber optic substitution by deepening high-speed copper interconnect R&D for 5G small-cell edge computing applications. Add dedicated JIS-compliant production cells to capture Japan's METI-mandated smart factory retrofit demand. For New Entrants and Emerging Players: Anchor in South Korea's MFDS-certified medical device interconnect niche, where sterilization-resistant microminiature connectors command protected pricing. Target Australia's mining equipment rebuild programs for MIL-spec circular connectors, where incumbent relationships are weakest and qualification cycles are shorter than defense procurement. Pursue direct sales relationships with Chinese EV battery pack integrators bypassing traditional harness assemblers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors materials-backed conglomerates with captive polymer and optical fiber divisions over assembly-dependent specialists. Long-term viability rests on plating chemistry compliance capabilities and high-voltage certification track records. Watch for inflection when China's MIIT expands GB/T charging standards to commercial vehicle segments, accelerating production line retooling requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plating Operations | Captive REACH-compliant chemistry control protects margin structure against regulatory disqualification. |
| JIS-Certified Production Cell Investment | Dedicated Japan-bound capacity locks in METI-mandated smart factory procurement consolidation. |
| High-Voltage Interconnect Certification | MIIT GB/T compliance opens direct purchasing relationships with Chinese EV platform engineers. |
| Fiber Optic Vertical Integration | In-house optical fiber drawing captures South Korean 5G backhaul and Australian data center expansion. |
| Renewable Energy Factory Certification | Dual carbon alignment qualifies suppliers for premium positioning in China's Yangtze River Delta corridor. |
Research Methodology
Operator-level perspectives from connector procurement managers at automotive tier-1 suppliers, platform engineers at Chinese EV OEMs, and certification leads at Japanese industrial machinery builders anchored the qualitative base. Primary interviews combined with secondary validation from MIIT GB/T standard filings, METI JIS certification registries, and customs trade data for copper alloy and polymer compound flows. Bottom-up shipment estimates from Yangtze River Delta production clusters triangulated against top-down demand modeling from vehicle production and telecommunications infrastructure databases.
Sensitivity analysis across plating chemistry compliance scenarios and EV penetration trajectories informed value projections over the analysis window. Segmentation dimensions modeled include product type, end-use application, connection method, and regional regulatory cluster. CAGRs derived from historical shipment correlations with named industry drivers and elasticity-adjusted adoption curves. Forecast inputs incorporated MIIT mandate implementation timelines and South Korean 5G small-cell deployment schedules.
Material uncertainties — regulatory expansion of China's dual carbon audit requirements, fiber optic substitution rates in telecommunications backbones, and automotive qualification timeline compression — sit outside the modeled envelope. Forecasts reflect documented assumptions about standard adoption and supplier consolidation patterns. Practitioners should keep alternative scenarios live as METI smart factory interoperability mandates and MFDS medical device testing protocols evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Connectors
Liquid Cooling Connector Market
Connectors
Automotive Data Connectors Market
Connectors
Pin Retainer Market
Connectors
Hazardous Location Connectors Market
Connectors
Canada Connector Market
Connectors
Connector Kits Market
Connectors
Small Bore Connectors Market
Connectors
SATA Connector Market
Connectors
Press Fit Connector Market
Connectors
DIN Connectors Market
Connectors
China Connector Market
Connectors
Underwater Mate Connectors Market
Connectors
Global Multi Coaxial Connectors Market
Connectors
Circular Connectors Market
Connectors
Australia Connector Market
Connectors
Latin America Connector Market