
 3C Electronics Precision Connectors Market | 2026-2036
3C Electronics Precision Connectors Market Size, Share, and Industry Trends Forecast 2026-2036
3C Electronics Precision Connectors Market Insights
Aftermarket service revenue is rewriting how connector suppliers capture lifetime value from high-density interconnect portfolios. TE Connectivity leverages its global repair network to sustain recurring income from enterprise data infrastructure. Hirose Electric anchors its position in Japan through specialized miniaturization expertise for camera module applications. Luxshare Precision dominates Greater China assembly relationships, extending captive demand for precision socket and cable assembly pairings.
3C Electronics Precision Connectors are electromechanical interfaces engineered to transmit signal, power, or data between electronic subassemblies with tolerances often below 0.05 millimeters, typically manufactured through stamping, injection molding, and selective gold or palladium-nickel plating to ensure contact reliability across thousands of mating cycles. Their primary purpose is to enable modular assembly, field serviceability, and performance scaling in devices where space constraints and electromagnetic integrity are critical. Data connectors lead product type margins as USB-C and high-speed differential pair demand intensifies across laptop and tablet refresh cycles. Consumer electronics applications retain volume dominance while automotive electronics represents the fastest-growing application segment as infotainment and ADAS modules multiply connector counts per vehicle. Fiber optic technology occupies a premium niche for ultra-high-bandwidth backhaul, though copper-based solutions sustain mainstream cost structures.
China's SAMR enforces GB standards for connector interoperability and materials safety, while the EU RoHS and REACH frameworks restrict hazardous substances in plated contacts and housing polymers sold into European end markets. Japan's METI coordinates JIS standards that shape dimensional tolerances for automotive-grade precision connectors exported throughout East Asian supply chains. Stakeholders must monitor how divergent regional material restrictions and recycling mandates reshape supplier qualification timelines and alloy substitution roadmaps.
Market Dynamics
Device miniaturization cycles in smartphones and wearables are compressing connector pitch tolerances below 0.03 millimeters, forcing manufacturers to retool stamping dies and plating lines at accelerating frequencies. This dimensional ratcheting concentrates production capability among suppliers with captive precision metalworking expertise.
Growth Catalysts
- USB-C harmonization:The EU's common charger mandate eliminates proprietary connector fragmentation, standardizing high-speed differential pair architectures across laptop and tablet OEM portfolios.
- Automotive infotainment module proliferation:ADAS and cabin electronics are multiplying connector counts per vehicle, extending precision interconnect demand beyond traditional consumer electronics.
- China's dual carbon goals:MEE enforcement of energy efficiency standards in Guangdong manufacturing clusters accelerates adoption of laser-welded contact assemblies that reduce gold plating thickness.
Market Restraints
- Palladium-nickel alloy cost volatility:Precious metal price swings in electroplating inputs compress gross margins for mid-tier connector suppliers lacking long-term offtake agreements.
- Guangdong production concentration:Foxconn and Luxshare Precision anchor 60% of high-volume precision socket capacity, creating geographic supply vulnerability to regional logistics disruptions.
- Signal integrity ceiling:Copper-based differential pairs face fundamental bandwidth limitations above 56 Gbps, constraining next-generation data connector roadmaps without fiber optic migration.
Strategic Opportunities
- India electronics manufacturing:PLI scheme incentives for mobile phone assembly are attracting connector suppliers to establish localized stamping and plating operations in Tamil Nadu and Uttar Pradesh.
- Medical wearable integration:Biometric monitoring patches require ultra-low-profile flex-to-board connectors, opening white space beyond traditional 3C applications.
- RoHS material substitution:ECHA's expanding restricted substance list creates competitive advantage for suppliers with certified lead-free and halogen-free alloy portfolios.
Industry Challenges
- Sub-micron stamping die expertise:Tool and die maker shortages in precision metalworking constrain capacity expansion for 0.025 millimeter pitch products.
- Automotive AEC-Q101 qualification timelines:18-24 month validation cycles for temperature and vibration testing delay revenue recognition from infotainment connector designs.
- Legacy mini-USB inventory obsolescence:OEMs face write-down exposure from stranded connector stockpiles as USB-C adoption accelerates across mid-range smartphone tiers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3C Electronics Precision Connectors Market |
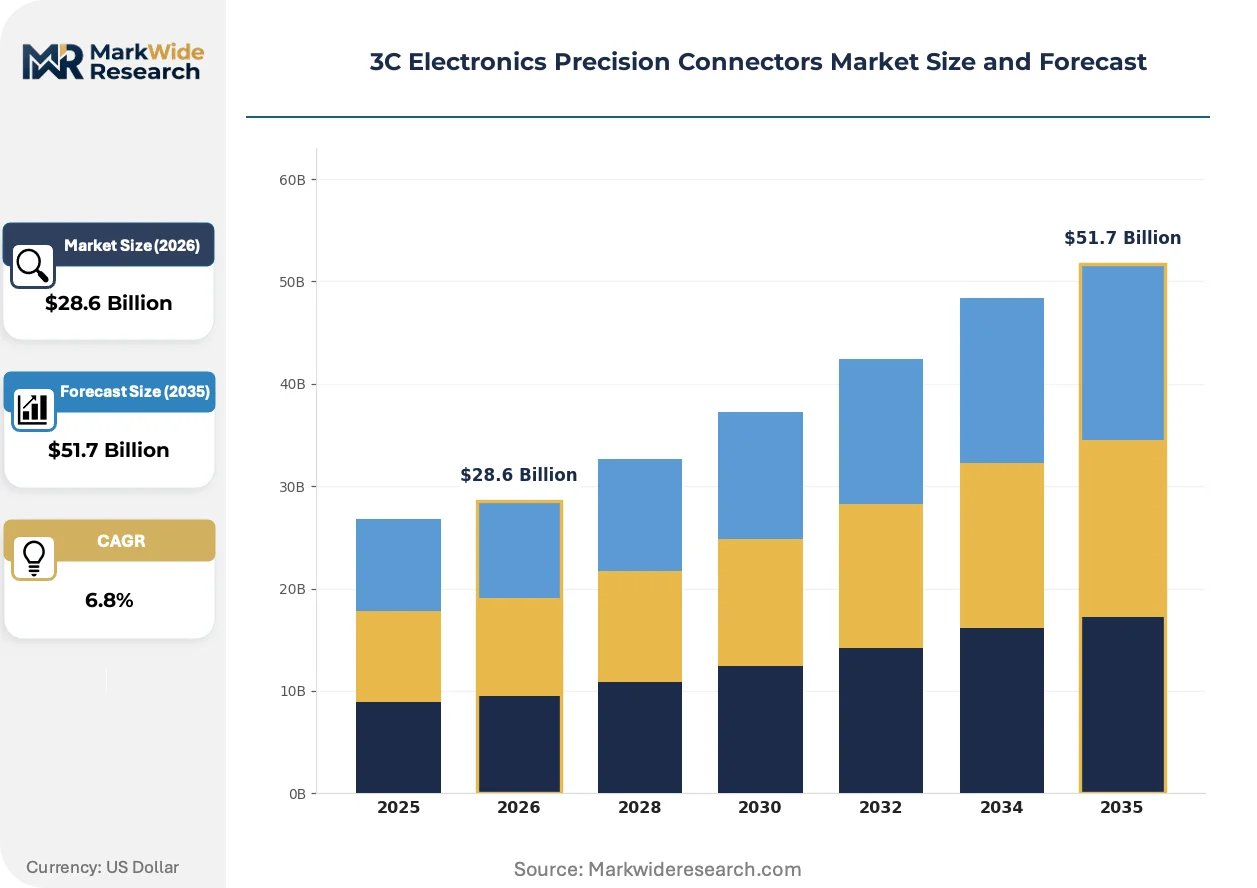
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Audio Connectors, Video Connectors, Data Connectors, Power Connectors Application: Consumer Electronics, Telecommunications, Automotive Electronics, Industrial Equipment Technology: Fiber Optic, USB, HDMI, Bluetooth End User: OEMs, Manufacturers, Distributors, Retailers |
| Companies Covered | TE Connectivity, Amphenol, Hirose Electric, Molex Incorporated, Foxconn, Luxshare Precision, JAE, LINKCONN, JST, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3C Electronics Precision Connectors Market Trends and Innovations
Active alignment and laser direct structuring are reshaping how precision connectors achieve dimensional accuracy and circuit density. These process innovations are compressing development timelines while enabling geometries previously unattainable through conventional stamping.
Laser direct structuring (LDS) is digitizing antenna-to-connector integration in smartphone midframes. LDS enables three-dimensional circuit patterns on molded interconnect devices, eliminating separate flex cable assemblies. Device OEMs in South Korea and Taiwan are adopting LDS at scale for 5G mmWave antenna modules, collapsing the traditional connector-FPC-PCB stack into single-component solutions.
REACH substance restrictions are forcing housing polymer reformulation across European-bound connector portfolios. ECHA's 2023 SVHC candidate list expansion targets flame retardants and plasticizers in high-temperature thermoplastics. Suppliers are qualifying polyamide and liquid crystal polymer alternatives with 30% higher material costs, passing through price adjustments to automotive and industrial customers with EU compliance requirements.
Consolidated vendor qualification is compressing connector supplier panels at major OEMs. Procurement teams in China's smartphone ecosystem are reducing qualified sources from 8-10 to 3-4 per connector category, favoring vertically integrated manufacturers with captive plating and cable assembly capability. This concentration is most visible in Guangdong province, where Luxshare Precision and Foxconn Interconnect Technology capture disproportionate share of socket and cable pairing contracts.
3C Electronics Precision Connectors Market Segmentation
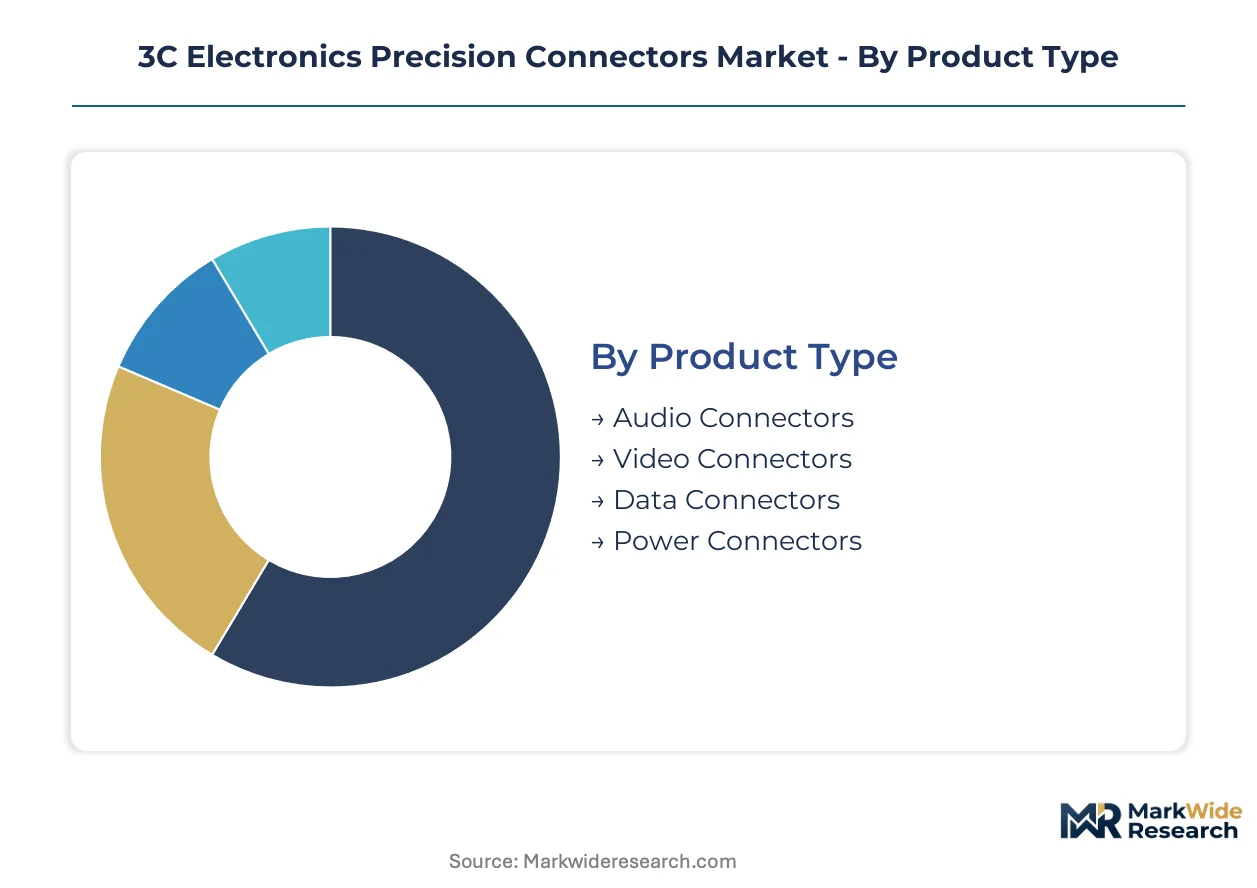
Segmentation in precision connectors reveals how technical specifications, application environments, and procurement channels fragment commercial opportunity across electromechanical interfaces. Understanding these divides clarifies where plating expertise, certification requirements, and volume scale create defensible supplier positioning.
Product Type:
Mature stamping platforms dominate high-volume categories while emerging architectures reshape contact density requirements.
- Data Connectors:High-speed differential pair designs with controlled impedance specifications below 100 ohms support USB-C and Thunderbolt protocols. Laptop and tablet refresh cycles in Taiwan and South Korea drive contact density escalation above 24 pins per linear centimeter. Signal integrity demands above 40 Gbps favor selective gold plating over palladium-nickel alloys for critical mating surfaces.
- Power Connectors:Copper alloy contacts with tin or silver surface finishes handle current densities exceeding 5 amps per contact in fast-charging applications. Smartphone OEMs in Guangdong province specify these for 100W+ adapter interfaces, though thermal cycling durability constraints limit pitch miniaturization below 0.5 millimeters.
- Audio Connectors:3.5mm and 2.5mm jack formats retain niche presence in professional equipment and legacy industrial systems.
- Video Connectors:HDMI and DisplayPort interfaces serve monitor and television assembly with standardized mechanical footprints.
Data connectors retain volume leadership; power connectors hold the steepest expansion curve.
Application:
Cost tier differentiation separates consumer-grade specifications from automotive qualification burdens.
- Consumer Electronics:Smartphones, tablets, and wearables demand sub-0.03 millimeter pitch tolerances with 10,000+ mating cycle durability. Foxconn and Luxshare Precision in China's Guangdong province anchor assembly demand, compressing supplier margins through consolidated procurement panels.
- Automotive Electronics:Infotainment modules and ADAS sensor clusters require AEC-Q101 temperature validation across -40°C to 125°C ranges. Germany's KBA and Japan's METI coordinate divergent vibration test protocols, extending supplier qualification timelines to 18-24 months.
- Telecommunications:Base station and router equipment prioritize electromagnetic shielding performance in high-density backplane configurations.
- Industrial Equipment:Factory automation systems specify IP67+ sealing ratings for connector housings in contaminated environments.
Consumer electronics retains volume leadership; automotive electronics holds the steepest expansion curve.
Technology:
Application context determines whether copper-based or photonic transmission architectures capture design wins.
- USB:Type-C reversible interfaces with 24-pin configurations consolidate charging and data protocols across device categories. The EU's common charger mandate eliminates proprietary fragmentation, standardizing high-speed differential pair demand across laptop and tablet OEM portfolios.
- HDMI:19-pin high-definition multimedia interfaces support uncompressed video streams up to 48 Gbps in display applications.
- Fiber Optic:MPO and MTP ferrule assemblies enable 400 Gbps+ backhaul in hyperscale data centers, though material costs constrain adoption outside enterprise infrastructure.
- Bluetooth:Wireless protocols reduce physical connector counts in peripheral accessories, displacing low-speed wired alternatives in audio and input devices.
USB retains volume leadership; fiber optic holds the steepest expansion curve.
End User:
Customer type segmentation separates captive production demand from distributed resale channels.
- OEMs:Apple, Samsung, and Dell specify custom connector geometries with exclusive tooling investments, locking suppliers into multi-year volume commitments. Direct relationships with Guangdong-based assembly partners enable co-development of 0.025 millimeter pitch prototypes.
- Manufacturers:Contract electronics assemblers in Vietnam and India procure standard JEDEC-compliant sockets through authorized distributors, prioritizing inventory availability over technical customization.
- Distributors:Arrow Electronics and Avnet maintain buffer stock for MRO replacement demand in industrial and automotive aftermarket channels.
- Retailers:Consumer-facing channels supply cable and adapter replacements through e-commerce platforms and electronics specialty stores.
OEMs retain volume leadership; manufacturers hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Guangdong province concentrates over half of high-volume precision socket capacity, with Foxconn and Luxshare Precision anchoring supply chains that feed global OEM assembly networks. This geographic clustering creates vulnerability to regional logistics disruptions while simultaneously driving regulatory harmonization around China's GB standards and the EU RoHS directive.
China
Guangdong province hosts Foxconn and Luxshare Precision facilities that dominate precision connector stamping and plating for global smartphone OEMs. SAMR enforces GB standards for interoperability and materials safety across connector portfolios. Shenzhen and Dongguan industrial clusters specialize in 0.025 millimeter pitch prototypes co-developed with assembly partners.
Japan
Camera module miniaturization for smartphone OEMs drives demand for sub-0.03 millimeter pitch connectors with 10,000+ mating cycle durability. METI coordinates JIS standards that shape dimensional tolerances for automotive-grade precision connectors exported throughout East Asian supply chains. Hirose Electric anchors specialized expertise in Nagoya and Tokyo manufacturing corridors.
South Korea
5G mmWave antenna module production accelerates laser direct structuring adoption for antenna-to-connector integration in smartphone midframes. National R&D programs support three-dimensional circuit patterning on molded interconnect devices. Seoul and Suwon industrial complexes host device OEMs collapsing traditional connector-FPC-PCB stacks into single-component solutions.
Germany
Automotive infotainment and ADAS module proliferation extends precision interconnect demand beyond consumer electronics into temperature-validated applications. KBA coordinates vibration test protocols that extend supplier qualification timelines to 18-24 months. Bavaria and Baden-Württemberg host automotive electronics clusters specifying AEC-Q101 validated connectors across -40°C to 125°C ranges.
India
PLI scheme incentives for mobile phone assembly attract connector suppliers to establish localized stamping and plating operations. BIS certification requirements shape materials qualification timelines for lead-free alloy portfolios. Tamil Nadu and Uttar Pradesh emerging manufacturing corridors concentrate new capacity investments from contract electronics assemblers.
3C Electronics Precision Connectors Market Competitive Landscape
Vertically integrated assemblers and specialized component suppliers split the market into distinct capability tiers. Foxconn and Luxshare Precision leverage captive demand from Greater China assembly relationships, while TE Connectivity and Amphenol sustain global repair networks for aftermarket service revenue. Three archetypes dominate: assembly-integrated manufacturers with in-house connector production, independent precision specialists with plating expertise, and diversified interconnect conglomerates with multi-industry portfolios. Competitive dynamics center on consolidated vendor qualification panels at major OEMs and geographic expansion into India electronics manufacturing corridors.
Within the assembly-integrated tier, Foxconn and Luxshare Precision occupy positions that exemplify backward integration into precision socket and cable assembly pairings. TE Connectivity represents the diversified conglomerate archetype with global service network scale. Hirose Electric sits within the specialized miniaturization tier, anchoring expertise for camera module applications in Japanese supply chains.
| Leading Market Players |
|---|
| TE Connectivity |
| Amphenol |
| Hirose Electric |
| Molex Incorporated |
| Foxconn |
| Luxshare Precision |
| JAE |
| LINKCONN |
| JST |
| Others |
Pricing and Supply Chain Analysis
Guangdong province's concentration of precision stamping and plating capacity concentrates margin capture among vertically integrated assemblers, while mid-tier suppliers face cost compression from palladium-nickel alloy volatility and OEM procurement consolidation.
Pricing Analysis
EU RoHS and REACH directives dictate the pricing tier structure across European-bound connector portfolios, separating AEC-Q101 automotive-validated products from consumer-grade alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification burden, plating specification, and volume commitment scale. Cost compression in mid-tier consumer electronics runs through consolidated vendor panels at major OEMs. Contract manufacturers in Vietnam and India exhibit highest price sensitivity; automotive Tier 1 suppliers accept premium positioning for temperature-validated reliability.
Supply Chain Analysis
Tariff exposure between China and key export markets dominates supply chain risk calculus for precision connector suppliers. Production gravity centers on China's Guangdong province, South Korea's Seoul-Suwon corridor, and Japan's Nagoya-Tokyo manufacturing belts. Raw material dependencies include copper alloy feedstock, gold and palladium electroplating salts, and high-temperature thermoplastic resins. Single-source vulnerability concentrates in sub-micron stamping die fabrication, where qualified toolmakers remain scarce. Distribution runs through captive assembly relationships for OEM-direct volume, with authorized distributors serving contract manufacturer and aftermarket replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among three to four qualified sources per connector category at major OEMs, compressing supplier margins while rewarding vertically integrated manufacturers with captive plating and cable assembly capability.
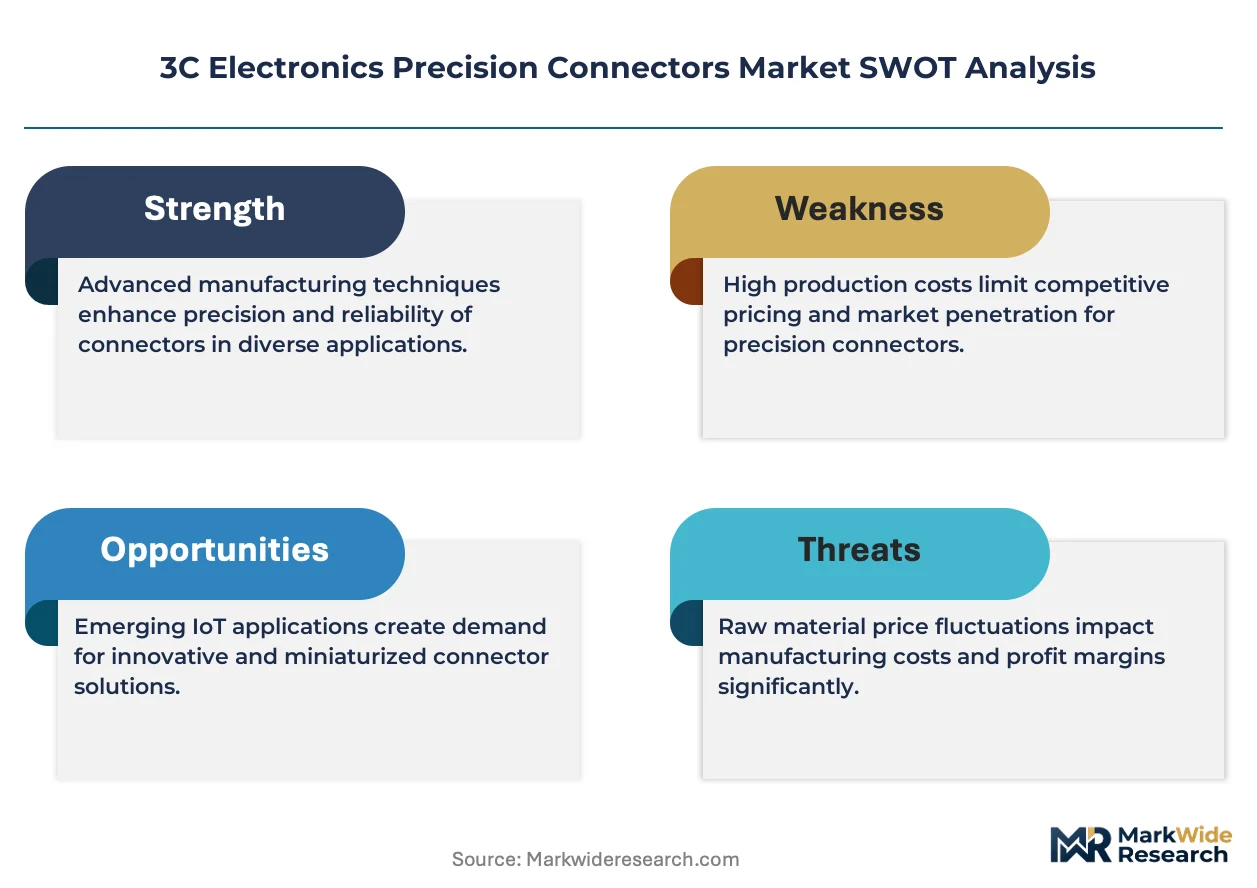
For Market Incumbents: Pre-empt margin erosion by securing long-term offtake agreements for palladium-nickel alloy inputs and accelerating laser-welded contact assembly adoption to reduce gold plating thickness. Backward integration into sub-micron stamping die production addresses the toolmaker shortage constraining 0.025 millimeter pitch capacity expansion. Defensive positioning against fiber optic substitution in data connectors requires sustained R&D investment in copper-based differential pair architectures above 56 Gbps. For New Entrants and Emerging Players: Build out localized stamping and plating operations in India's Tamil Nadu and Uttar Pradesh corridors to capture PLI scheme-linked mobile phone assembly demand. Medical wearable biometric monitoring patches represent the most penetrable white-space application, requiring ultra-low-profile flex-to-board connectors beyond traditional 3C specifications. Go-to-market positioning should emphasize RoHS-certified lead-free and halogen-free alloy portfolios as ECHA restrictions expand. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision metalworking specialists possessing captive plating expertise but lacking OEM-direct assembly relationships. Long-term viability in this market hinges on qualification timeline compression and geographic diversification beyond Guangdong production concentration. Watch for India electronics manufacturing corridor maturation as the signal indicating shift in regional supply gravity.| Strategic Initiative | Industry Significance |
|---|---|
| Laser-Welded Contact Assembly Adoption | MEE enforcement of energy efficiency standards in Guangdong accelerates gold plating reduction. |
| Sub-Micron Stamping Die Capability Buildout | Toolmaker scarcity constrains 0.025 millimeter pitch production for smartphone miniaturization cycles. |
| India Manufacturing Footprint Establishment | PLI scheme incentives attract connector suppliers to Tamil Nadu and Uttar Pradesh assembly corridors. |
| AEC-Q101 Automotive Qualification Investment | KBA and METI protocols extend validation timelines for infotainment and ADAS module suppliers. |
| RoHS-Certified Alloy Portfolio Expansion | ECHA SVHC list expansion creates competitive advantage for lead-free and halogen-free material roadmaps. |
Research Methodology
A standing panel of connector procurement executives at smartphone OEMs, plating process engineers at precision metalworking facilities, automotive Tier 1 supplier quality directors, and contract electronics assembler supply chain managers provided ongoing calibration across primary fieldwork. Secondary validation drew from SAMR GB standard filings, EU ECHA SVHC candidate list updates, JIS automotive connector specifications, and SEC 10-K disclosures from listed interconnect manufacturers. Bottom-up unit economics modeling triangulated against top-down OEM bill-of-materials analysis.
Scenario-bracketing framed low, base, and high cases across the projection horizon without year-specific anchoring. Segmentation dimensions modeled include product type, application environment, technology protocol, and end-user procurement channel. CAGRs derived from connector content-per-device trajectories in smartphone refresh cycles, automotive electronics penetration curves, and regional manufacturing shift assumptions. Industry-specific forecast inputs captured USB-C harmonization mandates, dual carbon goal enforcement intensity, and India PLI scheme uptake rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by fiber optic interconnect specialists or India-based contract manufacturers would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Connectors
Connector for PV System Market
Connectors
Wire-To-Board Connector Market
Connectors
Hazardous Location Connectors Market
Connectors
Underwater Connectors Market
Connectors
Mexico Connector Market
Connectors
High-Reliability Connectors Market
Connectors
Connector Adapter Kits Market
Connectors
DIN Connectors Market
Connectors
Middle East Connector Market
Connectors
Pin Retainer Market
Connectors
Power Connector Market
Connectors
Line Clamp Market
Connectors
Australia Connector Market
Connectors
Heavy-Duty Connector Market
Connectors
Global Automotive Connector Market
Connectors
Asia-Pacific Connector Market