
 Magnetic Connector Market | 2026-2036
Magnetic Connector Market Size, Share, and Industry Trends Forecast 2026-2036
Magnetic Connector Market Foresight
OEM direct procurement channels are reconfiguring as device manufacturers consolidate supplier bases for magnetic connector modules. TE Connectivity leverages its vertical integration in precision stamping and plating to sustain cost leadership in high-volume consumer programs. Amphenol Corporation anchors its position through specialized magnetic latching designs for ruggedized industrial applications. Rosenberger competes in automotive-grade magnetic connectors where vibration resistance and IP sealing differentiate performance tiers.
A magnetic connector employs precisely aligned permanent magnets or magnetically permeable materials to enable self-aligning, detachable electrical interfaces without mechanical latching mechanisms. These devices typically incorporate neodymium-iron-boron magnet arrays paired with gold-plated pogo pin or spring-contact terminals, achieving mating cycles exceeding 10,000 operations while maintaining contact resistance below 50 milliohms. Magnetic latching technology dominates consumer charging applications where user convenience drives specification, while magnetic induction architectures command premium positioning in medical device sterilization environments where galvanic isolation is mandatory. The charging solutions application segment concentrates volume demand from smartphone and laptop OEMs, whereas data transfer configurations sustain higher average selling prices in industrial automation networks requiring EMI shielding compliance.
FCC Part 15 emissions standards in the United States, the EU's RoHS substance restrictions under ECHA oversight, and China's GB 4943.1 safety mandates collectively shape product certification requirements and material selection for magnetic connector suppliers seeking multi-region market access. Japan's METI technical standards for consumer electronics further constrain thermal and magnetic field exposure parameters in compact device designs. Stakeholders must monitor evolving automotive functional safety standards as magnetic connectors penetrate electric vehicle charging and battery management architectures.
Market Dynamics
Magnetic connector procurement is consolidating around integrated module suppliers as OEMs reduce vendor counts and shift technical compliance burdens upstream. This supplier-base compression is restructuring competitive relationships across consumer electronics, automotive, and medical device verticals.
Growth Catalysts
- Wearable Device Proliferation:Smartwatch and hearable manufacturers are specifying magnetic connectors for water-resistant charging interfaces, creating volume pull for compact, high-cycle mating systems.
- EU RoHS Directives:ECHA substance restrictions are accelerating lead-free plating process adoption, favoring suppliers with certified green manufacturing lines for European market access.
- Shenzhen-Dongguan Cluster Concentration:East Asian manufacturing ecosystems enable rapid prototype-to-production cycles for magnetic connector assemblies serving global electronics brands.
Market Restraints
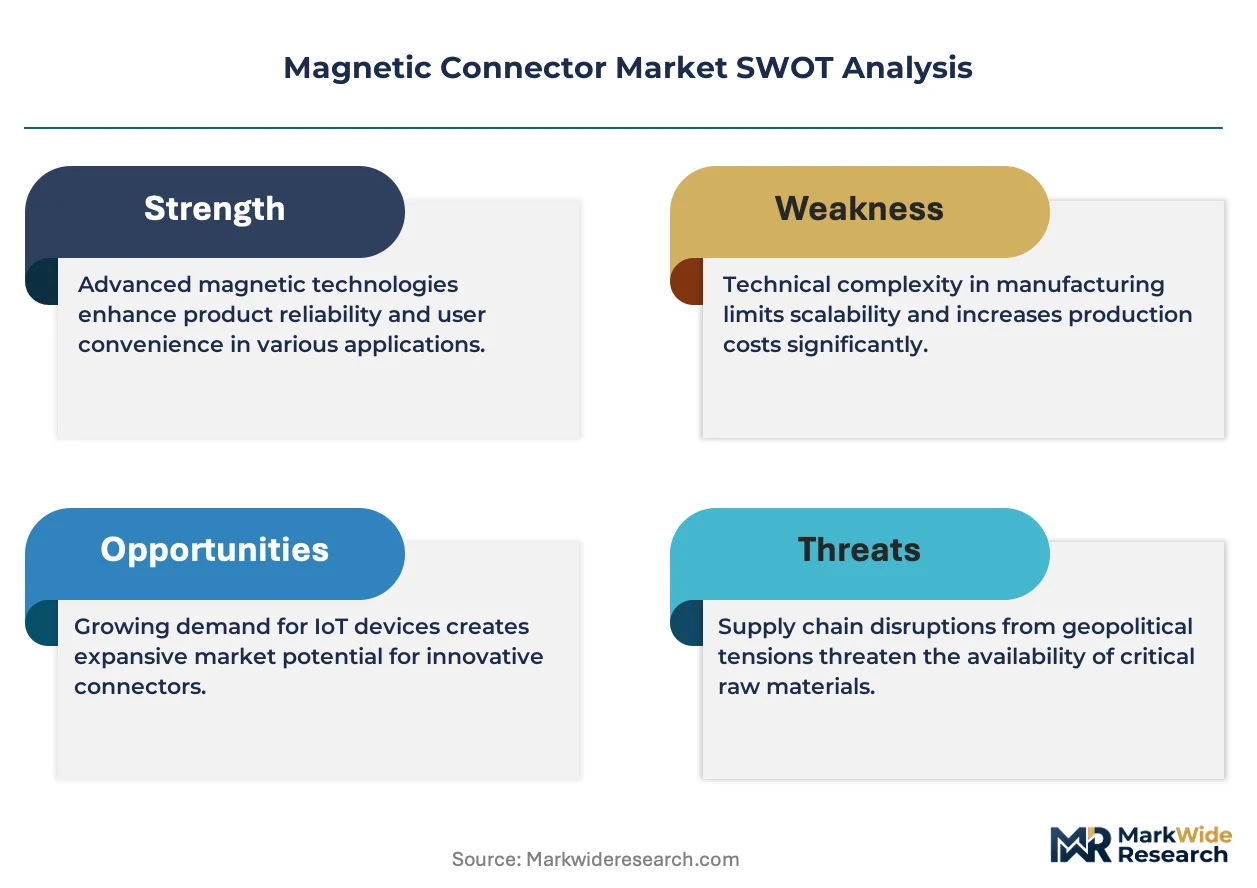
- Neodymium Price Volatility:Rare earth magnet input costs fluctuate with Chinese export quota policies, compressing margin predictability for connector assemblers.
- Single-Source Magnet Supply:Concentrated rare earth processing capacity in China creates geographic supply risk that Western OEMs cannot easily diversify.
- USB-C Mechanical Latching:Standardized connector formats with positive retention mechanisms limit magnetic connector penetration in cost-sensitive smartphone segments.
Strategic Opportunities
- Electric Vehicle Charging:Magnetic alignment systems for autonomous charging robots represent an emerging application with automotive-grade reliability requirements.
- India PLI Scheme:Production-linked incentives for electronics manufacturing are attracting magnetic connector assembly investments to serve domestic smartphone production.
- WPT-Magnetic Hybrid Architectures:Convergence of wireless power transfer with magnetic mechanical alignment is opening medical sterilization equipment specifications.
Industry Challenges
- Precision Plating Talent Scarcity:Gold and palladium-nickel electroplating expertise for sub-50 milliohm contact resistance is concentrated among aging specialist workforces in Japan and Germany.
- Multi-Region Certification Timelines:Simultaneous FCC Part 15, EU RoHS, and China GB 4943.1 compliance extends product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Magnetic Connector Market |
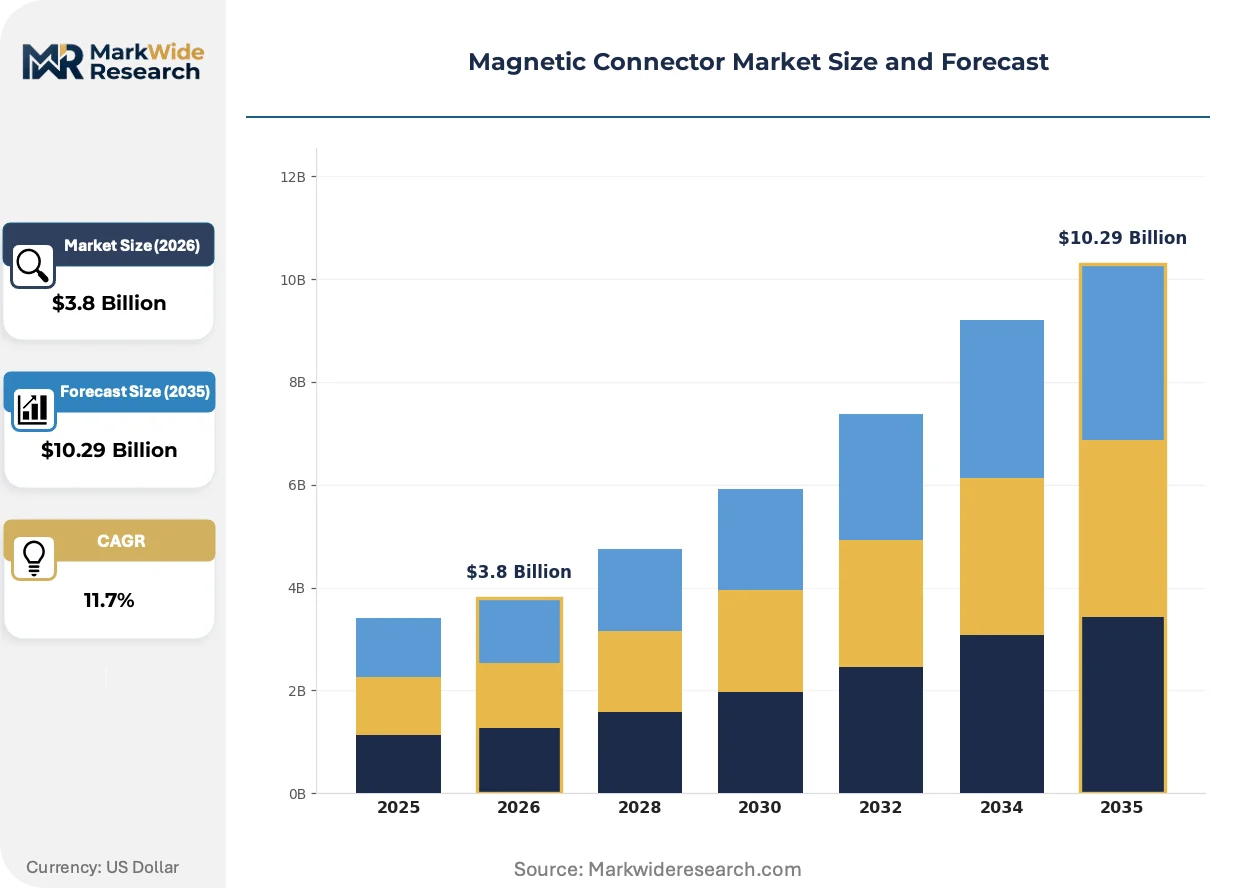
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.29 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Magnetic Plugs, Magnetic Sockets, Magnetic Adapters, Magnetic Cables Technology: Magnetic Latching, Magnetic Induction, Magnetic Attraction, Magnetic Coupling End User: Consumer Electronics, Automotive Industry, Industrial Equipment, Medical Devices Application: Charging Solutions, Data Transfer, Power Supply, Audio Connectivity |
| Companies Covered | TE Connectivity, Amphenol Corporation, Rosenberger, Molex, Yamaichi Electronics, Samtec, TT Electronics, JAE Electronics, Promax Pogo Pin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Magnetic Connector Market Shifts & Advancements
Magnetic connector technology is bifurcating between consumer convenience applications and mission-critical industrial deployments, with divergent performance specifications driving parallel innovation tracks. This dual-path evolution is fragmenting supplier capabilities and certification requirements.
Spring-loaded pogo pin architectures are migrating from consumer charging docks toward industrial automation networks requiring EMI shielding and vibration immunity. Automotive battery management system designers are piloting these contact technologies for maintenance-free diagnostic ports. The shift is compressing demand for traditional mechanical latch connectors in factory floor environments.
Japan's METI technical standards for magnetic field exposure in compact consumer devices are tightening thermal and flux density parameters. Connector suppliers must now validate SAR-compliant magnet arrays for wearable applications. Medical device manufacturers targeting Japanese distribution are redesigning magnetic latching mechanisms to satisfy these proximity safety mandates.
Direct OEM module procurement is displacing tiered distributor networks for high-volume magnetic connector programs. Electronics manufacturing services providers in Vietnam and Mexico are establishing captive sourcing relationships with Asian connector specialists. This channel restructuring is most visible in laptop and tablet supply chains where Dell, HP, and Lenovo procurement teams negotiate directly with Shenzhen-based module integrators.
Magnetic Connector Market Segmentation
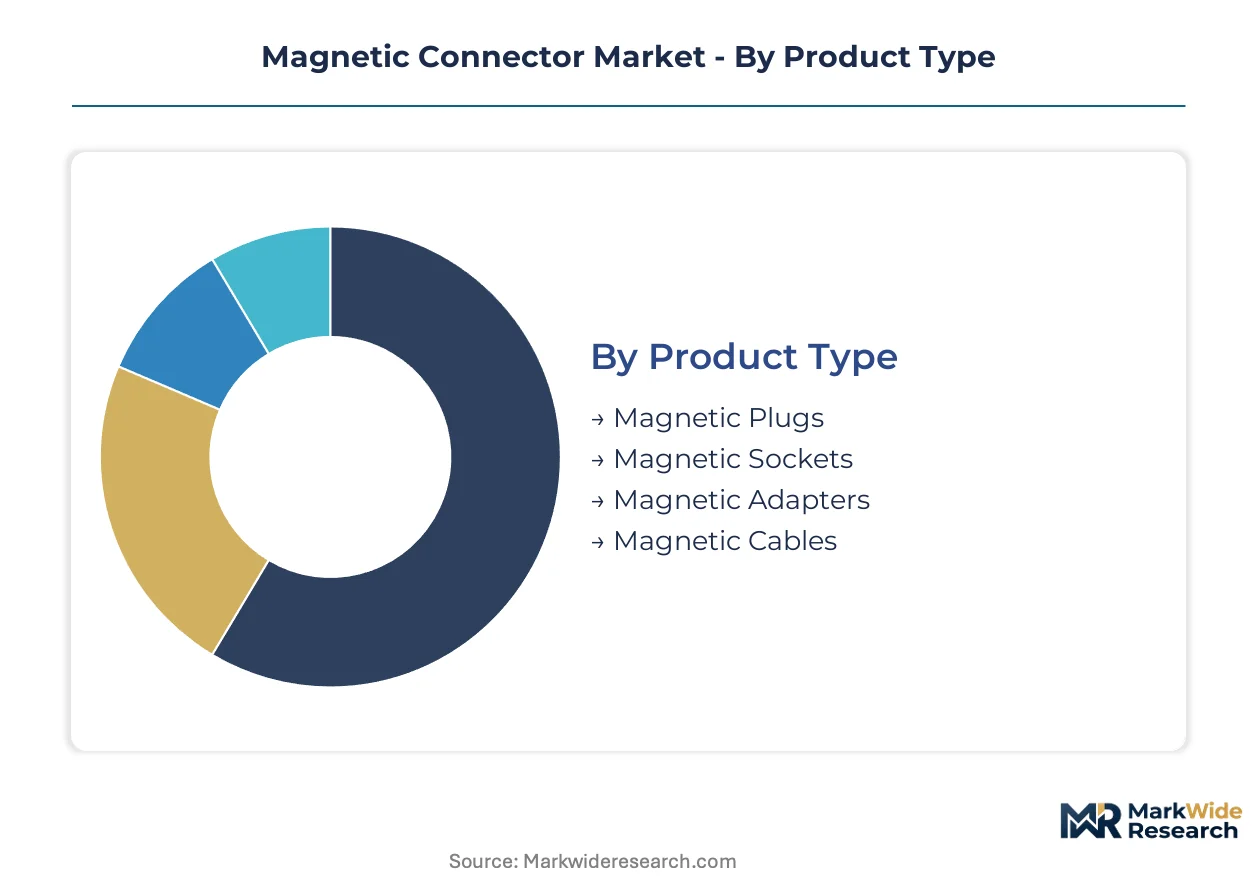
Magnetic connector procurement patterns diverge sharply across product architectures and end-use environments. Technical specifications for contact resistance, mating cycle durability, and IP sealing ratings create distinct commercial segments with non-overlapping supplier bases.
Product Type:
After-sales service intensity varies dramatically by product form factor, with field-replaceable units commanding higher technical support margins than integrated cable assemblies.
- Magnetic Plugs:Self-contained male interfaces incorporating neodymium magnet arrays and gold-plated contact pins for direct device integration. Smartphone OEMs in Shenzhen and Dongguan specify these for water-resistant charging ports, driven by consumer demand for seamless mating cycles exceeding 10,000 operations.
- Magnetic Sockets:Female receptacles with magnetically permeable housings designed to receive complementary plug interfaces. Laptop manufacturers concentrate procurement in Taiwan and South Korea, constrained by FCC Part 15 emissions certification timelines for multi-region product launches.
- Magnetic Adapters:Bridge components enabling legacy port compatibility with magnetic mating systems.
- Magnetic Cables:Tethered assemblies integrating both plug terminations with flexible conductor bundles.
By volume, Magnetic Cables leads. By growth pace, Magnetic Adapters is climbing the fastest.
Technology:
Cost tier stratification separates consumer-grade magnetic attraction systems from medical-grade induction architectures requiring galvanic isolation.
- Magnetic Latching:Permanent magnet arrays providing mechanical retention without electrical induction, dominant in consumer charging docks. Wearable manufacturers in Japan specify METI-compliant flux density limits for compact smartwatch applications.
- Magnetic Induction:Coupled coil architectures enabling wireless power transfer through magnetic field coupling. Medical sterilization equipment OEMs in Germany specify these for isolated power delivery in surgical environments.
- Magnetic Attraction:Basic polarity-aligned magnet systems for simple mechanical alignment.
- Magnetic Coupling:Precision-tuned field geometries for industrial automation networks.
Magnetic Latching captures the highest shipment volumes. Magnetic Induction commands the steepest expansion trajectory in premium medical applications.
End User:
Application maturity dictates supplier qualification requirements, with automotive functional safety standards creating the most stringent certification barriers.
- Consumer Electronics:Volume-driven segment encompassing smartphones, laptops, tablets, and wearables. Dongguan manufacturing clusters supply magnetic connectors for Apple, Samsung, and Xiaomi programs under compressed 12-week design-to-production cycles.
- Automotive Industry:Electric vehicle charging and battery management applications requiring vibration resistance and IP6K9K sealing. German KBA and US NHTSA safety mandates constrain supplier selection to Tier 1-certified manufacturers.
- Industrial Equipment:Factory automation and process control networks.
- Medical Devices:Sterilizable diagnostic and therapeutic equipment.
Consumer Electronics dominates absolute volume. Medical Devices is gaining share fastest amid sterilization-grade specification expansion.
Application:
Customer type bifurcation separates high-volume charging commodity procurement from low-volume, high-margin data transfer configurations.
- Charging Solutions:Power delivery interfaces for battery-powered devices, representing the volume anchor of magnetic connector demand. USB-C mechanical latching competition constrains pricing power in smartphone segments.
- Data Transfer:Signal integrity-focused configurations with EMI shielding for industrial and automotive networks. German automotive OEMs specify these for Ethernet backbone connections in autonomous vehicle architectures.
- Power Supply:AC-DC adapter interfaces and distributed power distribution.
- Audio Connectivity:Magnetic retention for headphone and hearing aid applications.
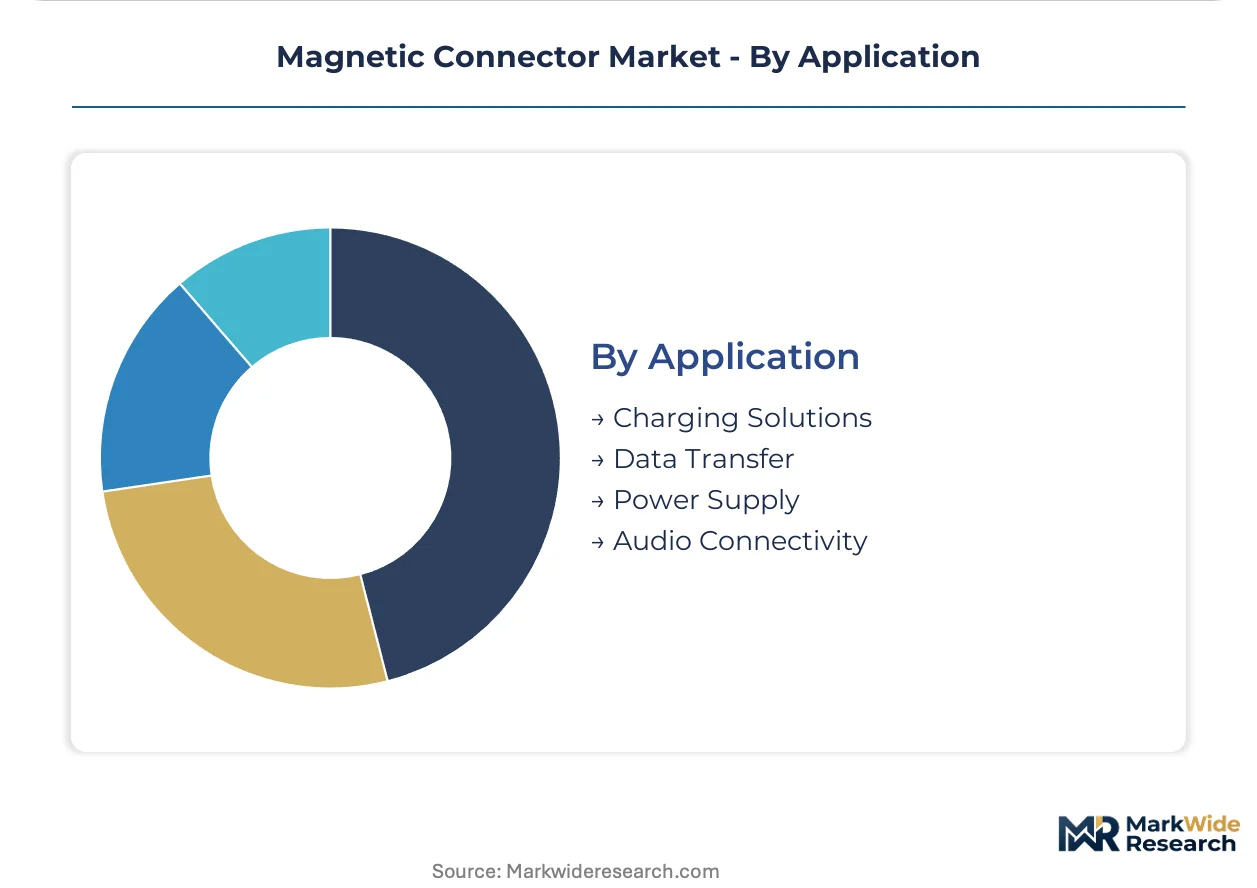
Charging Solutions leads by unit volume. Data Transfer exhibits the most rapid specification expansion in industrial automation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Pearl River Delta's container throughput infrastructure underwrites China's dominance in magnetic connector production, while Japan's METI technical standards and Germany's automotive certification regimes shape demand specifications across three continents.
China
Shenzhen and Dongguan manufacturing clusters supply magnetic connectors for Apple, Samsung, and Xiaomi wearable programs under compressed 12-week design cycles. MIIT's GB 4943.1 safety mandates constrain thermal and magnetic field exposure parameters for compact device exports. The Dongguan precision electronics corridor hosts over 200 connector assembly facilities serving global OEM direct procurement channels.
United States
Electric vehicle charging infrastructure deployment and medical device sterilization equipment specifications drive magnetic connector demand in automotive and healthcare verticals. FCC Part 15 emissions standards govern RF interference compliance for consumer electronics distribution. California's clean energy procurement policies accelerate magnetic alignment system adoption for autonomous charging robot pilots.
Germany
Automotive OEMs specify magnetic connectors for battery management diagnostic ports and Ethernet backbone connections in autonomous vehicle architectures. KBA functional safety mandates constrain supplier qualification to Tier 1-certified manufacturers with vibration resistance and IP6K9K sealing validation. Bavaria's industrial automation equipment manufacturers source EMI-shielded magnetic data transfer configurations for factory floor networks.
Japan
Smartwatch and hearable manufacturers specify METI-compliant magnetic latching systems with validated SAR exposure limits for compact wearable applications. METI technical standards for magnetic field exposure tighten flux density parameters below thresholds acceptable in other markets. Tokyo and Osaka electronics clusters concentrate precision plating expertise for sub-50 milliohm contact resistance requirements.
South Korea
Laptop manufacturers concentrate magnetic socket procurement for multi-region product launches constrained by FCC Part 15 certification timelines. MFDS medical device regulations shape sterilizable magnetic connector specifications for diagnostic equipment exports. Seoul's semiconductor-adjacent manufacturing ecosystem enables rapid prototyping of neodymium magnet arrays paired with gold-plated terminals.
Magnetic Connector Market Competitive Landscape
On the supply side, the industry is consolidating around integrated module suppliers as OEMs compress vendor counts and shift technical compliance burdens upstream. Three strategic archetypes dominate: precision stamping and plating specialists with captive magnet sourcing, ruggedized industrial application designers with IP sealing expertise, and automotive-grade reliability manufacturers with functional safety certification. Competitive moves center on backward integration into rare earth magnet supply chains and geographic expansion to India PLI scheme manufacturing zones.
Among established connector manufacturers, TE Connectivity exemplifies the precision stamping archetype with upstream control over plating processes, while Amphenol Corporation occupies a position within the ruggedized industrial tier. Rosenberger anchors the automotive-grade segment where vibration resistance and IP sealing differentiate performance tiers. These three companies represent distinct competitive vectors rather than overlapping market positions, with each sitting within non-intersecting certification and specification domains.
| Leading Market Players |
|---|
| TE Connectivity |
| Amphenol Corporation |
| Rosenberger |
| Molex |
| Yamaichi Electronics |
| Samtec |
| TT Electronics |
| JAE Electronics |
| Promax Pogo Pin |
| Others |
Supply & Pricing Matrix
The Dongguan precision electronics corridor concentrates over 200 connector assembly facilities serving global OEM direct procurement channels, compressing pricing power for commodity-grade magnetic plugs while premium medical-grade induction architectures sustain margin premiums through sterilization-grade certification barriers.
Pricing Analysis
Three-tier pricing structure across automotive-grade, industrial-grade, and consumer-grade levels separates TE Connectivity's precision-stamped high-volume programs from Amphenol's ruggedized IP-sealed configurations and Shenzhen-based commodity assemblers. Price differentiation hinges on FCC Part 15 emissions certification tier and gold-plating thickness for sub-50 milliohm contact resistance. Cost compression in smartphone charging segments intensifies because USB-C mechanical latching constrains magnetic connector specification share. Automotive OEMs exhibit lowest price sensitivity due to KBA functional safety mandates, while Dongguan-sourced consumer electronics buyers drive aggressive annual cost-down negotiations.
Supply Chain Analysis
Neodymium-iron-boron magnet feedstock draws from Chinese rare earth processing capacity concentrated in Inner Mongolia and Jiangxi provinces, with secondary refining dependencies in Japan and Germany for high-purity magnet alloys. Raw material inputs hinge on neodymium price volatility, gold bullion for plating baths, and palladium-nickel alloy for corrosion-resistant contact surfaces. Single-source magnet supply risk concentrates geographic vulnerability that Western OEMs cannot easily diversify without 18-24 month qualification cycles. Distribution runs through direct OEM module procurement channels displacing tiered distributor networks, with Dell, HP, and Lenovo procurement teams negotiating directly with Shenzhen-based integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Magnetic connector procurement is consolidating around integrated module suppliers as Apple, Samsung, and Xiaomi compress vendor counts and shift GB 4943.1 and RoHS compliance burdens upstream, amplifying buyer leverage over fragmented plating specialists.
For Market Incumbents: Insulate margin position through backward integration into captive neodymium magnet sourcing and precision stamping capacity in Dongguan satellite facilities. TE Connectivity's vertical control over gold-plating processes exemplifies the defensive posture required against USB-C mechanical latching substitution in smartphone segments. Certification investment in automotive-grade IP6K9K sealing and KBA functional safety validation creates switching costs that lock in German OEM diagnostic port specifications.
For New Entrants and Emerging Players: Pursue electric vehicle autonomous charging robot alignment systems and India PLI scheme manufacturing zones as white-space targets where incumbent certification footprints remain underdeveloped. Medical sterilization equipment in Germany offers the most penetrable premium segment given galvanic isolation requirements that exclude commodity suppliers. A go-to-market angle anchored in WPT-magnetic hybrid architectures for surgical environments bypasses established consumer electronics procurement channels.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because supplier-base compression is restructuring competitive relationships across consumer, automotive, and medical verticals. Acquisition targets should emphasize precision plating expertise concentrated among aging specialist workforces in Japan and Germany. The signal to watch is India PLI scheme electronics manufacturing investments attracting magnetic connector assembly capacity away from Shenzhen-Dongguan cluster dominance.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Magnet Supply | Captive neodymium sourcing insulates margin from Chinese export quota volatility. |
| Automotive Functional Safety Certification | KBA validation locks in electric vehicle battery management diagnostic port specifications. |
| India PLI Scheme Manufacturing Expansion | Production-linked incentives attract assembly investments serving domestic smartphone OEMs. |
| WPT-Magnetic Hybrid Architecture Development | Wireless power convergence opens medical sterilization equipment specifications in Germany. |
| Precision Plating Talent Acquisition | Gold and palladium-nickel electroplating expertise scarcity concentrates in Japan and Germany. |
Research Methodology
The analysis maps magnetic latching, magnetic induction, magnetic attraction, and magnetic coupling technology segments, each validated through connector procurement managers at Dell, HP, and Lenovo, plating process engineers at Japanese precision metalwork facilities, and regulatory affairs specialists navigating FCC Part 15 and ECHA RoHS compliance. Primary interviews with OEM direct sourcing teams and secondary validation against MIIT GB standard filings, SEC 10-K disclosures from TE Connectivity and Amphenol, and customs trade data for neodymium magnet imports combine through bottom-up and top-down triangulation.
Assumptions held fixed include sustained Chinese rare earth export quota policies, continued EU RoHS substance restriction enforcement, and stable METI magnetic field exposure standards for wearable applications, while neodymium price trajectories and India PLI scheme uptake rates varied across sensitivity scenarios. Segmentation dimensions modeled encompass product architecture, technology tier, end-use vertical, and application function across the projection horizon. CAGRs derive from shipment volume trajectories weighted by average selling price evolution in charging versus data transfer configurations, with electric vehicle charging infrastructure deployment and medical sterilization-grade specification expansion as key demand drivers.
Macroeconomic conditions sit as an overlay; deviation in rare earth commodity prices, automotive production cycles, or electronics manufacturing relocation patterns would shift the trajectory. Forecasts reflect these documented assumptions with acknowledged sensitivity to regulatory timeline acceleration in multi-region certification processes. Cross-checking against IHS Markit electronics production data and hospital procurement database trends for sterilizable connectors is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Connectors
China Connector Market
Connectors
Power Connector Market
Connectors
Middle East and Africa Hazardous Location Connectors Market
Connectors
Pin Retainer Market
Connectors
Global Automotive Connector Market
Connectors
Latin America Connector Market
Connectors
Global Wired Interface Market
Connectors
Heavy-Duty Connector Market
Connectors
Connector and Terminal Systems for Harsh Environment Wiring Market
Connectors
Micro-Miniature Co-Axial Adapter Market
Connectors
Global Fiber Optic Connectors Market
Connectors
IC Socket Market
Connectors
AS-Interface Market
Connectors
Circular Waterproof Connector Market
Connectors
Terminal Pins Market
Connectors
Space Grade Connectors Market