
 Japan Connector Market | 2026-2036
Japan Connector Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Connector Market Insights
Automotive-grade connector specifications is bifurcating the competitive landscape into safety-critical and standard interconnect tiers. Yazaki dominates vehicle wire harness integration with captive terminal and connector production. Hirose Electric specializes in high-density board-to-board solutions for precision electronics. JAE anchors aerospace and defense connector supply through JIS-certified manufacturing lines.
Connectors are electromechanical devices that establish removable interfaces between conductors, with contact pitches ranging from sub-millimeter micro-coaxial formats to heavy-duty circular shells rated for hundreds of amperes. Their primary purpose is to enable modular assembly, field serviceability, and signal integrity across power, data, and RF transmission paths. Board-to-board configurations lead in unit volume within consumer electronics and telecommunications equipment, while circular formats command premium positioning in aerospace systems and industrial automation where environmental sealing and vibration resistance justify higher price points. Surface mount technology competes aggressively on assembly cost for high-volume electronics, whereas press fit technology sustains margin pools in automotive and telecom infrastructure where solder-free reliability reduces field failure rates.
METI enforces JIS standards for industrial and automotive connector interoperability, while PMDA oversight extends to medical device connectors where biocompatibility and sterilization resistance are mandatory. The EU AI Act and CSRD, though extraterritorial, shape export-bound Japanese connector portfolios as European OEMs demand supply chain documentation and recyclability compliance. Stakeholders must monitor how Japan's semiconductor equipment subsidies redirect connector procurement toward domestic fab construction and advanced packaging lines.
Market Dynamics
Electric vehicle powertrain electrification is restructuring procurement volumes across Japanese automotive OEMs, with high-voltage interconnect architectures demanding new connector specifications and supplier qualification pathways.
Growth Catalysts
- Semiconductor Localization Mandates:METI's domestic fab construction subsidies are redirecting connector procurement toward local packaging lines and advanced substrate facilities.
- Vehicle Electrification Standards:Automotive-grade high-voltage interconnect demand from Toyota, Nissan, and Honda is expanding procurement for 800V architectures.
- Kanto Manufacturing Density:Electronics clusters in Tokyo, Kanagawa, and Saitama prefectures concentrate procurement volumes and enable just-in-time supplier integration.
Market Restraints
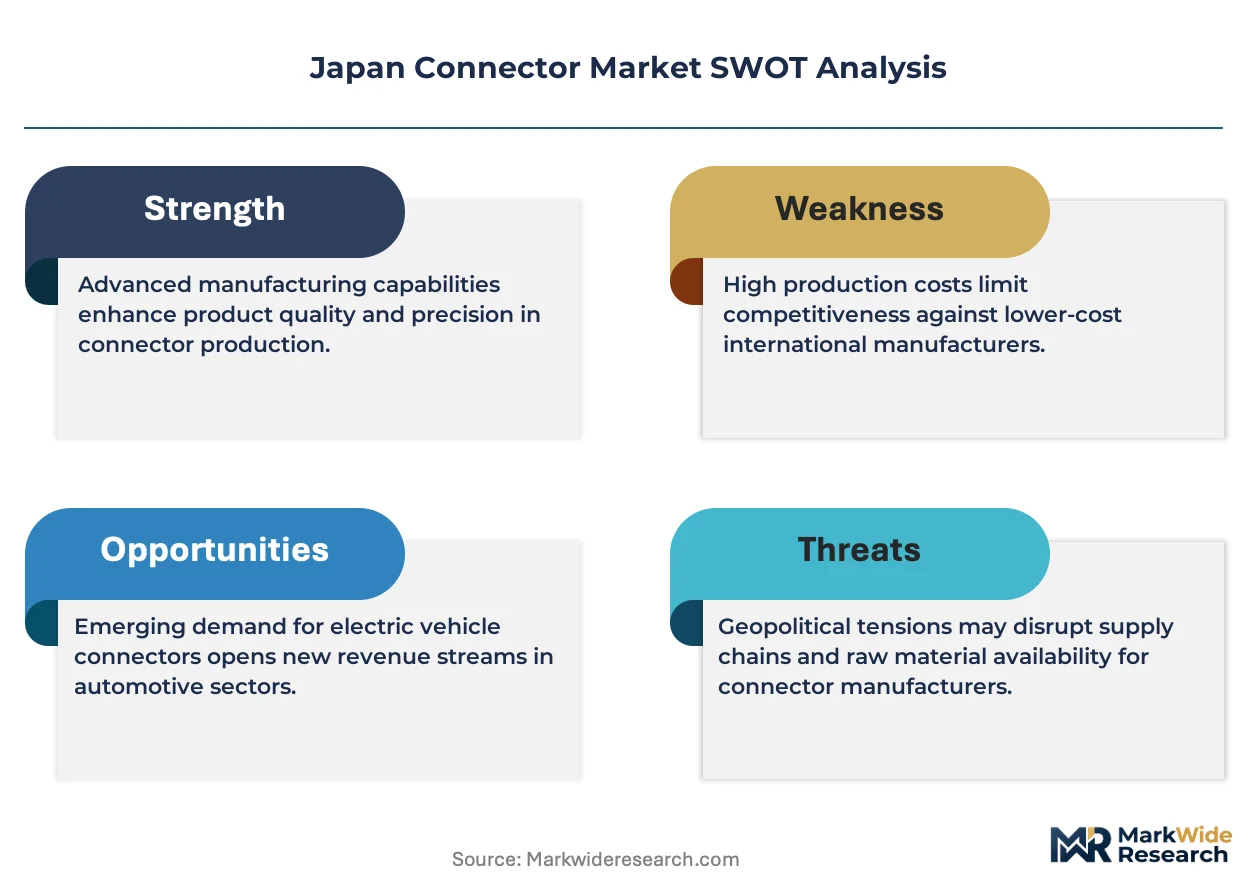
- Copper and Rare Earth Volatility:Terminal plating materials and magnet wire inputs face price swings that compress margin predictability for mid-tier suppliers.
- Single-Source Automotive Dependency:Tier-1 wire harness consolidation around Yazaki's captive connector production limits independent component vendor access.
- Miniaturization Physics Limits:Sub-millimeter pitch board-to-board formats encounter signal integrity degradation that constrains further density gains.
Strategic Opportunities
- Kyushu Semiconductor Corridor:Kumamoto and Miyazaki prefectures host new TSMC and Kioxia fabs requiring localized connector supply chains.
- Medical Device Convergence:PMDA's streamlined biocompatibility pathways for disposable surgical connectors open adjacent revenue pools.
- Wire-to-Board Hybrid Architectures:Press-fit and compliant pin technologies are converging with traditional crimp methods in automotive power distribution units.
Industry Challenges
- Automotive Qualification Timelines:AEC-Q100 and USCAR validation cycles extend 18-24 months, locking suppliers into pre-platform development commitments.
- Legacy Equipment Integration:Industrial automation retrofits demand backward-compatible connector footprints that constrain next-generation performance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Connector Market |
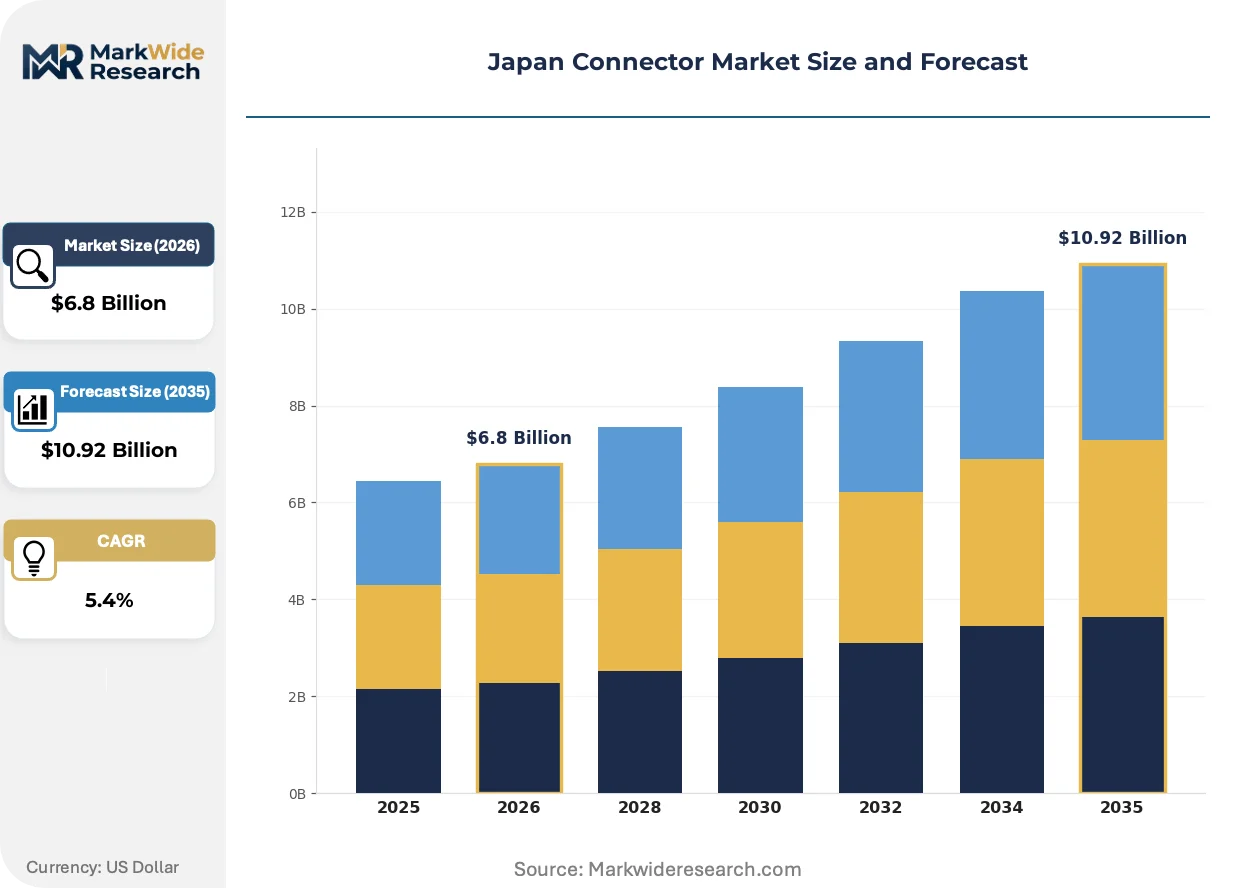
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Board-to-Board, Wire-to-Board, Coaxial, Circular, Rectangular Technology: Surface Mount, Through Hole, Press Fit, Wire Wrap, Crimp Application: Consumer Electronics, Telecommunications, Aerospace Systems, Renewable Energy, Industrial Automation End User: Electronic Device Manufacturers, Network Equipment Providers, Aircraft Fabricators, Solar Panel Suppliers, Factory Automation Companies |
| Companies Covered | Yazaki, JST (Japan Solderless Terminals), TE Connectivity, Molex, Sumitomo Electric, Amphenol, JAE (Japan Aviation Electronics), Aptiv, Hirose Electric, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Connector Market Trends and Innovations
Connector architectures are pivoting toward solderless assembly methods and modular standardization, driven by automotive reliability mandates and semiconductor packaging evolution.
Press-fit compliant pin technology is supplanting surface-mount solder joints in automotive powertrain and telecom base station applications. Tier-1 suppliers are adopting these interfaces for 48V mild-hybrid systems and 5G massive MIMO arrays. This transition is compressing field failure rates while elevating capital requirements for precision stamping and plating equipment.
METI's JIS C 5402 revisions for industrial connector interoperability are mandating unified mating interfaces across factory automation equipment. The standards body is enforcing compatibility testing that accelerates vendor switching but increases compliance documentation burdens. Automotive and robotics OEMs in Aichi and Osaka prefectures are consolidating supplier lists around certified platforms.
Japanese automotive OEMs are unbundling connector procurement from captive wire harness suppliers, creating direct component sourcing relationships. Tier-2 connector specialists now negotiate volume contracts with Nissan and Subaru engineering divisions. This disintermediation is most visible in Kanagawa and Tochigi prefectures where EV platform development centers operate.
Japan Connector Market Segmentation
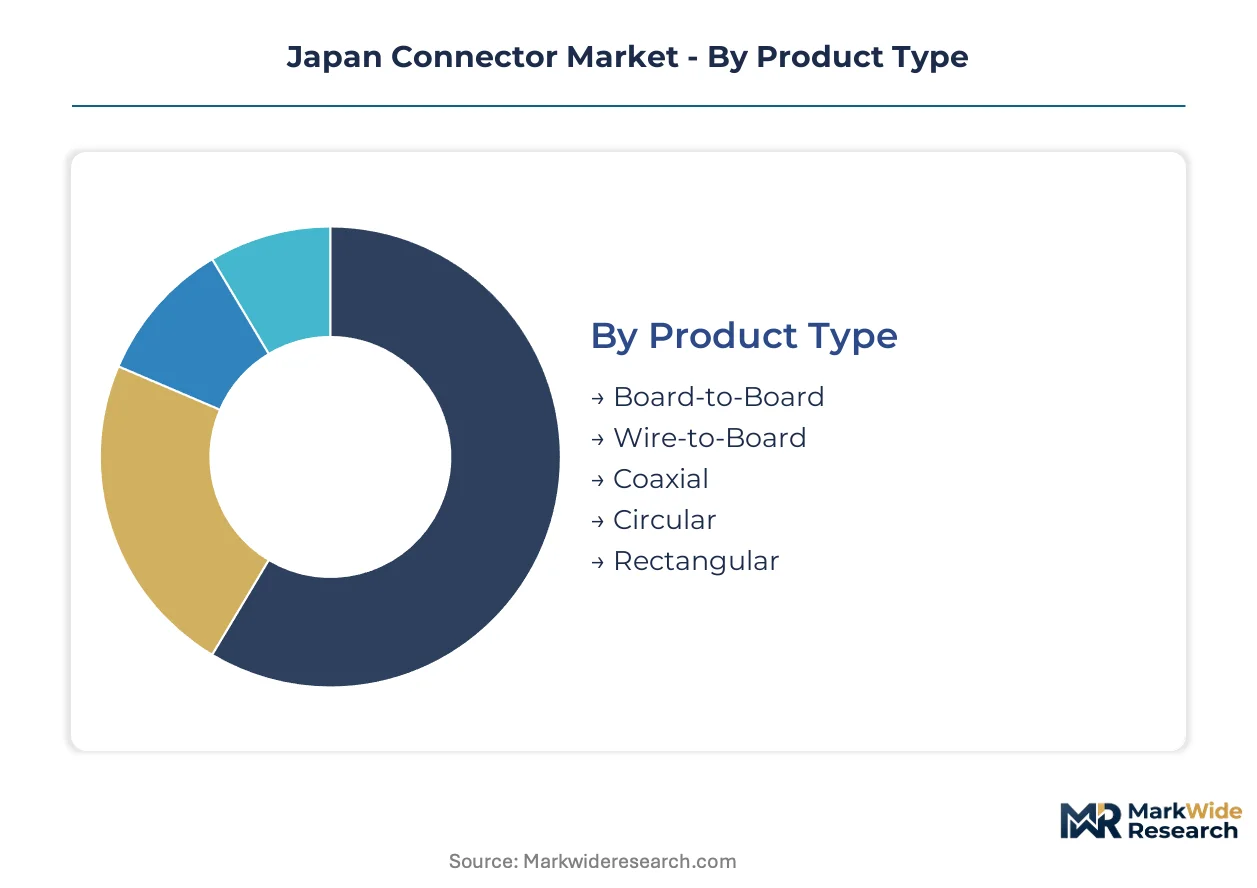
Segmentation in the Japan Connector Market reveals how METI's JIS standards and automotive electrification mandates reshape procurement patterns across product architectures. Understanding these divides clarifies where supplier qualification cycles concentrate and which technology transitions command capital allocation.
Product Type:
METI's JIS C 5402 interoperability mandates differentiate mating interface requirements across industrial and automotive applications, elevating certification burdens for circular formats while streamlining board-to-board standardization.
- Board-to-Board:High-density micro-pitch configurations dominate smartphone and tablet assembly lines in Kanagawa prefecture. Hirose Electric and local competitors face signal integrity thresholds below 0.35mm pitch that constrain further miniaturization. Established volume favors Board-to-Board; emerging adoption favors Circular.
- Wire-to-Board:Hybrid press-fit and crimp architectures are displacing pure solder joints in automotive power distribution units. Toyota's EV platform teams in Aichi prefecture specify these interfaces for 48V mild-hybrid battery management systems. Demand concentrates where vibration resistance and field serviceability justify premium positioning.
- Coaxial:RF transmission formats serve 5G base station deployments and precision test equipment with controlled impedance requirements.
- Circular:Environmental sealing rated to IP67 and beyond anchors aerospace and factory robotics applications where JIS-certified suppliers maintain qualification advantages.
- Rectangular:Modular industrial automation backplanes in Osaka prefecture favor these footprints for backward-compatible equipment retrofits.
Cost tier separation distinguishes high-reliability circular formats from commodity board-to-board volumes.
Technology:
Assembly method selection directly determines capital intensity and field failure liability, with automotive OEMs shifting procurement toward solderless interfaces that reduce thermal stress on powertrain electronics.
- Press Fit:Compliant pin technology eliminates solder joints in telecom base stations and 800V EV architectures. Precision stamping and selective plating equipment requirements exceed $50 million for qualified production lines. Nissan's engineering divisions in Kanagawa specify these for battery disconnect units. Established volume favors Press Fit; emerging adoption favors Surface Mount.
- Surface Mount:High-volume consumer electronics in Saitama prefecture rely on these for pick-and-place assembly speed. Cost compression from tape-and-reel automation sustains margin pools below automotive-grade thresholds. Miniaturization physics limits below 0.25mm pitch are forcing hybrid approaches.
- Through Hole:Legacy industrial equipment and high-voltage power supplies retain these for mechanical strain relief.
- Wire Wrap:Prototyping and low-volume aerospace applications sustain niche demand with manual assembly economics.
- Crimp:Yazaki's captive terminal production dominates automotive wire harness integration with qualified tooling ecosystems.
Application maturity separates crimp's automotive lock-in from press fit's expansion trajectory.
Application:
End-use concentration in the Kanto corridor creates geographic clustering effects, with prefecture-level procurement volumes shaping supplier location decisions and just-in-time integration depth.
- Consumer Electronics:Smartphone and wearable assembly in Tokyo and Kanagawa prefectures drives unit volume leadership. Board-to-board micro-pitch specifications from domestic OEMs set regional technology roadmaps. Established volume favors Consumer Electronics; emerging adoption favors Renewable Energy.
- Telecommunications:5G massive MIMO deployments and fiber optic backhaul equipment concentrate in Saitama and Chiba prefectures. Press-fit backplane demand from NTT and Rakuten Mobile infrastructure teams elevates reliability specifications.
- Aerospace Systems:JAE's JIS-certified manufacturing lines in Shizuoka prefecture anchor defense and satellite connector supply with radiation-hardened qualifications.
- Renewable Energy:Solar inverter and energy storage system connectors face emerging standardization from METI's grid interconnection mandates.
- Industrial Automation:Factory robotics OEMs in Aichi and Osaka prefectures consolidate supplier lists around JIS C 5402 certified platforms.
Customer concentration distinguishes electronics volume from aerospace margin premiums.
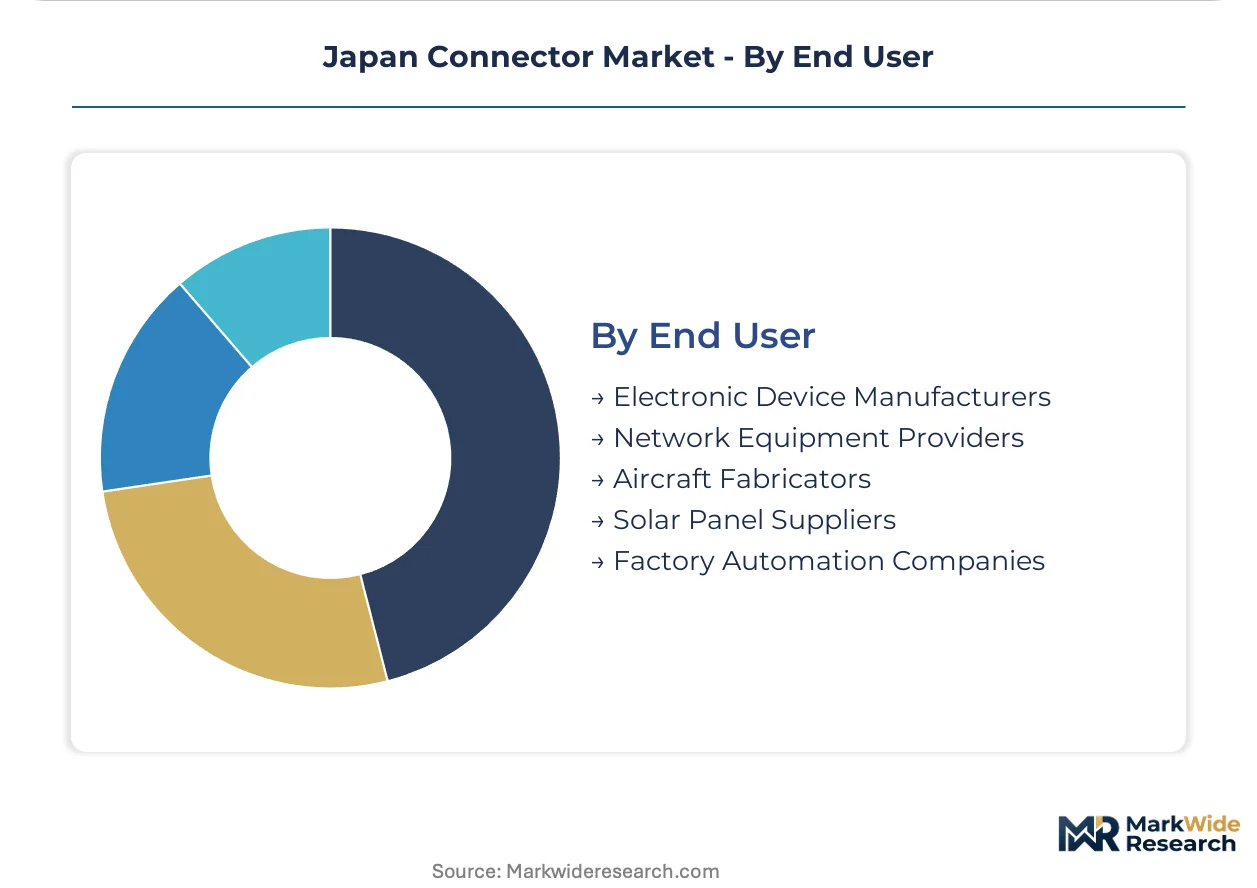
End User:
Procurement authority structures bifurcate between captive Tier-1 integration and direct component sourcing, with automotive electrification unbundling traditional wire harness supplier relationships.
- Electronic Device Manufacturers:Sony and Panasonic engineering teams in Tokyo specify board-to-board densities that cascade through Asian contract manufacturing networks. Established volume favors Electronic Device Manufacturers; emerging adoption favors Solar Panel Suppliers.
- Network Equipment Providers:NEC and Fujitsu's 5G infrastructure divisions in Kawasaki source press-fit backplanes with 25-year field life specifications.
- Aircraft Fabricators:Mitsubishi Heavy Industries and Subaru's aerospace divisions in Aichi and Gifu prefectures maintain dual-source qualifications for JIS-certified circular connectors.
- Solar Panel Suppliers:Sharp and local inverter manufacturers face emerging connector standardization for utility-scale storage integration.
- Factory Automation Companies:Fanuc and Yaskawa in Yamanashi and Fukuoka prefectures specify backward-compatible footprints that constrain next-generation performance.
Supply chain configuration favors electronics scale; regulatory qualification favors aerospace durability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's connector trade balance tilts toward import substitution as domestic semiconductor fabs expand, though high-value aerospace and automotive-grade formats retain export competitiveness. Regional demand concentrates in manufacturing corridors where METI's industrial policy directs procurement localization.
Kanto/Tokyo
Consumer electronics assembly and telecommunications infrastructure anchor procurement volumes across Tokyo, Kanagawa, and Saitama prefectures. METI's subsidies for advanced packaging facilities redirect connector sourcing toward domestic substrate suppliers. Sony and Panasonic engineering teams in Tokyo specify board-to-board densities that cascade through regional contract manufacturing networks.
Kansai/Osaka
Industrial automation OEMs in Osaka and Kyoto prefectures drive demand for backward-compatible rectangular connectors in factory robotics retrofits. JIS C 5402 certification requirements consolidate supplier lists around qualified platforms. Fanuc and Yaskawa procurement teams specify mating interfaces that constrain next-generation performance to legacy footprints.
Chubu/Nagoya
Toyota, Honda, and Subaru engineering divisions in Aichi prefecture expand 800V EV platform procurement for high-voltage interconnect architectures. Automotive-grade qualification cycles extend 18-24 months, locking suppliers into pre-development commitments. Tier-2 connector specialists now negotiate direct volume contracts unbundled from captive wire harness suppliers.
Kyushu
TSMC and Kioxia fab construction in Kumamoto and Miyazaki prefectures creates localized connector demand for semiconductor equipment and advanced packaging lines. METI's semiconductor supply chain resilience mandates redirect procurement toward domestic vendors. New substrate facilities require press-fit and high-density board-to-board formats for probe card and test socket applications.
Japan Connector Market Competitive Landscape
Listed leaders compete with private specialists across technology tiers, with publicly traded manufacturers commanding capital access for precision equipment while family-held specialists retain niche qualification advantages. The vendor base stratifies into three tiers: integrated wire harness suppliers with captive connector production, independent component specialists with JIS-certified lines, and foreign-owned multinationals with global scale. Dominant competitive moves include backward integration into terminal stamping and selective plating capacity, plus strategic partnerships with domestic fab construction consortia.
Among Japan-based fabricators, Yazaki, Hirose Electric, and JAE occupy distinct archetype positions. Yazaki exemplifies the integrated wire harness model with captive terminal production. Hirose Electric represents the high-density board-to-board specialist tier serving precision electronics. JAE anchors aerospace and defense supply through JIS-certified manufacturing qualifications. Foreign-owned multinationals including TE Connectivity, Molex, and Amphenol compete on global scale and cross-regional qualification portfolios.
| Leading Market Players |
|---|
| Yazaki |
| JST (Japan Solderless Terminals) |
| TE Connectivity |
| Molex |
| Sumitomo Electric |
| Amphenol |
| JAE (Japan Aviation Electronics) |
| Aptiv |
| Hirose Electric |
| Others |
Pricing and Supply Chain Analysis
Press-fit compliant pin technology replacing surface-mount solder joints in automotive powertrain applications is simultaneously relocating procurement toward precision stamping facilities in Aichi and Kanagawa prefectures while compressing margin pools for mid-tier suppliers lacking selective plating capabilities. This substitution dynamic concentrates pricing power among capital-intensive producers while fragmenting commodity board-to-board segments.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with JIS C 5402 certification grade and volume scale as the primary differentiation drivers. Cost compression in consumer electronics board-to-board segments is intensifying because tape-and-reel automation sustains margin pools below automotive-grade thresholds. Electronic device manufacturers in Tokyo exhibit highest price sensitivity due to Asian contract manufacturing network pressures, while aerospace fabricators in Aichi and Gifu prefectures demonstrate lowest sensitivity given radiation-hardened qualification requirements.
Supply Chain Analysis
Japan and South Korea anchor terminal plating and precision stamping capacity, with Taiwan feeding substrate-level interconnect demand for semiconductor probe card applications. Copper cathode and rare earth magnet wire inputs draw from Chilean mining operations and Chinese refining complexes. Single-source vulnerability concentrates around Yazaki's captive terminal production for automotive wire harness integration. Distribution runs through just-in-time supplier networks anchored in Kanto manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive OEM procurement unbundling from captive wire harness suppliers has shifted buyer power toward direct component sourcing relationships, consolidating negotiation leverage among platform engineering divisions at Toyota, Nissan, and Honda.
For Market Incumbents: Fortify backward integration into selective plating and precision stamping equipment to defend margin position against emerging press-fit specialists. Prioritize JIS C 5402 certification investment for industrial automation platforms in Osaka and Kyoto prefectures. Channel control through qualified tooling ecosystems remains the critical defensive lever against disintermediation.
For New Entrants and Emerging Players: Lead with Kyushu semiconductor corridor localization as the most penetrable geography, targeting substrate-level connector demand from TSMC and Kioxia fab construction in Kumamoto and Miyazaki prefectures. Medical device disposable surgical connectors offer adjacent white-space given PMDA's streamlined biocompatibility pathways. A direct volume contract approach with EV platform engineering teams bypasses traditional wire harness gatekeepers.
For Investors and Strategic Acquirers: The market sits at a supplier consolidation phase that favors JIS-certified specialists with automotive qualification portfolios. Long-term viability hinges on exposure to 800V EV architectures and domestic fab construction mandates. The signal to watch is METI semiconductor subsidy disbursement velocity as inflection indicator for localized procurement redirection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Selective Plating | Captive terminal production defends margin pools against Yazaki's wire harness lock-in. |
| JIS C 5402 Certification Investment | Industrial automation OEMs in Osaka consolidate supplier lists around qualified platforms. |
| Kyushu Semiconductor Corridor Expansion | Localized supply chains capture TSMC and Kioxia fab procurement in Kumamoto prefecture. |
| Medical Device Connector Development | PMDA biocompatibility pathways open adjacent revenue pools beyond automotive dependence. |
| Press-Fit Technology Scale-Up | Compliant pin architectures displace solder joints in Nissan 800V battery disconnect units. |
Research Methodology
A spread of perspectives from automotive platform engineers, industrial automation procurement leads, semiconductor fab construction managers, and connector manufacturing executives converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation through METI subsidy disbursement records, JIS certification registries, customs trade data, and OEM engineering specification documents. Bottom-up unit volume estimates triangulated against top-down value projections across product type, technology, application, and end user segmentation dimensions.
Product type, technology assembly method, application vertical, end user procurement authority, and prefecture-level manufacturing cluster density served as the core segmentation dimensions modeled across the projection horizon. CAGRs derived from historical shipment correlations with semiconductor equipment capex and automotive production schedules. Industry-specific forecast inputs included EV platform electrification roadmaps from Toyota, Nissan, and Honda, plus METI domestic fab construction timelines.
Forecasts assume regulatory continuity in METI industrial standards and PMDA medical device pathways; material policy shifts would require re-modeling. Specific risks include copper and rare earth price volatility, automotive qualification timeline extensions, and miniaturization physics limits constraining board-to-board density gains. Recalibration cycles align with material shifts in semiconductor localization mandates and EV platform procurement unbundling.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Connectors
Wire-To-Board Connector Market
Connectors
3C Electronics Precision Connectors Market
Connectors
Latin America Connector Market
Connectors
Global Wired Interface Market
Connectors
Liquid Cooling Connector Market
Connectors
India Connector Market
Connectors
Circular Connectors Market
Connectors
Connector and Terminal Systems for Harsh Environment Wiring Market
Connectors
SATA Connector Market
Connectors
Micro-Miniature Co-Axial Adapter Market
Connectors
IC Socket Market
Connectors
Hybrid Fiber Optic Connectors Market
Connectors
Connector for PV System Market
Connectors
Mexico Connector Market
Connectors
Hazardous Location Connectors Market
Connectors
Terminal Pins Market