
 Connector Market | 2026-2036
Connector Market Size, Share, and Industry Trends Forecast 2026-2036
Connector Market Analysis
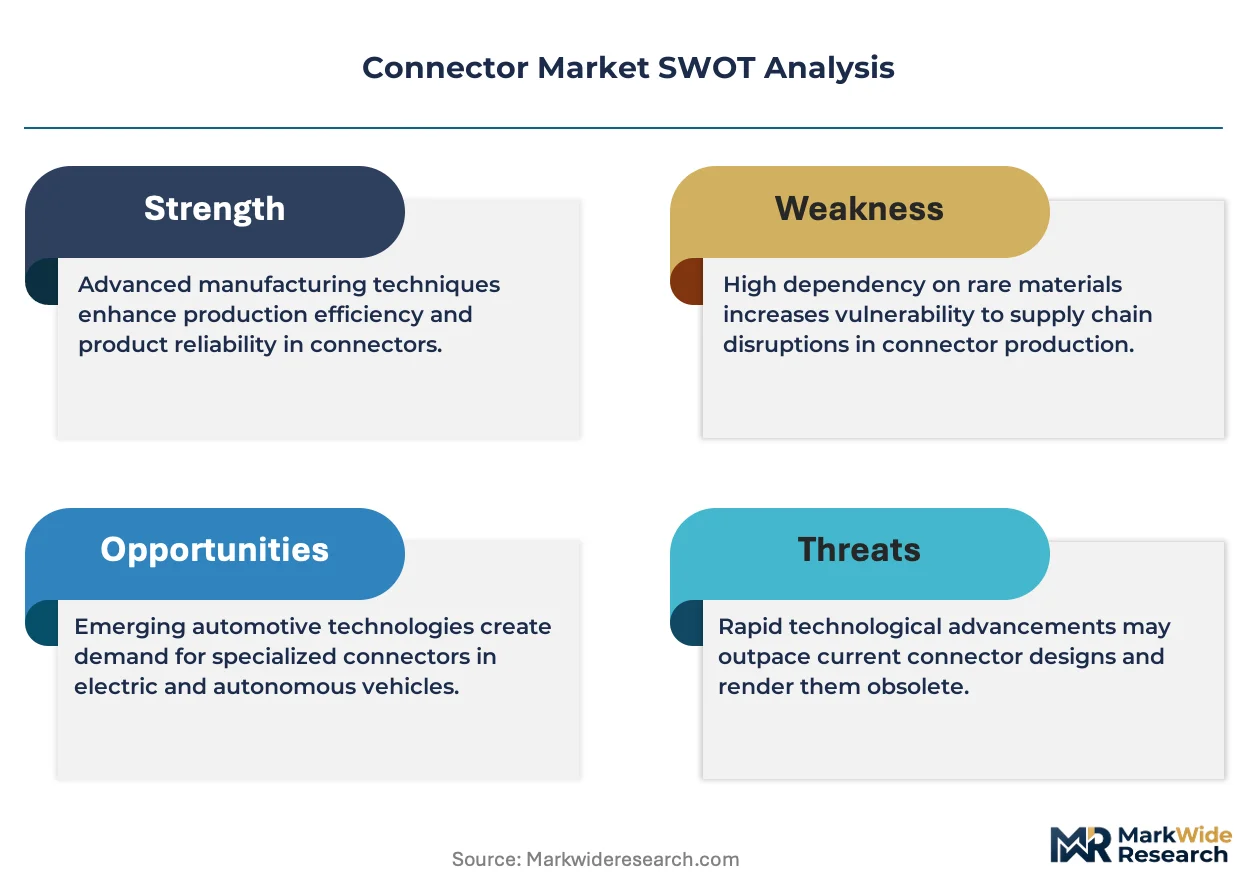
Direct procurement from tier-one automotive harness suppliers is reshaping how connector manufacturers secure long-term supply agreements. TE Connectivity leverages its captive cable assembly operations to sustain pricing power across EV charging infrastructure contracts. Amphenol Corporation dominates military-aerospace specification channels where qualification timelines lock out new entrants. Molex specializes in miniaturized board-to-board configurations for smartphone OEMs, a segment where design cycles compress annually.
Connectors are electromechanical devices engineered to establish temporary or permanent junctions between conductors, typically rated by contact pitch, current-carrying capacity, insertion force, and environmental sealing against moisture or electromagnetic interference. Their primary purpose is to enable signal integrity and power distribution across disassemblable interfaces in complex electronic systems. Fiber optic connectors command premium positioning as data center throughput requirements escalate, while RF technology segments face margin compression from commoditized cellular antenna interfaces. Industrial automation applications absorb the fastest volume growth as factory retrofit cycles accelerate, whereas modular connectors in consumer electronics represent a mature replacement market with stable but lower returns.
FCC equipment authorization rules govern RF connector emissions compliance in US telecommunications deployments, while the EU RoHS directive and REACH substance restrictions constrain plating chemistries and halogenated plastics used in European-bound product lines. China's GB standards and MIIT certification requirements create discrete technical barriers for imported interconnect products serving domestic 5G base station rollouts. Stakeholders must monitor evolving automotive functional safety standards and material disclosure mandates as qualification costs rise across multiple jurisdictions.
Market Dynamics
High-voltage interconnect architectures are forcing connector manufacturers to requalify entire product portfolios as electric vehicle platforms scale from 400V to 800V battery systems. This voltage migration demands redesigned contact geometries, enhanced insulation materials, and thermal management integration that legacy automotive suppliers cannot retrofit.
Growth Catalysts
- EU F-Gas Regulation:Phase-down schedules for fluorinated greenhouse gases are accelerating sealed connector housing redesigns toward fluorine-free polymer alternatives.
- Data center fiber throughput:Hyperscale cloud operators are procuring MPO-16 and MPO-32 multi-fiber push-on connectors to support 800G optical transceiver deployments.
- Stuttgart supplier corridor:Germany's automotive harness ecosystem concentrates procurement decisions for European EV charging infrastructure, creating localized demand pull for high-current contact systems.
Market Restraints
- Copper price volatility:Contact plating and conductor materials expose margins to London Metal Exchange commodity swings that OEMs refuse to index.
- Asian PCB substrate concentration:Taiwan and South Korea dominate high-layer-count board manufacturing, creating single-source risk for board-to-board connector mating surfaces.
- RF connector commoditization:Cellular antenna interfaces face margin compression as smartphone OEMs consolidate to standardized SMP and MMCX variants.
Strategic Opportunities
- Industrial automation retrofit cycles:European and North American factory modernization programs absorb modular fieldbus connectors with IP67 sealing and vibration resistance.
- China MIIT certification pathways:Domestic 5G base station rollouts create technical barriers that qualified foreign suppliers can leverage for premium positioning.
- Functional safety integration:ISO 26262-compliant connector designs for autonomous vehicle sensor networks command qualification premiums from tier-one harness suppliers.
Industry Challenges
- Automotive qualification timelines:PPAP submission and production part approval processes stretch 18-24 months, freezing design iterations across model-year cycles.
- REACH substance disclosure complexity:Full material declaration requirements for SVHC screening impose documentation burdens that smaller connector houses cannot resource internally.
- High-voltage safety certification:IEC 60664-1 clearance and creepage distance compliance for 800V systems demands specialized tooling investments that fragment supplier capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Connector Market |
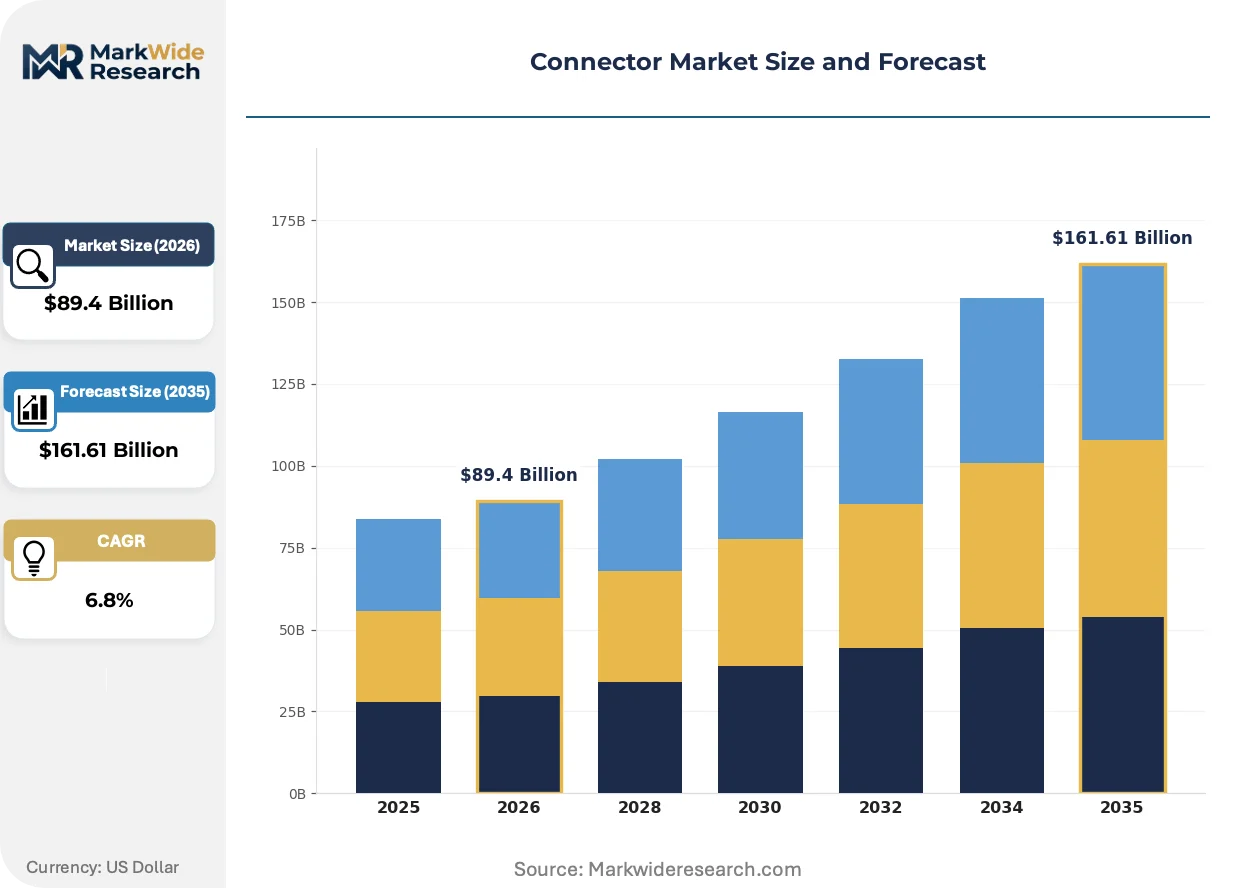
| Market Size in 2026 | $89.4 Billion |
| Market Size in 2035 | $161.61 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Connectors, Circular Connectors, RJ45 Connectors, Fiber Optic Connectors Application: Automotive Systems, Industrial Automation, Telecommunication, Consumer Electronics Technology: Optical Technology, Wireless Technology, RF Technology, Power Technology End User: Aerospace, Healthcare, Energy Sector, IT Services |
| Companies Covered | Aptiv, Luxshare Precision, TE Connectivity, Rosenberger, Yazaki Corporation, Amphenol Corporation, Foxconn Interconnect Technology, Hirose Electric, Molex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Connector Market Emerging Trajectories
Connector technology is bifurcating between extreme miniaturization for portable electronics and ruggedized high-power architectures for electrified transportation. This divergence is compressing design cycle methodologies and forcing manufacturers to maintain parallel R&D streams.
Contact plating chemistry is migrating from traditional tin-lead and pure tin finishes to silver-palladium and nickel-palladium-gold alloys. Automotive powertrain engineers are specifying these advanced metallurgies for 800V battery disconnect units and inverter interfaces. The shift is migrating from niche aerospace applications into mainstream EV production, compressing qualification timelines and forcing plating houses to retool electrolytic bath configurations.
REACH substance restrictions and EU F-Gas Regulation phase-down mandates are eliminating halogenated flame retardants and fluoropolymer seals from European-bound connector lines. ECHA SVHC candidate list expansions now cover brominated and chlorinated compounds common in thermoplastic housings. Automotive suppliers serving Stuttgart, Wolfsburg, and Munich manufacturing clusters are reformulating polyamide and PBT compounds to maintain UL 94 V-0 ratings without restricted substances.
Direct OEM engagement is displacing tiered distribution for high-reliability connector categories. Defense contractors and medical device manufacturers now require vendor-managed inventory programs with dedicated field application engineering support. This pattern is most visible in US aerospace corridors around Seattle and Wichita, where Boeing and Spirit AeroSystems have consolidated supplier bases to reduce qualification overhead.
Connector Market Segmentation
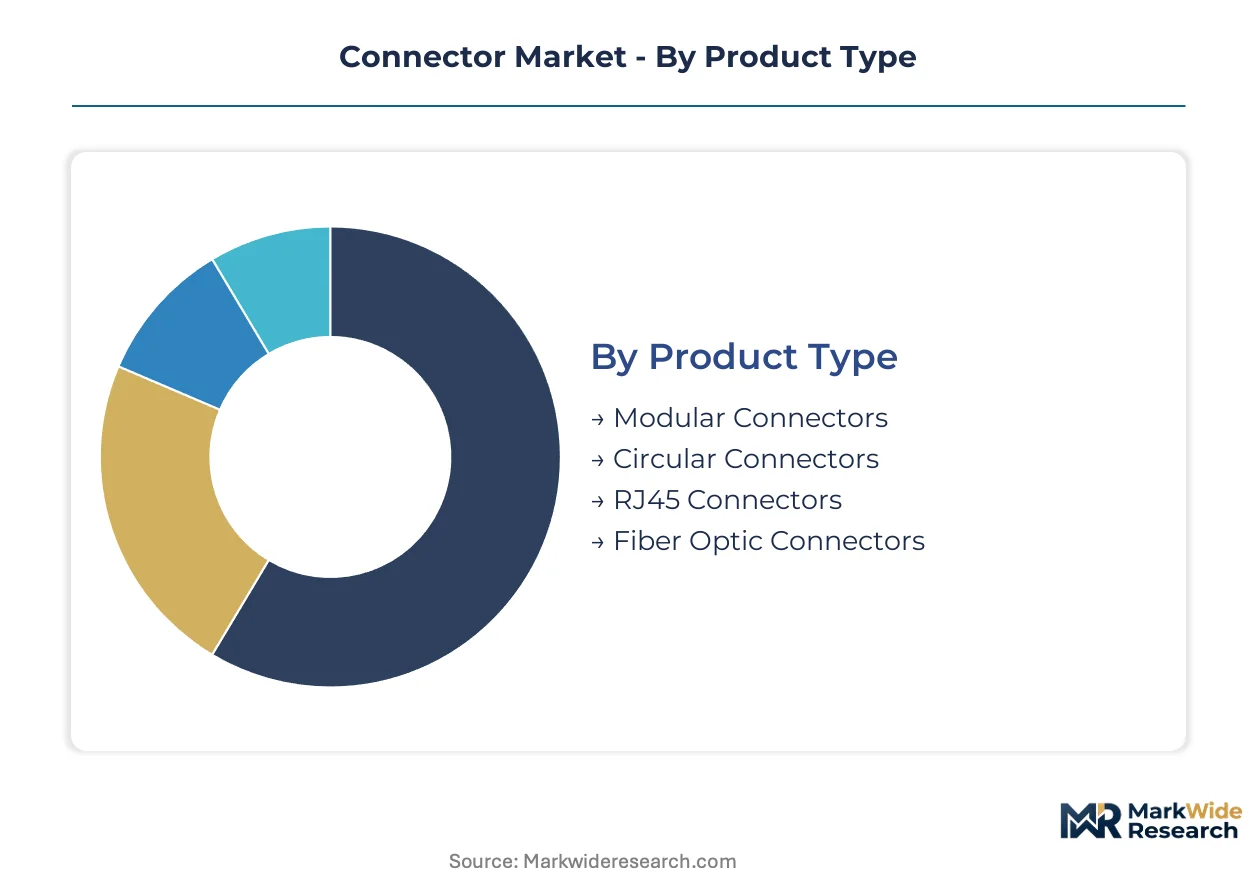
Connector procurement cycles vary dramatically across segments, from smartphone design cycles under 12 months to aerospace qualification timelines exceeding 24 months. Understanding these velocity differentials helps manufacturers allocate R&D resources and inventory investments across diverging demand patterns.
Product Type:
Design refresh cycles stretch from 18 months for standardized modular formats to 5+ years for sealed circular architectures in heavy industrial applications.
- Circular Connectors:Sealed cylindrical housings with threaded or bayonet coupling mechanisms rated for IP67+ environmental protection. Demand concentrates in Germany's automotive supplier corridor around Stuttgart, where EV charging infrastructure procurement requires 800V-rated contact systems with enhanced thermal management.
- Fiber Optic Connectors:Precision-aligned ferrule assemblies enabling single-mode and multi-mode optical transmission with insertion loss below 0.3dB. Hyperscale data center operators in Northern Virginia and Frankfurt are procuring MPO-16 and MPO-32 configurations to support 800G optical transceiver deployments, though ferrule polishing equipment costs limit supplier entry.
- Modular Connectors:Standardized rectangular housings with configurable contact arrangements for signal and power mixing. Factory automation retrofit programs in Michigan and Bavaria absorb high volumes with shorter qualification timelines.
- RJ45 Connectors:Eight-position modular jacks for twisted-pair Ethernet termination. Enterprise networking infrastructure refresh cycles in commercial buildings drive steady replacement demand with minimal specification volatility.
Circular connectors anchor the volume base while fiber optic connectors gain share at the steepest rate.
Application:
Margin structures diverge sharply between automotive programs with 18-24 month PPAP timelines and consumer electronics with annual design churn.
- Automotive Systems:High-voltage interconnect architectures for battery electric vehicles, including 800V battery disconnect units and inverter interfaces. EU F-Gas Regulation and REACH compliance are tightening material specifications for sealed connector housings across Stuttgart, Wolfsburg, and Munich manufacturing clusters.
- Industrial Automation:Fieldbus and sensor connectors with IP67 sealing and vibration resistance for factory floor deployment. European and North American modernization programs are absorbing modular designs as retrofit cycles accelerate.
- Telecommunication:RF and fiber interfaces for 5G base station and data center interconnect. China's MIIT certification requirements create technical barriers that qualified foreign suppliers can leverage for premium positioning in domestic rollout programs.
- Consumer Electronics:Miniaturized board-to-board and I/O configurations for smartphones, tablets, and wearables. Design cycles compress annually as OEMs chase form factor reductions, squeezing supplier margins despite high unit volumes.
Automotive systems command the highest qualification premiums while industrial automation represents the fastest volume expansion trajectory.
Technology:
Capital intensity separates optical fabrication requiring sub-micron polishing equipment from power contact stamping operations with lower tooling barriers.
- Power Technology:High-current contact systems rated for 100A+ continuous operation with silver-palladium plating chemistries. The voltage migration from 400V to 800V EV platforms is forcing contact geometry redesigns and enhanced insulation material selection.
- Optical Technology:Physical contact and expanded beam fiber interconnection with ceramic ferrule precision. Data center throughput escalation is driving MPO-16 and MPO-32 multi-fiber push-on connector procurement from cloud operators.
- RF Technology:Coaxial and waveguide interfaces for electromagnetic signal transmission. Cellular antenna connectors face margin compression as smartphone OEMs consolidate to standardized SMP and MMCX variants.
- Wireless Technology:Inductive and capacitive coupling solutions for contactless power and data transfer. Niche adoption in medical sterilization environments and hazardous area applications where galvanic isolation is mandatory.
Power technology carries the heaviest automotive qualification burden while optical technology climbs the fastest on data center investment cycles.
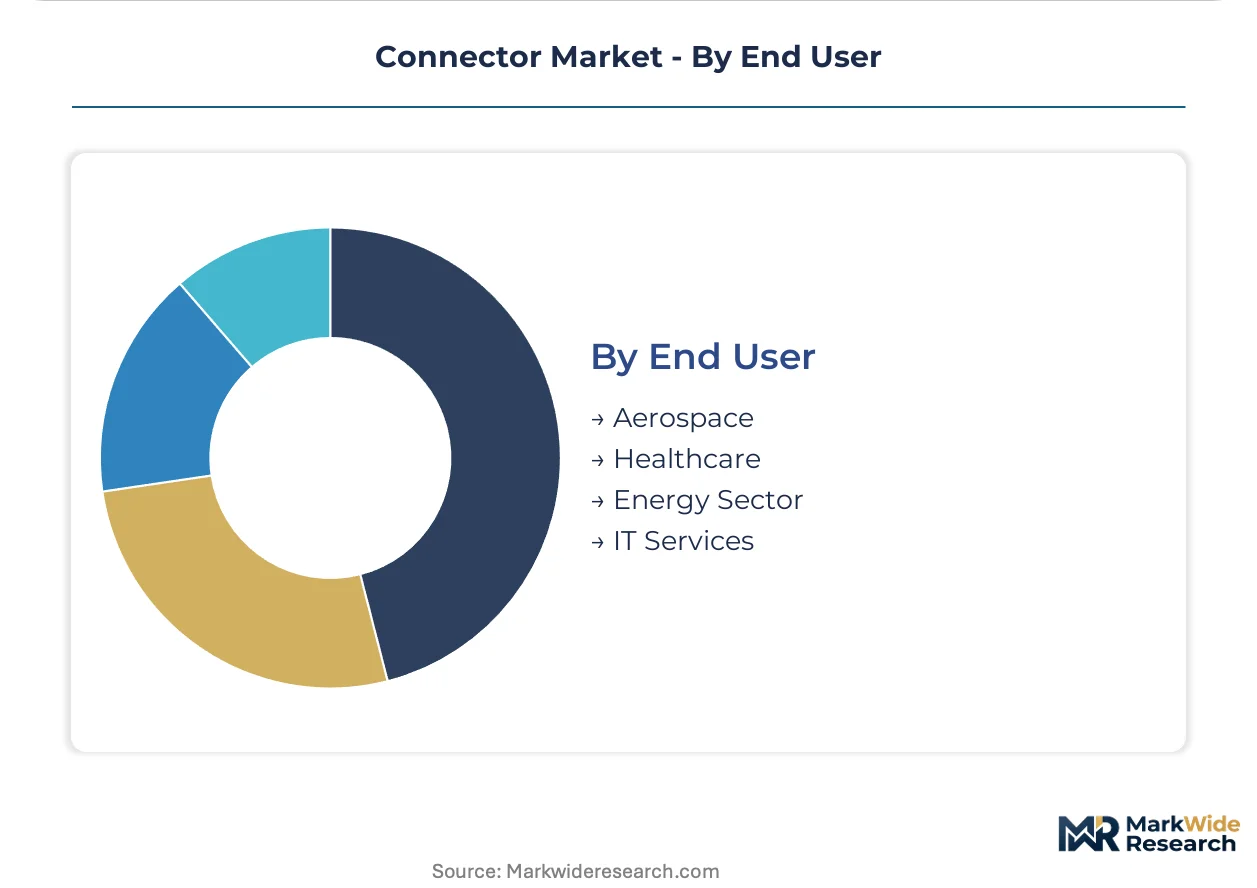
End User:
Contract structures range from vendor-managed inventory with dedicated field engineering in aerospace to spot-market procurement in commodity IT infrastructure.
- Aerospace:MIL-SPEC qualified interconnect with traceability documentation and extended temperature range performance. Boeing and Spirit AeroSystems in Seattle and Wichita corridors have consolidated supplier bases to reduce qualification overhead.
- IT Services:Standardized copper and fiber infrastructure for enterprise and hyperscale data center deployment. Rapid technology turnover compresses product lifecycles despite high annual volumes.
- Healthcare:Sterilization-resistant and EMI-shielded connectors for diagnostic and therapeutic equipment. FDA device regulations extend validation timelines beyond typical industrial applications.
- Energy Sector:Harsh-environment interconnect for oil and gas exploration, renewable generation, and grid infrastructure. IEC 60664-1 clearance and creepage compliance for medium-voltage systems fragments supplier capabilities.
IT services generates the highest unit volumes while aerospace sustains the most durable margin premiums through qualification barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU F-Gas Regulation phase-down schedules and REACH substance restrictions are redirecting connector procurement toward fluorine-free polymer alternatives across multiple jurisdictions. National electrification targets and data center buildouts are concentrating demand in specific industrial corridors.
Germany
Automotive electrification is absorbing high-voltage interconnect systems for 800V battery platforms. EU F-Gas Regulation compliance mandates are eliminating fluoropolymer seals from sealed connector housings. The Stuttgart supplier corridor concentrates procurement decisions for European EV charging infrastructure.
China
Domestic 5G base station rollouts are creating qualified demand for MIIT-certified fiber and RF interconnect. GB standards and MIIT certification requirements establish technical barriers for imported products. Yangtze River Delta manufacturing clusters are scaling optical connector production for hyperscale data center deployment.
United States
FCC equipment authorization rules govern RF connector emissions compliance for telecommunications infrastructure. Defense contractors and medical device manufacturers are requiring vendor-managed inventory with dedicated field engineering support. Seattle and Wichita aerospace corridors are consolidating supplier bases to reduce qualification overhead.
Japan
METI industrial policy is supporting precision manufacturing capabilities for miniaturized board-to-board configurations. JIS standards and automotive functional safety requirements extend validation timelines beyond typical consumer electronics cycles. Kanto and Kansai manufacturing belts are maintaining captive production of ceramic ferrule assemblies for fiber optic connectors.
India
BIS certification requirements and PLI scheme incentives are attracting connector assembly investments for domestic electronics manufacturing. Central electricity regulator mandates are shaping grid infrastructure interconnect specifications. Maharashtra and Tamil Nadu industrial corridors are absorbing modular fieldbus connectors for factory automation retrofit programs.
Connector Market Vendor Landscape
On the supply side, the industry is consolidating around three distinct capability tiers. Large diversified manufacturers with captive cable assembly operations sustain pricing power across long-term automotive contracts. Specialized mid-scale fabricators concentrate on qualification-intensive aerospace and medical segments where documentation traceability creates retention barriers. Pure-play commodity producers compete on stamping throughput and plating line efficiency for high-volume consumer electronics. M&A activity targets regional connector houses with established PPAP approval status, while capacity expansion concentrates in automotive supplier corridors proximate to OEM final assembly.
Among diversified multinational suppliers, TE Connectivity, Amphenol Corporation, and Molex exemplify the tier-one archetype with integrated manufacturing and qualification infrastructure. These entities occupy positions where automotive harness supplier relationships and multi-jurisdictional regulatory compliance create defensive moats. Their geographic footprints span the Stuttgart automotive corridor, US aerospace clusters, and Asian electronics manufacturing regions. The concentration of named players in raw data suggests a market where scale-driven qualification capabilities separate sustainable participants from marginal competitors.
| Leading Market Players |
|---|
| Aptiv |
| Luxshare Precision |
| TE Connectivity |
| Rosenberger |
| Yazaki Corporation |
| Amphenol Corporation |
| Foxconn Interconnect Technology |
| Hirose Electric |
| Molex |
| Others |
Supply Flow & Price Mechanics
Taiwan and South Korea's dominance in high-layer-count PCB substrate manufacturing concentrates bargaining power upstream, forcing connector assemblers to absorb commodity volatility while tier-one automotive harness suppliers extract volume discounts downstream. This asymmetry compresses margin pools at the mid-market fabrication tier while rewarding integrated manufacturers with captive cable assembly operations.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates MIL-SPEC aerospace connectors with full traceability documentation from automotive PPAP-qualified products and commodity consumer electronics variants. Price differentiation hinges on certification grade—ISO 26262 functional safety compliance commands substantial premiums—plus geographic delivery cost differentials to Stuttgart and Detroit corridors. Cost compression in the consumer electronics tier is intensifying because smartphone OEMs consolidate to standardized SMP and MMCX RF variants. Automotive harness suppliers exhibit the lowest price sensitivity due to 18-24 month qualification lock-in, while IT infrastructure procurement teams drive the hardest volume negotiations.
Supply Chain Analysis
US export controls on advanced semiconductor manufacturing equipment and dual-use technologies are fragmenting supplier networks as Chinese connector houses accelerate domestic ceramic ferrule and precision stamping capacity. Manufacturing concentrates in China, Germany, and Japan, with raw material dependencies spanning copper cathodes from Chilean mines, silver-palladium plating chemistries, and high-performance polyamide resins. Single-source vulnerability in Taiwan's PCB substrate ecosystem poses acute disruption risk. Distribution runs through tier-one automotive harness suppliers, direct OEM engagement in aerospace and medical segments, and spot-market procurement for commodity IT infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The connector market is entering a cyclical recovery phase as automotive electrification capital expenditure rebounds from model-year inventory corrections and data center fiber deployment resumes its expansion trajectory.
For Market Incumbents: Entrench qualification barriers by accelerating ISO 26262 certification investments for 800V battery disconnect architectures before competitor PPAP submissions freeze design slots. Deepen backward integration into silver-palladium plating chemistries to offset London Metal Exchange copper volatility. Consolidate channel control through vendor-managed inventory programs with dedicated field application engineering in Seattle and Wichita aerospace corridors.
For New Entrants and Emerging Players: Industrial automation retrofit programs in Michigan and Bavaria represent the most penetrable entry point, as shorter qualification timelines and modular fieldbus standardization reduce incumbent lock-in. China's MIIT-certified 5G base station supply chain offers a second white-space target where technical barriers protect premium positioning. Pursue acquisition of regional connector houses with established automotive PPAP approval status rather than greenfield capacity builds.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across optical connector fabrication as MPO-16 and MPO-32 polishing equipment costs limit supplier entry. Five-to-ten-year viability favors mid-scale fabricators with qualification-intensive aerospace and medical documentation traceability. Monitor hyperscale cloud operator capex disclosures as the primary inflection signal for fiber optic connector demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| High-Voltage Platform Qualification | 800V battery system certification locks out competitors across Stuttgart supplier corridor. |
| Backward Integration into Plating | In-house silver-palladium chemistries insulate margins from London Metal Exchange copper swings. |
| MIIT Certification Pathway | China's 5G base station technical barriers create premium positioning for qualified foreign suppliers. |
| Vendor-Managed Inventory Expansion | Dedicated field engineering support consolidates Boeing and Spirit AeroSystems supplier relationships. |
| Fluorine-Free Polymer Reformulation | EU F-Gas Regulation compliance maintains UL 94 V-0 ratings without restricted halogenated compounds. |
Methodological Framework
Initial hypotheses were tested against primary input from tier-one automotive harness procurement directors, OEM platform engineers, fiber optic connector polishing equipment manufacturers, and aerospace supplier quality managers, then refined through secondary validation. Primary sources combined structured interviews with aftermarket distribution channel heads and medical device GPO contracts managers. Secondary data drew from SEC 10-K filings of diversified interconnect manufacturers, MIIT certification registries, ECHA SVHC candidate list updates, and IHS Markit vehicle production databases. Bottom-up demand modeling triangulated against top-down industry association estimates.
Demand-supply-balance framing anchored the analytical approach across the projection horizon, with segmentation dimensions spanning product type, application, technology tier, and regional production cluster. CAGRs were derived from regression analysis of historical procurement cycle data and forward-looking capital expenditure intentions. Industry-specific forecast inputs incorporated EV platform voltage migration timelines and hyperscale data center optical transceiver deployment schedules.
Practitioners should monitor copper price volatility, REACH substance list expansions, and automotive model-year inventory corrections for early signals of forecast deviation. Material shifts in EU F-Gas Regulation phase-down schedules or China MIIT certification pathway modifications would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Connectors
PCI-E Connectors Market
Connectors
AS-Interface Market
Connectors
Terminal Pins Market
Connectors
Japan Connector Market
Connectors
Circular Waterproof Connector Market
Connectors
Connector for PV System Market
Connectors
India Connector Market
Connectors
Hybrid Fiber Optic Connectors Market
Connectors
Global Board to Board (BTB) Connectors Market
Connectors
Liquid Cooling Connector Market
Connectors
Hazardous Location Connectors Market
Connectors
Global Multi Coaxial Connectors Market
Connectors
Middle East and Africa Hazardous Location Connectors Market
Connectors
High-Reliability Connectors Market
Connectors
Australia Connector Market
Connectors
Micro-Miniature Co-Axial Adapter Market