
 AS-Interface Market | 2026-2036
AS-Interface Market Size, Share, and Industry Trends Forecast 2026-2036
AS-Interface Market Intelligence
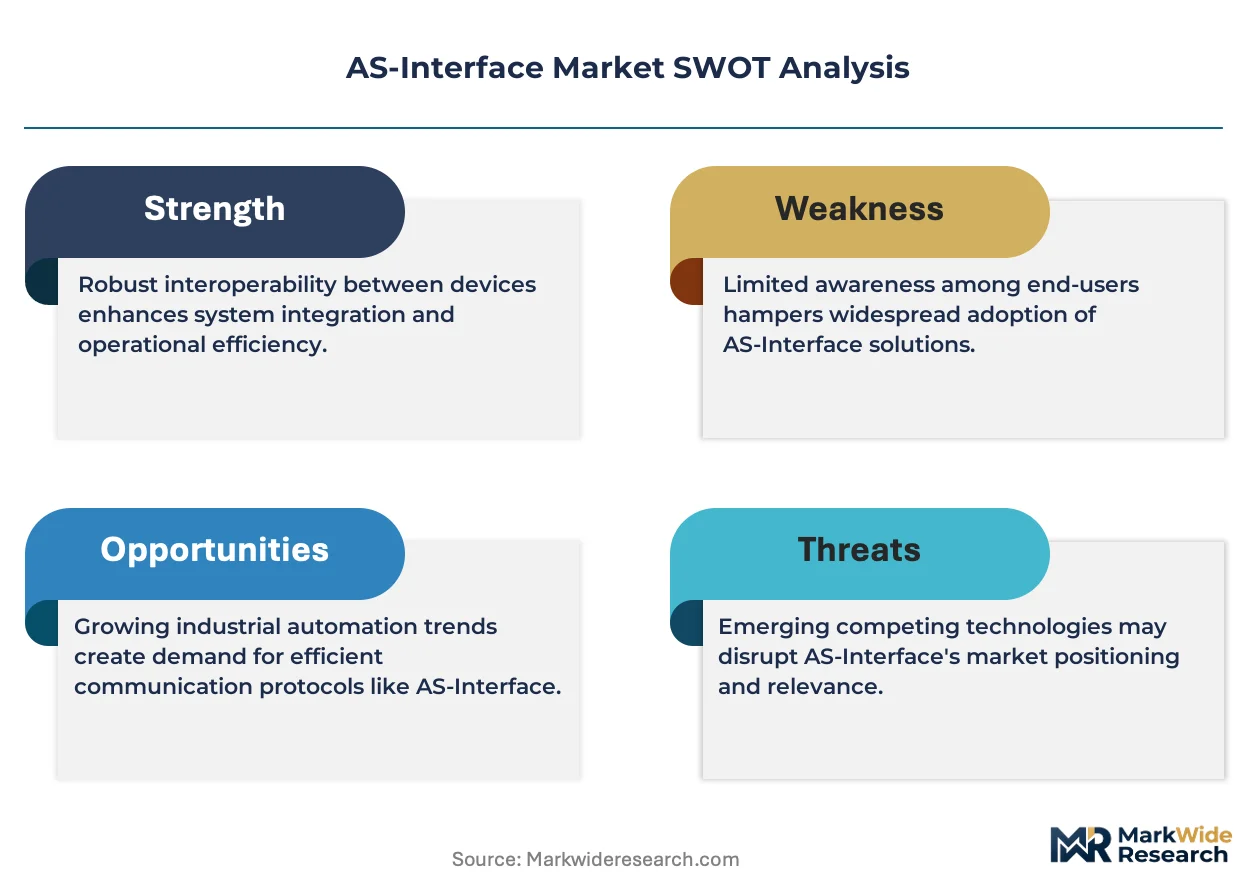
REACH compliance is recalibrating the cost-of-entry calculus for AS-Interface component suppliers entering European industrial channels. Siemens leverages its embedded safety portfolio to anchor premium positioning in safety-integrated wired deployments. Schneider Electric sustains broad geographic coverage through its factory automation distribution network. Rockwell Automation specializes in North American process-control integrations where diagnostic communication modules command higher configuration margins.
AS-Interface is a two-wire, unshielded cabling system operating at 31.25 kbit/s that connects binary sensors and actuators to controller-level fieldbus networks, primarily designed to reduce wiring complexity in discrete manufacturing environments. Slave modules and master devices together constitute the core hardware revenue pool, with slave modules benefiting from proliferating sensor counts per machine cell. Wired bus systems retain dominant share in automotive manufacturing and metal fabrication, while wireless interface adoption is gaining traction in material handling applications where cable fatigue drives maintenance costs.
IEC 62026 and ISO 16484 shape product certification requirements for AS-Interface devices deployed in building and industrial automation systems across multiple geographies. Germany's KBA and France's ANSM do not directly regulate this equipment, yet EU machinery safety directives enforced through national bodies mandate functional safety ratings that filter market access. Stakeholders must monitor how China's GB standards evolution and the EU AI Act's peripheral coverage of autonomous production systems reshape compliance investment timelines for next-generation interface architectures.
Market Dynamics
Factory automation buyers in automotive manufacturing are consolidating sensor-level networking deployments around single-cable architectures, compressing vendor selection cycles and elevating safety-integrated wired systems over legacy parallel wiring.
Growth Catalysts
- EU F-Gas Regulation:Tightening environmental compliance mandates energy-efficient industrial communication hardware, accelerating replacement of pneumatic actuation with electric alternatives networked via AS-Interface.
- China's smart-manufacturing investments:Domestic production facility construction is proliferating actuator-sensor interface architectures in new greenfield automotive and electronics plants.
- Sensor proliferation per machine cell:Rising binary sensor counts in discrete manufacturing environments expand addressable demand for slave modules and distributed I/O.
Market Restraints
- Copper price volatility:Two-wire unshielded cabling systems remain exposed to raw material input cost swings that compress hardware margins.
- Wireless substitution in material handling:Cable fatigue maintenance costs in conveyor and AGV applications are displacing wired bus systems with industrial wireless alternatives.
- REACH compliance burden:European chemical substance restrictions recalibrate cost-of-entry for component suppliers, filtering smaller participants from industrial distribution channels.
Strategic Opportunities
- India's PLI scheme for manufacturing:Production-linked incentives for electronics and automotive sectors create underpenetrated demand for sensor-level networking in new assembly lines.
- EU AI Act peripheral coverage:Autonomous production system classifications may mandate diagnostic communication capabilities that AS-Interface safety-integrated architectures can address.
- Convergence with IO-Link:Hybrid architectures combining AS-Interface backbone with point-to-point intelligent sensor communication open process-control adjacent applications.
Industry Challenges
- IEC 62026 certification timelines:Multi-geography product approval requirements delay market entry for next-generation interface architectures with enhanced safety ratings.
- Legacy fieldbus integration complexity:Retrofit deployments in brownfield metal fabrication facilities require bridging gateways that add configuration overhead and commissioning labor.
- Functional safety engineering scarcity:SIL-rated system design expertise concentrates in German and Austrian automation clusters, constraining project execution capacity elsewhere.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AS-Interface Market |
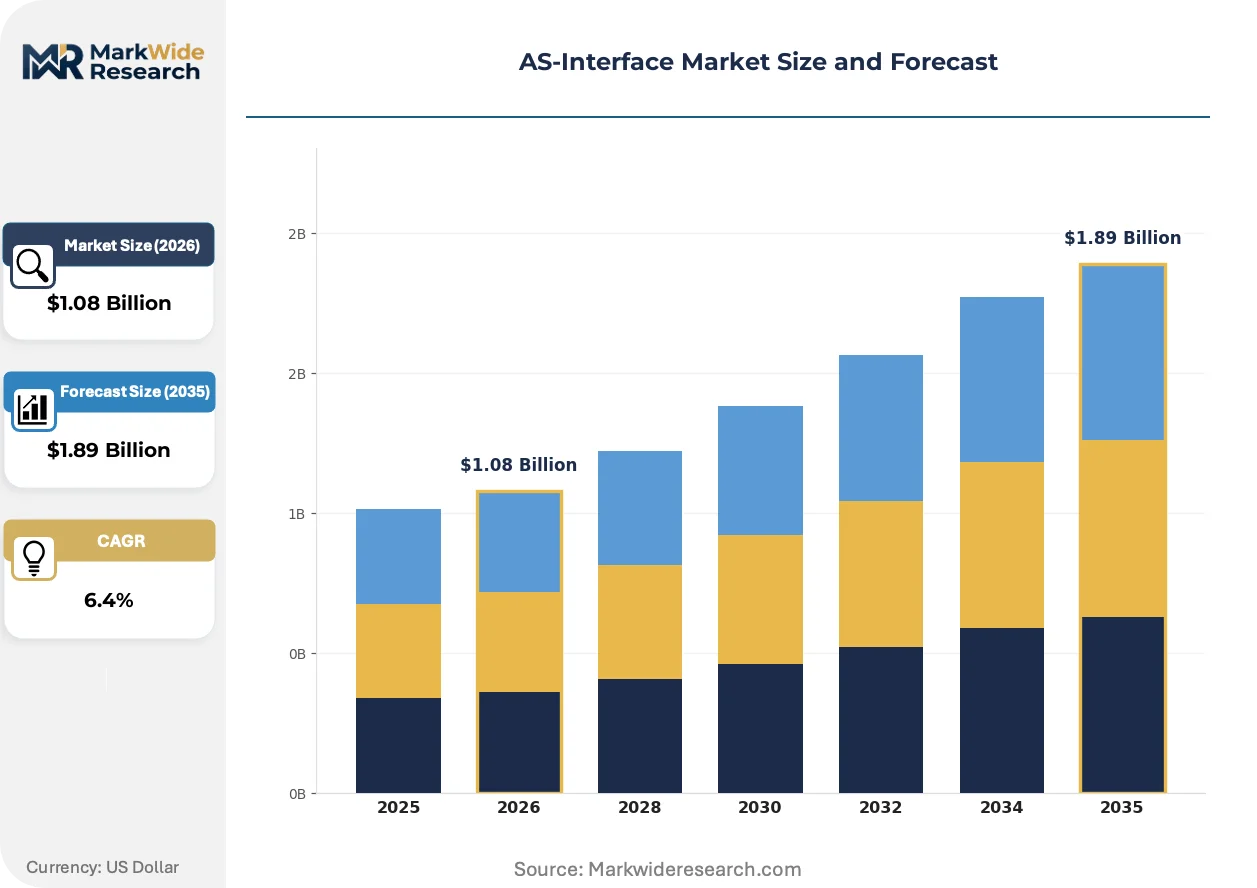
| Market Size in 2026 | $1.08 Billion |
| Market Size in 2035 | $1.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Master Devices, Slave Modules, Power Supplies, Couplers, Repeaters Technology: Wired Bus Systems, Wireless Interface, Safety Integrated, Fieldbus Integration, Diagnostic Communication Application: Factory Automation, Process Control, Packaging Equipment, Material Handling, Machine Tools End User Industry: Automotive Manufacturing, Food Processing, Consumer Electronics, Pharmaceutical Production, Metal Fabrication |
| Companies Covered | Schneider Electric, Texas Instruments, Siemens, NXP Semiconductors, Analog Devices, Rockwell Automation, Honeywell International, STMicroelectronics, ABB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AS-Interface Market Strategic Shifts & Innovations
Electrification of factory floor architectures is compressing the boundary between power distribution and sensor networking, forcing cable infrastructure to carry both energy and data through unified two-wire topologies.
AS-Interface Safety at Work technology is electrifying machine guard integration by embedding safe torque-off and light curtain communication directly onto the standard bus without separate safety relays. Automotive body-in-white lines at BMW and Volkswagen Group facilities are deploying these architectures at accelerated pace. The technology is electrifying competitive positioning for vendors with embedded functional safety portfolios against legacy safety relay suppliers.
Germany's Machinery Regulation implementation through national enforcement bodies is mandating documented functional safety ratings for all networked actuators in collaborative robot cells. Industrial OEMs must now certify AS-Interface slave modules to SIL 3 / PLe ratings to maintain market access. German automotive Tier-1 suppliers are responding by pre-qualifying only safety-integrated master devices in new capital equipment specifications.
Buyer procurement for sensor-level networking is consolidating around system integrator channel partners who bundle AS-Interface hardware with commissioning services. Direct OEM sales are fragmenting as mid-sized machine builders outsource electrical design to regional automation houses. This pattern is most visible in China's Yangtze River Delta manufacturing belt where domestic system integrators now specify interface architectures for foreign-owned automotive joint ventures.
AS-Interface Market Segmentation
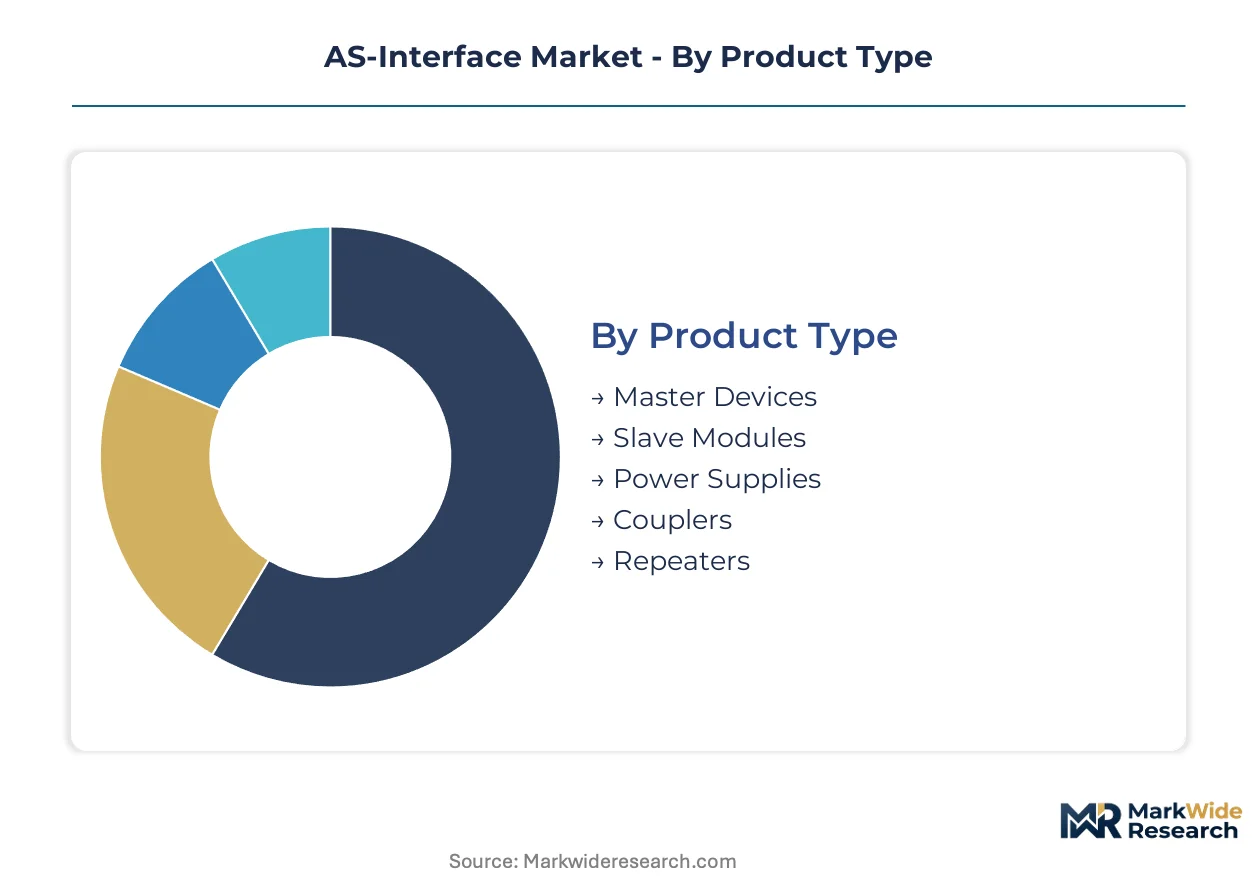
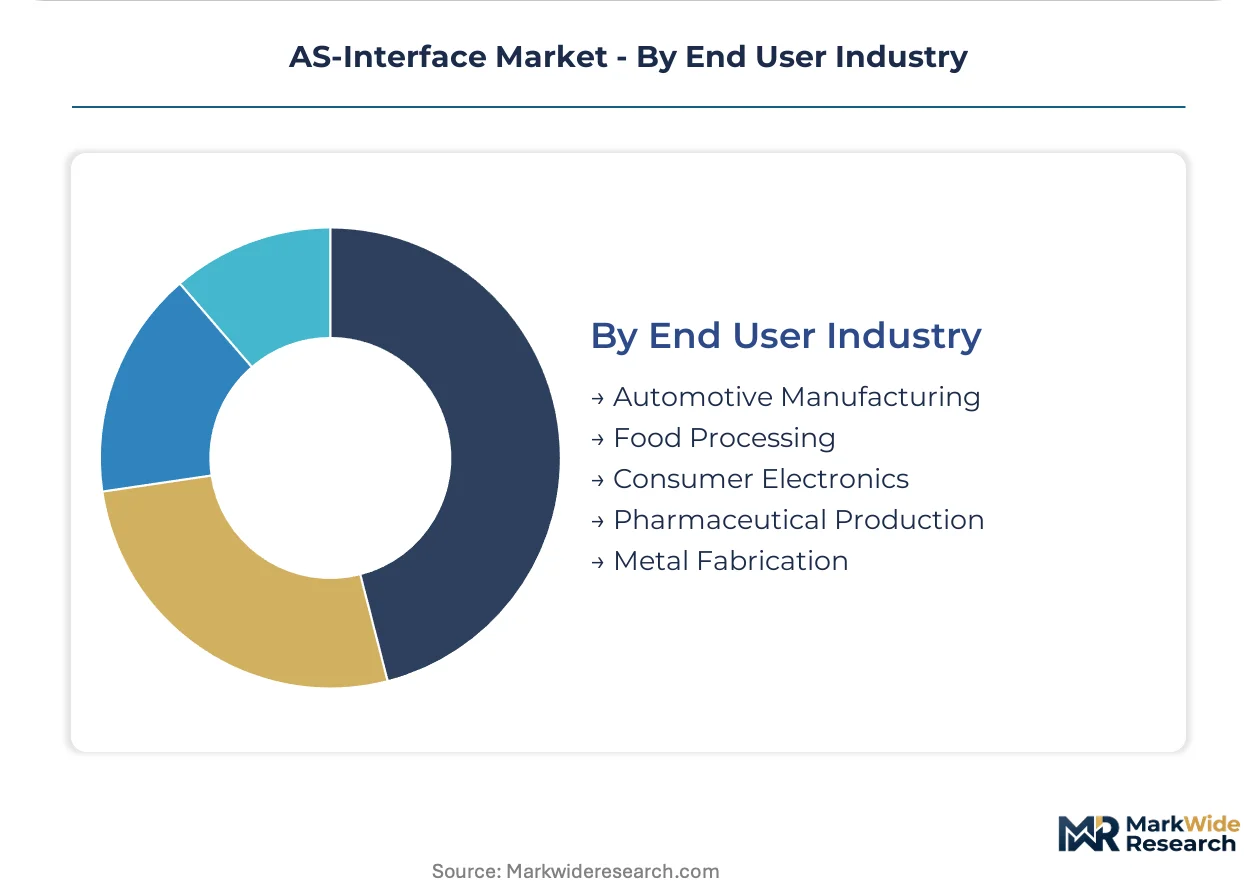
AS-Interface market segmentation reveals how procurement priorities diverge across hardware tiers, connectivity architectures, and compliance-sensitive end-use environments. Buyers optimize around wiring density reduction, functional safety ratings, and integration complexity with legacy fieldbus infrastructures.
Product Type:
Cost tier separates high-volume component buyers from system integrators seeking bundled safety architectures.
- Master Devices:Controller-interface gateways manage network timing and slave addressing across 31.25 kbit/s two-wire bus topologies. Demand concentrates with German automotive Tier-1 suppliers mandating SIL 3 pre-qualification for collaborative robot cells under Machinery Regulation enforcement.
- Slave Modules:Distributed I/O terminals connect binary sensors and actuators through compact IP67-rated housings. Sensor proliferation per machine cell in China's Yangtze River Delta electronics plants expands module counts per installation.
- Power Supplies:30V DC regulated units with integrated data decoupling maintain signal integrity across extended cable runs.
- Couplers:Fieldbus bridging devices translate AS-Interface protocols to PROFIBUS or EtherNet/IP for brownfield retrofit deployments.
- Repeaters:Signal regeneration hardware extends network reach beyond 100-meter cable limits in sprawling material handling facilities.
Volume sits with Slave Modules; growth tilts toward Master Devices.
Technology:
Application environment dictates whether buyers prioritize cable durability, electromagnetic resilience, or diagnostic granularity.
- Wired Bus Systems:Unshielded two-wire cabling at 31.25 kbit/s dominates automotive body-in-white lines at BMW and Volkswagen Group facilities where welding electromagnetic interference demands robust physical layer signaling.
- Safety Integrated:AS-Interface Safety at Work embeds safe torque-off and light curtain communication directly onto standard bus architectures without separate safety relays. Germany's national enforcement of Machinery Regulation for collaborative robot cells accelerates SIL 3 / PLe certification requirements.
- Wireless Interface:Industrial radio alternatives displace wired systems in conveyor and AGV applications suffering cable fatigue maintenance costs.
- Fieldbus Integration:Gateway protocols bridge sensor-level networks to controller-level fieldbuses in hybrid automation architectures.
- Diagnostic Communication:Extended parameterization channels enable predictive maintenance data extraction from intelligent slave devices.
Revenue concentrates in Wired Bus Systems; Safety Integrated climbs the fastest.
Application:
Customer type differentiates between discrete manufacturing specialists and continuous process operators with divergent uptime requirements.
- Factory Automation:Discrete manufacturing cells with high sensor density leverage AS-Interface for parallel wiring replacement. China's smart-manufacturing investments in greenfield automotive plants proliferate actuator-sensor interface architectures.
- Material Handling:Conveyor systems and automated storage applications balance cable durability against wireless substitution economics.
- Process Control:Continuous manufacturing environments demand diagnostic communication modules commanding higher configuration margins.
- Packaging Equipment:High-speed machinery with frequent format changes requires modular I/O for rapid reconfiguration.
- Machine Tools:Metal cutting and forming equipment integrates sensor networking with existing CNC fieldbus infrastructures.
Deployment scale favors Factory Automation; expansion tilts toward Process Control.
End User Industry:
Margin structure separates regulated pharmaceutical environments from price-sensitive consumer electronics assembly.
- Automotive Manufacturing:Body-in-white, paint shop, and final assembly lines consolidate sensor-level networking around single-cable architectures. Germany's KBA enforcement of EU machinery safety directives filters market access to safety-integrated suppliers.
- Pharmaceutical Production:Batch manufacturing with stringent hygiene requirements drives IP69K-rated slave module specifications and validation documentation.
- Food Processing:Washdown environments mandate stainless steel housings and corrosion-resistant connectors for dairy and beverage applications.
- Consumer Electronics:High-volume assembly lines in China's Pearl River Delta optimize for lowest per-point I/O cost.
- Metal Fabrication:Welding-intensive operations require electromagnetic immunity certification for reliable operation near arc equipment.
Value capture concentrates in Automotive Manufacturing; regulatory tailwinds favor Pharmaceutical Production.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta special economic zones concentrate smart-manufacturing investments that proliferate actuator-sensor interface architectures across new automotive and electronics facilities. Domestic system integrators now specify network hardware for foreign-owned joint ventures, compressing procurement cycles.
China
Greenfield automotive plants in Shanghai and Suzhou deploy slave modules at accelerating density per machine cell. MIIT's dual carbon goals mandate energy-efficient industrial communication hardware, filtering supplier selection toward low-power architectures. Yangtze River Delta electronics assembly lines now source AS-Interface components through domestic distribution channels.
Germany
Automotive Tier-1 suppliers in Stuttgart and Munich consolidate sensor-level networking around single-cable architectures with embedded safety ratings. KBA enforcement of Machinery Regulation mandates SIL 3 certification for collaborative robot cell components. Bavarian automation clusters concentrate functional safety engineering expertise that constrains project execution capacity elsewhere.
United States
Process-control integrations in Houston and Detroit command higher configuration margins for diagnostic communication modules. OSHA workplace safety directives shape functional safety requirements for networked actuators in automotive body shops. Midwest metal fabrication facilities require electromagnetic immunity certification for reliable operation near welding equipment.
India
Production-linked incentives for electronics and automotive sectors create underpenetrated demand in new Pune and Chennai assembly lines. BIS standards evolution for industrial automation equipment filters market access for imported components. Tamil Nadu manufacturing corridors attract greenfield investments where sensor proliferation expands addressable module demand.
Japan
Machine tool builders in Nagoya and Osaka integrate sensor networking with existing CNC fieldbus infrastructures. METI's industrial digitalization roadmap accelerates replacement of legacy parallel wiring in discrete manufacturing cells. Chubu region automotive suppliers pre-qualify safety-integrated master devices for capital equipment specifications.
AS-Interface Market Key Industry Players
German producers anchor one tier; French specialists hold distribution scale in factory automation channels. The vendor base stratifies across three tiers: diversified electrical conglomerates with embedded safety portfolios, semiconductor specialists supplying transceiver components, and regional automation houses bundling hardware with commissioning services. Strategic moves concentrate on backward integration into ASIC design and geographic expansion through system integrator partnerships.
Within the diversified industrial tier, Schneider Electric and Siemens exemplify archetypes with factory automation distribution networks and embedded safety portfolios respectively. Texas Instruments occupies a position among semiconductor specialists supplying physical layer components. These three anchors represent competitive positioning vectors: distribution reach, functional safety integration, and component-level supply.
| Leading Market Players |
|---|
| Schneider Electric |
| Texas Instruments |
| Siemens |
| NXP Semiconductors |
| Analog Devices |
| Rockwell Automation |
| Honeywell International |
| STMicroelectronics |
| ABB |
| Others |
Cost & Logistics Intelligence
Copper conductor costs cascade through AS-Interface hardware tiers, with two-wire unshielded cabling exposed to London Metal Exchange volatility that compresses margins on economy-grade slave modules while German automotive Tier-1 buyers absorb premium pricing for SIL 3 certified master devices.
Pricing Analysis
Lead-time compression commands premium positioning in AS-Interface procurement, with German automotive OEMs paying standard-tier rates for 8-week delivery while spot inventory in Chinese distribution channels clears at economy discounts. Price differentiation stratifies across functional safety certification tiers, with SIL 3 / PLe rated master devices capturing margin premiums against uncertified alternatives. Pricing pressure stems from raw material volatility in copper and semiconductor transceiver components, eroding hardware margins at the economy tier. Consumer electronics assemblers in China's Pearl River Delta exhibit acute price sensitivity, while pharmaceutical production buyers prioritize IP69K validation documentation over per-point cost.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Shanghai, and Chicago anchor hub-and-spoke fulfillment patterns for AS-Interface hardware, with German producers maintaining captive inventory for European automotive just-in-time programs. Manufacturing concentrates in Germany, China, and the United States, with semiconductor transceiver fabrication drawing from Taiwan and South Korea. Raw material dependencies span copper cathodes, epoxy molding compounds, and ASIC silicon. Single-source vulnerability in safety-certified ASIC design concentrates with German and Austrian engineering clusters. Distribution runs through system integrator channel partners who bundle hardware with commissioning services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Functional safety engineering scarcity props AS-Interface pricing power, with SIL 3 certification capacity constrained to Bavarian and Austrian automation clusters that limit supply expansion.
For Market Incumbents: Lock in backward integration into ASIC design to secure transceiver component supply against semiconductor allocation volatility. Anchor channel control through exclusive system integrator partnerships in China's Yangtze River Delta, where domestic specification authority is displacing foreign OEM procurement influence. Prioritize certification investment in GB standards alignment for MIIT compliance windows. For New Entrants and Emerging Players: The premium-to-economy price-point gap in safety-integrated master devices opens white-space entry for mid-tier SIL 2 certified alternatives targeting India's PLI-funded automotive assembly lines. Target process-control diagnostic communication modules in North American metal fabrication, where configuration margin premiums exceed automotive volume plays. Pursue go-to-market alignment with regional automation houses bundling hardware with commissioning services. For Investors and Strategic Acquirers: METI's industrial digitalization roadmap accelerating legacy parallel wiring replacement is the leading indicator that Japanese machine tool retrofit demand is inflecting toward sensor-level networking architectures. Position for 5-10 year viability around semiconductor specialists with captive ASIC design capabilities and safety certification portfolios. Acquisition target archetype: regional automation houses with embedded system integrator relationships in underpenetrated manufacturing corridors. Watch China's GB standards evolution as the signal for compliance investment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into ASIC Design | Captive transceiver supply secures margins against semiconductor allocation volatility from Taiwan foundries. |
| SIL 3 Certification Expansion | German KBA enforcement of Machinery Regulation mandates functional safety ratings for collaborative robot market access. |
| System Integrator Channel Partnerships | Domestic specification authority in China's Yangtze River Delta compresses procurement cycles for foreign joint ventures. |
| GB Standards Alignment Investment | MIIT dual carbon goals filter supplier selection toward energy-efficient architectures in greenfield plants. |
| Hybrid IO-Link Convergence Development | Intelligent sensor communication opens process-control adjacent applications beyond discrete manufacturing. |
Research Approach
Multi-period observation of sensor proliferation rates, certification timeline extensions, and copper price volatility anchored the trend analysis, supplemented by interviews with factory automation procurement directors, plant engineers at automotive Tier-1 suppliers, system integrator specification leads, and semiconductor component sales managers. Secondary validation drew from IEC 62026 certification databases, EU F-Gas Regulation implementation notices, MIIT industrial policy disclosures, and customs trade data for AS-Interface hardware categories. Bottom-up module shipment tracking triangulated against top-down factory automation capital expenditure surveys.
Segment-weighting approaches distributed value across master devices, slave modules, and power supply hardware tiers, with technology splits between wired bus systems, safety-integrated architectures, and wireless alternatives. Application segmentation captured factory automation, material handling, and process control deployment patterns. End-use industry weights reflected automotive manufacturing concentration against pharmaceutical and food processing regulatory premiums. CAGRs derived from installed base expansion modeling and replacement cycle analysis across the projection horizon. Forecast inputs incorporated Machinery Regulation enforcement timelines and China's smart-manufacturing investment trajectories.
Inputs from certification body disclosure filings and national regulator implementation notices were available through the study window; gaps in real-time inventory positioning data from Chinese distribution channels introduce uncertainty bands around short-term pricing trajectory assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Connectors
Automotive Data Connectors Market
Connectors
Hybrid Fiber Optic Connectors Market
Connectors
Global Automotive Connector Market
Connectors
Connector and Terminal Systems for Harsh Environment Wiring Market
Connectors
Connector Kits Market
Connectors
India Connector Market
Connectors
IC Socket Market
Connectors
Global Multi Coaxial Connectors Market
Connectors
Liquid Cooling Connector Market
Connectors
Underwater Mate Connectors Market
Connectors
Line Clamp Market
Connectors
Connector Market
Connectors
Middle East Connector Market
Connectors
Space Grade Connectors Market
Connectors
Filtered Connectors Market
Connectors
Pin Retainer Market