
 Mexico Connector Market | 2026-2036
Mexico Connector Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Connector Market Insights
Modular connector bundling is repositioning procurement patterns across Mexican manufacturing clusters. Yazaki Corporation leverages its vertical integration into wire harness and connector production to dominate supply relationships with automotive assemblers in central Mexico. TE Connectivity Ltd. anchors its position through R&D intensity focused on high-voltage interconnect architectures for electrified platforms. Amphenol Corporation specializes in ruggedized circular connectors serving aerospace and defense channels that require ITAR-compliant supply chains.
Connectors are electromechanical devices engineered to establish removable electrical pathways between circuits, typically specified by contact pitch, current-carrying capacity, insertion force, and environmental sealing ratings per IP or MIL-STD classifications. Wire-to-Board configurations sustain the largest volume footprint in Mexico due to proliferation of PCB-centric consumer electronics and telecom infrastructure assembly. Board-to-Board interconnects lead margin pools as data-center and server-farm builds in Querétaro demand denser pitch tolerances and signal-integrity performance. Surface Mount Technology competes with Through Hole methods in automotive applications where vibration resistance and thermal cycling requirements dictate joint reliability standards.
Secretaría de Economía oversees NOM compliance for electrical component safety, while PROFEPA enforces environmental regulations affecting plating and coating processes in connector fabrication. The USMCA rules of origin framework shapes demand by mandating regional value content thresholds that redirect sourcing toward North American qualified suppliers. Stakeholders must monitor evolving energy-transition mandates from CRE and CENACE that will rewire connector specifications across solar inverter and battery storage integration projects.
Market Dynamics
Electric vehicle assembly expansion across central Mexico is restructuring connector procurement, with NOM-001-SEDE electrical safety standards and USMCA regional content rules forcing qualification upgrades across supplier networks.
Growth Catalysts
- USMCA Regional Value Content:North American sourcing mandates redirect procurement toward qualified suppliers in Querétaro and Guanajuato, tightening cross-border component flows.
- Automotive Electrification:OEMs expanding EV lines in Aguascalientes drive procurement of high-voltage interconnect architectures for battery and powertrain integration.
- NOM-001-SEDE Compliance:Stricter electrical safety certification requirements under Secretaría de Economía oversight accelerate replacement cycles in legacy installations.
Market Restraints
- Copper Price Volatility:Raw material cost swings in global commodity markets compress margin pools for contact and terminal fabricators.
- Asian Supplier Concentration:Dominance of specialized plating and precision stamping capacity in East Asia creates supply vulnerability for Mexican assemblers.
- Technical Limitation in Miniaturization:Denser pitch tolerances below 0.4mm face yield constraints in high-volume automotive applications.
Strategic Opportunities
- Solar and Battery Storage Integration:CRE and CENACE energy-transition mandates rewire connector specifications across inverter and grid-tied storage projects in northern Mexico.
- Defense and Aerospace Channels:ITAR-compliant supply chains for ruggedized circular connectors serve underpenetrated military electronics procurement.
- Modular Bundling Models:Wire harness and connector package contracts displace discrete component purchasing in Bajío automotive corridors.
Industry Challenges
- Certification Timeline Compression:PROFEPA environmental regulations for plating processes extend qualification cycles beyond OEM launch windows.
- High-Voltage Skill Scarcity:Shortage of engineers trained in 800V+ interconnect safety protocols constrains R&D staffing for electrified platforms.
- Legacy System Integration:Through Hole methods persist in maintenance networks, complicating Surface Mount Technology migration for vibration-critical applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Connector Market |
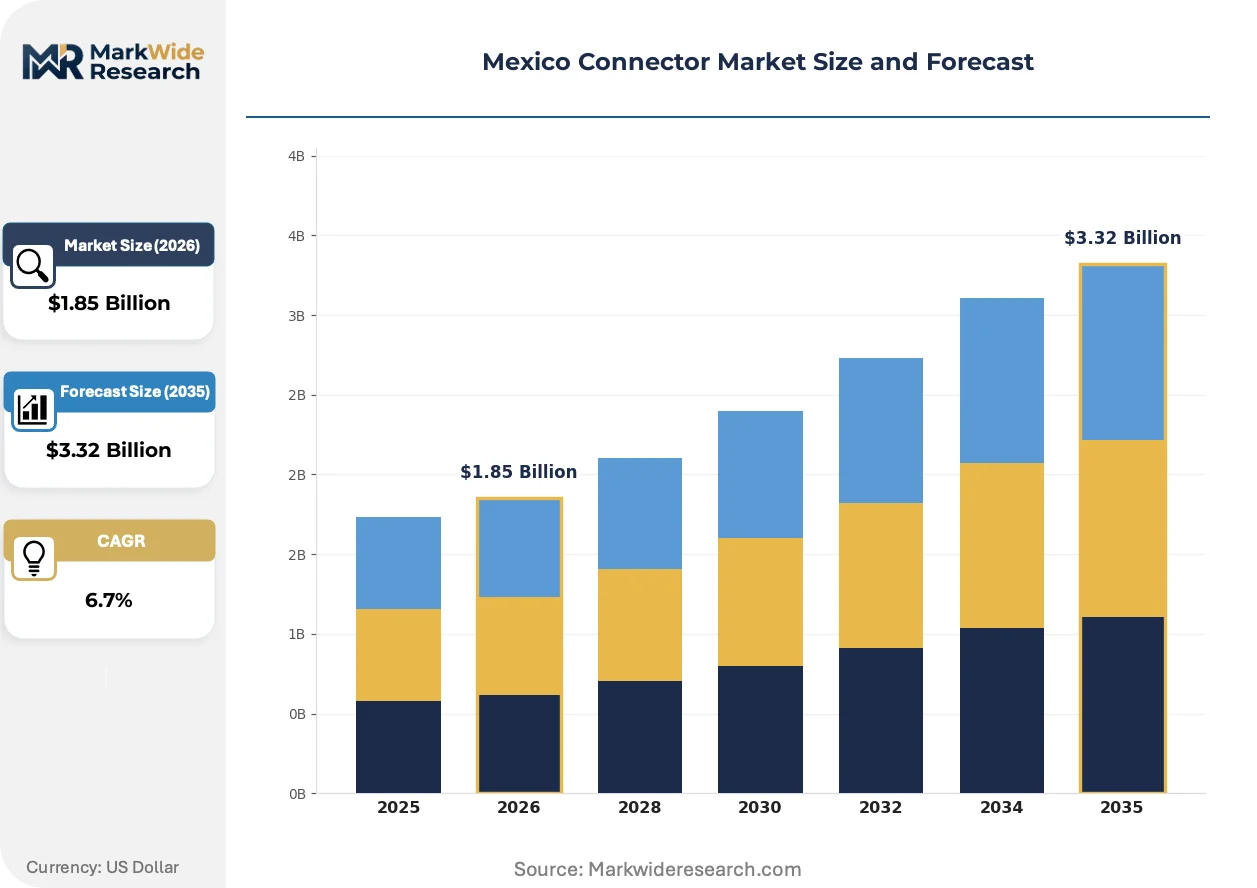
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.32 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wire-to-Board, Board-to-Board, Coaxial, Circular, Rectangular, D-Sub Technology: Surface Mount, Through Hole, Wire Wrap, Press Fit, Solderless Application: Consumer Electronics, Aerospace Systems, Telecommunications, Renewable Energy, Automotive OEMs, Defense Equipment End User: Original Equipment Manufacturers, Electronic Contract Manufacturers, System Integrators, Independent Repair Providers |
| Companies Covered | Yazaki Corporation, Japan Aviation Electronics Industry, Ltd., TE Connectivity Ltd., Phoenix Contact, Hirose Electric Co. Ltd., Amphenol Corporation, Aptiv PLC, Foxconn Interconnect Technology Limited, Molex LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Connector Market Trends and Innovations
Connector architectures in Mexico are pivoting toward high-voltage platforms and modular procurement structures, with regulatory alignment and supply chain reconfiguration as concurrent forces.
High-voltage interconnect technology is converging with automotive platform electrification. OEMs in Guanajuato and Querétaro are adopting 800V+ capable contact systems for next-generation EV architectures. This convergence is compressing development cycles for traditional low-voltage connector portfolios while expanding R&D allocation toward thermal management and arc suppression engineering.
NOM-001-SEDE electrical safety standards under Secretaría de Economía oversight are tightening insulation and creepage distance requirements. Industrial consequence includes mandatory recertification for existing product lines serving consumer electronics and telecom infrastructure. Wire-to-Board configurations in PCB-centric assembly operations face the steepest compliance cost adjustments.
Automotive assemblers are consolidating supplier relationships around bundled wire harness and connector packages. Discrete component distributors in central Mexico are losing share to vertically integrated subsystem contractors. This pattern concentrates most visibly in the Bajío corridor, where Yazaki and similar suppliers anchor tier-one procurement relationships.
Mexico Connector Market Segmentation
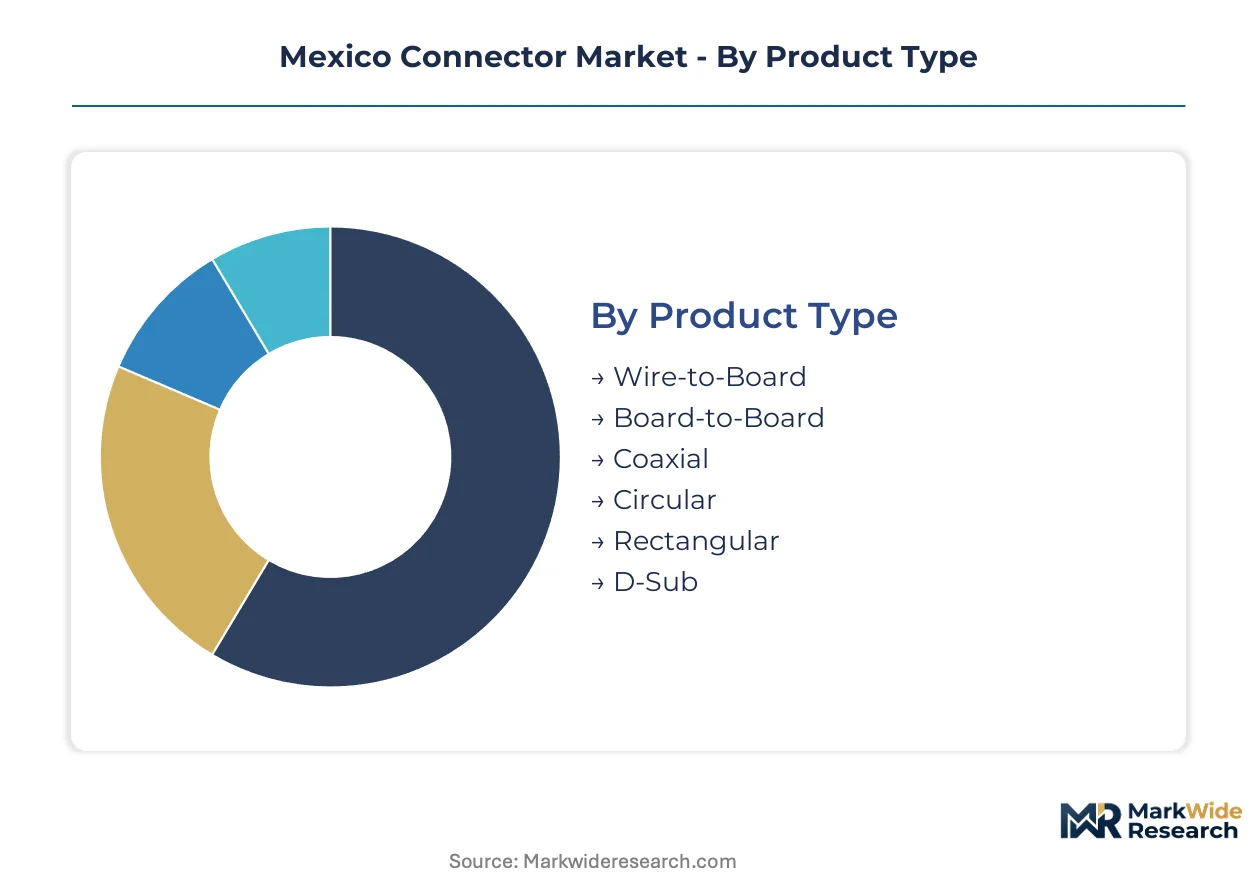
Connector procurement in Mexico fragments across technical specifications, assembly methods, and end-use requirements that reshape supplier qualification priorities. Understanding how demand concentrates within each dimension clarifies where capacity investments and certification efforts yield competitive advantage.
Product Type:
Supply concentration in the Bajío automotive corridor and Querétaro electronics clusters dictates which connector geometries dominate procurement volumes.
- Wire-to-Board:Configurations establish removable electrical pathways between cable assemblies and printed circuit boards, typically specified by contact pitch and current-carrying capacity. PCB-centric consumer electronics and telecom infrastructure assembly in Querétaro absorb the largest volume footprint, driven by NOM-001-SEDE compliance costs that accelerate replacement cycles in legacy installations.
- Board-to-Board:Interconnects enable signal transmission between adjacent PCBs without intermediary cabling, requiring denser pitch tolerances and signal-integrity performance. Data-center and server-farm builds in Querétaro concentrate demand, with margin pools expanding as electrified platforms require higher-density architectures.
- Coaxial:Cylindrical connectors maintain controlled impedance for radio frequency signal transmission in telecommunications infrastructure.
- Circular:Ruggedized housings with threaded coupling mechanisms serve aerospace and defense channels requiring ITAR-compliant supply chains.
- Rectangular:High-pin-count configurations dominate automotive harness applications where space efficiency and modularity intersect.
- D-Sub:Trapezoidal shell connectors persist in industrial automation and legacy military equipment maintenance networks.
Wire-to-Board absorbs the bulk of installed capacity; Board-to-Board is expanding most quickly.
Technology:
Cost tier differentiation separates premium automated assembly methods from labor-intensive alternatives that persist in maintenance and low-volume production.
- Surface Mount:Termination technology solders connector leads directly onto PCB pads without through-board penetration, enabling higher component density and automated placement. Automotive applications in Aguascalientes concentrate demand where vibration resistance and thermal cycling requirements dictate joint reliability standards, though migration from Through Hole methods faces legacy system integration challenges.
- Through Hole:Leads pass through drilled PCB holes and solder on the opposite side, providing mechanical anchoring superior to surface-mounted alternatives. Industrial and defense maintenance networks in central Mexico retain significant volume, constrained by certification timeline compression under PROFEPA plating regulations.
- Wire Wrap:Gas-tight connections wrap wire around square posts without soldering, surviving in prototyping and low-volume aerospace applications.
- Press Fit:Compliant pins insert into plated through-holes with controlled interference fit, eliminating solder processes in high-reliability telecom infrastructure.
- Solderless:Insulation displacement and crimp technologies accelerate field installation in modular wire harness bundles across Bajío automotive corridors.
Through Hole retains the deepest installed base in maintenance networks; Surface Mount commands the steepest expansion trajectory in new automotive platforms.
Application:
Customer type maturity separates established OEM procurement from emerging channel opportunities that rewire supplier relationship structures.
- Automotive OEMs:Assembly operations demand high-voltage interconnect architectures for battery and powertrain integration as EV lines expand across Aguascalientes and Guanajuato. OEMs are consolidating supplier relationships around bundled wire harness and connector packages, displacing discrete component distributors.
- Consumer Electronics:Assembly of smartphones, laptops, and peripherals in Baja California and Tijuana concentrates Wire-to-Board procurement for PCB-centric manufacturing.
- Aerospace Systems:Commercial aviation and satellite subsystems require circular and rectangular connectors with extended temperature ranges and shock resistance.
- Telecommunications:5G infrastructure and data-center builds in Querétaro drive Board-to-Board demand for signal-integrity performance.
- Renewable Energy:Solar inverter and battery storage integration projects in northern Mexico rewire connector specifications under CRE and CENACE energy-transition mandates.
- Defense Equipment:ITAR-compliant supply chains for ruggedized circular connectors serve underpenetrated military electronics procurement channels.
Automotive OEMs absorb the bulk of installed capacity; Renewable Energy is climbing the fastest on energy-transition policy tailwinds.
End User:
Margin structure varies sharply between captive production, contract manufacturing, and aftermarket channels that reshape pricing discipline.
- Original Equipment Manufacturers:Vertically integrated assemblers in the Bajío corridor procure connectors as part of bundled subsystem contracts rather than discrete components. Yazaki and similar suppliers anchor tier-one procurement relationships, compressing development cycles for traditional low-voltage portfolios while expanding R&D allocation toward thermal management.
- Electronic Contract Manufacturers:Flex, Jabil, and Foxconn operations across Mexico absorb standardized connector volumes for multi-client electronics assembly, prioritizing cost and availability over customization.
- System Integrators:Industrial automation and infrastructure project contractors specify connectors for customized installations in renewable energy and telecommunications deployments.
- Independent Repair Providers:Aftermarket maintenance networks for automotive and industrial equipment retain demand for Through Hole and legacy D-Sub configurations, complicating Surface Mount Technology migration.
Electronic Contract Manufacturers absorb the bulk of standardized volume; System Integrators are gaining share fastest on renewable energy and telecom infrastructure builds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Connector production in Mexico concentrates in central manufacturing corridors while consumption spreads across automotive, electronics, and energy infrastructure end uses. The Bajío region anchors assembly capacity for automotive OEMs, whereas northern border states absorb cross-border electronics manufacturing. Regulatory alignment with USMCA and NOM standards shapes regional investment flows.
Bajío Region
Automotive electrification programs in Aguascalientes and Guanajuato drive procurement of high-voltage interconnect systems for battery and powertrain integration. NOM-001-SEDE electrical safety standards under Secretaría de Economía oversight mandate recertification for supplier networks serving OEM assembly lines. Querétaro anchors the densest concentration of wire harness and connector bundling contracts, with Yazaki and similar suppliers consolidating tier-one procurement relationships.
Nuevo León
Appliance and industrial equipment manufacturers in Monterrey sustain demand for rectangular and circular connector configurations in automation systems. PROFEPA environmental regulations extend qualification timelines for plating and coating processes, compressing development cycles for new product introductions. The Monterrey metro area hosts electronics assembly operations that source standardized connector volumes for multi-client contract manufacturing.
Northern Border States
Consumer electronics assembly in Baja California and Tijuana concentrates Wire-to-Board procurement for PCB-centric smartphone and laptop manufacturing. USMCA regional value content rules redirect sourcing toward North American qualified suppliers, tightening cross-border component flows from Asian plating specialists. The Tijuana-San Diego corridor functions as a logistics hub for connector inventory staging and rapid fulfillment to US electronics assemblers.
Jalisco
Telecommunications infrastructure and aerospace subsystems in Guadalajara generate demand for Board-to-Board and ruggedized circular connectors. CRE and CENACE energy-transition mandates rewire connector specifications for solar inverter integration projects spreading across the state. The Guadalajara metro area anchors ITAR-compliant supply chain nodes for defense electronics channels requiring specialized circular connector fabrication.
Mexico City Metro
System integrators and independent repair providers in the capital retain demand for legacy Through Hole and D-Sub configurations in maintenance networks. The central location supports distribution logistics for connector inventories serving industrial automation projects nationwide. Mexico City's concentration of engineering services firms supplies technical support for high-voltage interconnect safety protocol implementation across electrified automotive platforms.
Mexico Connector Market Competitive Landscape
The competitive structure tilts toward vertically integrated subsystem contractors over discrete component distributors. Japanese and American suppliers anchor tier-one relationships with automotive OEMs through bundled wire harness and connector packages. Three archetypes dominate: integrated harness-connector producers, high-voltage interconnect specialists, and ruggedized circular connector fabricators. Competitive moves concentrate on backward integration into precision stamping and captive plating capacity, plus geographic co-location with OEM assembly corridors.
Among Japanese-origin suppliers, Yazaki Corporation and Japan Aviation Electronics Industry exemplify the integrated production archetype through captive wire harness and connector manufacturing. TE Connectivity Ltd. represents the high-voltage specialization vector with R&D intensity focused on electrified platform architectures. Amphenol Corporation anchors the ruggedized circular connector segment serving aerospace and defense channels requiring ITAR-compliant supply chains.
| Leading Market Players |
|---|
| Yazaki Corporation |
| Japan Aviation Electronics Industry, Ltd. |
| TE Connectivity Ltd. |
| Phoenix Contact |
| Hirose Electric Co. Ltd. |
| Amphenol Corporation |
| Aptiv PLC |
| Foxconn Interconnect Technology Limited |
| Molex LLC |
| Others |
Pricing and Supply Chain Analysis
Precision stamping and plating engineers concentrated in Querétaro and Guanajuato command wage premiums that compress margin spreads between economy-grade and high-reliability connector tiers. NOM-001-SEDE recertification costs and PROFEPA environmental compliance create fixed-cost barriers that amplify pricing differentiation across supplier qualification levels.
Pricing Analysis
Cost-down pressure on standard-grade interconnects accelerates because Asian stamping capacity floods commodity segments while Mexican assemblers absorb USMCA regional content premiums. Three-tier pricing structure across ITAR-compliant, automotive-qualified, and economy commercial levels separates buyers by certification burden and volume scale. OEMs in Aguascalientes exhibit highest price sensitivity due to bundled wire harness procurement consolidating purchase power. Defense aerospace channels show lowest sensitivity given ITAR compliance scarcity and single-source qualification timelines.
Supply Chain Analysis
Regional distribution centers in Querétaro and Monterrey operate hub-and-spoke patterns feeding just-in-sequence delivery to Bajío automotive corridors and Tijuana electronics clusters. Manufacturing concentration in China, Japan, and Germany supplies precision stamping dies and specialized plating chemistry that Mexican fabricators draw from under long-term technical service agreements. Single-source vulnerability concentrates in high-purity copper rod and palladium-nickel plating salts subject to commodity price volatility. Distribution runs through tier-one subsystem contractors displacing discrete component distributors in automotive procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
NOM-001-SEDE electrical safety standards and PROFEPA plating regulations erect compliance moats that favor incumbent suppliers with captive certification infrastructure and environmental permitting.
For Market Incumbents: Anticipate margin compression from Asian commodity suppliers by deepening backward integration into precision stamping and captive plating capacity in Guanajuato. Anchor tier-one relationships through bundled wire harness-connector packages that displace discrete component distributors. Prioritize R&D allocation toward 800V+ thermal management architectures as EV platforms proliferate across Aguascalientes assembly lines. For New Entrants and Emerging Players: High-voltage interconnect safety protocols offer a technology-first wedge into electrified automotive procurement underserved by legacy low-voltage portfolios. Target renewable energy system integrators in Jalisco and northern Mexico where CRE mandates rewire connector specifications for solar inverter and battery storage integration. Pursue ITAR-compliant circular connector fabrication for defense channels with qualification timelines that deter commodity competitors. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated subsystem contractors given USMCA regional value content rules tightening cross-border component flows. Long-term viability centers on suppliers co-located with OEM assembly corridors possessing captive environmental permitting and NOM certification infrastructure. Monitor CENACE energy-transition mandate acceleration as inflection signal for grid-tied storage connector demand scaling.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Stamping | Captive die production reduces Asian supplier dependency for Yazaki-tier automotive contracts. |
| High-Voltage Interconnect R&D Expansion | 800V+ thermal management capabilities align with TE Connectivity's electrified platform specialization. |
| ITAR-Compliant Supply Chain Certification | Amphenol's aerospace defense positioning leverages qualification barriers that commodity suppliers cannot replicate. |
| Modular Wire Harness Bundling | Discrete component distributors lose share to subsystem contractors consolidating Bajío procurement relationships. |
| Environmental Permitting Investment | PROFEPA plating compliance accelerates qualification cycles beyond OEM launch windows for permitted facilities. |
Research Methodology
Trade databases, SEC filings from connector manufacturers, and NOM certification registries formed the secondary backbone for market sizing and competitive positioning. Primary interviews with Tier 1 automotive supplier procurement managers, wire harness subsystem contractors, Secretaría de Economía compliance officers, and electronics contract manufacturing operations directors validated demand assumptions and pricing dynamics. Bottom-up and top-down triangulation reconciled production capacity data from Querétaro and Guanajuato industrial parks against OEM bill-of-materials estimates.
Bottom-up volume modeling aggregated connector consumption by vehicle platform, PCB assembly line, and renewable energy project scale across the projection horizon. Top-down validation cross-referenced USMCA trade flow data and copper alloy import volumes to anchor value estimates. Segmentation dimensions included product geometry, termination technology, end-use application, and customer type. CAGRs derived from regression analysis of historical OEM production schedules and electrification program announcements.
Several conditions sit outside the modeled scope, including potential tariff renegotiations affecting USMCA regional value content calculations and unanticipated mineral export restrictions from copper-producing jurisdictions. Forecasts reflect documented assumptions around EV adoption trajectories and energy-transition policy implementation timing. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Connectors
Cable Connectors and Adapters Market
Connectors
Australia Connector Market
Connectors
PCI-E Connectors Market
Connectors
Relay Sockets Market
Connectors
Connector Kits Market
Connectors
Global Wired Interface Market
Connectors
Terminal Pins Market
Connectors
Micro-Miniature Co-Axial Adapter Market
Connectors
Power Connector Market
Connectors
USB Type-C Market
Connectors
Canada Connector Market
Connectors
Smart Crimper Market
Connectors
Automotive Data Connectors Market
Connectors
Connector Adapter Kits Market
Connectors
Underwater Mate Connectors Market
Connectors
Press Fit Connector Market