
 Terminal Pins Market | 2026-2036
Terminal Pins Market Size, Share, and Industry Trends Forecast 2026-2036
Terminal Pins Market Insights
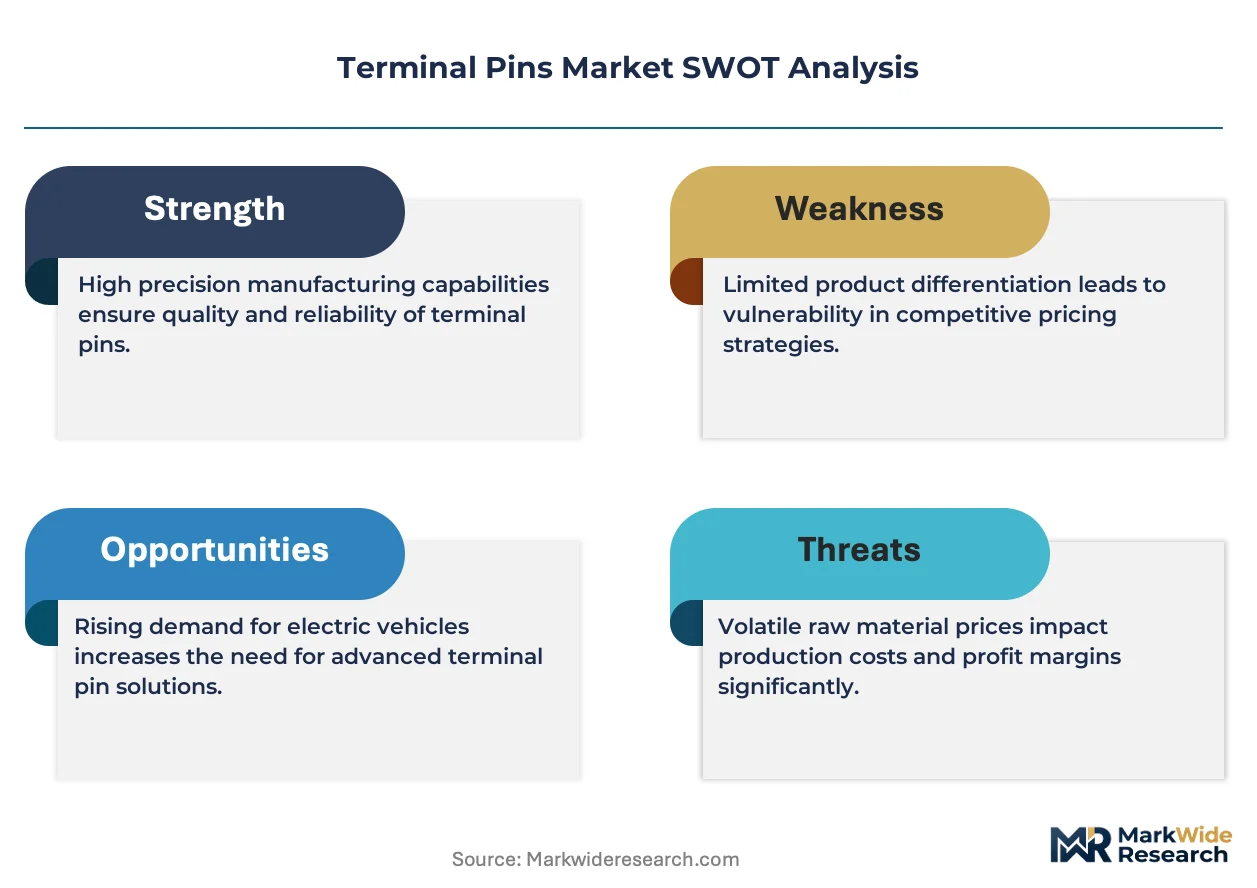
EU REACH restrictions on cadmium and lead content in electrical components is shifting procurement specifications across European automotive supply chains. TE Connectivity leverages captive metallurgy labs to qualify compliant plating chemistries ahead of enforcement deadlines. Molex anchors its European production footprint in Czech Republic and Slovakia to sustain just-in-time delivery to German OEMs. Yazaki competes through vertical integration into wire-harness assembly, controlling downstream demand pull for its proprietary pin architectures.
Terminal pins are precision-machined or stamped conductive elements, typically manufactured from brass or copper alloys with tin, nickel, or gold plating, designed to establish removable electrical connections between circuit boards, cables, and device housings. Surface mount pins are gaining share in miniaturized consumer electronics where PCB real estate commands premium value, while through hole pins retain dominance in industrial equipment subject to mechanical stress and thermal cycling. Brass remains the volume leader in material selection due to favorable machinability and conductivity balance, though stainless steel is displacing legacy alloys in medical devices where sterilization compatibility and corrosion resistance define specification thresholds.
FDA device classification rules for active implantable electronics impose traceability and biocompatibility requirements on terminal pin suppliers serving medical device OEMs. EPA hazardous waste regulations govern plating shop effluent in US manufacturing, elevating capital requirements for domestic surface treatment capacity. ISO 13485 quality management standards shape supplier qualification protocols across medical and automotive segments alike. Stakeholders must monitor evolving RoHS exemptions for high-reliability applications, as sunset reviews could force rapid alloy transitions in aerospace and defense-adjacent product lines.
Market Dynamics
Automotive electrification is compressing development cycles for terminal pin architectures as battery management systems demand higher current density and thermal resilience than legacy internal combustion platforms required.
Growth Catalysts
- Battery Management System Expansion:Electric vehicle powertrains require terminal pin counts per vehicle to multiply across high-voltage interconnects, DC-DC converters, and cell monitoring modules.
- REACH Phase-Out Deadlines:ECHA restrictions on cadmium and lead in electrical components are accelerating qualification of compliant plating chemistries ahead of enforcement windows.
- Supplier Park Proximity:German OEM clustering around Stuttgart and Wolfsburg creates localized demand pull for just-in-time terminal pin delivery.
Market Restraints
- Copper Price Volatility:Brass and copper alloy feedstock costs fluctuate with London Metal Exchange pricing, compressing margin stability for stamping and machining operations.
- Plating Capacity Concentration:Surface treatment shops capable of high-reliability gold and nickel deposition concentrate in East Asia, creating single-source vulnerability for European and North American terminal manufacturers.
- RoHS Exemption Uncertainty:Sunset reviews for high-reliability aerospace and defense applications threaten forced alloy transitions before alternative materials complete qualification cycles.
Strategic Opportunities
- Medical Device Biocompatibility:Active implantable electronics under FDA device classification rules impose traceability requirements that qualified suppliers can monetize through premium positioning.
- Stainless Steel Substitution:Sterilization-compatible alloys are displacing legacy brass in surgical equipment where corrosion resistance defines specification thresholds.
- Surface Mount Miniaturization:Consumer electronics PCB real estate constraints favor compact pin geometries that reduce material intensity per connection point.
Industry Challenges
- Plating Chemistry Transition:Lead-free and cadmium-free surface treatments require capital-intensive line conversions and extended customer requalification timelines.
- ISO 13485 Certification Burden:Medical and automotive supplier qualification protocols demand documented quality management systems that smaller stamping houses struggle to maintain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Terminal Pins Market |
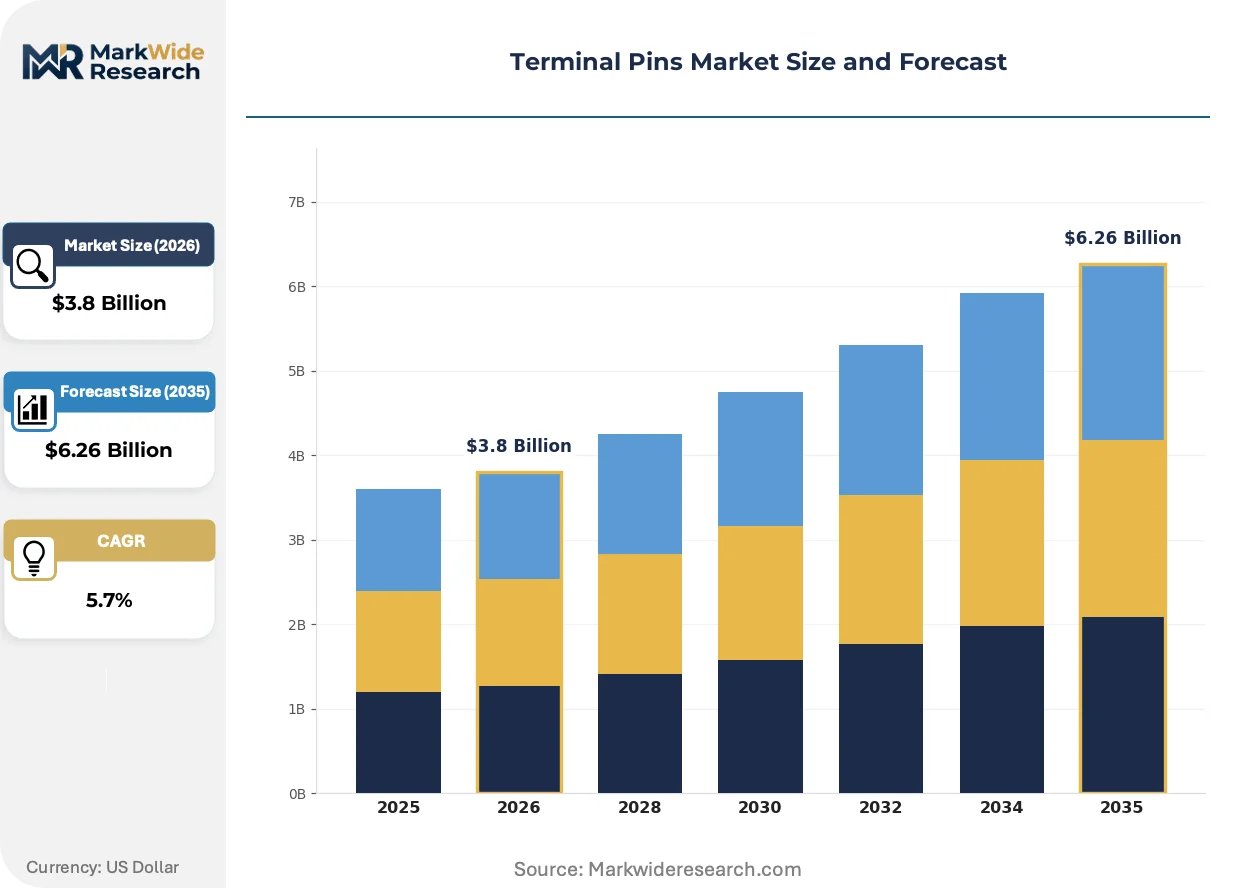
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Through Hole Pins, Surface Mount Pins, Female Pins, Male Pins Material: Brass, Copper, Stainless Steel, Aluminum Application: Automotive, Consumer Electronics, Industrial Equipment, Medical Devices Connection Type: Crimp, Solder, Screw, Plug |
| Companies Covered | TE Connectivity, Amphenol, Molex, Aptiv, Foxconn Interconnect Technology, Luxshare Precision, Yazaki, Rosenberger, JST, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Terminal Pins Market Trends and Innovations
Terminal pin manufacturing is pivoting toward material-light designs and compliant surface chemistries as end-use specifications tighten across electrified transport and regulated medical devices.
Stamped contact geometries with integrated retention features are integrating into single-piece designs that eliminate secondary assembly operations. Automotive tier-one suppliers are adopting these architectures for high-volume battery interconnect programs. The consolidation of machining and forming steps is integrating cost reduction with throughput gains.
EPA hazardous waste regulations governing plating shop effluent are elevating capital requirements for domestic surface treatment capacity in the United States. Shops must install closed-loop wastewater recovery and sludge handling systems to maintain operating permits. Medical device OEMs sourcing from US-based suppliers face extended lead times as compliant plating capacity lags demand.
Consolidated supplier contracts are compressing vendor counts as automotive OEMs reduce qualification overhead. Tier-one connector manufacturers are absorbing terminal pin sourcing decisions previously delegated to harness assemblers. German automotive supply chains exhibit the most pronounced concentration, with single-source agreements replacing dual-qualified arrangements.
Terminal Pins Market Segmentation
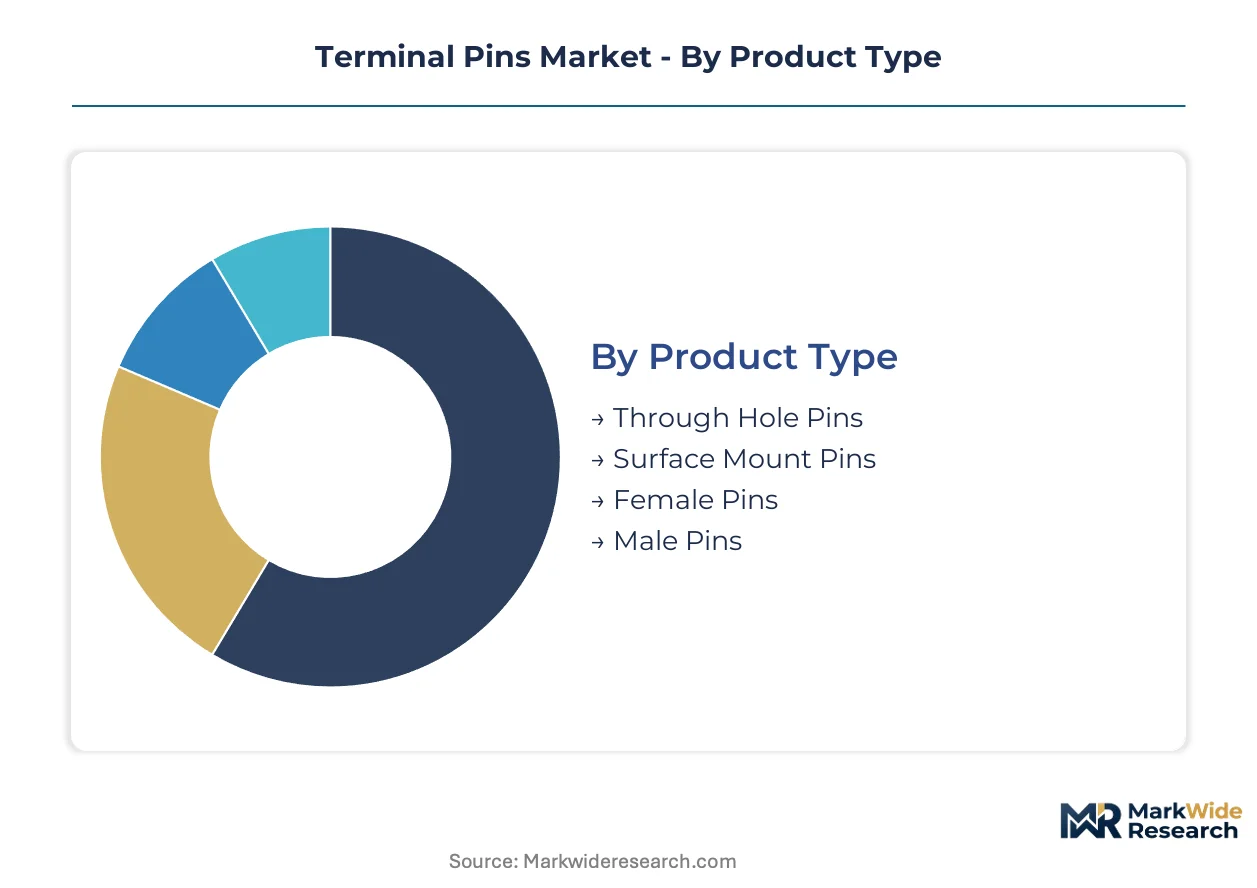
Terminal pin architectures diverge sharply between standalone discrete components and embedded connector systems, with integration depth determining specification rigor, qualification cycles, and supplier relationship intensity across automotive, medical, and industrial end-uses.
Product Type:
Standalone pin formats dominate high-reliability applications requiring field serviceability, while surface mount variants embed permanently into densely packed PCB assemblies where repair access is sacrificed for space efficiency.
- Through Hole Pins:These pins penetrate PCB substrates and secure via solder fillets on opposite faces, delivering mechanical robustness against vibration and thermal cycling. Automotive powertrain modules in Stuttgart supplier parks specify through hole termination for high-current battery interconnects where joint integrity is non-negotiable.
- Surface Mount Pins:Flattened gull-wing or J-lead geometries solder directly to pad surfaces, minimizing vertical clearance. Consumer electronics OEMs in South Korea and Taiwan specify these for smartphone and wearable assemblies where every millimeter of Z-height is contested.
- Female Pins:Receptacle-style contacts designed to accept mating male pins, often incorporating spring retention features for repeated mating cycles.
- Male Pins:Protruding contact posts that insert into female receptacles, typically formed from solid wire or stamped strip with precision tip geometries.
Volume placements concentrate in through hole formats for automotive and industrial durability requirements; the faster expansion belongs to surface mount geometries as consumer electronics miniaturization accelerates.
Material:
Material selection tracks a cost-performance-biocompatibility hierarchy, with commodity alloys serving high-volume automotive programs and premium metallurgies penetrating regulated medical and aerospace channels.
- Brass:Copper-zinc alloys balance electrical conductivity against machinability and cost, making them the default for stamped and machined pins across automotive and industrial volumes. German OEM supplier parks consume brass terminal pins by the billion-piece scale for wire harness assemblies.
- Copper:Pure or oxygen-free copper delivers maximum conductivity for high-current applications, though softness requires nickel underplating to prevent mechanical deformation. Battery management system architects specify copper pins for DC fast charging interconnects where I²R losses directly impact thermal budgets.
- Stainless Steel:Austenitic grades provide sterilization compatibility and corrosion resistance for surgical instruments and implantable devices under FDA oversight.
- Aluminum:Lightweight alternative for aerospace and weight-sensitive transport applications, though oxide formation complicates reliable electrical contact without specialized plating.
Brass retains the dominant placement position across automotive and industrial procurement; stainless steel is climbing the fastest as FDA device classification rules tighten biocompatibility requirements on active implantable electronics.
Application:
End-use segmentation reflects divergent regulatory exposure, with automotive and medical channels imposing qualification burdens that filter supplier participation while consumer electronics rewards speed-to-volume.
- Automotive:Terminal pins populate battery management systems, power distribution centers, and sensor harnesses across internal combustion and electric vehicle platforms. Electrification multiplies pin counts per vehicle as high-voltage architectures proliferate.
- Consumer Electronics:Smartphones, laptops, and wearables demand miniaturized surface mount pins with tight pitch tolerances and RoHS-compliant finishes.
- Industrial Equipment:Programmable logic controllers, motor drives, and robotics require through hole pins that withstand mechanical stress and extended thermal cycling in factory environments.
- Medical Devices:Active implantables and surgical equipment impose ISO 13485 quality systems and traceability requirements that qualified suppliers monetize through premium positioning against commodity competitors.
Automotive procurement generates the deepest volume commitments; medical device qualification barriers are producing the steepest margin expansion trajectory for certified suppliers.
Connection Type:
Attachment mechanics determine assembly automation compatibility, field serviceability, and joint reliability under environmental stress, with permanent methods favored in sealed systems and removable formats in serviceable equipment.
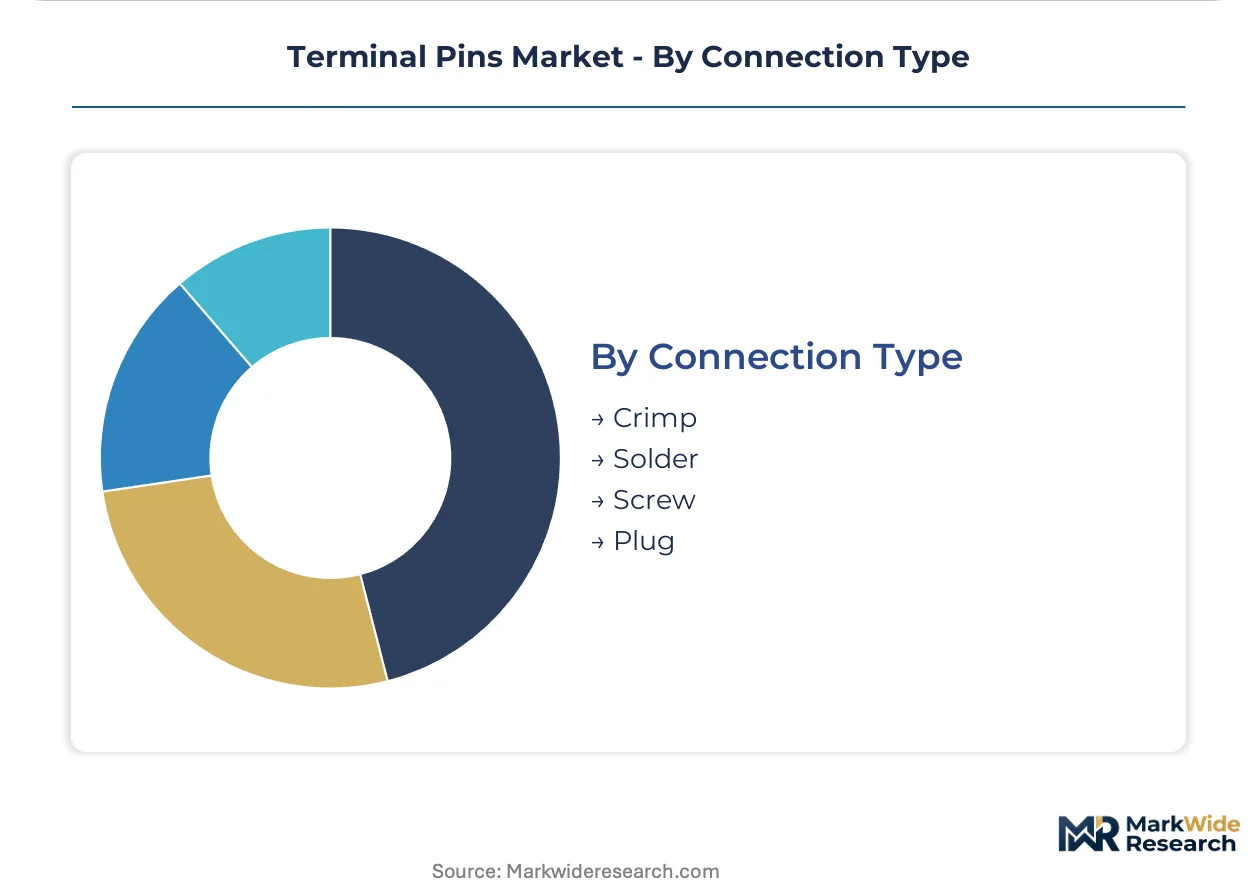
- Crimp:Mechanical compression of terminal barrels onto stripped wire conductors creates gas-tight joints without thermal exposure to insulation. Automotive harness assemblers in Czech Republic and Slovakia deploy crimp terminals at million-piece daily rates.
- Solder:Metallic fusion of pin to PCB pad or wire, delivering electrical continuity and mechanical retention in a single operation. Surface mount and through hole pins both terminate via solder reflow or wave processes.
- Screw:Threaded mechanical clamping allows field termination and reconfiguration, common in industrial terminal blocks and power distribution equipment.
- Plug:Mating connector pairs enable rapid assembly and disassembly, with pin contacts housed in insulating bodies that ensure polarization and environmental sealing.
Crimp and solder dominate high-volume manufacturing; plug-style separable interfaces are gaining share fastest in modular equipment architectures requiring field upgradeability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of terminal pins concentrates in East Asian stamping and plating corridors, while consumption tilts toward German automotive clusters and North American medical device corridors. This geographic split creates supply chain latency that shapes inventory positioning and qualification protocols.
United States
Medical device OEMs in Minneapolis and Boston corridors drive demand for ISO 13485-certified stainless steel pins under FDA active implantable regulations. EPA hazardous waste rules constrain domestic plating capacity expansion, forcing OEMs to source surface-treated components from offshore shops. The Southeast automotive belt around Tennessee and South Carolina absorbs through-hole terminals for EV battery assembly plants.
Germany
Stuttgart and Wolfsburg supplier parks generate concentrated demand pull for brass terminal pins in wire harness and powertrain applications. ECHA REACH phase-out deadlines for cadmium and lead accelerate plating chemistry transitions across tier-one connector suppliers. Bavarian precision machining clusters around Munich qualify lead-free surface treatments ahead of enforcement windows.
China
MIIT industrial standards and dual carbon goals reshape plating shop environmental compliance in Guangdong and Jiangsu provinces. Pearl River Delta stamping houses supply surface mount pins to consumer electronics OEMs in Shenzhen and Dongguan. Yangtze River Delta clusters around Shanghai concentrate high-volume brass pin production for automotive export programs.
Japan
METI industrial policy supports miniaturization R&D for consumer electronics terminal geometries in Kansai corridor facilities. Osaka-based connector specialists supply gull-wing surface mount pins to smartphone manufacturers. Nagoya automotive clusters consume through-hole terminals for hybrid powertrain modules under JIS quality standards.
South Korea
MFDS medical device regulations and METI-aligned industrial standards shape biocompatibility requirements for Seoul-based implantable electronics suppliers. Busan-Ulsan automotive corridors absorb high-current copper pins for battery electric vehicle platforms. Samsung and LG supply chain proximity drives just-in-time delivery specifications for surface mount components.
Terminal Pins Market Competitive Landscape
The competitive structure tilts toward diversified interconnect specialists with captive metallurgy capabilities. Consolidation pressure runs high as automotive OEMs reduce vendor counts and absorb sourcing decisions previously delegated to harness assemblers. Three archetypes dominate: integrated connector manufacturers with in-house stamping and plating, specialized terminal pin pure-plays serving medical and aerospace niches, and diversified electronics fabricators leveraging scale across consumer and industrial segments. Capacity expansion and strategic partnerships constitute the primary competitive moves, with qualification timelines for new plating chemistries acting as a barrier to rapid share shifts.
Among diversified interconnect specialists, TE Connectivity, Molex, and Yazaki exemplify archetypes spanning the competitive spectrum. TE Connectivity occupies a position defined by captive metallurgy laboratory infrastructure. Molex exemplifies geographic positioning strategy through Central European production footprinting. Yazaki represents backward integration into wire-harness assembly as a demand-pull mechanism for proprietary pin architectures. These three anchors illustrate how scale, geographic proximity, and supply chain control differentiate positioning without requiring specific product or financial claims.
| Leading Market Players |
|---|
| TE Connectivity |
| Amphenol |
| Molex |
| Aptiv |
| Foxconn Interconnect Technology |
| Luxshare Precision |
| Yazaki |
| Rosenberger |
| JST |
| Others |
Pricing and Supply Chain Analysis
Brass and copper alloy feedstock costs cascade through three pricing tiers as London Metal Exchange volatility compresses margin stability at stamping operations serving German automotive clusters. Plating chemistry premiums separate qualified suppliers from commodity competitors across REACH-compliant and legacy product lines.
Pricing Analysis
Current density throughput in battery management systems anchors value-based pricing for high-reliability terminal pins. Three-tier pricing structure across premium, standard, and economy levels separates ISO 13485-certified medical grades from automotive commodity volumes and consumer electronics miniaturized formats. Cost compression in standard-grade brass pins is intensifying because OEM supplier parks are consolidating vendor counts. Consumer electronics OEMs exhibit the highest price sensitivity due to PCB real estate constraints, while medical device manufacturers accept premiums for traceability and biocompatibility certification.
Supply Chain Analysis
Container freight rates from Guangdong and Jiangsu provinces to Stuttgart and Wolfsburg corridors directly elevate landed costs for just-in-time automotive programs. High-volume brass stamping concentrates in China, Germany, and the Czech Republic, while gold and nickel plating capacity clusters in East Asian surface treatment shops. Raw material draws from copper concentrate smelters, zinc alloy suppliers, and specialty chemical formulators. Single-source vulnerability in compliant plating chemistry creates structural risk for European manufacturers dependent on Asian deposition capacity. Distribution runs through tier-one connector manufacturers absorbing sourcing decisions previously delegated to harness assemblers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plating capacity scarcity props pricing power for qualified suppliers as REACH enforcement deadlines approach. Automotive OEM consolidation into single-source agreements limits spot-market availability for unqualified entrants.
For Market Incumbents: Deepen captive metallurgy laboratory capabilities to accelerate lead-free and cadmium-free chemistry qualification ahead of ECHA enforcement windows. Add stamping capacity in Bavarian precision machining clusters to secure proximity to Stuttgart and Wolfsburg supplier parks. Consolidation pressure from tier-one connector manufacturers demands documented ISO 13485 quality systems that smaller competitors cannot replicate. For New Entrants and Emerging Players: E-commerce procurement platforms for aftermarket industrial replacement parts offer the lowest barrier to customer access. Target medical device OEMs in Minneapolis and Boston corridors where FDA traceability requirements filter out commodity competitors. Qualify stainless steel pin architectures for active implantable electronics as biocompatibility specifications tighten fastest in this segment. For Investors and Strategic Acquirers: ECHA sunset review announcements for RoHS exemptions are the leading indicator that forced alloy transitions will create acquisition opportunities among plating-dependent specialists unable to finance chemistry line conversions. Five-to-ten year viability favors suppliers with backward integration into wire-harness assembly controlling downstream demand pull. Monitor MIIT environmental compliance actions in Guangdong province as signals of Chinese plating shop consolidation that could disrupt automotive supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| Plating Chemistry Line Conversion | REACH-compliant surface treatments qualify suppliers for German automotive electrification programs. |
| ISO 13485 Certification Investment | Medical device OEMs in US corridors pay premiums for traceable biocompatible pin supply. |
| Supplier Park Proximity Expansion | Czech and Slovakian production footprints sustain just-in-time delivery to Wolfsburg clusters. |
| Stainless Steel Alloy Qualification | FDA active implantable rules displace brass in surgical equipment corrosion specifications. |
| Surface Mount Miniaturization R&D | South Korean consumer electronics OEMs demand reduced Z-height for wearable assemblies. |
Research Methodology
Document review covered SEC filings from diversified interconnect specialists, ECHA regulatory enforcement calendars, and automotive OEM supplier qualification protocols, complemented by interviews with tier-one connector procurement directors, plating shop operations managers, and medical device quality assurance leads. Secondary validation drew from customs trade data, IHS Markit vehicle production databases, and FDA 510(k) submission records. Bottom-up segmentation modeling triangulated against top-down market sizing from disclosed capacity expansions.
Historical shipment patterns cross-referenced against panel input from automotive harness assemblers and industrial equipment OEMs shaped the analytical framework across the analysis window. Segmentation dimensions included product architecture, material grade tier, end-use regulatory exposure, and geographic production cluster. CAGRs derived from fitted growth curves incorporating battery electric vehicle penetration rates and medical device approval velocities. Industry-specific inputs encompassed copper price volatility indices and REACH exemption review timelines.
The model holds under stable alloy qualification timelines and sustained automotive electrification investment; deviation in plating chemistry approval delays or RoHS exemption sunset accelerations would shift volume trajectories. Stakeholders should weight assumptions against their own operating context and regulatory compliance readiness.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Connectors
Heavy-Duty Connector Market
Connectors
Connector and Terminal Systems for Harsh Environment Wiring Market
Connectors
Liquid Cooling Connector Market
Connectors
Middle East and Africa Hazardous Location Connectors Market
Connectors
DIN Connectors Market
Connectors
Filtered Connectors Market
Connectors
Hazardous Location Connectors Market
Connectors
Space Grade Connectors Market
Connectors
Underwater Mate Connectors Market
Connectors
3C Electronics Precision Connectors Market
Connectors
PCI-E Connectors Market
Connectors
Australia Connector Market
Connectors
Line Clamp Market
Connectors
High-Reliability Connectors Market
Connectors
Automotive Data Connectors Market
Connectors
Pin Retainer Market