
 Seven Segment Display Market | 2026-2036
Seven Segment Display Market Size, Share, and Industry Trends Forecast 2026-2036
Seven Segment Display Market Analysis
REACH compliance is decoupling low-efficiency display components from European industrial equipment supply chains. Vishay Intertechnology leverages captive semiconductor packaging capacity to sustain margin structures under tightening material disclosure rules. ROHM anchors its position through backward integration into gallium arsenide epitaxy for high-brightness LED dies. Kingbright Electronic Co. Ltd. dominates the common cathode segment via Shenzhen-based manufacturing scale and direct OEM channel control.
A seven segment display is an optoelectronic device comprising seven individually addressable bar-shaped elements arranged to form numeric characters zero through nine, typically constructed from gallium phosphide or gallium arsenide phosphide semiconductor substrates for LED variants and requiring forward currents between five and twenty milliamperes per segment for standard luminance. Its primary commercial purpose is to present quantized numerical data in cost-constrained applications where full graphical resolution remains economically unjustified. Common cathode configurations lead unit shipments across consumer electronics and basic instrumentation, while OLED technology within the technology dimension captures expanding share in premium automotive and medical settings where wide viewing angles and contrast ratios command price premiums. Surface mount installation types are accelerating fastest as contract manufacturers push pick-and-place automation rates toward throughput ceilings.
The EU Green Deal and F-Gas Regulation constrain refrigerant monitoring display specifications in commercial HVAC, while China's GB standards and MIIT energy-labeling rules shape domestic procurement thresholds for household appliance interfaces. FDA device-labeling requirements in the United States enforce legibility standards for seven segment readouts in portable healthcare equipment, creating certification friction for unvalidated suppliers. Stakeholders must monitor divergence between regional efficiency mandates and legacy inventory amortization schedules to time technology transitions without stranding installed capacity.
Market Dynamics
Automotive electrification is forcing instrument cluster redesigns at scale, decoupling incandescent backlighting from new vehicle platforms and concentrating procurement around LED-based seven segment architectures that align with MIIT energy-labeling mandates.
Growth Catalysts
- China's dual carbon goals:Energy-efficiency mandates are accelerating replacement cycles in household appliance interfaces, pulling gallium arsenide phosphide LED dies into new procurement windows ahead of legacy amortization schedules.
- Surface mount installation:Contract manufacturers in Shenzhen and Seoul metropolitan clusters are pushing pick-and-place automation rates toward throughput ceilings, standardizing surface mount seven segment formats across consumer electronics and basic instrumentation.
- FDA legibility standards:Device-labeling requirements for portable healthcare equipment are creating certification pull for validated seven segment suppliers, filtering unvalidated competitors from medical procurement pools.
Market Restraints
- Raw material concentration:Gallium arsenide epitaxy capacity concentrates among Japanese and Korean substrate producers, exposing downstream packaging operations to input bottlenecks during semiconductor cycle upturns.
- REACH compliance friction:ECHA material disclosure rules are decoupling low-efficiency display components from European industrial equipment supply chains, forcing inventory write-downs for non-compliant legacy stock.
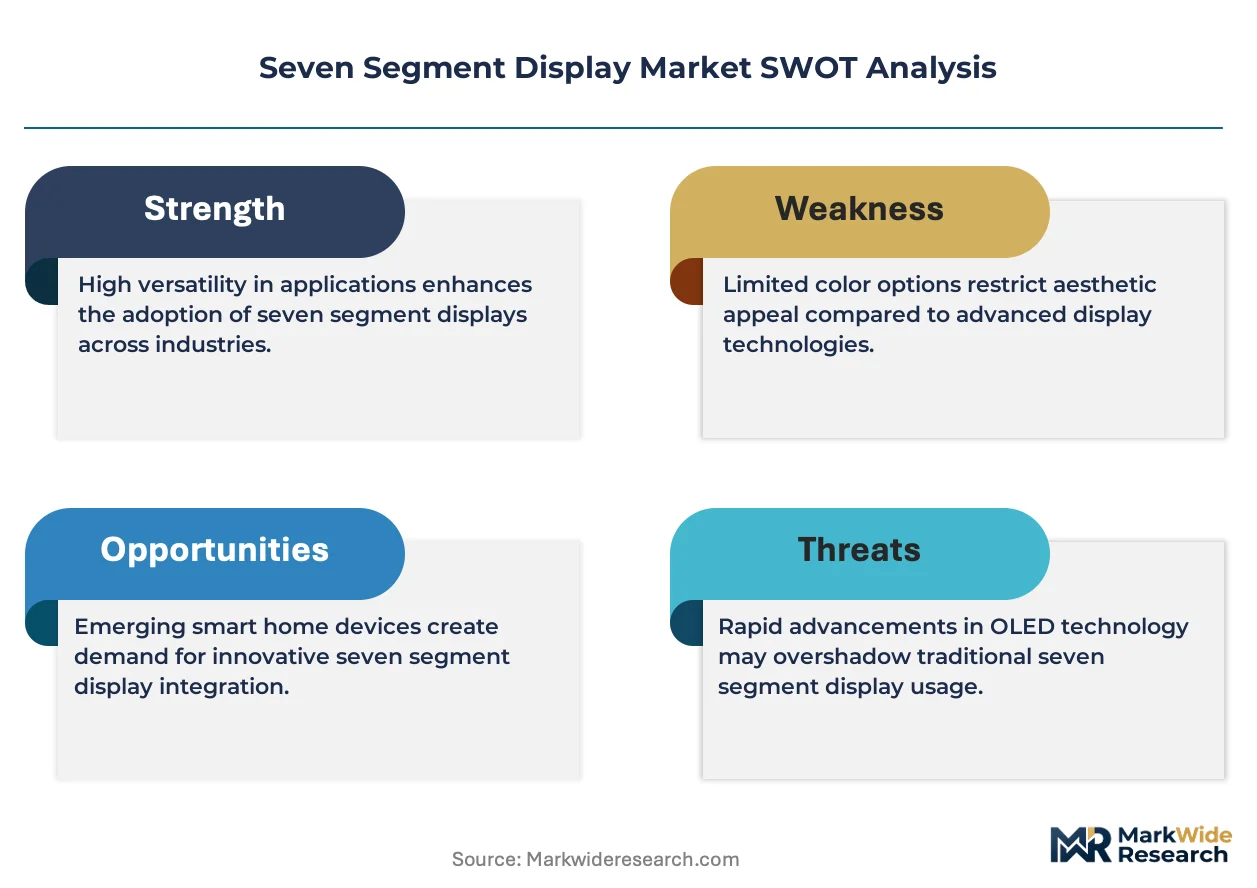
- OLED substitution pressure:Organic LED technology is capturing share in premium automotive and medical settings where wide viewing angles command price premiums, compressing addressable volume for conventional seven segment formats.
Strategic Opportunities
- Commercial HVAC monitoring:EU F-Gas Regulation constraints on refrigerant monitoring display specifications are opening specification windows for high-reliability seven segment readouts in building automation retrofits.
- India appliance manufacturing:BIS energy-labeling rules and domestic production incentives are localizing display procurement for cooling equipment and metering devices, creating import substitution openings for regional assemblers.
- Automotive OLED convergence:Hybrid instrument clusters combining seven segment numeric readouts with OLED graphical zones are emerging as a cost-optimized architecture for mid-tier electrified vehicle platforms.
Industry Challenges
- GB standard compliance timelines:China's MIIT certification cycles for household appliance interfaces are lengthening as testing protocols expand, delaying revenue recognition for new product introductions.
- Legacy system integration:Industrial equipment retrofit projects require signal-level compatibility with existing incandescent driver circuits, forcing additional engineering overhead for LED-based replacement modules.
- Epitaxial wafer sourcing:Captive gallium arsenide capacity at major LED die producers is limiting merchant market availability, constraining scaling options for mid-tier packaging houses without backward integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Seven Segment Display Market |
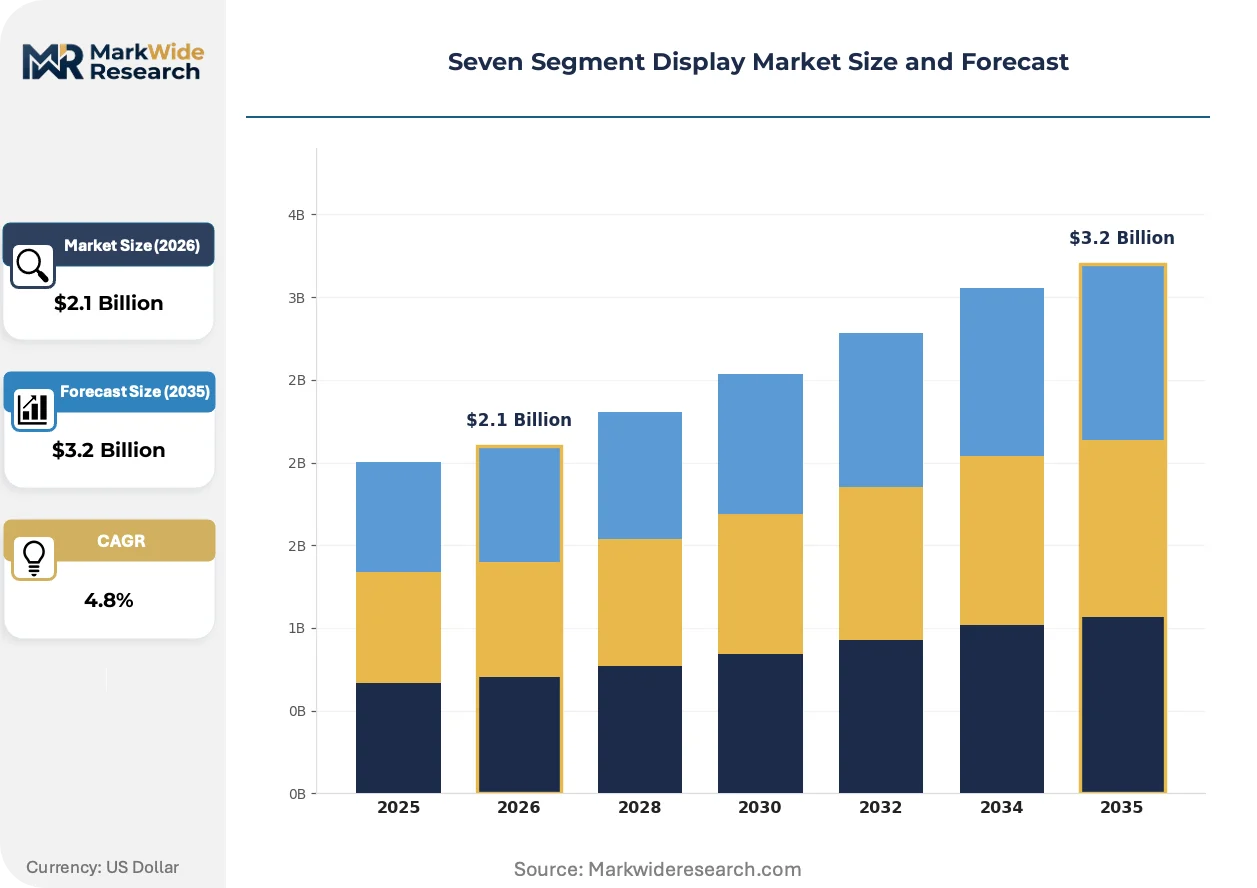
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.2 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Common Cathode, Common Anode, Digit Display, Alphanumeric End User: Consumer Electronics, Automotive, Industrial Equipment, Healthcare Devices Technology: LED, LCD, OLED, VFD Installation Type: Panel Mount, Surface Mount, Through Hole, Embedded |
| Companies Covered | LITE-ON Technology Corporation, Vishay Intertechnology Inc., Broadcom Inc., ROHM, Lumex Inc., Everlight Electronics Co. Ltd., Asian Electronics, Texas Instruments Inc., Kingbright Electronic Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Seven Segment Display Market Emerging Trajectories
Active matrix addressing and chip-on-board packaging are compressing module footprints while regulatory efficiency mandates are rewriting procurement specifications across automotive and appliance verticals.
Chip-on-board seven segment modules are eliminating leadframe substrates by mounting bare LED dies directly onto printed circuit carriers. Automotive tier-one suppliers in Germany and Japan are adopting these formats for instrument cluster applications where space and thermal density constraints intensify. This architecture is modularizing sub-assembly supply chains, allowing display integrators to source dies and drivers separately rather than purchasing complete packaged units.
REACH and RoHS amendments are tightening cadmium and lead exemptions for display phosphors and solder alloys. European industrial equipment OEMs are requalifying supply chains to maintain CE marking eligibility, with material disclosure documentation now required at the component level. Medical device manufacturers face the steepest compliance burden, as ECHA substance restrictions intersect with MDR technical file requirements to extend validation timelines.
Appliance OEMs are consolidating display procurement through direct channel relationships with Shenzhen-based manufacturers, bypassing traditional distribution layers. This pattern is most visible in cooling equipment and metering device production, where Kingbright Electronic and comparable suppliers have established direct OEM account management. The shift compresses margin pools for regional distributors while transferring inventory risk to end-equipment manufacturers.
Seven Segment Display Market Segmentation
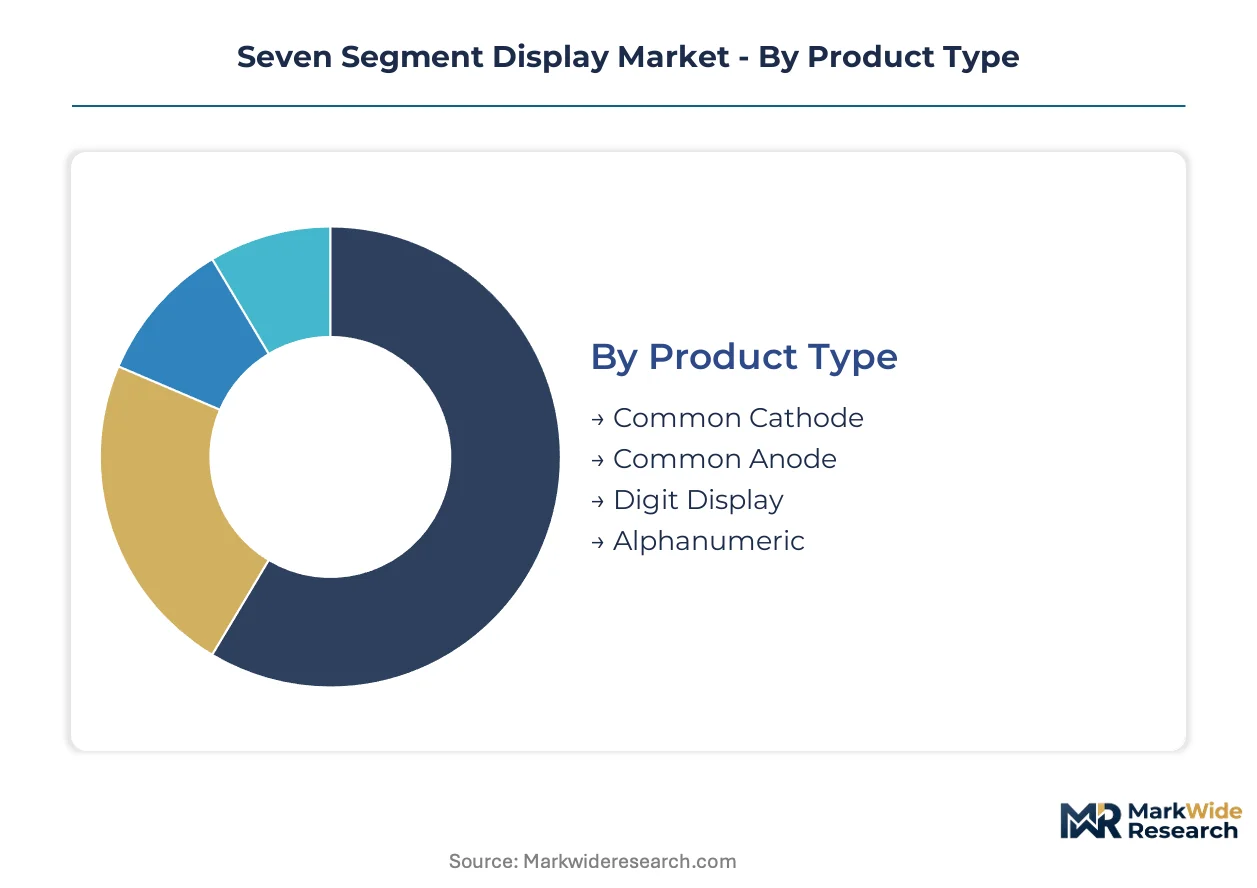
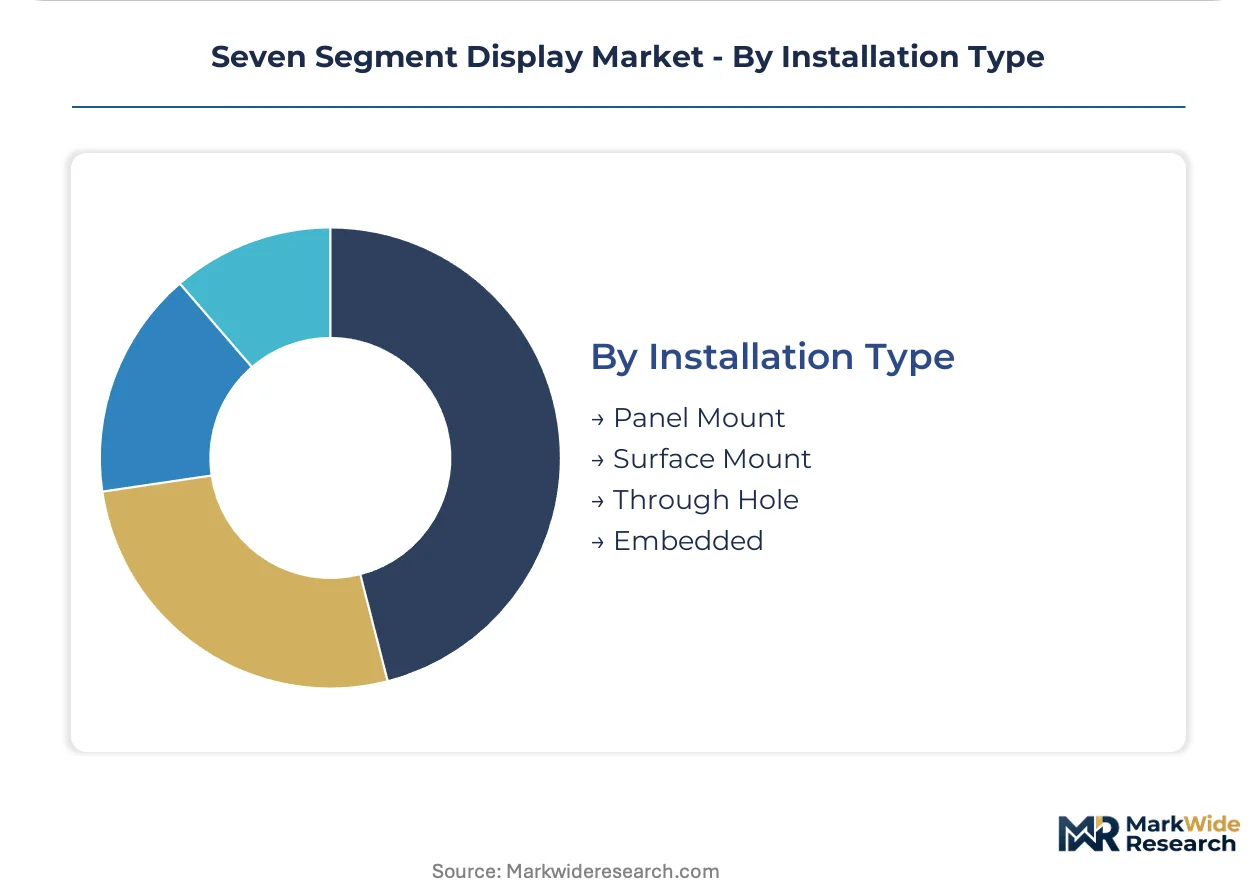
Seven segment display procurement patterns diverge sharply across electrical configuration, end-use environment, and mounting technology. Buyers select architectures based on driver circuit compatibility, luminance requirements, and automation constraints in downstream assembly.
Product Type:
Cost tier and circuit complexity separate buyers in this category.
- Common Cathode:All segments share a single negative terminal, simplifying driver IC requirements and reducing PCB trace density. Demand concentrates in Shenzhen-manufactured consumer electronics and basic instrumentation where Kingbright Electronic leverages direct OEM channel control.
- Common Anode:Shared positive terminal configuration suits high-side driver architectures prevalent in automotive instrument clusters. Procurement tilts toward German and Japanese tier-one suppliers where MIIT energy-labeling mandates and electrified vehicle redesigns are decoupling incandescent backlighting from new platforms.
- Digit Display:Multi-digit modules integrate multiple seven-segment characters with internal multiplexing circuitry.
- Alphanumeric:Extended segment counts (fourteen or sixteen segments) enable limited letter display for industrial equipment readouts.
Volume sits with Common Cathode; growth tilts toward Common Anode.
End User:
Application environment dictates reliability specifications and certification requirements.
- Automotive:Instrument cluster and dashboard readouts require automotive-grade temperature cycling resistance and EMI compliance. Electrified vehicle architectures are forcing redesigns at scale, concentrating procurement around LED-based architectures that align with dual carbon goals.
- Healthcare Devices:Portable equipment demands FDA legibility standards and MDR technical file alignment, creating certification friction that filters unvalidated suppliers from procurement pools.
- Consumer Electronics:Cost-optimized applications in household appliances and basic timers.
- Industrial Equipment:HVAC monitoring and process control interfaces subject to REACH material disclosure rules.
Shipment volume clusters in Consumer Electronics; certification premiums expand fastest in Healthcare Devices.
Technology:
Performance tier and viewing angle requirements segment buyer preferences.
- LED:Gallium phosphide and gallium arsenide phosphide substrates deliver standard luminance at five to twenty milliamperes per segment. ROHM anchors position through backward integration into gallium arsenide epitaxy for high-brightness dies.
- OLED:Organic emitters provide wide viewing angles and contrast ratios commanding price premiums in premium automotive and medical settings.
- LCD:Passive matrix configurations serve cost-constrained applications with ambient lighting.
- VFD:Vacuum fluorescent technology persists in legacy industrial equipment requiring high brightness and wide temperature range.
LED dominates unit economics; OLED climbs the fastest on premium substitution.
Installation Type:
Assembly automation compatibility and thermal density drive format selection.
- Surface Mount:Pick-and-place automation compatibility accelerates throughput in Shenzhen and Seoul contract manufacturing clusters. This format is standardizing across consumer electronics as manufacturers push automation rates toward ceilings.
- Panel Mount:Bezel-integrated housings suit retrofit industrial equipment and appliance interfaces.
- Through Hole:Legacy through-hole configurations persist in high-vibration automotive and industrial applications requiring mechanical strain relief.
- Embedded:Chip-on-board modules mounting bare dies directly onto PCB carriers eliminate leadframe substrates for space-constrained instrument clusters.
Panel Mount retains installed base; Surface Mount gains share fastest on automation economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seven segment display procurement concentrates in East Asian manufacturing corridors, with electrified vehicle instrument clusters and energy-efficiency mandates driving replacement cycles across multiple regulatory jurisdictions.
China
MIIT energy-labeling rules and dual carbon goals are decoupling legacy incandescent technologies from new appliance procurement cycles. GB standards certification timelines are lengthening as testing protocols expand, delaying revenue recognition for household interface suppliers. Shenzhen metropolitan clusters dominate manufacturing scale, with direct OEM channel control consolidating procurement through local manufacturers.
Japan
Automotive electrification is forcing instrument cluster redesigns at scale, concentrating demand around LED-based architectures. METI efficiency mandates align procurement with high-brightness gallium arsenide phosphide dies. Tokyo and Nagoya metropolitan areas anchor substrate production capacity, with captive epitaxy operations limiting merchant market availability for downstream packaging houses.
Germany
Automotive tier-one suppliers are adopting chip-on-board formats for space-constrained instrument clusters where thermal density constraints intensify. REACH compliance and RoHS amendments are tightening material disclosure requirements, forcing requalification of industrial equipment supply chains. KBA vehicle-type approval processes intersect with ECHA substance restrictions to extend validation timelines for display module suppliers.
South Korea
Seoul metropolitan contract manufacturers are pushing pick-and-place automation rates toward throughput ceilings, standardizing surface mount formats across consumer electronics. MFDS medical device regulations create certification friction for portable healthcare equipment interfaces, filtering unvalidated competitors from procurement pools. Local substrate producers concentrate gallium arsenide epitaxy capacity, exposing downstream operations to input bottlenecks.
United States
FDA legibility standards for portable healthcare equipment are creating certification pull for validated seven segment suppliers. EPA energy-efficiency programs and state-level appliance standards are accelerating replacement cycles in household interfaces. Industrial equipment retrofit projects in Midwest manufacturing corridors require signal-level compatibility with existing incandescent driver circuits, forcing additional engineering overhead for LED-based modules.
Seven Segment Display Market Vendor Landscape
East Asian producers anchor one tier; European and North American specialists hold differentiated positions in automotive and medical certification-intensive segments. The vendor base organizes around three strategic archetypes: integrated semiconductor houses with captive epitaxy capacity, Shenzhen-based scale manufacturers with direct OEM channel control, and diversified component conglomerates leveraging packaging expertise. Competitive moves concentrate on backward integration into substrate production and geographic expansion through direct account management with appliance OEMs.
Within the integrated semiconductor tier, ROHM exemplifies backward integration into gallium arsenide epitaxy for high-brightness LED dies. Among scale-focused manufacturers, Kingbright Electronic Co. Ltd. occupies a position defined by Shenzhen-based manufacturing scale and direct OEM channel control in the common cathode segment. Vishay Intertechnology sits within the diversified component archetype, leveraging captive semiconductor packaging capacity to sustain margin structures under tightening material disclosure rules.
| Leading Market Players |
|---|
| LITE-ON Technology Corporation |
| Vishay Intertechnology Inc. |
| Broadcom Inc. |
| ROHM |
| Lumex Inc. |
| Everlight Electronics Co. Ltd. |
| Asian Electronics |
| Texas Instruments Inc. |
| Kingbright Electronic Co. Ltd. |
| Others |
Supply Flow & Price Mechanics
Automotive tier-one suppliers in Germany and Japan anchor procurement volume for LED-based seven segment modules, concentrating price negotiation leverage around long-term contract structures that index gallium arsenide substrate costs against spot market volatility.
Pricing Analysis
Lead-time-driven pricing differentiates validated suppliers from spot-market merchants, with FDA-certified medical display modules commanding premiums against standard industrial grades. Pricing stratifies across automotive-grade, medical-certified, and consumer-economy tiers, with certification level and volume scale as primary differentiation drivers. Cost compression in the consumer electronics tier is intensifying as Shenzhen-based manufacturers consolidate direct OEM channel control. Appliance OEMs exhibit highest price sensitivity, while medical device manufacturers absorb certification premiums with limited negotiation leverage.
Supply Chain Analysis
Single-source vulnerability sits with Japanese and Korean gallium arsenide epitaxy producers, where captive capacity at ROHM and comparable integrated houses constrains merchant market availability. Substrate production concentrates in Japan, South Korea, and Taiwan, with downstream packaging operations drawing from concentrated wafer supply. Tariff exposure on semiconductor materials feeds into module cost structures. Distribution runs through direct OEM account management with Shenzhen-based manufacturers, bypassing traditional component distribution layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gallium arsenide epitaxy capacity scarcity props pricing power for backward-integrated suppliers, creating supply-constrained conditions that favor incumbents with captive substrate operations.
For Market Incumbents: Extend backward integration into gallium arsenide epitaxy to secure die supply against semiconductor cycle upturns. Deepen direct OEM channel control in Shenzhen manufacturing corridors to defend margin structures against distributor disintermediation. OLED substitution in premium automotive instrument clusters threatens conventional seven segment volume, requiring hybrid architecture development to maintain platform relevance. For New Entrants and Emerging Players: Launch via direct OEM partnerships with India-based appliance manufacturers under BIS energy-labeling localization incentives. Target commercial HVAC retrofit specifications under EU F-Gas Regulation constraints, where REACH compliance creates qualification barriers for unvalidated competitors. White-space concentrates in India appliance manufacturing and European industrial equipment retrofit channels lacking certified LED module supply. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier packaging houses with automotive certification pipelines in South Korea and Germany. Long-term viability hinges on backward integration access or hybrid technology transition capability. Watch gallium arsenide spot price volatility as inflection indicator for downstream margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Gallium Arsenide Epitaxy | Captive substrate supply insulates ROHM and comparable houses from wafer market bottlenecks during demand surges. |
| Direct OEM Channel Expansion | Kingbright Electronic's Shenzhen-based account management bypasses distribution layers and compresses competitor margin pools. |
| Hybrid Instrument Cluster Development | Combining seven segment numeric zones with OLED graphical areas addresses mid-tier electrified vehicle cost constraints. |
| REACH Compliance Requalification | European industrial OEMs must rebuild supply chains to maintain CE marking eligibility under tightened material disclosure rules. |
| Surface Mount Format Standardization | Pick-and-place automation compatibility accelerates throughput in Seoul and Shenzhen contract manufacturing clusters. |
Methodological Framework
Independent corroboration across display module procurement directors, automotive tier-one supplier engineers, and appliance OEM sourcing managers underwrites the qualitative findings. Primary fieldwork engaged semiconductor packaging specialists, regulatory compliance officers, and contract manufacturing operations heads across Shenzhen, Seoul, and Tokyo metropolitan clusters. Secondary validation drew from MIIT energy-labeling documentation, ECHA REACH substance databases, FDA 510(k) device filings, and customs trade flow records. Bottom-up segment sizing triangulated against top-down industry value estimates.
Rate-of-change decomposition across the analysis window separates volume growth from price trajectory and mix shift effects. The modeling framework segments by electrical configuration, end-use environment, mounting technology, and regional regulatory cluster. CAGRs derive from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs include electrified vehicle platform rollout schedules, appliance energy-efficiency mandate compliance timelines, and semiconductor capital expenditure cycles.
Semiconductor cycle downturns, regulatory certification timeline extensions, and OLED technology cost curves are the dominant revision risks. Deviation in gallium arsenide substrate capacity expansion would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Field Emission Display Market
Display Technologies
Global Smartphone Display Panel Market
Display Technologies
Global Portable Monitor Market
Display Technologies
Europe Computer Monitor Market
Display Technologies
Global Ferro Liquid Display Market
Display Technologies
Backlit Displays Market
Display Technologies
Large Format Display (LFD) Market
Display Technologies
United States Microdisplay Market
Display Technologies
Paper-Thin Display Market
Display Technologies
Head-Mounted Display Market
Display Technologies
Display Semiconductor Components Market
Display Technologies
Europe Transparent Conductive Films Market
Display Technologies
Resistive Touchscreen Market
Display Technologies
Global Industrial Display System Market
Display Technologies
Commercial Display Market
Display Technologies
Asia Pacific Computer Monitor Market