
 Hazardous Location Connectors Market | 2026-2036
Hazardous Location Connectors Market Size, Share, and Industry Trends Forecast 2026-2036
Hazardous Location Connectors Market Outlook
Preventive maintenance contracts and condition-monitoring subscriptions is recalibrating how hazardous location connectors are monetized, shifting revenue from unit sales to lifecycle service agreements. Amphenol Industrial Products Group leverages its global certification portfolio to anchor long-term framework contracts with integrated oil majors. Eaton Corp. Plc competes through integrated power distribution platforms that bundle connectors with switchgear and motor control centers. Hubbell-Killark specializes in corrosion-resistant marine-grade assemblies that dominate offshore platform retrofit programs.
Hazardous location connectors are engineered electrical interconnection devices constructed with flame-path enclosures, sealing glands, and metallurgy rated for explosive atmospheres, designed to contain internal arcs and prevent ignition of surrounding flammable gases or dusts. These components typically achieve ingress protection ratings from IP66 through IP68 and operate across temperature extremes from minus 60 degrees Celsius to plus 180 degrees Celsius, serving critical functions in process industries where standard connectors would constitute ignition sources. Explosion-proof product types command the largest installed base due to decades of specification in legacy petrochemical infrastructure, though sealing connectors are capturing disproportionate growth in hydrogen handling and carbon capture applications where gas-tight integrity exceeds mechanical containment priorities. Oil and gas applications retain the deepest specification heritage, while chemical processing is generating faster upgrade cycles as European REACH compliance drives replacement of legacy halogenated cable gland materials.
IECEx equipment certification schemes, ATEX Directive 2014/34/EU, and OSHA 29 CFR 1910.307 hazardous classification standards collectively dictate material selection, testing protocols, and market access across major industrial geographies. NEMA 7 and 9 enclosure standards in North America create parallel certification requirements that fragment supplier qualification costs and protect regionally established players. Stakeholders must monitor evolving hydrogen-specific ignition energy thresholds and corresponding connector redesign mandates as energy transition infrastructure scales beyond pilot phases.
Market Dynamics
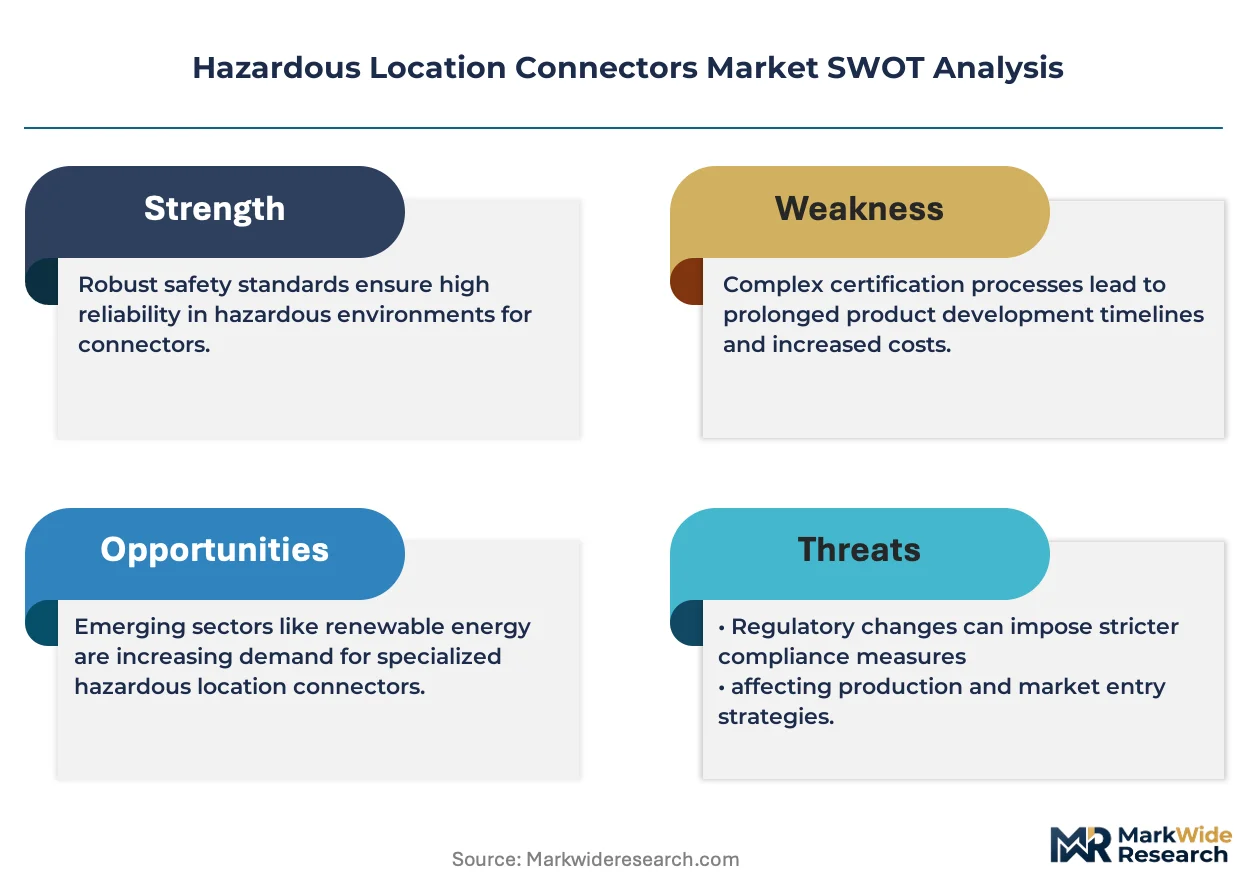
Certification-driven material requalification is compressing supplier margins while simultaneously consolidating procurement authority among integrated oil majors and EPC firms with transnational framework agreements.
Growth Catalysts
- Offshore platform electrification:Brownfield cable replacement programs across Gulf of Mexico and North Sea installations are accelerating Zone 1 connector procurement cycles as aging infrastructure reaches end-of-design-life.
- ATEX Directive material mandates:European REACH compliance is forcing halogenated cable gland phase-outs, creating replacement demand for fluoropolymer and stainless steel sealing solutions in chemical processing corridors.
- Hydrogen infrastructure buildout:Gas-tight sealing connectors rated for 700-bar hydrogen service are capturing specification share from legacy explosion-proof designs in electrolyzer and refueling station projects.
Market Restraints
- Nickel and copper price volatility:Flame-path enclosures rely on high-grade copper alloys and nickel-plated steel, exposing margins to London Metal Exchange commodity swings without pass-through pricing power.
- Dual certification cost burden:Suppliers must simultaneously qualify products under IECEx schemes and OSHA 29 CFR 1910.307 classifications, fragmenting engineering resources and extending time-to-market.
- Extended qualification timelines:Third-party testing laboratories in Germany and the United States carry 14-18 month backlogs for ATEX and NEMA 7 certification, freezing product launches.
Strategic Opportunities
- Carbon capture utilization and storage:Supercritical CO2 handling specifications are emerging as a white space where gas-tight sealing ratings exceed legacy mechanical containment requirements.
- United States LNG export terminals:FERC permitting acceleration along the Gulf Coast is concentrating demand for Division 1 rated assemblies in modular electrical skids.
- Condition-monitoring integration:Embedding temperature and vibration sensors within connector housings converges electrical interconnection with predictive maintenance platforms.
Industry Challenges
- IECEx competent person scarcity:Qualified explosion protection engineers capable of interpreting flame-path tolerance calculations are concentrated among aging specialists in Germany and the United Kingdom.
- Legacy system interoperability:Retrofitting Zone 2 digital monitoring connectors onto 1970s-era explosion-proof conduit systems requires custom adapter engineering that extends project schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hazardous Location Connectors Market |
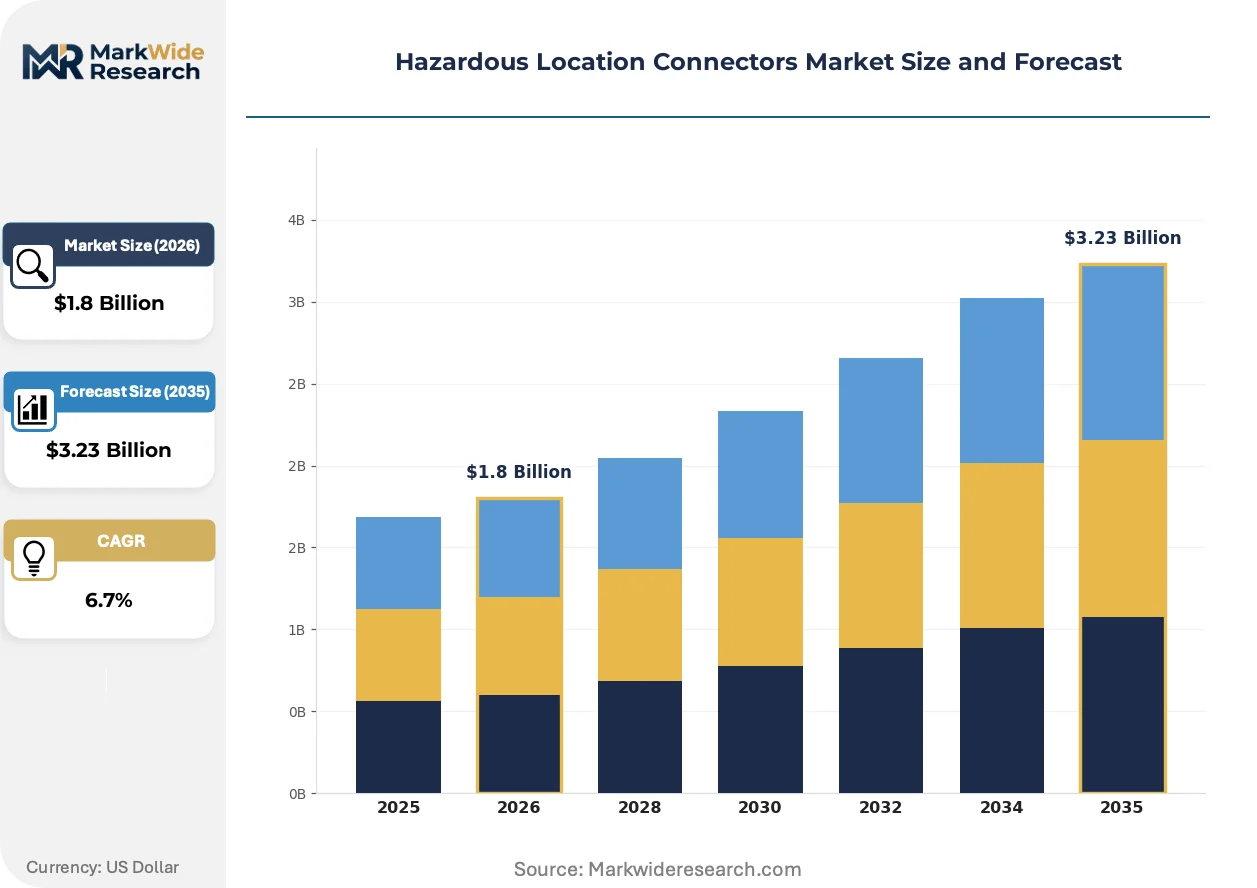
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Explosion-Proof, Corrosion-Resistant, Sealing Connectors, High-Temperature Application: Oil & Gas, Chemical Processing, Mining, Wastewater Treatment End User: Utilities, Industrial Manufacturing, Pharmaceutical, Marine Installation: Fixed, Portable, Surface Mount, Submersible |
| Companies Covered | American Connectors, Amphenol Industrial Products Group, ABB Ltd., Hubbell-Killark, Thomas & Betts, Texcan, Eaton Corp. Plc, Emerson Electric Co., ITT BIW Connector Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hazardous Location Connectors Market Strategic Shifts
Material science breakthroughs and certification regime evolution are simultaneously expanding performance envelopes and compressing supplier response windows across hazardous location interconnection markets.
Additive manufacturing of stainless steel flame-path components is rewriting supply chain economics for low-volume, geometrically complex sealing glands. Offshore platform operators in Norway and Brazil are qualifying laser-powder-bed-fusion parts for Zone 1 subsea applications. The technology is compressing minimum order quantities from thousands to hundreds while maintaining ATEX-certified metallurgical traceability.
The European Union's F-Gas Regulation phase-down is restricting perfluorinated sealing compounds in electrical equipment, forcing compounders to reformulate elastomer specifications for hydrogen sulfide resistance. Chemical processors in the ARA cluster must revalidate cable gland materials against new permeation thresholds. Connector suppliers are accelerating fluorosilicone and FFKM compound qualification programs to maintain market access.
Integrated oil majors are unbundling connector procurement from capital equipment packages and centralizing specifications through corporate engineering standards. EPC contractors in the United States Gulf Coast must now source Division 1 assemblies from approved vendor lists rather than project-specific selections. This concentration is shifting pricing power toward buyers with multi-year framework contracts and technical qualification teams.
Hazardous Location Connectors Market Segmentation
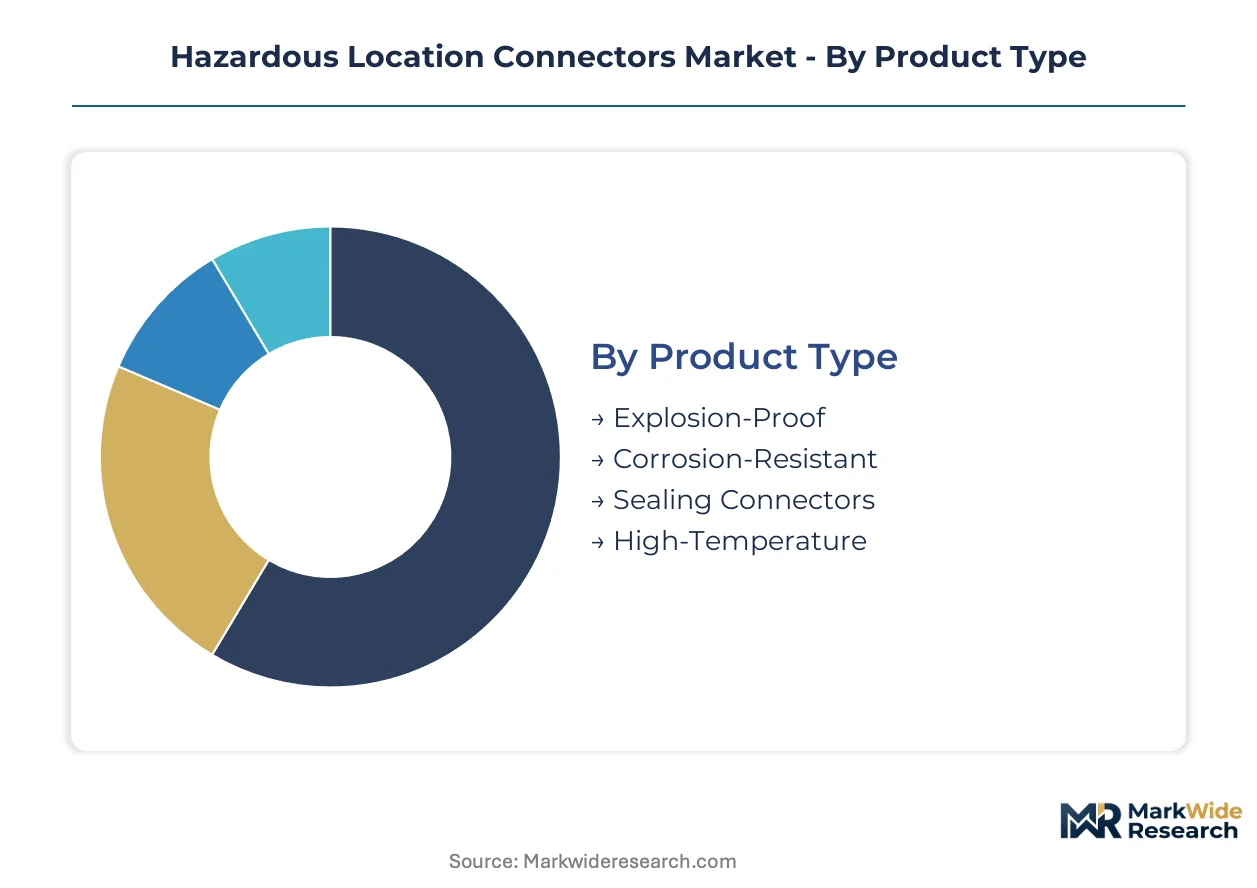
Certification requirements and operating environment severity create sharp purchasing behavior differences across connector specifications. Buyers prioritize flame-path integrity in petrochemical corridors while hydrogen infrastructure demands gas-tight sealing ratings above mechanical containment.
Product Type:
Cost tier differentiation separates legacy specification holders from transition-technology adopters in procurement decisions.
- Explosion-Proof:Flame-path enclosures contain internal arcs through precision-machined metal joints that cool escaping gases below ignition temperatures. Gulf Coast petrochemical operators specify these for Division 1 hazardous areas under OSHA 29 CFR 1910.307, though qualification timelines extend 14-18 months through third-party laboratories.
- Sealing Connectors:Gas-tight designs using fluoropolymer and FFKM compounds prevent gas permeation rather than containing explosions. Electrolyzer projects in Germany and hydrogen refueling stations across California are capturing specification share as ECHA REACH compliance phases out halogenated cable gland materials.
- Corrosion-Resistant:Marine-grade stainless steel assemblies with nickel-plated flame paths serve North Sea and Brazil offshore platforms.
- High-Temperature:Metallurgy rated to plus 180 degrees Celsius addresses geothermal and thermal processing applications.
Explosion-Proof leads volumes today; Sealing Connectors is gaining share fastest.
Application:
End-use maturity cycles determine replacement urgency and certification burden intensity.
- Oil & Gas:Upstream operators across United States shale basins and North Sea installations are compressing replacement cycles as aging infrastructure reaches end-of-design-life. Brownfield electrification projects concentrate procurement authority with integrated majors holding transnational framework agreements.
- Chemical Processing:European REACH compliance is forcing material revalidation across ARA cluster facilities. Fluorosilicone compound qualification programs are accelerating to maintain market access under F-Gas Regulation phase-down mandates.
- Mining:Underground coal and metal operations in Australia and South Africa require IP68-rated submersible assemblies for slurry handling.
- Wastewater Treatment:Biogas capture facilities specify corrosion-resistant sealing glands for methane-rich atmospheres.
Oil & Gas dominates installed base value; Chemical Processing shows steepest expansion trajectory from regulatory-driven replacement.
End User:
Customer scale and technical qualification capability fragment procurement channel structures.
- Industrial Manufacturing:Petrochemical and specialty chemical producers in United States Gulf Coast corridor centralize specifications through corporate engineering standards. EPC contractors must source from approved vendor lists rather than project-specific selections.
- Utilities:Power generation and distribution operators in Germany and United Kingdom face IECEx competent person scarcity for flame-path tolerance interpretation.
- Pharmaceutical:Batch processing facilities require CIP/SIP-compatible sealing solutions.
- Marine:Offshore platform operators in Norway and Brazil are qualifying laser-powder-bed-fusion components for Zone 1 subsea applications.
Industrial Manufacturing anchors procurement volumes; Marine is climbing the fastest from additive manufacturing qualification.
Installation:
Deployment mobility requirements dictate enclosure geometry and cable management complexity.
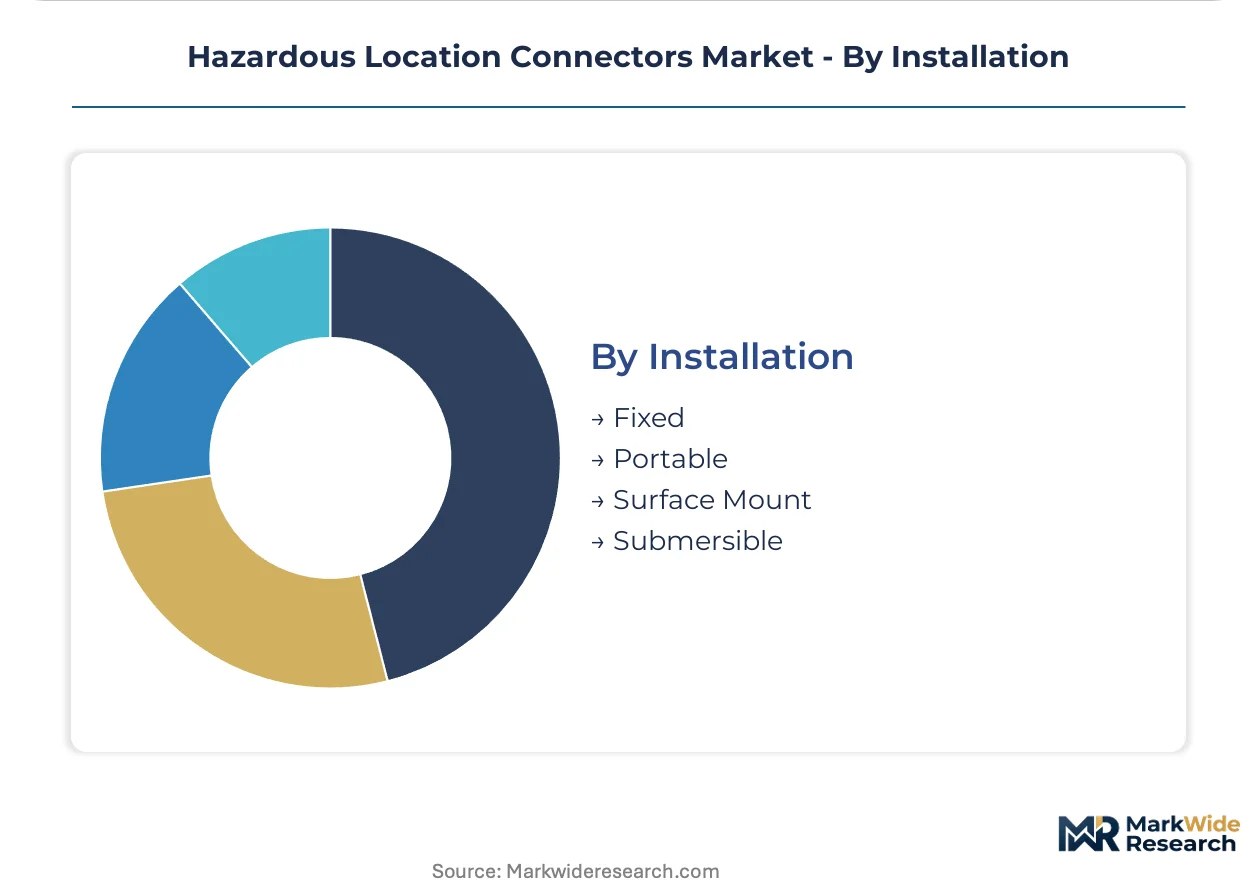
- Fixed:Permanent conduit systems in legacy petrochemical infrastructure specify NEMA 7 and 9 enclosures. Retrofitting Zone 2 digital monitoring connectors onto 1970s-era explosion-proof systems requires custom adapter engineering.
- Submersible:IP68-rated assemblies with stainless steel flame paths serve subsea production trees and underwater electrolyzer connections. Norwegian operators are compressing minimum order quantities from thousands to hundreds through additive manufacturing adoption.
- Portable:Temporary power distribution for maintenance turnarounds demands rapid-deployment sealing glands.
- Surface Mount:Modular electrical skids at United States LNG export terminals concentrate Division 1 assembly demand.
Fixed installation retains specification heritage; Submersible is expanding most quickly from subsea energy infrastructure buildout.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping supplier footprints as IECEx certification costs in Germany diverge from OSHA compliance timelines in the United States, prompting manufacturers to concentrate qualification investments where procurement volumes justify extended laboratory backlogs.
United States
FERC permitting acceleration along the Gulf Coast petrochemical corridor is concentrating demand for Division 1 rated assemblies. OSHA 29 CFR 1910.307 hazardous classification standards govern material specifications for flame-path designs. Houston and Corpus Christi anchor brownfield electrification projects where integrated oil majors centralize procurement through corporate engineering standards.
Germany
Electrolyzer buildout in the Rhineland and hydrogen refueling station deployment across Bavaria are capturing specification share for gas-tight sealing connectors. ECHA REACH compliance and the EU F-Gas Regulation phase-down are forcing halogenated cable gland phase-outs. The ARA cluster facilities in Rotterdam-Antwerp-Ghent must revalidate materials against new permeation thresholds.
China
Dual carbon goals under MIIT directives are accelerating carbon capture utilization and storage infrastructure specifications. GB standards for explosion-proof electrical equipment create parallel certification requirements that fragment supplier qualification costs. Sichuan-Chongqing and Shandong Peninsula industrial zones concentrate supercritical CO2 handling projects where gas-tight ratings exceed legacy mechanical containment.
Brazil
Pre-salt offshore platform electrification programs are compressing Zone 1 connector replacement cycles as aging infrastructure reaches end-of-design-life. ANVISA and national petroleum regulator specifications govern subsea production tree interconnections. Rio de Janeiro and Espírito Santo anchor laser-powder-bed-fusion qualification programs for additive-manufactured stainless steel flame-path components.
Norway
North Sea installation brownfield cable replacement programs are accelerating procurement of IP68-rated submersible assemblies. IECEx equipment certification schemes administered by Norwegian competent persons interpret flame-path tolerance calculations. Stavanger and Bergen offshore clusters are qualifying additive-manufactured sealing glands with minimum order quantities compressed from thousands to hundreds.
Hazardous Location Connectors Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated industrial conglomerates anchoring framework contracts while regional fabricators capture project-specific retrofit demand. The supplier base concentrates among electrical equipment multinationals with transnational certification portfolios and mid-tier specialists with corrosion-resistant marine-grade expertise. Three archetypes dominate: global certification holders with long-term oil major relationships, regional specialists in subsea or high-temperature metallurgy, and contract manufacturers serving EPC procurement channels. Competitive moves center on additive manufacturing adoption for low-volume geometric complexity and condition-monitoring integration into connector housings.
Among North American electrical equipment conglomerates, Eaton Corp. Plc and Hubbell-Killark exemplify divergent positioning archetypes, with the former representing integrated power distribution platform bundling and the latter occupying a specialist position in corrosion-resistant marine-grade assemblies. Amphenol Industrial Products Group anchors the global certification holder tier with transnational framework contract penetration. These three names illustrate how supplier strategies diverge across the oil and gas upstream, chemical processing, and offshore platform retrofit channels without implying specific market share or revenue figures.
| Leading Market Players |
|---|
| American Connectors |
| Amphenol Industrial Products Group |
| ABB Ltd. |
| Hubbell-Killark |
| Thomas & Betts |
| Texcan |
| Eaton Corp. Plc |
| Emerson Electric Co. |
| ITT BIW Connector Systems |
| Others |
Value Chain & Pricing Dynamics
Copper alloy and nickel-plated steel feedstock costs cascade through three distinct pricing tiers, with high-grade metallurgy for flame-path enclosures commanding premium positioning against standard-grade alternatives in procurement negotiations.
Pricing Analysis
Distributor margins compress most severely at the standard-grade tier, where EPC contractors wield approved vendor list leverage to extract volume discounts. Certification grade—specifically IECEx versus ATEX tier differentiation—drives the widest price spreads, with dual-certified assemblies carrying 40-60 percent markups over single-standard equivalents. Pricing pressure stems from integrated oil majors unbundling connector procurement from capital equipment packages and centralizing specifications through corporate engineering standards. Small-to-mid EPC contractors exhibit highest price sensitivity due to project-specific bidding constraints, while offshore platform operators in Norway and Brazil demonstrate lowest sensitivity given additive manufacturing qualification timelines and subsea reliability premiums.
Supply Chain Analysis
Fluoropolymer and FFKM compound supply rests on German and Japanese specialty chemical producers, with stainless steel flame-path metallurgy drawing from Chinese and South Korean mill sources. High-grade copper alloys and nickel-plated steel constitute critical raw material dependencies, while laser-powder-bed-fusion equipment for additive manufacturing anchors in Germany and the United States. Single-source vulnerability concentrates in qualified elastomer compounders serving ECHA REACH compliance deadlines. Distribution runs through authorized electrical equipment distributors in Houston, Rotterdam, and Singapore, with direct-to-OEM channels gaining share among integrated majors with transnational framework agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hazardous location connectors market reads as a late-cycle quality story, with specification authority concentrating among buyers demanding gas-tight sealing ratings above legacy mechanical containment as hydrogen infrastructure scales beyond pilot phases.
For Market Incumbents: Hedge certification portfolio concentration by accelerating fluorosilicone and FFKM compound qualification programs ahead of EU F-Gas Regulation phase-down deadlines. Anchor backward integration into additive manufacturing capabilities for low-volume, geometrically complex sealing glands, compressing minimum order quantities to defend against regional fabricators capturing project-specific retrofit demand. Prioritize condition-monitoring sensor integration into connector housings to shift revenue from unit sales toward lifecycle service agreements. For New Entrants and Emerging Players: Launch via direct qualification with EPC contractors in the United States Gulf Coast corridor, where FERC permitting acceleration concentrates Division 1 assembly demand in modular electrical skids. Target carbon capture utilization and storage specifications as the most penetrable white space, where supercritical CO2 handling requirements exceed legacy mechanical containment capabilities. Pursue additive manufacturing partnerships with Norwegian or Brazilian offshore clusters to bypass 14-18 month third-party laboratory backlogs for flame-path certification. For Investors and Strategic Acquirers: Consolidation pressure builds where IECEx competent person scarcity concentrates technical qualification capability among aging specialists in Germany and the United Kingdom. Frame long-term viability around certification regime complexity and material science barriers that protect incumbent returns across the analysis window. Acquisition target archetype: regional specialists with corrosion-resistant marine-grade expertise and established ANVISA or national petroleum regulator relationships in Brazil. Signal to watch: hydrogen-specific ignition energy threshold mandates triggering connector redesign cycles and requalification spending inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Additive Manufacturing Qualification | Laser-powder-bed-fusion adoption compresses minimum order quantities from thousands to hundreds for Norwegian subsea operators. |
| Condition-Monitoring Integration | Embedding temperature and vibration sensors converges electrical interconnection with predictive maintenance platforms for integrated oil majors. |
| Dual Certification Investment | Simultaneous IECEx and ATEX qualification extends addressable market across European and Asia-Pacific procurement channels. |
| Fluoropolymer Compound Partnership | Strategic supply agreements with German and Japanese specialty chemical producers secure REACH-compliant sealing material access. |
| Framework Contract Penetration | Long-term agreements with EPC contractors in Houston and Corpus Christi anchor recurring revenue in brownfield electrification cycles. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with electrical equipment procurement managers, EPC contractor specification engineers, offshore platform maintenance directors, and third-party certification laboratory technical leads with secondary validation. Bottom-up and top-down triangulation anchored against SEC 10-K filings from electrical equipment conglomerates, IECEx and ATEX certification database extracts, FERC permitting records for Gulf Coast LNG terminals, and trade flow data for copper alloy and fluoropolymer imports.
Comparable-period anchoring established baseline reference points across historical certification cycles and replacement demand waves, with projections extending over the analysis window through segmented modeling. Dimensions included product type tier, application severity, end-user scale and qualification capability, installation mobility requirements, and regional regulatory cluster. CAGRs derived from regression against capital expenditure patterns in oil and gas upstream, chemical processing, and hydrogen infrastructure buildout, with cross-validation against electrolyzer deployment pipelines and carbon capture project financing announcements.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extended third-party laboratory backlogs, nickel and copper price volatility without pass-through mechanisms, and hydrogen-specific ignition energy threshold mandates accelerating redesign cycles. A small set of named triggers—F-Gas Regulation enforcement timing, ANVISA subsea specification updates, and integrated oil major unbundling pace—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Connectors
Middle East Connector Market
Connectors
Magnetic Connector Market
Connectors
Global Wired Interface Market
Connectors
Connector Adapter Kits Market
Connectors
High-Reliability Connectors Market
Connectors
Liquid Cooling Connector Market
Connectors
Hybrid Fiber Optic Connectors Market
Connectors
Latin America Connector Market
Connectors
Press Fit Connector Market
Connectors
Telecom Mounting Hardware Market
Connectors
India Connector Market
Connectors
5G Connector Market
Connectors
Global Multi Coaxial Connectors Market
Connectors
Filtered Connectors Market
Connectors
Global Fiber Optic Connectors Market
Connectors
Wire-To-Board Connector Market