
 Space Grade Connectors Market | 2026-2036
Space Grade Connectors Market Size, Share, and Industry Trends Forecast 2026-2036
Space Grade Connectors Market Outlook
United States production capacity is tilting toward radiation-hardened and high-reliability connector lines. TE Connectivity sustains broad qualification across NASA and DoD programs. Amphenol Aerospace dominates military-space crossover applications with vertically integrated shielding capabilities. Glenair Inc. specializes in hermetic and environmental-sealing solutions for extreme-thermal orbit conditions.
Space grade connectors are precision-engineered electromechanical interfaces manufactured from aluminum, titanium, or composite housings with gold-plated contacts, designed to maintain signal integrity across temperature swings exceeding 200°C in vacuum environments. Circular connectors occupy the largest volume share due to legacy compatibility with launch-vehicle and satellite bus architectures; high-density variants represent the fastest-expanding category as payload miniaturization drives pin-count escalation in constrained form factors. Composite-material housings are gaining structural share as satellite prime contractors seek mass reduction for constellation economics.
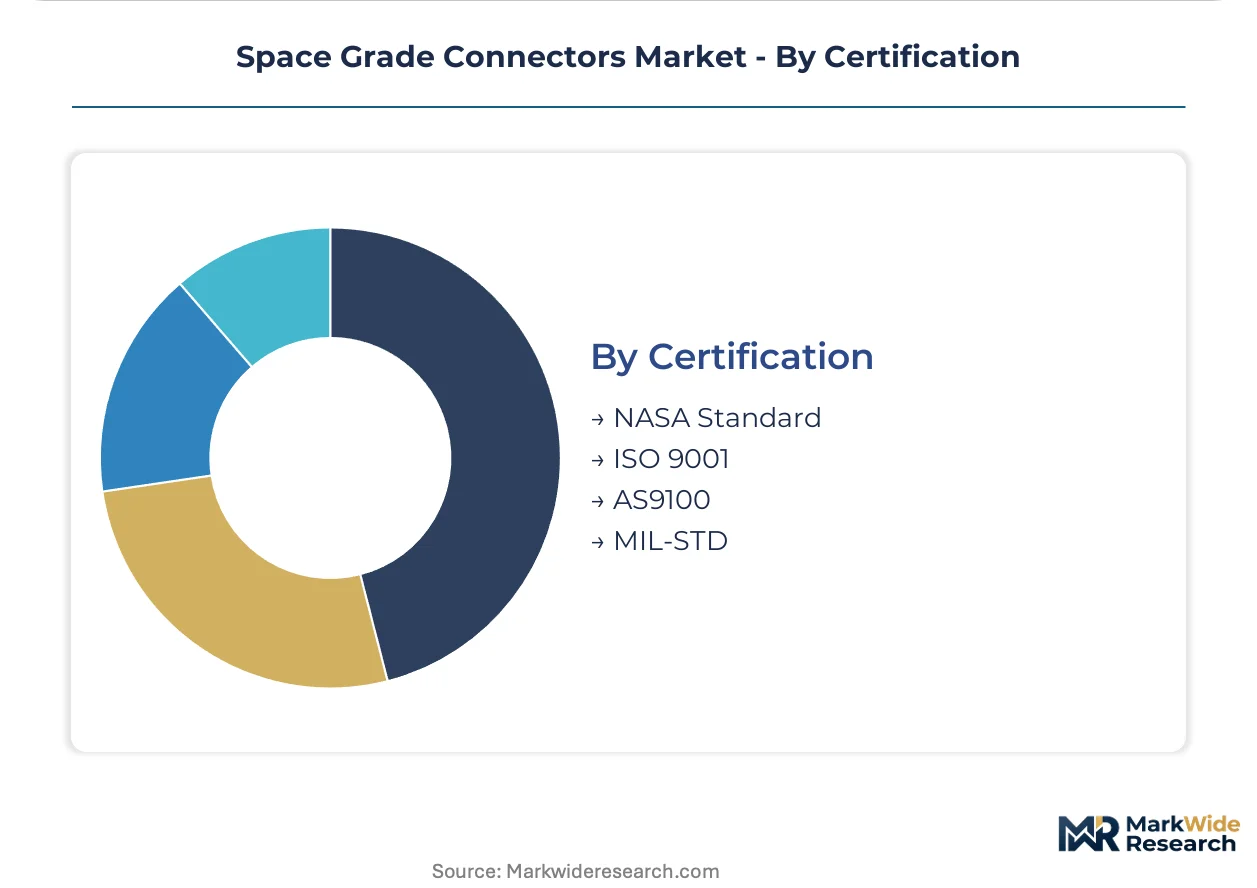
NASA Standard workmanship requirements, AS9100 quality frameworks, and MIL-STD qualification protocols collectively gate market access for non-domestic suppliers. ESA's ECSS specifications and JAXA's equivalent standards create parallel but non-interchangeable certification burdens for global vendors. Stakeholders must monitor evolving debris-mitigation rules and their downstream implications for connector redesign cycles in long-duration orbital assets.
Market Dynamics
Satellite constellation operators are compressing procurement cycles for radiation-hardened interconnects, forcing suppliers to accelerate qualification timelines while maintaining NASA workmanship standards. This tension between volume scaling and heritage reliability protocols defines current competitive positioning.
Growth Catalysts
- LEO Constellation Deployment:Commercial operators like SpaceX and Amazon's Project Kuiper are ordering qualified interconnects in multi-thousand-unit batches for phased orbital planes.
- NASA Standard 8739:Updated workmanship requirements for spaceflight hardware are mandating higher qualification thresholds that favor established domestic suppliers with existing certification infrastructure.
- Titanium Alloy Advances:Additive manufacturing of connector housings is reducing lead times for complex geometries while maintaining mass-critical strength-to-weight ratios.
Market Restraints
- Precious Metal Input Volatility:Gold-plated contact requirements expose manufacturers to COMEX price swings that compress margin predictability on fixed-price defense contracts.
- Domestic Supply Concentration:United States-based production of hermetic sealing technologies limits qualified vendor pools for ESA and JAXA programs seeking dual-source assurance.
- MIL-STD-1553 Legacy Lock-in:Military platform upgrade cycles extend decades, delaying adoption of high-density optical interconnects that exceed legacy bus specifications.
Strategic Opportunities
- In-Space Servicing Infrastructure:Northrop Grumman's MEV program and emerging orbital logistics vehicles require connectors rated for repeated mating cycles in vacuum environments.
- Artemis Lunar Surface Systems:NASA's return-to-Moon initiative is creating demand for connectors surviving extreme thermal cycling across 14-day lunar night periods.
- Quantum Key Distribution Payloads:Photonic interconnect convergence with traditional RF connectors is opening specification windows for hybrid fiber-copper assemblies in secure communications satellites.
Industry Challenges
- Heritage Engineering Talent Scarcity:Retiring workforce with Apollo-era workmanship expertise constrains knowledge transfer for manual soldering and inspection protocols.
- Qualification Timeline Compression:AS9100 certification cycles averaging 18-24 months misalign with constellation operators demanding 6-month delivery windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Space Grade Connectors Market |
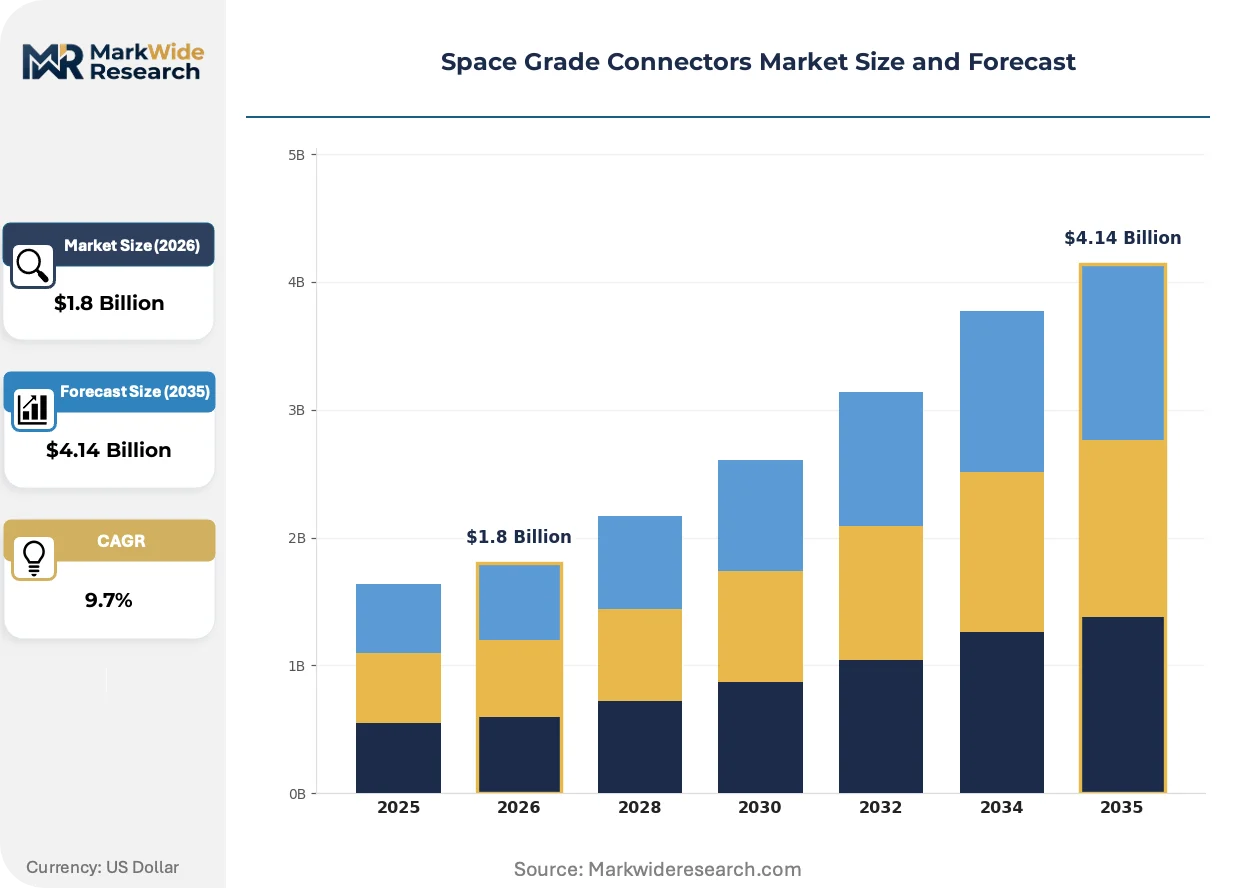
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Circular Connectors, Rectangular Connectors, Micro D Connectors, High-Density Connectors Material: Aluminum, Stainless Steel, Titanium, Composite Materials Application: Aerospace, Satellite Systems, Launch Vehicles, Space Robotics Certification: NASA Standard, ISO 9001, AS9100, MIL-STD |
| Companies Covered | ITT Inc., Radiall, TE Connectivity, Omnetics Connector Corporation, Fischer Connectors, Amphenol Aerospace, Glenair Inc., Harwin plc, Eaton Corporation (SOURIAU SUNBANK), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Space Grade Connectors Market Strategic Shifts
Connector architectures are bifurcating between ultra-miniaturized payload interconnects and heavy-lift launch vehicle harnesses, with material science advances enabling both trajectories simultaneously.
Composite housing technology is migrating from experimental satellite demonstrators to mainstream constellation buses. Carbon-fiber-reinforced polymer shells from Toray and Hexcel are replacing aluminum in non-hermetic applications, cutting mass by 40% while maintaining EMI shielding effectiveness. Prime contractors including Lockheed Martin and Boeing are qualifying these materials for 15-year orbital lifetimes, compressing the traditional metal-to-composite transition that took avionics three decades.
REACH substance restrictions are forcing reformulation of cadmium-plated hardware historically used for galvanic corrosion protection in aluminum-titanium interfaces. European suppliers must certify alternative coatings—tin-zinc and ion-vapor-deposited aluminum—by 2026 sunset dates for Annex XVII exemptions. Satellite prime contractors with dual US-EU supply chains are most affected, accelerating parallel qualification programs to avoid single-source vulnerability.
Buying patterns among constellation operators are consolidating procurement authority at the prime contractor level, displacing traditional subsystem vendor selection. SpaceX and OneWeb now specify connector families directly, forcing tier-2 harness suppliers into specification-taker roles. This concentration is most visible in the United States, where vertical integration at SpaceX's Hawthorne facility has internalized connector specification and incoming inspection functions previously outsourced.
Space Grade Connectors Market Segmentation
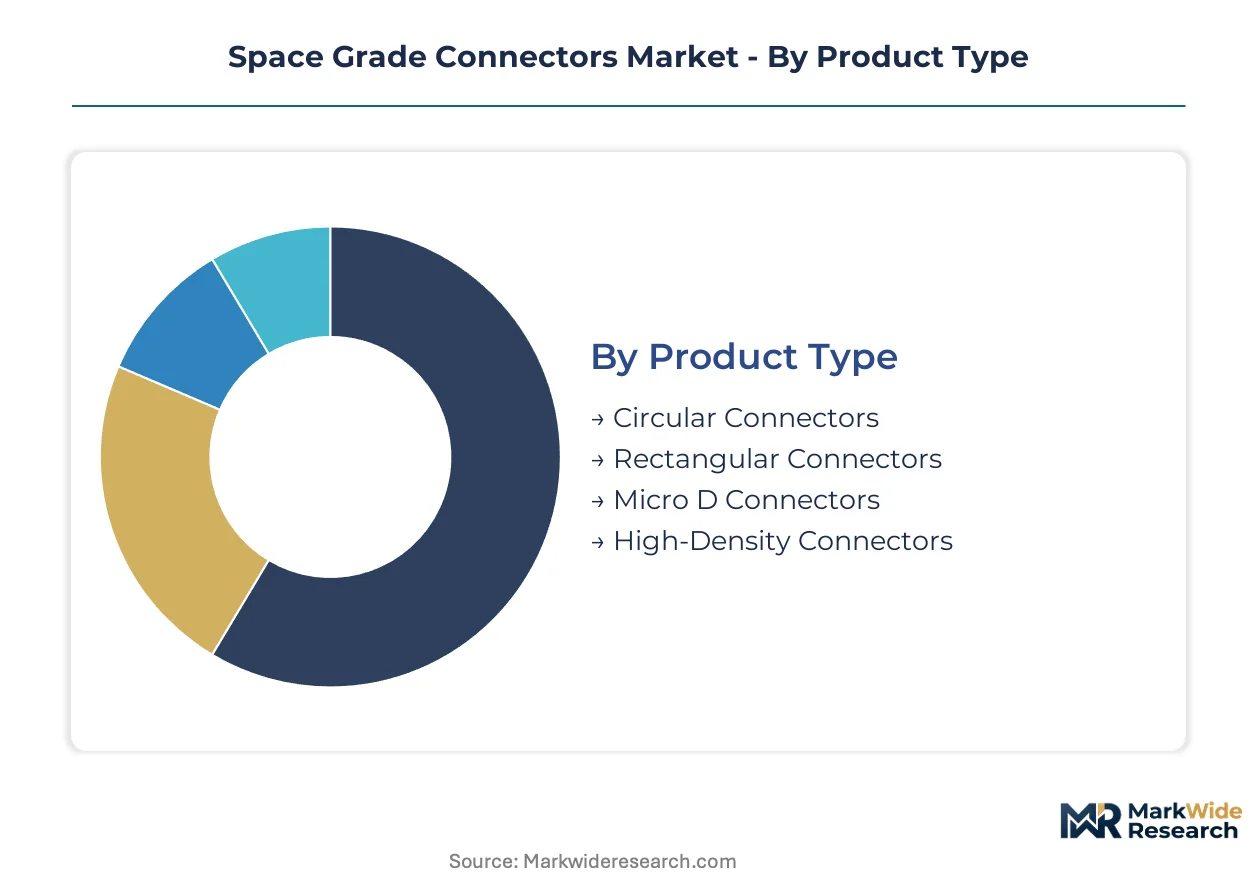
Segmentation in the space grade connectors market reflects divergent technical requirements across orbital environments, material science trajectories, and qualification regimes. Each dimension shapes procurement patterns and supplier positioning differently.
Product Type:
Circular connectors anchor legacy compatibility across launch-vehicle and satellite bus architectures, while rectangular and high-density variants address payload miniaturization pressures.
- Circular Connectors:Aluminum or titanium housings with threaded coupling mechanisms dominate launch-vehicle harness assemblies. Demand concentrates in United States defense programs at Cape Canaveral and Vandenberg Space Force Base, where heritage mating interfaces resist specification changes.
- High-Density Connectors:Miniaturized pin arrays exceeding 200 contacts per square inch serve Earth observation payloads with severe form-factor constraints. Satellite constellation operators in Redmond and Hawthorne, California specify these for phased orbital plane deployment.
- Rectangular Connectors:Rack-and-panel configurations suit avionics bay installations with blind-mating requirements.
- Micro D Connectors:Subminiature footprints address CubeSat and small-satellite power distribution with reduced mass penalties.
The dominant share belongs to Circular Connectors, while High-Density Connectors are expanding most quickly as payload integration density escalates.
Material:
Mass-critical applications drive titanium and composite adoption, though aluminum retains cost-sensitive volume positions.
- Composite Materials:Carbon-fiber-reinforced polymer housings from Toray and Hexcel cut mass by 40% versus aluminum in non-hermetic satellite applications. Lockheed Martin and Boeing qualification programs in Denver and El Segundo, California are validating 15-year orbital lifetimes for constellation buses.
- Titanium:Additive manufacturing of Ti-6Al-4V housings compresses lead times for complex geometries while maintaining strength-to-weight ratios for deep-space missions. NASA JPL procurement in Pasadena, California favors these for Mars Sample Return thermal cycling requirements.
- Aluminum:6061-T6 and 7075 alloys remain standard for launch-vehicle stage separation harnesses.
- Stainless Steel:300-series variants serve hermetic sealing applications where CTE matching with glass feedthroughs matters.
Composite Materials command the steepest expansion trajectory, while Aluminum retains volume leadership in launch-vehicle applications.
Application:
End-use differentiation separates multi-decade military platforms from rapid-replacement commercial constellations.
- Satellite Systems:Geostationary, medium-Earth, and low-Earth orbit configurations each impose distinct thermal cycling and radiation exposure profiles. Commercial operators in Redmond, Washington and Hawthorne, California procure qualified interconnects in multi-thousand-unit batches for phased deployment.
- Launch Vehicles:Stage separation, avionics, and propulsion harnesses require connectors surviving vibration spectra exceeding 20 Grms. United Launch Alliance and SpaceX manufacturing in Decatur, Alabama and Hawthorne, California drive specification authority consolidation.
- Aerospace:Crewed spacecraft and space station modules demand NASA Standard 8739 workmanship compliance.
- Space Robotics:In-space servicing vehicles require connectors rated for repeated mating cycles in vacuum environments.
Satellite Systems absorb the dominant procurement volume, while Space Robotics is gaining share fastest on Northrop Grumman MEV program expansion.
Certification:
Qualification regimes gate market access and sustain incumbent supplier advantages through certification infrastructure investments.
- NASA Standard:Updated NASA-STD-8739 workmanship requirements for spaceflight hardware mandate higher qualification thresholds. Domestic suppliers with existing certification infrastructure in California, Texas, and Florida capture Artemis lunar surface system contracts.
- MIL-STD:MIL-STD-1553 and MIL-STD-38999 protocols govern military-space crossover applications. Defense contracts at Lockheed Martin Space in Littleton, Colorado and Northrop Grumman in Redondo Beach, California specify these for platform commonality.
- AS9100:Aerospace quality management frameworks align with ISO 9001 but add sector-specific traceability requirements.
- ISO 9001:Baseline quality certification serves commercial satellite operators with reduced heritage requirements.
MIL-STD certification holds the largest qualified vendor base, while NASA Standard is climbing the fastest on Artemis program procurement acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA certification requirements for commercial spaceflight hardware anchor procurement gravity in the United States, while ESA's ECSS specifications and JAXA's equivalent standards create parallel certification burdens across European and Japanese supply chains.
United States
NASA's Artemis program and SpaceX's Starlink constellation drive multi-thousand-unit connector orders. NASA Standard 8739 workmanship requirements tighten qualification thresholds for lunar surface systems. Manufacturing clusters in Hawthorne, California and Decatur, Alabama consolidate specification authority at prime contractor level.
France
ArianeGroup launch vehicle production and Thales Alenia Space satellite manufacturing sustain qualified vendor demand. ESA's ECSS-Q-ST-70-38C standards govern soldering and assembly processes for European spaceflight hardware. Toulouse and Cannes-Mandelieu industrial corridors host specialized connector qualification laboratories.
Germany
OHB System and Airbus Defence and Space satellite platforms require MIL-STD-38999 qualified interconnects for military-space crossover applications. The country's national aerospace regulator enforces REACH Annex XVII compliance for cadmium-plated hardware sunset dates. Bremen and Ottobrunn manufacturing sites validate composite housing technologies for constellation buses.
Japan
JAXA's H3 launch vehicle and HTV-X cargo spacecraft programs specify domestically qualified connectors for government missions. METI industrial standards align with ISO 19683 for small spacecraft electrical interfaces. Tsukuba Space Center and Nagoya aerospace clusters coordinate qualification testing with prime contractors.
United Kingdom
Surrey Satellite Technology and Airbus UK small-satellite production compress procurement cycles for radiation-hardened interconnects. The UK Space Agency's National Space Strategy prioritizes domestic supply chain resilience for critical space components. Harwell Space Cluster and Stevenage manufacturing facilities concentrate connector specification expertise.
Space Grade Connectors Market Competitive Environment
Capability concentration sits with heritage-qualified specialists; scale advantage sits with diversified interconnect conglomerates. The vendor base separates into three tiers: established aerospace-electronics houses with NASA and DoD certification infrastructure, mid-size specialists in hermetic or high-density niches, and emerging composite-material entrants. Consolidation pressure intensifies as constellation operators consolidate procurement authority at prime contractor level, forcing tier-2 harness suppliers into specification-taker positions. Strategic moves center on additive manufacturing qualification for titanium housings and backward integration into precious metal contact plating.
Among diversified interconnect conglomerates, TE Connectivity and Amphenol Aerospace occupy positions reflecting broad qualification across military and civil space programs. Glenair Inc. sits within the hermetic sealing specialist tier. ITT Inc., Radiall, and Fischer Connectors represent European and US heritage-qualified vendors with established ESA and NASA certification infrastructure. These named entities exemplify archetype positioning rather than specific market share claims.
| Leading Market Players |
|---|
| ITT Inc. |
| Radiall |
| TE Connectivity |
| Omnetics Connector Corporation |
| Fischer Connectors |
| Amphenol Aerospace |
| Glenair Inc. |
| Harwin plc |
| Eaton Corporation (SOURIAU SUNBANK) |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in United States hermetic sealing fabrication is tightening supplier pricing power for NASA-qualified interconnects while compressing delivery windows for constellation operators. Gold-plated contact requirements and titanium alloy feedstock constraints are amplifying cost pass-through dynamics for domestic manufacturers serving Artemis and defense programs.
Pricing Analysis
United States pricing for NASA-STD-8739 qualified connectors commands substantial premiums over ISO 9001 commercial-grade equivalents, with European ECSS-certified products occupying intermediate positioning. Three-tier pricing structure across heritage-qualified, mid-tier AS9100, and commercial-grade levels reflects certification infrastructure investment recovery and manual workmanship intensity. Pricing pressure stems from SpaceX and Amazon procurement consolidation at prime contractor level, forcing tier-2 harness suppliers into specification-taker roles with compressed margins. Constellation operators exhibit highest price sensitivity for high-density payload interconnects, while lunar surface system contractors demonstrate lowest sensitivity due to qualification switching costs.
Supply Chain Analysis
ITAR and EAR export controls restrict titanium alloy additive manufacturing equipment and precious metal plating chemistry flows to qualified domestic suppliers, fragmenting global vendor pools. Manufacturing concentrates in the United States, France, and Germany for hermetic sealing and radiation-hardened assembly. Raw material dependencies center on gold contact plating chemistry, Ti-6Al-4V powder feedstock, and carbon-fiber-reinforced polymer housings from Toray and Hexcel. Single-source vulnerability concentrates in United States hermetic glass feedthrough production. Distribution runs through prime contractor specification authority at Lockheed Martin, Boeing, and Northrop Grumman facilities, displacing traditional subsystem vendor selection.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
LEO constellation deployment acceleration and NASA's updated workmanship standards are creating a high-growth disruption window for qualified interconnect suppliers. The tension between volume scaling and heritage reliability protocols is reshaping competitive positioning across certification tiers.
For Market Incumbents: Pre-empt composite housing qualification programs before REACH cadmium-plating sunset dates force parallel certification investments. Lock in additive manufacturing capacity for titanium Ti-6Al-4V geometries to compress lead times against emerging entrants. Defensive consolidation should target hermetic sealing specialists in Denver and El Segundo industrial corridors to secure Artemis lunar surface system contracts.
For New Entrants and Emerging Players: Establish a beachhead in CubeSat micro-connector segments where ISO 9001 requirements permit faster market entry without NASA infrastructure investment. Target European ESA ECSS certification pathways as dual-source assurance demands from JAXA and ESA programs create vendor pool expansion. Go-to-market positioning should emphasize REACH-compliant tin-zinc coating alternatives for satellite prime contractors with dual US-EU supply chains.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across additive manufacturing qualification and precious metal contact plating infrastructure. Long-term viability over a multi-year horizon favors heritage-qualified specialists with existing NASA and DoD certification infrastructure over de novo entrants facing 18-24 month AS9100 cycles. Acquisition targets should display established ECSS or JAXA parallel certification to capture dual-source assurance mandates. The signal to watch is constellation operator procurement consolidation velocity at SpaceX Hawthorne and Redmond facilities.
| Strategic Initiative | Industry Significance |
|---|---|
| Composite Housing Qualification | Lockheed Martin and Boeing 15-year orbital lifetime programs validate carbon-fiber-reinforced polymer mass reduction. |
| Additive Manufacturing Certification | NASA JPL Ti-6Al-4V procurement for Mars Sample Return compresses lead times for complex geometries. |
| REACH-Compliant Coating Transition | Tin-zinc and ion-vapor-deposited aluminum alternatives secure European satellite prime contractor supply positions. |
| Hermetic Sealing Capacity Expansion | Northrop Grumman MEV program repeated vacuum mating cycle requirements drive specialized fabrication investment. |
| Dual Certification Infrastructure | Parallel NASA-STD-8739 and ECSS-Q-ST-70-38C qualification captures ESA and JAXA dual-source assurance demand. |
Study Parameters
Initial hypotheses were tested against primary input from satellite constellation procurement directors, NASA workmanship certification officers, prime contractor supply chain executives, and hermetic sealing manufacturing engineers, then refined through secondary validation. Primary fieldwork combined structured interviews with tier-1 connector suppliers and tier-2 harness assembly houses across Hawthorne, Decatur, and Denver manufacturing clusters. Secondary sources included NASA procurement databases, ESA ECSS specification registries, FAA commercial spaceflight certification records, and defense contract award filings. Bottom-up unit demand estimates from constellation deployment schedules were triangulated against top-down market value reconstructions.
Demand-supply balance modeling across the projection horizon incorporated satellite bus architecture evolution, launch vehicle production rates, and in-space servicing vehicle deployment timelines. Segmentation dimensions covered product type circular-to-high-density mix, material aluminum-titanium-composite trajectories, application satellite-launch vehicle-robotics splits, and certification NASA-MIL-STD-AS9100-ISO tiering. CAGRs were derived from unit volume buildups by orbital plane deployment phase and value-per-unit escalation from miniaturization density requirements. Industry-specific forecast inputs captured Artemis lunar surface system procurement acceleration and REACH Annex XVII compliance deadline effects.
Sensitivities concentrate around constellation operator bankruptcy or consolidation, titanium alloy powder supply disruption, and NASA workmanship standard further tightening. Forecasts reflect assumptions on LEO deployment cadence, qualification timeline compression feasibility, and prime contractor vertical integration boundaries. Material shifts in ITAR/EAR export control scope or ESA cadmium-plating exemption extensions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Connectors
Telecom Mounting Hardware Market
Connectors
SATA Connector Market
Connectors
Line Clamp Market
Connectors
DIN Connectors Market
Connectors
Underwater Mate Connectors Market
Connectors
Japan Connector Market
Connectors
Terminal Pins Market
Connectors
Small Bore Connectors Market
Connectors
LCP Connectors Market
Connectors
Mexico Connector Market
Connectors
Connector and Terminal Systems for Harsh Environment Wiring Market
Connectors
5G Connector Market
Connectors
PCI-E Connectors Market
Connectors
Automotive Data Connectors Market
Connectors
Connector Kits Market
Connectors
Connector Adapter Kits Market