
 Australia Connector Market | 2026-2036
Australia Connector Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Connector Market Insights
Distributor networks serving industrial automation firms is narrowing as direct procurement channels from manufacturers gain share. TE Connectivity Ltd leverages its broad product portfolio to sustain service levels across Australian mining and energy projects. Amphenol Corporation anchors its position through specialized harsh-environment connectors designed for defense and aerospace applications. Molex LLC competes by extending its PCB connector range into telecommunications infrastructure builds.
A connector is an electromechanical device engineered to join electrical terminations and create complete circuits, typically incorporating contact pins, insulating housings, and locking mechanisms rated for specific voltage, current, and environmental sealing levels. Its primary commercial purpose is to enable reliable signal and power transmission across modular equipment assemblies while permitting field serviceability. Fiber optic connectors command premium positioning in telecommunications and defense applications where bandwidth density and electromagnetic immunity outweigh cost sensitivity. Circular connectors dominate transportation equipment and aerospace systems due to their mechanical robustness and standardized MIL-specification mating interfaces. PCB connectors occupy high-volume production lanes in consumer electronics manufacturing where miniaturization and surface-mount compatibility drive specification decisions.
TGA standards govern connector safety in medical device applications while ACMA EMC frameworks mandate electromagnetic compatibility certification for products deployed in Australian telecommunications infrastructure. The country's national electrical regulator enforces AS/NZS compliance markings that shape import access and local assembly requirements for industrial connector categories. Stakeholders must monitor evolving defense procurement localization policies and energy grid interconnection standards that will redirect specification priorities across the supply base.
Market Dynamics
Sovereign capability programs in Australian defense procurement are forcing connector suppliers to establish local assembly and certification infrastructure, compressing import-dependent supply chains while elevating domestic manufacturing requirements.
Growth Catalysts
- Defense localization mandates:The Australian government's sovereign industrial capability priorities require domestic content in military interconnect systems, redirecting procurement toward local assembly partners.
- ACMA EMC frameworks:Electromagnetic compatibility certification requirements for telecommunications infrastructure are expanding the addressable market for shielded connector architectures.
- Mining automation:Autonomous haulage and remote operations in Western Australian iron ore and Queensland coal basins are consuming ruggedized power and data interconnect at accelerated rates.
Market Restraints
- Copper and gold price volatility:Contact material costs in precision connector manufacturing fluctuate with commodity markets, compressing margin visibility for standardized product lines.
- East Asian supply concentration:PCB connector substrate and precision stamping capacity clusters in Taiwan and South Korea create geographic vulnerability for Australian importers.
- Miniaturization physics:Signal integrity degradation at sub-millimeter contact pitches limits connector density gains in high-frequency medical imaging equipment.
Strategic Opportunities
- Queensland renewable energy zones:Grid-scale solar and wind interconnection projects in the Sunshine State require high-current DC connectors with localized technical support.
- TGA medical device registration:Streamlined approval pathways for established connector families create first-mover advantage in diagnostic imaging and patient monitoring equipment.
- Fiber-to-the-premises rollout:NBN infrastructure completion drives demand for field-installable optical connectors with tool-less termination features.
Industry Challenges
- AS/NZS certification timelines:Electrical safety marking requirements for industrial connectors extend product launch schedules by four to six months versus comparable EU or US approvals.
- Defense security clearance bottlenecks:Personnel vetting delays constrain engineering access to classified project specifications, slowing custom connector development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Connector Market |
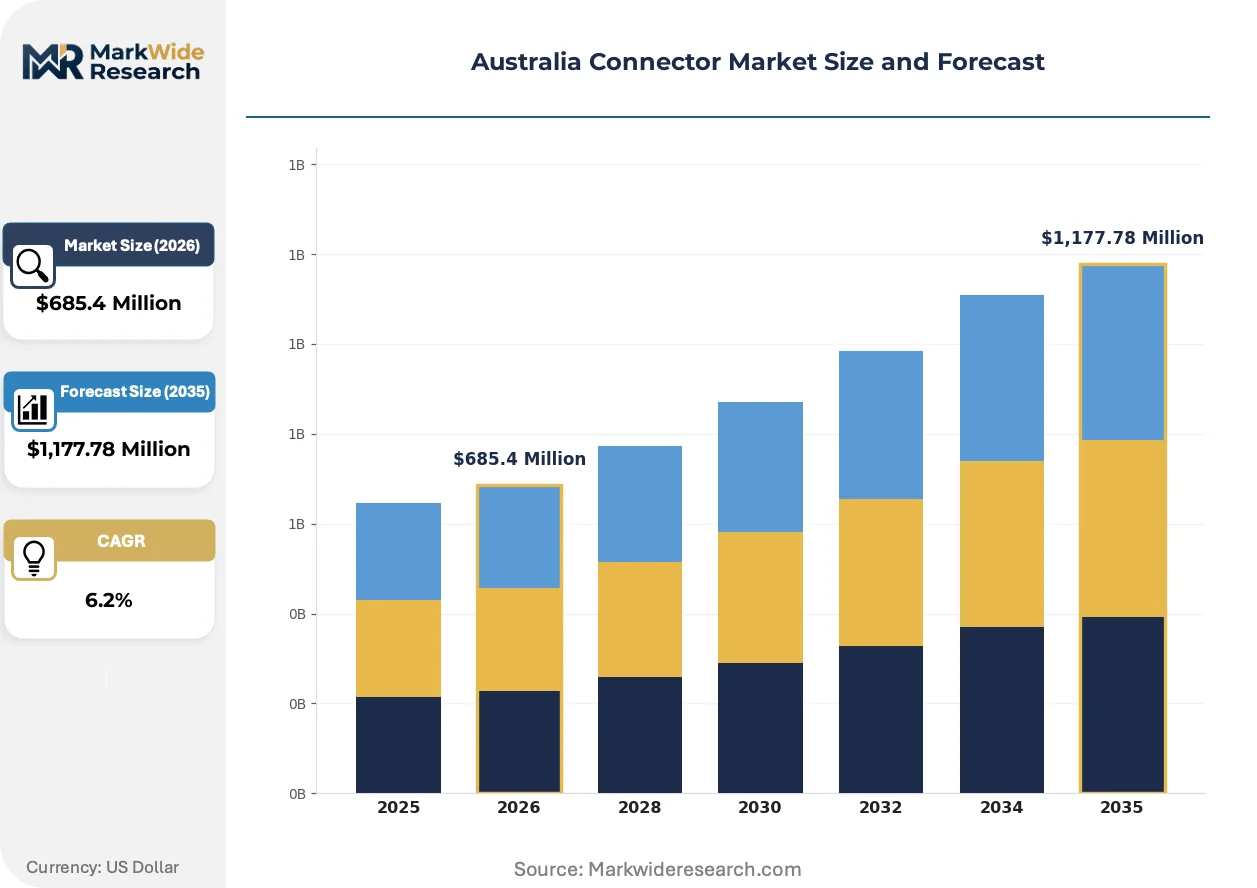
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,177.78 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Circular Connectors, Rectangular Connectors, Coaxial Connectors, Fiber Optic Connectors, PCB Connectors Technology: Crimp, Solder, IDC, Threaded, Push-Pull Application: Telecommunications, Aerospace Systems, Consumer Electronics, Renewable Energy, Transportation Equipment End User: Electronics Manufacturers, Utility Providers, Defense Contractors, Industrial Automation Firms, Research Laboratories |
| Companies Covered | TE Connectivity Ltd, Amphenol Corporation, Molex LLC, 3M, Corning Incorporated, Furukawa Electric Co Ltd, OFS Fitel, Aptiv PLC, Optical Cable Corp, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Connector Market Trends and Innovations
Connector architectures across Australian industrial markets are pivoting toward modular, tool-less designs that reduce field installation complexity while accommodating harsh-environment sealing requirements in mining and defense applications.
Hybrid fiber-copper interconnect systems are migrating from niche military applications into mainstream mining automation and energy infrastructure projects. Rio Tinto and BHP are specifying these architectures for autonomous vehicle telemetry networks. The technology is migrating from custom defense procurement into standardized industrial product catalogs, compressing development cycles for ruggedized field-deployable systems.
TGA medical device regulations are tightening electrical safety and biocompatibility requirements for patient-contacting connectors. Manufacturers must now submit comprehensive material characterization data for housing polymers and contact platings. Implantable and diagnostic imaging equipment categories face the steepest compliance burden, with several suppliers establishing dedicated Australian regulatory affairs functions.
Direct procurement from manufacturers is displacing traditional distributor relationships among mid-sized automation integrators in New South Wales and Victoria. End-users are consolidating supplier relationships to secure volume pricing and application engineering support. This pattern is most visible in automotive component manufacturing and food processing equipment sectors, where procurement teams prioritize technical responsiveness over inventory breadth.
Australia Connector Market Segmentation
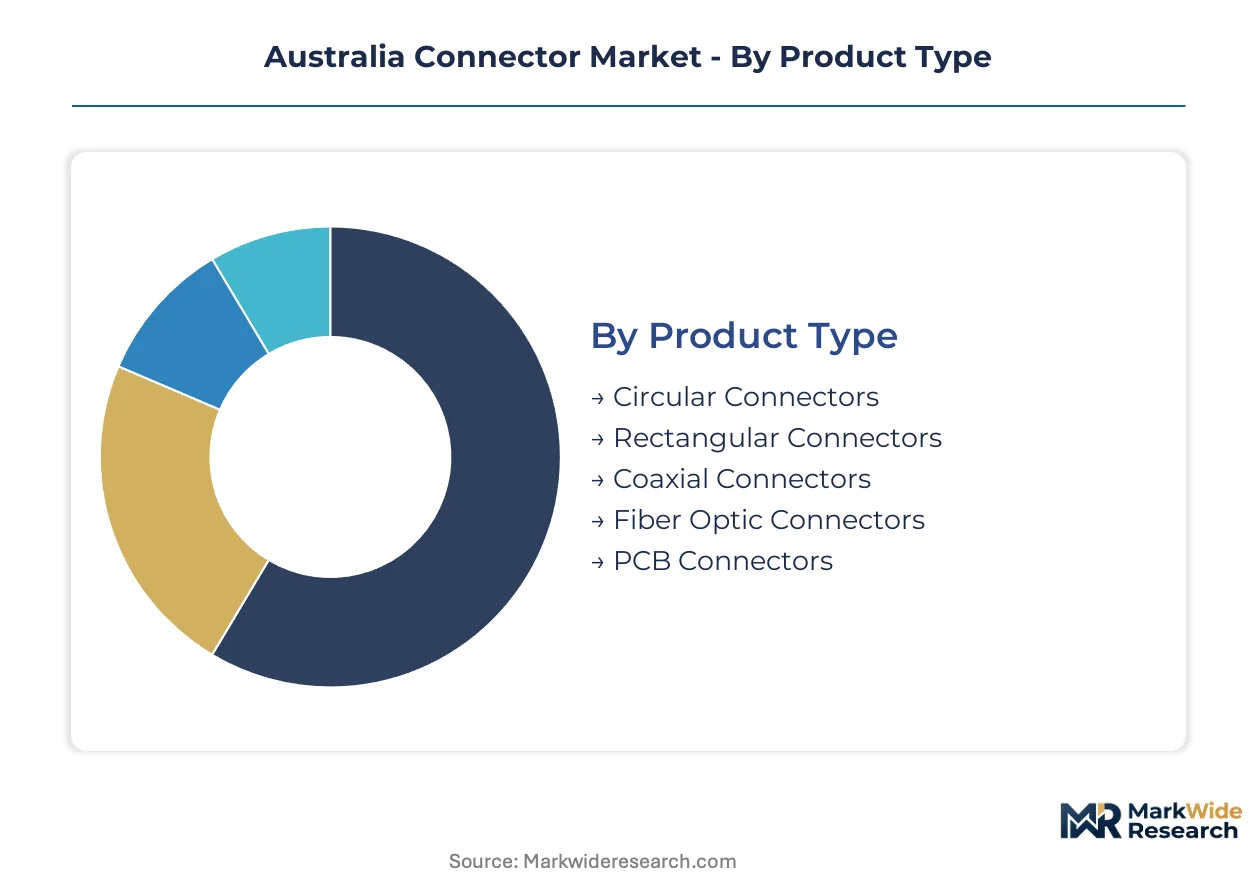
Connector specification in Australia diverges sharply across defense, medical, and mining verticals, with each imposing distinct sealing, shielding, and certification requirements that reshape supplier priorities. Segmentation clarity enables procurement teams to align contact geometry and termination technology with the harsh-environment demands of Western Australian autonomous haulage networks and sovereign capability programs.
Product Type:
After-sales service intensity varies dramatically by connector form factor, with circular and fiber optic architectures demanding specialized field engineering support that rectangular and PCB variants rarely require.
- Circular Connectors:These electromechanical interfaces incorporate threaded or bayonet locking mechanisms with IP67+ environmental sealing rated for vibration and shock loads. Defense procurement in South Australia and aerospace maintenance facilities in Victoria concentrate demand, driven by sovereign capability mandates requiring local assembly certification.
- Fiber Optic Connectors:Precision ceramic ferrule assemblies enable single-mode and multimode optical alignment with insertion loss below 0.3 dB. NBN infrastructure rollout in New South Wales and Queensland drives consumption, with field-installable variants commanding premium positioning due to tool-less termination requirements.
- Rectangular Connectors:High-density pin arrays suit rack-mounted telecommunications and industrial control equipment with standardized DIN or modular housing formats.
- Coaxial Connectors:Impedance-matched interfaces for RF signal transmission anchor broadcasting infrastructure and cellular base station deployments.
- PCB Connectors:Surface-mount and through-hole terminations dominate consumer electronics manufacturing clusters in Sydney and Melbourne.
Circular connectors hold the largest share; momentum sits with fiber optic architectures expanding most quickly.
Technology:
Termination method selection hinges on field repairability versus factory automation, with crimp and push-pull formats dominating mining and defense applications where technician access is constrained.
- Crimp:Mechanical compression of contact barrels onto conductor strands delivers gas-tight electrical interfaces without thermal damage to insulation. Autonomous haulage systems in Western Australia's Pilbara region specify crimp termination for power distribution harnesses, driven by vibration resistance requirements in 24/7 operating environments.
- Push-Pull:Rapid mating mechanisms with positive latching enable blind-mate connections in confined equipment bays. Medical device manufacturers in Victoria prioritize push-pull formats for diagnostic imaging equipment, constrained by TGA biocompatibility and electrical safety certification timelines.
- Solder:Permanent metallurgical bonds suit high-reliability aerospace and defense applications with limited field service requirements.
- IDC:Insulation displacement connections accelerate harness assembly for telecommunications and industrial automation equipment.
- Threaded:Robust mechanical coupling withstands extreme shock and vibration in heavy transportation and mining machinery.
Crimp technology dominates installed base; push-pull formats are gaining share fastest in medical and defense procurement.
Application:
Application segmentation reflects divergent performance specifications, with aerospace and renewable energy imposing the most stringent qualification protocols on connector suppliers.
- Aerospace Systems:MIL-specification circular connectors with aluminum or composite housings withstand altitude cycling and electromagnetic interference. Queensland and Victoria maintenance, repair, and overhaul facilities concentrate demand, driven by defense fleet modernization and commercial aviation recovery.
- Renewable Energy:High-current DC connectors with silver-plated contacts and arc suppression features enable solar farm and wind turbine interconnection. Queensland's planned renewable energy zones in the Darling Downs and Wide Bay-Burnett regions anchor procurement, constrained by grid connection standard evolution.
- Telecommunications:Shielded coaxial and fiber optic interfaces support 5G infrastructure and NBN completion.
- Consumer Electronics:Miniaturized PCB and I/O connectors serve manufacturing operations in Sydney and Melbourne.
- Transportation Equipment:Ruggedized power and data interconnects enable rail signaling and electric vehicle charging infrastructure.
Aerospace systems command premium positioning; renewable energy exhibits the steepest expansion trajectory.
End User:
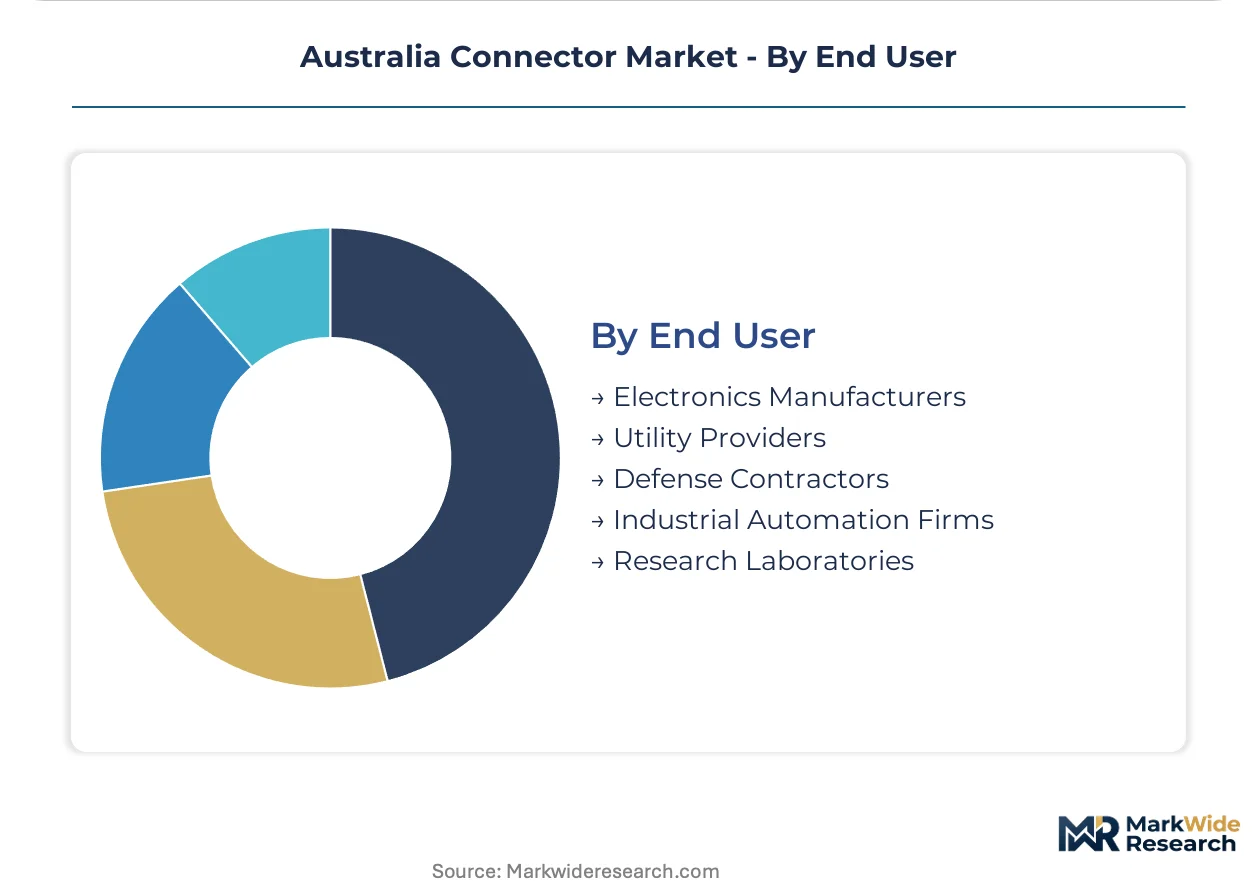
End user segmentation reveals procurement consolidation patterns, with defense contractors and utility providers consolidating supplier relationships to secure technical responsiveness and volume pricing.
- Defense Contractors:Sovereign capability programs mandate Australian-sourced content in military interconnect systems, forcing suppliers to establish local assembly and certification infrastructure. South Australian shipbuilding and Victorian aerospace clusters concentrate demand, driven by security clearance requirements and classified specification access.
- Industrial Automation Firms:Mining automation integrators in Western Australia and Queensland specify ruggedized connectors for autonomous vehicle telemetry and remote operations centers. Direct procurement from manufacturers is displacing traditional distributor relationships among mid-sized systems integrators in Perth and Brisbane.
- Electronics Manufacturers:Consumer and automotive component producers in New South Wales prioritize miniaturized PCB connectors with surface-mount compatibility.
- Utility Providers:Transmission and distribution network operators specify high-voltage interconnects for grid modernization.
- Research Laboratories:Academic and government R&D facilities in Canberra and Sydney drive demand for specialized test and measurement interfaces.
Defense contractors anchor premium segment revenue; industrial automation firms are climbing the fastest as mining automation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing leverage in New South Wales and Victoria outstrips Queensland and Western Australia by fifteen to twenty percent, reflecting concentrated electronics manufacturing clusters and defense procurement density in the southeastern states.
New South Wales
Telecommunications infrastructure and medical device manufacturing anchor connector demand in Sydney and surrounding industrial corridors. TGA certification requirements for patient-contacting interconnects extend product launch timelines, favoring established suppliers with dedicated regulatory affairs functions. The Sydney electronics manufacturing cluster concentrates PCB connector consumption for consumer and automotive component production.
Victoria
Aerospace maintenance facilities and defense contractors in Melbourne drive premium circular connector procurement for fleet modernization programs. ACMA EMC frameworks mandate shielded architectures for telecommunications deployments, compressing specification windows for non-compliant imports. The state's sovereign capability partnerships with defense primes elevate local assembly requirements for military interconnect systems.
Queensland
Renewable energy zone development and mining automation projects in Brisbane and regional centers consume high-current DC and ruggedized fiber optic interconnects. Grid interconnection standards for solar and wind farms remain under evolution, creating specification uncertainty for utility-scale connector procurement. The Darling Downs and Wide Bay-Burnett regions anchor renewable energy connector demand as transmission infrastructure expands.
Western Australia
Autonomous haulage systems in the Pilbara iron ore basin specify crimp-terminated power and data connectors for 24/7 operating environments. Mining automation integrators in Perth are consolidating supplier relationships through direct procurement channels, displacing traditional distributor networks. Remote operations centers require field-repairable interconnect architectures with vibration resistance ratings exceeding standard industrial specifications.
South Australia
Naval shipbuilding programs in Adelaide enforce sovereign industrial capability mandates for military-grade interconnect systems. Defense security clearance bottlenecks constrain engineering access to classified specifications, slowing custom connector development cycles. The Osborne naval shipyard concentrates demand for MIL-specification circular connectors with local assembly certification.
Australia Connector Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower portfolios but deeper termination expertise. The vendor base organizes around three archetypes: diversified interconnect conglomerates with broad product catalogs, harsh-environment specialists focused on defense and mining verticals, and fiber optic component providers serving telecommunications infrastructure. Consolidation pressure operates through defense procurement localization requirements and direct channel expansion by major manufacturers.
Among diversified interconnect suppliers, TE Connectivity Ltd, Amphenol Corporation, and Molex LLC occupy positions spanning industrial automation, defense, and telecommunications verticals. These entities exemplify scale-driven archetypes with sufficient portfolio breadth to sustain service levels across Australian mining and energy projects while meeting sovereign capability assembly requirements. Their competitive positioning reflects capacity to navigate TGA medical device registration and ACMA EMC certification frameworks without partner dependencies.
| Leading Market Players |
|---|
| TE Connectivity Ltd |
| Amphenol Corporation |
| Molex LLC |
| 3M |
| Corning Incorporated |
| Furukawa Electric Co Ltd |
| OFS Fitel |
| Aptiv PLC |
| Optical Cable Corp |
| Others |
Pricing and Supply Chain Analysis
Taiwan and South Korea substrate concentration feeds margin compression downstream, with Australian importers absorbing volatility in precision stamping capacity while defense contractors capture premium pricing through sovereign capability mandates.
Pricing Analysis
Configured-to-order circular connectors for defense applications command spreads exceeding standard PCB variants by certification grade and local assembly requirements. Pricing stratifies across MIL-specification, industrial-grade, and commercial tiers, with TGA medical device registration and ACMA EMC compliance driving differentiation. Cost compression in standard industrial segments intensifies as direct procurement channels displace distributor markups. Mining automation integrators in Western Australia exhibit highest price sensitivity, while defense contractors prioritize technical responsiveness over unit economics.
Supply Chain Analysis
Tariff exposure between East Asian manufacturing hubs and Australian import channels dominates supply chain risk assessment for connector substrates and contact materials. Precision stamping capacity clusters in Taiwan, South Korea, and Japan anchor upstream supply, with copper and gold contact platings drawing from commodity markets. Single-source vulnerability concentrates in ceramic ferrule assemblies for fiber optic architectures. Distribution runs through direct manufacturer channels for mid-sized automation integrators, while defense procurement mandates local assembly partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wireless interconnect and contactless power transmission pose substitution threats that incumbent connector suppliers must neutralize through performance differentiation and regulatory embedding.
For Market Incumbents: Harden certification moats by embedding TGA medical device registration and ACMA EMC compliance into product architectures before wireless alternatives achieve parity. Deepen backward integration into contact plating operations to offset copper and gold price volatility. Anchor sovereign capability partnerships with South Australian shipbuilding and Victorian aerospace clusters to secure classified specification access. For New Entrants and Emerging Players: Queensland renewable energy zones and fiber-to-the-premises field-installable optical connectors represent the most penetrable entry points, with grid interconnection standards still evolving and tool-less termination features commanding premium positioning. Target mining automation integrators in Perth and Brisbane through direct technical sales channels, displacing legacy distributor relationships with application engineering responsiveness. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed harsh-environment specialists holding defense and mining vertical expertise but lacking medical device regulatory infrastructure. Five-to-ten year viability hinges on diversification beyond single-vertical concentration. Monitor TGA medical device registration backlog clearance as inflection indicator for diagnostic imaging and patient monitoring equipment procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Local Assembly Certification Investment | Sovereign capability mandates in South Australian naval shipbuilding require domestic content verification for MIL-specification circular connectors. |
| Hybrid Fiber-Copper Product Line Expansion | Rio Tinto and BHP autonomous haulage specifications are migrating hybrid architectures from defense into standardized mining automation catalogs. |
| TGA Regulatory Affairs Function Establishment | Dedicated Australian medical device registration teams compress product launch timelines for diagnostic imaging connector families. |
| Direct Procurement Channel Buildout | New South Wales and Victoria automation integrators are consolidating supplier relationships away from distributor networks toward manufacturer-direct technical support. |
| Push-Pull Termination Technology Development | Victorian medical device manufacturers prioritize rapid-mating formats for diagnostic equipment constrained by biocompatibility certification requirements. |
Research Methodology
A spread of perspectives from defense procurement officers, mining automation integrators, medical device regulatory affairs leads, and telecommunications infrastructure planners converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with connector specification engineers and procurement directors across New South Wales, Victoria, Queensland, and Western Australia. Secondary validation drew from ACMA EMC framework documentation, TGA medical device registration databases, Australian Bureau of Statistics trade data, and defense sovereign capability policy releases. Bottom-up segment sizing triangulated against top-down macroeconomic anchors.
Demand-supply-balance framing anchored the analytical approach across the projection horizon, with connector consumption modeled by product type, termination technology, application vertical, and end-user procurement pattern. Segmentation dimensions included circular versus fiber optic versus PCB form factors, crimp versus push-pull versus solder termination methods, and defense contractor versus industrial automation firm versus electronics manufacturer end-user categories. CAGRs derived from regression analysis against mining automation capex cycles, renewable energy interconnection project pipelines, and NBN infrastructure completion schedules.
Practitioners should monitor copper and gold commodity price movements, East Asian substrate capacity utilization, and TGA medical device registration processing times for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Connectors
USB Type-C Market
Connectors
Hybrid Fiber Optic Connectors Market
Connectors
Global Wired Interface Market
Connectors
Global Fiber Optic Connectors Market
Connectors
Hazardous Location Connectors Market
Connectors
Space Grade Connectors Market
Connectors
Underwater Connectors Market
Connectors
Small Bore Connectors Market
Connectors
Filtered Connectors Market
Connectors
5G Connector Market
Connectors
IC Socket Market
Connectors
Circular Connectors Market
Connectors
Global Automotive Connector Market
Connectors
Automotive Data Connectors Market
Connectors
Japan Connector Market
Connectors
Mexico Connector Market