
 Pin Retainer Market | 2026-2036
Pin Retainer Market Size, Share, and Industry Trends Forecast 2026-2036
Pin Retainer Market Insights
Digital thread integration across manufacturing execution systems is fragmenting traditional procurement channels for precision mechanical components. Seeger-Orbis GmbH leverages its European tooling footprint to serve tier-one automotive transmission builders. Rotor Clip Company anchors North American supply through specialized circlip and retaining ring production. Waldes Truarc competes on legacy brand recognition in aerospace specification channels.
A pin retainer is a mechanical fastening device, typically manufactured from spring steel or stainless steel with hardness ratings between 38 and 45 HRC, designed to secure components on shafts or within bores through radial tension or mechanical interference. Cotter pins and split pins dominate agricultural and marine maintenance segments due to low unit cost and field-service simplicity, while spring pins and roll pins capture machine assembly applications where vibration resistance and reusability command premium positioning. Titanium material grades are gaining specification in aerospace equipment as OEMs pursue weight reduction targets without sacrificing shear strength.
FDA material safety standards govern stainless steel grades used in food-processing machinery assemblies, while REACH restrictions in Europe limit hexavalent chromium surface treatments common to carbon steel retainers. The FAA's continuing airworthiness directives influence fastener replacement protocols for commercial aviation maintenance providers. Stakeholders must monitor evolving alloy certification requirements across multiple regulator jurisdictions to preserve market access.
Market Dynamics
Airframe OEM procurement cycles are compressing supplier lead times for precision fasteners, forcing retainer manufacturers to synchronize production with just-in-time assembly schedules across multiple aerospace programs.
Growth Catalysts
- Titanium alloy specifications:Aerospace equipment manufacturers specify Ti-6Al-4V grades for weight-critical applications, expanding addressable demand for high-performance retainers.
- REACH material restrictions:European ECHA enforcement against hexavalent chromium plating accelerates stainless steel substitution in industrial machinery.
- Transmission rebuild volumes:Germany's automotive belt sustains replacement-part demand for circlips and snap rings in powertrain remanufacturing.
Market Restraints
- Spring steel price volatility:Alloy surcharges on 1070 and 1095 carbon grades compress margin stability for high-volume producers.
- Specialized heat-treatment capacity:Vacuum furnace availability concentrates in Ohio and Baden-Württemberg, creating geographic bottlenecks for hardness certification.
- Adhesive bonding substitution:Structural anaerobic compounds displace mechanical retainers in light-assembly consumer electronics.
Strategic Opportunities
- India PLI scheme:Production-linked incentives for automotive component manufacturing attract retainer suppliers to Pune and Chennai industrial corridors.
- Additive manufacturing integration:Binder-jet production of 17-7PH stainless geometries enables lot-size-one customization for MRO providers.
- FAA continuing airworthiness directives:Mandatory fastener replacement intervals for aging commercial fleets generate recurring aftermarket demand.
Industry Challenges
- AS9100D certification timelines:Aerospace quality system accreditation requires 18-24 month implementation cycles, delaying market entry for new suppliers.
- Legacy ERP integration:Digital thread requirements for MES connectivity force capital expenditure on shop-floor data infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pin Retainer Market |
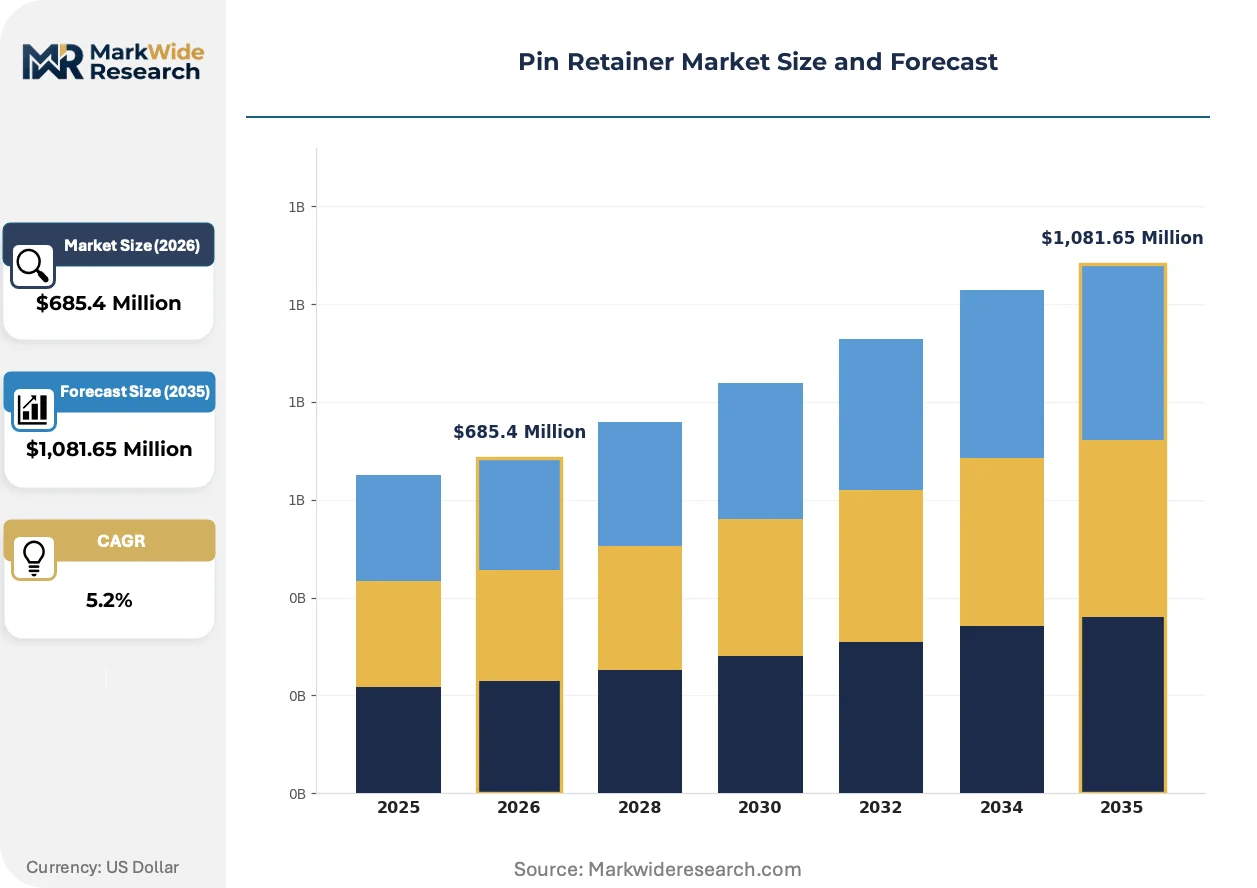
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,081.65 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spring Pin, Roll Pin, Cotter Pin, Dowel Pin, Taper Pin, Split Pin Material: Stainless Steel, Carbon Steel, Brass, Aluminum, Titanium, Bronze Application: Machine Assembly, Aerospace Equipment, Consumer Electronics, Agricultural Implements, Construction Machinery, Marine Equipment End User Industry: OEM Manufacturers, Repair Workshops, Fabrication Units, Maintenance Providers, Engineering Firms, Industrial Suppliers |
| Companies Covered | Seeger-Orbis GmbH, Rotor Clip Company, Waldes Truarc, Hugo Benzing, Apex Fasteners, SKF Group, Timken Company, NTN Corporation, Schaeffler AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pin Retainer Market Trends and Innovations
Material science advances and regulatory chemistry restrictions are reconfiguring specification standards across precision fastening. Digital manufacturing workflows are compressing prototype-to-production cycles for custom geometries.
Shape-memory nickel-titanium alloys enable self-actuating retention mechanisms that activate at specific thermal thresholds. Medical device manufacturers in Minnesota and Massachusetts specify these for implantable instrument assemblies. Conventional spring steel circlips with manual installation tools is rendering obsolete in catheter and endoscope applications where space constraints prohibit mechanical access.
EPA enforcement of TSCA Section 6 restrictions on per- and polyfluoroalkyl substances limits PTFE-based dry-film lubricants historically applied to stainless steel retainers. Surface treatment houses in Michigan and Pennsylvania are qualifying molybdenum disulfide and tungsten disulfide alternatives. Food-processing machinery OEMs face the tightest compliance windows, with FDA equipment validation protocols requiring lubricant requalification within 24-month transition periods.
Consolidated procurement platforms for MRO inventory are displacing traditional distributor relationships in industrial maintenance. Large fleet operators in Texas and Alberta negotiate direct specifications with retainer manufacturers, bypassing regional fastener distributors. This channel compression is most pronounced in oilfield services, where rig operators standardize on single-source agreements for API-certified retaining hardware.
Pin Retainer Market Segmentation
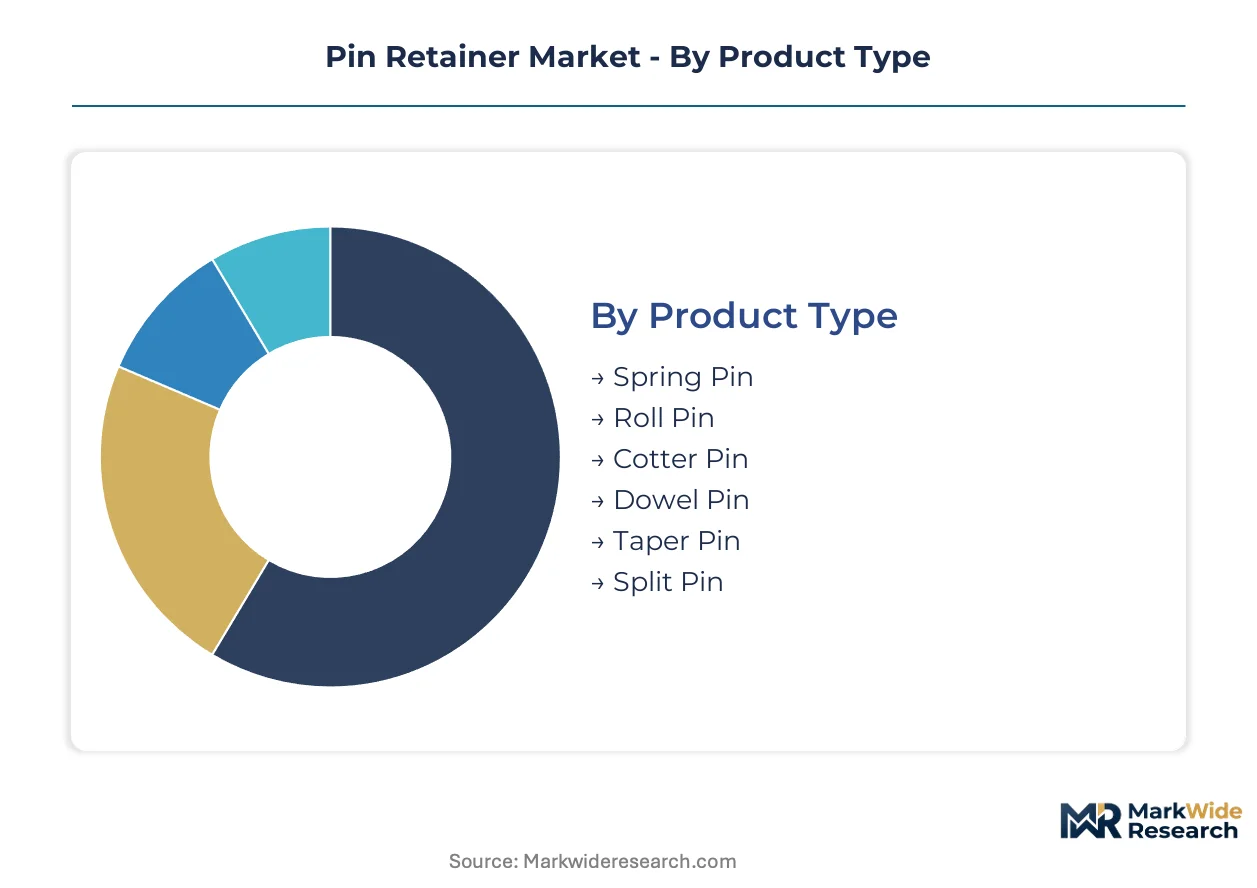
Pin retainer procurement patterns diverge sharply across material specifications and end-use severity. Segmentation reveals how aerospace-grade titanium alloys command fundamentally different supply chains than agricultural cotter pins.
Product Type:
Cost tier determines manufacturing complexity and margin structure across mechanical fastening categories.
- Spring Pin:Manufactured from coiled spring steel strip with precise radial tension characteristics. Machine assembly lines in Germany's automotive belt specify these for vibration-resistant shaft retention in transmission housings.
- Roll Pin:Spiral-wound construction provides distributed load bearing and reusability. Aerospace equipment manufacturers in Toulouse and Wichita specify roll pins for control surface actuators where shear strength tolerances are non-negotiable.
- Cotter Pin:Simple split-wire design dominates field maintenance in marine and agricultural segments.
- Dowel Pin:Precision-ground cylinders align mating components in jig and fixture applications.
- Taper Pin:Wedging action secures heavy machinery pivots and construction equipment linkages.
- Split Pin:Lowest unit cost drives specification in non-critical agricultural implement assemblies.
Spring Pin holds installed capacity. Roll Pin is rotating up the share rankings.
Material:
Application severity and regulatory chemistry restrictions reshape alloy selection across precision fastening.
- Stainless Steel:300-series austenitic grades with 38-42 HRC hardness ratings satisfy FDA material safety standards for food-processing machinery. ECHA REACH enforcement against hexavalent chromium plating accelerates substitution from carbon steel in European industrial equipment.
- Carbon Steel:1070 and 1095 spring grades offer cost-optimized hardness but face alloy surcharge volatility. Heat-treatment capacity concentrates in Ohio and Baden-Württemberg, creating geographic bottlenecks for certification.
- Brass:Corrosion resistance suits marine hardware and decorative architectural applications.
- Aluminum:Weight-critical consumer electronics assemblies specify anodized grades.
- Titanium:Ti-6Al-4V aerospace specifications expand addressable demand for weight-critical airframe retention.
- Bronze:Galvanic compatibility drives specification in saltwater marine environments.
Carbon Steel maintains volume leadership. Titanium is climbing the fastest on specification intensity.
Application:
End-use performance requirements fragment procurement channels and certification standards.
- Machine Assembly:High-volume automated installation demands consistent dimensional tolerance and feed reliability. German transmission builders synchronize just-in-time retainer procurement with assembly line cycle times.
- Aerospace Equipment:FAA continuing airworthiness directives mandate traceable fastener replacement intervals. AS9100D quality system accreditation requires 18-24 month implementation cycles, filtering supplier participation.
- Consumer Electronics:Structural anaerobic adhesives displace mechanical retainers in light-assembly applications.
- Agricultural Implements:Field-service simplicity favors low-cost cotter and split pin specifications.
- Construction Machinery:Heavy-load retention requires hardened steel grades with surface durability.
- Marine Equipment:Saltwater corrosion resistance specifies brass, bronze, or passivated stainless grades.
Machine Assembly dominates procurement volume. Aerospace Equipment commands the steepest expansion trajectory on fleet renewal cycles.
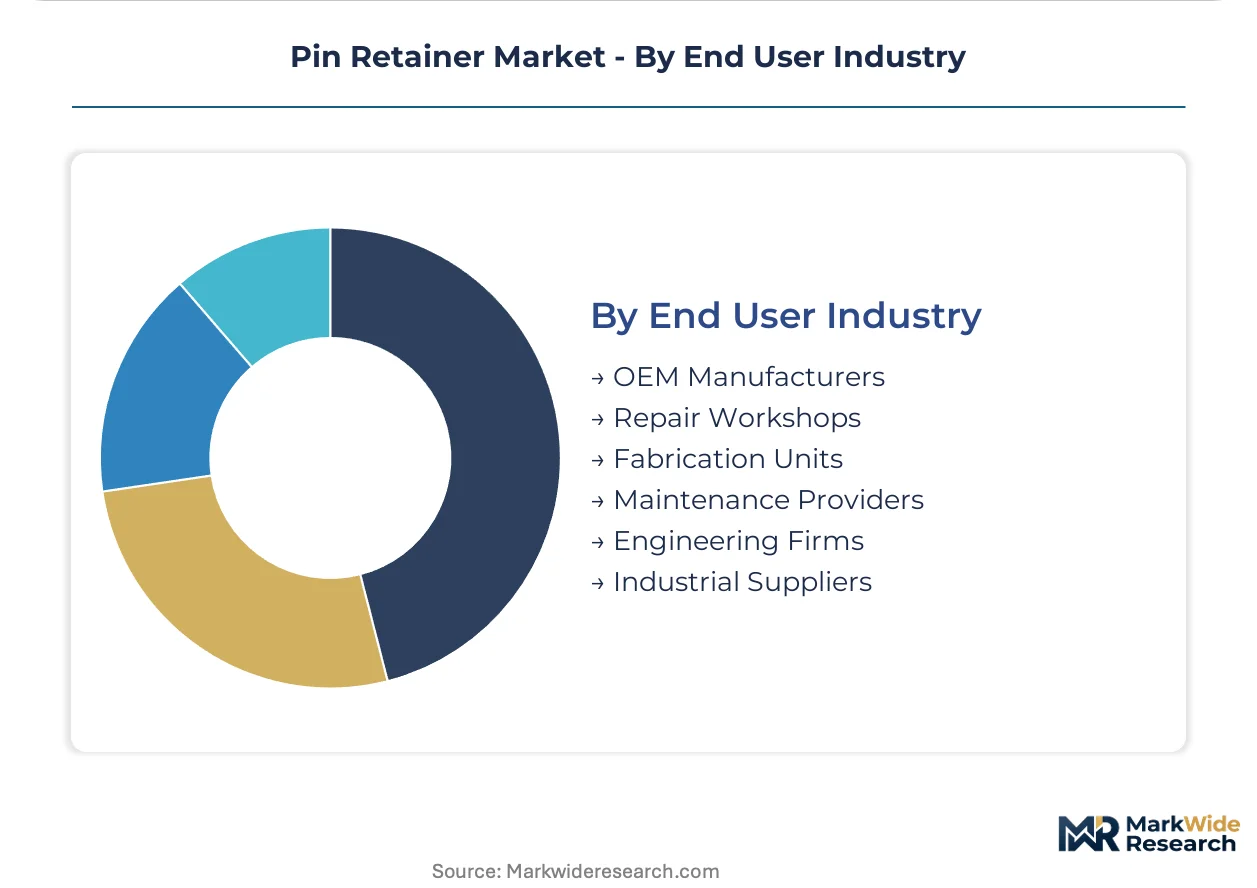
End User Industry:
Customer scale and technical capability determine specification authority and channel access.
- OEM Manufacturers:Direct engineering relationships enable custom geometry specification and lot-size optimization. Consolidated procurement platforms in Texas and Alberta bypass traditional distributor relationships for API-certified retaining hardware.
- Repair Workshops:Fragmented demand concentrates through regional fastener distributors with inventory breadth.
- Fabrication Units:Project-based procurement favors standard catalog geometries with rapid availability.
- Maintenance Providers:FAA-mandated replacement intervals generate recurring aftermarket demand for traceable aerospace-grade retainers.
- Engineering Firms:Specification authority in capital projects drives premium-grade selection.
- Industrial Suppliers:Inventory positioning and logistics capability determine competitive position.
OEM Manufacturers anchor specification authority. Maintenance Providers are gaining share fastest on fleet aging and regulatory replacement mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pin retainer trade flows reveal concentrated manufacturing capacity in industrialized economies alongside import-dependent demand in emerging industrial corridors. Export-oriented producers in Germany and the United States supply aerospace and automotive specifications to assembly operations across multiple continents. Regional regulatory divergence on material chemistry and surface treatment standards fragments procurement compliance requirements.
United States
Aerospace OEM procurement in Wichita and Seattle drives specification-grade titanium retainer demand for airframe assembly programs. FAA continuing airworthiness directives mandate traceable fastener replacement intervals for commercial aviation maintenance providers. Vacuum heat-treatment capacity concentrates in Ohio industrial corridors, creating geographic bottlenecks for hardness certification of 1070 and 1095 carbon grades.
Germany
Transmission builders in Stuttgart and Munich sustain circlip and snap ring demand for powertrain remanufacturing and new vehicle assembly. ECHA REACH enforcement against hexavalent chromium plating accelerates stainless steel substitution in industrial machinery across Baden-Württemberg. Seeger-Orbis GmbH leverages its European tooling footprint to serve tier-one automotive suppliers with just-in-time delivery synchronization.
China
Machine tool manufacturers in Yangtze River Delta industrial zones specify spring pins and roll pins for automated assembly lines serving domestic and export markets. GB standards for mechanical fasteners govern material composition and dimensional tolerance requirements in domestic procurement. Binder-jet additive manufacturing of 17-7PH stainless geometries is emerging in Shanghai and Shenzhen MRO provider networks.
India
Automotive component manufacturing under the PLI scheme attracts retainer suppliers to Pune and Chennai industrial corridors for transmission and engine assembly programs. BIS certification requirements for precision metal components create compliance entry barriers for imported specifications. Tier-one suppliers in Tamil Nadu are qualifying local heat-treatment partners to reduce dependence on European vacuum furnace capacity.
Japan
Precision equipment manufacturers in Nagoya and Osaka specify shape-memory nickel-titanium alloys for medical device and semiconductor handling applications. METI industrial standards govern surface treatment chemistry for food-processing machinery assemblies. JIS-certified spring steel grades from domestic mills anchor supply security for high-reliability retention mechanisms in robotics and factory automation systems.
Pin Retainer Market Competitive Landscape
On the supply side, the industry is structured around specialized fastening manufacturers with deep metallurgical capabilities and diversified industrial conglomerates with bearing and power transmission portfolios. Three strategic archetypes dominate: European precision tooling specialists with automotive transmission relationships, North American circlip and retaining ring producers serving aerospace specification channels, and integrated bearing manufacturers leveraging distribution scale. Competitive moves center on AS9100D quality system accreditation timelines and additive manufacturing integration for lot-size-one MRO customization.
Among German-based precision tooling specialists, Seeger-Orbis GmbH and Hugo Benzing occupy positions exemplifying the European automotive transmission supply archetype. Rotor Clip Company anchors North American supply representation for specialized circlip production. Waldes Truarc sits within the legacy brand recognition tier for aerospace specification channels. These named entities represent positioning patterns rather than operational specifics, with each archetype facing distinct certification and capacity constraints.
| Leading Market Players |
|---|
| Seeger-Orbis GmbH |
| Rotor Clip Company |
| Waldes Truarc |
| Hugo Benzing |
| Apex Fasteners |
| SKF Group |
| Timken Company |
| NTN Corporation |
| Schaeffler AG |
| Others |
Pricing and Supply Chain Analysis
Vacuum heat-treatment capacity concentration in Ohio and Baden-Württemberg feeds margin capture by certified suppliers serving aerospace specification channels, while uncertified producers compete on spot-market spring steel pricing for agricultural cotter pin demand.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures with volume-scaled discounts for AS9100D-certified titanium retainers. Price differentiation separates FAA-traceable aerospace grades from uncataloged economy pins for field maintenance. Cost compression in carbon steel tiers is intensifying because alloy surcharges on 1070 and 1095 grades fluctuate with scrap metal indices. Tier-one automotive transmission builders show lowest price sensitivity due to just-in-time synchronization penalties, while agricultural implement distributors negotiate aggressively on split-pin unit economics.
Supply Chain Analysis
Specialized heat-treatment houses in Germany, the United States, and Japan hold captive capacity for hardness certification above 38 HRC. Raw material supply draws from Swedish spring steel mills, Chinese titanium sponge processors, and domestic stainless producers in each manufacturing cluster. Single-source vulnerability concentrates in vacuum furnace availability for aerospace-grade lot qualification. Distribution runs through consolidated MRO procurement platforms in Texas and Alberta that displace traditional fastener distributors for oilfield services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Titanium alloy substitution in commercial aviation airframes constitutes a high-growth disruption as FAA continuing airworthiness directives expand addressable aftermarket demand for traceable fastener replacement.
For Market Incumbents: Entrench AS9100D certification moats by accelerating additive manufacturing integration for lot-size-one MRO customization in Wichita and Seattle aerospace clusters. Secure captive vacuum furnace partnerships in Ohio to defend margin position against heat-treatment capacity bottlenecks. Backward integration into 17-7PH stainless wire drawing reduces exposure to specialty alloy surcharge volatility. For New Entrants and Emerging Players: Build out binder-jet production capabilities for medical device-grade nickel-titanium geometries in Minnesota and Massachusetts catheter markets. Target India's PLI scheme corridors in Pune and Chennai for automotive transmission circlip supply with local BIS certification. Qualify indigenous heat-treatment partners in Tamil Nadu to bypass European furnace dependence. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across additive manufacturing-enabled MRO customization tiers. Long-term viability favors vertically integrated specialists controlling both metallurgical formulation and digital thread connectivity for aerospace specification channels. Watch FAA airworthiness directive issuance cadence as fleet aging inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Additive Manufacturing Integration | Binder-jet production of 17-7PH geometries enables lot-size-one customization for Wichita MRO providers. |
| Backward Integration | In-house vacuum heat-treatment capacity in Ohio eliminates certification bottlenecks for aerospace-grade output. |
| Regulatory Certification Investment | AS9100D quality system accreditation filters supplier participation in FAA-traceable replacement protocols. |
| Geographic Manufacturing Footprint | Pune and Chennai industrial corridors under India's PLI scheme attract transmission retainer production. |
| Material Substitution Program | Stainless steel grades displace hexavalent chromium-plated carbon steel under ECHA REACH enforcement. |
Research Methodology
A spread of perspectives from aerospace procurement directors, automotive transmission sourcing managers, vacuum heat-treatment operators, and MRO inventory platform executives converged on the working assumptions. Primary fieldwork combined with secondary validation from FAA continuing airworthiness directive databases, ECHA REACH restriction filings, and customs trade flow records. Bottom-up segment sizing across material grades and application severities was triangulated against top-down industrial production indices for fastening components.
Demand-supply balance modeling tracked procurement cycle compression against heat-treatment capacity utilization across the analysis window. Segmentation dimensions included product type, material specification, application severity, and end-user industry vertical. CAGRs were derived from elasticity-adjusted replacement demand curves and fleet aging profiles. Forecast inputs incorporated titanium alloy specification intensity in airframe programs and PLI scheme uptake rates in Indian automotive corridors.
Stress conditions across spring steel alloy surcharge volatility, vacuum furnace availability constraints, and adhesive bonding substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on regulatory enforcement timelines and OEM procurement synchronization patterns. Quarterly review of FAA airworthiness directive issuance and ECHA restriction amendment cadence is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Connectors
Wire-To-Board Connector Market
Connectors
Smart Crimper Market
Connectors
Connector Market
Connectors
Connector Adapter Kits Market
Connectors
Hybrid Fiber Optic Connectors Market
Connectors
Press Fit Connector Market
Connectors
Automotive Data Connectors Market
Connectors
LCP Connectors Market
Connectors
Relay Sockets Market
Connectors
Asia-Pacific Connector Market
Connectors
Terminal Pins Market
Connectors
Space Grade Connectors Market
Connectors
Small Bore Connectors Market
Connectors
Global Automotive Connector Market
Connectors
Underwater Connectors Market
Connectors
Telecom Mounting Hardware Market