
 Vertical Cavity Surface Emitting Laser (Vcsels) Market | 2026-2036
Vertical Cavity Surface Emitting Laser (Vcsels) Market Size, Share, and Industry Trends Forecast 2026-2036
Vertical Cavity Surface Emitting Laser (Vcsels) Market Analytics
East Asian foundry expansion is realigning VCSEL wafer supply chains toward 6-inch GaAs platforms. Coherent Corp. leverages vertical integration across epitaxy and packaging to sustain cost leadership in datacom transceivers. Lumentum Operations LLC anchors its position through dominant share of 3D sensing arrays for consumer handsets. ams OSRAM AG differentiates via specialized high-power VCSELs for automotive LiDAR modules.
A Vertical Cavity Surface Emitting Laser emits light perpendicular to the semiconductor surface through a monolithic resonator cavity formed by distributed Bragg reflectors, typically operating at 850 nm or 940 nm wavelengths with threshold currents below 1 mA for single-mode devices. Its primary purpose is enabling high-density optical interconnects and precision depth sensing where beam quality and array scalability matter. Multimode VCSELs occupy the largest revenue pool in data center interconnect, while high-power VCSELs represent the fastest-expanding category as automotive LiDAR moves from pilot to series production. Sensing applications in consumer electronics command premium pricing due to tighter wavelength uniformity requirements.
FCC equipment authorization rules govern VCSEL integration into consumer devices in the United States, while FDA laser product performance standards classify emission safety levels for medical imaging applications. The EU RoHS directive and REACH chemical restrictions constrain gallium arsenide sourcing and substrate recycling protocols. Stakeholders must monitor how IEC 60825 laser safety revisions and emerging automotive functional safety standards reshape qualification timelines for next-generation arrays.
Market Dynamics
Wafer-scale migration to 6-inch GaAs platforms is compressing unit economics while tightening wavelength uniformity tolerances for 3D sensing arrays, forcing foundries to recalibrate epitaxy-to-packaging workflows.
Growth Catalysts
- Hyperscale data center buildouts:Cloud operators in the United States are procuring multimode transceivers at volume scale, driving VCSEL array demand for short-reach optical interconnects.
- China's GB energy efficiency standards:Mandatory efficiency thresholds for data center infrastructure are accelerating replacement cycles for legacy 850 nm modules with higher-conversion-efficiency designs.
- Automotive LiDAR qualification:Tier-1 suppliers are validating high-power VCSEL arrays for series production, opening a path from pilot programs to embedded vehicle platforms.
Market Restraints
- Gallium arsenide supply concentration:Substrate production clusters in East Asian foundries, exposing buyers to single-source risk during geopolitical trade friction.
- EU REACH chemical restrictions:Hazardous substance protocols complicate GaAs wafer recycling and end-of-life disposal, adding compliance overhead to European deployments.
- Edge-emitting laser substitution:Distributed feedback lasers retain cost advantages in long-haul telecom applications, capping VCSEL penetration beyond 500-meter reaches.
Strategic Opportunities
- Industrial automation sensing:Factory robotics in Germany and Japan are adopting VCSEL-based time-of-flight modules for precise spatial mapping, creating non-consumer volume channels.
- India's PLI scheme for electronics:Production-linked incentives for semiconductor packaging are attracting VCSEL module assembly investments to serve domestic handset and automotive demand.
- Convergence with silicon photonics:Hybrid integration of VCSEL emitters with silicon waveguides is enabling co-packaged optics architectures for next-generation switch silicon.
Industry Challenges
- Epitaxy technician scarcity:MOCVD reactor operation and DBR layer optimization require specialized compound-semiconductor expertise that outpaces vocational training pipelines.
- IEC 60825-1 certification timelines:Laser safety classification revisions for high-power arrays are extending qualification periods, delaying automotive LiDAR program ramps.
- Legacy transceiver integration:Backward compatibility with installed multimode fiber infrastructure constrains wavelength and modulation format innovation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vertical Cavity Surface Emitting Laser (Vcsels) Market |
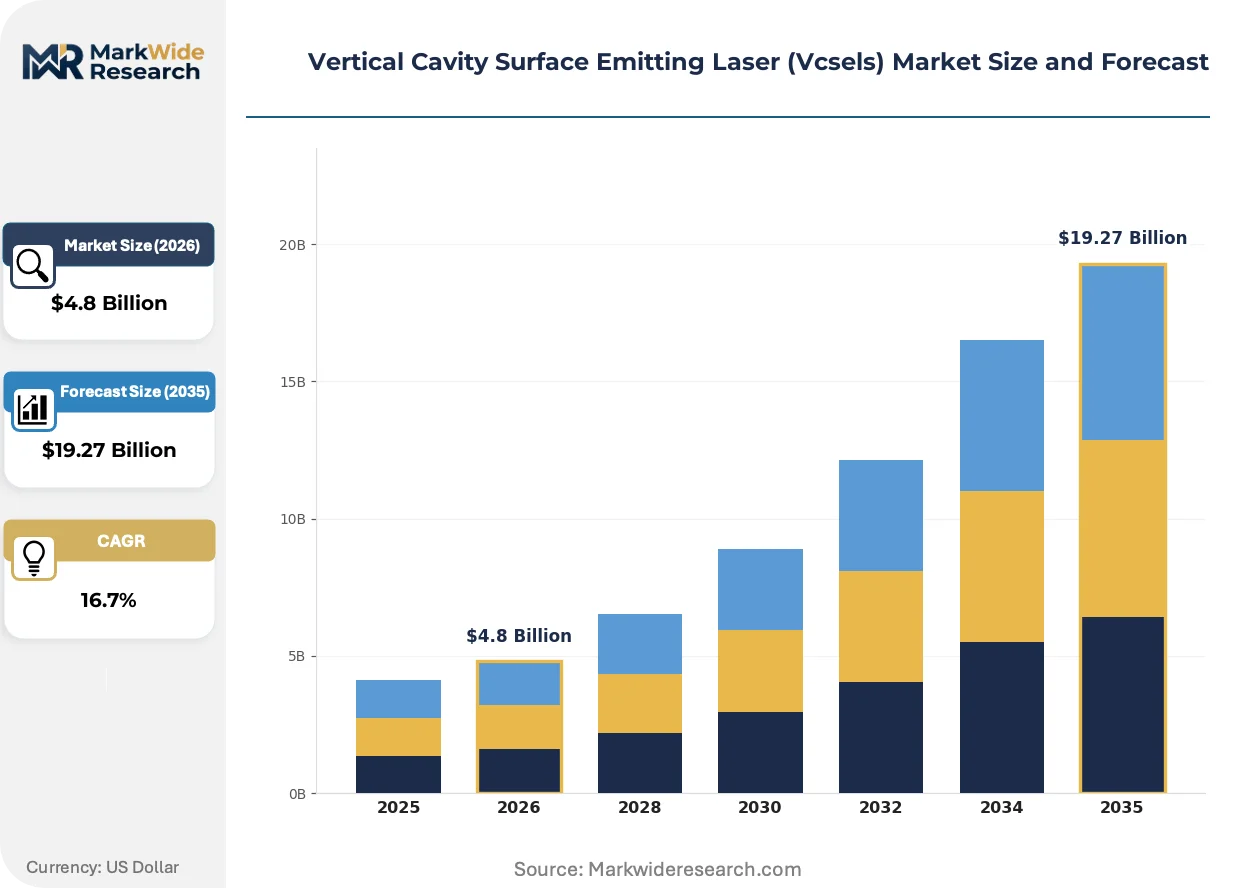
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $19.27 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
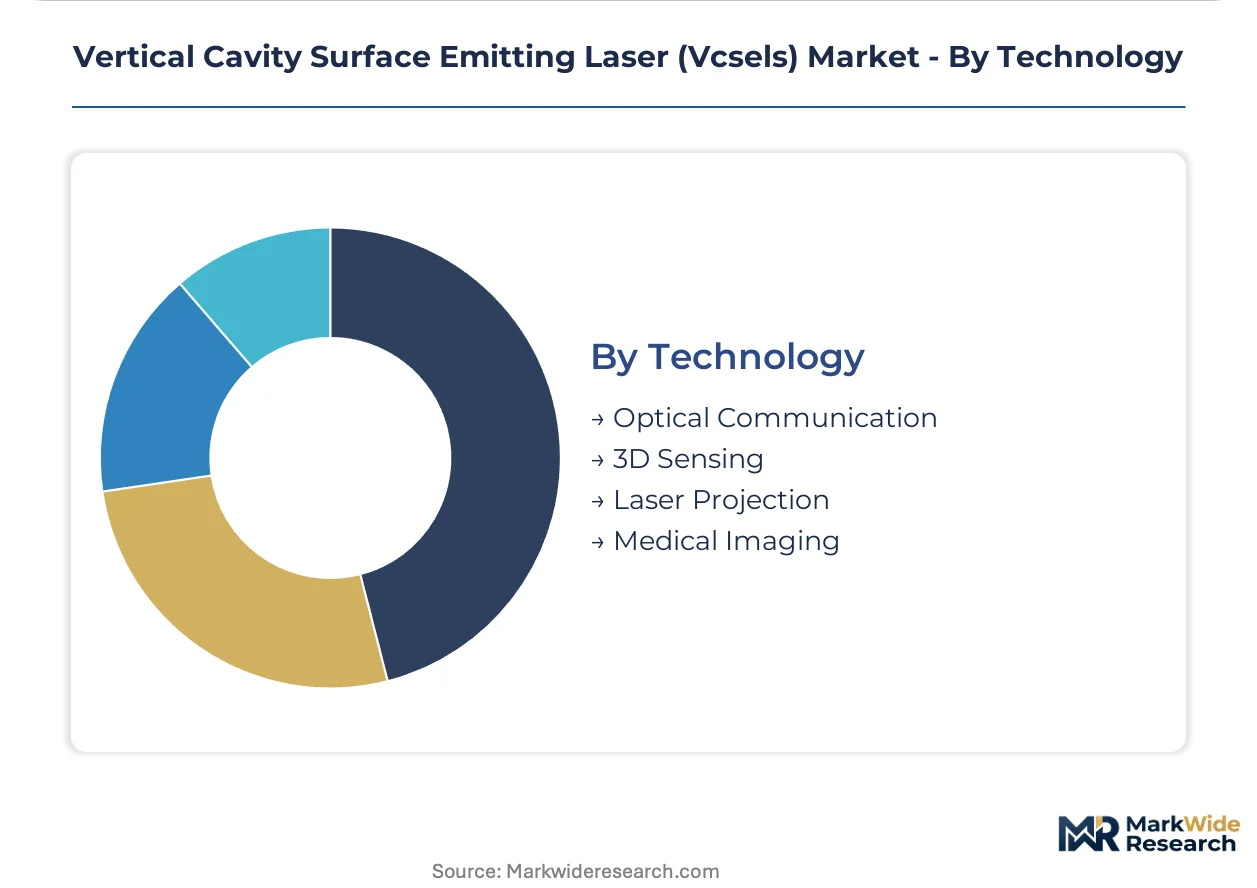
| Segmentation | Product Type: Single-Mode VCSELs, Multimode VCSELs, High-Power VCSELs, Tunable VCSELs Application: Data Center Interconnect, Consumer Electronics, Sensing Applications, Automotive LiDAR End User: Telecommunications, Healthcare, Automotive, Industrial Automation Technology: Optical Communication, 3D Sensing, Laser Projection, Medical Imaging |
| Companies Covered | Coherent Corp., Lumentum Operations LLC, ams OSRAM AG, TRUMPF, Broadcom, MKS Instruments, Hamamatsu Photonics KK, Santec Holdings Corporation, Leonardo Electronics US, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vertical Cavity Surface Emitting Laser (Vcsels) Market Evolving Landscape
Active alignment between wavelength stability requirements and automotive functional safety mandates is redefining how VCSEL arrays are specified, tested, and qualified across end-use verticals.
Photonic integration platforms are embedding VCSEL arrays directly onto silicon interposers alongside driver electronics and micro-optics. Datacom transceiver manufacturers are adopting these co-packaged architectures to reduce electrical parasitics and shrink module form factors. The technology is integrating previously discrete subsystems into unified optical engines, compressing assembly steps and improving thermal management uniformity.
China's dual carbon goals and associated GB standards on data center power usage effectiveness are mandating component-level efficiency disclosures. MIIT enforcement of these protocols is disqualifying legacy VCSEL designs from state-funded infrastructure projects. Domestic cloud operators are responding by tightening supplier qualification criteria around wall-plug efficiency and thermal stability under load.
Automotive OEMs are unbundling LiDAR module procurement from tiered system integrators, establishing direct relationships with VCSEL array suppliers to secure wavelength binning consistency. This disintermediation is visible most acutely in Germany, where KBA type-approval processes reward suppliers with documented traceability from epitaxy to final test. Tier-1 integrators are responding by deepening their own metrology capabilities to defend their position in the value chain.
Vertical Cavity Surface Emitting Laser (Vcsels) Market Segmentation
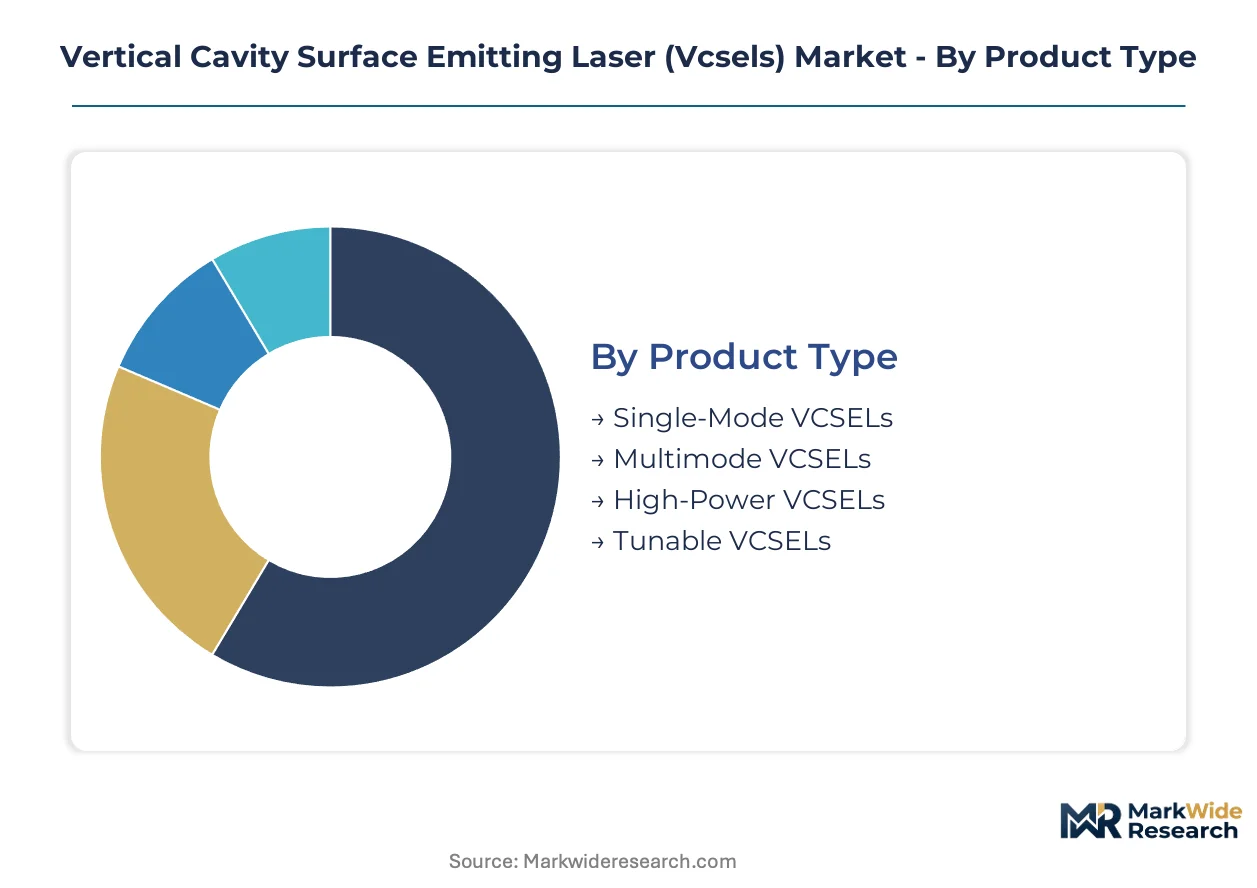
VCSEL procurement patterns diverge sharply across wavelength, power class, and integration complexity. Capital allocation decisions in epitaxy capacity and packaging automation hinge on which segments buyers prioritize.
Product Type:
Single-mode and multimode variants demand heavy upfront investment in MOCVD reactors and wafer-level testing infrastructure, while high-power arrays require additional thermal management tooling.
- Single-Mode VCSELs:These devices operate at threshold currents below 1 mA with narrow spectral linewidths below 0.5 nm, enabling precise wavelength control for coherent optical links. Demand concentrates in United States hyperscale data centers where 100G and 400G transceivers require tight dispersion budgets. China's GB energy efficiency standards are disqualifying legacy designs with poor wall-plug efficiency from state-funded procurement.
- Multimode VCSELs:Emitting multiple transverse modes across larger apertures, these arrays dominate short-reach optical interconnects up to 100 meters. Cloud operators in the United States are procuring these at volume scale for spine-leaf architectures, though single-mode competition is encroaching at longer reaches. Capital intensity concentrates in automated wafer probing and burn-in stations.
- High-Power VCSELs:Arrays delivering watt-class output powers for automotive LiDAR require specialized heat spreaders and reliability screening. Tier-1 suppliers in Germany are validating these for series production under KBA type-approval protocols.
- Tunable VCSELs:Incorporating micro-electromechanical mirrors or thermal tuning elements, these devices enable wavelength-agile routing in reconfigurable optical networks. Telecommunications infrastructure deployments in Japan drive niche demand.
Most installed capacity flows through multimode VCSELs. Expansion is steepest in high-power VCSELs.
Application:
Application mix determines whether suppliers prioritize wavelength uniformity, modulation bandwidth, or eye-safety certification in their process flows.
- Data Center Interconnect:Short-reach optical links between server racks and switches constitute the dominant revenue pool, with hyperscale operators specifying 850 nm or 940 nm arrays in QSFP-DD and OSFP form factors. United States cloud buildouts are accelerating procurement of 112G-per-lane capable devices.
- Consumer Electronics:3D sensing modules for facial authentication and augmented reality depend on VCSEL arrays with tight wavelength binning across millions of units. Premium pricing reflects the metrology burden of maintaining ±1 nm uniformity at wafer scale.
- Sensing Applications:Industrial time-of-flight systems for factory robotics in Germany and Japan require robust packaging against vibration and thermal cycling.
- Automotive LiDAR:Flash and scanning LiDAR architectures are driving qualification of high-power arrays for 200-meter ranging, with functional safety mandates under ISO 26262 extending development timelines.
Datacom interconnect claims the largest revenue share. Automotive LiDAR is climbing the fastest as pilot programs convert to series awards.
End User:
End-user concentration shapes whether suppliers pursue high-volume automation or specialized reliability certification tracks.
- Telecommunications:Carrier networks and internet exchange points deploy VCSEL-based transceivers for metro aggregation, with China's MIIT enforcing component-level efficiency disclosures under dual carbon goals.
- Healthcare:Medical imaging and phototherapy applications require FDA laser product performance standards compliance, with 808 nm and 940 nm devices dominating dermatological and surgical tooling.
- Automotive:OEMs in Germany are disintermediating tiered integrators to secure direct VCSEL supply relationships with documented epitaxy-to-test traceability.
- Industrial Automation:Factory robotics in Japan and Germany are adopting VCSEL-based time-of-flight modules for spatial mapping, creating non-consumer volume channels with less stringent uniformity requirements than consumer electronics.
Telecommunications absorbs the most wafer output. Industrial automation is gaining share fastest as manufacturing reshoring accelerates sensing deployments.
Technology:
Technology positioning determines integration depth, with some architectures demanding co-packaged optics and others permitting discrete component sourcing.
- Optical Communication:Datacom transceivers are adopting silicon photonics hybrid integration, embedding VCSEL emitters directly onto interposers with driver electronics to reduce electrical parasitics.
- 3D Sensing:Structured light and time-of-flight architectures for smartphones and tablets require diffractive optical elements paired with wavelength-stabilized arrays.
- Laser Projection:Pico-projectors and head-up displays utilize RGB VCSEL combinations or frequency-doubled infrared sources, with thermal management limiting brightness scaling.
- Medical Imaging:Optical coherence tomography and photoacoustic systems leverage swept-source and tunable VCSELs for depth-resolved tissue visualization, with FDA classification governing clinical deployment.
Optical communication commands the most capital deployment. 3D sensing is expanding most quickly as automotive cabin monitoring adds new volume beyond handsets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting VCSEL wafer production toward jurisdictions with lower compound-semiconductor compliance costs, even as end-demand concentrates in markets with stringent energy-efficiency mandates.
United States
Hyperscale cloud operators in Virginia and Oregon are procuring multimode transceivers at volume scale, driving 850 nm array demand for spine-leaf data center architectures. FCC equipment authorization rules govern VCSEL integration into consumer devices, with emission safety testing concentrated in Silicon Valley and Austin certification labs. The Pacific Northwest cluster hosts burn-in and wafer-probing facilities serving datacom module assemblers.
China
Domestic cloud operators are replacing legacy modules under MIIT-enforced GB energy efficiency standards that disqualify poor wall-plug efficiency designs from state-funded procurement. Dual carbon goals are tightening component-level disclosure requirements for data center infrastructure. Yangtze River Delta foundries are expanding 6-inch GaAs epitaxy capacity to capture displaced orders from higher-cost jurisdictions.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg are disintermediating tiered integrators to establish direct VCSEL supply relationships with documented epitaxy-to-test traceability. KBA type-approval processes reward suppliers with wavelength binning consistency, extending qualification timelines for high-power arrays. Stuttgart industrial robotics clusters are adopting time-of-flight modules for factory automation.
Japan
Telecommunications infrastructure deployments in Tokyo and Osaka are driving niche demand for tunable VCSELs in reconfigurable optical networks. METI efficiency guidelines are pressuring datacom transceiver suppliers to improve thermal stability under load. Chubu region packaging houses are investing in automated alignment equipment for silicon photonics hybrid integration.
India
Production-linked incentives for semiconductor packaging under the PLI scheme are attracting VCSEL module assembly investments to serve domestic handset and emerging automotive demand. Telangana and Karnataka are establishing compound-semiconductor clusters with simplified environmental clearances for GaAs processing. Chennai and Bengaluru electronics manufacturing zones are qualifying suppliers for 3D sensing array integration.
Vertical Cavity Surface Emitting Laser (Vcsels) Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue automotive LiDAR and industrial sensing specializations where qualification barriers limit immediate competition. The vendor base stratifies across three tiers: integrated epitaxy-to-module suppliers, pure-play array manufacturers, and packaging-focused assemblers. Two dominant competitive moves are reshaping positioning: backward integration into MOCVD reactor capacity and strategic partnerships with silicon photonics foundries for co-packaged optics.
Among United States-based suppliers, Coherent Corp. and Lumentum Operations LLC exemplify divergent archetypes—one leveraging captive epitaxy for datacom cost leadership, the other anchoring consumer electronics through 3D sensing array dominance. European presence concentrates in German and Austrian specialists, with ams OSRAM AG representing the automotive LiDAR high-power tier. These named entities serve as structural anchors for understanding how geographic specialization and integration depth map to segment exposure.
| Leading Market Players |
|---|
| Coherent Corp. |
| Lumentum Operations LLC |
| ams OSRAM AG |
| TRUMPF |
| Broadcom |
| MKS Instruments |
| Hamamatsu Photonics KK |
| Santec Holdings Corporation |
| Leonardo Electronics US, Inc. |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap GaAs foundries in Taiwan and South Korea anchor upstream wafer supply, translating concentrated ownership into disciplined capacity allocation and tight pricing discipline for epitaxy services. Their captive control over MOCVD reactor fleets limits spot-market availability, forcing datacom module assemblers into long-term offtake contracts with fixed-volume pricing clauses.
Pricing Analysis
Distributor margins on VCSEL arrays compress as direct OEM procurement expands, particularly among United States hyperscale cloud operators negotiating volume-tiered rebates for multimode transceiver modules. Three-tier pricing structure across premium, standard, and economy levels separates automotive LiDAR-grade arrays with ISO 26262 traceability from consumer electronics bins and legacy datacom surplus. Price differentiation hinges on wavelength uniformity certification and thermal stability under load. Cost compression in standard-tier 850 nm modules intensifies as China's MIIT enforcement of GB energy efficiency standards accelerates replacement demand. Consumer electronics buyers exhibit lowest price sensitivity due to tight ±1 nm uniformity requirements, while industrial automation purchasers prioritize unit economics over spectral precision.
Supply Chain Analysis
Regional distribution centers in Kaohsiung, Seoul, and Shanghai form a hub-and-spoke pattern for GaAs wafer logistics, with consolidated airfreight lanes feeding module assembly clusters in Penang and Shenzhen. Epitaxy capacity concentrates in Taiwan, South Korea, and China, drawing from gallium metal refiners in Kazakhstan and China plus high-purity arsine suppliers in Japan and the United States. Single-source vulnerability pervades 6-inch GaAs substrate supply, with two foundries controlling qualified automotive-grade output. Distribution runs through tiered electronics manufacturing service providers who consolidate array procurement for transceiver module assembly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
VCSEL demand functions as a stable compounder, with hyperscale data center interconnect buildouts providing recurring revenue visibility across technology refresh cycles regardless of macroeconomic volatility.
For Market Incumbents: To counter silicon photonics substitution at longer reaches, Coherent Corp. and Lumentum Operations LLC should deepen backward integration into 6-inch GaAs epitaxy capacity in Taiwan and South Korea while accelerating IEC 60825-1 certification pipelines for high-power automotive arrays. Captive MOCVD reactor fleets and documented wavelength binning traceability defend margin position against emerging pure-play array manufacturers. For New Entrants and Emerging Players: Industrial automation buyers in Germany and Japan represent an underserved buyer archetype with less stringent uniformity requirements than consumer electronics and shorter qualification timelines than automotive LiDAR. Entry through VCSEL-based time-of-flight modules for factory robotics avoids direct confrontation with entrenched 3D sensing incumbents. Partnership with Stuttgart or Nagoya-based system integrators provides channel access without tier-1 automotive certification burdens. For Investors and Strategic Acquirers: Valuations sit cheapest among packaging-focused assemblers lacking captive epitaxy, as margin compression in standard-tier datacom modules erodes standalone profitability. Long-term viability centers on hybrid integration capabilities for co-packaged optics architectures. The signal to watch is KBA type-approval award announcements for high-power arrays, which validate supplier process maturity and typically precede multi-year OEM supply agreements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into MOCVD Capacity | Captive epitaxy control insulates Coherent Corp. from GaAs wafer spot-price volatility and secures wavelength uniformity for datacom transceivers. |
| Automotive Functional Safety Certification | ISO 26262 qualification opens series production awards from BMW and Mercedes-Benz under KBA type-approval protocols. |
| Silicon Photonics Hybrid Integration | Co-packaged optics architectures reduce electrical parasitics for 112G-per-lane transceivers demanded by United States hyperscale operators. |
| Industrial Sensing Channel Partnership | Collaboration with KUKA or FANUC accelerates VCSEL time-of-flight adoption in German and Japanese factory automation deployments. |
| India PLI Scheme Module Assembly | Telangana and Karnataka packaging investments capture domestic handset and emerging automotive demand under simplified environmental clearances. |
Research Methodology
Bottom-up datacenter interconnect and automotive LiDAR modeling reconciled against top-down GaAs wafer supply tracking forms the analytical core of this study. Primary interviews with epitaxy technicians, datacom transceiver procurement managers, automotive Tier 1 supplier quality engineers, and industrial robotics system integrators combined with secondary validation from SEC 10-K filings, MIIT GB standard enforcement notices, KBA type-approval registries, and hyperscaler capex disclosures. Triangulation between demand-side volume assumptions and supply-side capacity announcements ensures internal consistency across the projection horizon.
Historical trendline analysis of MOCVD reactor utilization rates and wavelength yield curves informed growth trajectory assumptions across the analysis window. Segmentation modeling incorporated product type, application, end user, and technology dimensions alongside regional regulatory cluster variations. CAGRs derived from fitted growth curves adjusted for technology substitution risks and qualification timeline delays specific to automotive functional safety mandates.
Underlying measurement precision varies by segment; datacom interconnect and consumer electronics carry tighter precision than emerging industrial automation applications due to established procurement reporting channels. Forecasts reflect documented assumptions regarding hyperscaler buildout schedules, MIIT enforcement intensity, and KBA approval velocity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optoelectronics
Europe Optoelectronics Market
Optoelectronics
China Optical Detector Market
Optoelectronics
Quantum Dots Market
Optoelectronics
EPON ONU Market
Optoelectronics
Optical Emission Spectroscopy Market
Optoelectronics
IT & Telecom Optoelectronics Market
Optoelectronics
Global Indium Phosphide (Inp) Wafers Market
Optoelectronics
South Korea Optoelectronics Market
Optoelectronics
Global Optocoupler Market
Optoelectronics
Taiwan Optoelectronics Market
Optoelectronics
Quantum Dot Lasers Market
Optoelectronics
Gallium Arsenide Market
Optoelectronics
Global Infrared Optoelectronics Market
Optoelectronics
Laser Diode Market
Optoelectronics
Gaas Photodiode Market
Optoelectronics
China Optoelectronics Market