
 DIN Connectors Market | 2026-2036
DIN Connectors Market Size, Share, and Industry Trends Forecast 2026-2036
DIN Connectors Market Outlook
Distributor consolidation in European industrial automation is narrowing the path to market for mid-tier connector vendors. TE Connectivity leverages its captive cable assembly network to sustain direct OEM relationships in German machine building. Amphenol Corporation anchors its position through backward integration into precision metal stamping for high-density pin blocks. Hirose Electric competes on miniaturized variants for robotics controllers where space constraints dominate specification sheets.
DIN connectors are standardized multi-pin interconnects governed by Deutsches Institut für Normung dimensional specifications, typically manufactured with phosphor bronze contacts and glass-reinforced polyester housings to achieve IEC 60512 mechanical and electrical endurance ratings. Their primary purpose is to ensure signal integrity across backplanes, rack-mounted equipment, and industrial control cabinets subject to vibration and thermal cycling. Metal-housing plug and socket configurations command the strongest margin pools where electromagnetic shielding and IP67 sealing justify premium positioning. Plastic-bodied 3-pin and 7-pin variants occupy high-volume, price-sensitive tiers in commercial equipment and building automation. Panel mount receptacles with 15-pin density are gaining traction in aerospace test rigs where MIL-DTL interchangeability meets civilian cost structures.
REACH substance restrictions and RoHS Directive compliance enforced by ECHA shape material selection across European supply chains, while FDA electrical safety standards for medical device interconnects create parallel qualification burdens in the United States. German BIS-equivalent DIN standards institutes coordinate with ISO/IEC working groups to harmonize dimensional tolerances, reducing friction for exporters but raising tooling costs for new market entrants. Stakeholders must monitor the divergence between EU F-Gas Regulation thermal management requirements and NHTSA automotive EMC thresholds as these determine which connector families qualify for cross-sector platform designs.
Market Dynamics
Industrial automation OEMs in Germany and Japan are consolidating supplier relationships around sealed metal-housing variants certified for factory-floor Ethernet backbones, compressing qualification timelines and elevating IEC 61076-2-101 compliance to a non-negotiable procurement filter.
Growth Catalysts
- RoHS material restrictions:European supply chains are eliminating cadmium-plated contacts, forcing redesigns that favor phosphor bronze alternatives with superior cycle life in backplane architectures.
- Machine-tool builders in Stuttgart:High-pin-count DIN 41612 configurations are becoming standard for rack-mounted control cabinets subject to continuous vibration.
- Robotics controller miniaturization:Space-constrained motion control systems are specifying reduced-footprint variants that maintain signal integrity under thermal cycling.
Market Restraints
- Phosphor bronze input volatility:Copper-tin alloy pricing fluctuations directly compress margin pools on standard-density pin blocks.
- Precision metal stamping concentration:Tooling expertise for high-density contact arrays clusters in southern German industrial zones, creating single-source vulnerabilities.
- USB-C and industrial Ethernet substitution:Lower-cost interconnect standards are displacing plastic-bodied 3-pin variants in commercial equipment.
Strategic Opportunities
- Aerospace test rig certification:Panel mount 15-pin receptacles meeting MIL-DTL interchangeability standards are penetrating civilian cost structures.
- EU F-Gas Regulation thermal mandates:Sealed metal-housing variants with integrated thermal management are qualifying for cross-sector platform designs.
- Medical device interconnects:FDA electrical safety standards are creating parallel qualification pathways for biocompatible contact plating.
Industry Challenges
- Tooling engineer scarcity:Precision stamping die design expertise is concentrating among aging workforces in Bavaria and Baden-Württemberg.
- REACH substance documentation:ECHA compliance timelines are extending supplier qualification cycles by six to nine months for new material formulations.
- Legacy backplane integration:DIN 41612 retrofits into 1980s-era rack architectures require custom adapter blocks that fragment production runs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | DIN Connectors Market |
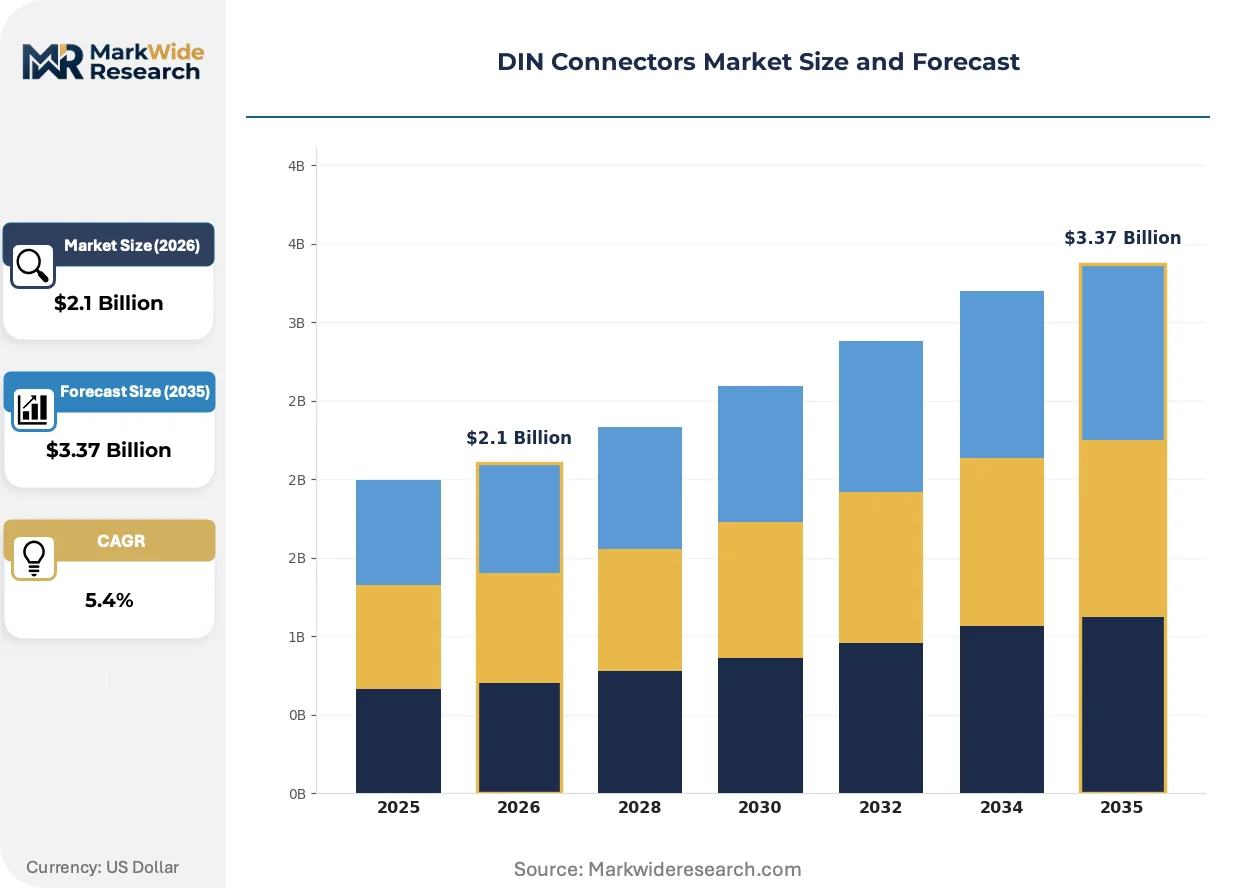
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.37 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Connector Type: Plug, Socket, Receptacle, Panel Mount Material: Plastic, Metal, Rubber, Composite Usage Environment: Industrial, Commercial, Automotive, Aerospace Pin Configuration: 3-Pin, 7-Pin, 10-Pin, 15-Pin |
| Companies Covered | TE Connectivity, Amphenol Corporation, Hirose Electric, Molex, Harting Technology Group, Phoenix Contact, Lumberg Holding, Switchcraft, Cinch Connectivity Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
DIN Connectors Market Strategic Shifts
Contact metallurgy and housing materials are undergoing forced evolution as regulatory thresholds tighten and end-use specifications diverge between industrial automation, medical, and aerospace verticals.
Gold-over-nickel plating on phosphor bronze contacts is migrating from standard commercial grades to high-reliability variants specified by German machine-tool builders. Stuttgart-area OEMs are mandating 30-microinch minimum gold thickness for backplane connectors in 24/7 production environments. This migration from thinner deposits is compressing price competition among mid-tier stamping houses unable to sustain precious metal inventory.
REACH substance restrictions enforced by ECHA are eliminating hexavalent chromium conversion coatings from metal housing surface treatments. Connector manufacturers serving European medical device OEMs are switching to trivalent chromium or zinc-nickel alternatives that meet RoHS Directive compliance without sacrificing salt-spray endurance. German BIS-equivalent standards institutes are coordinating these material transitions with ISO/IEC working groups to preserve dimensional interchangeability.
Specification authority is concentrating among procurement teams at Japanese automotive Tier-1 suppliers who now mandate JIS-standard test protocols for DIN-compatible interconnects. These buyers are unbundling cable assembly from connector supply, forcing vendors to certify standalone performance rather than captive harness integration. This pattern is most visible in Nagoya-area robotics controller manufacturing where space constraints dominate specification sheets.
DIN Connectors Market Segmentation
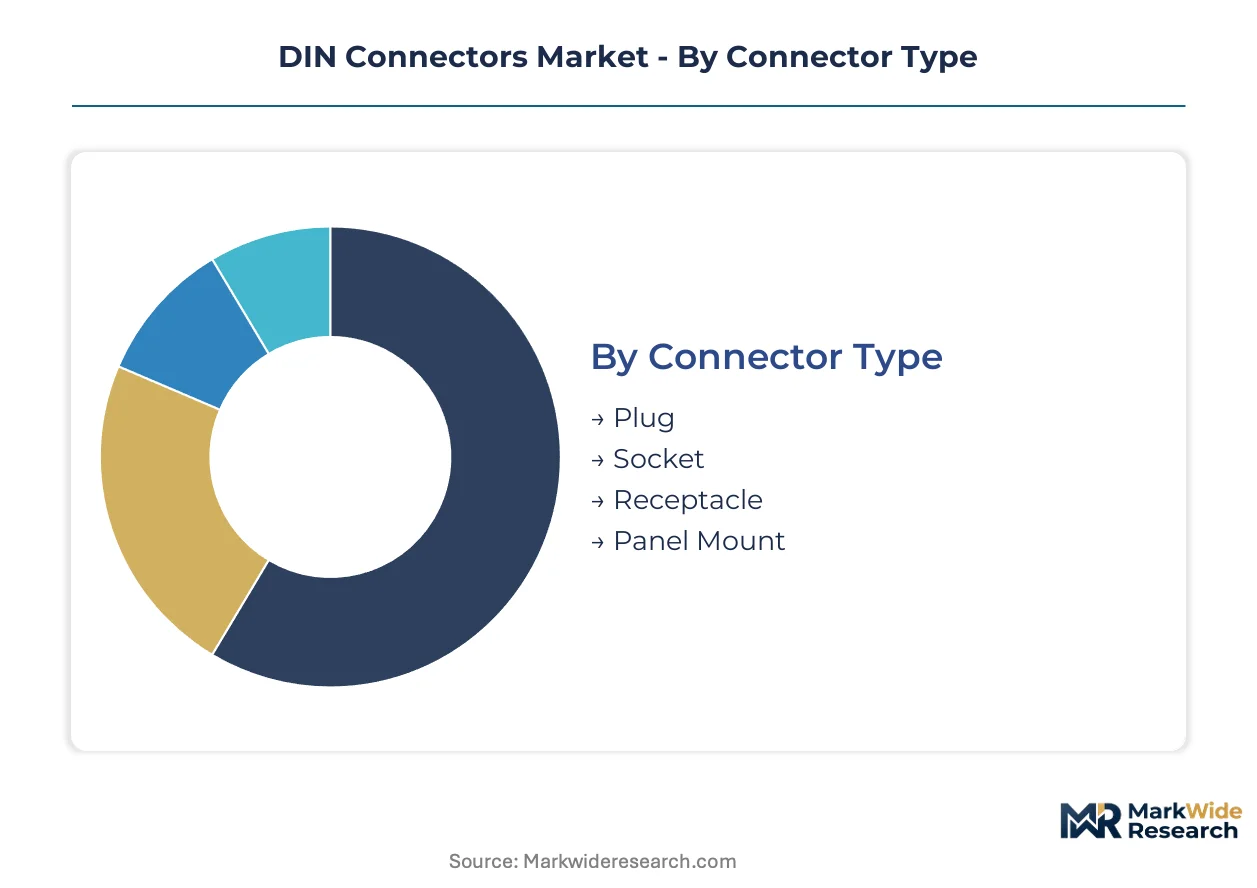
DIN connector procurement splits sharply between legacy backplane architectures and emerging miniaturized applications. Specification authority concentrates with German machine-tool builders and Japanese robotics OEMs who unbundle connector supply from cable assembly.
Connector Type:
Mature socket and plug configurations dominate installed base volumes while panel mount variants emerge as the specification frontier for aerospace test integration.
- Plug:Metal-housing plug configurations with IP67 sealing command premium positioning in factory-floor Ethernet backbones. Stuttgart-area machine-tool builders specify these for rack-mounted control cabinets subject to continuous vibration and thermal cycling.
- Socket:Backplane sockets in DIN 41612 high-density arrays anchor industrial automation procurement. German OEMs mandate 30-microinch gold-over-nickel plating for 24/7 production environments, compressing margins for stamping houses without precious metal inventory capacity.
- Receptacle:Standard-density receptacles serve building automation and commercial equipment with phosphor bronze contacts.
- Panel Mount:15-pin panel mount variants meeting MIL-DTL interchangeability standards penetrate civilian aerospace test rigs.
Socket configurations handle the majority of throughput; panel mount is expanding most quickly on specification share.
Material:
Cost tier differentiation separates shielded metal-housing premium offerings from price-sensitive plastic-bodied commercial tiers.
- Metal:Sealed metal housings with electromagnetic shielding qualify for IEC 61076-2-101 compliance in industrial automation. REACH substance restrictions are eliminating hexavalent chromium conversion coatings, forcing migration to trivalent chromium or zinc-nickel alternatives.
- Plastic:Glass-reinforced polyester housings occupy high-volume tiers in commercial equipment and building automation. USB-C substitution is displacing plastic-bodied 3-pin variants in consumer-facing applications.
- Rubber:Elastomeric seals integrate with metal housings for IP67-rated industrial deployments.
- Composite:Hybrid material formulations address weight constraints in aerospace and portable industrial equipment.
Metal captures the dominant revenue pool; composite formulations are climbing the fastest on technical specification share.
Usage Environment:
Application-driven qualification burdens split between industrial automation's IEC compliance and medical device's FDA electrical safety standards.
- Industrial:Factory-floor Ethernet backbones in Germany and Japan specify sealed metal-housing variants with RoHS-compliant phosphor bronze contacts. ECHA documentation timelines extend supplier qualification cycles by six to nine months for new material formulations.
- Commercial:Building automation and office equipment favor plastic-bodied 7-pin configurations with standard commercial plating thickness.
- Automotive:JIS-standard test protocols mandated by Nagoya-area Tier-1 suppliers unbundle connector certification from captive harness integration.
- Aerospace:Panel mount receptacles with MIL-DTL interchangeability meet civilian cost structures in test rig applications.
Industrial environments absorb the dominant procurement volume; aerospace specifications are gaining share fastest on certification breadth.
Pin Configuration:
Volume concentration favors low-pin-count commercial variants while high-density arrays command technical specification authority.
- 15-Pin:High-density 15-pin arrays in DIN 41612 configurations anchor backplane architectures for German machine-tool builders. Custom adapter blocks fragment production runs for retrofits into 1980s-era rack systems.
- 3-Pin:Standard 3-pin plastic-bodied variants serve building automation with price-sensitive procurement profiles.
- 7-Pin:Mid-density 7-pin configurations balance signal count with footprint constraints in commercial equipment.
- 10-Pin:Specialized 10-pin arrays address robotics controller miniaturization where space constraints dominate specification sheets.
15-pin configurations command the dominant specification authority; 10-pin variants are expanding most quickly on robotics controller integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA REACH substance restrictions and RoHS Directive compliance are reshaping procurement patterns across European industrial automation clusters, while Japanese automotive Tier-1 suppliers and US aerospace test rig operators drive qualification divergence in their respective markets.
Germany
Machine-tool builders in Stuttgart and Munich specify high-pin-count DIN 41612 configurations for backplane architectures in 24/7 production environments. ECHA documentation timelines extend supplier qualification cycles by six to nine months for new phosphor bronze contact formulations. The Baden-Württemberg industrial corridor concentrates precision metal stamping expertise for high-density contact arrays.
Japan
Nagoya-area robotics OEMs mandate JIS-standard test protocols for DIN-compatible interconnects in space-constrained motion control systems. METI coordinates with ISO/IEC working groups to harmonize dimensional tolerances for export qualification. Chubu regional suppliers face unbundling pressure as Tier-1 buyers separate connector certification from captive harness integration.
United States
FDA electrical safety standards for medical device interconnects create parallel qualification burdens distinct from industrial automation requirements. Panel mount 15-pin receptacles meeting MIL-DTL interchangeability standards penetrate civilian aerospace test rigs in California and Texas. The Midwest industrial belt sustains demand for sealed metal-housing variants in factory-floor Ethernet deployments.
China
MIIT GB standards and dual carbon goals are tightening material selection criteria for connector housings in domestic industrial equipment. Yangtze River Delta manufacturing clusters specify RoHS-compliant phosphor bronze alternatives to eliminate cadmium-plated contacts. Shenzhen-area electronics assemblers drive volume consumption of plastic-bodied 3-pin variants in commercial equipment.
India
BIS certification requirements and PLI scheme incentives are accelerating localization of DIN connector supply chains for industrial automation OEMs. Maharashtra and Gujarat industrial zones specify standard-density receptacles for building automation and commercial equipment deployment. CDSCO medical device regulations create emerging qualification pathways for biocompatible contact plating in diagnostic equipment.
DIN Connectors Market Competitive Environment
Vertically integrated multinationals and specialized regional fabricators split the market along certification depth and geographic proximity vectors. Tier-1 procurement teams in German machine building and Japanese automotive consolidate supplier relationships around IEC 61076-2-101 compliance and JIS-standard test protocols respectively. Two strategic archetypes dominate: captive cable assembly networks with direct OEM relationships, and precision stamping houses with backward integration into contact metallurgy. Competitive moves concentrate on M&A to secure regional stamping expertise and strategic partnerships to unbundle connector supply from harness integration.
Among US-based connectivity specialists, TE Connectivity and Molex exemplify the captive assembly archetype through their direct OEM relationship models in industrial automation. Amphenol Corporation anchors the precision metallurgy tier with its position in high-density pin block manufacturing. Hirose Electric occupies a specialist position in miniaturized variants for robotics controllers where space constraints dominate specification authority.
| Leading Market Players |
|---|
| TE Connectivity |
| Amphenol Corporation |
| Hirose Electric |
| Molex |
| Harting Technology Group |
| Phoenix Contact |
| Lumberg Holding |
| Switchcraft |
| Cinch Connectivity Solutions |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in southern German precision stamping facilities is compressing margin pools across standard-density pin blocks while elevating pricing power for metal-housing variants with IEC 61076-2-101 certification. Stuttgart-area OEMs absorb premium positioning for 30-microinch gold-over-nickel plating as tooling engineer scarcity constrains supply expansion.
Pricing Analysis
German industrial clusters command 15-20% price premiums over Asian-sourced equivalents for DIN 41612 backplane configurations. Three-tier pricing structure across premium metal-housing, standard plastic-bodied, and economy commercial tiers anchors procurement segmentation. Cost compression in plastic-bodied 3-pin variants is intensifying because USB-C substitution erodes volume scale. Building automation buyers exhibit highest price sensitivity; aerospace test rig operators demonstrate lowest sensitivity due to MIL-DTL interchangeability requirements.
Supply Chain Analysis
Phosphor bronze feedstock draws from German copper-tin alloy mills and Japanese specialty metal suppliers, with secondary sourcing from South Korean refiners. High-density contact arrays rest on precision stamping dies, glass-reinforced polyester housings, and elastomeric IP67 seals. Single-source vulnerability concentrates in Baden-Württemberg tooling expertise as aging workforces constrain capacity expansion. Distribution runs through direct OEM relationships anchored by captive cable assembly networks and specialized industrial distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are inflecting as JIS-standard test protocols unbundle connector certification from captive harness integration, creating interoperability-driven consolidation pressure across German and Japanese supply chains.
For Market Incumbents: Pre-empt USB-C and industrial Ethernet substitution by deepening backward integration into phosphor bronze contact metallurgy and securing ECHA pre-registration for trivalent chromium surface treatments. Lock in Stuttgart-area machine-tool builders through dedicated capacity allocation for 15-pin DIN 41612 configurations. For New Entrants and Emerging Players: Indian industrial automation clusters around Maharashtra and Gujarat offer underpenetrated white-space for standard-density receptacles as PLI scheme incentives accelerate localization. Target CDSCO medical device qualification pathways for biocompatible contact plating. Penetrate through BIS certification partnerships with established cable assemblers lacking connector stamping capability. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across sealed metal-housing variants as REACH compliance tooling costs rise. Five-to-ten year viability favors precision stamping houses with in-house die design capability and precious metal inventory management. Monitor ECHA substance restriction timelines as inflection indicators for material transition capex cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Contact Metallurgy | Phosphor bronze stamping capability secures margin control against alloy price volatility. |
| ECHA Pre-Registration for Trivalent Chromium | REACH-compliant surface treatments qualify suppliers for European medical device procurement. |
| JIS-Standard Test Protocol Certification | Unbundled connector performance validation opens Nagoya-area robotics controller supply. |
| MIL-DTL Interchangeability Qualification | Civilian aerospace test rig penetration commands premium positioning in California and Texas. |
| Precision Stamping Die Design Acquisition | Bavarian tooling expertise addresses single-source vulnerability in high-density arrays. |
Study Parameters
A standing panel of OEM procurement directors, precision stamping plant managers, ECHA compliance officers, and industrial distributor category managers provided ongoing calibration throughout the study. Primary fieldwork combined structured interviews with connector specification authorities at German machine-tool builders and Japanese automotive Tier-1 suppliers. Secondary validation drew from IEC standard revision drafts, ECHA substance restriction updates, BIS certification registries, and SEC filings of publicly traded connectivity specialists. Bottom-up demand modeling triangulated against top-down industrial automation capex projections.
Scenario-bracketing framed volume and value outputs across the projection horizon, with segmentation dimensions spanning connector type, material grade, pin configuration density, and usage environment qualification tier. Modeled CAGRs derived from installed base replacement cycles, retrofit penetration rates into legacy backplane architectures, and miniaturization adoption curves in robotics controllers. Industry-specific forecast inputs incorporated phosphor bronze alloy price indices and precision stamping capacity utilization rates from southern German industrial zones.
Practitioners should monitor ECHA substance restriction enforcement intensity and JIS-standard protocol adoption velocity for early signals requiring forecast revision. Cross-checking against IEC 61076-2-101 certification database trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Connectors
Heavy-Duty Connector Market
Connectors
Connector for PV System Market
Connectors
Space Grade Connectors Market
Connectors
Power Connector Market
Connectors
High-Reliability Connectors Market
Connectors
Underwater Connectors Market
Connectors
Australia Connector Market
Connectors
Connector Adapter Kits Market
Connectors
Filtered Connectors Market
Connectors
Connector Kits Market
Connectors
Canada Connector Market
Connectors
Relay Sockets Market
Connectors
Micro-Miniature Co-Axial Adapter Market
Connectors
Connector Market
Connectors
PCI-E Connectors Market
Connectors
Japan Connector Market