
 Sand Control System Market | 2026-2036
Sand Control System Market Size, Share, and Industry Trends Forecast 2026-2036
Sand Control System Market Intelligence
Heightened well integrity standards, influenced by frameworks from regulators like the US BSEE, is consolidating the supplier base around companies with extensive engineering capabilities. Schlumberger leverages its integrated project management and digital modeling to optimize complex completions. Halliburton specializes in sand control solutions for challenging high-pressure, high-temperature environments. Baker Hughes differentiates through its portfolio of advanced expandable sand screens and chemical consolidation treatments.
A sand control system comprises methods and equipment to prevent formation sand from entering a wellbore during hydrocarbon production. These systems use components like screens with precise micron ratings to protect equipment and maintain well productivity. While gravel pack systems are a mature technology for many onshore wells, expandable sand screens see greater adoption in demanding deepwater drilling applications. Oilfield operators are the primary end users, selecting systems based on well complexity and expected lifecycle.
Regulatory bodies such as the US Bureau of Safety and Environmental Enforcement (BSEE), Brazil's ANP, and Norway's Petroleum Safety Authority (PSA) set stringent requirements for offshore operations. These rules govern equipment qualification and installation procedures, directly impacting system design and material choices. Future competitiveness will depend on a vendor's ability to deliver solutions that balance initial capital expenditure with long-term production uptime.
Market Dynamics
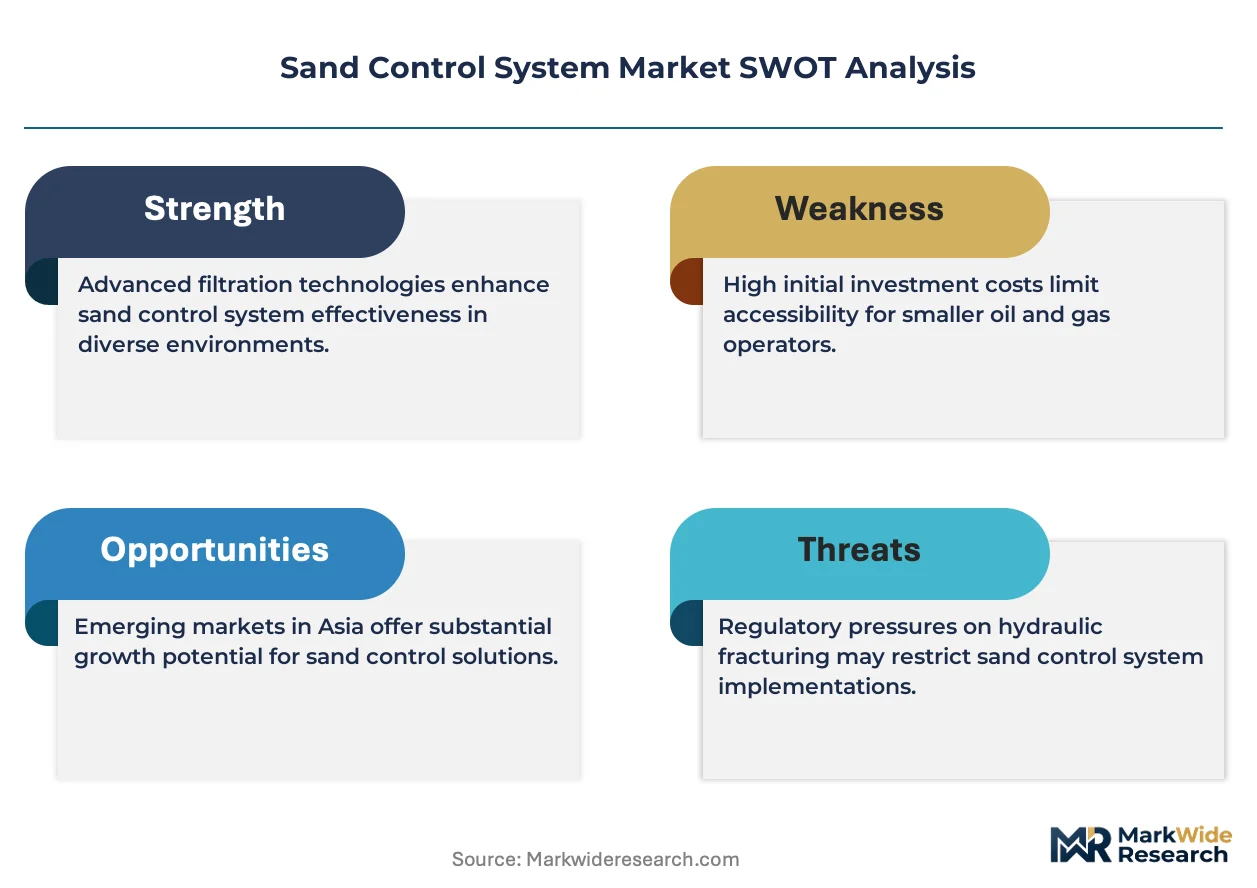
The central structural force shaping the Sand Control System Market is the non-negotiable demand for well integrity, driven by stringent regulatory frameworks from bodies like the US BSEE and Brazil's ANP, which elevates the barrier to entry for suppliers.
Growth Catalysts
- Deepwater Exploration:Renewed investment in complex deepwater and ultra-deepwater projects, particularly in Brazil's pre-salt basins and the Gulf of Mexico, necessitates advanced sand control technologies to manage unconsolidated formations.
- Expandable Sand Screens:The technical advantages of expandable screens over traditional gravel packs in terms of higher production efficiency and smaller operational footprint are driving their adoption in high-value offshore wells.
- Well Integrity Mandates:Stricter regulations from authorities like Norway's Petroleum Safety Authority (PSA) governing well lifecycle and abandonment are compelling operators to install more durable and reliable sand control systems from the outset.
Market Restraints
- High Capital Expenditure:The significant upfront cost of sophisticated systems, such as intelligent completions with integrated sand control, can be prohibitive for smaller operators or in marginal onshore fields, limiting adoption.
- Technical Limitations in HPHT:Performance and material degradation of some sand control components, including elastomers and screens, remain a challenge in extreme high-pressure, high-temperature (HPHT) environments, restricting operational envelopes.
- Supplier Concentration:The market for complex, engineered solutions is dominated by a few large service companies, creating potential supply chain bottlenecks and limited pricing leverage for oilfield operators on major projects.
Strategic Opportunities
- Digital Integration:There is a significant opportunity to integrate real-time fiber-optic sensing and predictive analytics with sand control systems, enabling proactive monitoring of sand production and optimizing well performance.
- Geothermal and CCUS Applications:Adapting sand control technologies for emerging sectors like geothermal energy production and carbon capture, utilization, and storage (CCUS) wells opens new, non-cyclical revenue streams for vendors.
- Chemical Consolidation Systems:Developing next-generation resin-based chemical consolidation treatments that offer longer-term stability and are less sensitive to formation mineralogy presents a growth avenue for brownfield applications.
Industry Challenges
- Specialized Talent Scarcity:A persistent shortage of completion engineers and field technicians with the specific expertise to design, model, and install complex sand control solutions for deepwater environments constrains project execution. *Logistical Complexity: Delivering large, delicate, and high-value sand screen assemblies and related equipment to remote offshore locations on time requires a sophisticated and resilient supply chain, which is vulnerable to disruption.
- System Integration:Ensuring seamless mechanical and hydraulic integration of new sand control hardware with existing downhole tools and legacy wellhead equipment during workover operations is a significant technical hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sand Control System Market |
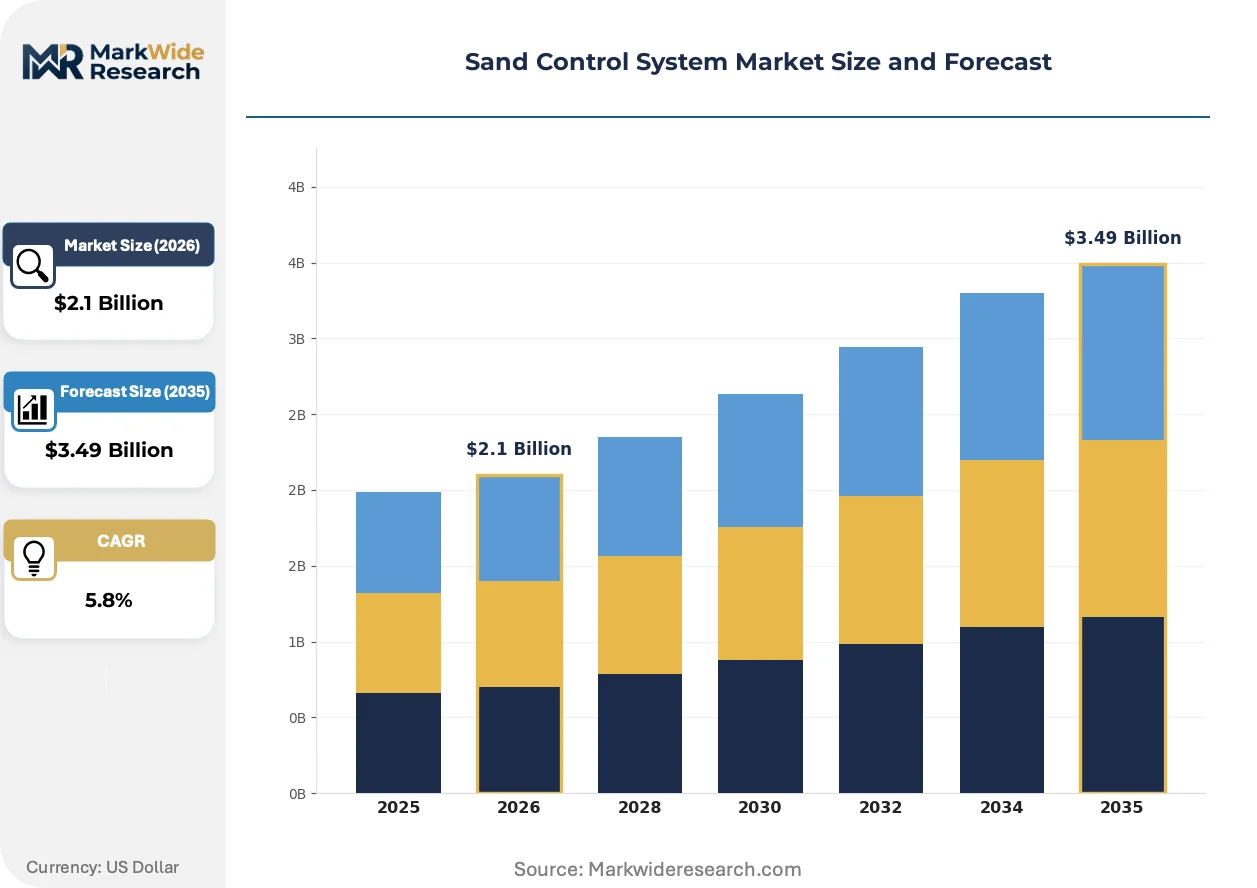
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.49 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Gravel Pack, Standalone Screens, Expandable Sand Screens, Chemical Consolidation Application: Onshore Wells, Subsea Wells, Deepwater Drilling, Enhanced Oil Recovery Installation Method: Coiled Tubing, Workover Rig, Drill Pipe Conveyed, Hydraulic Setting End User: Oilfield Operators, Service Companies, Engineering Firms, Drilling Contractors |
| Companies Covered | Weatherford International, Superior Energy Services, Schlumberger, Expro Group, Welltec, Halliburton, National Oilwell Varco, Tendeka, Baker Hughes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sand Control System Market Strategic Shifts & Innovations
The market is evolving toward integrated, data-driven completion solutions. Technology and service models are shifting to maximize long-term production uptime and de-risk operations in increasingly complex geological and regulatory settings, moving beyond simple component supply.
Digital twin technology for wellbore simulation provides a virtual environment to model sand production dynamics and system performance before installation. Major oilfield operators are adopting this for complex offshore projects to mitigate risks associated with unconsolidated reservoirs. This technology is automating the process of optimizing screen selection and gravel pack design, reducing reliance on generalized field data.
Regulations from Brazil's ANP, which mandate specific technical qualifications and local content for equipment in pre-salt fields, are directly influencing supplier strategy. This industrial policy forces international service companies to invest in local manufacturing, assembly, and engineering support within Brazil. The deepwater completion equipment segment is most affected, prompting a localization of supply chains to serve the region's long-term development plans.
A notable shift is occurring from the transactional purchase of hardware to long-term service agreements that bundle system design, installation, and lifecycle monitoring. This model displaces the traditional approach where operators procure individual components like screens or packers from various vendors. The trend is most visible in high-cost deepwater projects, where operators transfer well-integrity and production-inflow performance risk to specialized service providers.
Sand Control System Market Segmentation
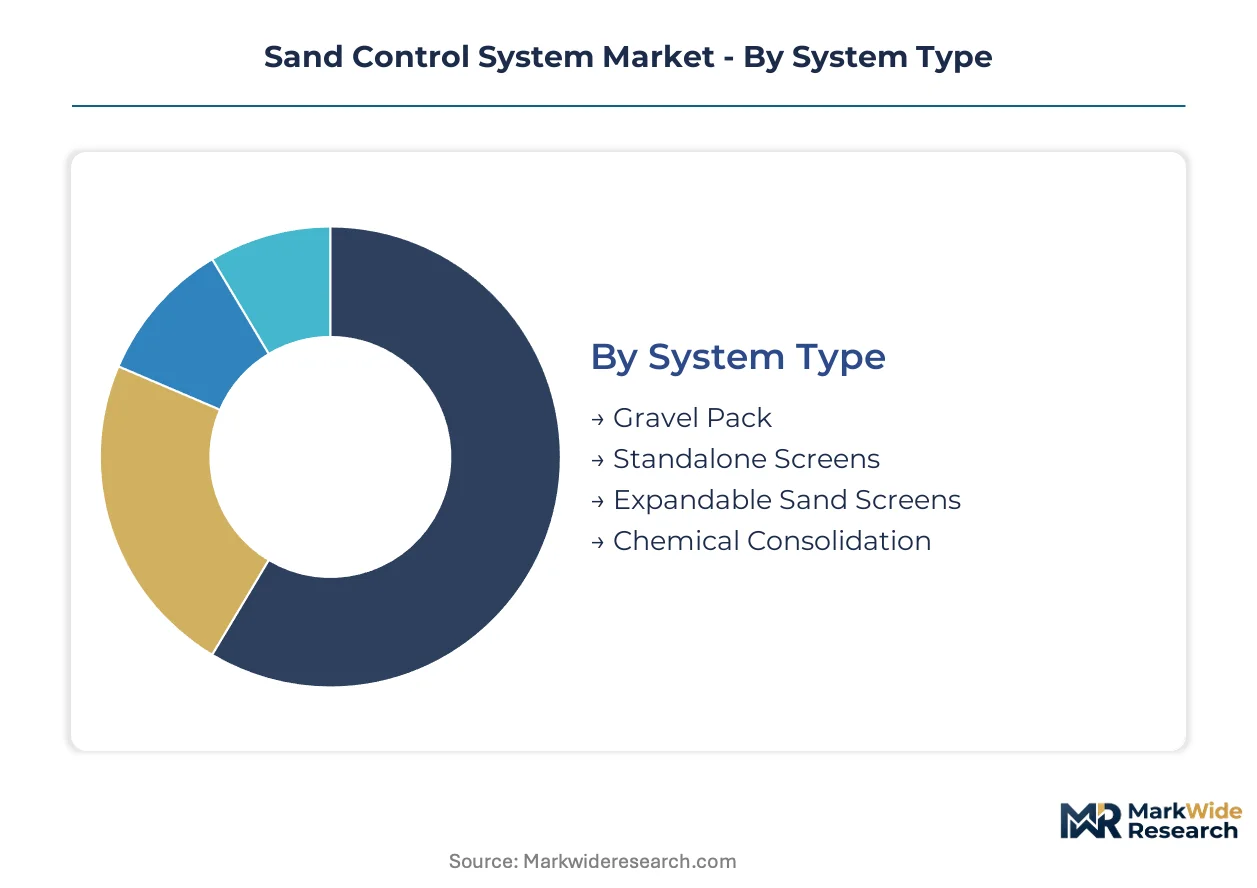
The Sand Control System Market segmentation reflects the diverse technical requirements and operational contexts within hydrocarbon production. Understanding these segments allows stakeholders to identify where specific technologies deliver the most value, aligning system capabilities with reservoir challenges and regulatory compliance. This granular view informs strategic investments in product development and market penetration.
System Type:
Operators prioritize system types based on reservoir characteristics, wellbore geometry, and desired production longevity. This decision framework balances initial capital expenditure with long-term operational efficiency.
- Gravel Pack:This mature technology involves pumping gravel into the annulus between the screen and the wellbore to filter sand. Gravel packs remain a standard solution for many conventional onshore wells due to their proven reliability and cost-effectiveness.
- Standalone Screens:These systems utilize pre-packed or wire-wrapped screens installed directly in the wellbore without an external gravel pack. Standalone screens offer a simpler completion design, often used in formations with moderate sand production or where gravel packing is impractical.
- Expandable Sand Screens:These advanced screens are run into the well and then expanded against the formation, providing a large flow area and mechanical sand retention. Expandable sand screens see greater adoption in demanding deepwater drilling applications, offering enhanced production efficiency and a smaller operational footprint.
- Chemical Consolidation:This method injects resins or chemicals into the formation to bind sand grains together, preventing their migration into the wellbore. Chemical consolidation treatments are utilized in challenging high-pressure, high-temperature environments or for brownfield applications where mechanical solutions are difficult.
Volume sits with Gravel Pack systems; growth tilts toward Expandable Sand Screens.
Application:
The operational environment heavily influences the choice of sand control solutions, dictating the complexity, durability, and cost of the required systems.
- Onshore Wells:These applications typically utilize conventional sand control methods like gravel packs due to simpler logistics and lower operational pressures. Onshore wells represent a significant volume segment for mature sand control technologies.
- Subsea Wells:These wells are completed on the seabed, requiring highly reliable and durable sand control systems with minimal intervention requirements. Subsea wells often integrate advanced screen technologies and remote monitoring capabilities.
- Deepwater Drilling:Complex deepwater and ultra-deepwater projects, such as those in Brazil's pre-salt basins, necessitate advanced sand control technologies to manage unconsolidated formations under high pressure. This segment demands robust, high-performance solutions.
- Enhanced Oil Recovery:EOR projects, particularly those involving steam injection or chemical floods, require sand control systems capable of withstanding corrosive fluids and elevated temperatures. These applications demand specialized materials and designs.
Deepwater Drilling applications drive significant investment, spurred by new exploration mandates and reservoir complexity.
Installation Method:
Efficiency and technical feasibility dictate the preferred installation method for sand control systems, impacting project timelines and overall completion costs.
- Coiled Tubing:This method uses a continuous pipe to deploy sand control components, offering flexibility and reduced rig time for certain well interventions. Coiled tubing is often employed in horizontal wells or for re-completions.
- Workover Rig:Traditional workover rigs are used for larger-scale installations and repairs, capable of handling heavy equipment and complex downhole operations. This method provides robust lifting capacity for deep and challenging wells.
- Drill Pipe Conveyed:Sand control systems are run into the well using drill pipe, offering precise placement and robust mechanical integrity during installation. Drill pipe conveyed methods are common in deep and highly deviated wells.
- Hydraulic Setting:This technique uses hydraulic pressure to activate and set downhole tools and screens, eliminating the need for mechanical manipulation from the surface. Hydraulic setting enhances operational safety and efficiency in remote locations.
Demand for Workover Rig installation is stable, while Drill Pipe Conveyed methods are gaining traction due to operational flexibility.
End User:
The end-user landscape reflects varying levels of technical expertise, purchasing power, and direct involvement in well operations, influencing sales and service models.
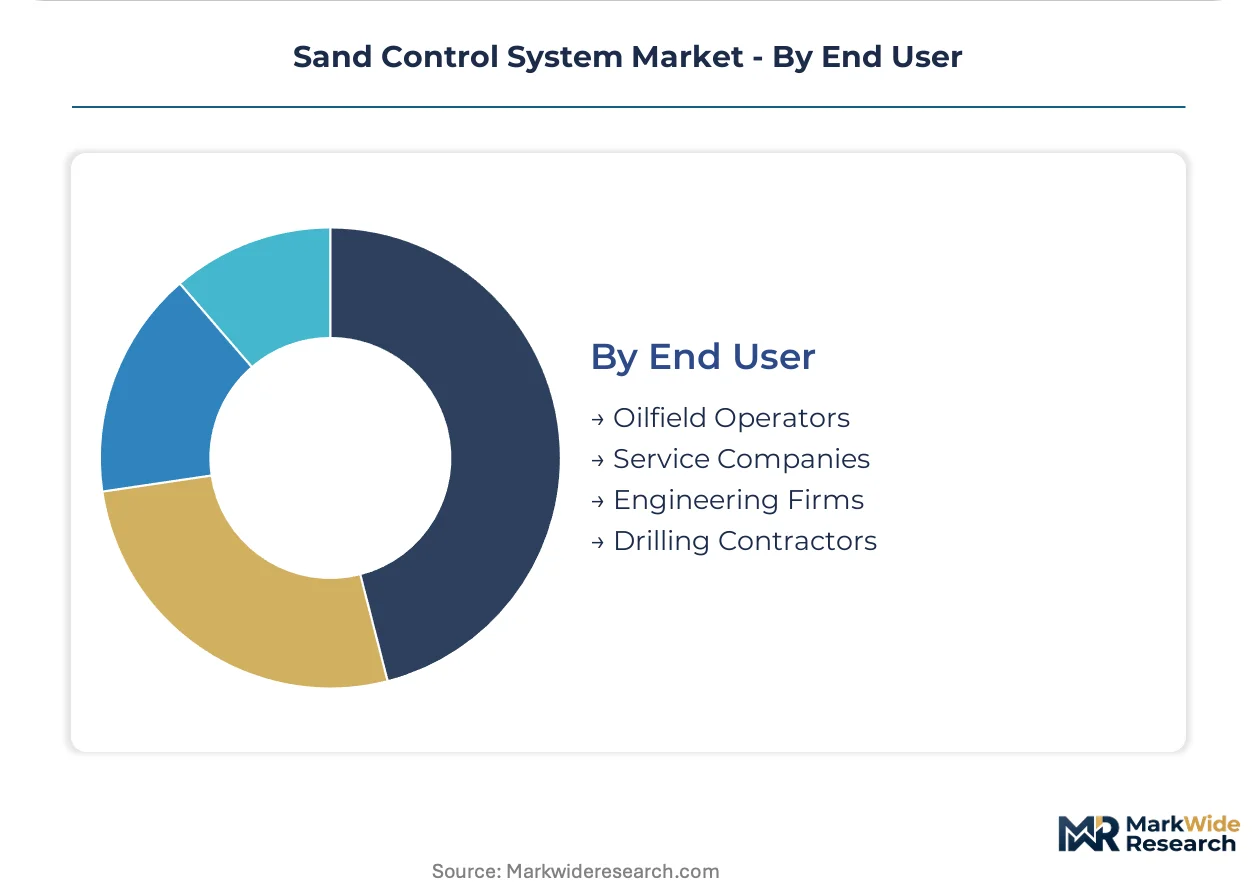
- Oilfield Operators:These entities own and manage hydrocarbon reservoirs, making them the primary decision-makers and purchasers of sand control systems. Oilfield operators select systems based on well complexity and expected lifecycle.
- Service Companies:Large service companies provide integrated sand control solutions, including design, installation, and often long-term monitoring. These companies consolidate the supplier base for complex, engineered solutions.
- Engineering Firms:These firms provide specialized design and consulting services for well completions, including sand control system selection and optimization. Engineering firms influence technology adoption through their recommendations.
- Drilling Contractors:Drilling contractors execute the physical drilling and completion phases, often working in conjunction with operators and service companies. They are involved in the logistical and operational aspects of system deployment.
Oilfield Operators represent the largest purchasing power, with Service Companies providing the most integrated solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's pre-salt basins, a strategic national resource zone, drives significant investment in advanced sand control systems, setting a precedent for similar deepwater exploration globally. This concentration of activity, coupled with stringent regulatory oversight, establishes key regional demand patterns. Each region's unique geological and regulatory landscape shapes the specific technological requirements for sand control.
Brazil
Renewed investment in Brazil's pre-salt basins drives demand for advanced sand control technologies to manage unconsolidated formations. Brazil's ANP regulations mandate specific technical qualifications and local content for deepwater completion equipment. The Rio de Janeiro and Macaé regions are seeing increased localization of supply chains for offshore development plans.
United States
Complex deepwater projects in the Gulf of Mexico necessitate robust sand control solutions for high-pressure environments. The US BSEE enforces strict well integrity standards, compelling operators to adopt reliable technologies from the outset. Houston serves as a central hub for engineering firms and service companies developing advanced sand control systems.
Norway
North Sea operations, characterized by mature fields and enhanced oil recovery (EOR) initiatives, require specialized sand control for long-term production uptime. Norway's Petroleum Safety Authority (PSA) sets stringent requirements for equipment qualification and installation procedures. The Stavanger region hosts a concentration of offshore technology providers focused on high-uptime solutions.
Saudi Arabia
Maintaining high production volumes in Saudi Arabia's vast oilfields requires effective sand management for both conventional and challenging reservoirs. The Ministry of Energy's directives emphasize long-term well integrity and production efficiency across national assets. Dhahran and the Eastern Province are centers for research and deployment of sand control technologies in mature fields.
Sand Control System Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists, creating a market structure that balances broad service offerings with niche technical expertise. Integrated service providers and specialized technology developers represent the primary strategic archetypes. Competitive moves often involve portfolio diversification to address various well complexities and strategic partnerships for digital integration.
Among integrated service providers, Schlumberger exemplifies the digital integration trend with its project management and modeling capabilities. Halliburton represents specialization in challenging environments, particularly high-pressure, high-temperature applications. Baker Hughes occupies a position focused on advanced mechanical solutions, such as expandable sand screens, and chemical consolidation treatments.
| Leading Market Players |
|---|
| Weatherford International |
| Superior Energy Services |
| Schlumberger |
| Expro Group |
| Welltec |
| Halliburton |
| National Oilwell Varco |
| Tendeka |
| Baker Hughes |
| Others |
Cost & Logistics Intelligence
Strict well integrity mandates, such as those from the US BSEE, gate access for qualified suppliers and drive premium-tier pricing for advanced sand control systems. This ensures compliance and long-term operational reliability.
Pricing Analysis
Short lead times for bespoke sand control solutions command a premium, while standardized components may see discounts for inventory. Project-based pricing dominates for complex deepwater installations, with differentiation driven by extensive engineering capabilities and material specifications for high-pressure, high-temperature environments. Pricing softness stems from operator pressure to optimize initial capital expenditure, particularly for less complex onshore applications. Deepwater operators exhibit lower price sensitivity due to stringent regulatory compliance and the critical need for long-term well integrity.
Supply Chain Analysis
Single-source vulnerability sits with specialized manufacturers of expandable sand screens and high-grade alloys. Geographic supply concentrates in regions like the United States and Europe for advanced components, while Brazil emphasizes local content for deepwater projects. The industry relies on specialized high-grade alloys and performance elastomers, creating dependencies. Logistical complexity for delivering large, delicate assemblies to remote offshore locations presents a structural risk, with distribution primarily occurring through major integrated service companies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sand control system market is supply-constrained, with a persistent shortage of specialized completion engineers creating a bottleneck that props up pricing for advanced solutions. This scarcity limits project execution for complex well designs.
For Market Incumbents: Cement integrated project management capabilities by investing in advanced digital twin technology for wellbore simulation and predictive analytics. Expand research and development into next-generation high-pressure, high-temperature materials to counter performance degradation, ensuring compliance with Norway's PSA standards. This strategy defends against emerging specialized technology firms and reinforces the value proposition of comprehensive solutions. Certification investment for new material qualifications is a key lever for market incumbents.
For New Entrants and Emerging Players: Capture white-space opportunities by adapting existing sand control technologies for emerging sectors like geothermal energy production and carbon capture, utilization, and storage (CCUS). Focus on next-generation chemical consolidation systems for brownfield applications, where mechanical solutions are difficult to deploy. The most penetrable segment lies in these non-cyclical energy transition applications. A go-to-market angle involves strategic partnerships with specialized engineering firms to co-develop and deploy tailored solutions.
For Investors and Strategic Acquirers: Increased M&A activity in digital completion technologies is the leading indicator that the market is consolidating around integrated offerings. The sand control market demonstrates strong long-term viability, driven by persistent deepwater exploration and non-negotiable well integrity standards. Acquisition targets should be niche technology providers with proven digital integration platforms or advanced material science for extreme environments. Regulatory updates from Brazil's ANP regarding local content requirements will signal shifts in regional investment strategy.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Integration Platform Launch | Enhances predictive analytics for sand production, optimizing well performance and reducing operator risk. |
| Advanced Material R&D Program | Extends operational envelopes for sand control components in extreme high-pressure, high-temperature environments. |
| Local Manufacturing Investment (Brazil) | Ensures compliance with Brazil's ANP local content mandates, securing access to critical deepwater markets. |
| Long-Term Service Agreement Expansion | Transfers well-integrity and production-inflow performance risk from operators to specialized service providers. |
| Geothermal/CCUS Technology Adaptation | Opens new, non-cyclical revenue streams for sand control vendors in emerging energy transition sectors. |
Research Approach
Multi-period observation of deepwater drilling activity, regulatory compliance rates, and technological advancements anchored the trend analysis, supplemented by interviews with industry stakeholders. Primary research involved discussions with oilfield operators, service company executives, completion engineers, and regulatory body officials. Secondary validation utilized regulatory filings, industry association reports, and technical journals, employing both bottom-up and top-down triangulation.
An input-output matrix framework underpinned the quantitative modeling, integrating macro-economic indicators with industry-specific data. Segmentation dimensions included system type, application, installation method, end-user, and regional regulatory frameworks. Compound Annual Growth Rates were derived from historical growth patterns and projected investment trends. Key inputs included oil and gas capital expenditure and deepwater rig counts.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to geopolitical instability and fluctuating crude oil prices. All forecasts reflect underlying assumptions regarding regulatory stability and technological advancements. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Ball Valves Market
Valves
Portable Valve Actuator Market
Valves
Global Fluid Management Systems Market
Valves
Flow Computer Market
Valves
Carbon Seal Rings Market
Valves
Global Automotive Valves Market
Valves
Angle Opening Ball Locator Market
Valves
Pneumatic Slide Gates Market
Valves
Hydraulic Diaphragm Valve Market
Valves
Sandblast Valves Market
Valves
Rising Stem Ball Valve Market
Valves
Butterfly Valves Market
Valves
Pipeline Integrity Management (PIM) Market
Valves
Blasting Stemming Plugs Market
Valves
Pipeline and Process Services Market
Valves
Global Plug Valve Market