
 Angle Opening Ball Locator Market | 2026-2036
Angle Opening Ball Locator Market Size, Share, and Industry Trends Forecast 2026-2036
Angle Opening Ball Locator Market Insights
Buyer concentration among professional sports academies and elite coaching programs is hardening as institutional procurement replaces individual athlete purchases. SKF leverages its precision sensor heritage to supply high-reliability electronic locator components for integrated training systems. Schaeffler anchors European demand through specialized optical encoder modules designed for motion-capture applications. NTN competes in Asian markets with compact magnetic locator assemblies optimized for portable archery training devices.
An angle opening ball locator is a precision instrument that measures the angular displacement between a reference plane and a spherical object's position using electronic, optical, or magnetic sensing elements with typical resolution below 0.1 degrees. The device converts spatial orientation into quantifiable data for biomechanical feedback in sports training and recreational skill development. Electronic locators command the premium tier due to embedded accelerometer fusion and wireless telemetry capabilities, while mechanical variants retain cost-sensitive recreational segments where durability outweighs precision requirements. Optical locators represent the fastest-growing category as camera-based machine vision enables sub-degree accuracy without physical contact with the ball.
The US Consumer Product Safety Commission encloses durability and battery safety standards for electronic training devices sold to youth sports programs. The EU REACH regulation restricts certain phthalates in polymer housings, compelling manufacturers to reformulate grip materials for European distribution. Japan's METI promotes precision measurement instrument exports through quality certification frameworks that facilitate market access across Asia-Pacific. Stakeholders must monitor evolving battery chemistry regulations and sensor calibration standards as product categories blur between consumer recreation and professional athletic equipment.
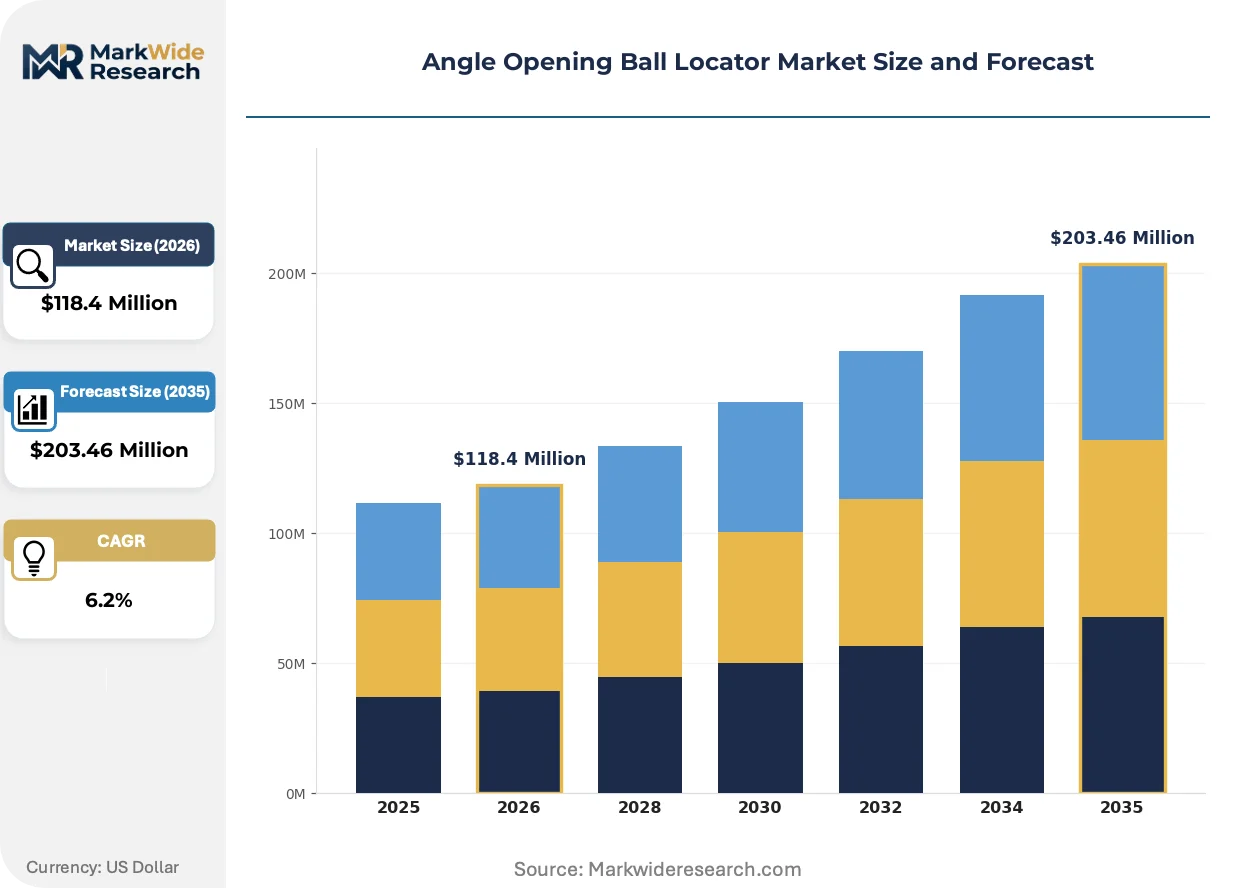
Market Dynamics
Machine vision integration is compressing price-performance thresholds across electronic and optical locator categories, forcing component suppliers to recalibrate sensor fusion architectures for recreational and professional tiers simultaneously.
Growth Catalysts
- EU Green Deal material mandates:Traceability requirements for recyclable polymer housings are accelerating R&D investment in bio-based grip compounds and circular supply partnerships.
- Golf instruction digitization:Private academies across Sun Belt states are consolidating purchases of wireless telemetry-enabled locators for biomechanical feedback systems.
- Machine vision cost curves:Sub-degree camera-based accuracy without ball contact is opening mid-market segments previously served by mechanical alternatives.
Market Restraints
- Precision sensor supply concentration:High-reliability accelerometer and encoder sourcing clusters in East Asian manufacturing corridors, exposing buyers to logistics volatility.
- REACH phthalate restrictions:ECHA-enforced polymer reformulation timelines extend European product certification cycles by 8-14 months.
- Magnetic interference limitations:Compact magnetic locator assemblies face accuracy degradation near ferrous infrastructure, constraining urban training facility deployments.
Strategic Opportunities
- Portable archery training expansion:Compact magnetic assemblies optimized for mobile coaching rigs address underserved recreational segments in secondary US markets.
- EU battery chemistry harmonization:Emerging standards for youth sports device safety create first-mover advantages for suppliers with integrated cell management systems.
- Optical-wireless convergence:Camera-based machine vision paired with low-latency telemetry enables subscription-based analytics platforms for coaching networks.
Industry Challenges
- Sensor calibration talent scarcity:Biomechanical instrumentation expertise concentrates in precision agriculture and medical device sectors, inflating recruitment costs for sports technology divisions.
- Multi-jurisdiction certification complexity:Divergent CPSC durability standards, REACH substance restrictions, and METI quality frameworks require parallel compliance tracks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Angle Opening Ball Locator Market |
| Market Size in 2026 | $118.4 Million |
| Market Size in 2035 | $203.46 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronic Locators, Mechanical Locators, Magnetic Locators, Optical Locators Use Case: Sports Training, Golf Instruction, Archery, Outdoor Recreation End User: Coaches, Athletes, Recreational Users, Sports Academies Distribution Channel: Online Retail, Specialty Sports Stores, Direct Sales, Wholesale Distributors |
| Companies Covered | SKF, NSK, Schaeffler, Timken, RBC Bearings, THK, JTEKT, NTN, Hawkeye Innovations, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Angle Opening Ball Locator Market Trends and Innovations
Edge computing architectures are redistributing data processing from centralized training systems to device-level inference, altering hardware specifications and supplier value capture across the locator category.
Camera-based machine vision is decentralizing quality assurance from laboratory calibration to real-time field adjustment. Elite coaching programs in Arizona and Florida training facilities are adopting optical locators with embedded neural processing units for instantaneous angular feedback. This capability compression eliminates post-session data upload dependencies and reduces hardware redundancy in portable coaching setups.
REACH substance restrictions are compelling housing manufacturers to validate alternative plasticizers through ECHA-registered third-party testing. European distributors now require batch-level material documentation for polymer grip components, shifting procurement screening criteria toward supply chain transparency metrics. Youth sports programs represent the most affected segment, as reformulated compounds undergo extended abrasion testing cycles.
Institutional procurement consolidation is displacing individual athlete purchases across private club and academy channels. Equipment managers now negotiate enterprise licensing for integrated training systems rather than per-device transactions, compressing vendor sales cycles and expanding after-sales service obligations. This pattern concentrates most visibly across Texas and California golf instruction networks.
Angle Opening Ball Locator Market Segmentation
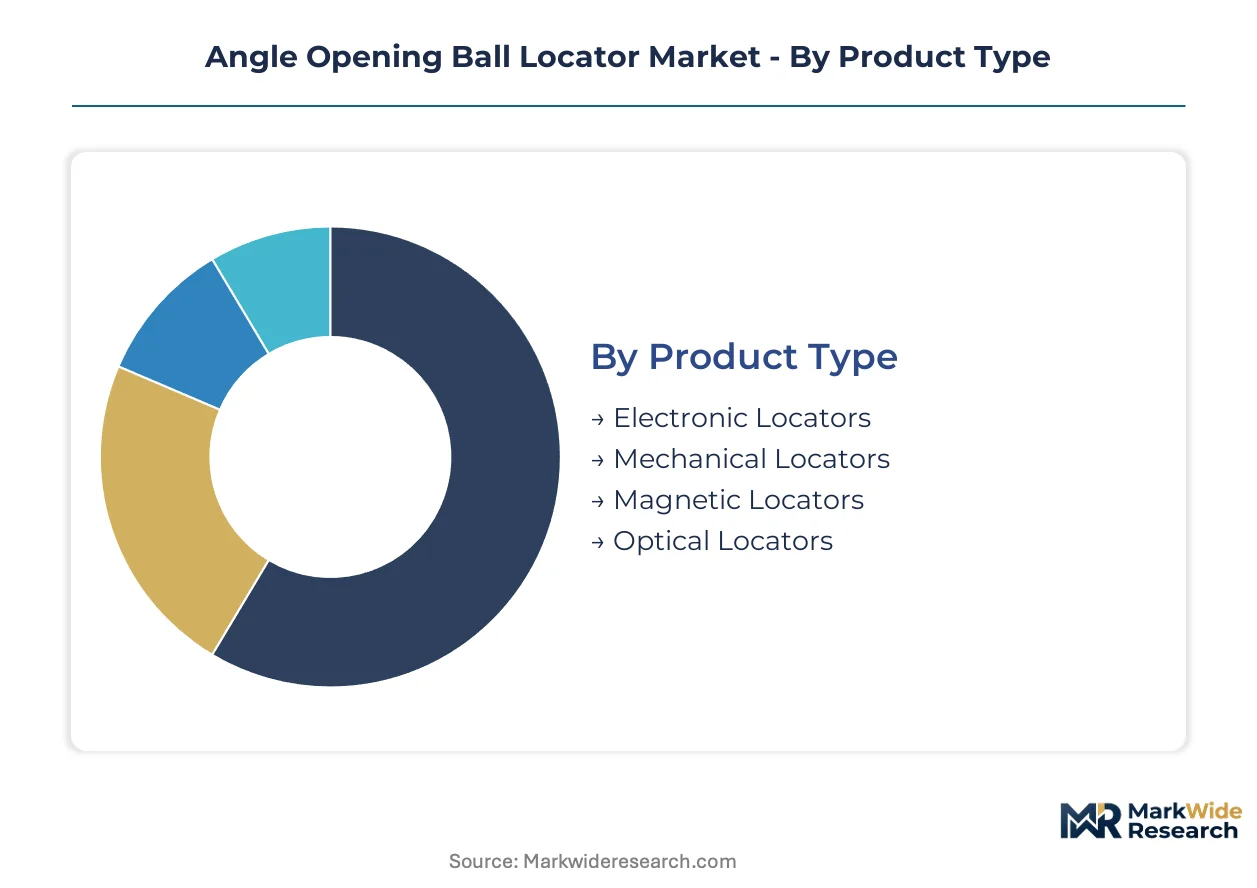
Angle opening ball locators serve divergent precision requirements across recreational and professional tiers, with product architecture and distribution economics varying sharply by use intensity and institutional procurement scale. Segmentation reveals how electronic complexity commands premium positioning while mechanical simplicity retains cost-sensitive volume channels.
Product Type:
Electronic locators dominate value capture through embedded sensor fusion, while mechanical variants anchor unit volume in entry-level recreational segments.
- Electronic Locators:These devices integrate accelerometer arrays with wireless telemetry modules to deliver sub-0.1-degree resolution and real-time biomechanical feedback. Demand concentrates among private golf academies across Florida and Arizona, where institutional procurement of integrated training systems replaces individual athlete purchases. SKF supplies precision sensor components for high-reliability installations in elite coaching environments.
- Optical Locators:Camera-based machine vision enables contactless angular measurement with neural processing units for instantaneous field-level inference. Arizona and Florida training facilities are adopting these systems for portable coaching setups that eliminate post-session data dependencies. This category is climbing the fastest as cost curves compress price-performance thresholds across mid-market segments.
- Mechanical Locators:Spring-loaded goniometer mechanisms serve durability-focused recreational users where precision requirements stay above 0.5 degrees.
- Magnetic Locators:Hall-effect sensor assemblies from NTN target compact archery training devices in Asian markets with ferrous-interference limitations.
Mature deployment sits with Electronic Locators in established golf instruction networks. Newer deployment is concentrated in Optical Locators as machine vision cost curves enable mid-market penetration.
Use Case:
Professional instruction applications drive premium tier specifications, while recreational self-training sustains mechanical and magnetic locator volume.
- Golf Instruction:Biomechanical feedback systems at Sun Belt private clubs require wireless telemetry integration with swing analysis software. Texas and California networks are consolidating enterprise licensing for integrated training platforms rather than per-device transactions.
- Sports Training:Multi-sport academies deploy electronic locators across baseball pitching and tennis serve applications, with sensor calibration expertise recruited from precision agriculture sectors.
- Archery:Compact magnetic assemblies serve mobile coaching rigs in secondary US markets where portability outweighs urban infrastructure constraints.
- Outdoor Recreation:Casual users in year-round outdoor recreation infrastructure purchase mechanical variants through specialty retail channels.
Revenue concentration aligns with Golf Instruction's institutional procurement consolidation. Volume expansion is accelerating fastest in Archery as portable training formats penetrate underserved geographic markets.
End User:
Institutional buyers are displacing individual purchases through enterprise licensing frameworks, altering vendor sales cycles and service obligations.
- Sports Academies:Equipment managers negotiate multi-year service contracts encompassing calibration, firmware updates, and analytics platform access. Procurement screening now emphasizes supply chain transparency metrics for polymer components under REACH substance restrictions.
- Coaches:Independent professionals purchase optical-wireless convergent systems for subscription-based analytics platforms serving distributed athlete networks.
- Athletes:Elite competitors access locator data through academy infrastructure rather than personal device ownership.
- Recreational Users:Price-sensitive purchasers select mechanical locators through online retail channels with minimal after-sales service expectations.
Procurement authority has shifted decisively toward Sports Academies. Individual Athlete purchases are retreating to entry-tier mechanical products.
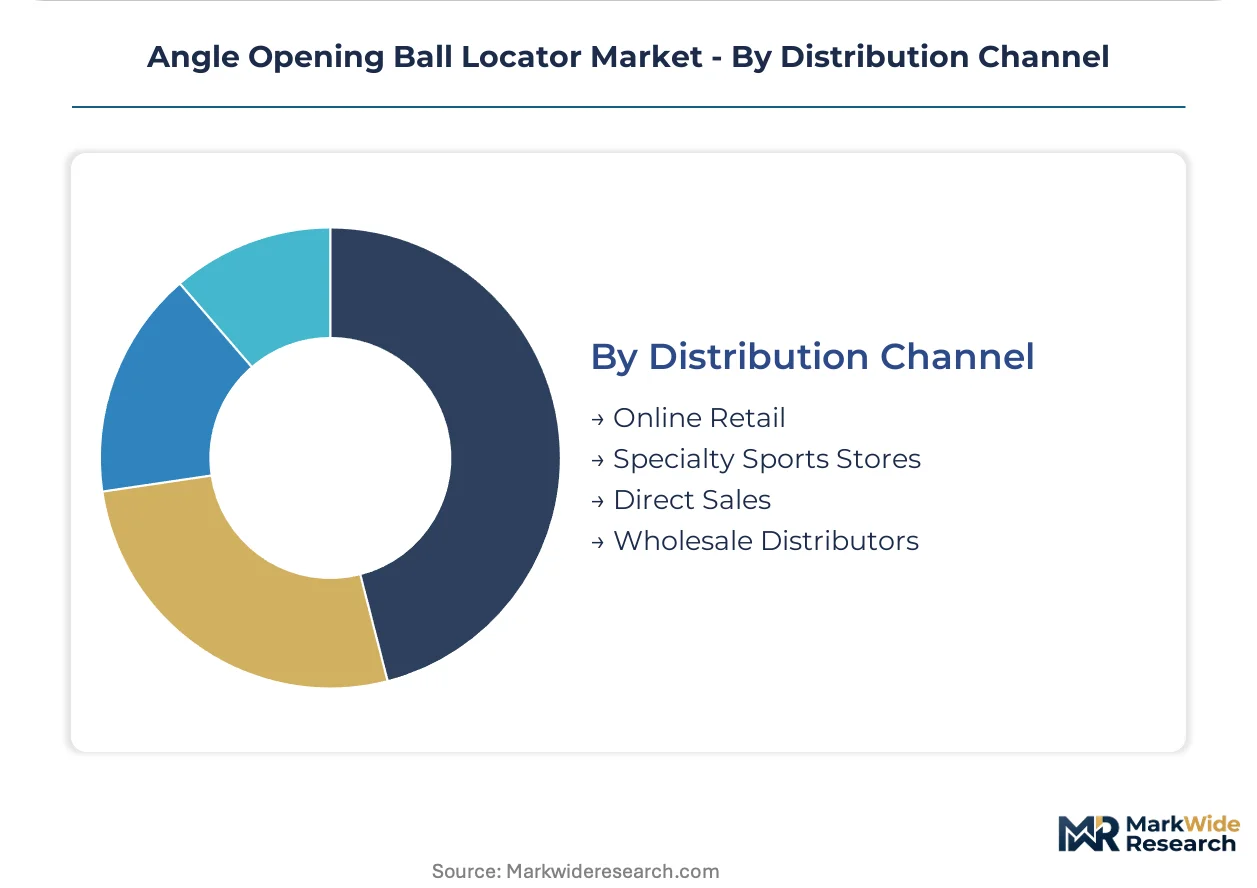
Distribution Channel:
Channel economics reflect the divergence between high-touch institutional sales and low-margin recreational volume.
- Direct Sales:Vendor field teams engage golf academy equipment managers with integrated system demonstrations and enterprise licensing negotiations. This channel captures premium pricing through embedded service obligations and calibration support.
- Specialty Sports Stores:Pro shops at private clubs stock electronic locators for member purchase, with staff trained on basic operation and troubleshooting.
- Online Retail:E-commerce platforms serve recreational users seeking mechanical and entry-tier electronic locators with standardized specifications and minimal configuration.
- Wholesale Distributors:Regional distributors inventory magnetic and optical locators for archery specialty retailers and outdoor recreation outlets.
Margin retention is strongest in Direct Sales with embedded service contracts. Volume scaling is concentrated in Online Retail as recreational self-service purchases expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision polymer feedstock availability in the Rhine-Ruhr corridor anchors European manufacturing capacity for angle opening ball locator housings, while East Asian semiconductor foundry clusters supply the sensor substrates that determine device accuracy tiers.
United States
Sun Belt golf academies in Arizona and Florida drive institutional procurement of wireless telemetry-enabled locators for year-round outdoor instruction. The US Consumer Product Safety Commission enforces durability and battery safety standards for youth sports training devices. Dallas-Fort Worth and Houston training networks are consolidating enterprise licensing agreements for integrated biomechanical feedback systems.
Germany
Specialized optical encoder demand from motion-capture applications in Baden-Württemberg industrial zones sustains component manufacturing. ECHA-enforced REACH phthalate restrictions extend product certification cycles for polymer grip reformulations. Stuttgart-area precision engineering clusters supply calibration expertise for European professional coaching programs.
Japan
METI quality certification frameworks facilitate precision measurement instrument exports across Asia-Pacific markets. Tokyo and Osaka metropolitan training facilities adopt edge-computing optical locators with embedded neural processing units. Kansai-region component suppliers optimize compact magnetic assemblies for archery training device integration.
China
Domestic golf instruction digitization in Shenzhen and Guangzhou creates demand for mid-tier electronic locator systems. MIIT standards for wireless telemetry devices shape product specifications for youth sports applications. Yangtze River Delta manufacturing corridors concentrate high-reliability accelerometer sourcing for integrated training platforms.
Angle Opening Ball Locator Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue machine vision and edge-computing integration to compress price-performance thresholds. The vendor base stratifies across three tiers: precision bearing conglomerates with sensor heritage, specialized optical encoder fabricators, and compact magnetic assembly specialists. Competitive positioning hardens around M&A activity targeting calibration expertise and strategic partnerships for circular polymer supply chains.
Among precision bearing conglomerates, SKF and Schaeffler exemplify archetypes leveraging industrial sensor heritage for high-reliability electronic locator components. NTN occupies a position within the compact magnetic assembly tier, serving Asian market demand for portable archery training devices. These three entities represent the dominant competitive anchors across electronic, optical, and magnetic locator categories respectively.
| Leading Market Players |
|---|
| SKF |
| NSK |
| Schaeffler |
| Timken |
| RBC Bearings |
| THK |
| JTEKT |
| NTN |
| Hawkeye Innovations |
| Others |
Pricing and Supply Chain Analysis
Machine vision cost compression is simultaneously collapsing electronic locator price floors and concentrating optical sensor sourcing among East Asian foundry clusters. This dual restructuring forces component suppliers to recalibrate margin expectations while buyers exploit expanded negotiating leverage across wireless telemetry tiers.
Pricing Analysis
Embedded calibration warranties separate premium electronic locator contracts from unbundled mechanical alternatives sold through online retail. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by wireless telemetry integration and REACH-compliant polymer certification grades. Pricing pressure stems from camera-based accuracy thresholds encroaching on mid-market electronic segments previously protected by accelerometer fusion complexity. Recreational users purchasing through e-commerce channels exhibit highest price sensitivity, while Sun Belt golf academies prioritize service bundling over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for high-reliability accelerometer substrates, while China dominates compact magnetic Hall-effect sensor fabrication. Polymer housing production draws from Germany's Rhine-Ruhr precision feedstock corridor and China's Yangtze River Delta molding clusters. Tariff exposure on wireless telemetry modules creates logistics volatility for North American assembly operations. Distribution runs through direct vendor field teams for institutional procurement and wholesale distributors serving archery specialty retailers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around machine vision integration capabilities that marginalize mechanical locator specialists lacking optical R&D infrastructure.
For Market Incumbents: Anticipate margin compression in electronic tiers as camera-based systems displace accelerometer-dominant architectures at lower price points. Defend positioning through backward integration into polymer compounding for REACH-compliant grip materials, securing ECHA-registered third-party validation ahead of certification cycle extensions. Prioritize calibration expertise acquisition from precision agriculture and medical device sectors where biomechanical instrumentation talent concentrates. For New Entrants and Emerging Players: Capture white-space opportunity in portable archery training devices for secondary US markets where magnetic locator accuracy constraints are less prohibitive than urban infrastructure interference. Target Sun Belt golf instruction networks with subscription-based analytics platforms bundling optical-wireless convergent systems. Deploy through independent coach networks rather than competing directly with established academy procurement channels. For Investors and Strategic Acquirers: Exit pathways concentrate in precision bearing conglomerates seeking sensor fusion capabilities for integrated training system portfolios. Long-term viability favors vendors with demonstrated ECHA compliance documentation and embedded neural processing unit integration for edge-computing inference. Monitor machine vision patent filing velocity as inflection indicator for category displacement timing.| Strategic Initiative | Industry Significance |
|---|---|
| Machine Vision Patent Portfolio Expansion | Camera-based accuracy patents from Arizona training facility deployments protect mid-market positioning against mechanical alternatives. |
| REACH-Compliant Polymer Compounding Partnership | ECHA-registered third-party testing relationships accelerate European certification cycles for youth sports device distribution. |
| Calibration Expertise Acquisition | Precision agriculture and medical device sector recruitment addresses sensor fusion talent scarcity inflating sports technology division costs. |
| Wireless Telemetry Module Integration | Low-latency telemetry capabilities enable subscription-based analytics platforms for Texas and California coaching networks. |
| Direct Academy Field Sales Expansion | Enterprise licensing negotiations with Florida and Arizona equipment managers capture premium pricing through embedded service obligations. |
Research Methodology
SEC filings, ECHA substance restriction databases, and golf instruction equipment procurement records formed the secondary backbone for market sizing and competitive positioning assessment. Primary interviews with golf academy equipment managers, optical encoder R&D directors, polymer compound procurement leads, and sports technology division heads validated demand assumptions and pricing dynamics. Bottom-up and top-down triangulation reconciled unit shipment estimates with institutional procurement value capture across Sun Belt training networks.
Bottom-up modeling aggregated segment-level unit economics across electronic, optical, mechanical, and magnetic locator categories, while top-down analysis cross-referenced precision measurement instrument trade flows with METI export certification frameworks. Segmentation dimensions included product architecture complexity, use case intensity, end user procurement authority, and distribution channel service embedding. CAGRs were derived from fitted growth curves incorporating machine vision cost trajectory assumptions and REACH compliance timeline impacts across the projection horizon.
The model holds under sustained machine vision cost compression and stable REACH enforcement intensity; deviation in semiconductor substrate availability or ECHA substance restriction expansion would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Steam Safety Valve Market
Valves
Global Globe Valve Market
Valves
Emergency Shutdown Valves Market
Valves
Pipeline and Process Services Market
Valves
Float Traps Market
Valves
Valve Cover Gasket Market
Valves
Hydraulic Diaphragm Valve Market
Valves
North America Butterfly Valve Market
Valves
Thermal Power Valve Market
Valves
Pneumatic Slide Gates Market
Valves
Middle East and Africa Machined Seals Market
Valves
Asia-Pacific Industrial Valves Market
Valves
Instrumentation Valves and Fittings Market
Valves
Christmas Tree Valves Market
Valves
Pipeline Integrity Management (PIM) Market
Valves
Blow - Off Valves Market