
 Blasting Stemming Plugs Market | 2026-2036
Blasting Stemming Plugs Market Size, Share, and Industry Trends Forecast 2026-2036
Blasting Stemming Plugs Market Analysis
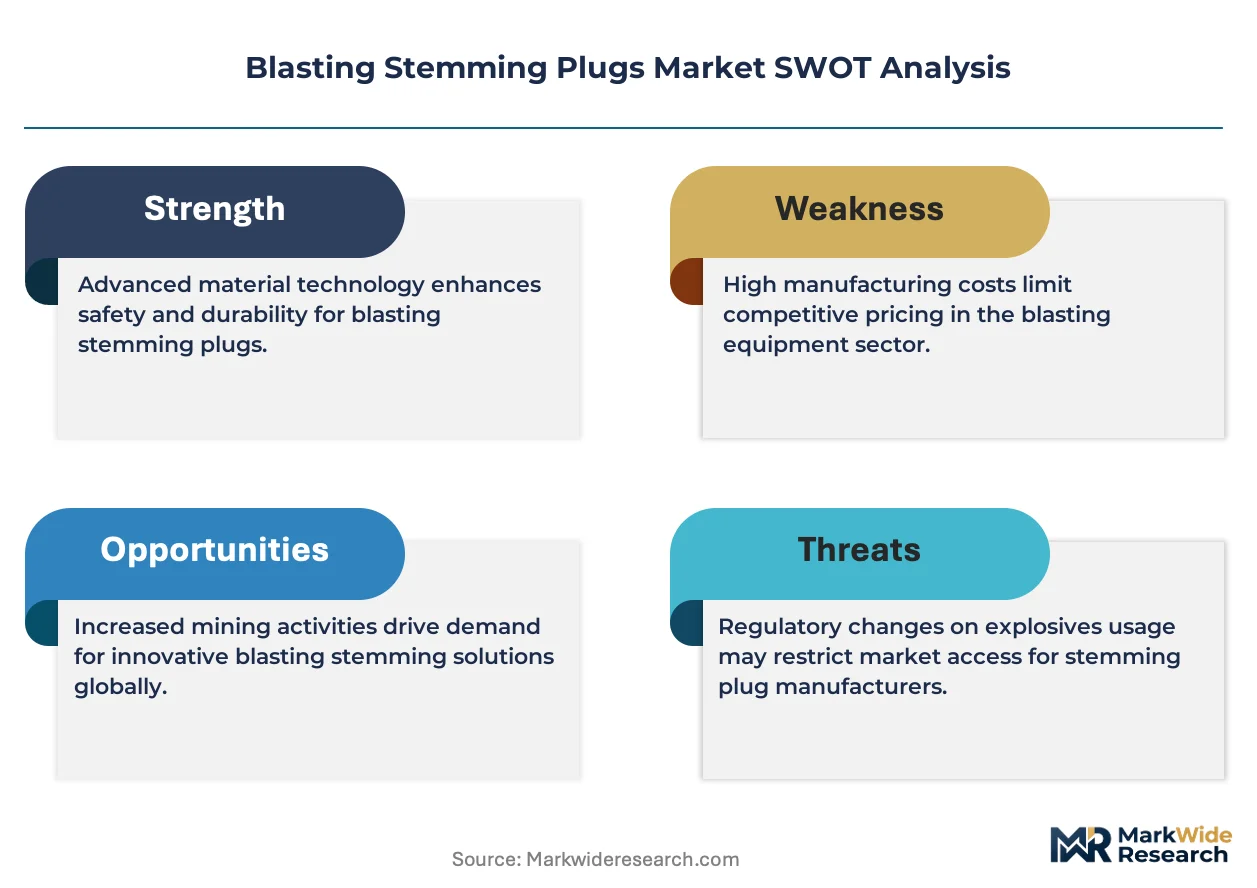
Equipment leasing and rental financing for blast accessories is reconfiguring competitive dynamics by lowering capital barriers for mid-tier quarry operators. Advanced Blasting Technology Inc leverages its specialized product portfolio to anchor premium positioning in North American mining districts. MOCAP competes through manufacturing scale and broad material compatibility across plastic and rubber stemming plug lines. Stemlock Inc differentiates via technology leadership in mechanical-locking designs that reduce installation time in deep boreholes.
Blasting stemming plugs are cylindrical devices inserted into the collar zone of a blasthole to confine explosive energy and prevent premature venting through the hole mouth; composite variants typically integrate fiberglass-reinforced polymers rated for compressive loads exceeding 50 MPa, while rubber plugs employ elastomeric compounds designed for conformable sealing in irregular borehole walls. The mining application segment dominates volume consumption due to continuous blast cycles in surface and underground extraction, though demolition contractors represent the fastest-growing demand pool as urban deconstruction projects require precise fragmentation control near sensitive infrastructure. Plastic stemming plugs occupy the largest product category share driven by cost efficiency in high-volume quarrying, yet composite plugs command superior margin pools where thermal stability and dimensional precision justify specification in deep-hole metal mining.
The US Mine Safety and Health Administration enforces flyrock containment standards that directly mandate engineered stemming systems in surface coal operations, while Australia's Department of Industry, Science and Resources coordinates state-level blasting codes that specify minimum stemming length ratios. The EU's REACH regulation governs chemical composition disclosures for rubber compound formulations used in stemming plug manufacturing, affecting import compliance for non-European suppliers. Stakeholders must monitor evolving fragmentation efficiency metrics and regulatory harmonization between national mining safety frameworks to anticipate specification shifts that will reshape procurement criteria for stemming systems.
Market Dynamics
Composite stemming plug adoption is compressing conventional stemming material demand as Australia's Department of Industry, Science and Resources tightens blast containment protocols across Pilbara iron ore operations.
Growth Catalysts
- Mechanical-locking technology:Stemlock Inc's installation-speed designs reduce collar-zone preparation time in deep boreholes, accelerating contractor throughput in Western Australia's high-frequency blasting schedules.
- Flyrock containment mandates:Australia's national resources regulator now specifies engineered plug systems over loose fill, compelling procurement shifts across surface and underground extraction sites.
- Urban demolition precision:Demolition contractors in dense infrastructure corridors require conformable rubber plug sealing to control fragmentation near sensitive structures.
Market Restraints
- Petrochemical input volatility:Fiberglass-reinforced polymer and elastomeric compound costs fluctuate with crude derivatives, squeezing margin pools for composite and rubber plug manufacturers.
- Supplier concentration risk:Specialized polymer compounding capacity clusters in select industrial zones, creating vulnerability for blast accessory procurement during supply shocks.
- Deep-hole dimensional limits:Mechanical-locking designs face technical constraints in boreholes exceeding 15 meters, restricting specification in ultra-deep metal mining applications.
Strategic Opportunities
- Equipment leasing channels:Rental financing for blast accessories lowers capital barriers for mid-tier quarry operators, expanding addressable demand beyond tier-one mining houses.
- REACH compliance positioning:EU rubber compound disclosure requirements create import friction for non-European suppliers, opening share capture for REACH-certified manufacturers.
- Demolition vertical expansion:Urban deconstruction projects in North American and Australian metropolitan cores represent underpenetrated demand for precision fragmentation control.
Industry Challenges
- Blast engineering skill scarcity:Specialized borehole collar design expertise remains concentrated among veteran contractors, constraining workforce scalability for expanding operations.
- Legacy stemming integration:Conventional loose-fill systems persist in cost-sensitive quarrying, creating specification friction during composite plug conversion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blasting Stemming Plugs Market |
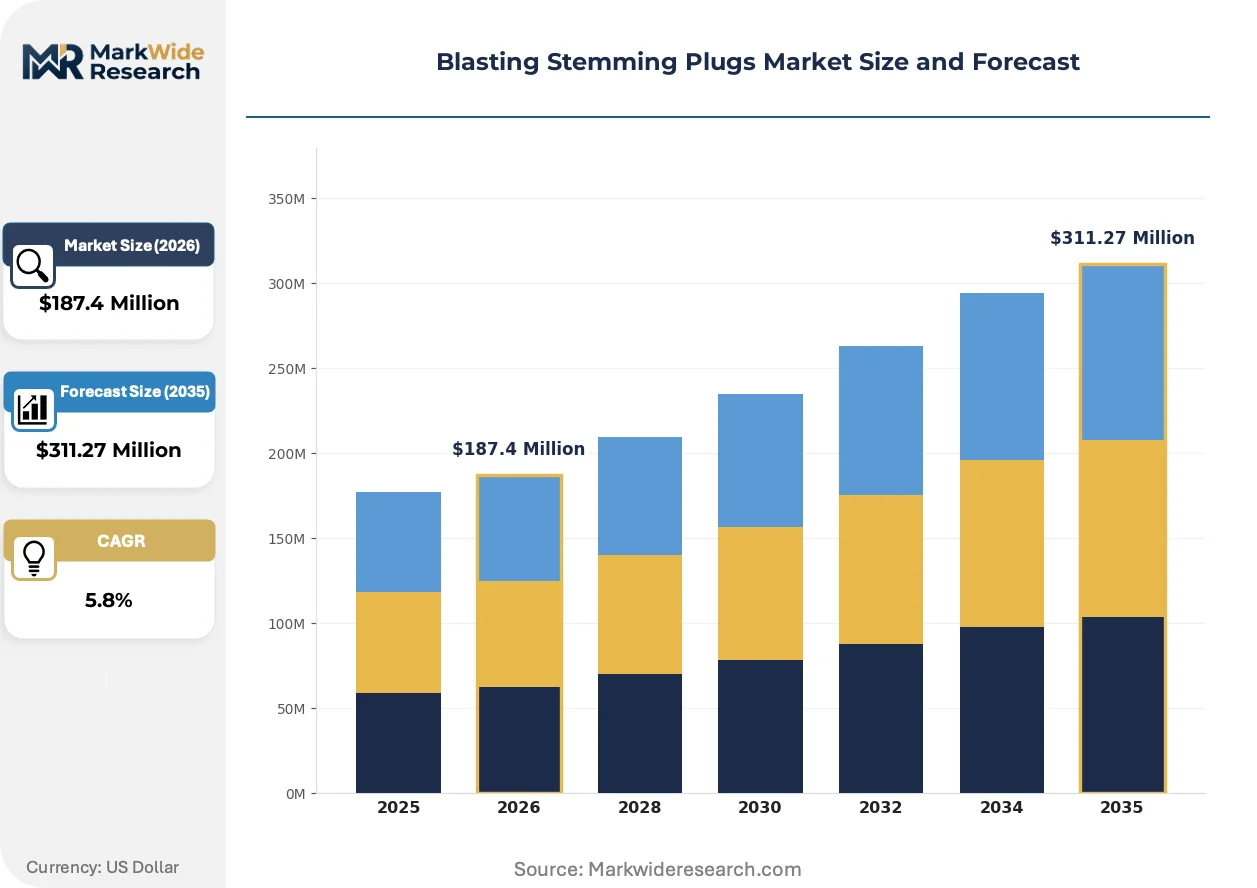
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Rubber, Composite, Wood Application: Mining, Construction, Quarrying, Demolition End User: Contractors, Mining Companies, Construction Firms, Government Agencies Distribution Channel: Direct Sales, Distributors, Online Retail, Resellers |
| Companies Covered | Advanced Blasting Technology Inc, MOCAP, Stemlock Inc, AMA Group, Paraplug, Superplug SA, AECE, Vala Stemming Systems, Peri Nitrates Pvt Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blasting Stemming Plugs Market Emerging Trajectories
Smart borehole monitoring and material science advances are converging to reshape stemming system specification criteria across extraction and demolition verticals.
Sensor-embedded composite plugs are digitizing blast performance feedback by transmitting collar-zone pressure data to central control systems. Underground mining contractors in Australia's Pilbara region pilot these devices to optimize stemming depth and explosive loading in real time. This capability is digitizing fragmentation efficiency benchmarking, compressing the iteration cycle between blast design and outcome measurement.
REACH regulation governing chemical composition disclosures for rubber compound formulations is restructuring import compliance burdens for stemming plug manufacturers. Non-European suppliers face documentation and testing cost escalation to maintain EU market access. Composite plug categories gain relative positioning where polymer formulations bypass REACH's elastomer disclosure thresholds.
Leasing and rental financing for blast accessories is displacing capital purchase models among mid-tier quarry operators. Equipment lessors bundle stemming plugs with drill rigs and initiation systems, consolidating procurement relationships. This channel shift concentrates most visibly in North American mining districts where capital discipline pressures favor operational expenditure structures over asset ownership.
Blasting Stemming Plugs Market Segmentation
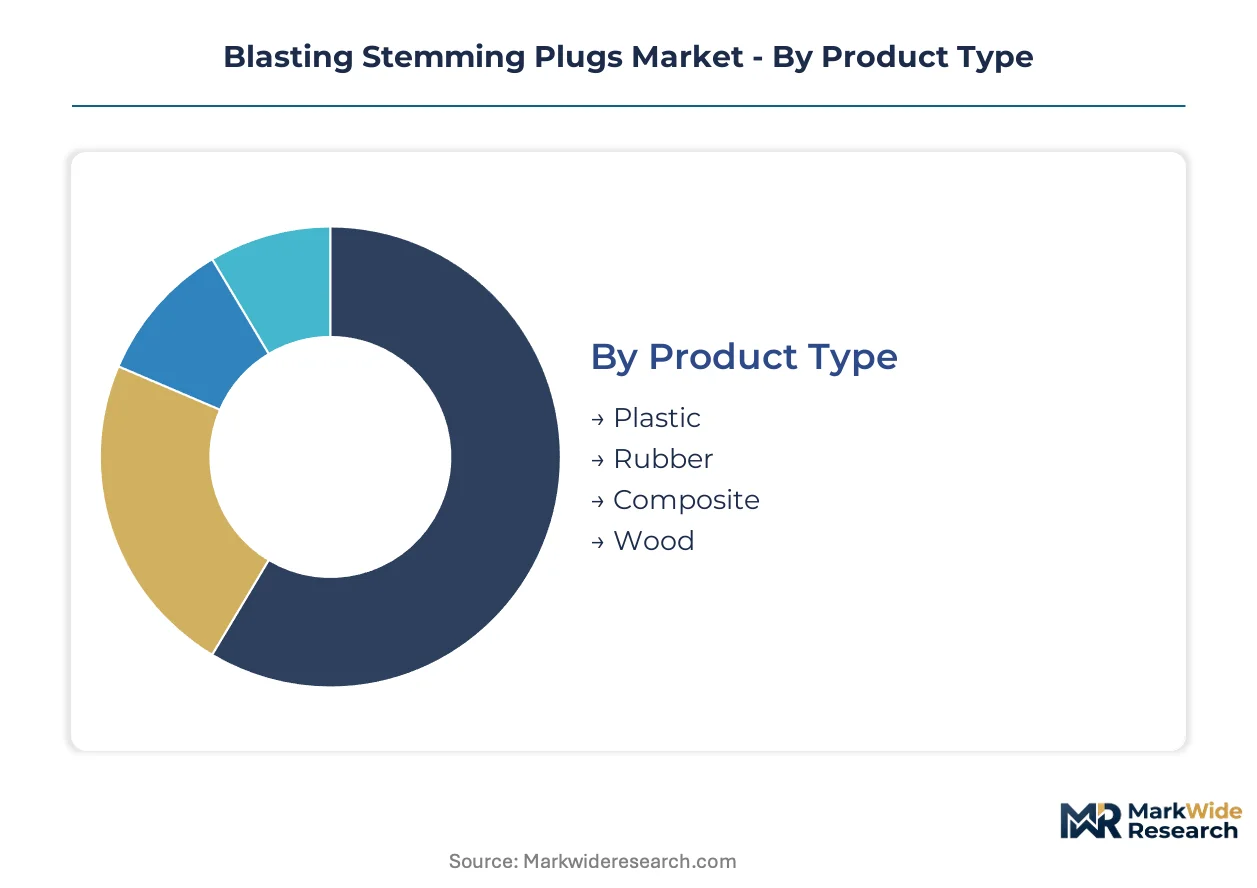
Blasting stemming plugs serve divergent performance requirements across extraction depths, regulatory environments, and fragmentation precision needs. Segmentation reveals how material selection and procurement channels align with operational scale and safety mandates.
Product Type:
Material composition determines compressive load tolerance, thermal stability, and installation speed across collar-zone applications.
- Plastic:Injection-molded polymer formulations deliver cost efficiency for high-volume quarrying operations. Demand concentrates in North American surface limestone quarries where blast frequency justifies disposable economics over reuse cycles.
- Composite:Fiberglass-reinforced polymers rated above 50 MPa compressive load anchor specification in Western Australia's Pilbara iron ore deep-hole operations. Australia's Department of Industry, Science and Resources mandates engineered systems in this category for flyrock containment compliance.
- Rubber:Elastomeric compounds conform to irregular borehole walls for sealing integrity. REACH disclosure requirements govern EU import compliance for these formulations.
- Wood:Traditional timber stemming persists in cost-sensitive manual drilling contexts. Limited specification in regulated mining jurisdictions constrains volume.
Plastic holds installed capacity. Composite is rotating up the share rankings.
Application:
End-use context dictates stemming length ratios, energy confinement requirements, and proximity sensitivity to surrounding infrastructure.
- Mining:Continuous blast cycles in surface and underground extraction dominate volume consumption. Western Australia's high-frequency iron ore schedules specify mechanical-locking designs for collar-zone efficiency.
- Demolition:Urban deconstruction near sensitive infrastructure demands conformable sealing and precision fragmentation control. Contractors in Australian and North American metropolitan cores drive specification for rubber plug systems in this vertical.
- Construction:Road building and foundation work utilize standard plastic stemming for controlled breakage in rock excavation. Project-based procurement favors distributor channels over direct manufacturer relationships.
- Quarrying:Mid-tier aggregate producers balance cost discipline with regulatory baseline compliance. Equipment leasing models lower capital barriers for stemming system adoption in this segment.
Mining anchors volume throughput. Demolition is climbing the fastest.
End User:
Procurement authority and technical specification capability vary sharply across organizational scale and in-house blasting expertise.
- Mining Companies:Tier-one extraction houses with dedicated blast engineering teams specify premium composite systems. Direct sales relationships with manufacturers enable custom polymer formulation for site-specific geology.
- Contractors:Specialized blasting subcontractors rotate across project sites with portable equipment inventories. Rental financing for stemming plugs aligns with their operational expenditure structure and capital discipline pressures.
- Construction Firms:General contractors subcontract blasting operations and procure stemming through distributor networks. Price sensitivity favors plastic categories in standard borehole diameters.
- Government Agencies:Public infrastructure projects mandate compliance with national mining safety frameworks. Procurement specifications reference engineered plug systems over loose-fill alternatives in regulated jurisdictions.
Mining companies hold installed capacity. Contractors are gaining share fastest.
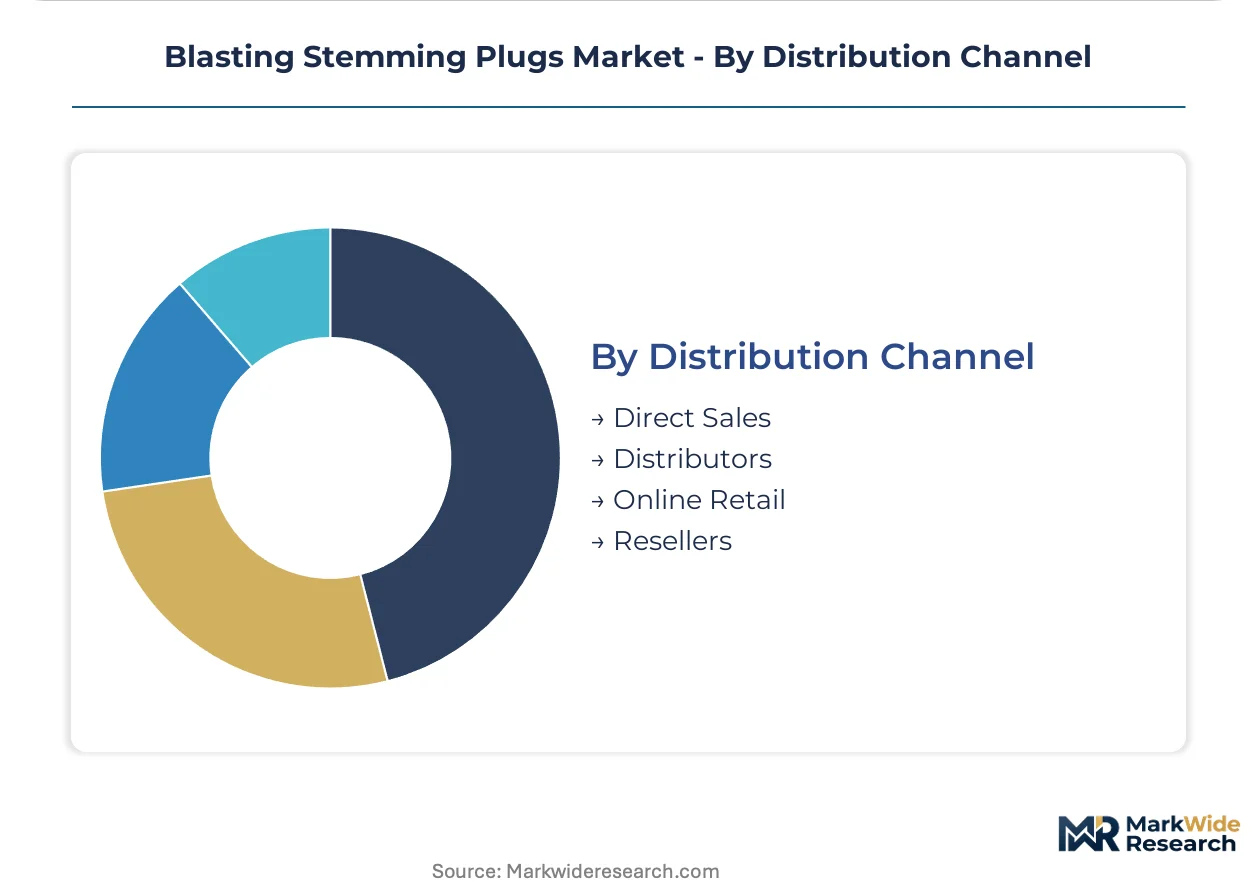
Distribution Channel:
Channel selection reflects order scale, technical support requirements, and geographic proximity to manufacturing or compounding capacity.
- Direct Sales:Large-volume mining houses negotiate polymer formulation customization and volume pricing. Manufacturer technical teams provide borehole collar design support for deep-hole metal mining applications.
- Distributors:Regional blast supply houses consolidate stemming plugs with initiation systems and drill consumables. Quarrying and construction segments rely on distributor inventory proximity for just-in-time project delivery.
- Resellers:Independent agents broker procurement relationships for mid-tier contractors without established supplier credit. Channel fragmentation creates price transparency challenges.
- Online Retail:Standard-dimension plastic plugs move through digital procurement platforms for small-quantity orders. Limited technical consultation constrains specification complexity.
Direct sales holds installed capacity. Distributors are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australia's Department of Industry, Science and Resources has mandated engineered stemming systems across Pilbara iron ore operations, triggering procurement shifts that reverberate through supplier networks worldwide. National mining safety frameworks in major extraction economies are tightening flyrock containment protocols, compressing demand for conventional loose-fill materials.
Australia
Western Australia's Pilbara region anchors regional demand through high-frequency blasting schedules at deep-hole iron ore mines. The national resources regulator specifies composite stemming plugs for flyrock containment compliance, displacing gravel and drill cuttings in collar-zone applications. Perth-based procurement offices coordinate direct manufacturer relationships for polymer formulation customization.
United States
Surface coal operations in Appalachia and the Powder River Basin drive specification for engineered stemming under MSHA flyrock containment standards. The Mine Safety and Health Administration mandates collar-zone confinement systems in surface blasting permits, compelling operator compliance across Kentucky, West Virginia, and Wyoming extraction sites. Equipment lessors in Nevada's gold mining districts bundle stemming plugs with drill rig rentals.
China
Iron ore mining in Hebei Province and copper extraction in Jiangxi Province concentrate demand for cost-efficient plastic stemming systems. The Ministry of Emergency Management coordinates provincial blasting safety codes that reference stemming length ratios for open-pit operations. Yangtze River Delta manufacturing clusters supply injection-molded polymer plugs to domestic quarrying operations.
Brazil
Iron ore extraction in Minas Gerais and copper mining in Pará state generate volume consumption for composite and rubber stemming categories. The National Mining Agency enforces blast pattern documentation requirements that favor engineered plug systems over variable loose-fill performance. Equipment distributors in Belo Horizonte consolidate stemming procurement with initiation system sales.
South Africa
Platinum group metal mining in the Bushveld Complex and gold extraction in the Witwatersrand Basin specify stemming plugs for deep-hole thermal stability. The Department of Mineral Resources and Energy mandates blast management plans that reference collar-zone confinement standards. Johannesburg-based blasting contractors rotate composite plug inventories across multiple mine sites.
Blasting Stemming Plugs Market Vendor Landscape
On the supply side, the industry is structured around three distinct capability tiers: specialized polymer compounders with custom formulation expertise, scale manufacturers serving high-volume quarrying segments, and technology-focused designers of mechanical-locking installation systems. Strategic moves concentrate on rental financing channel development and REACH compliance positioning for EU market access.
Specialists in mechanical-locking designs include Stemlock Inc, which occupies a position in the technology-driven tier alongside composite-focused Advanced Blasting Technology Inc. MOCAP represents the scale-manufacturing archetype with broad material compatibility across plastic and rubber product lines. These three companies exemplify the competitive vectors shaping procurement relationships: installation speed optimization, premium material performance, and manufacturing throughput.
| Leading Market Players |
|---|
| Advanced Blasting Technology Inc |
| MOCAP |
| Stemlock Inc |
| AMA Group |
| Paraplug |
| Superplug SA |
| AECE |
| Vala Stemming Systems |
| Peri Nitrates Pvt Ltd |
| Others |
Supply Flow & Price Mechanics
Petrochemical input volatility determines both pricing tier spreads and supply chain shape across the blasting stemming plugs market. Crude derivative fluctuations compress margin pools for fiberglass-reinforced polymer and elastomeric compound manufacturers, forcing tiered pricing stratification that separates REACH-certified European suppliers from import-dependent operators in Asia-Pacific and Latin America.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers in this market. Three-tier pricing structure across premium, standard, and economy levels reflects compliance burden differentiation, with REACH-certified rubber compound formulations commanding substantial premiums over non-certified alternatives. Cost compression in composite categories is intensifying because fiberglass-reinforced polymer feedstock prices track naphtha derivatives. Mid-tier quarry operators exhibit highest price sensitivity, while Pilbara iron ore mining houses prioritize thermal stability and dimensional precision over unit economics.
Supply Chain Analysis
Contract manufacturing concentration for injection-molded polymer plugs centers on Yangtze River Delta facilities serving domestic Chinese quarrying operations. Raw material sourcing draws from Saudi Arabian petrochemical complexes for polymer resin, Australian mining districts for fiberglass reinforcement, and Malaysian rubber plantations for elastomeric compounds. Single-source vulnerability clusters in specialized polymer compounding capacity located in Germany's industrial corridor. Distribution runs through regional blast supply houses that consolidate stemming plugs with initiation systems and drill consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The blasting stemming plugs market sits in early-cycle expansion as Australia's flyrock containment mandates trigger procurement shifts across engineered plug systems. Regulatory harmonization between national mining safety frameworks is accelerating specification conversion from loose-fill materials.
For Market Incumbents: Build regulatory certification moats through REACH compliance investment and TGA alignment for Australian market access. Backward integration into fiberglass-reinforced polymer compounding secures margin control against petrochemical volatility. Capacity addition in Perth-based distribution hubs captures Pilbara procurement relationships. Stemlock Inc's mechanical-locking patent portfolio demonstrates how installation-speed technology anchors premium positioning.
For New Entrants and Emerging Players: Establish a beachhead in North American urban demolition verticals where conformable rubber plug demand outpaces established supply relationships. Target mid-tier quarry operators through equipment leasing partnerships that bundle stemming systems with drill rig rentals. Direct-to-contractor digital procurement platforms offer lowest-friction go-to-market entry for standard-dimension plastic categories.
For Investors and Strategic Acquirers: Australia's Department of Industry, Science and Resources flyrock mandate reshapes the acquisition landscape toward REACH-certified manufacturers with Pilbara operational presence. Long-term viability favors compounders with in-house polymer formulation capability and direct mining house relationships. Monitor state-level blasting code adoptions across Brazil's National Mining Agency and South Africa's Department of Mineral Resources and Energy as inflection indicators for specification shift velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| REACH Compliance Certification | EU rubber compound disclosure requirements create import friction for non-European suppliers. |
| Equipment Leasing Partnership | Rental financing bundles stemming plugs with drill rigs for mid-tier quarry operators. |
| Mechanical-Locking R&D Investment | Installation-speed designs reduce collar-zone preparation time in Western Australia's deep boreholes. |
| Perth Distribution Hub Expansion | Proximity to Pilbara iron ore procurement offices enables just-in-time polymer customization. |
| Demolition Vertical Channel Development | Urban deconstruction projects in Australian and North American metropolitan cores drive rubber plug specification. |
Methodological Framework
A standing panel of blast engineering directors, mine procurement managers, quarry operations supervisors, and demolition contracting principals provided ongoing calibration throughout this study. Primary interviews with these stakeholders combined with secondary validation from customs trade databases, Australian Department of Industry regulatory filings, SEC 10-K disclosures from listed mining services firms, and MSHA enforcement records. Bottom-up unit consumption estimates triangulated against top-down market sizing derived from regional blasting frequency data and stemming length ratio specifications.
Scenario-bracketing framed volume and value outputs across the projection horizon, with segmentation modeling across product type, application, end user archetype, and distribution channel dimensions. CAGRs were derived from regression analysis against iron ore production forecasts and demolition permit issuance trends. Industry-specific forecast inputs included Pilbara blast frequency schedules and urban deconstruction project pipelines in North American metropolitan cores.
Sensitivities concentrate around petrochemical price volatility, regulatory adoption timelines for flyrock containment mandates, and mechanical-locking technology penetration rates in deep-hole applications. Forecasts reflect assumptions regarding continued specification shift from loose-fill materials to engineered plug systems. Quarterly review of state-level blasting code amendments and mining safety framework harmonization progress is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Stainless Steel Valve Tag Market
Valves
Europe Electro Hydraulic Servo Valve Market
Valves
Battery Pack Cooling Valve Actuator Systems Market
Valves
Global Valve Positioners Market
Valves
Pressure Gauge Market
Valves
Chemical Injection Skid Market
Valves
Valve Seat Inserts Market
Valves
Pulsation Dampeners Market
Valves
Hydraulic Diaphragm Valve Market
Valves
Pigging Valves Market
Valves
Portable Valve Actuator Market
Valves
Global Plastic Valves Market
Valves
China Explosion-Proof Equipment Market
Valves
Air Heated Vaporizer Market
Valves
Fluid Transfer Solutions Market
Valves
Valve Grinder Market