
 Norway Oil and Gas EPC Market | 2026-2036
Norway Oil and Gas EPC Market Size, Share, and Industry Trends Forecast 2026-2036
Norway Oil and Gas EPC Market Analytics
The Norway Oil and Gas EPC market is pivoting on a widening split between premium integrated subsea projects and commoditized onshore maintenance contracts. Aker Solutions ASA anchors its position through in-house production of subsea production systems tied to Norwegian continental shelf developments. TechnipFMC plc leverages integrated engineering, procurement, and construction delivery models for complex floating platform assignments. Kvaerner ASA specializes in modular fabrication and heavy-lift installation, competing on execution certainty rather than scale.
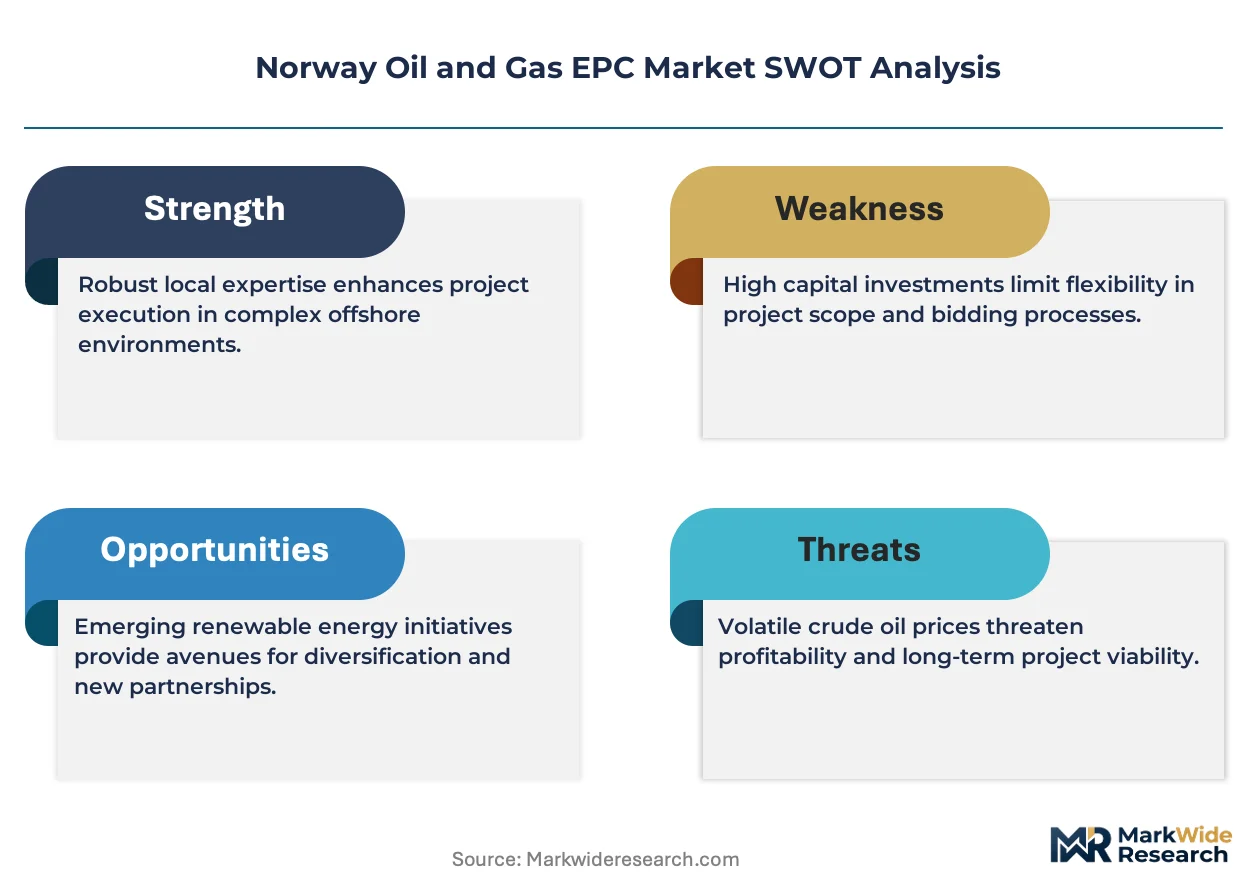
Norway Oil and Gas EPC encompasses the full-scope contracting of engineering design, materials procurement, and physical construction for hydrocarbon extraction, processing, and transport infrastructure, typically executed under lump-sum or cost-reimburse arrangements with performance guarantees on schedule and safety. Offshore technology segments command premium margins due to harsh-environment specifications for North Sea pressure and temperature extremes, while subsea scopes absorb disproportionate R&D investment as operators push toward deeper reservoirs. Floating platform applications represent the fastest-growing structural category as electrification and power-from-shore requirements reshape hull and topsides design. Upstream maintenance retains volume scale but faces margin compression from standardized procurement frameworks.
Petroleumstilsynet, the Norwegian petroleum safety authority, enforces stringent facility integrity and barrier management standards that elevate engineering documentation and construction quality requirements above North Sea norms. The EU Taxonomy and Norwegian CO2 storage licensing framework, administered by the Ministry of Petroleum and Energy, redirect operator capital toward carbon capture integration in new brownfield modifications. Stakeholders must track how electrification mandates and evolving seabed mining regulations reshape contractor capability requirements and long-term backlog composition.
Market Dynamics
The Norwegian continental shelf electrification mandate is redirecting capital from standalone offshore power generation toward shore-connected infrastructure, compressing project scopes for floating platform contractors while expanding subsea tieback engineering requirements.
Growth Catalysts
- CO2 storage licensing:The Ministry of Petroleum and Energy's carbon capture integration incentives redirect brownfield modification budgets toward EPC contractors with subsurface injection expertise.
- Johan Sverdrup cluster expansion:Subsea tieback projects around this North Sea hub concentrate demand for specialized production system integration.
- Floating offshore wind:Hybrid platform designs that combine hydrocarbon processing with power generation are expanding the addressable market for hull and topsides fabricators.
Market Restraints
- Steel alloy supply concentration:Premium duplex and super-duplex piping for high-pressure subsea systems sources from a limited Nordic-German supplier base, creating input cost volatility.
- Petroleumstilsynet barrier documentation:The Norwegian petroleum safety authority's facility integrity standards extend engineering timelines and inflate front-end loading costs beyond North Sea norms.
- Electrification capex displacement:Power-from-shore cable systems absorb capital that previously funded standalone platform power modules, reducing contract values for generator package specialists.
Strategic Opportunities
- Northern Barents Sea frontier:Underexplored reservoirs beyond the Snøhvit field offer first-mover positioning for contractors with Arctic-class vessel access and ice-load engineering capabilities.
- Seabed mineral harvesting convergence:Polymetallic nodule extraction technology transfer from offshore oil and gas subsea robotics creates adjacent service revenue streams.
- EU Taxonomy alignment:The sustainable finance classification framework rewards lower-carbon EPC scopes with preferential project finance terms, advantaging electrification-integrated bids.
Industry Challenges
- Subsea controls engineering scarcity:Specialists in high-pressure hydraulic and all-electric actuator systems command premium labor rates that compress project margins.
- Legacy platform integration complexity:Brownfield modification scopes require interface management with 1980s-era topsides designs lacking complete as-built documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Norway Oil and Gas EPC Market |
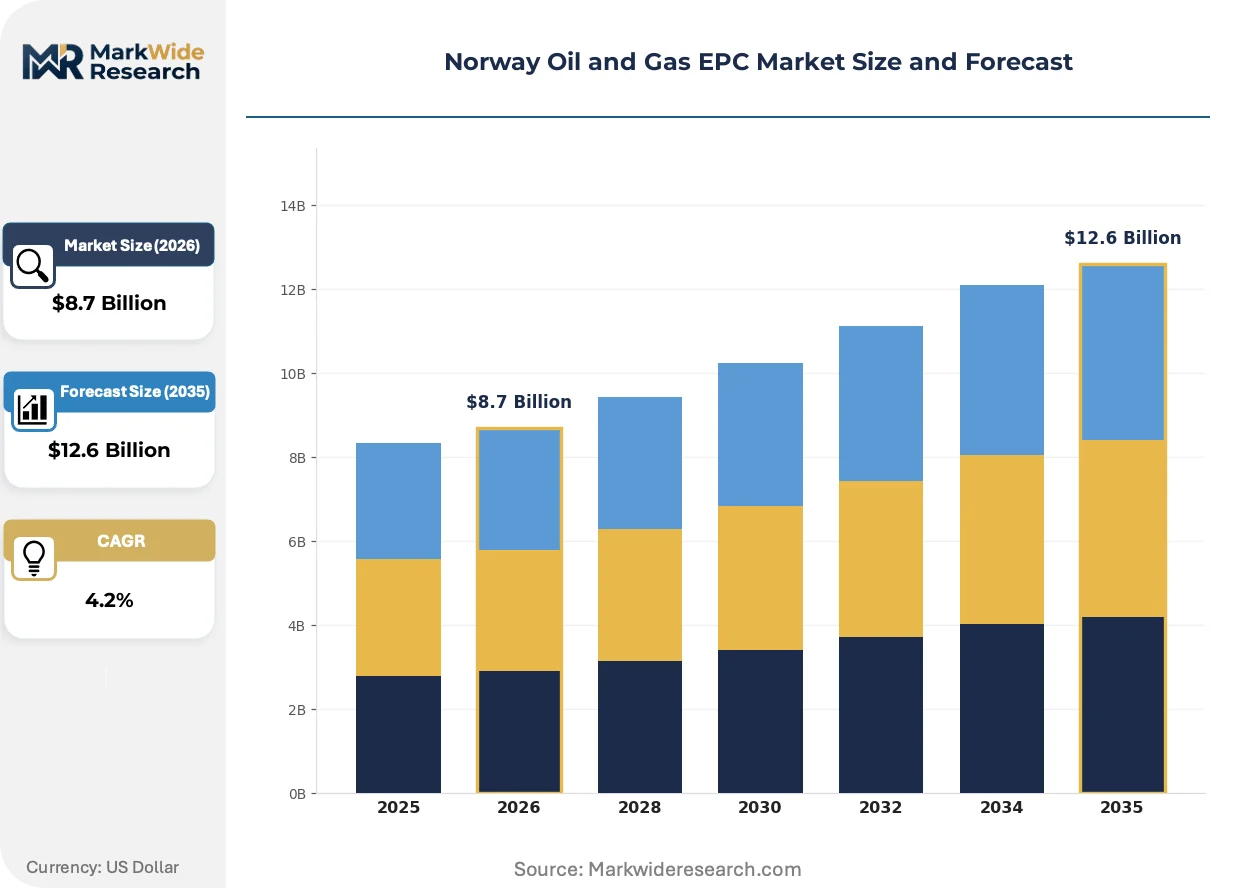
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $12.6 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Engineering, Procurement, Construction, Project Management Technology: Offshore, Subsea, Onshore, Floating Platforms End User: Exploration Companies, Production Firms, Service Providers, Government Agencies Application: Upstream, Midstream, Downstream, Maintenance |
| Companies Covered | John Wood Group PLC, Kvaerner ASA, Aker Solutions ASA, Petrofac Limited, Aibel AS, TechnipFMC plc, Worley Limited, KBR, Inc., Subsea 7 S.A., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Norway Oil and Gas EPC Market Evolving Landscape
Digital twin deployment and modular fabrication methods are compressing offshore construction schedules while Petroleumstilsynet's evolving safety standards reshape engineering documentation workflows across the Norwegian continental shelf.
All-electric subsea production systems are expanding into deeper reservoir developments where hydraulic umbilical distance limitations previously constrained field architecture. Equinor and Aker BP are specifying all-electric trees and chokes for 2027-2030 project phases. This technology is expanding into pressure-boosting and separation applications that were historically topsides-dependent, enabling subsea factory configurations that reduce floating platform size requirements.
EU Taxonomy technical screening criteria for climate change mitigation are redirecting operator capital allocation toward projects demonstrating substantial greenhouse gas reduction. The Norwegian Ministry of Petroleum and Energy's CO2 storage licensing framework accelerates carbon capture integration in brownfield engineering scopes. Floating platform categories with shore power connection receive preferential permitting timelines, compressing project approval cycles relative to standalone power generation designs.
Integrated project delivery contracts with lump-sum conversion points are displacing traditional cost-reimburse engineering-procurement sequences for subsea tieback developments. Norwegian operators including Equinor, Var Energi, and DNO are consolidating contractor accountability at the FEED-to-execute transition. This pattern concentrates most visibly in the Johan Sverdrup and Johan Castberg clusters where repeat project phasing rewards relationship-based supplier selection over competitive tendering for every phase.
Norway Oil and Gas EPC Market Segmentation
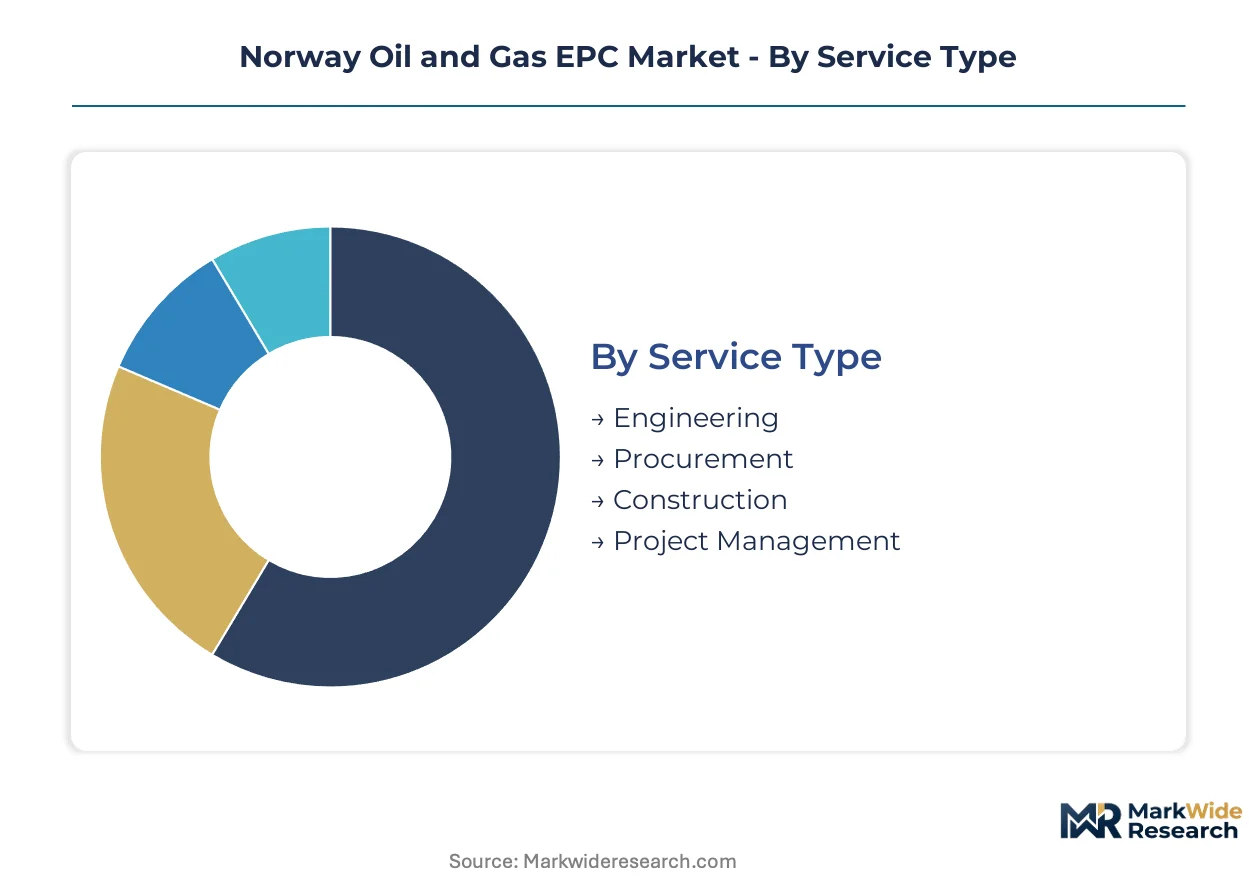
Segmentation reveals how Petroleumstilsynet certification requirements, electrification mandates, and CO2 storage incentives reshape contractor specialization across the Norwegian continental shelf. Distinct service, technology, end-user, and application categories concentrate investment flows toward subsea tiebacks and shore-powered floating platforms.
Service Type:
Petroleumstilsynet facility integrity standards impose tiered documentation burdens across service categories, with front-end engineering requiring barrier management certification that downstream construction scopes avoid.
- Engineering:Front-end design and detailed engineering for subsea production systems and floating platform hull specifications absorb disproportionate labor hours due to Petroleumstilsynet barrier documentation requirements. Demand concentrates around the Johan Sverdrup and Johan Castberg clusters where repeat project phasing rewards relationship-based contractor retention over competitive tendering.
- Procurement:Sourcing of duplex steel piping, subsea trees, and all-electric actuators faces supply concentration in Nordic-German supplier bases, creating input cost volatility that procurement specialists must hedge through long-term framework agreements. Norwegian electrification mandates redirect material specifications toward shore-power cable systems and away from standalone generator packages.
- Construction:Modular fabrication of platform topsides and subsea manifolds at Norwegian yard facilities competes on execution certainty under lump-sum arrangements with performance guarantees. The Ministry of Petroleum and Energy's CO2 storage licensing framework accelerates carbon capture integration in brownfield construction scopes.
- Project Management:Integrated delivery contracts with lump-sum conversion points displace traditional cost-reimburse sequences, concentrating accountability at the FEED-to-execute transition.
Engineering sits at the top of the volume ranking, with Project Management climbing the fastest.
Technology:
Cost tier differentiation separates premium harsh-environment systems from standardized onshore maintenance, with Arctic-class specifications commanding margin premiums over commoditized scopes.
- Offshore:Fixed platform and substructure installation for North Sea pressure and temperature extremes requires harsh-environment engineering that absorbs disproportionate R&D investment. Demand clusters around existing infrastructure hubs where brownfield modification scopes interface with 1980s-era topsides designs.
- Subsea:All-electric production systems including trees, chokes, and pressure-boosting equipment are expanding into deeper reservoirs beyond hydraulic umbilical distance limitations. Equinor and Aker BP specifications for 2027-2030 project phases concentrate contractor demand around the Johan Sverdrup cluster.
- Onshore:Processing facility construction and terminal expansion face margin compression from standardized procurement frameworks despite retaining volume scale.
- Floating Platforms:Hull and topsides fabrication for FPSOs and semi-submersibles represents the fastest-growing structural category as electrification and power-from-shore requirements reshape design specifications.
Subsea commands the premium margin tier, with Floating Platforms expanding most quickly.
End User:
Customer type determines contract structure complexity, with production firms driving integrated delivery models while government agencies impose regulatory compliance layers that extend timelines.
- Exploration Companies:Frontier appraisal drilling and early-stage field evaluation generate episodic demand for mobile offshore unit contracting.
- Production Firms:Equinor, Var Energi, and DNO consolidate contractor accountability through relationship-based selection for repeat cluster developments. These operators redirect capital toward lower-carbon EPC scopes aligned with EU Taxonomy technical screening criteria.
- Service Providers:Subcontracted specialist scopes in subsea controls engineering and heavy-lift installation face capability scarcity that compresses project margins.
- Government Agencies:Petroleumstilsynet enforcement of facility integrity standards and the Ministry of Petroleum and Energy's CO2 storage licensing create regulatory-driven demand segments.
Production Firms sit at the top of the volume ranking, with Government Agencies climbing the fastest.
Application:
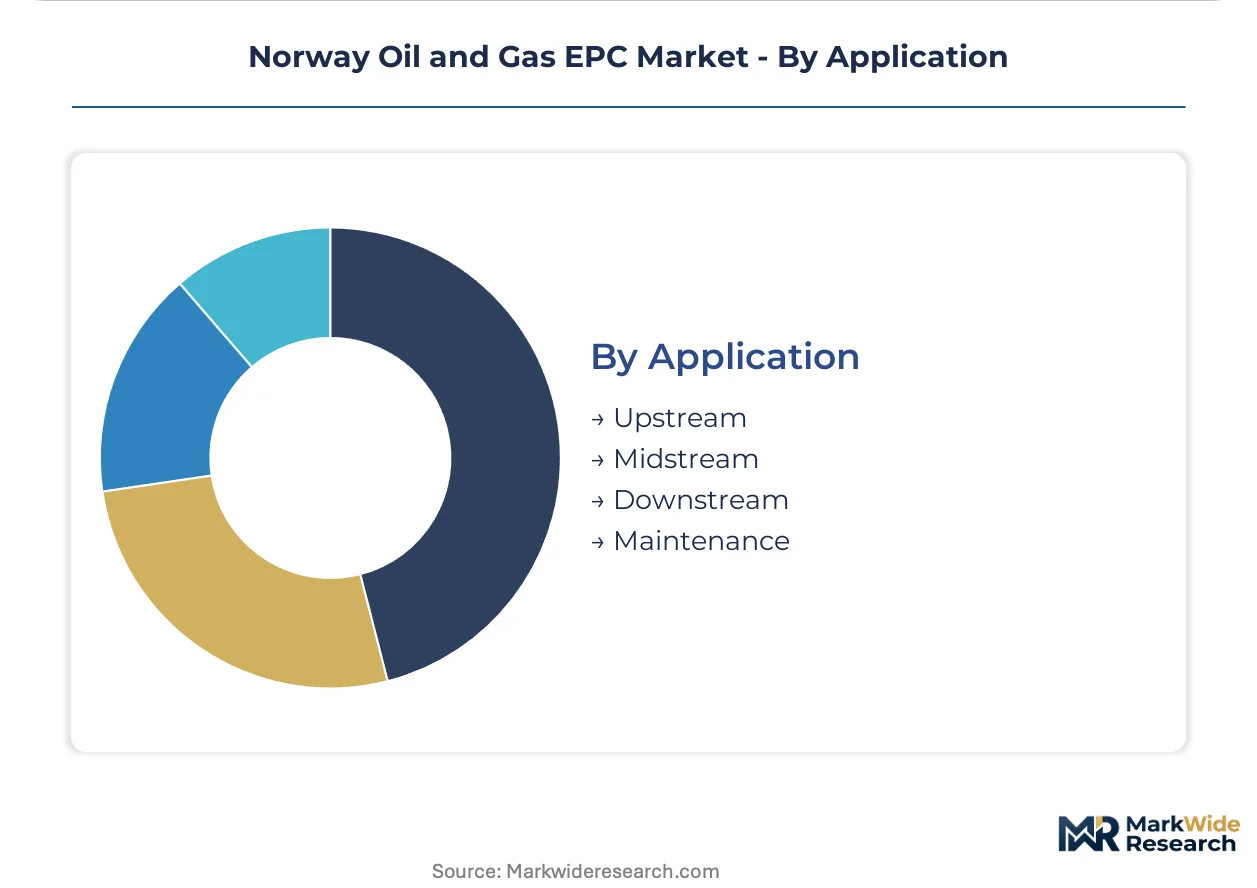
Maturity differentiation separates growth-phase upstream development from saturated maintenance volumes, with midstream infrastructure occupying a transitional position in investment cycles.
- Upstream:Greenfield development and brownfield modification for hydrocarbon extraction commands the largest share of EPC capital allocation. Electrification mandates and CO2 storage incentives redirect investment toward subsea tiebacks and shore-powered floating platforms.
- Midstream:Pipeline installation and processing facility construction face compressed scopes as power-from-shore cable systems absorb capital previously allocated to standalone platform infrastructure.
- Downstream:Refinery and terminal construction retains limited presence on the Norwegian continental shelf relative to extraction-focused investment.
- Maintenance:Legacy platform integrity management and barrier system upgrades generate recurring revenue but face margin pressure from standardized procurement frameworks.
Upstream sits at the top of the volume ranking, with Maintenance climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stavanger's subsea engineering workforce anchors Norwegian EPC capacity, while Bergen and Oslo maintain specialized fabrication and project management clusters. The North Sea basin concentrates contractor demand around electrification-linked developments.
North Sea Basin
Johan Sverdrup cluster expansions drive subsea tieback engineering demand for production system integration. Petroleumstilsynet facility integrity standards extend documentation timelines for barrier management certification. Stavanger-based engineering offices coordinate integrated delivery contracts with lump-sum conversion points for repeat project phasing.
Barents Sea Frontier
Snøhvit field extensions and underexplored reservoirs beyond generate Arctic-class vessel requirements for ice-load engineering. The Ministry of Petroleum and Energy's CO2 storage licensing framework accelerates carbon capture integration in frontier development scopes. Hammerfest serves as the logistical hub for subsea robotics deployment and seabed mineral harvesting technology transfer.
Oslo Metropolitan Area
Corporate headquarters and project management functions concentrate capital allocation decisions for floating platform electrification mandates. EU Taxonomy technical screening criteria redirect operator investment toward shore-power cable systems and away from standalone generator packages. Fornebu and Lysaker host engineering procurement centers managing Nordic-German duplex steel supply agreements.
Bergen Industrial Corridor
Modular fabrication yards compete on execution certainty for topsides and subsea manifold construction under lump-sum performance guarantees. Power-from-shore infrastructure absorbs capital previously allocated to platform power modules, compressing contract values for hull fabricators. Ågotnes and Hanøytangen facilities handle brownfield modification scopes interfacing with 1980s-era legacy designs.
Trondheim Technology Hub
All-electric subsea controls engineering specialists command premium labor rates for high-pressure actuator system development. Norwegian electrification mandates reshape R&D investment toward hydraulic umbilical replacement technologies. NTNU-affiliated research clusters feed talent pipelines into subsea factory configuration engineering for deeper reservoir applications.
Norway Oil and Gas EPC Market Competitive Landscape
Top-tier vendors anchor integrated subsea and floating platform delivery, while mid-tier fabricators compete on modular construction execution certainty. The Norwegian continental shelf rewards relationship-based contractor retention over competitive tendering for repeat cluster developments. Three archetypes dominate: full-scope integrators with in-house production systems, modular fabrication specialists with heavy-lift capabilities, and subsea technology licensors with controls engineering depth. Consolidation pressure operates through integrated project delivery contract structures and FEED-to-execute accountability transitions.
Among Norway-based engineering and construction groups, Aker Solutions ASA, Kvaerner ASA, and Aibel AS exemplify distinct competitive positions within the market structure. Aker Solutions ASA represents the integrated subsea production systems archetype with captive manufacturing capabilities. Kvaerner ASA occupies the modular fabrication and heavy-lift installation tier competing on schedule certainty rather than scale. Aibel AS anchors the brownfield modification and maintenance specialization vector where legacy platform integration complexity creates barrier-to-entry advantages. TechnipFMC plc and Subsea 7 S.A. sit within the international subsea technology and installation services tier, while John Wood Group PLC, Worley Limited, KBR, Inc., and Petrofac Limited represent global engineering houses competing for Norwegian operator procurement frameworks.
| Leading Market Players |
|---|
| John Wood Group PLC |
| Kvaerner ASA |
| Aker Solutions ASA |
| Petrofac Limited |
| Aibel AS |
| TechnipFMC plc |
| Worley Limited |
| KBR, Inc. |
| Subsea 7 S.A. |
| Others |
Value Network & Pricing Analysis
Duplex steel alloy spot indices in the Nordic-German corridor cascade through Norwegian EPC tiers, concentrating margin pressure on subsea system fabricators while rewarding contractors with captive forging capabilities and long-term offtake agreements with Statoil-qualified mills.
Pricing Analysis
The bundled-vs-unbundled service split separates integrated FEED-to-execute contracts from standalone engineering or construction scopes. Three-tier pricing structure across integrated subsea packages, modular fabrication blocks, and commoditized maintenance services reflects Petroleumstilsynet certification grade and execution certainty guarantees. Cost compression in standardized onshore maintenance runs through framework-agreement procurement, while premium subsea production systems retain pricing power due to all-electric actuator scarcity. Exploration companies exhibit highest price sensitivity on episodic drilling contracts; Equinor and Aker BP demonstrate lowest sensitivity on repeat-cluster developments where relationship-based retention overrides competitive tendering.
Supply Chain Analysis
Norwegian local-content rules under the Ministry of Petroleum and Energy's licensing framework reshape sourcing toward domestic yard capacity at Ågotnes, Hanøytangen, and Verdal facilities. Duplex and super-duplex piping draws from concentrated Nordic-German supplier bases, while subsea trees and all-electric chokes hinge on Norwegian and UK manufacturing clusters. Single-source vulnerability sits with super-duplex forging capacity at limited continental mills. Distribution runs through integrated project delivery contracts with lump-sum conversion points that compress traditional engineering-procurement sequences.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Norway Oil and Gas EPC market represents a late-cycle quality story where capital migrates toward premium integrated subsea scopes and Arctic-class floating platforms as electrification mandates disqualify commoditized standalone power generation.
For Market Incumbents: Deploy relationship-based FEED-to-execute retention as the primary lever. Anchor position through repeat project phasing at Johan Sverdrup and Johan Castberg clusters where competitive tendering displacement threatens margin erosion. Deepen backward integration into all-electric subsea controls engineering to offset specialist labor scarcity compressing project margins.
For New Entrants and Emerging Players: Digital-channel procurement platforms offer lower-friction entry into standardized maintenance and spare-parts logistics. Target brownfield modification scopes at 1980s-era platforms where legacy documentation gaps create execution barriers for incumbents. Position through seabed mineral harvesting technology transfer from offshore robotics capabilities as adjacent revenue streams.
For Investors and Strategic Acquirers: Asymmetric upside sits with modular fabrication specialists possessing heavy-lift installation assets and Petroleumstilsynet barrier certification. Long-term viability centers on contractors aligned with EU Taxonomy technical screening criteria for lower-carbon EPC scopes. Watch CO2 storage licensing velocity under the Ministry of Petroleum and Energy as the inflection signal for carbon capture integration demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Project Delivery Consolidation | Equinor and Var Energi concentrate contractor accountability at FEED-to-execute transitions, displacing cost-reimburse sequences. |
| All-Electric Subsea System Investment | Aker Solutions and TechnipFMC capture premium margins as Equinor specifies electric trees for 2027-2030 project phases. |
| Arctic-Class Vessel Capability Buildout | Contractors with ice-load engineering access Northern Barents Sea frontier developments beyond Snøhvit field extensions. |
| Carbon Capture Integration Licensing | Ministry of Petroleum and Energy CO2 storage framework redirects brownfield modification capital toward subsurface injection expertise. |
| Power-From-Shore Infrastructure Expansion | Shore-connected cable systems absorb capital previously allocated to standalone platform power modules, reshaping hull fabricator demand. |
Research Methodology
Direct dialogue with subsea project directors, floating platform procurement leads, Petroleumstilsynet compliance officers, and modular fabrication yard managers grounded qualitative assessment. Secondary validation drew from Ministry of Petroleum and Energy licensing records, EU Taxonomy technical screening documentation, Norwegian continental shelf project development databases, and SEC filings of listed EPC contractors. Bottom-up project pipeline enumeration and top-down operator capital allocation analysis triangulated market sizing.
Bottom-up volume modeling tracked individual field developments across the Johan Sverdrup cluster, Johan Castberg phases, and Northern Barents Sea frontier appraisals. Top-down reconciliation tested aggregate figures against operator disclosed spending frameworks and electrification-mandated capital reallocation patterns. Segmentation dimensions spanned service type, technology category, end-user archetype, and application maturity. CAGRs derived from project sanctioning timelines and repeat-phase contracting patterns rather than extrapolated trend lines. Industry-specific inputs included Petroleumstilsynet barrier documentation cost inflation and duplex steel supply concentration indices.
The model assumes a particular technology adoption path; alternative pathways for all-electric subsea production systems or floating offshore wind hybrid platforms would alter the outlook. Forecasts reflect documented assumptions regarding electrification mandate enforcement velocity and CO2 storage licensing uptake. Regulatory revision to EU Taxonomy criteria or seabed mining permitting frameworks could revise trajectory. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
Uzbekistan Oil and Gas Downstream Market
Offshore Oil and Gas
Oman Oil and Gas Downstream Market
Offshore Oil and Gas
Offshore Rental Equipment Market
Offshore Oil and Gas
Kuwait Oil and Gas Downstream Market
Offshore Oil and Gas
Asia-Pacific Floating Production Systems Market
Offshore Oil and Gas
Global Offshore Oil and Gas Seismic Equipment and Acquisitions Market
Offshore Oil and Gas
Offshore Remote Monitoring Solutions Market
Offshore Oil and Gas
Gabon Oil and Gas Downstream Market
Offshore Oil and Gas
Ecuador Oil and Gas Downstream Market
Offshore Oil and Gas
Brazil Oil and Gas Upstream Market
Offshore Oil and Gas
Asia-Pacific Floating Offshore Wind Power Market
Offshore Oil and Gas
Gulf of Mexico Oil and Gas Market
Offshore Oil and Gas
Offshore Oilfield Services Market
Offshore Oil and Gas
Kazakhstan Oil and Gas Upstream Market
Offshore Oil and Gas
Europe Offshore Energy Market
Offshore Oil and Gas
China Oil and Gas Upstream Market