
 Europe Subsea Pumps Market | 2026-2036
Europe Subsea Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Subsea Pumps Market Intelligence
Modular pump-train packaging is hardening as the dominant procurement configuration across North Sea brownfield projects. Aker Solutions ASA leverages its integrated subsea production systems to anchor long-term service contracts. Baker Hughes Company competes through permanent magnet motor technology leadership in deeper-water installations. Schlumberger Limited extends its position via reservoir-to-facility digital integration that bundles pump performance with real-time analytics.
Europe subsea pumps are pressure-rated centrifugal or positive-displacement units designed for seabed deployment at depths exceeding 300 meters, typically constructed from duplex stainless steel or nickel-aluminum bronze to resist chloride-induced corrosion in seawater and hydrocarbon service. Their primary function is to boost multiphase flow from subsea wells to surface facilities, overcoming hydrostatic head and friction losses across long tieback distances. Multiphase pumps now capture the largest margin pool as operators prioritize combined oil-gas-water handling over separate single-phase systems. Centrifugal configurations dominate installed base volume while reciprocating designs concentrate in high-pressure gas-lift and water injection applications where differential pressure requirements exceed 150 bar. Installation type segmentation shows fixed systems maturing in shallower Norwegian fields while floating and hybrid architectures gain share in UK pre-salt and west of Shetland developments.
The EU Green Deal and F-Gas Regulation constrain seal gas and cooling fluid selections, pushing manufacturers toward hermetically sealed motor designs and synthetic lubricant alternatives. ECHA REACH compliance adds material certification burdens for non-EU component suppliers, effectively filtering market access. Norway's Petroleum Safety Authority and the UK North Sea Transition Authority both mandate functional safety standards aligned with IEC 61508 for subsea control systems, directly influencing pump control module specifications. Stakeholders must monitor how EU methane emission performance standards propagate into equipment procurement criteria and whether UKCA marking divergence from CE requirements creates dual-certification costs for cross-border projects.
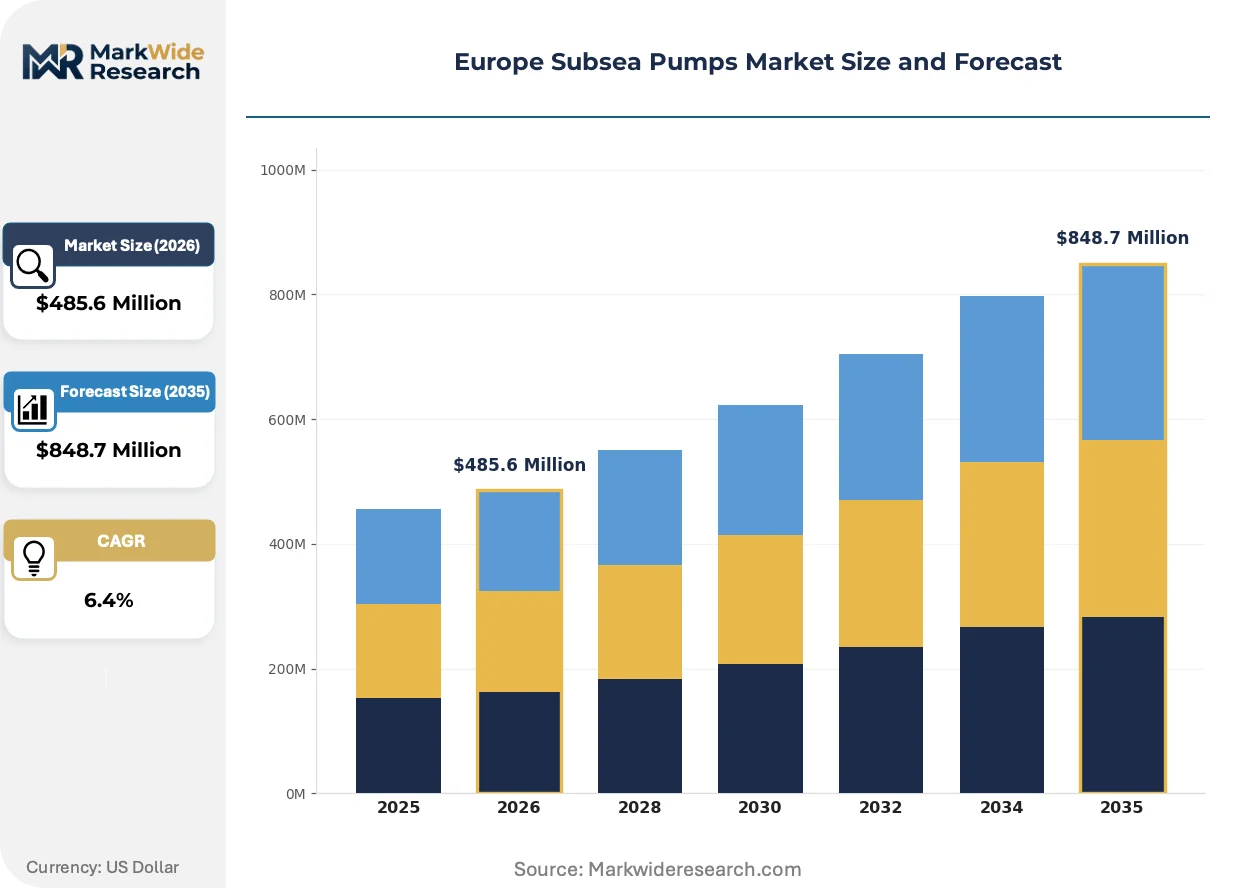
Market Dynamics
Modular pump-train procurement configurations are hardening as the dominant force across North Sea brownfield redevelopment, compressing vendor margins while locking in long-term service relationships through integrated subsea production systems.
Growth Catalysts
- Mature Basin Redevelopment:Norway, the United Kingdom, and Denmark are driving replacement cycles as aging North Sea infrastructure requires multiphase boosting upgrades to maintain production economics.
- EU Green Deal Efficiency Mandates:Tightening offshore methane regulations and equipment efficiency standards are forcing operators to retire legacy single-phase systems in favor of integrated multiphase pumps.
- Permanent Magnet Motor Technology:Deeper-water installations west of Shetland and in UK pre-salt developments are adopting high-efficiency motor designs that reduce power consumption and cooling requirements.
Market Restraints
- Duplex Stainless Steel Supply Concentration:Chloride-resistant alloys for pump housings and impellers face supply bottlenecks from Nordic specialty steel producers, creating input cost volatility.
- ECHA REACH Certification Burden:Material certification requirements for non-EU component suppliers effectively filter market access, lengthening procurement timelines for Asian motor and seal manufacturers.
- Hydraulic Reciprocating Pump Substitution:High-pressure gas-lift applications above 150 bar differential pressure remain dominated by reciprocating designs, limiting centrifugal pump penetration in water injection segments.
Strategic Opportunities
- West of Shetland Developments:Floating and hybrid subsea architectures in this UK frontier basin are creating demand for lighter, modular pump systems with reduced seabed footprint.
- Reservoir-to-Facility Digital Integration:Real-time pump performance analytics bundled with subsea control systems are opening new revenue streams through predictive maintenance contracts.
- Hermetically Sealed Motor Designs:F-Gas Regulation constraints on seal gas and cooling fluids are accelerating R&D investment in synthetic lubricant alternatives and sealed motor configurations.
Industry Challenges
- IEC 61508 Functional Safety Certification:Pump control module specifications must align with Norway's Petroleum Safety Authority and UK North Sea Transition Authority mandates, creating dual-compliance complexity for cross-border projects.
- Subsea Installation Skill Shortage:Specialized vessel availability and experienced offshore commissioning engineers are constraining deployment velocity for deeper-water installations.
- UKCA-CE Marking Divergence:Post-Brexit certification requirements are forcing manufacturers to maintain parallel conformity assessment processes for equipment serving both UK and EU markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Subsea Pumps Market |
| Market Size in 2026 | $485.6 Million |
| Market Size in 2035 | $848.7 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Multiphase Pumps, Centrifugal Pumps, Reciprocating Pumps, Screw Pumps Application: Oil Recovery, Gas Production, Water Injection, Riser Systems End User: Oil Companies, Utility Providers, Engineering Firms, Service Contractors Installation Type: Fixed Systems, Floating Systems, Hybrid Systems, Modular Systems |
| Companies Covered | Aker Solutions ASA, Baker Hughes Company, TechnipFMC PLC, Halliburton Company, Schlumberger Limited, Sulzer Ltd., Flowserve Corporation, National Oilwell Varco, Framo AS, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Subsea Pumps Market Strategic Shifts & Innovations
Permanent magnet motor technology and hermetically sealed designs are actively compressing the competitive landscape, while digital integration and modular packaging reconfigure how operators procure and deploy subsea boosting systems.
Synthetic lubricant formulations for hermetically sealed motor compartments are expanding into deeper-water installations where traditional oil-filled designs face F-Gas Regulation constraints. Norwegian operators in the Barents Sea and UK developers west of Shetland are adopting these configurations at accelerated pace to preempt regulatory non-compliance. This technology is expanding into the high-margin multiphase pump segment by eliminating seal gas systems and reducing topside support infrastructure.
The EU F-Gas Regulation and offshore methane emission performance standards are tightening permissible cooling fluid and seal gas chemistries across North Sea installations. Industrial consequence includes accelerated obsolescence of conventional open-loop motor cooling designs and forced migration to sealed architectures. UK and Norwegian subsea control system specifications are most affected, with procurement criteria now weighting hermetic designs above legacy configurations regardless of upfront capital cost.
Performance-based service contracting is displacing traditional equipment purchase models among North Sea operators seeking to transfer operational risk to vendors. Integrated subsea production system providers are capturing long-term revenue through availability guarantees and predictive maintenance subscriptions. Norway's mature brownfield operators and UK independent producers are the most visible adopters, with contract structures now bundling pump hardware, installation, and digital monitoring into single-source agreements.
Europe Subsea Pumps Market Segmentation
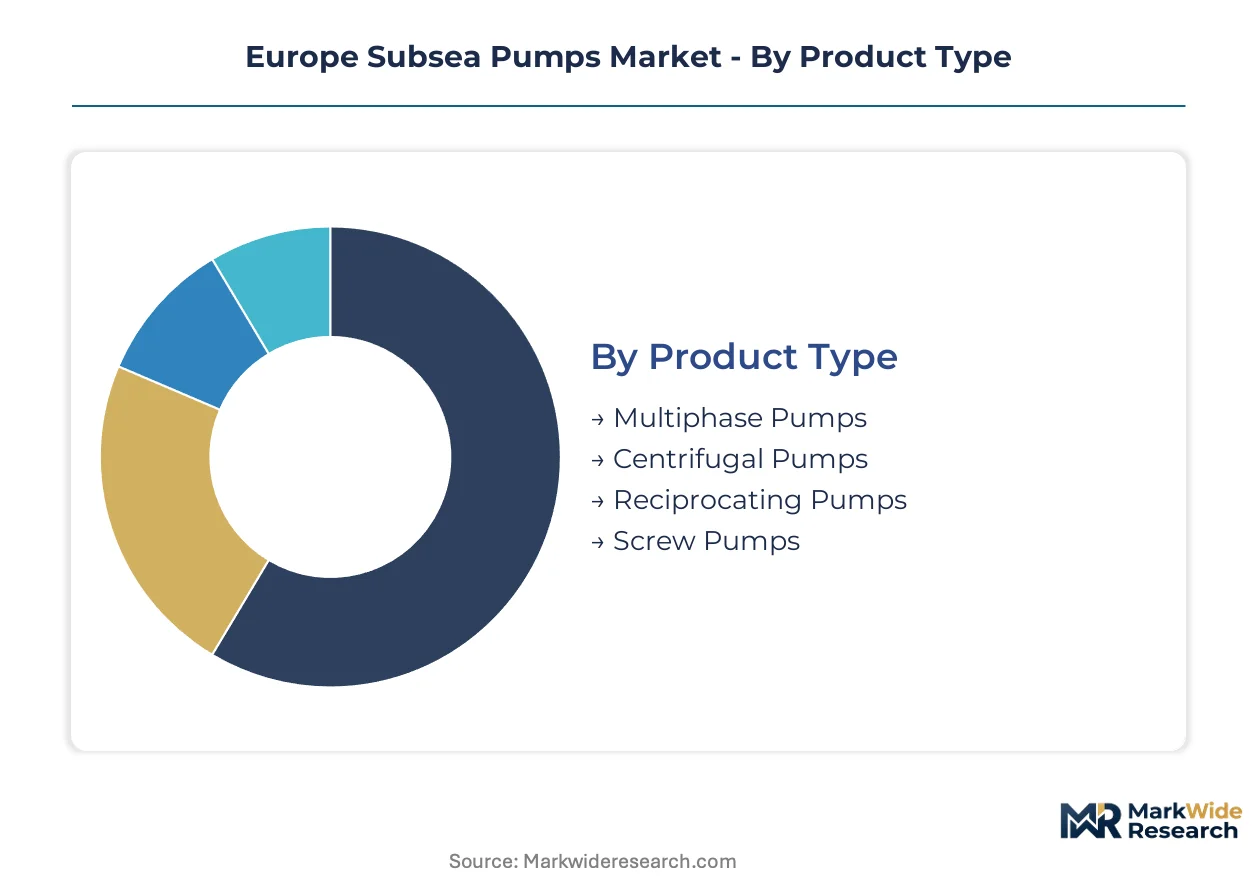
Segmentation in the Europe Subsea Pumps Market reveals how procurement priorities diverge across North Sea operators. Brownfield redevelopment in Norway and the United Kingdom favors modular configurations, while frontier developments west of Shetland drive demand for lighter, deployable architectures.
Product Type:
Centrifugal designs dominate installed base volume, yet margin concentration tilts toward multiphase systems that eliminate separate oil-gas-water handling infrastructure.
- Multiphase Pumps:Combined oil-gas-water handling eliminates topside separation equipment and reduces footprint on congested North Sea platforms. Norwegian operators in mature Barents Sea fields and UK brownfield independents prioritize these systems to extend field life without major facility upgrades. EU methane regulations accelerate displacement of legacy single-phase trains.
- Centrifugal Pumps:Axial-flow and mixed-flow configurations handle moderate differential pressures below 150 bar across high-volume water injection and crude export duties. Danish Central Graben developments and shallow Norwegian shelf fields maintain substantial installed base, though replacement cycles now favor multiphase alternatives where reservoir conditions permit.
- Reciprocating Pumps:Positive-displacement action delivers precise flow control for high-pressure gas-lift applications exceeding 150 bar differential.
- Screw Pumps:Progressive cavity designs handle viscous crudes and solids-laden production streams in heavy oil developments.
Today's leader: Centrifugal Pumps. Tomorrow's challenger: Multiphase Pumps.
Application:
Primary recovery applications command procurement volume, yet secondary and tertiary methods generate premium pricing through integrated boosting complexity.
- Oil Recovery:Primary and enhanced oil recovery operations deploy subsea boosting to maintain flow rates as reservoir pressure declines. UK pre-salt developments west of Shetland and Norwegian Barents Sea greenfields specify high-reliability systems with 25-year design life to justify deepwater capital commitment.
- Gas Production:Condensate-rich gas fields require multiphase handling as reservoir pressure drops below dewpoint. The UK North Sea Transition Authority's flaring reduction mandates push operators toward subsea compression and boosting rather than surface venting.
- Water Injection:Pressure maintenance and sweep efficiency programs depend on high-pressure injection pumps.
- Riser Systems:Topside-riser base boosting overcomes hydrostatic head in deepwater tieback configurations.
Oil Recovery captures current procurement spend. Gas Production is expanding most quickly under methane emission constraints.
End User:
Integrated oil companies anchor capital deployment, though independent producers and service contractors reshape contracting models through performance-based agreements.
- Oil Companies:Majors and national oil companies in Norway, the United Kingdom, and Denmark specify integrated subsea production systems combining pumps with controls and umbilicals. Equinor and Shell prioritize long-term service contracts with availability guarantees over discrete equipment purchases.
- Engineering Firms:EPC contractors front-end engineering and design studies increasingly bundle pump selection with subsea architecture decisions. TechnipFMC and Subsea 7 influence specifications before final investment determination, locking in preferred vendor relationships early in project development.
- Utility Providers:Offshore power and water infrastructure operators represent emerging demand for subsea processing equipment.
- Service Contractors:Independent operators and private equity-backed producers lease boosting capacity through rental and service agreements.
Oil Companies retain specification authority. Service Contractors are gaining procurement influence through risk-transfer contracting.
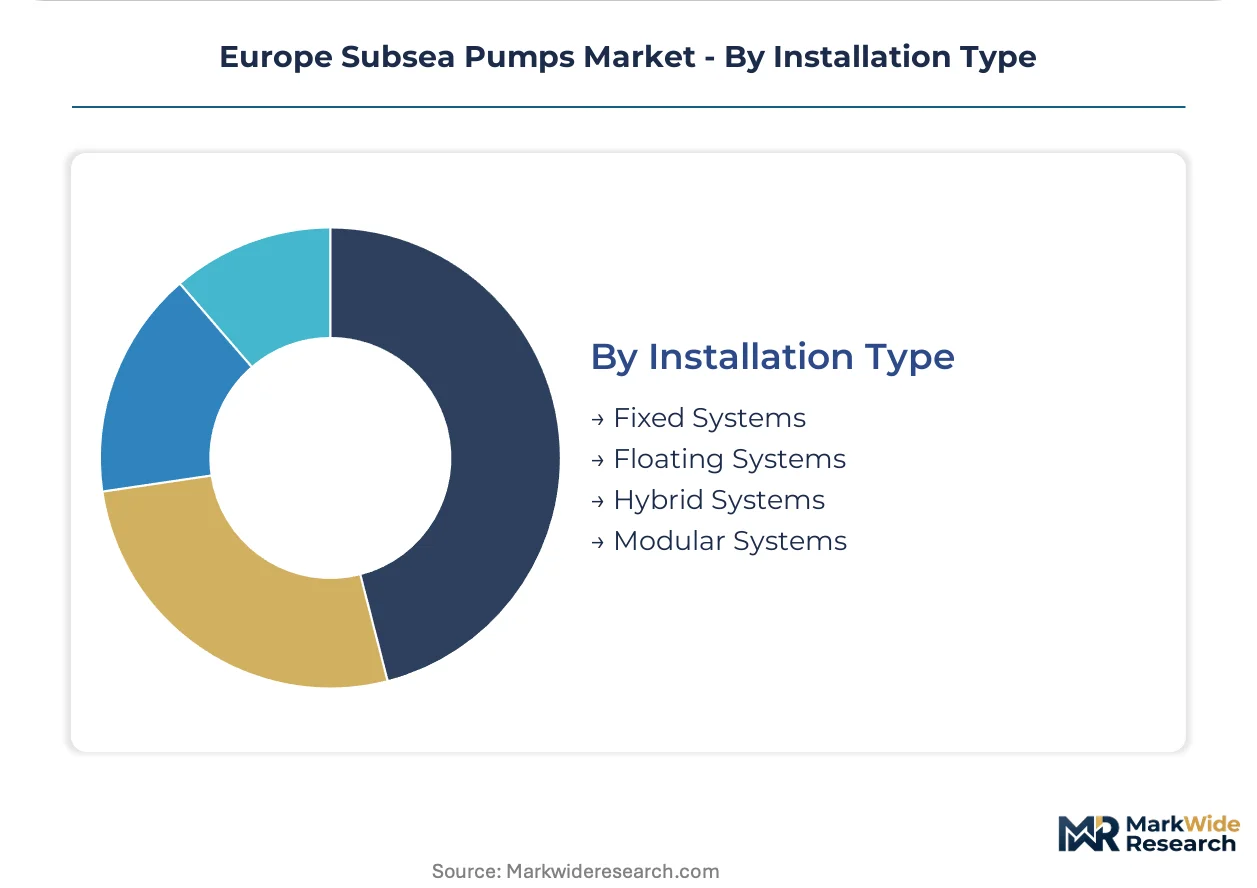
Installation Type:
Fixed platform heritage constrains brownfield retrofit options, while floating and hybrid architectures unlock frontier basin development.
- Fixed Systems:Platform-tethered pump configurations dominate mature Norwegian and Danish fields where jacket structures provide stable mounting points. Replacement cycles now favor modular retrofits that minimize platform shutdown duration and maintain production through tie-in sequencing.
- Floating Systems:Turret-moored FPSO and semi-submersible host vessels require seabed pump systems with reduced footprint and lighter installation loads. UK west of Shetland pre-salt developments and Barents Sea harsh-environment fields specify these configurations to avoid fixed infrastructure commitment.
- Hybrid Systems:Combinations of fixed and floating elements optimize brownfield expansion and greenfield phased development.
- Modular Systems:Standardized pump-train packages enable rapid deployment and vendor-managed inventory across multiple field developments.
Fixed Systems anchor current installed base. Floating Systems show the steepest expansion trajectory in frontier basins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
North Sea oil extraction scaled through Norwegian and UK continental shelf developments during the 1970s, establishing the subsea infrastructure lineage that now drives replacement demand across mature European basins.
Norway
Barents Sea brownfield redevelopment and Johan Sverdrup-phase expansions sustain multiphase pump procurement. The Petroleum Safety Authority mandates IEC 61508-aligned functional safety standards for subsea control systems. Stavanger anchors vendor engineering centers where Aker Solutions and Framo AS coordinate integrated production system deliveries.
United Kingdom
West of Shetland pre-salt developments and central North Sea tieback projects require lighter, modular pump architectures. The North Sea Transition Authority's flaring reduction mandates accelerate subsea compression adoption over surface venting. Aberdeen hosts the primary cluster of subsea engineering contractors influencing front-end specifications.
Denmark
Central Graben field life extension programs drive centrifugal pump replacement cycles in shallow-water installations. Danish Energy Agency efficiency requirements align with EU Green Deal methane performance standards. Esbjerg maintains fabrication yards serving cross-border North Sea projects with standardized modular packages.
Netherlands
Decommissioning-deferral strategies on the Dutch continental shelf prioritize subsea boosting over platform upgrades. REACH compliance burdens filter non-EU component supplier access to North Sea procurement chains. Rotterdam's offshore equipment logistics hub coordinates material certification for duplex stainless steel supply.
France
TechnipFMC's engineering headquarters in Paris-La Défense shapes subsea architecture decisions across European frontier developments. ANSM and CNIL oversight of industrial equipment standards influences control system cybersecurity specifications. Dunkirk and Le Havre ports support installation vessel mobilization for deeper-water deployments.
Europe Subsea Pumps Market Key Industry Players
Premium-margin players sit above commodity-margin players across integrated system bundling capability, with full-suite providers capturing long-term service contracts while component specialists defend position through technology differentiation in motors and seals. The vendor base organizes around three archetypes: integrated subsea production system houses, permanent magnet motor technology specialists, and pump component fabricators with regional certification advantages. Consolidation pressure runs through performance-based contracting models that transfer operational risk to vendors. Geographic expansion through Norwegian-UK cross-border project participation and backward integration into specialty steel supply chains constitute the dominant competitive moves.
Among integrated system providers, Aker Solutions ASA and TechnipFMC PLC occupy positions anchoring long-term service relationships through modular subsea production bundling. Baker Hughes Company exemplifies the technology-tier specialist archetype, with its permanent magnet motor capabilities supporting deeper-water positioning. Schlumberger Limited sits within the digital integration tier, representing reservoir-to-facility analytics bundling that reconfigures traditional equipment procurement models.
| Leading Market Players |
|---|
| Aker Solutions ASA |
| Baker Hughes Company |
| TechnipFMC PLC |
| Halliburton Company |
| Schlumberger Limited |
| Sulzer Ltd. |
| Flowserve Corporation |
| National Oilwell Varco |
| Framo AS |
| Others |
Cost & Logistics Intelligence
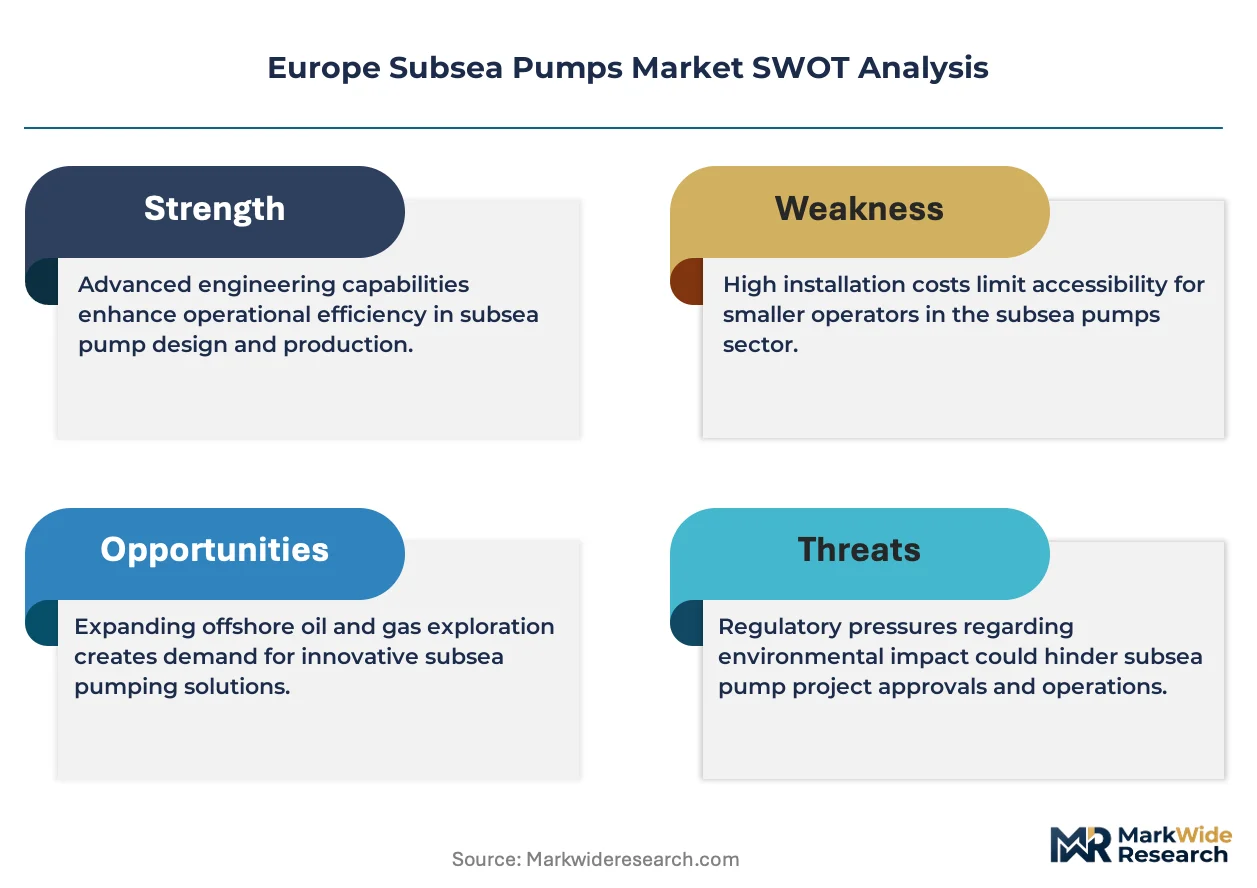
Captive integration into duplex stainless steel supply chains anchors both procurement security and pricing power for Nordic pump manufacturers serving North Sea brownfield redevelopment. Norwegian and UK operators absorb premium pricing for hermetically sealed motor configurations as ECHA REACH compliance filters non-EU component access, compressing vendor margins while locking in long-term service relationships through integrated subsea production systems.
Pricing Analysis
Performance-based service contracting dominates procurement across Norwegian and UK continental shelf developments, with availability guarantees and predictive maintenance subscriptions displacing discrete equipment purchases. Price differentiation hinges on IEC 61508 functional safety certification tier and permanent magnet motor efficiency grade, with deeper-water installations west of Shetland commanding substantial premiums over shallow-water Danish configurations. Cost compression in standard centrifugal pump tiers is intensifying as modular packaging standardization forces component-level competition. UK independent producers exhibit highest price sensitivity, while Equinor and Shell prioritize total lifecycle cost over upfront capital outlay.
Supply Chain Analysis
Freight costs for specialized installation vessels constrain deployment velocity and inflate project economics for frontier basin developments west of Shetland. Duplex stainless steel supply concentrates in Sweden, Finland, and Germany, with chloride-resistant alloy production feeding pump housing and impeller fabrication. Raw material dependencies center on nickel-aluminum bronze castings, permanent magnet motor assemblies, and synthetic lubricant formulations. Single-source vulnerability runs through Nordic specialty steel producers, creating input cost volatility when capacity tightens. Distribution runs through Stavanger and Aberdeen engineering centers coordinating with Esbjerg fabrication yards for standardized modular packages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Subsea Pumps Market functions as a regulatory compounder where EU Green Deal methane performance standards and F-Gas Regulation constraints continuously reset equipment replacement cycles across mature North Sea basins.
For Market Incumbents: Deepen backward integration into duplex stainless steel supply chains to insulate margin position against Nordic specialty steel bottlenecks. Anchor long-term service contracts through reservoir-to-facility digital integration that bundles real-time pump analytics with predictive maintenance subscriptions, preempting Schlumberger's software-led encroachment on hardware procurement decisions. For New Entrants and Emerging Players: Private equity-backed UK independents represent the most penetrable buyer archetype, with their risk-transfer appetite for leased boosting capacity outpacing integrated majors' preference for single-source integrated systems. Target modular retrofit opportunities in Danish Central Graben shallow-water installations where standardized packages minimize certification burden. Lead with hermetically sealed motor technology as a regulatory compliance wedge against legacy open-loop designs. For Investors and Strategic Acquirers: Roll-up economics work for permanent magnet motor technology specialists because deeper-water frontier developments west of Shetland and in the Barents Sea concentrate procurement authority among operators demanding efficiency-optimized configurations. Five-to-ten year viability hinges on R&D amortization across sufficient installed base. Watch for UKCA-CE marking divergence forcing dual-certification cost structures that favor acquirees with existing parallel conformity assessment capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Steel Supply | Nordic producers' captive alloy supply insulates margin volatility from REACH-constrained component sourcing. |
| Hermetic Motor Technology Licensing | F-Gas Regulation compliance accelerates displacement of conventional oil-filled designs across Norwegian Barents Sea fields. |
| Performance-Based Service Contracting | Availability guarantees transfer operational risk from UK independents to vendors, locking in recurring revenue streams. |
| Modular Packaging Standardization | Reduced seabed footprint configurations unlock UK west of Shetland pre-salt developments with lighter installation loads. |
| Reservoir-to-Facility Digital Integration | Real-time analytics bundling preempts pure-hardware competition through predictive maintenance subscription attach rates. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with subsea project engineers, procurement leads at Norwegian and UK operators, EPC contractors, and aftermarket service heads with secondary validation against EU Green Deal implementation documents, Petroleum Safety Authority technical standards, and North Sea Transition Authority flaring reduction mandates. Customs data for duplex stainless steel trade flows, SEC filings from listed oilfield service providers, and project development databases for west of Shetland and Barents Sea greenfield commitments anchored bottom-up and top-down triangulation.
Historical reference periods spanning mature basin redevelopment cycles anchored the projection horizon, with analytical frameworks modeling product type segmentation across multiphase, centrifugal, and reciprocating configurations alongside application splits between oil recovery, gas production, and water injection duties. CAGRs were derived from installation type trajectories contrasting fixed platform heritage against floating system expansion in frontier basins, incorporating permanent magnet motor adoption curves and hermetically sealed design penetration rates as industry-specific forecast inputs.
Underlying measurement precision varies by segment; multiphase pump forecasts carry tighter precision than reciprocating pump projections due to more visible brownfield replacement pipelines. Forecasts reflect assumptions about EU methane regulation enforcement consistency and UKCA marking divergence trajectory. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Rental Industrial Pump Market
Pumps and Control Devices
Self-Priming Centrifugal Pump Market
Pumps and Control Devices
Vane Pump Market
Pumps and Control Devices
Pressure Washer Pump Oil Market
Pumps and Control Devices
Solar Pump Inverter Market
Pumps and Control Devices
Heating Tape Market
Pumps and Control Devices
Europe, Middle-East and Africa Diaphragm Pump Market
Pumps and Control Devices
Industrial Pumps Market
Pumps and Control Devices
Air-Operated Double Diaphragm (AODD) Pumps Market
Pumps and Control Devices
Middle East and Africa Centrifugal Pumps Market
Pumps and Control Devices
India Industrial Pump Market
Pumps and Control Devices
US Industrial Pump Market
Pumps and Control Devices
Ultra High Pressure Water Pump Market
Pumps and Control Devices
Radial Piston Pumps Market
Pumps and Control Devices
Spin-On Hydraulic Filter Market
Pumps and Control Devices
Melt & Gear Pump Market