
 Pipeline and Process Services Market | 2026-2036
Pipeline and Process Services Market Size, Share, and Industry Trends Forecast 2026-2036
Pipeline and Process Services Market Analysis
Buyer concentration among supermajor operators and national oil companies is expanding, with integrated energy firms bundling long-term service contracts across inspection, maintenance, and integrity management scopes. Schlumberger Limited leverages its digital subsurface platform to integrate pipeline diagnostics with reservoir analytics, creating stickier operator relationships. Baker Hughes Company competes through specialized robotic inspection systems designed for unpiggable pipeline geometries. Halliburton Company anchors its position in North American onshore markets through embedded maintenance crews at major midstream hubs.
Pipeline and process services encompass the technical inspection, cleaning, repair, and integrity management of hydrocarbon and industrial fluid conveyance systems, typically operating across diameters from two to fifty-six inches and pressure ratings exceeding 1,440 psi to ensure leak-free transport over multi-decade design lives. The primary commercial purpose centers on maximizing throughput efficiency while preventing catastrophic failures that trigger regulatory penalties, environmental liability, and supply disruption. Inspection services dominate value capture due to mandatory inline assessment cycles, while robotic inspection represents the fastest-expanding technology segment as operators confront complex subsea and urban pipeline networks where conventional smart pigs cannot navigate. Maintenance commands the largest recurring revenue pool across the service type dimension, though repair margins spike during emergency response mobilizations.
PHMSA integrity management rules and the EPA's methane emissions standards shape United States demand by mandating continuous leak detection and prompt remediation timelines. The United Kingdom's Pipeline Safety Regulations and EU Industrial Emissions Directive impose comparable compliance burdens across European offshore and cross-border infrastructure. Stakeholders must monitor how regulatory divergence between jurisdictions affects service standardization and technician certification portability as project footprints span multiple continental shelf regimes.
Market Dynamics
PHMSA's integrity management mandates and the Pipeline Safety Regulations are compressing inspection cycles across North American and North Sea infrastructure, forcing operators to outsource specialized diagnostics rather than build in-house capabilities. This regulatory compression is consolidating service demand around vendors with multi-asset platform coverage and real-time data integration.
Growth Catalysts
- PHMSA Integrity Management Rules:Mandatory inline inspection cycles for high-consequence areas are expanding the addressable market for smart pigging and corrosion monitoring services across United States interstate pipelines.
- Unpiggable Pipeline Robotics:Complex subsea networks and urban distribution systems are driving adoption of robotic crawlers and electromagnetic inspection tools where conventional pigging proves impossible.
- Permian Basin Infrastructure Buildout:Midstream capacity expansion in West Texas and New Mexico is creating sustained demand for pre-commissioning cleaning, hydrostatic testing, and ongoing integrity management.
Market Restraints
- Specialized Labor Scarcity:Certified inline inspection analysts and robotic technicians command premium wages, compressing margins for service providers unable to automate diagnostic interpretation.
- Equipment Concentration Risk:Smart pig manufacturing concentrates among German and United States suppliers, exposing service contractors to extended lead times during demand surges.
- Methane Detection Substitution:Satellite-based emissions monitoring and continuous sensor networks are displacing some scheduled physical inspection visits for leak detection scopes.
Strategic Opportunities
- Offshore Brazil Pre-Salt Expansion:Petrobras and international partners are deploying subsea tieback architectures requiring specialized riser inspection and flexible flowline maintenance capabilities.
- EU Industrial Emissions Directive:Cross-border pipeline operators must demonstrate continuous emissions compliance, creating demand for integrated monitoring platforms that combine leak detection with process optimization.
- Digital Twin Convergence:Integration of inline inspection data with predictive analytics platforms is enabling condition-based maintenance contracts that replace fixed-schedule service agreements.
Industry Challenges
- API 1163 Certification Bottlenecks:Technician qualification timelines for in-line inspection system operators are extending project mobilization schedules and limiting fleet utilization rates.
- Legacy SCADA Integration:Real-time diagnostic platforms must interface with decades-old control systems, requiring custom protocol gateways that delay deployment and inflate engineering costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pipeline and Process Services Market |
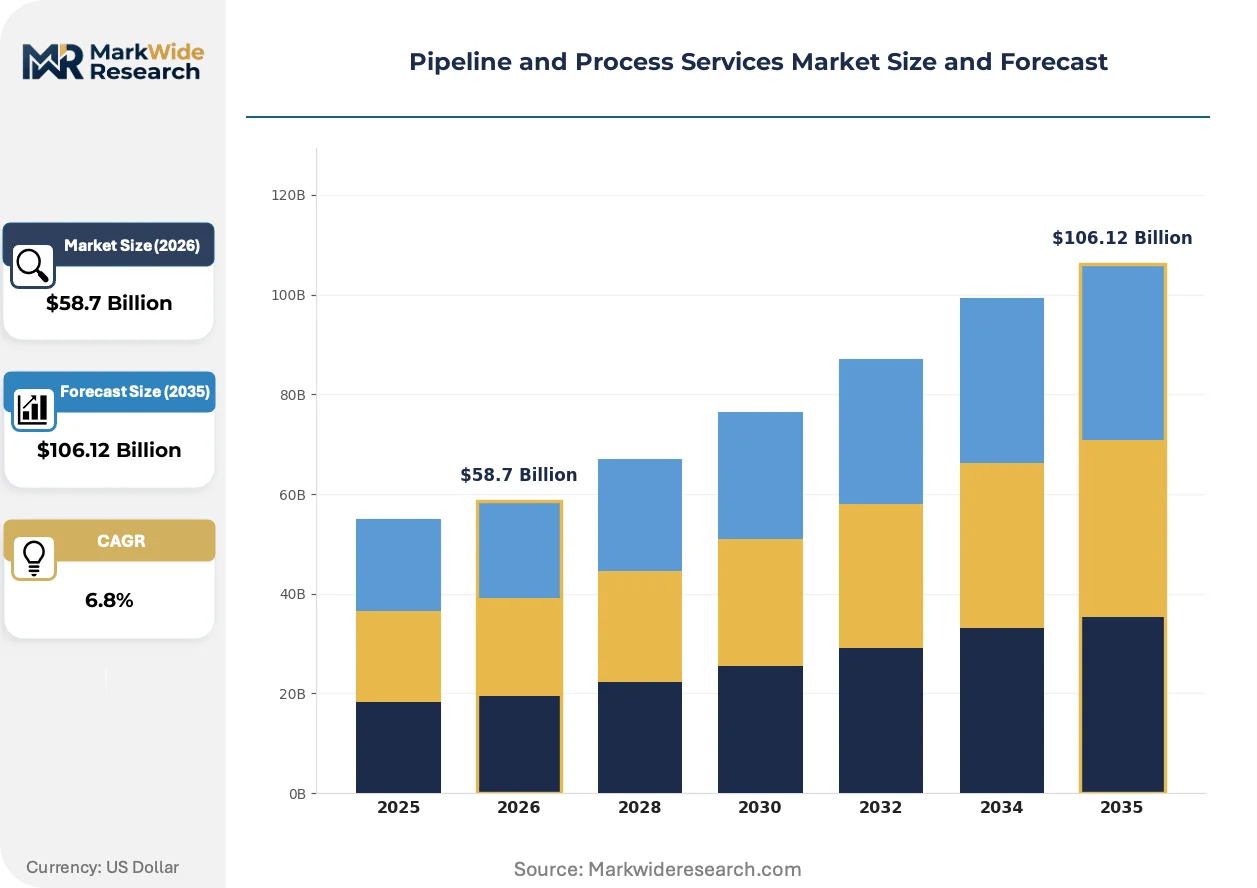
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $106.12 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Inspection, Cleaning, Maintenance, Repair Technology: Hydrostatic Testing, Ultrasonic Testing, Smart Pigs, Robotic Inspection End User: Oil & Gas, Water Supply, Chemicals, Power Generation Application: Pipeline Construction, Pipeline Maintenance, Process Optimization, Network Management |
| Companies Covered | TechnipFMC plc, ROSEN Group, Schlumberger Limited, Saipem S.p.A., T.D. Williamson Inc., Halliburton Company, Wood PLC, McDermott International, Inc., Baker Hughes Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pipeline and Process Services Market Emerging Trajectories
Robotic inspection systems and machine-learning diagnostic platforms are compressing the traditional separation between data acquisition and integrity decision-making. Operators now demand predictive failure models rather than static anomaly reports.
Electromagnetic acoustic transducer technology is consolidating ultrasonic inspection and magnetic flux leakage into single-pass platforms for crack and metal loss detection. Offshore operators in the Gulf of Mexico and North Sea are adopting these hybrid tools to reduce vessel time and subsea intervention costs. The technology is consolidating multiple inspection vendors into single-source integrity partnerships.
The EPA's methane emissions standards are mandating continuous monitoring with specified detection sensitivity thresholds and repair timelines. Midstream operators must deploy optical gas imaging or sensor networks meeting quarterly reporting requirements. Gathering and processing segments face the steepest compliance costs, driving consolidation toward integrated service providers with emissions verification accreditation.
Long-term service contracting is displacing spot procurement for integrity management scopes. Supermajor operators are bundling inspection, maintenance, and repair across multi-year frameworks with outcome-based performance metrics. This shift concentrates procurement authority at corporate technical centers in Houston and London, marginalizing regional maintenance managers who previously awarded discrete work packages.
Pipeline and Process Services Market Segmentation
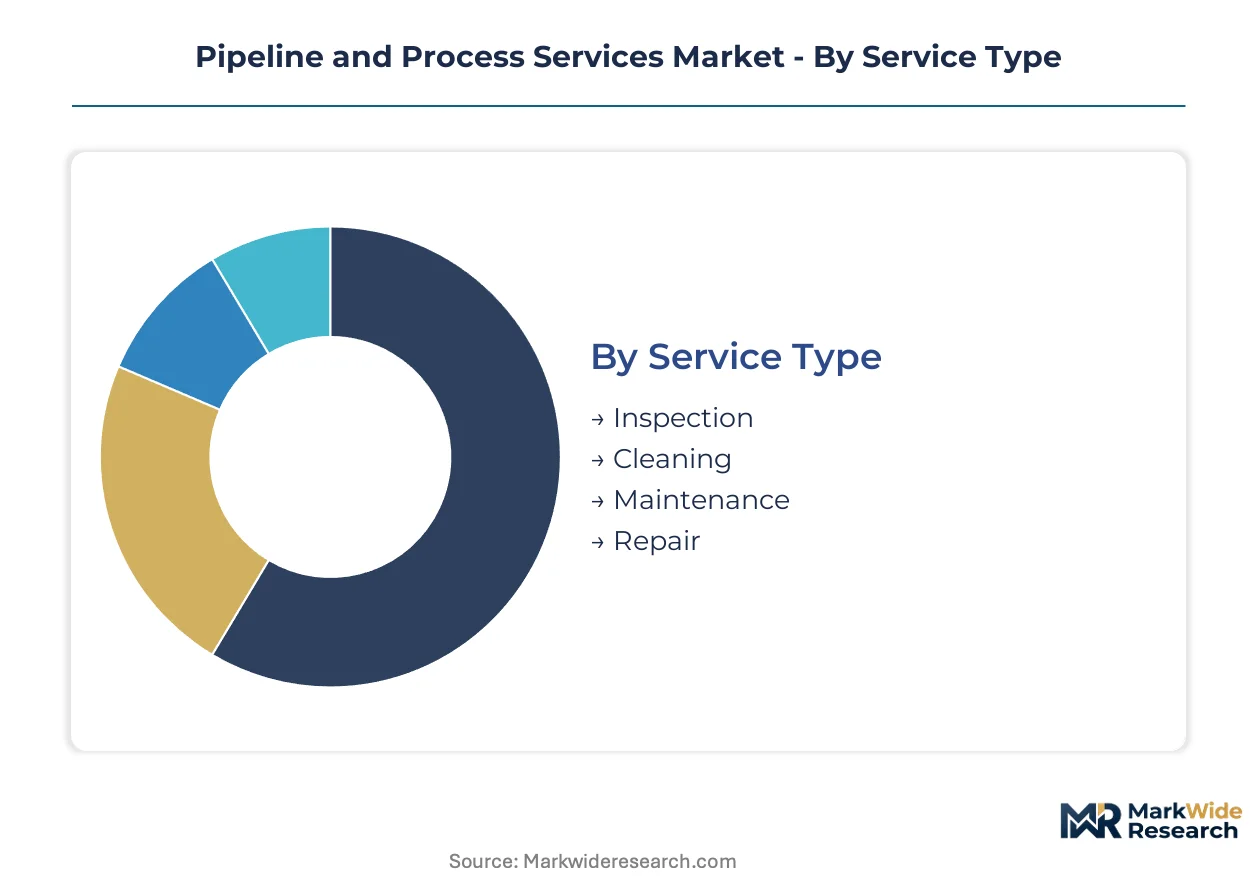
Pipeline and process services fragment across service intensity, diagnostic sophistication, and asset lifecycle stage. Each segment carries distinct margin profiles and regulatory exposure that shape vendor positioning and operator procurement strategies.
Service Type:
Inspection commands premium pricing through mandatory compliance cycles, while maintenance generates volume through recurring crew deployments.
- Inspection:Inline assessment services using magnetic flux leakage and ultrasonic tools detect metal loss, cracks, and geometric anomalies. PHMSA mandates in the United States compress inspection intervals for high-consequence areas, concentrating demand around vendors with multi-asset platform coverage and real-time data integration.
- Maintenance:Recurring crew-based services include valve exercising, cathodic protection monitoring, and coating rehabilitation. Embedded maintenance contracts at Permian Basin midstream hubs anchor revenue stability for service providers with localized technician pools.
- Cleaning:Pigging and chemical circulation services remove wax, scale, and debris to restore throughput capacity. Pre-commissioning cleaning for new Permian infrastructure buildouts is expanding fastest.
- Repair:Emergency clamp installation, sleeve welding, and composite reinforcement address integrity threats. Repair margins spike during unplanned mobilizations, though revenue concentration remains event-driven and geographically scattered.
Mature deployment sits with Maintenance. Newer deployment is concentrated in Inspection.
Technology:
Conventional pigging platforms dominate unit volumes, while robotic systems capture expanding share in geometrically constrained environments.
- Smart Pigs:Self-propelled inspection platforms equipped with magnetic flux leakage and ultrasonic sensors traverse piggable pipelines to generate wall thickness maps and anomaly inventories. Gulf Coast corridor operators rely on smart pig vendors for baseline integrity assessments across interstate transmission systems.
- Robotic Inspection:Tethered crawlers and autonomous vehicles navigate unpiggable geometries including subsea tiebacks, urban distribution networks, and multi-diameter lines. Petrobras pre-salt developments in Brazil are accelerating adoption of subsea robotic systems for riser and flowline assessment.
- Ultrasonic Testing:Handheld and automated ultrasonic thickness measurement complements inline systems for targeted verification. Offshore platform operators deploy ultrasonic testing for riser splash zone monitoring where pig access is impossible.
- Hydrostatic Testing:Pressure verification using water or nitrogen confirms structural integrity following construction or repair. New pipeline pre-commissioning in West Texas and New Mexico sustains steady demand for hydrostatic testing crews.
Established infrastructure relies on Smart Pigs. Steepest expansion trajectory belongs to Robotic Inspection.
End User:
Oil and gas operators generate the majority of service revenue, while water and power utilities represent emerging verticals with distinct procurement rhythms.
- Oil & Gas:Upstream, midstream, and downstream operators mandate the full spectrum of inspection, maintenance, and repair services. Supermajor bundling of multi-year integrity contracts concentrates procurement authority at corporate technical centers.
- Chemicals:Process plant operators require pressure vessel and pipeline integrity management to satisfy OSHA process safety management rules. Chemical corridor facilities along the United States Gulf Coast sustain specialized service demand.
- Water Supply:Municipal and industrial water utilities are adopting inline inspection for aging transmission mains. Large-diameter water pipeline assessments in California and Texas are expanding the addressable market beyond hydrocarbon applications.
- Power Generation:Cooling water intake, ash slurry, and hydrogen pipeline systems require specialized inspection protocols. Combined cycle gas turbine facilities with hydrogen blending infrastructure are creating new service specifications.
Revenue concentration rests with Oil & Gas. Fastest-growing engagement is emerging in Water Supply.
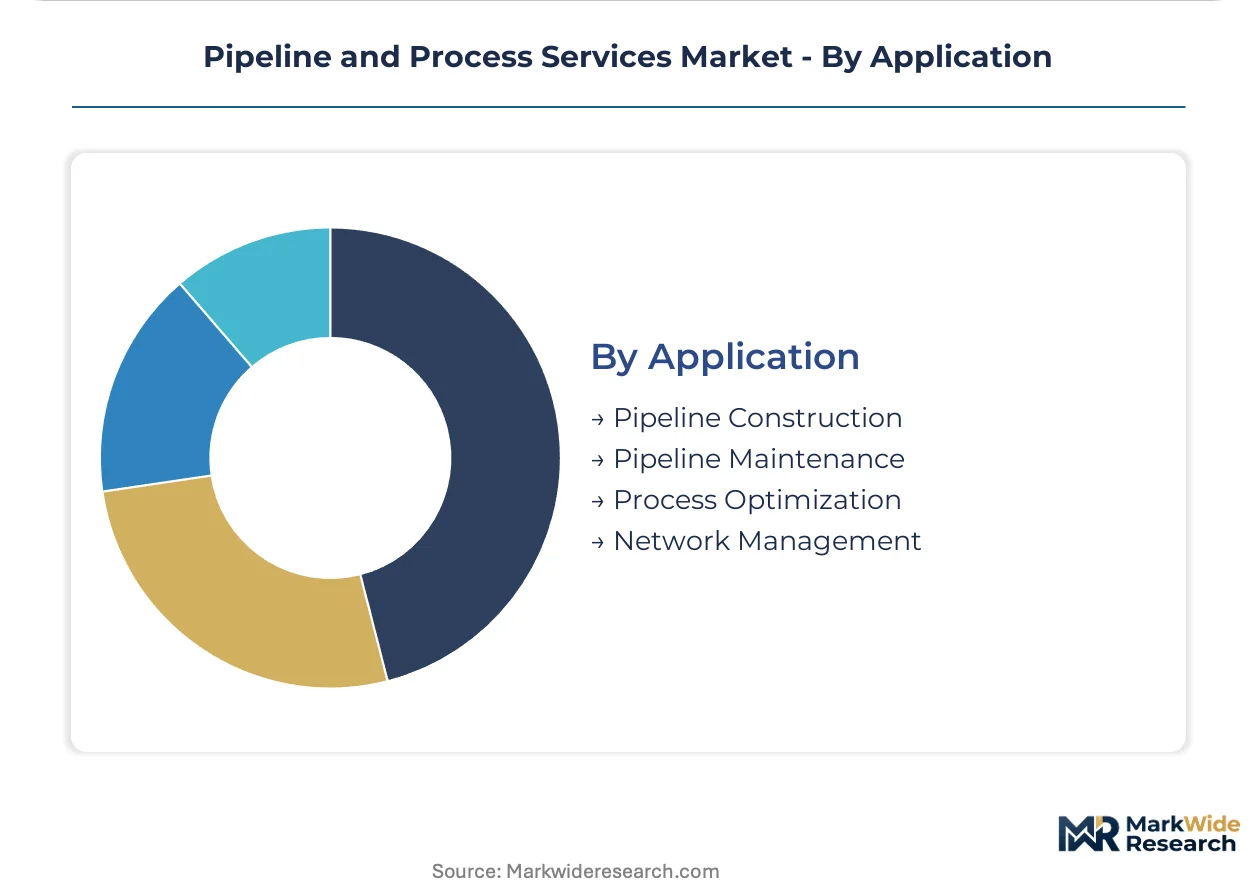
Application:
Construction-phase services compete on speed and mobilization cost, while maintenance-phase contracts emphasize outcome-based performance metrics.
- Pipeline Maintenance:Sustained integrity management programs encompass scheduled inspection, preventive maintenance, and condition monitoring. Long-term service contracting is displacing spot procurement as operators seek predictable cost structures.
- Pipeline Construction:Pre-commissioning cleaning, hydrostatic testing, and initial inline inspection verify integrity before operational handover. Permian Basin infrastructure buildouts are compressing construction service timelines.
- Process Optimization:Flow assurance studies, drag reduction analysis, and throughput enhancement recommendations leverage inspection data for operational improvement. Digital twin integration is enabling predictive maintenance contracts that replace fixed-schedule agreements.
- Network Management:Geographic information system integration, risk-based integrity planning, and regulatory reporting coordination consolidate multiple service streams. Network management contracts bundle field services with data analytics for enterprise-scale operators.
Contract maturity centers on Pipeline Maintenance. Technology investment is concentrating in Process Optimization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Permian Basin crude and pre-salt Brazilian reserves anchor regional service demand. Pipeline integrity mandates from Washington to London compress inspection cycles. Midstream buildouts in West Texas and offshore Brazil sustain contractor mobilization.
United States
PHMSA integrity rules compress inspection intervals for high-consequence areas. The EPA's methane emissions standards mandate continuous leak detection with specified repair timelines. Gulf Coast corridor midstream hubs in Houston and Corpus Christi anchor embedded maintenance crew deployments.
Brazil
Petrobras pre-salt developments drive subsea tieback architecture demand. ANP regulatory frameworks require riser inspection and flexible flowline maintenance certification. Santos Basin offshore clusters sustain specialized robotic inspection mobilizations.
United Kingdom
Pipeline Safety Regulations impose integrity management burdens on North Sea infrastructure. The HSE mandates corrosion monitoring for aging offshore assets. Aberdeen service bases anchor subsea inspection contractor operations.
Germany
Smart pig manufacturing concentration exposes European contractors to equipment lead time risks. ECHA chemical safety rules affect pipeline coating rehabilitation specifications. Ruhr industrial corridor chemical facilities sustain pressure vessel inspection demand.
Canada
Alberta oil sands operators require specialized slurry pipeline integrity programs. The Canada Energy Regulator mandates inline assessment for interprovincial transmission systems. Calgary technical centers anchor pipeline integrity contractor headquarters.
Pipeline and Process Services Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue robotic unpiggable inspection capabilities. The vendor base concentrates around integrated energy service conglomerates and specialized inspection technology developers. Three archetypes dominate: full-service conglomerates bundling digital subsurface platforms, robotic specialists targeting geometrically constrained assets, and embedded maintenance providers anchoring at midstream hubs. Competitive moves center on multi-year outcome-based contracting and predictive analytics platform integration.
Among Houston-based energy service conglomerates, Schlumberger Limited, Halliburton Company, and Baker Hughes Company exemplify the full-service archetype. Schlumberger represents the digital integration tier, anchoring positions through reservoir analytics convergence. Halliburton occupies the embedded maintenance vector, with crew deployments at major North American midstream hubs. Baker Hughes sits within the robotic specialization tier, serving unpiggable pipeline geometries. European specialists including ROSEN Group and T.D. Williamson Inc. complement this structure with inline inspection technology concentration. Saipem S.p.A. and TechnipFMC plc exemplify the offshore project execution archetype, with subsea infrastructure capabilities. Wood PLC and McDermott International, Inc. represent the engineering-procurement-construction tier, bundling integrity management with capital project delivery.
| Leading Market Players |
|---|
| TechnipFMC plc |
| ROSEN Group |
| Schlumberger Limited |
| Saipem S.p.A. |
| T.D. Williamson Inc. |
| Halliburton Company |
| Wood PLC |
| McDermott International, Inc. |
| Baker Hughes Company |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up inspection specialists anchor supply behavior across the United States Gulf Coast and North Sea, consolidating fragmented maintenance crews into platform-scale entities that enforce pricing discipline through embedded long-term contracts. This ownership pattern concentrates procurement leverage at supermajor technical centers while compressing margins for unconsolidated regional players lacking multi-asset coverage.
Pricing Analysis
Volume concentrates in recurring maintenance contracts while margins concentrate in emergency repair mobilizations and robotic inspection deployments. Three-tier pricing structure across premium certified, standard compliant, and economy spot-service levels separates PHMSA-accredited providers from uncertified competitors. Cost compression in standard-tier smart pigging intensifies because German and United States equipment suppliers extend manufacturing lead times during demand surges. Midstream operators with bundled multi-year frameworks exhibit lowest price sensitivity; spot-market buyers in Permian Basin construction phases drive hardest rate negotiations.
Supply Chain Analysis
Certified inline inspection analysts and robotic technicians concentrate in Houston, Aberdeen, and Stavanger, creating workforce bottlenecks that delay project mobilization and inflate wage premiums. Smart pig manufacturing draws from Germany and the United States; subsea robotic systems rely on Norwegian and Brazilian engineering clusters. Single-source vulnerability runs through German magnetic flux leakage sensor suppliers exposed to export licensing friction. Distribution runs through embedded crew deployments at midstream hubs rather than centralized inventory models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
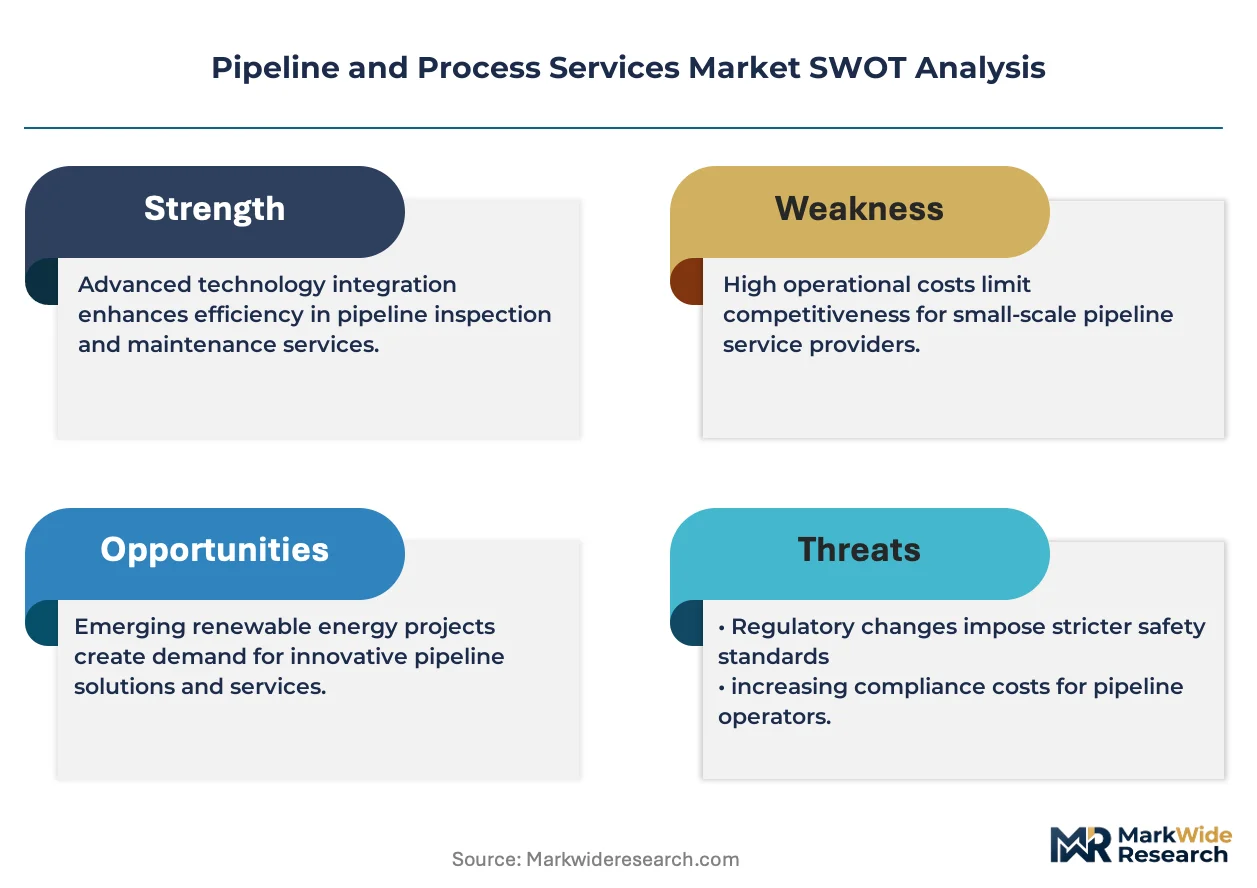
This market reads as a cost-of-compliance story where PHMSA integrity management rules erect barrier-to-entry moats that favor accredited incumbents with certified analyst pools and real-time data platforms.
For Market Incumbents: Anticipate methane detection substitution from satellite-based emissions monitoring by accelerating predictive analytics platform integration that bundles leak detection with process optimization. Defensive consolidation moves center on acquiring unpiggable pipeline robotics capabilities to counter emerging specialists, and securing API 1163 certification pipelines to lock in technician supply. Capacity addition in Brazil's Santos Basin anchors long-term contract visibility against North American margin pressure.
For New Entrants and Emerging Players: Capture white-space in water utility inline inspection for aging transmission mains in California and Texas, where hydrocarbon-sector expertise transfers with minimal adaptation. Municipal procurement rhythms favor fixed-price assessment contracts over outcome-based frameworks prevalent in oil and gas. Go-to-market angle emphasizes emissions verification accreditation that satisfies EPA quarterly reporting requirements without incumbent legacy SCADA integration burdens.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap inspection technology developers with proprietary electromagnetic acoustic transducer platforms and established Petrobras subsea relationships. Long-term viability across the projection horizon rests on digital twin convergence capabilities that displace fixed-schedule maintenance contracts. Signal to watch is regulatory divergence between PHMSA methane detection thresholds and EU Industrial Emissions Directive specifications, which would fragment service standardization and favor multi-jurisdiction platform operators.
| Strategic Initiative | Industry Significance |
|---|---|
| Robotic Unpiggable System Development | Petrobras pre-salt tiebacks create captive demand for subsea crawler technologies. |
| API 1163 Certification Pipeline Investment | PHMSA mandates compress analyst qualification timelines and limit fleet utilization. |
| Digital Twin Platform Integration | Condition-based maintenance contracts displace fixed-schedule agreements at supermajors. |
| Water Utility Market Entry | California and Texas transmission main assessments expand addressable market beyond hydrocarbons. |
| Emissions Verification Accreditation | EPA methane standards mandate optical gas imaging with quarterly reporting requirements. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with pipeline integrity managers, PHMSA compliance officers, midstream procurement directors, and robotic inspection technicians. Secondary sources encompassed PHMSA incident databases, EPA emissions disclosure filings, ANP regulatory bulletins, and smart pig manufacturing export records from German and United States customs authorities. Bottom-up crew deployment estimates and top-down contract value triangulation validated segment sizing.
Granularity-level modeling examined service type, technology platform, end-user vertical, and application lifecycle stage at the country-regulator cluster level across the analysis window. CAGRs derived from regression against historical inspection cycle compression, infrastructure age profiles, and regulatory mandate expansion trajectories. Industry-specific forecast inputs incorporated Permian Basin midstream buildout timelines and Petrobras pre-salt development schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory divergence between PHMSA and EU Industrial Emissions Directive specifications, equipment supplier concentration disruptions, and methane detection technology substitution rates. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Asia-Pacific Medium Voltage Switchgear Market
Valves
Fluid Handling Systems Market
Valves
Cathodic Protection Market
Valves
Industrial Valves Market
Valves
Global Plastic Valves Market
Valves
Float Traps Market
Valves
US Water & Wastewater Valves Market
Valves
APAC Valves Market
Valves
Directional Control Valves Market
Valves
Axial and Radial Seals Market
Valves
Refrigeration Valves Market
Valves
Reciprocating Compressor Components Market
Valves
Orifice Reducers Market
Valves
Gas Equipment Market
Valves
Leak Detection Market
Valves
Chemical Injection Skid Market