
 Ball Valves Market | 2026-2036
Ball Valves Market Size, Share, and Industry Trends Forecast 2026-2036
Ball Valves Market Intelligence
Stainless steel is broadening its share against carbon steel in corrosive-service ball valve specifications due to extended lifecycle economics in offshore environments. Emerson Electric Co. leverages integrated digital valve monitoring to sustain premium positioning in LNG cryogenic applications. Flowserve Corporation anchors its Gulf Coast manufacturing footprint to compete on lead times for North American energy projects. KITZ Corporation specializes in small-bore forged ball valves for Japanese chemical processors, occupying a defensible niche against larger-format rivals.
A ball valve is a quarter-turn rotary valve employing a perforated hollow sphere to control fluid flow, typically rated for pressures from ANSI Class 150 to 2500 and temperatures spanning cryogenic to 538°C depending on seat material selection. Its primary industrial purpose is rapid shutoff and bidirectional sealing in pipelines handling gases, liquids, and slurries across process industries. Trunnion-mounted designs dominate high-pressure oil and gas transmission where pipeline diameters exceed 24 inches, while floating ball configurations retain cost advantages in water treatment distribution below 12 inches. Stainless steel material grades command margin premiums in chemical processing end uses where chloride-induced pitting resistance proves critical.
The American Petroleum Institute API 6D pipeline valve specification governs design validation for North American energy infrastructure, while the EU Pressure Equipment Directive and ISO 17292 dimensional standards shape product conformity for European project tenders. China's GB/T 12224 valve pressure-temperature ratings and NMPA-equivalent boiler safety codes dictate local sourcing requirements for domestic power generation contractors. Stakeholders must monitor divergence between API 6D's latest fugitive-emissions testing protocols and REACH-aligned material restrictions when configuring dual-certified product lines for multinational project portfolios.
Market Dynamics
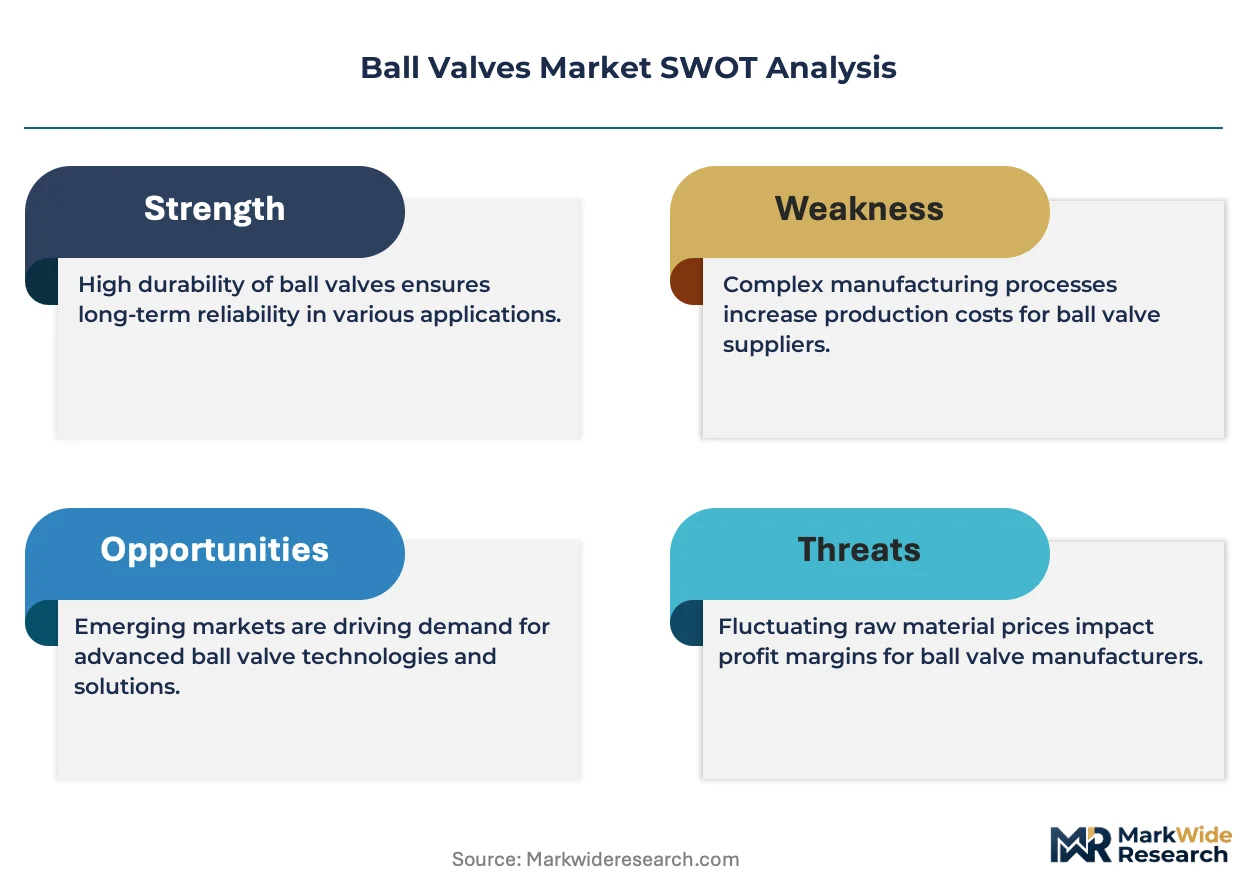
Water treatment infrastructure mandates across North America and Europe are compressing procurement cycles while tightening material specifications, forcing valve manufacturers to recertify product lines against revised pressure-testing protocols.
Growth Catalysts
- EPA Lead and Copper Rule revisions:Municipal utilities in the United States face accelerated replacement schedules for legacy distribution components, expanding procurement volumes for compliant ball valve assemblies.
- Stainless steel material migration:Offshore oil and gas operators specify super-duplex grades for subsea manifolds, extending field service life against chloride-induced corrosion.
- ISO 5208 pressure-testing protocols:European project tenders now require enhanced fugitive-emissions documentation, elevating demand for certified trunnion-mounted designs in high-pressure transmission.
Market Restraints
- Nickel alloy input volatility:Super-austenitic stainless grades depend on nickel and molybdenum spot markets, compressing margin predictability for forged-body manufacturers.
- Foundry capacity concentration:Ductile iron casting for waterworks-grade valves clusters in specific industrial zones, creating lead-time vulnerability for North American distributors.
- Butterfly valve substitution:HVAC and chilled-water systems increasingly specify high-performance butterfly designs for cost-sensitive shutoff applications below ANSI Class 300.
Strategic Opportunities
- Hydrogen pipeline infrastructure:Germany and the Netherlands are commissioning dedicated hydrogen distribution networks requiring specialized ball valve sealing technologies for embrittlement-resistant service.
- Digital valve positioners:Integration of IoT-enabled diagnostics with pneumatic actuators opens predictive maintenance revenue streams for process industry operators.
- Carbon capture injection wells:Enhanced oil recovery projects in the United States and Norway specify cryogenic-rated ball valves for supercritical CO2 handling.
Industry Challenges
- Dual-certification complexity:Manufacturers serving multinational energy projects must reconcile API 6D fugitive-emissions protocols with REACH material restrictions, extending engineering validation timelines.
- Weld overlay technician scarcity:Corrosion-resistant cladding of valve bodies requires specialized orbital welding expertise that outpaces current vocational training output.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ball Valves Market |
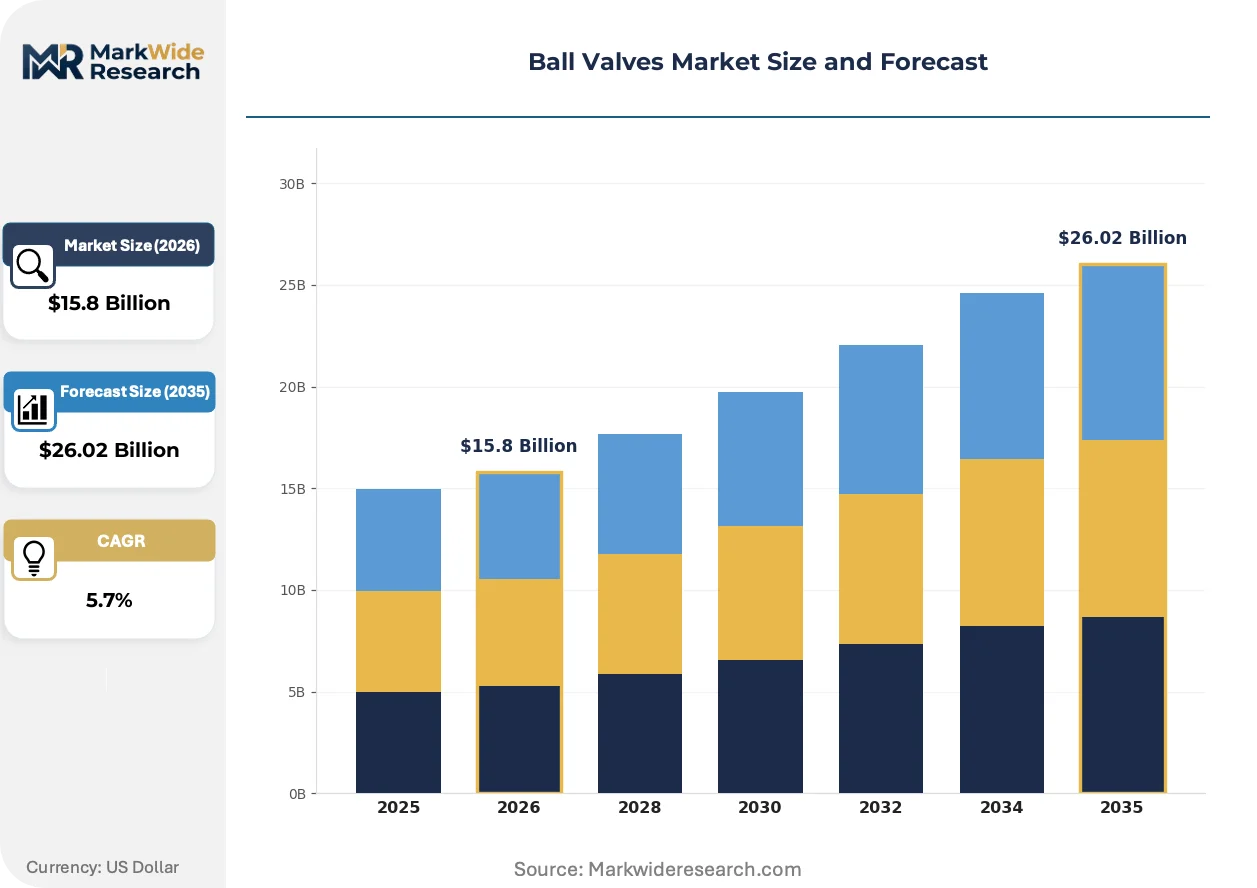
| Market Size in 2026 | $15.8 Billion |
| Market Size in 2035 | $26.02 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Floating Ball Valve, Trunnion Ball Valve, V-Port Ball Valve, Multi-Port Ball Valve End User: Oil & Gas, Water Treatment, Power Generation, Chemical Processing Size: Small, Medium, Large, Extra Large Material: Stainless Steel, Carbon Steel, Brass, PVC |
| Companies Covered | Emerson Electric Co., Flowserve Corporation, Schlumberger (Cameron), IMI plc, KITZ Corporation, Crane Co., Valmet, Neway Valve (Suzhou) Co., Ltd., Alfa Laval, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ball Valves Market Strategic Shifts & Innovations
Digital instrumentation and advanced metallurgy are compressing the traditional divide between mechanical valve hardware and process control systems, enabling condition-based maintenance models.
Metal-seated ball valve technology is rewriting reliability expectations in severe-service applications. Sintered tungsten carbide coatings on sealing surfaces now withstand continuous particulate erosion in mining slurry pipelines. Australian iron ore operators have adopted these designs for tailings transport, eliminating the quarterly maintenance shutdowns associated with soft-seat alternatives. The technology is rewriting asset lifecycle economics by extending mean time between failures beyond eight years in abrasive service.
REACH-aligned material restrictions are forcing reformulation of elastomer seat compounds across European process industries. ECHA substance-of-very-high-concern listings now restrict certain fluoropolymer curing agents previously standard in chemical-resistant seats. German chemical processors are qualifying hydrogenated nitrile alternatives for steam service above 200°C. The policy shift is accelerating supplier consolidation as compounders invest in compliant formulation capacity.
Integrated procurement platforms are consolidating vendor selection for mid-size engineering contractors. Digital tendering systems now embed ISO 17292 dimensional compliance filters, automatically disqualifying non-certified suppliers before technical review. United States-based municipal water authorities have adopted these platforms for distribution network upgrades, compressing supplier qualification from months to weeks. The channel shift favors manufacturers with pre-loaded certification documentation and API Q1 quality system credentials.
Ball Valves Market Segmentation
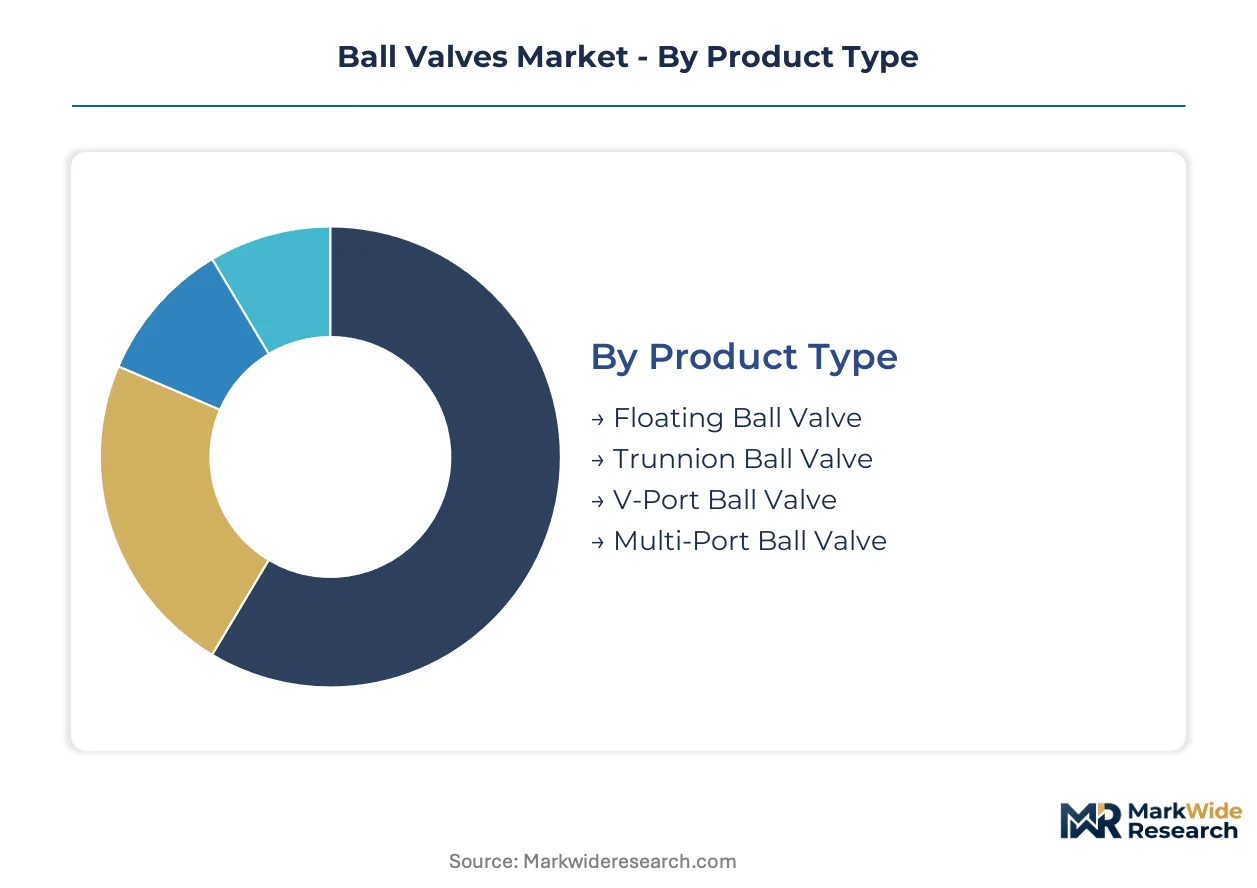
Ball valve procurement decisions hinge on pressure ratings, media compatibility, and lifecycle cost calculations that vary sharply across industrial applications. Certification requirements from API, ISO, and national regulators create divergent compliance burdens that reshape competitive positioning within each segment category.
Product Type:
API 6D certification governs pipeline transmission valves above ANSI Class 600, while ISO 17292 dimensional standards apply to floating designs in general service. Trunnion-mounted configurations require additional fugitive-emissions documentation for European tenders.
- Trunnion Ball Valve:Anchored ball design with upper and lower shaft supports handles pressures to ANSI Class 2500 in 24-inch-plus transmission lines. Demand concentrates in United States shale gathering networks where pipeline operators prioritize seal reliability over initial cost. API 6D twenty-fourth edition testing protocols now mandate extended thermal cycling validation for these specifications.
- Floating Ball Valve:Ball element suspended between two seat rings achieves bidirectional sealing through line pressure activation. Water treatment utilities in Germany specify these for distribution networks under 12 inches diameter, driven by ISO 5208 shell-test requirements that favor simpler geometries. Seat material selection—PTFE versus reinforced TFM—determines temperature ceiling and chemical resistance.
- V-Port Ball Valve:Characterized ball bore enables throttling control in pulp stock and slurry applications. Pulp mills in Finland deploy these for consistency control in bleaching lines.
- Multi-Port Ball Valve:L- or T-port configurations divert flow between three or more pipeline branches. Tank farm operators in Rotterdam specify these for product blending manifolds.
Floating ball valves sit at the top of the volume ranking, with trunnion designs climbing the fastest as high-pressure transmission infrastructure expands.
End User:
Customer procurement sophistication spans municipal bid processes with rigid specification compliance to energy sector frame agreements prioritizing total cost of ownership.
- Oil & Gas:Exploration, production, and midstream operations specify cryogenic-rated materials for LNG liquefaction trains and sour-service metallurgy for hydrogen sulfide environments. Norwegian North Sea operators require NORSOK M-630 compliance for subsea installations. Super-duplex grades resist chloride stress corrosion in offshore manifolds.
- Water Treatment:Municipal distribution networks and industrial wastewater facilities drive specification toward ductile iron bodies with fusion-bonded epoxy coatings. United States utilities face EPA Lead and Copper Rule replacement schedules that compress procurement cycles. NSF/ANSI 61 drinking water system component certification filters supplier qualification.
- Power Generation:Combined cycle plants and nuclear facilities specify pressure-seal bonnet designs for steam service above 260°C. French EPR reactor projects require RCC-M nuclear pressure equipment codes.
- Chemical Processing:Corrosive media handling demands alloy selection mapped to chloride concentration and pH profiles. German chemical parks specify EN 12516 pressure-temperature ratings for integrated site utilities.
Water treatment commands the highest unit volume, while hydrogen pipeline applications within oil and gas are expanding most quickly.
Size:
Manufacturing process economics bifurcate sharply at the 24-inch threshold between forged-body and cast-body fabrication methods.
- Large:24-60 inch nominal pipe size range dominates transmission pipeline specifications where welded construction or cast steel bodies prevail. United States interstate pipeline operators source these through multi-year frame agreements with API Q1-certified foundries. Automated orbital welding of body-to-bonnet joints reduces field failure rates.
- Medium:6-24 inch range captures process plant piping and municipal water distribution mains. Italian valve assemblers specialize in this bracket, leveraging flexible manufacturing cells for batch-size-one production.
- Small:Under 6 inch instrumentation and sampling lines specify forged-barstock bodies with threaded or socket-weld end connections. Japanese chemical processors favor KITZ Corporation forged designs for reliability in high-cycle service.
- Extra Large:Above 60 inch diameter applications include hydroelectric penstocks and cooling water intakes. Project-specific engineering with finite-element analysis of body stresses characterizes this bracket.
Medium sizes generate the steepest revenue concentration, with large diameters gaining share fastest as pipeline replacement cycles accelerate.
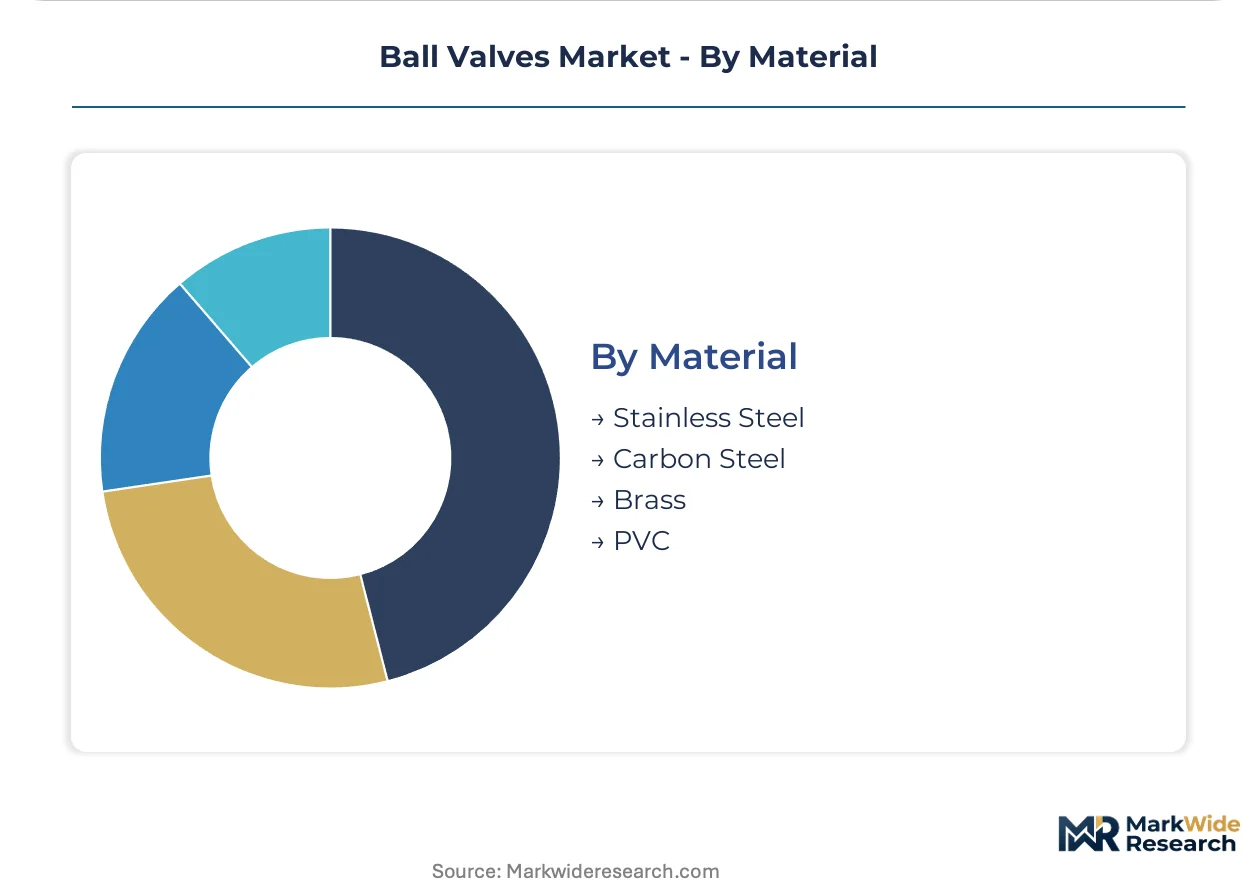
Material:
Raw material volatility and corrosion resistance requirements drive specification migration toward higher alloy grades despite cost premiums.
- Stainless Steel:Austenitic 316 grades resist moderate chlorides; super-austenitic 6Mo and duplex 2205 handle seawater and aggressive chemicals. Offshore platform operators in the United Kingdom sector specify these for twenty-five-year field life without replacement. Nickel content exposure links margin predictability to London Metal Exchange pricing.
- Carbon Steel:ASTM A216 WCB castings and A105 forgings dominate waterworks and non-corrosive hydrocarbon service. Foundry capacity concentration in specific industrial zones creates lead-time vulnerability for North American distributors. Fusion-bonded epoxy internal coatings extend service life in mildly corrosive water.
- Brass:Lead-free C89833 and C27450 alloys satisfy United States Safe Drinking Water Act requirements for potable plumbing. California Proposition 65 compliance drives specification toward bismuth-substituted machinability additives.
- PVC:Thermoplastic construction handles corrosive chemicals and ultrapure water in semiconductor fabrication facilities. Singapore wafer fabs specify these for deionized water distribution to eliminate metallic ion contamination.
Carbon steel retains volume leadership in unit terms, with stainless steel grades showing the steepest expansion trajectory as lifecycle economics favor corrosion resistance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Houston-Gulf Coast petrochemical corridor generates concentrated demand for high-pressure trunnion designs serving shale gathering networks and LNG export terminals. Municipal water authorities across multiple continents are accelerating procurement cycles to meet infrastructure replacement mandates. Regulatory divergence between API 6D and ISO 5208 protocols forces manufacturers to maintain parallel certification tracks for multinational project portfolios.
United States
Shale basin operators in the Permian and Marcellus formations specify API 6D-certified trunnion valves for gathering lines above ANSI Class 600. The EPA Lead and Copper Rule revisions compel municipal utilities in Michigan and Illinois to replace legacy lead-containing components on compressed schedules. Pittsburgh-area water authorities are consolidating procurement through digital tendering platforms that pre-filter for NSF/ANSI 61 certification.
Germany
Hydrogen pipeline pilot projects in the Ruhr industrial cluster require specialized sealing technologies for embrittlement-resistant service at elevated pressures. The EU Pressure Equipment Directive mandates enhanced fugitive-emissions documentation for high-pressure transmission tenders. Valve fabricators in North Rhine-Westphalia are qualifying hydrogenated nitrile seat compounds to satisfy ECHA substance-of-very-high-concern restrictions on legacy fluoropolymer curing agents.
China
Domestic power generation contractors source GB/T 12224-rated valves under NMPA-equivalent boiler safety codes for ultra-supercritical coal and nuclear projects. The Yangtze River Delta concentration of chemical processors drives specification migration toward super-austenitic grades for chloride-rich environments. Shanghai municipal waterworks are integrating ISO 17292 dimensional compliance filters into digital procurement platforms.
Japan
Chemical processors in the Keiyo industrial zone favor small-bore forged designs for high-cycle sampling and instrumentation lines. METI industrial standards shape pressure-temperature rating requirements for domestic refinery maintenance cycles. Osaka-based engineering contractors specify JIS-compliant floating ball configurations for distribution networks under 12 inches diameter.
Netherlands
Rotterdam tank farm operators deploy multi-port configurations for product blending manifolds serving European refining and chemical export hubs. The EU Green Deal hydrogen backbone initiative is commissioning dedicated distribution networks requiring cryogenic-rated materials for sub-zero service. Dutch engineering contractors are consolidating vendor qualification through platforms that embed REACH-aligned material restriction filters.
Ball Valves Market Key Industry Players
Global majors compete with regional champions across certification depth and lead-time responsiveness. The vendor base clusters around three strategic tiers: integrated conglomerates with full API Q1 quality systems, mid-scale specialists dominating single geography or product format, and foundry-dependent assemblers competing on price for waterworks-grade specifications. Consolidation pressure is accelerating through multi-year frame agreement concentration and digital procurement platform vendor pre-qualification requirements.
Among diversified industrial conglomerates, Emerson Electric Co. and Flowserve Corporation exemplify the integrated-tier archetype with comprehensive certification portfolios spanning cryogenic through sour-service ratings. KITZ Corporation occupies a defensible position within the precision-forged specialist tier. These three entities anchor the competitive structure, with Emerson and Flowserve representing the scale-driven end and KITZ exemplifying focused manufacturing depth in small-bore formats.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| Flowserve Corporation |
| Schlumberger (Cameron) |
| IMI plc |
| KITZ Corporation |
| Crane Co. |
| Valmet |
| Neway Valve (Suzhou) Co., Ltd. |
| Alfa Laval |
| Others |
Cost & Logistics Intelligence
Nickel alloy spot pricing on the London Metal Exchange feeds directly into forging cost structures for super-austenitic grades, compressing margins at the premium tier while carbon steel waterworks specifications absorb foundry energy surcharges through longer-term municipal contracts.
Pricing Analysis
Input-cost pass-through from nickel and molybdenum volatility dominates margin dynamics for forged-body manufacturers serving offshore oil and gas. Three-tier pricing structure across API 6D-certified premium, ISO 17292-compliant standard, and waterworks-grade economy levels reflects certification depth and testing documentation burden. Pricing pressure stems from butterfly valve substitution in HVAC applications below ANSI Class 300. Municipal utilities exhibit highest price sensitivity due to rigid bid processes, while LNG operators prioritize seal reliability over initial cost.
Supply Chain Analysis
Single-source vulnerability sits with ductile iron casting capacity concentrated in specific Chinese industrial zones, creating lead-time exposure for North American waterworks distributors. Super-duplex forging feedstock draws from United Kingdom and Swedish specialty steel mills. Foundry energy costs, nickel alloy spot markets, and orbital welding technician scarcity constitute critical dependencies. Tariff exposure runs through carbon steel raw material flows. Distribution runs through API Q1-certified foundry direct sales for large transmission valves and regional assembler networks for municipal specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where German hydrogen pipeline specifications outpace United States regulatory development, creating certification-premium capture for early movers in embrittlement-resistant sealing technologies.
For Market Incumbents: Extend API 6D certification depth into hydrogen service qualifications before ISO standards crystallize, locking in specification influence. Backward integration into nickel alloy forging feedstock hedges London Metal Exchange volatility. Channel control through digital procurement platform pre-qualification filters emerging competitors from municipal bid processes. For New Entrants and Emerging Players: Small-bore forged instrumentation valves for Japanese chemical processors represent an underserved buyer archetype with defensible niche economics against integrated conglomerates. White-space targets include hydrogenated nitrile seat compound formulation for REACH-compliant European tenders and cryogenic-rated designs for Netherlands CO2 injection infrastructure. Go-to-market leverage rests on orbital welding technician training partnerships with German vocational institutes. For Investors and Strategic Acquirers: Roll-up economics work for precision-forged specialists because API Q1 quality system credentialing creates acquisition currency for platform consolidation. Five-to-ten year viability hinges on hydrogen infrastructure deployment velocity. Target mid-scale Italian valve assemblers with flexible manufacturing cells in the 6-24 inch bracket. Watch German hydrogen backbone commissioning schedules as inflection indicator for specialized sealing demand.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen Service Qualification | German Ruhr pilot projects require embrittlement-resistant sealing above 100 bar. |
| Digital Valve Positioner Integration | IoT-enabled diagnostics open predictive maintenance revenue at Norwegian North Sea platforms. |
| REACH-Compliant Seat Reformulation | ECHA substance restrictions force hydrogenated nitrile qualification for steam above 200°C. |
| Foundry Capacity Expansion | Gulf Coast proximity reduces lead times for Permian Basin gathering line projects. |
| Orbital Welding Technician Training | Corrosion-resistant cladding scarcity limits super-duplex valve body output. |
Research Approach
Direct dialogue with valve procurement managers at municipal water authorities, maintenance directors at offshore platform operators, EPC contractors specializing in hydrogen infrastructure, and metallurgical engineers at specialty forging mills grounded qualitative findings. Secondary validation drew from API certification registries, EPA Lead and Copper Rule implementation timelines, ECHA substance restriction databases, and SEC filings of listed valve manufacturers. Bottom-up demand modeling triangulated against top-down energy infrastructure investment forecasts.
Bottom-up volume estimates aggregated across product type, end-use industry, size bracket, and material grade dimensions. Top-down cross-checks anchored in pipeline replacement cycle data and municipal capital expenditure disclosures across the analysis window. CAGRs derived from segment-level growth drivers including regulatory replacement mandates, hydrogen infrastructure deployment, and material specification migration. Forecast inputs incorporated nickel price volatility bands and foundry capacity utilization rates.
Underlying measurement precision varies by segment; hydrogen pipeline applications carry wider uncertainty bands than established water treatment specifications. Forecasts reflect assumptions on regulatory implementation pacing and commodity price trajectories. Nickel alloy cost spikes, foundry capacity constraints, or accelerated butterfly valve substitution could materially revise projections. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Backflow Preventers Market
Valves
Emergency Shut Down Valves (ESDV) Market
Valves
Hybrid Valve Market
Valves
Tank Hydrogen Valve Market
Valves
Off-Highway Hydraulic Valve Actuator Systems Market
Valves
Pneumatic Slide Gates Market
Valves
Compressor Valves Market
Valves
Valve Seat Inserts Market
Valves
Battery Safety Valve Market
Valves
Valve Sack Market
Valves
Carbon Seal Rings Market
Valves
Electrohydraulic Servo Valves (Ehsvs) Market
Valves
Directional Control Valves Market
Valves
Gate Impellers Market
Valves
Degassing Valves Market
Valves
Axial and Radial Seals Market