
 East Africa Refined Petroleum Products Market | 2026-2036
East Africa Refined Petroleum Products Market Size, Share, and Industry Trends Forecast 2026-2036
East Africa Refined Petroleum Products Market Foresight
Skilled refinery technicians and pipeline engineers is collapsing across East Africa, constraining operational uptime at import terminals and storage depots. TotalEnergies SE leverages its coastal storage infrastructure in Mombasa to dominate regional product throughput. Vivo Energy PLC anchors retail distribution through its extensive service station network spanning Kenya, Tanzania, and Uganda. National Oil Corporation of Kenya competes on strategic petroleum reserve management and emergency supply security.
East Africa refined petroleum products encompass hydrocarbon fuels produced through crude oil distillation, catalytic cracking, and hydrotreating processes, yielding gasoline, diesel, jet fuel, and kerosene with specified sulfur content and octane/cetane ratings for combustion engines and industrial burners. These products serve as the primary energy input for transportation fleets, aviation turbines, marine propulsion systems, and stationary power generation across the region. Diesel commands the dominant volume position due to heavy reliance on freight trucking and backup generators, while jet fuel represents the fastest-growing category as Addis Ababa and Nairobi airport hubs expand international connectivity. The automotive application segment captures the deepest margin pool through branded retail networks, whereas marine bunkering remains fragmented across smaller coastal suppliers.
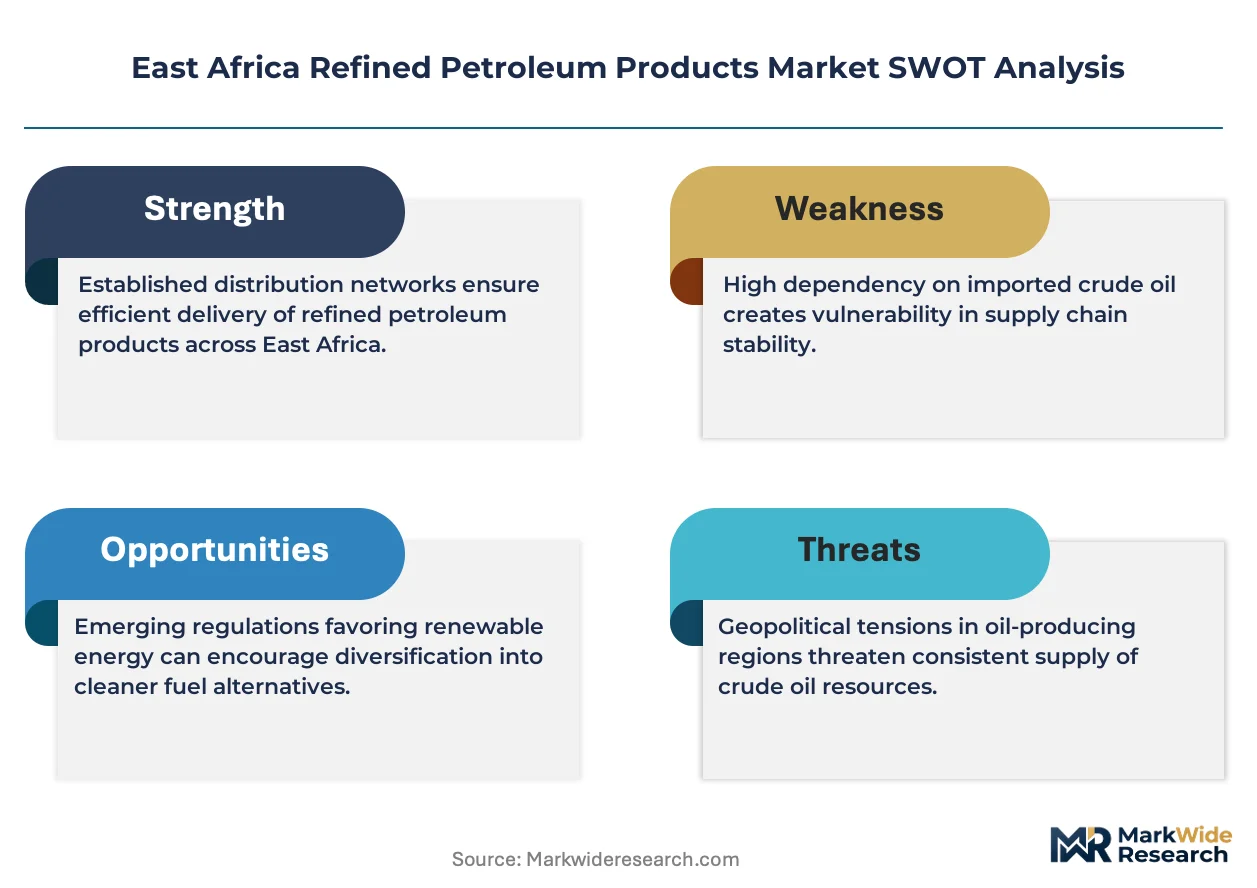
Kenya's Energy and Petroleum Regulatory Authority enforces petroleum product quality specifications and import licensing, while Tanzania's Energy and Water Utilities Regulatory Authority governs downstream pricing and infrastructure access. The East African Community's customs union protocol shapes cross-border product flows and tariff structures. Ethiopia's Ministry of Mines and Petroleum directs state-controlled procurement through National Oil Ethiopia PLC, limiting private sector participation. Stakeholders must monitor infrastructure financing decisions for the East African Crude Oil Pipeline and regional storage joint ventures.
Market Dynamics
East Africa's refined petroleum products market is being fundamentally reshaped by the East African Community's harmonization of fuel quality standards, which is forcing simultaneous infrastructure upgrades across coastal import terminals and inland storage depots while compressing margins for non-compliant suppliers.
Growth Catalysts
- Logistics corridor deepening:Kenya and Tanzania are expanding diesel procurement for transportation fleets as regional freight volumes surge along the Northern Corridor and Central Corridor routes.
- EAC customs union protocol:Cross-border tariff harmonization is accelerating product flows between Kenya, Tanzania, and Uganda, reducing transit friction for bulk fuel movements.
- Aviation hub expansion:Addis Ababa Bole International Airport and Nairobi Jomo Kenyatta International Airport are driving jet fuel demand as Ethiopian Airlines and Kenya Airways expand long-haul connectivity.
Market Restraints
- Crude price volatility:East African importers face margin compression when Brent crude spikes, as downstream pricing in Kenya and Tanzania remains partially regulated by national energy authorities.
- Coastal terminal concentration:Mombasa handles the majority of regional throughput, creating single-point-of-failure risk for landlocked markets in Uganda, Rwanda, and Burundi.
- Renewable substitution:Off-grid solar and mini-grid deployments in rural Tanzania and Kenya are displacing kerosene for household lighting and small-scale power generation.
Strategic Opportunities
- Ethiopian market opening:National Oil Ethiopia PLC's procurement monopoly shows early signs of relaxation, creating entry points for private traders in Africa's second-most populous nation.
- Marine bunkering consolidation:Dar es Salaam and Mombasa ports can capture regional vessel refueling demand currently fragmented across smaller coastal suppliers.
- Strategic reserve infrastructure:Kenya's Energy and Petroleum Regulatory Authority is mandating expanded emergency storage, opening public-private partnership slots for depot operators.
Industry Challenges
- Technical workforce scarcity:Skilled refinery technicians and pipeline engineers are collapsing across the region, constraining operational uptime at import terminals and forcing reliance on expatriate labor.
- Legacy storage retrofit costs:Existing coastal tanks require sulfur-handling upgrades to meet EAC low-sulfur diesel specifications, demanding capital deployment without immediate revenue recovery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | East Africa Refined Petroleum Products Market |
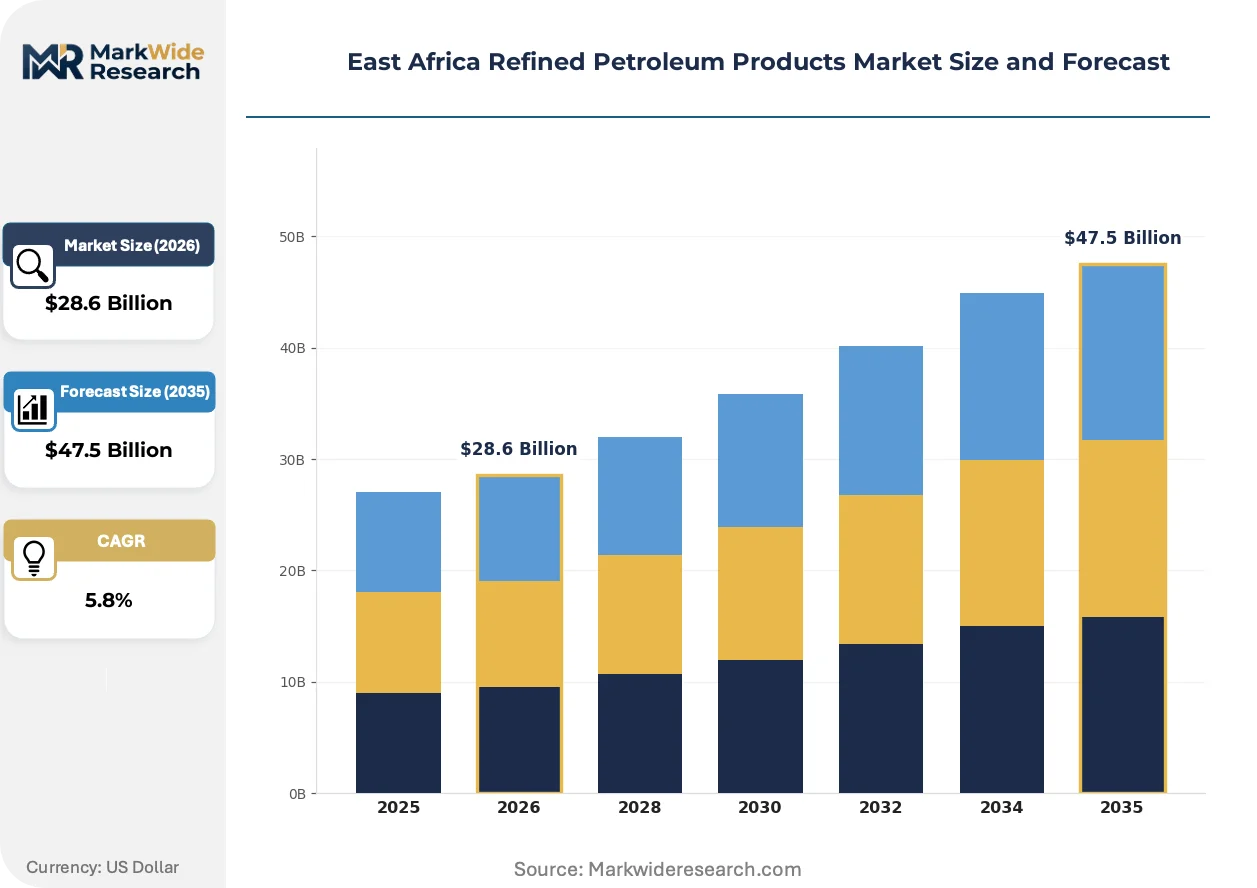
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gasoline, Diesel, Jet Fuel, Kerosene End User: Transportation, Manufacturing, Power Generation, Agriculture Distribution Channel: Retail Outlets, Wholesale, Direct Sales, Online Application: Automotive, Aviation, Industrial, Marine |
| Companies Covered | TotalEnergies SE, Shell PLC, Vivo Energy PLC, KenolKobil Ltd, National Oil Ethiopia PLC, PUMA Energy, Engen Petroleum, National Oil Corporation of Kenya, ExxonMobil Corporation, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
East Africa Refined Petroleum Products Market Shifts & Advancements
Digital fuel monitoring and hydrotreating process refinements are actively compressing quality variance and supply chain opacity across East African downstream operations. These shifts are reconfiguring how products flow from coastal terminals to inland markets.
Hydrotreating catalyst systems are decomposing historical sulfur content limitations in diesel production. Kenyan import terminals are adopting these units to meet EAC 50 ppm sulfur mandates ahead of enforcement deadlines. This technology is decomposing the competitive advantage of suppliers relying on higher-sulfur fuel stocks from non-compliant sources.
Kenya's Energy and Petroleum Regulatory Authority has tightened petroleum product quality specifications and import licensing requirements. Industrial consequence includes accelerated terminal upgrades and consolidation among smaller traders unable to finance compliance. The automotive retail segment is responding by pushing branded fuel networks to differentiate on certified quality rather than price alone.
Fleet operators across the Northern Corridor are consolidating diesel procurement through direct terminal offtake agreements, bypassing traditional retail intermediaries. This channel disintermediation is compressing margins for independent service station operators while rewarding coastal storage players with direct buyer relationships. Kenya's long-haul trucking sector exhibits the most visible concentration of this procurement model shift.
East Africa Refined Petroleum Products Market Segmentation
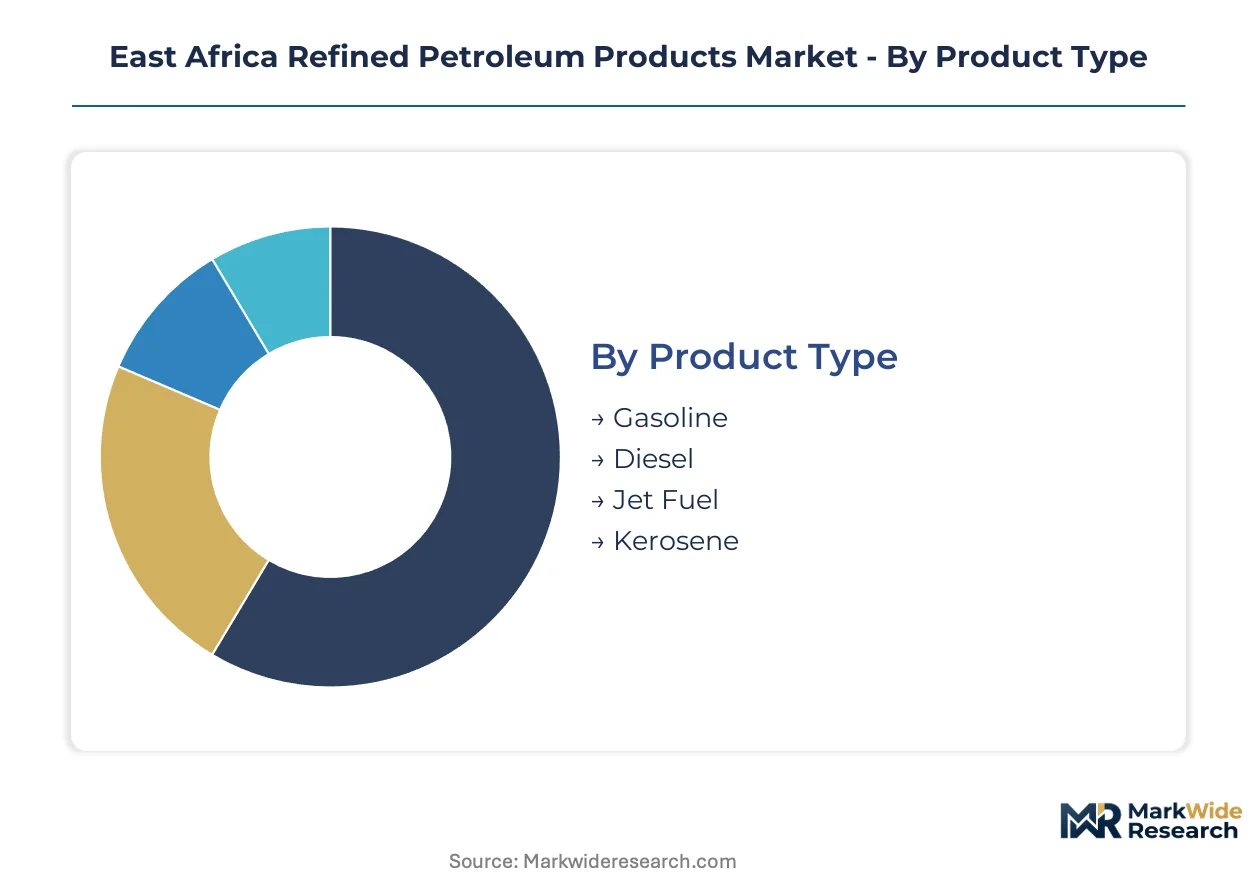
Segmentation in East Africa's refined petroleum products market reveals how margin pools concentrate around diesel volumes and aviation growth corridors. Understanding these divisions exposes where infrastructure investments and regulatory compliance costs will reshape competitive positioning across Kenya, Tanzania, and Uganda.
Product Type:
Diesel and jet fuel command the deepest margin pools, while gasoline and kerosene face diverging demand trajectories under EAC quality harmonization.
- Diesel:Hydrocarbon fuel with specified cetane ratings and sulfur content limits per EAC standards, produced through catalytic cracking and hydrotreating. Demand concentrates in Kenya's Northern Corridor freight trucking and backup power generation across Nairobi industrial zones, driven by logistics fleet expansion and grid reliability gaps.
- Jet Fuel:Aviation turbine kerosene meeting international specifications for flash point and freezing point characteristics. Demand concentrates at Addis Ababa Bole International Airport and Nairobi Jomo Kenyatta International Airport, driven by Ethiopian Airlines and Kenya Airways long-haul network expansion.
- Gasoline:Motor spirit with octane ratings for spark-ignition engines, primarily serving Kenya's passenger vehicle fleet and Tanzania's urban transport.
- Kerosene:Illuminating and cooking fuel facing displacement by off-grid solar and LPG substitution in rural Tanzania and Kenya.
Diesel holds installed capacity. Jet fuel is rotating up the share rankings.
End User:
Volume concentration sits with transportation operators, while margin extraction favors manufacturing procurement through direct terminal offtake agreements.
- Transportation:Freight trucking fleets, passenger bus operators, and aviation carriers consuming diesel, gasoline, and jet fuel. Kenya's long-haul trucking sector along the Mombasa-Nairobi axis drives the dominant volume position, with fleet operators consolidating procurement through direct terminal agreements that bypass retail intermediaries.
- Manufacturing:Industrial burners and captive power systems requiring consistent diesel supply for process heat and backup generation. Cement producers and textile mills in Kenya's Athi River industrial zone represent concentrated demand nodes with quality-sensitive procurement specifications.
- Power Generation:Grid-connected thermal plants and off-grid diesel generators serving rural electrification gaps.
- Agriculture:Irrigation pumps and farm machinery across Tanzania's Southern Highlands and Kenya's Rift Valley.
Transportation anchors volume throughput. Manufacturing is climbing the margin ladder fastest.
Distribution Channel:
Channel economics favor wholesale and direct sales where bulk volumes justify infrastructure investment, while retail outlets face margin compression from fleet disintermediation.
- Retail Outlets:Branded service station networks spanning Kenya, Tanzania, and Uganda, with Vivo Energy PLC operating the most extensive footprint. These outlets capture consumer automotive demand but face shrinking diesel volumes as fleet operators shift to direct terminal procurement.
- Wholesale:Bulk fuel distributors supplying independent retailers, industrial consumers, and regional traders across EAC borders. Wholesale channels benefit from EAC customs union tariff harmonization accelerating cross-border flows between Kenya, Tanzania, and Uganda.
- Direct Sales:Terminal-to-consumer agreements for large-volume industrial and fleet customers, bypassing intermediary margins.
- Online:Emerging digital platforms for fuel ordering and fleet management, currently limited by payment infrastructure and physical delivery requirements.
Wholesale holds infrastructure leverage. Direct sales is gaining transaction share.
Application:
Aviation applications extract premium pricing, while automotive volumes dominate throughput at coastal import terminals.
- Automotive:Passenger vehicles, commercial trucks, and buses consuming gasoline and diesel through retail and fleet channels. Kenya's matatu sector and Tanzania's intercity bus networks represent high-frequency demand nodes with price-sensitive procurement patterns.
- Aviation:Commercial airlines and cargo operators at Addis Ababa and Nairobi hubs, with jet fuel representing the steepest expansion trajectory as international connectivity deepens. Ethiopian Airlines' fleet growth drives disproportionate demand concentration.
- Industrial:Process heat, captive power, and manufacturing feedstock applications across cement, textiles, and food processing.
- Marine:Coastal and inland waterway bunkering for fishing vessels, cargo ships, and lake transport on Lake Victoria.
Automotive commands terminal throughput. Aviation is ascending the value curve fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kenya consumes diesel predominantly for freight corridors, while Ethiopia directs procurement toward aviation turbine fuel for state carrier expansion, and Tanzania balances industrial kerosene demand against rural solar displacement. These consumption-mix differentials shape infrastructure investment priorities across the region.
Kenya
Long-haul trucking fleets along the Mombasa-Nairobi corridor drive diesel procurement concentration, with cement and textile manufacturers in Athi River demanding consistent backup power supply. Kenya's Energy and Petroleum Regulatory Authority enforces petroleum product quality specifications and import licensing requirements. Mombasa port terminals handle the majority of regional product throughput, forcing simultaneous sulfur-handling upgrades across coastal storage infrastructure.
Tanzania
Diesel consumption centers on Central Corridor freight movements and grid-independent industrial generation, while off-grid solar deployment accelerates kerosene displacement in rural household lighting. Tanzania's Energy and Water Utilities Regulatory Authority governs downstream pricing and infrastructure access for private sector participants. Dar es Salaam port infrastructure supports both domestic distribution and re-export positioning for landlocked neighbors.
Ethiopia
Aviation turbine fuel demand concentrates at Addis Ababa Bole International Airport, driven by Ethiopian Airlines fleet expansion and long-haul network deepening. The Ministry of Mines and Petroleum directs state-controlled procurement through National Oil Ethiopia PLC, limiting private sector downstream participation. Addis Ababa's aviation hub status creates premium fuel logistics requirements distinct from regional ground transportation patterns.
Uganda
Landlocked positioning forces reliance on Kenyan and Tanzanian coastal terminals, with diesel procurement flowing through the Northern Corridor for Kampala industrial zones and agricultural processing. The East African Community customs union protocol shapes cross-border tariff structures and bulk fuel movements. Jinja industrial corridor hosts manufacturing clusters with captive power generation requirements.
Rwanda
Regional logistics hub status generates concentrated diesel demand for trucking fleets serving DRC and Burundi transit trade, with limited domestic storage capacity forcing just-in-time procurement patterns. National energy regulators coordinate with EAC harmonization timelines for fuel quality standard adoption. Kigali's position as a regional distribution node depends entirely on pipeline and road connectivity through neighboring territories.
East Africa Refined Petroleum Products Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with coastal storage infrastructure and retail network scale serving as the primary vertical differentiators. The market structure rewards players controlling import terminal access and inland depot positioning, while smaller traders face consolidation pressure from EAC quality compliance costs. Three archetypes dominate: integrated majors with coastal storage dominance, national oil companies with strategic reserve mandates, and independent retailers with localized service station footprints. Competitive moves center on terminal infrastructure partnerships and direct procurement agreements with fleet operators bypassing traditional retail channels.
Within the integrated major tier, TotalEnergies SE and Shell PLC exemplify coastal storage leverage, while Vivo Energy PLC anchors retail distribution archetypes through extensive branded networks. These players occupy positions shaped by infrastructure control rather than product differentiation, with terminal access determining regional throughput allocation. National Oil Corporation of Kenya represents state-backed competition focused on emergency supply security and strategic reserve management, operating under distinct regulatory mandates from private sector counterparts.
| Leading Market Players |
|---|
| TotalEnergies SE |
| Shell PLC |
| Vivo Energy PLC |
| KenolKobil Ltd |
| National Oil Ethiopia PLC |
| PUMA Energy |
| Engen Petroleum |
| National Oil Corporation of Kenya |
| ExxonMobil Corporation |
| Others |
Supply & Pricing Matrix
Forty-five to sixty-day coastal inventory cycles at Mombasa and Dar es Salaam terminals concentrate pricing power among storage-integrated majors while exposing smaller traders to working capital strain during Brent crude volatility spikes. This lead-time structure rewards players with direct terminal access and punishes intermediaries lacking inland depot positioning.
Pricing Analysis
Long-term offtake agreements between coastal storage operators and Northern Corridor fleet operators dominate diesel procurement, compressing spot market liquidity and standardizing price discovery around volume-scaled contracts. Price differentiation rests on sulfur compliance certification and direct terminal access rather than brand premiums. Pricing pressure intensifies as EAC quality mandates force retrofit capital deployment without immediate pass-through mechanisms. Fleet operators exhibit lowest price sensitivity due to operational criticality, while rural retail kerosene demand faces highest elasticity from solar substitution.
Supply Chain Analysis
Just-in-time procurement patterns among landlocked Ugandan and Rwandan industrial consumers contrast with strategic stockpile requirements mandated by Kenya's Energy and Petroleum Regulatory Authority for emergency reserve compliance. Supply concentrates in Kenya's Mombasa-Nairobi axis and Tanzania's Dar es Salaam-Central Corridor, with both countries drawing from Middle Eastern and Indian refinery sources. Single-point terminal vulnerability at Mombasa creates structural risk for regional throughput. Distribution runs through coastal import terminals, inland storage depots, and direct terminal-to-fleet agreements bypassing traditional retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Coastal storage infrastructure operates as a defensive moat in this market, with regulatory-mandated quality upgrades creating switching costs that entrench incumbent positions and erode marginal trader viability.
For Market Incumbents: Compound terminal infrastructure advantage by securing exclusive direct offtake agreements with expanding Northern Corridor fleet operators before competitors complete sulfur-handling upgrades. Accelerate backward integration into hydrotreating capacity to capture margin from EAC low-sulfur diesel mandates. Threat substitution from renewable mini-grids and solar displacement of backup generation demands proactive diesel-to-industrial-fuel pivoting. For New Entrants and Emerging Players: Lead with marine bunkering consolidation plays at Dar es Salaam and Mombasa ports, where fragmented coastal supplier structures offer penetrable white space against integrated majors. Target Ethiopian aviation turbine fuel procurement as National Oil Ethiopia PLC's monopoly shows relaxation signals. Go-to-market angle should emphasize certified quality differentiation and direct airport logistics integration rather than price competition. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational energy majors divesting non-core East African retail networks amid margin compression from fleet disintermediation. Long-term viability frames around infrastructure control rather than volume throughput, with coastal storage and pipeline access commanding premium positioning. Signal to watch is Ethiopian market liberalization pace, which would revalue regional throughput assumptions and depot network utility.| Strategic Initiative | Industry Significance |
|---|---|
| Sulfur-Handling Terminal Upgrade | Captures EAC 50 ppm diesel compliance premium ahead of enforcement deadlines. |
| Direct Fleet Offtake Agreement | Bypasses retail margin compression from Northern Corridor logistics consolidation. |
| Marine Bunkering Consolidation | Aggregates fragmented Dar es Salaam and Mombasa port refueling demand. |
| Strategic Reserve Partnership | Secures public-private slots under Kenya's Energy and Petroleum Regulatory Authority mandates. |
| Ethiopian Aviation Fuel Entry | Positions for National Oil Ethiopia PLC procurement relaxation at Addis Ababa hub. |
Research Methodology
Desk research of customs trade databases, EAC regulatory filings, and petroleum infrastructure project disclosures preceded structured interviews with coastal terminal operators, pipeline engineers, fleet procurement managers, and national energy regulatory officials. Primary fieldwork captured operational constraints around sulfur-handling upgrades and workforce scarcity patterns. Secondary validation drew from Kenya Energy and Petroleum Regulatory Authority quality specifications, Tanzania Energy and Water Utilities Regulatory Authority pricing determinations, and East African Community customs union protocols. Bottom-up terminal throughput estimates triangulated against top-down regional demand projections.
Variance decomposition across product type, end-user segment, distribution channel, and geographic market shaped the analytical framework over the projection horizon. Modeled dimensions included diesel versus jet fuel growth trajectories, transportation versus manufacturing demand concentration, retail versus direct sales channel evolution, and Kenya-Tanzania-Ethiopia-Uganda country clusters. CAGRs derived from segment-level volume build-ups calibrated to infrastructure capacity constraints and regulatory compliance timelines. Forecast inputs incorporated EAC fuel quality harmonization schedules and Ethiopian market opening assumptions.
The analysis sits within stated boundaries; outcomes outside sustained Brent crude price stability, EAC regulatory enforcement consistency, or Ethiopian procurement liberalization would require recalibration. Forecasts reflect documented assumptions regarding infrastructure financing availability and regional logistics corridor deepening. Revision becomes warranted when renewable substitution rates or workforce scarcity thresholds cross materiality levels.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petroleum Products
Spindle Oil Market
Petroleum Products
Saudi Arabia Refined Petroleum Products Market
Petroleum Products
Performance Oil Sales Market
Petroleum Products
West Africa Refined Petroleum Products Market
Petroleum Products
India White Oil Market
Petroleum Products
Southeast Asia Refined Petroleum Products Market
Petroleum Products
Pyrolysis Oil Market
Petroleum Products
Underground Storage Tanks Market
Petroleum Products
Natural Gas Liquid Market
Petroleum Products
Gasoline-Naphtha-Crude-MTBE Market
Petroleum Products
South Africa Refined Petroleum Products Market
Petroleum Products
Marine Minerals Market
Petroleum Products
Petroleum Wax Market
Petroleum Products
Petcoke Market
Petroleum Products
Alkylate Gasoline Market
Petroleum Products
Floating Roof Tank Market