
 Sandblast Valves Market | 2026-2036
Sandblast Valves Market Size, Share, and Industry Trends Forecast 2026-2036
Sandblast Valves Market Analytics
Heavy-duty specification upgrades is reorganizing competitive dynamics across the sandblast valves landscape. Clemco Industries leverages its captive foundry network to control alloy sourcing for high-wear components. Graco sustains technology leadership through precision metering systems that reduce abrasive consumption in automated blast cells. Empire Abrasive Equipment anchors North American distribution through dedicated service centers in industrial corridors.
A sandblast valve is a pressure-rated flow control device, typically constructed from hardened stainless steel or nickel-aluminum bronze with tungsten carbide inserts, designed to meter abrasive media at 90–125 psi in surface preparation and finishing operations. Pneumatic valves command the largest volume share due to their compatibility with existing compressed air infrastructure in manufacturing plants. Stainless steel material grades capture premium margin pools where chemical resistance and extended cycle life justify higher unit costs. Electric valve configurations represent the fastest-growing installation type as programmable logic controllers integrate blast parameters into automated production lines.
OSHA enforces permissible exposure limits for respirable crystalline silica that directly mandate sealed valve designs and dust containment in blast enclosures. EPA hazardous waste regulations govern spent abrasive disposal, pushing operators toward closed-loop systems with precision media flow control. ISO 12944 corrosion protection standards for steel structures specify surface cleanliness grades that require consistent blast pressure delivery. Stakeholders must evaluate valve replacement cycles against total cost of ownership models that incorporate compliance audit frequency and downtime penalties.
Market Dynamics
OSHA silica exposure limits and EPA abrasive media disposal rules are compressing replacement cycles while forcing capital deployment into sealed valve architectures and closed-loop recovery systems across surface preparation operations.
Growth Catalysts
- Aerospace maintenance expansion:Corrosion-resistant valve specifications are proliferating as MRO facilities upgrade blast cabinets for airframe component refurbishment, particularly in Germany's Ruhr industrial cluster.
- REACH chemical compliance:ECHA restrictions on hexavalent chromium coatings are redirecting surface preparation toward mechanical blasting methods that demand precision media flow control.
- Electric valve integration:Programmable logic controllers are displacing pneumatic actuation in automated blast cells, enabling real-time pressure modulation tied to production line sensors.
Market Restraints
- Tungsten carbide supply concentration:Hard-metal insert fabrication depends on Chinese rare earth processing capacity, exposing valve manufacturers to input volatility and export licensing delays.
- Capital intensity of foundry upgrades:In-house alloy casting capabilities require furnace investments that mid-tier suppliers cannot amortize against regional order volumes.
- Substitution by laser ablation:Precision cleaning applications in electronics and medical device manufacturing are bypassing abrasive blasting entirely for non-contact surface preparation.
Strategic Opportunities
- India steel fabrication modernization:BIS certification requirements for structural steel corrosion protection are mandating consistent blast pressure delivery that legacy equipment cannot achieve.
- EU Green Deal remanufacturing:Circular economy directives incentivize component refurbishment over replacement, expanding demand for gentle media flow control in delicate restoration work.
- Digital twin convergence:Valve sensor data integration with predictive maintenance platforms creates aftermarket service revenue streams beyond hardware margins.
Industry Challenges
- ISO 12944 certification timelines:Surface cleanliness grade validation requires documented blast parameter consistency that strains quality assurance staffing in smaller fabrication shops.
- Legacy pneumatic infrastructure integration:Electric valve retrofits demand compressed air line reconfiguration and control system reprogramming that extends installation downtime.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sandblast Valves Market |
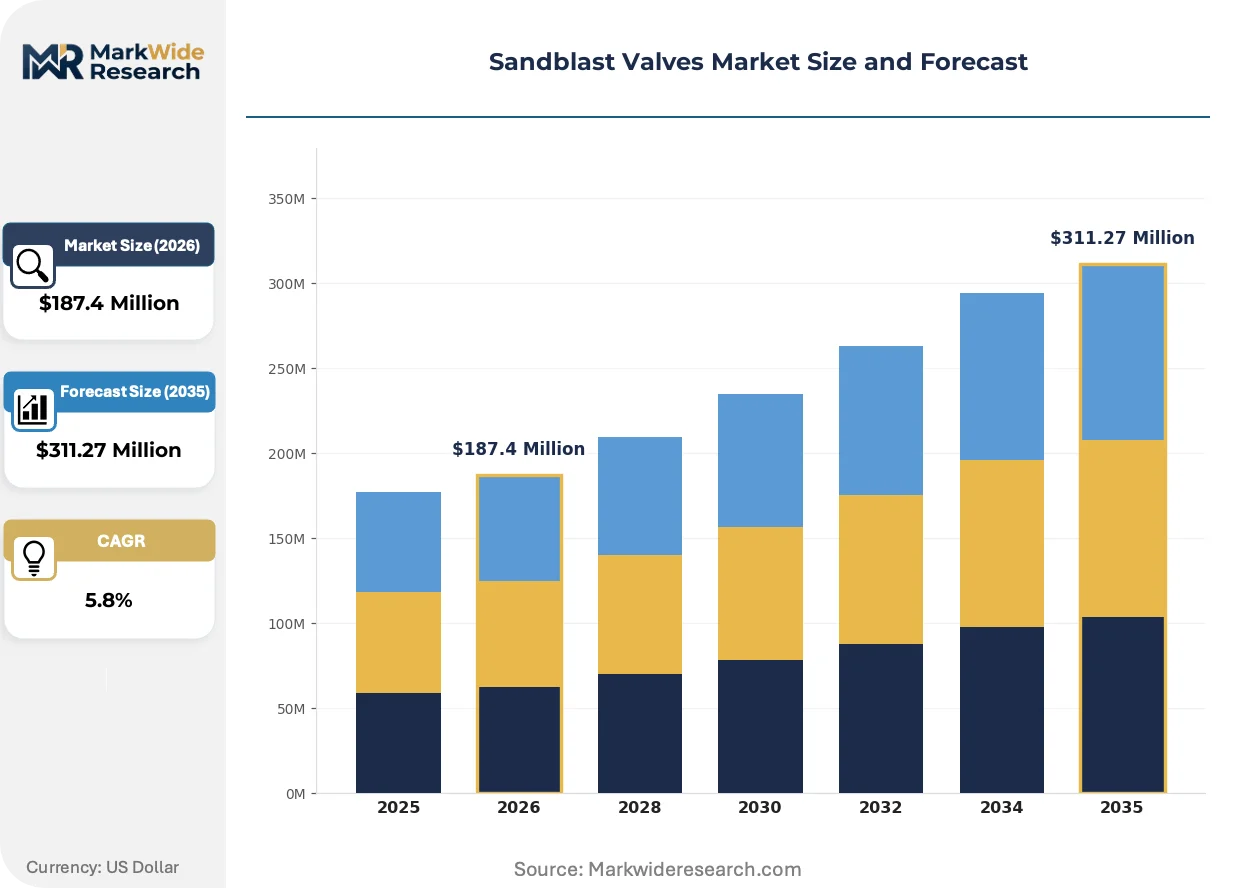
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Standard Valves, Pneumatic Valves, Manual Valves, Electric Valves Material: Stainless Steel, Cast Iron, Brass, Polypropylene Application: Manufacturing, Construction, Automotive, Aerospace Installation: Onshore, Offshore, Fixed, Portable |
| Companies Covered | Graco, Clemco Industries, Empire Abrasive Equipment, Axxiom Manufacturing, ABSS, Schmidt, INDUSCO, Blastquip, Airblast B.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sandblast Valves Market Evolving Landscape
Intelligent media metering and regulatory compliance automation are displacing manual valve adjustment across surface preparation workflows, compressing the viable technology set toward connected, sealed architectures.
Smart valve systems with embedded pressure transducers and edge computing capability are fragmenting the traditional separation between flow control hardware and process monitoring software. Automotive OEMs in Stuttgart and Wolfsburg are piloting these configurations for real-time quality traceability. The technology is fragmenting procurement decisions as buyers now evaluate firmware update policies alongside mechanical specifications.
EPA hazardous waste regulations governing spent abrasive disposal are mandating closed-loop media recovery systems with precision metering to minimize contamination. Blast equipment operators face quarterly compliance audits that penalize uncontrolled media discharge. Electric valve configurations with sealed housings are capturing preference in California and Texas fabrication corridors where enforcement staffing has expanded.
Maintenance contracting is consolidating valve replacement decisions under facility-wide service agreements rather than departmental capital budgets. Third-party MRO providers in Ohio and Pennsylvania are bundling valve inspection, rebuild, and sensor calibration into annual fixed-fee arrangements. This shift is most visible in steel bridge remediation projects where DOT contract terms now specify uptime guarantees that internal maintenance teams cannot underwrite.
Sandblast Valves Market Segmentation
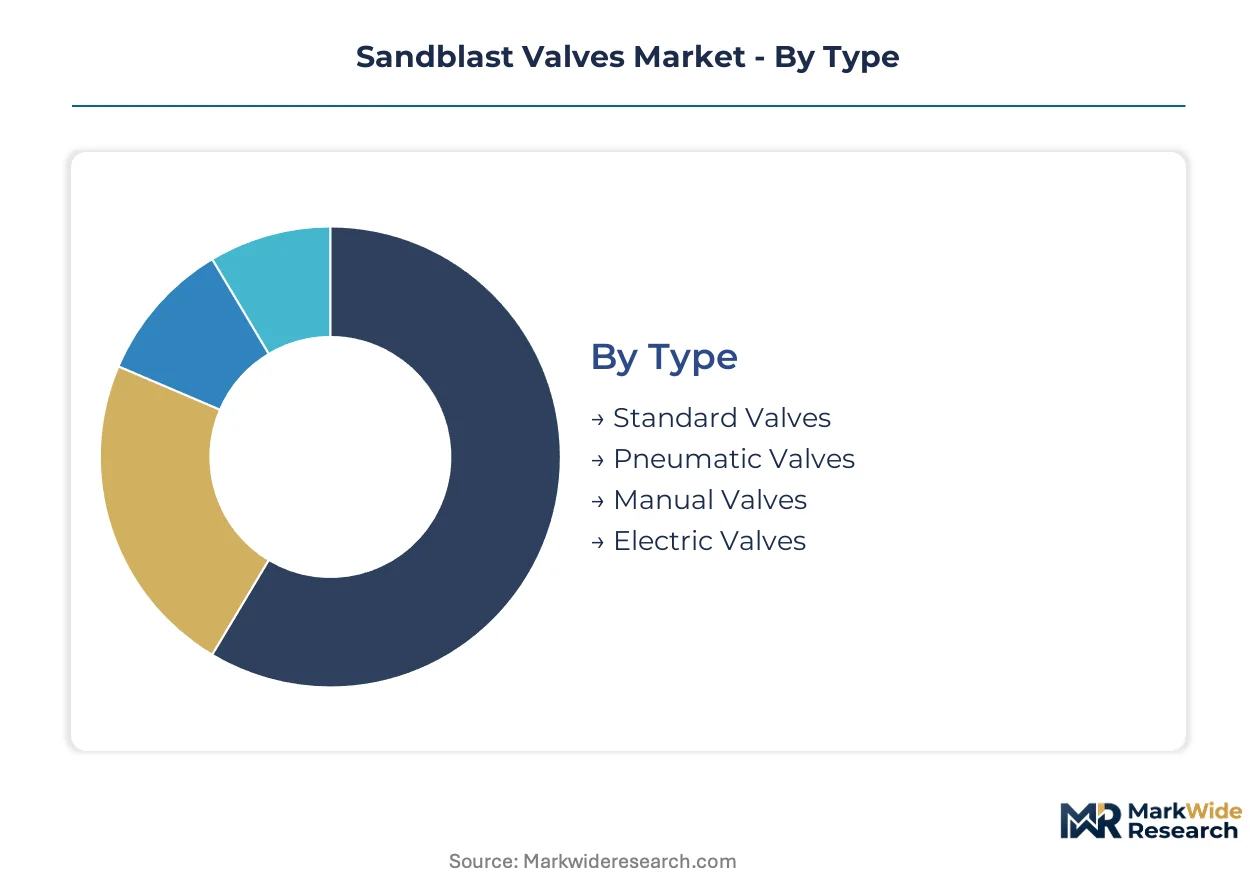
Segmentation in sandblast valves reveals how specification choices cascade through compliance costs and replacement cycles. Procurement decisions increasingly weight total cost of ownership against upfront unit pricing as regulatory enforcement tightens across industrial corridors.
Type:
Premium margin pools concentrate in actuation systems that integrate with automated production infrastructure.
- Pneumatic Valves:Compressed air compatibility dominates existing manufacturing plant infrastructure. Demand concentrates in Germany's Ruhr industrial cluster where automotive and steel fabrication plants modernize surface preparation lines under OSHA silica exposure compliance pressure.
- Electric Valves:Programmable logic controller integration enables real-time pressure modulation tied to production line sensors. Stuttgart and Wolfsburg automotive OEMs pilot these configurations for quality traceability, with sealed housings capturing preference in California and Texas fabrication corridors where EPA enforcement has expanded.
- Standard Valves:Basic flow control specifications serve cost-sensitive maintenance operations in smaller fabrication shops.
- Manual Valves:Direct operator adjustment persists in intermittent-use applications and legacy equipment refurbishment.
The dominant share belongs to Pneumatic Valves, while Electric Valves is closing the gap fastest.
Material:
Alloy selection directly determines corrosion resistance certification eligibility and cycle life in abrasive environments.
- Stainless Steel:Hardened grades with tungsten carbide inserts withstand 90–125 psi abrasive metering. Aerospace MRO facilities specify these for airframe component refurbishment where chemical resistance justifies higher unit costs.
- Cast Iron:Foundry-cast bodies offer economical wear resistance for general manufacturing blast cabinets with shorter replacement intervals.
- Brass:Nickel-aluminum bronze variants balance machinability against media compatibility in moderate-duty surface preparation.
- Polypropylene:Chemical-resistant polymer housings serve specialized applications requiring non-metallic contact surfaces.
Stainless Steel commands the widest specification adoption, though Cast Iron retains volume leadership in price-sensitive procurement.
Application:
End-use verticals stratify by surface cleanliness grade requirements and audit frequency exposure.
- Aerospace:Corrosion-resistant valve specifications proliferate as MRO facilities upgrade blast cabinets for airframe component refurbishment, particularly under ISO 12944 corrosion protection standards.
- Automotive:OEM integration of smart valve systems with embedded pressure transducers fragments procurement toward firmware-evaluated vendor selection.
- Manufacturing:General industrial surface preparation spans the broadest equipment age distribution and compliance maturity spectrum.
- Construction:Steel bridge remediation projects consolidate valve replacement under facility-wide service agreements with uptime guarantees.
Aerospace leads premium specification adoption, while Automotive is expanding most quickly through automated blast cell deployment.
Installation:
Deployment configuration determines sealed architecture requirements and media recovery system integration complexity.
- Fixed:Permanent installations anchor closed-loop media recovery systems with precision metering to minimize contamination under EPA hazardous waste regulations.
- Portable:Mobile blast units serve field remediation where compressed air infrastructure availability constrains actuation choice.
- Onshore:Land-based fabrication facilities face OSHA silica exposure limits that mandate sealed valve designs and dust containment.
- Offshore:Marine environments impose salt corrosion resistance requirements on alloy selection and housing sealing.
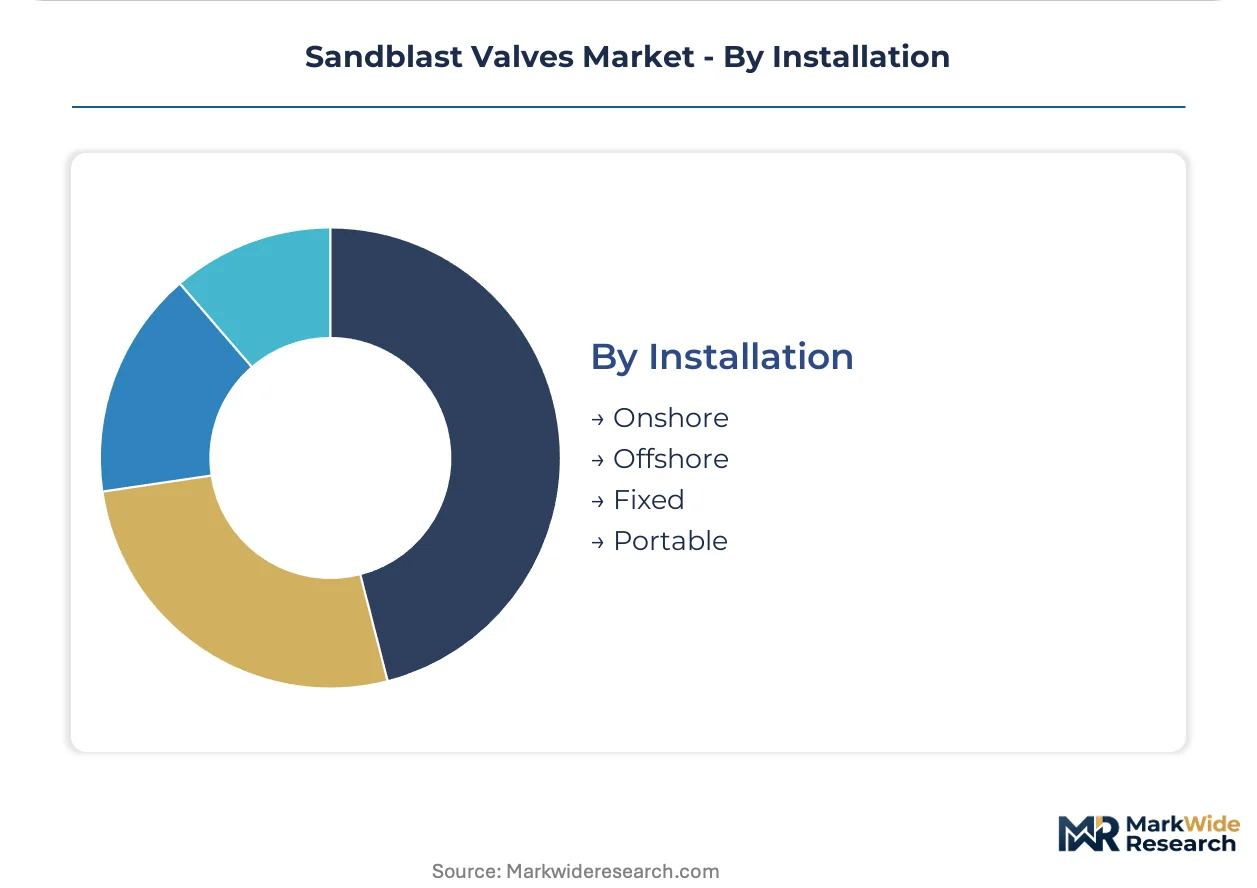
Fixed installations hold the largest installed base, while Portable configurations are gaining share fastest through maintenance contracting consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foundry capacity and alloy processing capability concentrate in industrial corridors where surface preparation equipment manufacturing has historically anchored. Germany's Ruhr cluster and the US Midwest maintain captive supply advantages for hardened valve components.
United States
OSHA silica exposure limits are compressing replacement cycles across fabrication shops in Ohio and Pennsylvania. EPA hazardous waste regulations mandate closed-loop media recovery systems with precision metering. Steel bridge remediation projects in the Midwest consolidate valve procurement under facility-wide service agreements with uptime guarantees.
Germany
REACH chemical compliance redirects surface preparation toward mechanical blasting methods demanding precision flow control. ECHA restrictions on hexavalent chromium coatings accelerate MRO facility upgrades. Stuttgart and Wolfsburg automotive OEMs pilot smart valve configurations for real-time quality traceability.
China
Domestic steel fabrication modernization drives specification upgrades for consistent blast pressure delivery. The country's national environmental regulator tightens abrasive waste discharge standards. Yangtze River Delta manufacturing clusters deploy automated blast cells with programmable logic controller integration.
India
BIS certification requirements for structural steel corrosion protection mandate valve performance that legacy equipment cannot achieve. Central government infrastructure spending accelerates surface preparation line modernization. Maharashtra and Gujarat fabrication hubs expand procurement of sealed valve architectures.
Japan
METI industrial efficiency standards promote precision media metering to reduce abrasive consumption. JIS certification requirements for surface cleanliness grades specify consistent blast pressure delivery. Kansai region automotive suppliers integrate electric valve configurations into automated production lines.
Sandblast Valves Market Competitive Landscape
Concentration sits with integrated manufacturers possessing captive foundry networks and dedicated distribution infrastructure. Three to five specialists control premium specification segments through alloy sourcing advantages and service center density. Mid-tier fabricators compete on regional fulfillment velocity. Dominant competitive moves include backward integration into alloy casting capacity and geographic expansion through dedicated service centers in industrial corridors.
Among North American equipment specialists, Graco and Clemco Industries exemplify the integrated manufacturing archetype through control over critical component supply chains. Empire Abrasive Equipment anchors regional distribution density. German fabricators Schmidt and Airblast B.V. occupy positions within the European precision-engineering tier. Australian specialist ABSS and Chinese manufacturers INDUSCO and Blastquip represent geographic coverage strategies. Axxiom Manufacturing and niche operators complete the competitive matrix.
| Leading Market Players |
|---|
| Graco |
| Clemco Industries |
| Empire Abrasive Equipment |
| Axxiom Manufacturing |
| ABSS |
| Schmidt |
| INDUSCO |
| Blastquip |
| Airblast B.V. |
| Others |
Value Network & Pricing Analysis
Foundry capacity utilization above 85 percent in Germany's Ruhr cluster and the US Midwest reinforces supply-side concentration and establishes price floors for hardened alloy components. Scale economies in captive tungsten carbide processing grant integrated manufacturers pricing power that mid-tier fabricators cannot match against regional order volumes.
Pricing Analysis
OSHA silica exposure limits dictate the pricing tier structure across sandblast valve procurement, separating sealed electric configurations with dust containment from basic pneumatic alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation under ISO 12944 corrosion protection standards and EPA hazardous waste compliance maturity. Cost compression in standard-grade cast iron valves is intensifying because Chinese rare earth export licensing delays inflate tungsten carbide insert costs. Smaller fabrication shops in Ohio and Pennsylvania exhibit the highest price sensitivity, while aerospace MRO facilities in Germany accept premium stainless steel specifications with minimal negotiation.
Supply Chain Analysis
China and Germany anchor tungsten carbide insert fabrication and hardened alloy casting respectively for sandblast valve manufacturing. Component sourcing draws from Chinese rare earth processing capacity, German captive foundry networks, and Indian steel fabrication modernization demand. Single-source vulnerability in Chinese hard-metal supply exposes valve manufacturers to export licensing delays and input volatility. Distribution runs through dedicated service centers in industrial corridors, with third-party MRO providers in the US Midwest bundling inspection and rebuild services into annual fixed-fee arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of in-house alloy casting capabilities and certified foundry capacity separates integrated manufacturers from regional competitors dependent on outsourced component supply. Captive furnace investments and tungsten carbide processing expertise constitute the decisive asset gap in this market.
For Market Incumbents: Consolidate backward integration into alloy sourcing through captive foundry capacity expansion in Germany's Ruhr cluster and the US Midwest. Deepen service center density in industrial corridors to capture maintenance contracting consolidation. Laser ablation substitution in electronics and medical device manufacturing threatens precision abrasive applications; counter through firmware-enabled smart valve differentiation that non-integrated competitors cannot replicate. For New Entrants and Emerging Players: Predictive maintenance platform integration represents an underserved service layer where incumbent hardware manufacturers under-invest in software capabilities. Target India's Maharashtra and Gujarat fabrication hubs, where BIS certification requirements for structural steel corrosion protection outpace legacy equipment performance. Establish go-to-market partnerships with third-party MRO providers bundling valve inspection and sensor calibration into annual service agreements. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors manufacturers with electric valve configurations and programmable logic controller integration capabilities. Long-term viability rests on automated blast cell deployment in automotive OEM supply chains and closed-loop media recovery system mandates under EPA enforcement expansion. Acquisition candidates should demonstrate captive alloy casting capacity and service center presence in at least two industrial corridors. Monitor EPA hazardous waste enforcement staffing levels in California and Texas as the signal indicating acceleration in sealed valve replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Casting | Captive foundry capacity insulates against Chinese tungsten carbide supply volatility and secures margin control. |
| Smart Valve System Development | Embedded pressure transducers and edge computing enable real-time quality traceability for Stuttgart automotive OEMs. |
| Service Center Network Expansion | Dedicated facilities in Ohio and Pennsylvania capture maintenance contracting consolidation in steel bridge remediation. |
| Predictive Maintenance Platform Launch | Sensor data integration creates aftermarket revenue streams beyond hardware margins for facility-wide agreements. |
| Electric Valve Configuration Scale-Up | Sealed housings address EPA enforcement expansion in California and Texas fabrication corridors. |
Research Methodology
Operator-level perspectives from maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with blast equipment operators and valve specification engineers across aerospace MRO facilities, automotive OEMs, and steel fabrication plants. Secondary validation drew from OSHA enforcement records, EPA hazardous waste compliance databases, ISO 12944 certification registries, and customs trade data for alloy component flows. Bottom-up unit economics triangulated against top-down market sizing across pneumatic, electric, standard, and manual valve configurations.
Sensitivity analysis tested forecast robustness across regulatory enforcement intensity scenarios and tungsten carbide supply disruption assumptions. The analytical framework modeled segmentation dimensions including actuation type, material grade, end-use vertical, and installation configuration across the projection horizon. CAGRs were derived from replacement cycle compression under OSHA silica limits and capital deployment patterns into automated blast cells. Industry-specific inputs incorporated EPA audit frequency expansion and REACH chemical compliance redirection toward mechanical blasting methods.
Forecasts assume regulatory continuity in OSHA permissible exposure limits, EPA hazardous waste regulations, and REACH chemical restrictions; material policy shifts would require re-modeling. Specific risks include export licensing delays in Chinese rare earth processing, laser ablation substitution acceleration in precision cleaning applications, and ISO 12944 certification timeline extensions straining quality assurance staffing. Recalibration cycles align with material shifts in enforcement staffing levels, alloy supply availability, and automotive OEM automation deployment rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
North America High Voltage Switchgear Market
Valves
Reciprocating Compressor Components Market
Valves
Middle East and Africa Industrial Valves Market
Valves
GCC and MENA Valves Market
Valves
Bend Restrictors and Stiffeners Market
Valves
Top Drive Systems Market
Valves
Pigging Valves Market
Valves
Float Traps Market
Valves
Fluid Power Cylinder Market
Valves
Global Valves in Oil and Gas Industry Market
Valves
North America Industrial Valves Market
Valves
Fin Tube Market
Valves
Actuators and Valves Market
Valves
Industrial Hydraulic Filters Market
Valves
Tubing Heads Market
Valves
Valve Manifold Box (VMB) Market