
 Flow Computer Market | 2026-2036
Flow Computer Market Size, Share, and Industry Trends Forecast 2026-2036
Flow Computer Market Analysis
Asset-light leasing models for flow measurement infrastructure are reshaping competitive dynamics in the sector. Emerson Electric Co. leverages its extensive rental and service network to place instruments without upfront capital burden on midstream operators. SLB anchors its position through integrated digital platforms that bundle flow computers with reservoir analytics. ABB competes by specializing in Coriolis-based custody transfer systems for LNG applications.
A flow computer is an electronic device that receives signals from flow meters, pressure transmitters, temperature sensors, and densitometers to calculate corrected volumetric or mass flow rates according to standards such as AGA-3, AGA-8, or ISO 5167. It performs real-time compensation for fluid properties and operating conditions to ensure accurate fiscal and allocation measurement in pipeline networks. Electromagnetic and ultrasonic product types dominate installed base volumes, though Coriolis systems command premium positioning in LNG and cryogenic service where direct mass measurement eliminates conversion uncertainty. Smart flow meter technology with embedded edge computing is displacing traditional remote terminal unit architectures, while wireless flow monitoring extends measurement reach to wellpad locations previously excluded by cabling costs.
The EPA enforces greenhouse gas reporting mandates that require continuous emissions monitoring, directly stimulating upgrades to certified flow measurement systems. API standards and NIST traceability requirements create compliance barriers that favor established suppliers with accredited calibration laboratories. Stakeholders must evaluate whether to deploy capital toward in-house metrology capabilities or outsource calibration through third-party service agreements as regulatory stringency intensifies.
Market Dynamics
Smart flow meter technology with embedded edge computing is compressing traditional remote terminal unit architectures, forcing vendors to reposition around software-defined measurement platforms rather than hardware-centric sales models.
Growth Catalysts
- EPA methane monitoring mandates:Greenhouse gas reporting rules in the United States require continuous emissions tracking, compelling pipeline operators to upgrade to certified flow measurement systems with NIST traceability.
- Shale production infrastructure:Permian Basin operators in Texas and New Mexico demand high-accuracy custody transfer systems to handle variable gas compositions from tight oil formations.
- Coriolis direct mass measurement:Cryogenic LNG loading terminals adopt Coriolis-based systems to eliminate fluid property conversion uncertainty in fiscal metering applications.
Market Restraints
- Stainless steel and exotic alloy input costs:Wetted components in cryogenic service require Inconel and titanium grades subject to aerospace and semiconductor demand competition.
- Calibration laboratory concentration:Accredited flow calibration facilities cluster in Germany, the United States, and Japan, creating logistics burdens for operators in Brazil, Nigeria, and Kazakhstan.
- Ultrasonic meter temperature limits:Transducer materials face signal attenuation above 200°C, excluding high-temperature refinery applications where orifice plates persist.
Strategic Opportunities
- Offshore Brazil pre-salt development:Floating production storage and offloading vessels require compact, SIL-rated flow computers for subsea tieback metering at extreme pressures.
- Hydrogen blending in natural gas grids:Hydrogen's altered compressibility and Joule-Thomson coefficients demand recalibrated algorithms and new sensor fusion approaches.
- Asset-light leasing channels:Rental and service-based commercial models reduce upfront capital barriers for midstream operators managing volatile throughput volumes.
Industry Challenges
- Metrology engineering talent scarcity:Universities produce few graduates fluent in AGA-8 equation implementations and PVT property modeling for supercritical fluids.
- Legacy RTU integration complexity:Brownfield sites with 1990s-era SCADA architectures face protocol translation burdens when adding IEC 62591 wireless flow transmitters.
- OIML R117 certification timelines:Pattern approval processes for custody transfer systems stretch 18-24 months, delaying product launches in regulated European markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flow Computer Market |
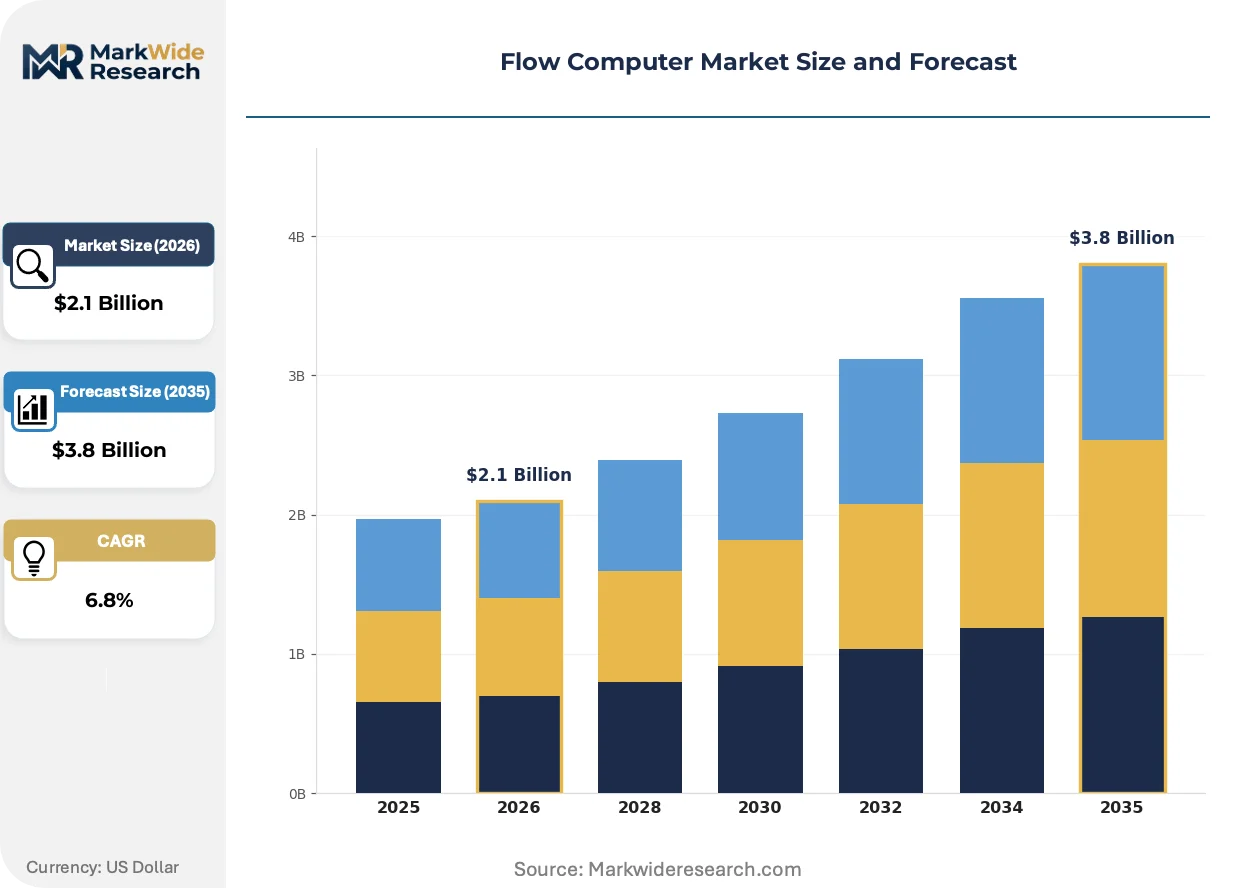
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electromagnetic, Ultrasonic, Coriolis, Positive Displacement Technology: Smart Flow Meters, Wireless Flow Monitoring, Mass Flow Measurement, Data Logging End User: Oil & Gas, Water Management, Food & Beverage, Pharmaceuticals Installation: Onshore, Offshore, Industrial Site, Commercial Facility |
| Companies Covered | Schneider Electric, SLB, Emerson Electric Co., OMNI Flow Computers, Inc., Thermo Fisher Scientific Inc., ABB, Yokogawa Corporation of America, KROHNE Group, Honeywell International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flow Computer Market Emerging Trajectories
Digitalization is collapsing the boundary between flow measurement hardware and cloud-native analytics, creating new competitive arenas around data monetization and predictive maintenance services.
Edge-enabled flow computers are hybridizing signal processing and fiscal calculation within the meter body itself. Midstream operators in North American shale plays deploy these devices to eliminate separate RTU enclosures and reduce wellpad wiring costs. This convergence is hybridizing vendor business models toward subscription software layers atop instrument hardware.
The EPA's greenhouse gas reporting mandates are tightening measurement uncertainty requirements for flare gas and vented emissions. Pipeline operators must install certified thermal mass or ultrasonic systems with continuous self-diagnostics. LNG export terminals on the US Gulf Coast face the steepest compliance burdens as their loading rates directly factor into national emissions inventories.
After-sales service unbundling is fragmenting traditional bundled maintenance contracts. End-users in the Permian Basin now procure calibration and verification services from third-party metrology specialists rather than original equipment manufacturers. This disintermediation is most pronounced among independent producers lacking captive instrument shops.
Flow Computer Market Segmentation
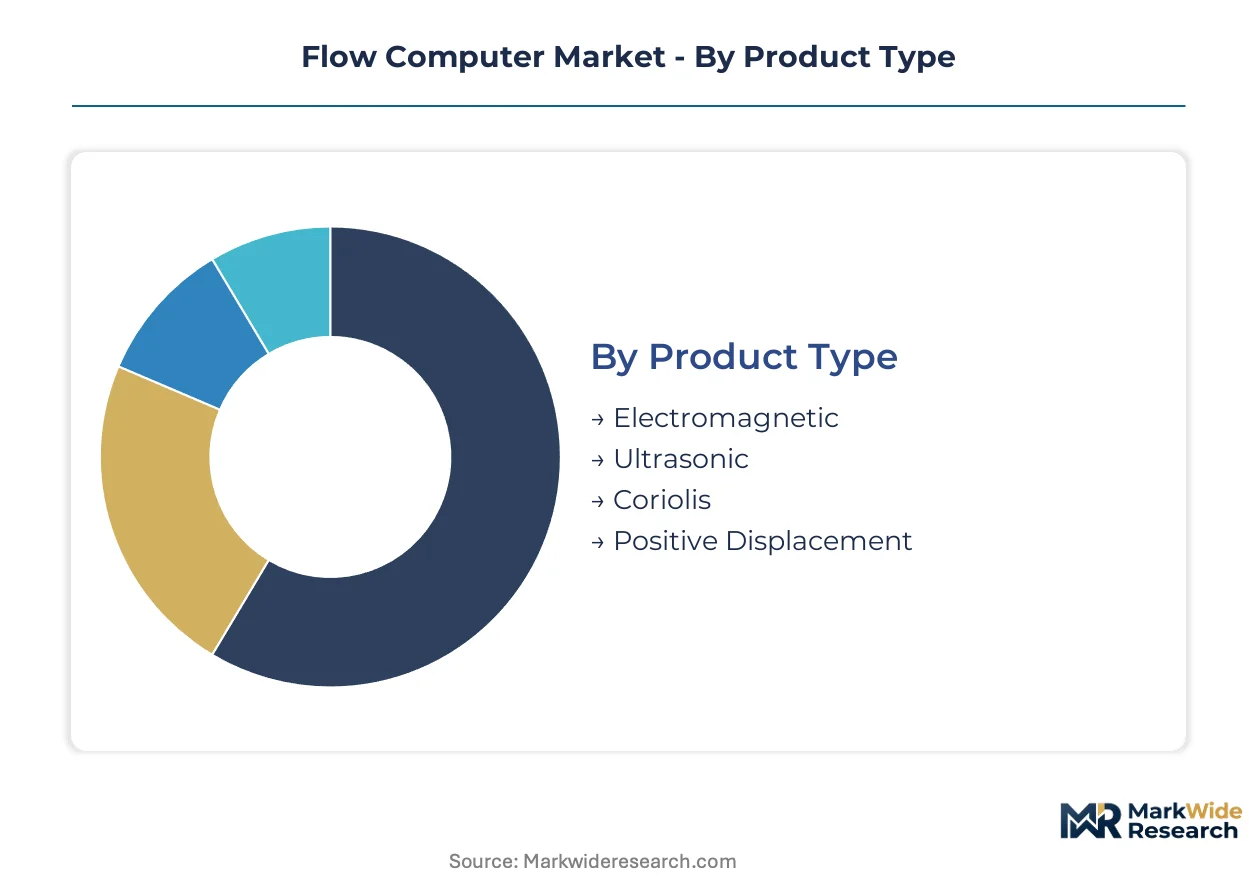
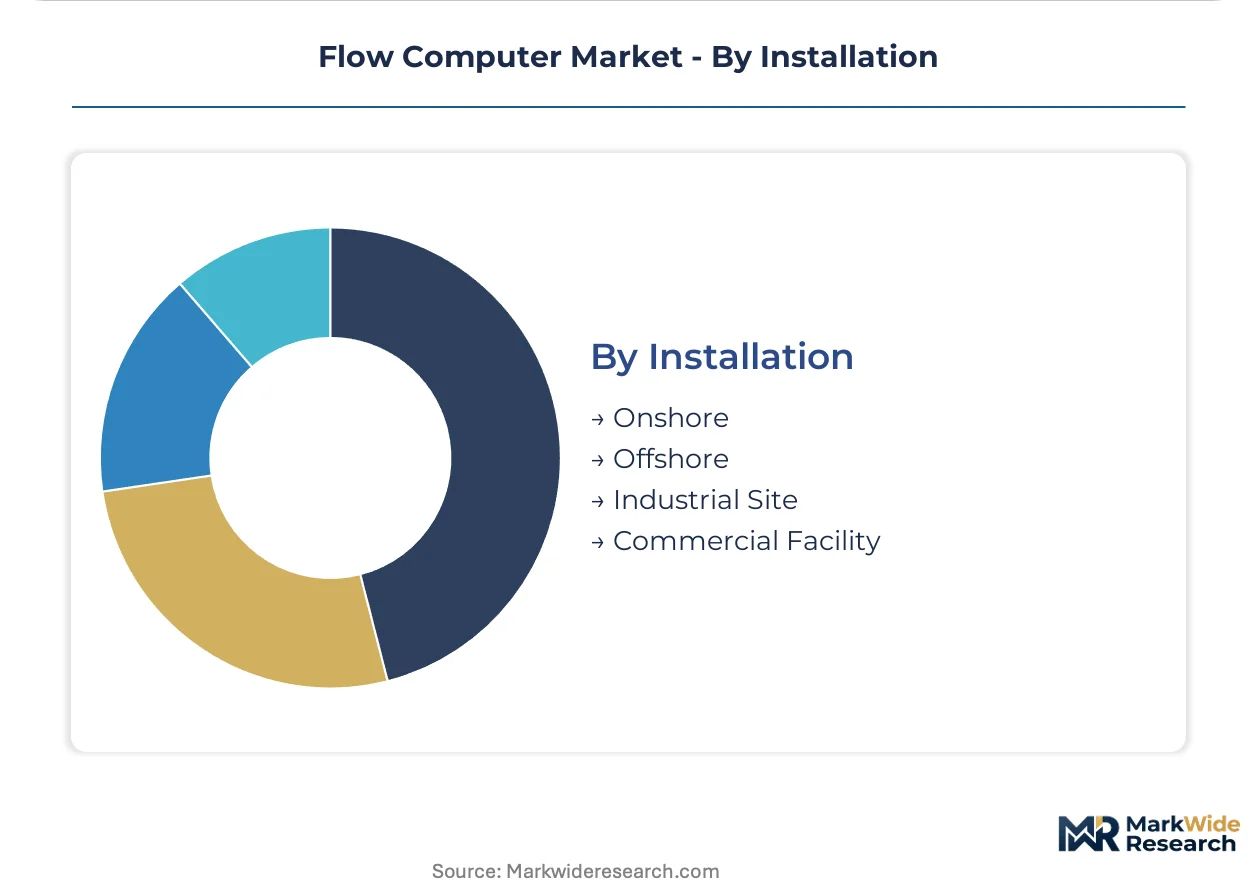
Flow computer procurement patterns diverge sharply across measurement technologies and deployment contexts. Understanding these segment boundaries reveals where hardware margins concentrate versus where service revenues dominate.
Product Type:
Replacement cycles stretch from 8 years for standard electromagnetic units to 15+ years for cryogenic Coriolis systems, creating divergent revenue recognition patterns across installed bases.
- Electromagnetic:These meters measure conductive fluids through Faraday's law of induction, with no moving parts and minimal pressure drop. Water treatment facilities in Germany and municipal utilities across the United States deploy these for custody transfer of treated effluent, driven by tightening EPA discharge monitoring requirements.
- Ultrasonic:Transit-time and Doppler variants send acoustic pulses through the fluid stream to calculate velocity profiles. Pipeline operators in the Permian Basin favor clamp-on configurations for retrofit applications where line shutdown is prohibitively expensive, though transducer temperature limits constrain refinery deployment above 200°C.
- Coriolis:Direct mass measurement via vibrating tube oscillation eliminates fluid property uncertainty in LNG loading terminals.
- Positive Displacement:Oval gear and rotary vane mechanisms dominate refined product terminals with high viscosity fluids.
Electromagnetic meters anchor the volume base while Coriolis systems gain share at the steepest rate.
Technology:
Cost tiers separate capital-intensive hardware purchases from recurring software subscriptions, with hybrid models emerging at the boundary.
- Smart Flow Meters:Embedded edge computing architectures perform fiscal calculations within the meter body itself, eliminating separate RTU enclosures. Midstream operators in Texas shale plays deploy these to reduce wellpad wiring costs and enable real-time anomaly detection through on-device algorithms.
- Wireless Flow Monitoring:IEC 62591 protocol networks extend measurement reach to remote wellpads previously excluded by trenching and cabling economics. Independent producers in New Mexico adopt these for marginal wells where traditional infrastructure payback exceeds field life.
- Mass Flow Measurement:Thermal and Coriolis principles serve hydrogen blending applications where compressibility deviations from natural gas baseline demand direct mass sensing.
- Data Logging:Local storage with batch transmission suits intermittent connectivity environments common in subsea tiebacks.
Smart flow meters dominate capital deployment while wireless monitoring expands most quickly among independent operators.
End User:
Application requirements dictate certification grades, with oil and gas demanding SIL-rated hardware and food processing emphasizing hygienic design standards.
- Oil & Gas:Custody transfer systems require NIST-traceable calibration and AGA-8 equation compliance for supercritical fluid property modeling. EPA methane monitoring mandates compel continuous emissions tracking at compressor stations and storage facilities, with LNG export terminals facing the steepest compliance verification burdens.
- Water Management:Non-revenue water reduction programs drive ultrasonic and electromagnetic adoption for district metering areas. Utilities in Japan deploy battery-powered loggers for leak detection in aging distribution networks.
- Food & Beverage:EHEDG and 3-A sanitary standards govern wetted surface finishes and cleanability protocols.
- Pharmaceuticals:USP Class VI material certifications and SIP/CIP compatibility constrain supplier qualification.
Oil and gas anchors the revenue base while water management climbs the fastest on utility modernization cycles.
Installation:
Geography and hazard classification separate explosion-proof offshore requirements from standard commercial enclosures.
- Onshore:Pipeline metering stations and tank farm loading racks constitute the bulk of installed base, with modular skid fabrication reducing field commissioning time. Permian Basin gathering systems require compact two-phase meters handling variable gas-liquid ratios from tight oil formations.
- Offshore:Floating production storage and offloading vessels demand compact, SIL-rated flow computers for subsea tieback metering at extreme pressures. Pre-salt developments offshore Brazil drive specification for corrosion-resistant alloys in sour service conditions.
- Industrial Site:Refinery and petrochemical complexes specify redundant measurement trains for critical product streams.
- Commercial Facility:Building energy management and district heating substations prioritize cost-optimized thermal mass meters.
Onshore installations anchor the unit volume base while offshore applications command the steepest premium expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German calibration laboratories while US shale operators absorb logistics premiums for rapid field service. Demand asymmetry between these markets shapes vendor capacity allocation and margin structures across the forecast window.
United States
EPA methane monitoring mandates drive replacement cycles at Permian Basin compressor stations and Gulf Coast LNG export terminals. The Bureau of Land Management enforces venting and flaring reduction targets that demand certified thermal mass measurement systems. Houston anchors the vendor service infrastructure, with calibration networks clustering around the Texas-New Mexico shale corridor.
Germany
REACH compliance and F-Gas Regulation enforcement elevate specifications for cryogenic custody transfer systems at Hamburg and Wilhelmshaven LNG import terminals. The Physikalisch-Technische Bundesanstalt maintains Europe's densest accredited flow calibration infrastructure, attracting cross-border testing from Dutch and Polish operators. Bavarian industrial automation suppliers integrate flow computers into district heating substations for municipal utilities.
China
Dual carbon goals and MEE emissions accounting standards compel refinery upgrades in the Yangtze River Delta and Shandong Peninsula. National oil companies deploy ultrasonic systems for West-East pipeline custody transfer stations spanning Gansu and Xinjiang provinces. Shenzhen-based instrumentation firms supply compact flow computers for hydrogen blending pilot projects in the Pearl River Delta.
Brazil
Pre-salt development offshore Rio de Janeiro demands SIL-rated subsea metering for floating production vessels at extreme pressures. ANP regulatory frameworks mandate fiscal measurement accuracy for Libra and Búzios field production allocation. Local content requirements channel procurement through domestic fabrication partnerships in the Macaé industrial cluster.
Saudi Arabia
Aramco Master Gas System expansion drives specification for corrosion-resistant alloy flow computers in sour service conditions. The Saudi Standards, Metrology and Quality Organization enforces custody transfer certification aligned with OIML R117 patterns. Jubail industrial city concentrates fabrication capacity for downstream petrochemical integration projects.
Flow Computer Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying calibrated sensor modules and algorithm licenses. Market structure consolidates around three global industrial conglomerates with captive metrology laboratories, while regional specialists occupy niche certification segments. Strategic archetypes separate hardware-anchored vendors from software-defined platform operators and third-party calibration service providers. Competitive moves concentrate on backward integration into exotic alloy supply chains and geographic expansion of accredited laboratory networks.
Among diversified industrial conglomerates, Schneider Electric, Emerson Electric Co., and ABB occupy positions spanning hardware fabrication through cloud analytics layers. These entities exemplify platform-scale archetypes with integrated calibration infrastructure and multi-protocol software stacks. Regional specialists including OMNI Flow Computers, Inc. and Yokogawa Corporation of America represent focused architectural approaches targeting specific custody transfer standards or geographic certification requirements.
| Leading Market Players |
|---|
| Schneider Electric |
| SLB |
| Emerson Electric Co. |
| OMNI Flow Computers, Inc. |
| Thermo Fisher Scientific Inc. |
| ABB |
| Yokogawa Corporation of America |
| KROHNE Group |
| Honeywell International Inc. |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on Inconel and titanium suppliers for cryogenic wetted components determines both the premium tier spreads for Coriolis systems and the geographic clustering of fabrication capacity around aerospace-grade alloy mills in Germany, Japan, and the United States.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on NIST-traceable certification grade and SIL safety integrity ratings, with LNG export terminals absorbing the steepest premiums. Cost compression in the standard electromagnetic tier is intensifying because independent producers in the Permian Basin now unbundle after-sales service from hardware procurement. Midstream operators with volatile throughput volumes exhibit the highest price sensitivity, while offshore pre-salt developers in Brazil demonstrate the lowest due to non-negotiable SIL requirements.
Supply Chain Analysis
Exotic alloy feedstock draws from mills in Germany, Japan, and the United States, with Inconel grades subject to competing aerospace and semiconductor demand. Wetted components for cryogenic service rest on titanium sponge from Ukrainian and Russian sources, plus precision-machined sensor housings from Swiss and German machine shops. Single-source vulnerability concentrates in accredited flow calibration facilities clustered in Germany, the United States, and Japan. Distribution runs through authorized service networks anchored in Houston, Singapore, and Rotterdam, with third-party metrology specialists disintermediating traditional OEM maintenance contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The flow computer market is recovering from a cyclical trough driven by deferred shale infrastructure investment during the 2020-2022 period. EPA methane monitoring mandates are now forcing replacement cycles that compress payback periods for upgraded custody transfer systems.
For Market Incumbents: Pre-empt software-defined measurement platform displacement by embedding fiscal calculation algorithms directly into smart meter firmware. Defend against third-party calibration disintermediation by captive supply of accredited laboratory capacity in the Permian Basin and Brazil pre-salt corridors. Channel control through asset-light leasing models reduces customer switching incentives.
For New Entrants and Emerging Players: Wireless flow monitoring adoption gaps in marginal New Mexico wellpads present white-space entry points where traditional infrastructure payback exceeds field life. Hydrogen blending pilot projects in the Pearl River Delta offer specification influence before standards crystallize. Partner with Shenzhen-based instrumentation firms for compact flow computer co-development targeting sub-$50k wellpad economics.
For Investors and Strategic Acquirers: Regional specialists with OIML R117 pattern approvals and captive metrology laboratories represent the most defensible acquisition archetype as regulatory stringency intensifies. Long-term viability rests on backward integration into exotic alloy supply chains rather than hardware commoditization exposure. Watch for ANP regulatory enforcement tightening in Brazil as the inflection signal for offshore SIL-rated system demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Exotic Alloys | Captive Inconel supply insulates margins from aerospace demand competition in cryogenic tiers. |
| Accredited Laboratory Network Expansion | PTB-recognized calibration capacity in Houston and Macaé reduces logistics premiums for Permian and pre-salt operators. |
| Software-Defined Measurement Platform Launch | Edge-enabled fiscal calculation within meter bodies eliminates separate RTU enclosures for shale wellpads. |
| Hydrogen Blending Algorithm Development | Recalibrated compressibility models for natural gas grids capture pilot project specification influence. |
| Asset-Light Leasing Channel Buildout | Rental service networks reduce upfront capital barriers for midstream operators managing volatile throughput. |
Methodological Framework
Cross-validation between primary interviews with custody transfer engineers, SCADA integration specialists, and metrology laboratory directors anchors the qualitative findings against secondary validation from EPA greenhouse gas reporting filings, API standards documentation, and OIML pattern approval databases. Bottom-up triangulation aggregates individual facility upgrade timelines across Permian Basin compressor stations and Gulf Coast LNG terminals, while top-down calibration benchmarks against Bureau of Land Management venting reduction targets and ANP fiscal measurement mandates.
Calibration against historical replacement cycles for electromagnetic versus Coriolis systems informs the analytical framework across the projection horizon. Segmentation dimensions modeled include measurement technology type, deployment context, certification grade, and regional regulatory cluster. CAGRs derive from facility-level capital expenditure tracking and vendor order backlog analysis. Industry-specific forecast inputs incorporate EPA enforcement intensity scenarios and pre-salt development timelines offshore Brazil.
Practitioners should monitor OIML R117 certification timeline extensions and REACH compliance cost escalations for early signals of product launch delays and margin compression. Forecasts reflect assumptions regarding shale production plateau timing and hydrogen blending standardization trajectories. Cross-checking against FERC pipeline construction permit data and ANP production allocation reporting is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Pneumatic Positioner Market
Valves
Safety Valve Test Benches Market
Valves
Valve Manifold Box (VMB) Market
Valves
Railway Emergency Valves Market
Valves
US Water & Wastewater Valves Market
Valves
Blow - Off Valves Market
Valves
Valve Grinder Market
Valves
Reciprocating Compressor Components Market
Valves
India Industrial Valves Market
Valves
Global Valves in Oil and Gas Industry Market
Valves
Global Valve Positioners Market
Valves
APAC Valves Market
Valves
Industrial Valves Market
Valves
Three Way Ball Valve Market
Valves
Degassing Valves Market
Valves
Motorized Valves Market