
 South America Battery Energy Storage System Market | 2026-2036
South America Battery Energy Storage System Market Size, Share, and Industry Trends Forecast 2026-2036
South America Battery Energy Storage System Market Analytics
Chile's renewable energy mandate for utilities is expanding procurement pipelines for large-scale storage. AES Andes S.A. anchors utility-scale project development across the Andean corridor. BYD Co Ltd leverages integrated cell-to-system manufacturing to compete on delivered cost. Enel S.p.A. sustains a dominant position through distributed energy resource management platforms.
A battery energy storage system comprises electrochemical cells, power conversion systems, and thermal management hardware assembled into containerized or building-integrated units designed to absorb, store, and dispatch electrical energy on demand. Lithium-ion phosphate configurations dominate utility-scale installations due to cycle stability above four thousand cycles at eighty percent depth of discharge. Utility-scale application segments capture the majority of capital deployment, while commercial and industrial units exhibit faster installation velocity as behind-the-meter peak shaving spreads among Brazilian manufacturers. Flow battery technology occupies niche positions in long-duration configurations where daily cycling exceeds eight hours.
Brazil's ANEEL regulates grid connection standards and remuneration frameworks that determine project economics for storage co-located with wind and solar assets. Chile's Ministry of Energy and SEC enforce technical norms for battery installation in seismic zones and salar-adjacent environments. Argentina's national electricity regulator shapes market access through renewable energy auction terms. Stakeholders must monitor how evolving capacity payment mechanisms and frequency regulation market designs alter investment timelines across the continent.
Market Dynamics
Utility-scale solar-plus-storage procurement in Chile's Atacama corridor is compressing project development timelines and forcing equipment suppliers to localize assembly capacity. Brazil's distributed generation framework is simultaneously expanding behind-the-meter installations among industrial off-takers.
Growth Catalysts
- ANEEL's grid modernization mandates:Brazil's national electricity regulator requires transmission operators to incorporate storage for frequency regulation, creating mandatory procurement pools for battery integrators.
- Lithium carbonate supply proximity:Argentina's salar extraction clusters in Catamarca and Jujuy provinces enable domestic cell manufacturing feedstock, reducing import dependency for regional assemblers.
- Chile's renewable energy auctions:The Ministry of Energy's tender mechanisms now include storage co-location requirements, mandating four-hour discharge capacity for winning solar and wind bids.
Market Restraints
- Lithium price volatility:Carbonate and hydroxide contract fluctuations on the Shanghai Metals Exchange directly impact lithium iron phosphate pack economics, squeezing integrator margins.
- Seismic engineering requirements:Chile's SEC enforces battery rack anchoring standards for Zone 3 earthquake territories, adding structural steel costs that inflate installed system prices.
- Lead-acid residual demand:Telecommunications backup power in remote Andean installations continues specifying flooded lead-acid cells, delaying lithium-ion penetration in stationary applications.
Strategic Opportunities
- Colombia's underpenetrated grid:The Andean nation's transmission-constrained Caribbean coast presents greenfield storage deployment potential for solar curtailment mitigation.
- Hybrid inverter convergence:Power electronics combining PV string inversion with bidirectional DC-AC conversion are collapsing balance-of-plant costs for co-located projects.
- Peru's mining sector electrification:Remote extraction operations in the Peruvian Andes are specifying containerized microgrids with battery buffers to displace diesel gensets.
Industry Challenges
- Thermal management engineering scarcity:Qualified HVAC designers capable of sizing liquid-cooled battery enclosures for salar-adjacent ambient conditions command premium compensation, constraining project staffing.
- Multi-standard certification timelines:Systems must sequentially secure IEC 62619 cell safety, UL 9540A fire propagation, and local grid code approvals, extending pre-commercialization intervals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Battery Energy Storage System Market |
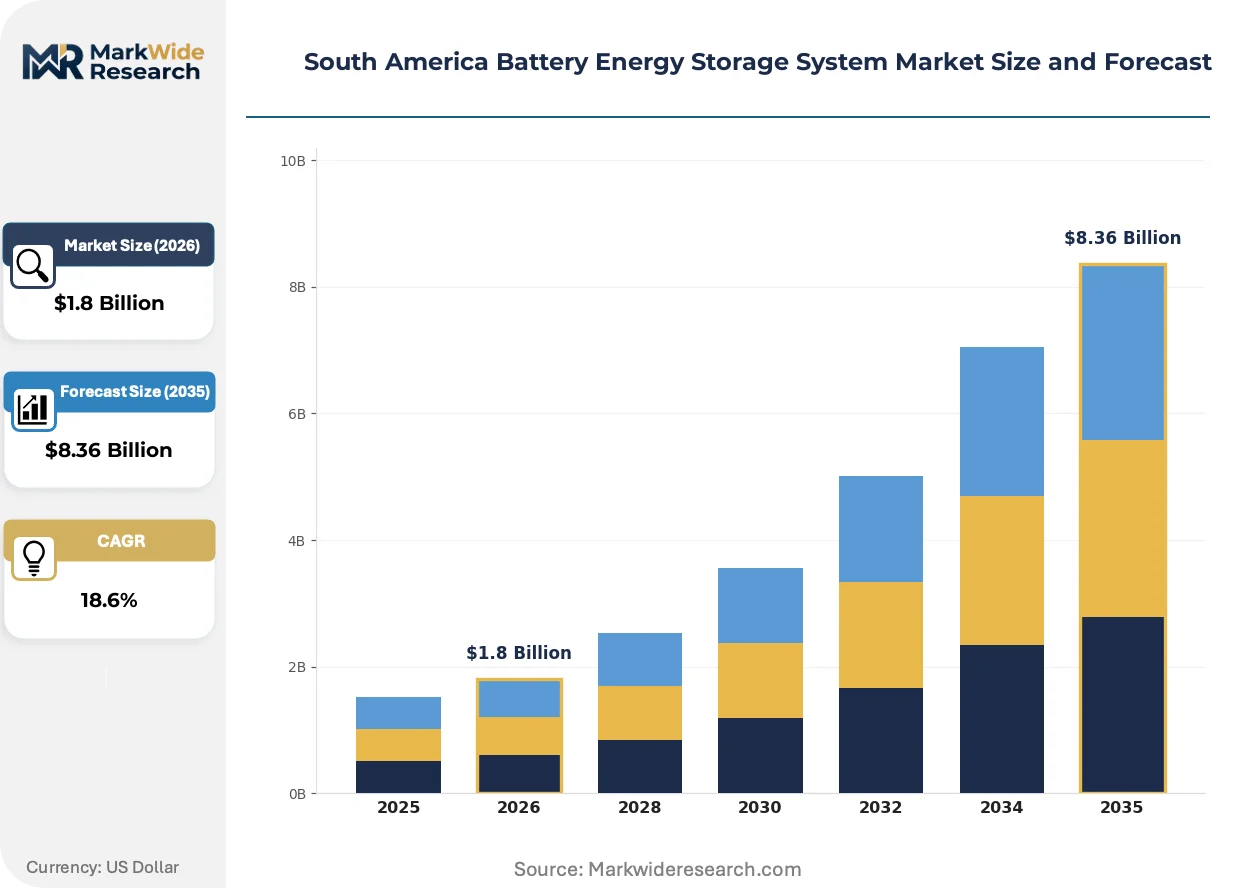
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Lithium-ion, Lead-acid, Flow Batteries, Sodium-sulfur Application: Utility-scale, Commercial, Industrial, Residential End User: Utilities, Renewable Energy Providers, Manufacturers, Corporations Capacity: Below 1 MW, 1-5 MW, 5-20 MW, Above 20 MW |
| Companies Covered | Enel S.p.A., AES Andes S.A., BYD Co Ltd, Engie SA, LG Energy Solution, AES Gener S.A., EnerSys, Saft Groupe SA, Acumuladores Moura S.A., Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Battery Energy Storage System Market Evolving Landscape
Solid-state electrolyte research is migrating from laboratory validation toward pilot manufacturing lines, while artificial intelligence-based predictive maintenance algorithms are embedding into battery management system firmware. These developments are compressing operational expenditure forecasts for asset owners.
Lithium metal anode technology paired with sulfide-based solid electrolytes is converging with silicon nanowire cathode architectures to enable energy densities exceeding four hundred watt-hours per kilogram. Chilean utility procurement teams are evaluating these configurations for long-duration seasonal shifting applications. The structural consequence is a potential displacement of conventional lithium-ion for eight-to-twelve hour discharge use cases.
Brazil's ANEEL has enacted Resolution 1,000 establishing remuneration frameworks for distributed storage providing ancillary services to the national interconnected system. Industrial consumers in Minas Gerais and São Paulo states are leveraging this mechanism to monetize peak shaving capacity. The regulation most directly affects commercial and industrial segment economics, where engineering procurement construction firms are now bundling financing with hardware supply.
Power purchase agreement structures are unbundling energy and capacity payments, enabling offtakers to contract storage-as-a-service without capital ownership. Brazilian automotive parts manufacturers in the ABC Paulista industrial corridor are adopting this model to manage demand charges. The shift is most visible among heavy electricity users seeking balance sheet preservation while securing price certainty.
South America Battery Energy Storage System Market Segmentation
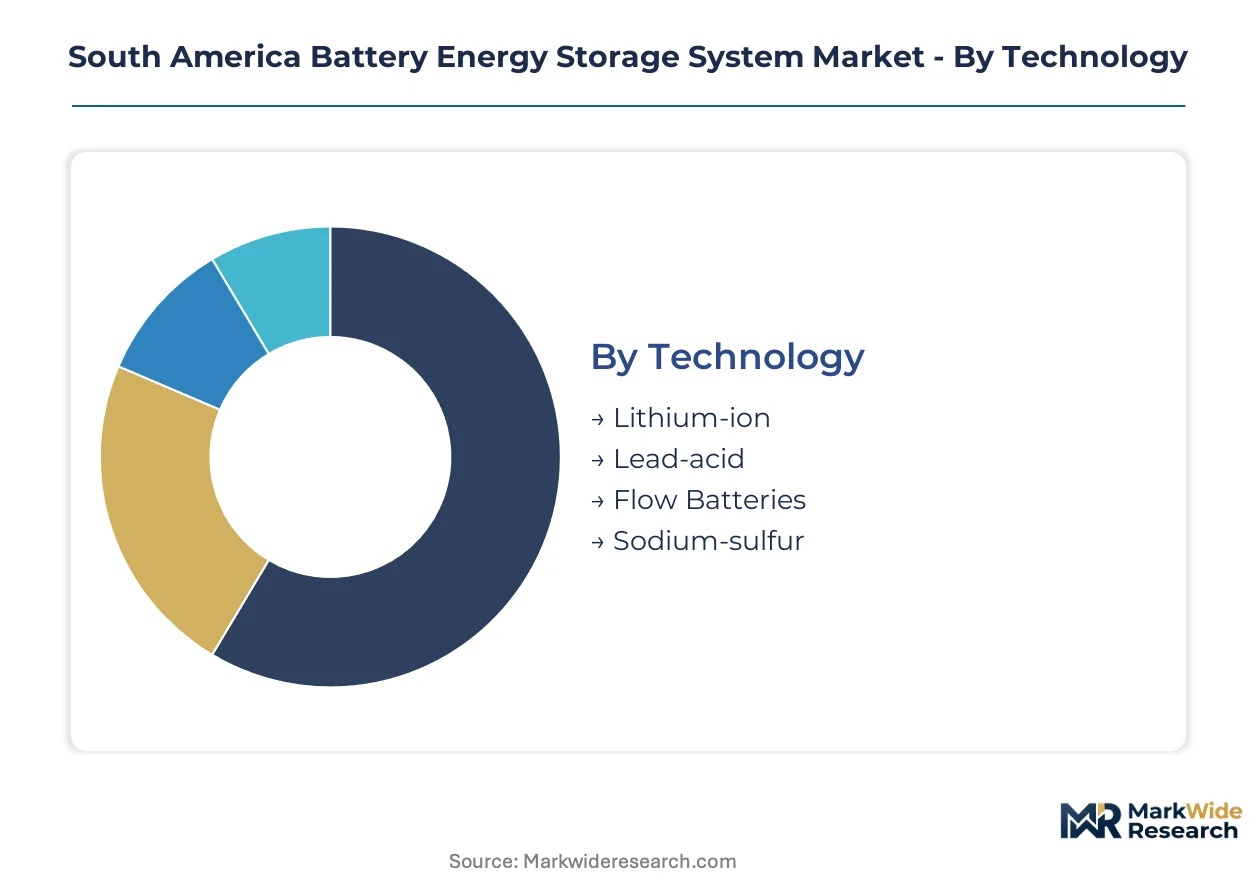
Technology selection and capacity sizing in South American battery storage deployments hinge on local lithium supply proximity, seismic engineering constraints, and auction-mandated discharge duration requirements. Procurement patterns diverge sharply between Chile's utility-scale solar corridor and Brazil's industrial behind-the-meter installations.
Technology:
Cell chemistry selection pivots on cycle stability requirements, local feedstock access, and installed cost targets across varying discharge durations.
- Lithium-ion:Lithium iron phosphate dominates utility-scale procurement due to cycle stability exceeding four thousand cycles at eighty percent depth of discharge. Chile's Atacama solar-plus-storage corridor concentrates demand for four-hour discharge configurations mandated by Ministry of Energy auction terms.
- Flow Batteries:Vanadium redox configurations occupy long-duration niches where daily cycling exceeds eight hours for seasonal shifting applications. Argentine salar-adjacent projects evaluate these systems for extended discharge without lithium price exposure.
- Lead-acid:Flooded cells persist in remote Andean telecommunications backup installations where capital constraints override cycle efficiency priorities.
- Sodium-sulfur:High-temperature chemistry sees limited pilot deployment for grid stabilization in transmission-constrained zones requiring compact energy density.
Lithium-ion leads on scale; flow batteries lead on momentum for duration extensions beyond eight hours.
Application:
Deployment scale determines balance-of-plant complexity, regulatory jurisdiction, and financing structure availability.
- Utility-scale:Containerized installations above twenty megawatts serve grid stabilization and renewable firming under ANEEL frequency regulation mandates. Brazilian transmission operators procure these systems through mandatory modernization pools.
- Industrial:Behind-the-meter peak shaving spreads among São Paulo and Minas Gerais manufacturers leveraging ANEEL Resolution 1,000 remuneration frameworks for ancillary services provision.
- Commercial:Mid-scale systems address demand charge management for retail and office facilities in Brazilian metropolitan load centers.
- Residential:Distributed units remain nascent outside premium off-grid installations in remote Patagonian and Andean settlements.
Utility-scale captures deployment volume; industrial applications climb fastest on regulatory enablement.
End User:
Off-taker category shapes procurement risk allocation, performance guarantee requirements, and operational integration complexity.
- Utilities:AES Andes and Enel Chile anchor procurement for renewable firming under auction-mandated storage co-location requirements. These entities prioritize bankable warranties and localized service networks.
- Renewable Energy Providers:Solar and wind developers integrate storage to meet Chilean tender discharge duration obligations and Brazilian grid connection standards.
- Manufacturers:Automotive parts producers in ABC Paulista corridor adopt storage-as-a-service models through unbundled power purchase agreements preserving balance sheet capacity.
- Corporations:Mining sector electrification drives containerized microgrid specifications in Peruvian Andes and Chilean northern regions displacing diesel generation.
Utilities dominate capital deployment; renewable providers gain share fastest on auction mechanism expansion.
Capacity:
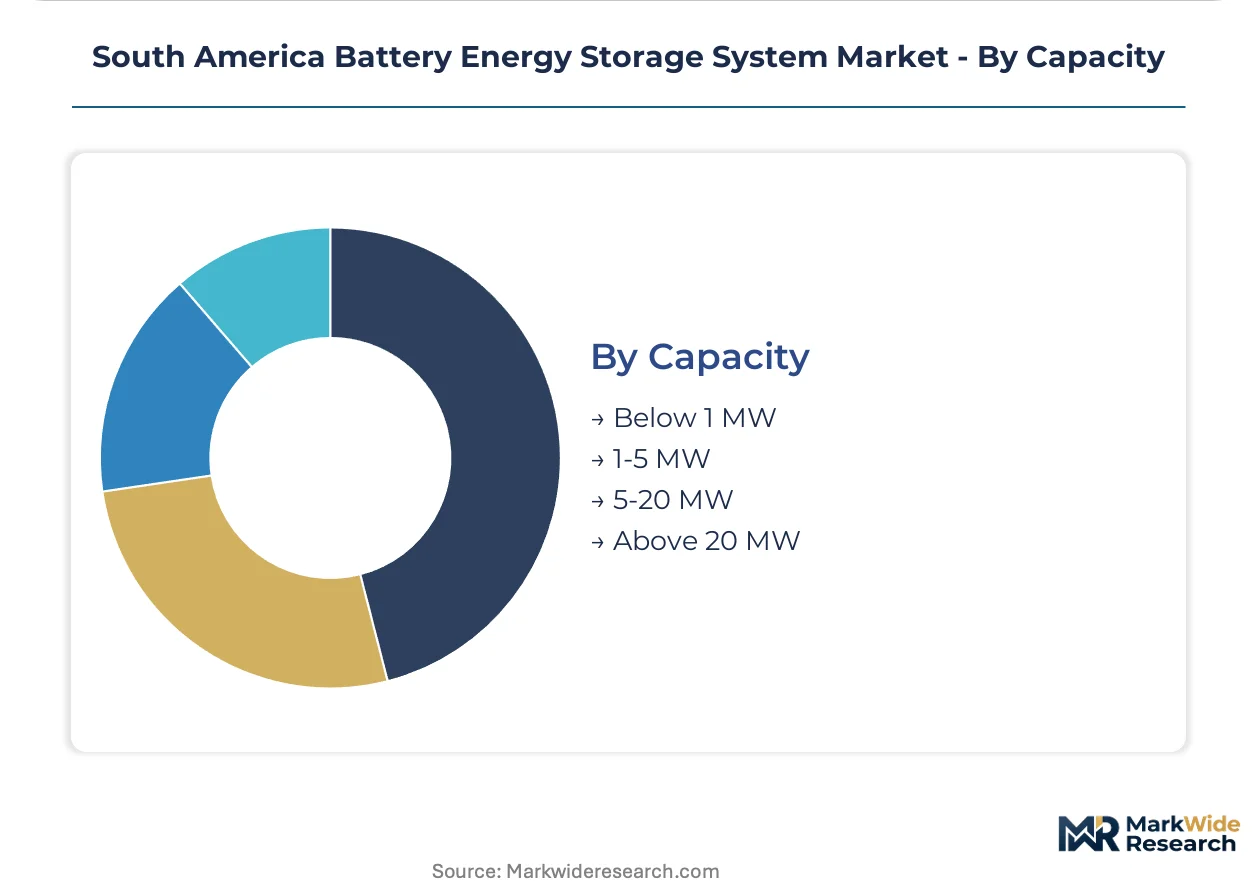
System scale thresholds determine containerization feasibility, thermal management architecture, and grid interconnection voltage class.
- Above 20 MW:Utility-scale installations require liquid-cooled enclosures and seismic Zone 3 anchoring compliance under Chilean SEC standards. These systems aggregate multiple megapack configurations for solar-plus-storage corridors.
- 5-20 MW:Mid-scale deployments serve industrial microgrids and smaller utility substations with air-cooled or hybrid thermal management reducing engineering complexity.
- 1-5 MW:Commercial and light industrial applications favor standardized containerized units with rapid installation protocols.
- Below 1 MW:Distributed commercial and residential segments employ building-integrated or skid-mounted configurations with simplified permitting pathways.
Above 20 MW leads on installed capacity; 5-20 MW expands most quickly on mining sector electrification demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent pools concentrated in São Paulo, Santiago, and Buenos Aires anchor project development capacity across the continent. Local workforce density determines execution velocity for utility-scale installations.
Brazil
ANEEL's grid modernization mandates drive transmission operator procurement for frequency regulation services. Resolution 1,000 establishes remuneration frameworks enabling industrial consumers to monetize ancillary services. São Paulo and Minas Gerais industrial corridors host behind-the-meter peak shaving deployments among automotive parts manufacturers.
Chile
The Atacama Desert solar-plus-storage corridor concentrates utility-scale demand under Ministry of Energy auction terms mandating four-hour discharge capacity. SEC enforces Zone 3 seismic anchoring standards for battery rack installations. Northern mining regions specify containerized microgrids displacing diesel generation.
Argentina
Catamarca and Jujuy province salar extraction clusters enable domestic lithium carbonate feedstock for regional cell assemblers. National electricity regulator auction mechanisms reshape market access terms for renewable-plus-storage bids. Buenos Aires engineering firms coordinate procurement for Patagonian wind firming projects.
Colombia
Transmission-constrained Caribbean coast conditions create greenfield storage deployment potential for solar curtailment mitigation. The national mining and energy planning unit evaluates grid flexibility investments. Barranquilla and Cartagena load centers present commercial and industrial behind-the-meter opportunities.
Peru
Remote Andean mining electrification drives containerized microgrid specifications with battery buffers replacing diesel gensets. Ministry of Energy and Mines regulations shape off-grid power system standards. Cerro de Pasco and Ancash extraction operations anchor demand for ruggedized thermal management systems.
South America Battery Energy Storage System Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the South America battery storage landscape. Integrated cell-to-system manufacturers face project developers and power electronics specialists in tender processes. Three archetypes dominate: vertically integrated Asian cell producers, regional utility affiliates with development expertise, and European energy majors with financing platforms. Competitive intensity centers on localization commitments and long-term service network density.
Within the utility-affiliate tier, AES Andes S.A. and AES Gener S.A. exemplify developers leveraging parent-company balance sheet capacity for auction participation. Enel S.p.A. occupies a position spanning both utility-scale procurement and distributed energy resource management. BYD Co Ltd represents the integrated manufacturing archetype with cell-to-system cost structures. These anchors illustrate how competitive positioning depends on capital access, local regulatory relationships, and manufacturing scale rather than technology differentiation alone.
| Leading Market Players |
|---|
| Enel S.p.A. |
| AES Andes S.A. |
| BYD Co Ltd |
| Engie SA |
| LG Energy Solution |
| AES Gener S.A. |
| EnerSys |
| Saft Groupe SA |
| Acumuladores Moura S.A. |
| Others |
Value Network & Pricing Analysis
Utility procurement concentration in Chile's Atacama corridor and Brazil's transmission modernization pools anchors contract-based long-term offtake pricing with volume-scaled discounts. This buyer archetype dominance compresses integrator margins while rewarding localized assembly commitments.
Pricing Analysis
Project-based pricing with unbundled energy and capacity payments structures procurement for utility-scale deployments. Price differentiation hinges on IEC 62619 certification tier and seismic engineering compliance grade. Cost compression in lithium iron phosphate pack economics is intensifying because carbonate contract volatility on the Shanghai Metals Exchange feeds directly into integrator bids. Industrial behind-the-meter buyers in São Paulo exhibit highest price sensitivity; mining sector offtakers in Peru accept premium positioning for ruggedized thermal management.
Supply Chain Analysis
Qualified HVAC designers and battery rack anchoring specialists command premium compensation in Santiago and São Paulo manufacturing clusters. Cell production draws from Chinese and South Korean cathode active material suppliers, with Argentine salar carbonate reducing import dependency for regional assemblers. Single-source vulnerability concentrates in power electronics semiconductors. Distribution runs through EPC contractors bundling financing with hardware supply for utility-scale corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on hybrid inverter convergence collapsing balance-of-plant costs and solid-state electrolyte pilots enabling premium-tier positioning for long-duration applications.
For Market Incumbents: Extend service network density into Catamarca and Jujuy provinces to capture lithium supply proximity advantages. Deepen backward integration into thermal management hardware to offset qualified engineering scarcity premiums. Counter flow battery entrants in eight-hour discharge niches by accelerating solid-state pilot timelines.
For New Entrants and Emerging Players: Begin with Colombia's transmission-constrained Caribbean coast where solar curtailment mitigation demand outpaces established supplier presence. Target mining electrification microgrids in Peru's Cerro de Pasco region with containerized offerings displacing diesel gensets. Leverage storage-as-a-service financing structures to bypass capital ownership barriers among Brazilian automotive parts manufacturers.
For Investors and Strategic Acquirers: European energy majors with financing platforms are the most active acquirer in this space, seeking project development pipelines over manufacturing assets. Long-term viability favors vertically integrated cell-to-system producers with captive lithium carbonate access. Watch Chilean Ministry of Energy auction term extensions for seasonal shifting duration requirements as inflection indicator for solid-state displacement timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Buildout | Localized assembly plants in Brazil reduce ANEEL grid code compliance costs for integrators. |
| Power Purchase Agreement | Unbundled energy and capacity structures enable mining sector storage-as-a-service adoption. |
| Technology Licensing | Hybrid inverter IP partnerships collapse balance-of-plant costs for solar-plus-storage developers. |
| Backward Integration into Storage | Upstream control over lithium carbonate feedstock insulates Argentine assemblers from Shanghai price volatility. |
| Green Certification Program | SEC seismic compliance certification unlocks Chilean Zone 3 utility procurement pools. |
Research Methodology
Direct dialogue with utility planning officers, EPC contractors, battery integrators, and mining sector energy managers combined with secondary validation from ANEEL regulatory filings, Chilean Ministry of Energy auction documentation, and Argentine salar production reports. Bottom-up and top-down triangulation cross-checks project pipeline databases against equipment supplier shipment disclosures.
Top-down market sizing anchors country-level regulatory mandates and auction capacity allocations, while bottom-up builds from named project development pipelines. Segmentation models technology chemistry, application scale, end-user category, and discharge duration requirements across the projection horizon. CAGR derivation incorporates lithium price elasticity coefficients and seismic engineering cost premiums specific to Chilean installations.
Several conditions sit outside the modeled scope, including solid-state electrolyte manufacturing scale-up timelines and potential ANEEL frequency regulation remuneration revisions. Forecasts reflect assumptions on auction mechanism continuity and carbonate supply chain stability. Material deviation in Chilean tender discharge duration mandates or Argentine export policy shifts warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Management System
North America Battery Management System Market
Battery Management System
Middle-East and Africa Battery Energy Storage System Market
Battery Management System
AC Coupled Solar Battery System Market
Battery Management System
Advanced Energy Storage Systems Market
Battery Management System
Asia-Pacific Battery Energy Storage System Market
Battery Management System
Smart Battery Maintainer Market
Battery Management System
Automotive Battery Management System Market
Battery Management System
Europe Electric Vehicle Battery Management System Market
Battery Management System
India Battery Energy Storage Systems Market
Battery Management System
Battery Fuel Gauge Market
Battery Management System
China Electric Vehicle Battery Thermal Management System Market
Battery Management System
Automotive Lithium-Ion Battery Management System Market
Battery Management System
Electric Vehicle Battery Management System Market
Battery Management System
Latin America Battery Energy Storage System Market
Battery Management System
Energy Storage Technologies Market
Battery Management System
Battery Energy Management System Market