
 US Sand Control Systems Market | 2026-2036
US Sand Control Systems Market Size, Share, and Industry Trends Forecast 2026-2036
US Sand Control Systems Market Outlook
Specialized completion engineering talent is reorganizing how sand control technologies reach tight-oil formations. Baker Hughes Company leverages its integrated well construction portfolio to dominate offshore mechanical solutions in the Gulf of Mexico. Halliburton Company anchors onshore market presence through its broad gravel pack and frac pack service footprint across Texas and North Dakota. Weatherford International differentiates with expandable screen technologies that reduce rig time in extended-reach laterals.
Sand control systems encompass downhole hardware and chemical treatments designed to prevent formation sand production while maintaining hydrocarbon flow rates, typically employing wire-wrapped screens, pre-packed gravel, or resin-coated proppants rated for temperatures exceeding 300°F and differential pressures above 5,000 psi. Mechanical solutions lead the technology segment due to proven reliability in high-volume Gulf of Mexico wells, while smart systems represent the fastest-growing category as operators integrate real-time pressure and sand detection sensors to optimize drawdown limits. Gravel packs remain the largest product type by installed base, though frac packs gain share in Permian and Eagle Ford completions where high-strength proppant conductivity proves critical.
EPA methane emissions regulations and BSEE well integrity standards shape product design requirements, pushing operators toward more durable screen metallurgies and tighter annular pack specifications that reduce remedial workover frequency. OSHA silica exposure limits affect surface handling procedures for gravel pack operations, particularly in West Texas basins where windborne particulate risks concentrate. Stakeholders must monitor how evolving EPA greenhouse gas reporting rules for offshore platforms redirect capital toward sand control systems that minimize formation damage and extend well life without intervention.
Market Dynamics
Permian Basin operators are forcing a recalibration of sand control economics as extended-reach laterals demand higher-conductivity gravel packs and real-time monitoring systems that extend well life without workover interventions.
Growth Catalysts
- EPA Methane Emissions Rules:Tightening completion standards under EPA regulations are accelerating deployment of durable screen metallurgies and annular pack specifications that reduce remedial frequency in Gulf of Mexico and onshore Texas operations.
- Frac Pack Technology:High-strength proppant conductivity requirements in Permian and Eagle Ford unconventional wells are pulling gravel pack upgrades across Texas shale plays where formation damage minimization drives completion design.
- West Texas Silica Handling:OSHA silica exposure enforcement in Midland-Odessa basins is standardizing surface handling automation for gravel pack operations, reducing windborne particulate risks and operational downtime.
Market Restraints
- Specialized Metallurgy Costs:Chrome-alloy and super-duplex screen materials required for high-temperature, high-pressure Gulf of Mexico wells carry 40-60% cost premiums over carbon steel alternatives, compressing margins for marginal field developments.
- Gulf Coast Fabrication Concentration:Downhole screen manufacturing and gravel pack service capacity clusters along the Texas-Louisiana corridor, creating hurricane exposure and logistics bottlenecks during peak completion seasons.
- Resin-Coated Proppant Substitution:Chemical consolidation treatments are displacing mechanical gravel packs in shallow, low-rate wells where temperature and pressure ratings permit simpler completion architectures.
Strategic Opportunities
- North Dakota Bakken Expansion:Underpenetrated sand control deployment in Williston Basin unconventional wells offers whitespace as operators address proppant flowback in high-stress, high-drawdown completion designs.
- Smart System Convergence:Integration of fiber-optic pressure sensing with expandable screen technologies enables real-time drawdown optimization, creating premium service tiers for extended-reach laterals in the Delaware Basin.
- IRA Manufacturing Credits:Domestic content incentives under the Inflation Reduction Act are redirecting capital toward US-based screen fabrication and proppant coating facilities serving Permian and Appalachia demand.
Industry Challenges
- Completion Engineering Talent Scarcity:Specialized gravel pack and frac pack design expertise concentrates among legacy Gulf of Mexico service hands, creating recruitment bottlenecks as Permian operators scale unconventional deployments.
- BSEE Well Integrity Certification:Offshore platform qualification timelines for new screen metallurgies and packer systems extend 18-24 months, delaying technology adoption in deepwater fields.
- Legacy SCADA Integration:Real-time sand detection sensors face protocol mismatches with existing offshore platform control systems, requiring custom middleware development that fragments vendor ecosystems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Sand Control Systems Market |
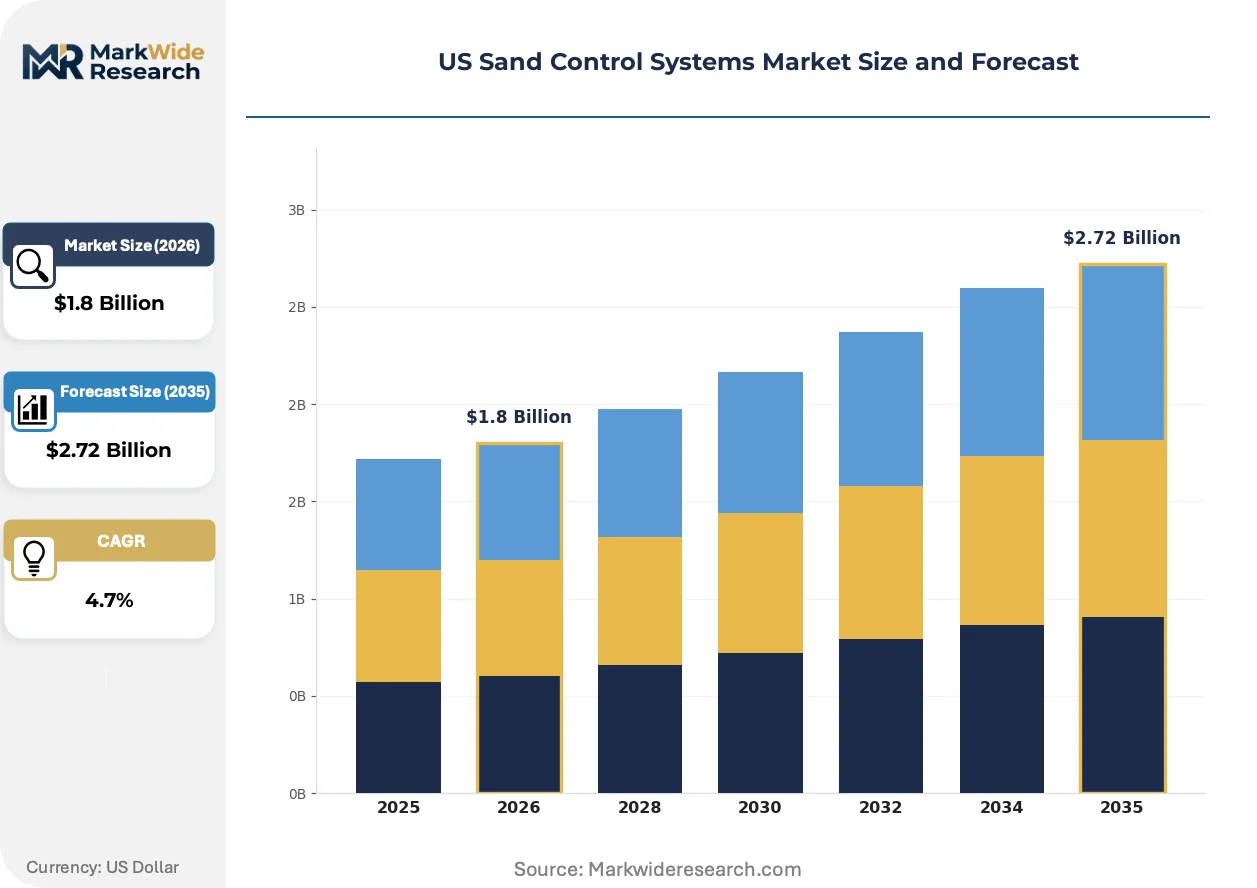
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gravel Packs, Frac Packs, Screened Systems, Chemical Stabilizers Technology: Mechanical Solutions, Chemical Solutions, Hybrid Technologies, Smart Systems End User: Oil & Gas Companies, Service Providers, Mining Operations, Heavy Industries Application: Offshore Operations, Onshore Operations, Production Wells, Exploration Wells |
| Companies Covered | Schlumberger Limited, Baker Hughes Company, Halliburton Company, Weatherford International, Oil States International, National Oilwell Varco, Welltec International, Tendeka, Packers Plus Energy Services, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Sand Control Systems Market Strategic Shifts
Downhole hardware is converging with digital sensing layers that transform sand control from passive barrier systems into actively managed production optimization tools.
Downhole fiber-optic pressure and sand detection arrays are miniaturizing to fit within expandable screen annuli without restricting flow area. Permian operators are piloting these systems in 15,000-foot laterals where conventional gauge placement fails. This miniaturization is compressing the distinction between mechanical sand control and intelligent completion architectures, forcing service companies to recombine hardware and software competencies.
EPA greenhouse gas reporting rules for offshore platforms are mandating tighter methane leak detection and repair protocols that extend to wellhead and packer integrity. BSEE is incorporating these standards into facility safety case reviews, affecting sand control system specification for new Gulf of Mexico developments. Deepwater operators are responding by specifying premium metallurgy and redundant barrier designs that reduce intervention frequency and associated emissions.
Integrated service contracting is consolidating procurement of screens, gravel, pumping, and real-time monitoring under single-vendor accountability structures. Large Permian independents are displacing fragmented, commodity-based sourcing that separated hardware from execution. This concentration is most visible in Midland Basin operations where pad development economics favor bundled pricing and guaranteed production outcomes over unit-rate competition.
US Sand Control Systems Market Segmentation
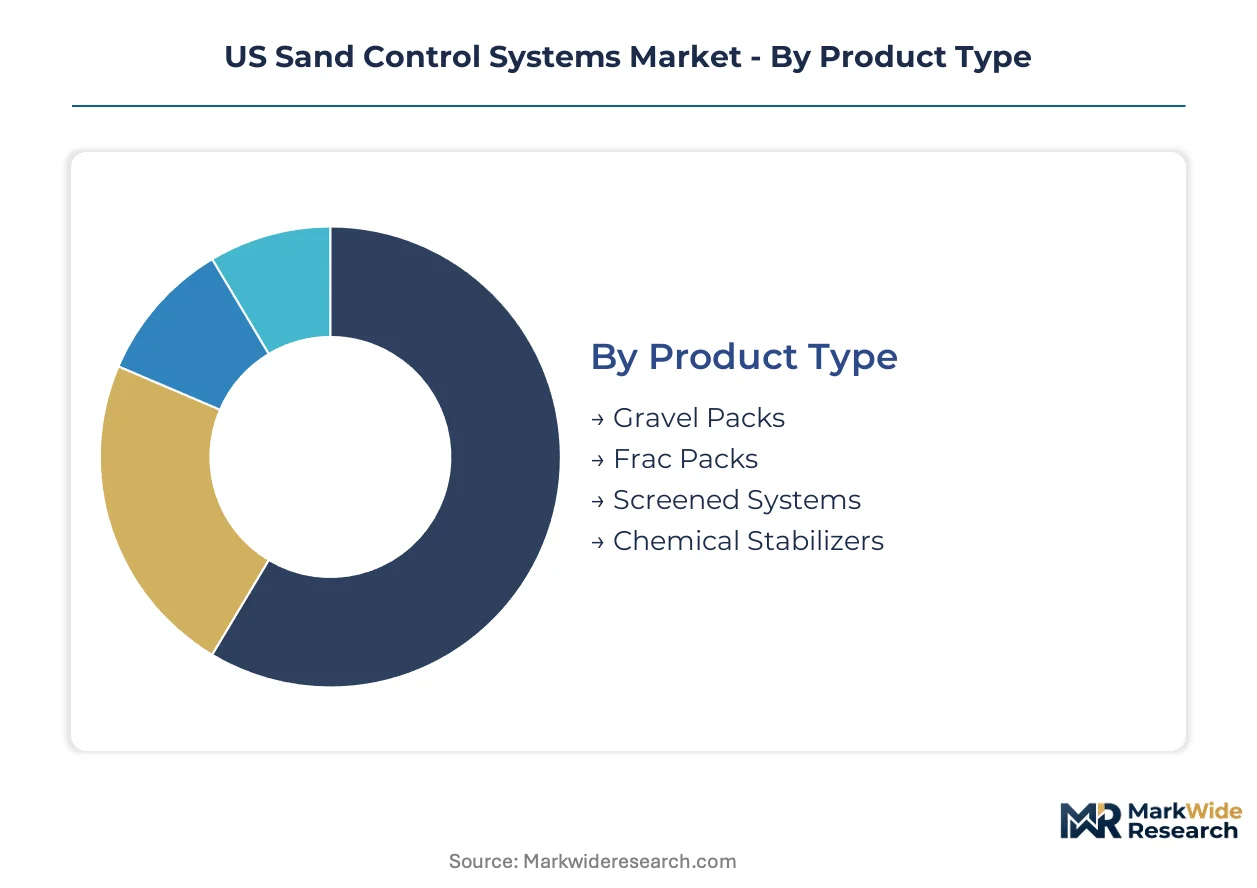
Sand control procurement in US hydrocarbon basins splits across four distinct category axes, each reflecting different technical risk profiles and capital deployment patterns. Product type and technology segmentation reveal where service margins concentrate, while end-user and application splits expose purchasing power dynamics between integrated operators and independent producers.
Product Type:
Premium gravel and proppant systems command the widest service margins, particularly where high-temperature ratings and conductivity specifications justify specialized metallurgy.
- Gravel Packs:Conventional annular packing with pre-sized gravel surrounding wire-wrapped screens remains the installed base leader across Gulf of Mexico shelf assets and Permian conventional completions. Texas operators favor these systems for proven reliability in high-volume producers where formation sand production risks justify upfront capital intensity.
- Frac Packs:Hybrid gravel-fracture treatments using high-strength proppant slurries dominate unconventional well completions in the Permian and Eagle Ford where fracture conductivity must coexist with sand exclusion. Delaware Basin independents are standardizing these designs for 15,000-foot laterals where drawdown optimization requires integrated fracture and sand control engineering.
- Screened Systems:Standalone wire-wrapped or pre-packed screens without gravel annulus serve lower-rate, lower-risk completions where cost minimization outweighs redundancy.
- Chemical Stabilizers:Resin-coated proppants and formation consolidation treatments occupy shallow, low-temperature niches where mechanical hardware economics fail.
The dominant share belongs to Gravel Packs, while Frac Packs is closing the gap fastest.
Technology:
Mechanical reliability standards set by BSEE for Gulf of Mexico installations create margin protection for established hardware suppliers against chemical substitution threats.
- Mechanical Solutions:Wire-wrapped screens, expandable screens, and gravel pack hardware represent the revenue core, with super-duplex and chrome-alloy metallurgies required for high-pressure, high-temperature Gulf of Mexico deepwater wells commanding substantial premiums over carbon steel alternatives.
- Smart Systems:Fiber-optic pressure sensing and real-time sand detection integrated within screen annuli are expanding most quickly in Permian extended-reach laterals where conventional gauge placement fails and drawdown optimization justifies sensor capital.
- Chemical Solutions:Resin consolidation and surface-treatment chemistry competes on cost in marginal well reactivations and shallow conventional assets.
- Hybrid Technologies:Combined mechanical-chemical approaches blend expandable screens with resin-coated proppants for intermediate applications.
Mechanical Solutions retains the largest revenue footprint, though Smart Systems is gaining share fastest among new capital commitments.
End User:
Integrated oil companies concentrate purchasing power through multi-year, multi-basin service agreements that compress unit margins in exchange for volume guarantees.
- Oil & Gas Companies:Majors and large independents in the Permian and Gulf of Mexico drive specification standards and technology adoption timelines through integrated drilling and completion programs.
- Service Providers:Contract pumpers and completion specialists purchase consumables and rental equipment for bundled service execution across Texas and North Dakota shale plays.
- Mining Operations:Limited sand control demand from geothermal and water injection applications in Southwestern mineral extraction.
- Heavy Industries:Niche geothermal and industrial water well applications with minimal market presence.
Oil & Gas Companies account for the dominant procurement volume, while Service Providers are consolidating purchasing influence through integrated contracting models.
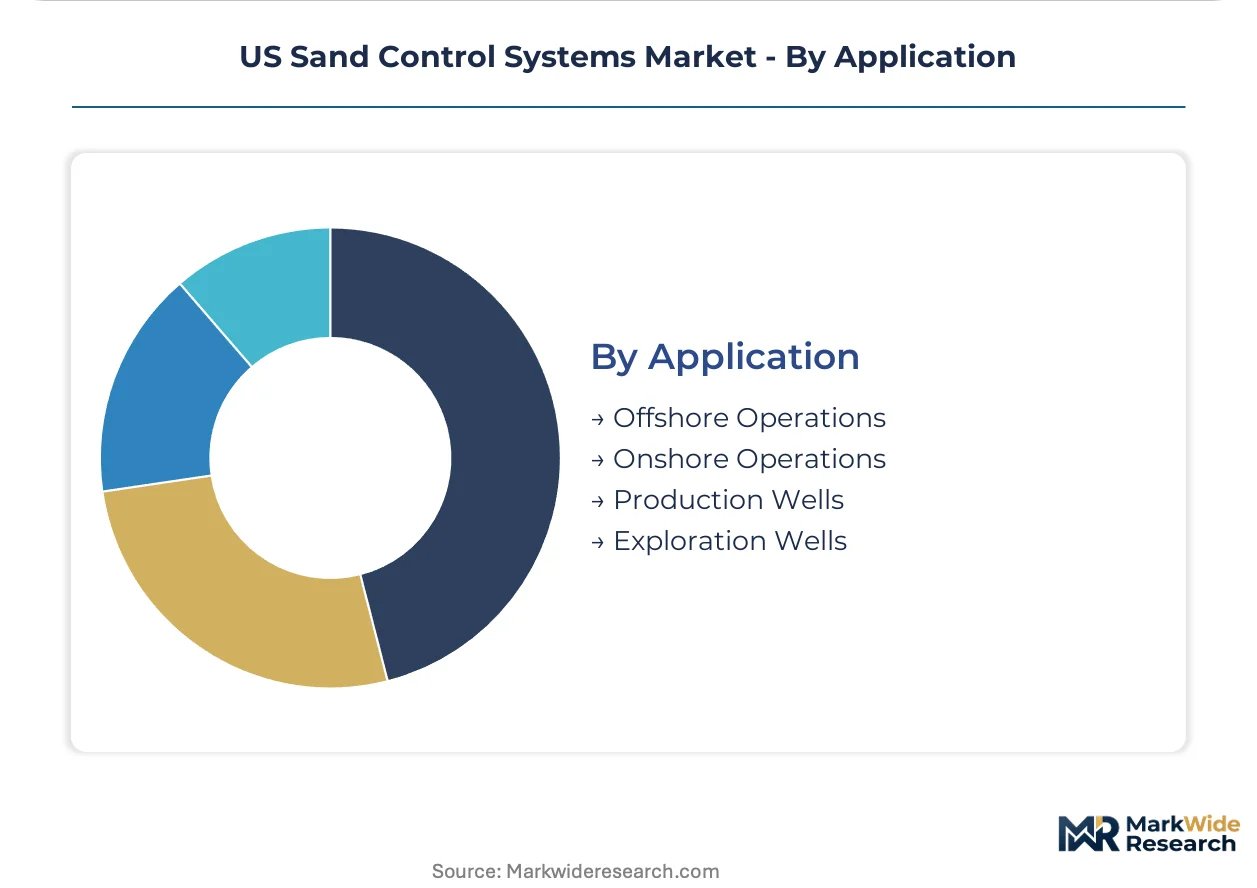
Application:
Offshore platform economics favor capital-intensive, intervention-avoidant designs that amortize premium hardware costs over extended production horizons.
- Offshore Operations:Gulf of Mexico deepwater and shelf developments demand redundant barrier designs, premium metallurgy, and BSEE-certified systems where workover costs exceed hardware premiums by an order of magnitude.
- Onshore Operations:Permian, Eagle Ford, and Bakken unconventional drilling programs prioritize cost-efficient frac packs and expandable screens that balance conductivity with sand exclusion across multi-well pad developments.
- Production Wells:Brownfield sand control interventions and workover replacements in maturing Texas and Louisiana conventional assets.
- Exploration Wells:Appraisal and wildcat drilling with limited sand control deployment pending reservoir characterization.
Onshore Operations generates the highest absolute unit volume, while Offshore Operations sustains the steepest margin per installation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA methane regulations and BSEE well integrity standards anchor sand control procurement in the Gulf of Mexico and Permian Basin, while OSHA silica enforcement shapes surface operations across Texas shale plays.
Texas
Permian Basin operators drive frac pack adoption in 15,000-foot laterals where high-strength proppant conductivity proves critical. EPA greenhouse gas reporting rules for onshore facilities tighten completion design requirements. Midland-Odessa service clusters concentrate gravel pack pumping capacity and expandable screen logistics.
Louisiana
Gulf of Mexico shelf and deepwater developments demand premium metallurgy and redundant barrier designs under BSEE safety case reviews. Offshore platform economics favor intervention-avoidant hardware that amortizes costs over extended production horizons. Houma-New Orleans fabrication corridors cluster wire-wrapped screen manufacturing and subsea packer assembly.
North Dakota
Williston Basin unconventional wells present underpenetrated sand control deployment as operators address proppant flowback in high-stress completion designs. State oil and gas commission well integrity rules align with federal baseline standards. Dickinson and Williston service yards are expanding frac pack staging capacity for multi-well pad developments.
New Mexico
Delaware Basin extensions push gravel pack upgrades in high-drawdown unconventional completions where formation damage minimization drives design. State environmental regulations mirror federal EPA methane protocols for leak detection and repair. Carlsbad and Hobbs logistics hubs channel proppant and screen inventory from West Texas supply chains.
Oklahoma
Anadarko Basin and STACK-SCOOP plays sustain niche gravel pack demand in conventional and select unconventional completions. Corporation Commission well construction rules govern annular pack specifications and pressure testing protocols. Oklahoma City service company offices coordinate regional pumping operations and equipment deployment.
US Sand Control Systems Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in sand control system supply. Three strategic archetypes dominate: full-service oilfield contractors bundling screens, gravel, and pumping under single accountability; premium metallurgy specialists serving Gulf of Mexico deepwater specifications; and smart system integrators combining fiber-optic sensing with expandable hardware. Competitive moves concentrate on integrated service contracting that displaces fragmented procurement, and domestic manufacturing expansion to capture IRA content credits.
Among Houston-based integrated service contractors, Baker Hughes Company, Halliburton Company, and Weatherford International exemplify the tier that combines well construction portfolios with sand control execution. These entities represent the archetype of bundled accountability structures now displacing commodity-based sourcing in Permian pad developments.
| Leading Market Players |
|---|
| Schlumberger Limited |
| Baker Hughes Company |
| Halliburton Company |
| Weatherford International |
| Oil States International |
| National Oilwell Varco |
| Welltec International |
| Tendeka |
| Packers Plus Energy Services |
| Others |
Value Chain & Pricing Dynamics
Integrated service contracting locks in multi-year gravel pack and frac pack commitments across Permian Basin pad developments, binding screen suppliers and pumping operators into guaranteed volume structures that stabilize unit economics while exposing both parties to EPA methane compliance cost fluctuations.
Pricing Analysis
Long-term offtake agreements dominate sand control procurement as Permian independents consolidate fragmented sourcing under single-vendor accountability. Three-tier pricing structure across premium metallurgy, standard carbon steel, and economy chemical consolidation tiers separates Gulf of Mexico deepwater specifications from Midland Basin unconventional completions. Cost compression in standard gravel pack tiers is intensifying because resin-coated proppant substitution erodes mechanical system share in shallow wells. Privately held Delaware Basin operators exhibit highest price sensitivity, while supermajor offshore divisions accept 40-60% chrome-alloy premiums to minimize intervention frequency.
Supply Chain Analysis
Houma-New Orleans fabrication corridors concentrate wire-wrapped screen manufacturing and subsea packer assembly, creating hurricane exposure that disrupts Gulf of Mexico completion schedules during peak seasons. Domestic supply draws from Texas-Louisiana metallurgy clusters for super-duplex alloys, West Texas proppant coating facilities for resin treatments, and Oklahoma City engineering centers for expandable screen design. Single-source vulnerability concentrates in deepwater BSEE certification bottlenecks where 18-24 month qualification timelines lock out alternative suppliers. Distribution runs through Midland-Odessa and Carlsbad logistics hubs that channel inventory to multi-well pad developments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as Permian independents displace fragmented commodity sourcing with bundled service contracts, compressing margins for unintegrated hardware suppliers while rewarding full-service contractors with volume guarantees.
For Market Incumbents: Shield Gulf of Mexico market position by accelerating BSEE pre-certification for next-generation expandable screen metallurgies before 24-month review windows delay competitor entry. Deepen backward integration into domestic proppant coating capacity to capture IRA manufacturing credits and deny feedstock access to emerging challengers. Prioritize fiber-optic sensing R&D to defend premium tier positioning against smart system specialists. For New Entrants and Emerging Players: Differentiate on real-time sand detection integration for extended-reach laterals where Baker Hughes and Halliburton bundled offerings lack standalone sensor optimization. Target North Dakota Bakken whitespace where frac pack penetration lags Permian benchmarks by a full development cycle. Pursue direct contracting with Williston Basin independents bypassing integrated service hierarchies. For Investors and Strategic Acquirers: Capital is best deployed toward smart system integrators combining fiber-optic pressure sensing with expandable hardware, as digital-mechanical convergence represents the steepest margin expansion vector across the projection horizon. Acquisition focus should center on fiber-optic sensor miniaturization specialists and domestic screen fabrication assets qualifying for IRA content credits. Monitor EPA methane enforcement intensity as the critical inflection signal for premium metallurgy demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Manufacturing Expansion | IRA content credits redirect capital toward US-based screen fabrication serving Permian demand. |
| Smart System Integration | Fiber-optic sensing convergence transforms passive sand control into active production optimization tools. |
| Long-term Service Contracting | Integrated accountability structures displace fragmented procurement in multi-well pad developments. |
| BSEE Pre-certification Investment | Early qualification timelines lock out competitors from Gulf of Mexico deepwater specifications. |
| Proppant Coating Backward Integration | In-house resin treatment capacity secures supply chain control and captures green manufacturing incentives. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, combining completion engineering directors at Permian independents, gravel pack service supervisors in Gulf of Mexico operations, and procurement leads at integrated oil companies with secondary validation from EPA enforcement databases, BSEE safety case filings, and SEC 10-K disclosures from oilfield service providers. Bottom-up well count and completion intensity models were triangulated against top-down sand control expenditure estimates from energy capital tracking databases.
Across the analysis window, volume and value outputs reflect analytical frameworks segmenting by product type, technology tier, end-user purchasing power, and application environment, with CAGRs derived from basin-specific drilling forecasts and completion design evolution patterns. Modeled inputs include Permian lateral length extension trajectories, EPA methane rule implementation pacing, and BSEE certification queue durations.
Material uncertainties — regulatory enforcement intensity shifts, hurricane disruption frequency, and resin-coated proppant substitution acceleration — sit outside the modeled envelope. Forecasts reflect assumptions around continued unconventional drilling economics and IRA credit durability. Practitioners should keep alternative scenarios live as EPA greenhouse gas reporting protocols and BSEE well integrity standards evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Land Drilling Rig Market
Oil & Gas
Thermal Spray Coating for Oil and Gas Market
Oil & Gas
Aqueous Flare Meter Market
Oil & Gas
India LNG Bunkering Market
Oil & Gas
GCC and North Africa Coiled Tubing Market
Oil & Gas
Floating Liquefied Natural Gas (FLNG) Terminals Market
Oil & Gas
Norway Oil and Gas Upstream Market
Oil & Gas
GCC Oil and Gas Separation Market
Oil & Gas
Oil and Gas Fittings Market
Oil & Gas
Asia-Pacific Oilfield Services Market
Oil & Gas
North America Wireline Services Market
Oil & Gas
United States Wireline Logging Services Market
Oil & Gas
Hydraulic Fracturing Market
Oil & Gas
Asia-Pacific Liner Hanger System Market
Oil & Gas
Intelligent Completion Sales Market
Oil & Gas
Chemical Enhanced Oil Recovery (EOR) Market