
 Rosacea Treatment Market | 2026-2036
Rosacea Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Rosacea Treatment Market Intelligence
Combination therapy bundling is consolidating physician prescribing behavior around multi-modal rosacea protocols. Galderma leverages its integrated dermatology platform to sustain formulary access across European markets. Pfizer anchors its position through primary care physician detailing networks. AbbVie differentiates via immunology R&D spillover into inflammatory skin conditions.
Rosacea treatment encompasses pharmacological and device-based interventions targeting vascular dysfunction, inflammatory cascades, and cutaneous barrier impairment in chronic facial dermatosis. Topical medications incorporating ivermectin or azelaic acid modulate Demodex mite populations and keratinocyte inflammation, while oral antibiotics address papulopustular subtypes through anti-inflammatory mechanisms rather than antimicrobial action alone. Topical medications command the largest revenue pool due to chronic usage patterns and favorable reimbursement profiles. Laser treatments represent the fastest-expanding segment as aesthetic centers adopt vascular-targeting devices for erythema reduction. Home care delivery is gaining traction through prescription-grade topicals paired with telemedicine monitoring.
FDA dermatology division reviews govern new molecular entity approvals in the United States, while EMA's Committee for Medicinal Products for Human Use shapes centralized market access across EU member states. REACH compliance requirements constrain formulation chemistry for European topical manufacturers, and ISO 13485 certification governs laser device commercialization pathways. Stakeholders must monitor evolving payer evidence requirements for combination therapy reimbursement and device efficacy thresholds.
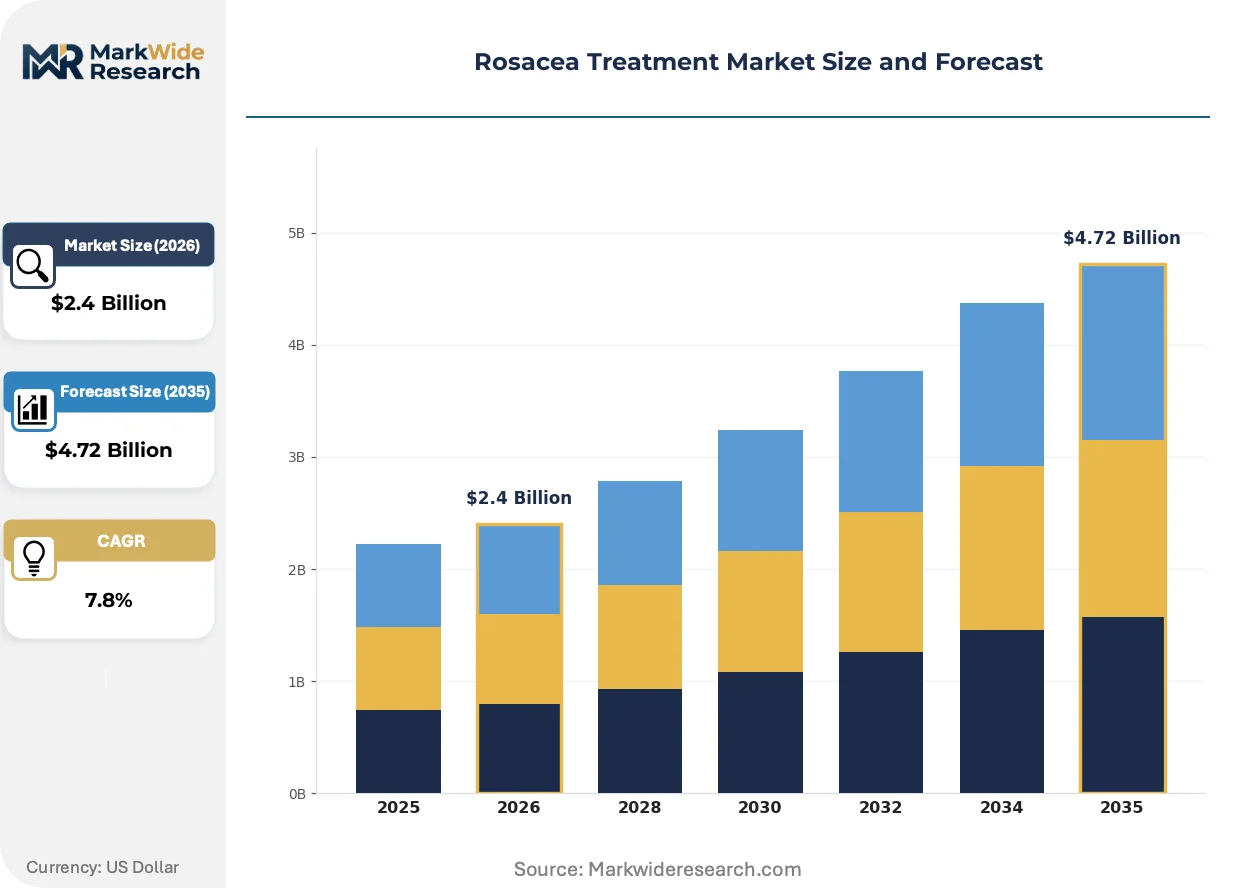
Market Dynamics
Combination therapy protocols are consolidating physician prescribing patterns around bundled rosacea management, forcing single-molecule formulations to defend access through outcome-based contracting and integrated care pathway alignment.
Growth Catalysts
- EMA Centralized Procedure:Streamlined marketing authorization across EU member states accelerates novel topical entry, reducing time-to-revenue for ivermectin-azelaic acid combination therapies.
- Laser Device Certification:ISO 13485 pathways for vascular-targeting systems enable aesthetic centers to deploy erythema-reduction platforms with validated safety profiles.
- Telemedicine Integration:Remote monitoring platforms in the United States pair prescription-grade topicals with digital adherence tracking, expanding chronic care reach beyond traditional dermatology visits.
Market Restraints
- API Supply Concentration:Azelaic acid and ivermectin active pharmaceutical ingredients concentrate among Indian and Chinese contract manufacturers, creating vulnerability to export restriction cascades.
- REACH Compliance Burden:European formulation chemistry faces ECHA registration thresholds that constrain excipient innovation and elevate reformulation costs for topical manufacturers.
- Antibiotic Stewardship Pressure:Oral doxycycline and minocycline prescriptions face institutional restriction protocols in Germany and Japan, limiting anti-inflammatory deployment for papulopustular subtypes.
Strategic Opportunities
- Home Care Channel Expansion:Direct-to-patient delivery models in the United States bypass traditional pharmacy networks, capturing margin through subscription-based topical replenishment.
- Microbiome-Targeted Platforms:Demodex mite modulation research converges with barrier repair science, opening formulation white space beyond existing ivermectin mechanisms.
- Japanese Aesthetic Clinic Network:Underpenetrated vascular laser deployment in Tokyo and Osaka metropolitan clusters offers device manufacturer growth vectors outside saturated US dermatology markets.
Industry Challenges
- Laser Technician Certification Delays:State-level licensing variance in the United States creates operational friction for multi-site aesthetic chain expansion.
- Combination Therapy Evidence Generation:Payer requirements for head-to-head trial data against monotherapy standards extend development timelines and elevate clinical investment thresholds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rosacea Treatment Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.72 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Medications, Oral Antibiotics, Laser Treatments, Light Therapy Application: Skin Redness, Acne-like Breakouts, Inflammation, Sensitivity End User: Dermatology Clinics, Hospitals, Home Care, Aesthetic Centers Delivery Mode: Topical, Injectable, Oral, Devices |
| Companies Covered | LEO Pharma, Sol-Gel Technologies, Galderma, Pfizer, Mayne Pharma Group Limited, Bausch Health, Journey Medical Corporation, Bayer AG, AbbVie, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rosacea Treatment Market Strategic Shifts & Innovations
Digital diagnostic tools and AI-enabled severity scoring are compressing the gap between patient self-assessment and specialist intervention, reshaping how rosacea severity is triaged and treated across care settings.
Intense pulsed light technology is converging with real-time skin temperature monitoring to enable personalized vascular treatment parameters. Aesthetic clinics in Germany and Japan are adopting these integrated platforms at accelerating pace. This convergence is compressing the efficacy variance between operator-dependent laser applications and standardized protocol outcomes.
REACH authorization timelines for novel topical excipients are extending formulation development cycles in European markets. ECHA's cumulative toxicity assessment requirements now govern preservative selection and emulsion stability testing. Mid-sized topical manufacturers are responding by consolidating European regulatory affairs functions and pre-submission scientific advice engagement.
Subscription-based home care models are displacing traditional pharmacy dispensing for chronic topical therapies. US-based telemedicine platforms now bundle prescription fulfillment with automated adherence prompting. This shift is most visible in metropolitan markets where dermatology appointment access constraints drive patients toward asynchronous care channels.
Rosacea Treatment Market Segmentation
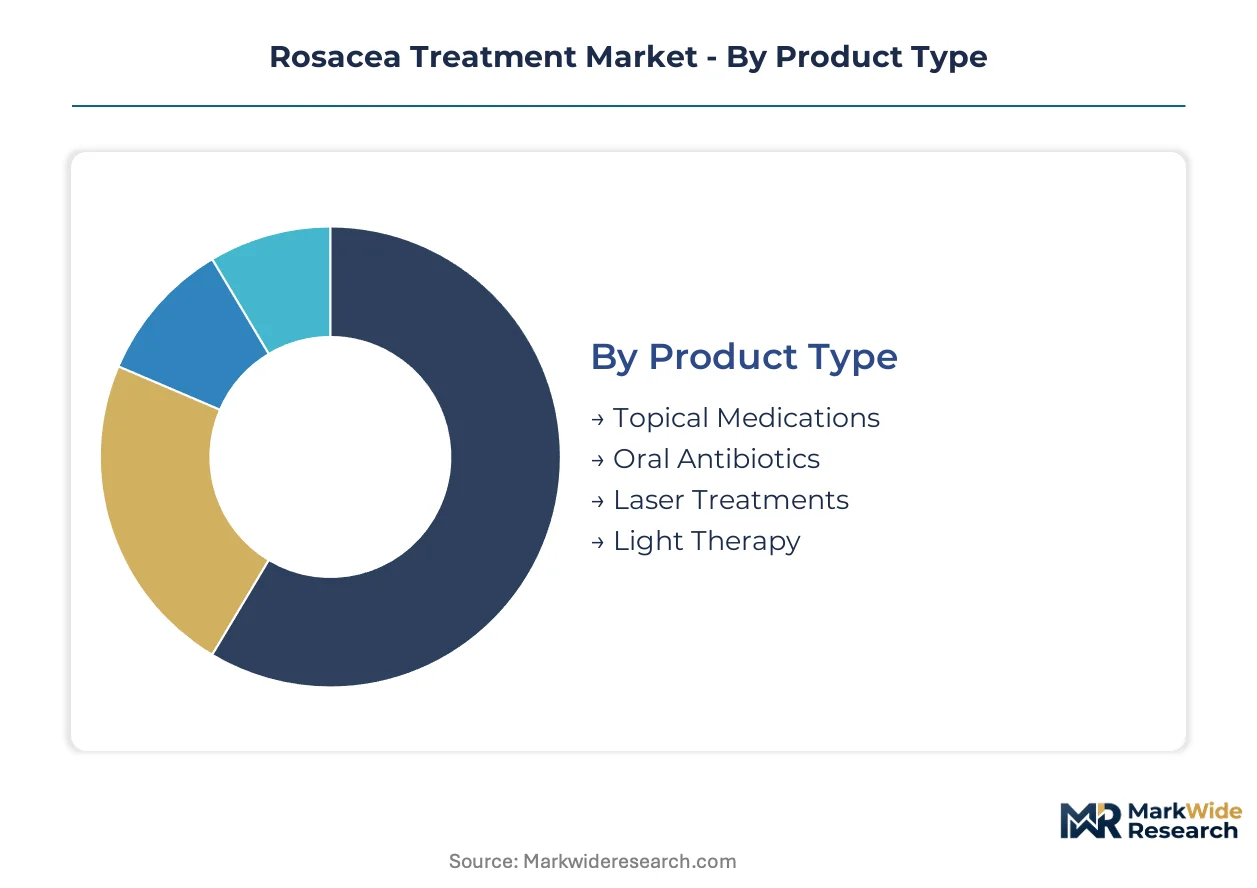
Rosacea treatment segmentation reveals how prescribing patterns bundle around chronic management versus acute intervention. Patient access routes and reimbursement structures vary sharply across product modalities and care settings.
Product Type:
Prescribing cost tiers drive physician selection between chronic maintenance and procedural intervention.
- Topical Medications:Ivermectin, azelaic acid, and metronidazole formulations dominate first-line therapy through daily application regimens. United States dermatology practices concentrate demand here due to favorable Medicare Part D reimbursement and patient preference for non-invasive management.
- Laser Treatments:Vascular-targeting devices using pulsed dye and Nd:YAG wavelengths address refractory erythema through selective photothermolysis. Aesthetic centers in Germany and Japan are deploying these platforms fastest as out-of-pocket cosmetic spending rises.
- Oral Antibiotics:Doxycycline and minocycline deploy anti-inflammatory dosing below antimicrobial thresholds for papulopustular subtypes.
- Light Therapy:LED-based systems offer home-use alternatives with lower energy density than clinical laser platforms.
Topical medications lead on scale; laser treatments lead on momentum.
Application:
Symptom severity and visibility determine whether patients seek specialist referral or self-manage through primary care.
- Skin Redness:Persistent facial erythema from cutaneous vascular hyperreactivity drives the largest patient presentation volume. German dermatology clinics report highest consultation rates for this subtype, where public health insurance covers vascular laser therapy when refractory to topicals.
- Acne-like Breakouts:Papulopustular lesions respond to combined topical-oral protocols with Demodex mite suppression. United States telemedicine platforms now triage these cases into prescription-strength ivermectin fulfillment without in-person examination.
- Inflammation:Neurogenic inflammatory cascades require barrier repair adjuncts alongside primary therapy.
- Sensitivity:Stinging and burning sensations often precede formal diagnosis, creating early intervention opportunities.
Skin redness captures the broadest patient base; acne-like breakouts show the steepest expansion trajectory through digital care channels.
End User:
Channel economics and regulatory scope separate institutional prescribing from direct-to-patient delivery models.
- Dermatology Clinics:Specialist practices in the United States, Germany, and Japan anchor formulary adoption through KOL influence and continuing medical education programs. These sites generate highest revenue per patient through combination protocol bundling and procedural add-ons.
- Home Care:Subscription-based topical replenishment paired with asynchronous dermatologist oversight is displacing traditional pharmacy dispensing. United States-based platforms lead this channel shift, capturing margin through automated adherence monitoring and direct fulfillment.
- Hospitals:Academic medical centers handle complex cases with ocular rosacea complications or antibiotic resistance patterns.
- Aesthetic Centers:Laser device operators target cosmetic-conscious patients outside formal medical reimbursement pathways.
Dermatology clinics lead on scale; home care leads on momentum.
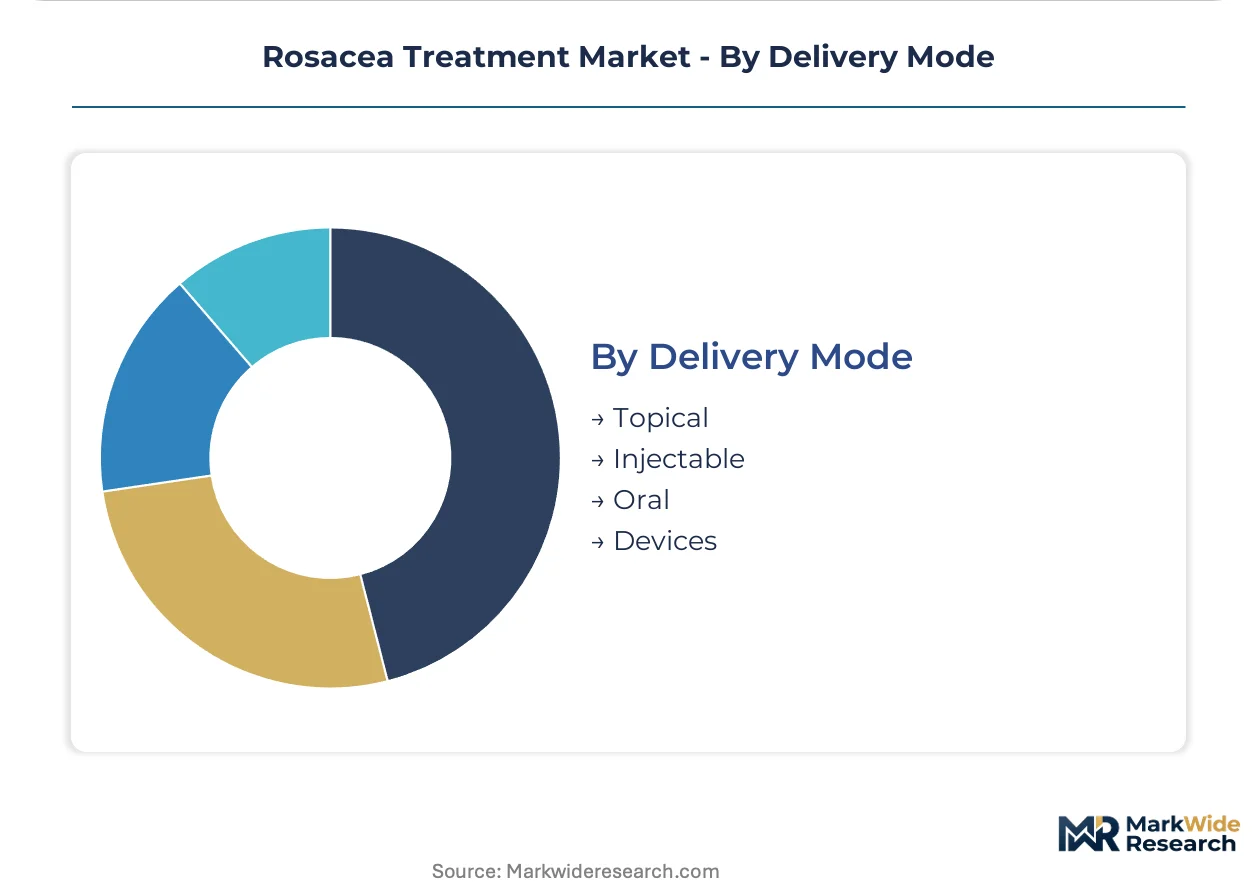
Delivery Mode:
Patient compliance barriers and reimbursement coding determine route selection for chronic versus episodic therapy.
- Topical:Cream, gel, and foam formulations command preferred status for maintenance therapy through ease of self-administration. United States payers require step-therapy failure on topicals before approving oral or device-based alternatives.
- Devices:Laser and light-based systems require capital investment and technician training but generate recurring revenue through treatment series. Japanese aesthetic clinic networks are expanding device fleets fastest outside saturated US metropolitan markets.
- Oral:Systemic agents face institutional restriction protocols under antibiotic stewardship mandates.
- Injectable:Intralesional and botulinum toxin approaches remain niche for selected refractory cases.
Topical delivery leads on scale; devices lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rosacea therapeutics originated in European dermatology research centers during the late twentieth century, with German and Swiss pharmaceutical laboratories pioneering the first topical formulations. Specialist dermatology infrastructure in the United States, Germany, and Japan now anchors commercial deployment.
United States
FDA dermatology division reviews govern new molecular entity approvals, with streamlined pathways accelerating ivermectin-azelaic acid combinations. Medicare Part D reimbursement favors chronic topical regimens over procedural alternatives. New York and Los Angeles metropolitan clusters concentrate aesthetic laser deployment for refractory erythema.
Germany
EMA centralized procedures enable unified marketing authorization across EU member states from Frankfurt-based regulatory operations. Public health insurance covers vascular laser therapy when topical therapy fails. Munich and Hamburg dermatology clinics report highest consultation volumes for persistent facial redness subtypes.
Japan
PMDA reviews shape pharmaceutical market entry timelines for topical and oral rosacea therapies. METI industrial policy supports medical device innovation for aesthetic applications. Tokyo and Osaka metropolitan areas show underpenetrated vascular laser deployment relative to patient prevalence.
United Kingdom
NICE technology appraisals determine National Health Service reimbursement for combination therapy protocols. MHRA post-Brexit regulatory autonomy maintains alignment with EMA standards through mutual recognition agreements. London specialist dermatology centers anchor private-pay aesthetic laser demand.
India
CDSCO regulates topical pharmaceutical manufacturing for domestic consumption and contract export supply. Indian API manufacturers concentrate azelaic acid and ivermectin production for global formulation houses. Hyderabad and Ahmedabad clusters supply active pharmaceutical ingredients to European and North American topical manufacturers.
Rosacea Treatment Market Key Industry Players
Premium-margin players sit above commodity-margin players across dermatology specialization depth and integrated care pathway control. The vendor base stratifies into three tiers: multinational pharmaceutical conglomerates with dermatology divisions, mid-cap topical specialists with formulation expertise, and emerging telemedicine platforms with direct-to-patient distribution. Consolidation pressures favor players with captive supply of active pharmaceutical ingredients and established payer contracting relationships. Dominant competitive moves include portfolio diversification into adjacent inflammatory skin conditions and geographic expansion through regulatory pathway optimization.
Within the multinational pharmaceutical tier, Galderma and Pfizer exemplify divergent strategic positioning. Galderma occupies a position as a dedicated dermatology platform with integrated European formulary access. Pfizer anchors a position through primary care physician detailing networks spanning multiple therapeutic areas. AbbVie sits within the immunology R&D spillover archetype, leveraging inflammatory disease expertise into cutaneous applications.
| Leading Market Players |
|---|
| LEO Pharma |
| Sol-Gel Technologies |
| Galderma |
| Pfizer |
| Mayne Pharma Group Limited |
| Bausch Health |
| Journey Medical Corporation |
| Bayer AG |
| AbbVie |
| Others |
Cost & Logistics Intelligence
Captive API sourcing from Indian and Chinese contract manufacturers anchors pricing power for European and North American formulation houses, while REACH compliance costs and antibiotic stewardship protocols compress margins for players without backward integration into active pharmaceutical ingredient production.
Pricing Analysis
Subscription-based replenishment models for chronic topical therapies are displacing traditional pharmacy dispensing, with pricing stratifying across premium prescription-grade ivermectin formulations, standard azelaic acid generics, and economy-tier metronidazole alternatives. Cost compression in the oral antibiotic segment is intensifying because institutional stewardship protocols in Germany and Japan restrict anti-inflammatory dosing. Aesthetic centers show lowest price sensitivity for vascular laser platforms, while primary care physicians face highest formulary pressure from payer step-therapy requirements.
Supply Chain Analysis
Regional distribution centers in Hyderabad and Ahmedabad feed global formulation houses through hub-and-spoke patterns, with Indian API manufacturers concentrating azelaic acid and ivermectin production. European topical manufacturing rests on REACH-registered excipient supply chains governed by ECHA toxicity thresholds. Single-source vulnerability concentrates in Chinese ivermectin fermentation capacity. Distribution runs through specialty pharmacy networks in the United States and direct-to-patient subscription platforms bypassing traditional wholesale.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
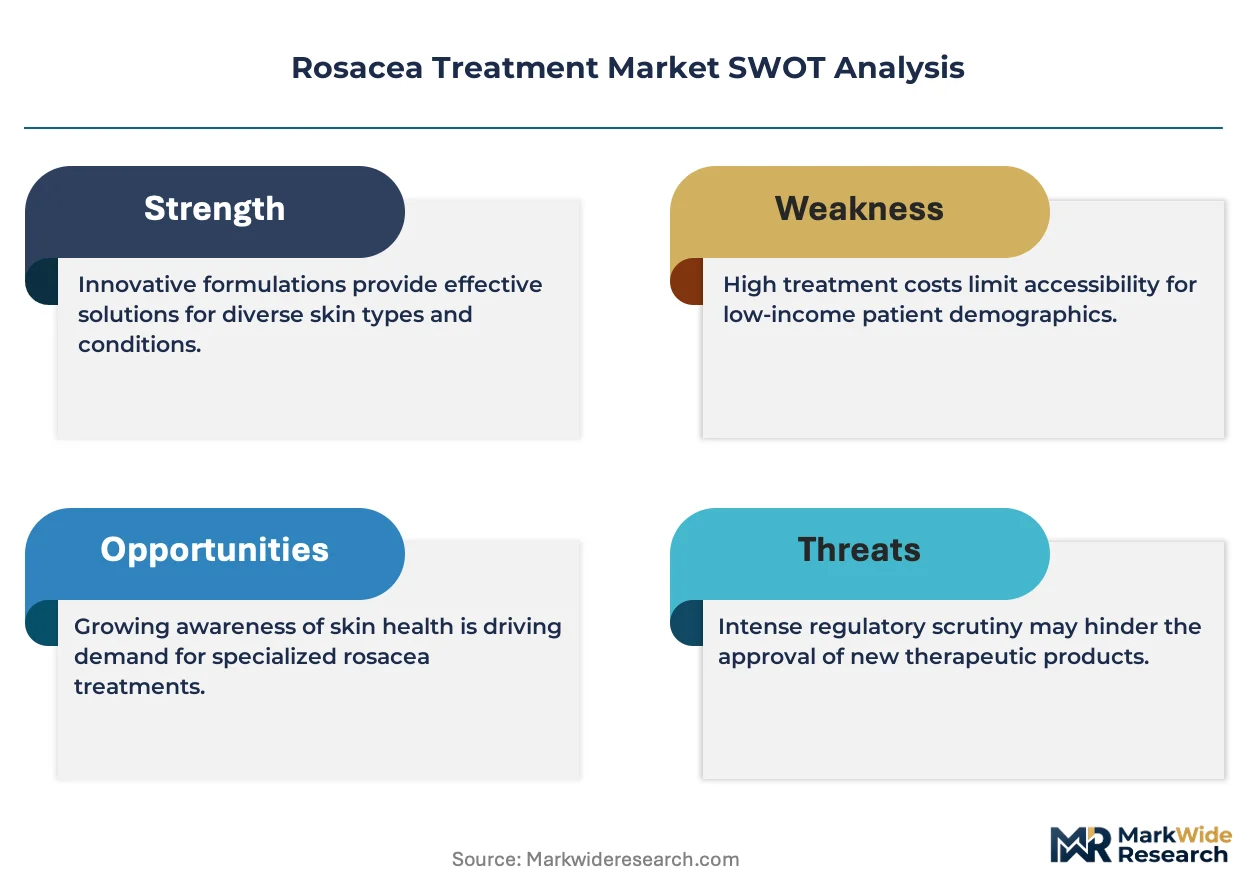
Margin expansion in rosacea therapeutics hinges on captive API supply and premium-tier laser device adoption, with cost-down drivers from telemedicine-enabled patient acquisition offsetting REACH compliance burdens for European manufacturers.
For Market Incumbents: Anchor formulary position through outcome-based contracting with United States payers for combination therapy protocols, while building captive azelaic acid supply through Indian manufacturing partnerships to deflect API export restriction risk. Defend against telemedicine platform disintermediation by integrating digital adherence monitoring into direct fulfillment channels. For New Entrants and Emerging Players: Launch via direct-to-patient subscription models targeting United States metropolitan markets with dermatology appointment access constraints, capturing margin through automated topical replenishment. Target Japanese aesthetic clinic networks in Tokyo and Osaka for vascular laser deployment, where device penetration lags patient prevalence. Exploit microbiome-targeted formulation white space beyond existing ivermectin mechanisms. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap topical specialists with REACH compliance infrastructure and European formulary access because regulatory barriers deter new entrants and concentrate acquisition targets. Long-term viability favors players with integrated dermatology platforms spanning prescription and device modalities. Watch FDA dermatology division review timelines as inflection indicator for novel formulation entry velocity.| Strategic Initiative | Industry Significance |
|---|---|
| API Supply Integration | Captive azelaic acid production insulates European formulators from Indian export restriction cascades. |
| Telemedicine Platform Partnership | Asynchronous dermatologist oversight expands chronic topical reach beyond traditional appointment constraints. |
| EMA Centralized Submission | Streamlined marketing authorization accelerates ivermectin-azelaic acid combination entry across EU member states. |
| Japanese Aesthetic Clinic Network Expansion | Underpenetrated Tokyo and Osaka metro clusters offer device manufacturer growth outside saturated US markets. |
| Microbiome R&D Investment | Demodex modulation research opens formulation pathways beyond existing parasiticidal mechanisms. |
Research Approach
Direct dialogue with dermatology practice managers, formulary directors at United States payers, regulatory affairs leads at topical manufacturers, and procurement officers at Indian API suppliers grounded qualitative findings, cross-referenced against FDA 510(k) filings, EMA centralized procedure documentation, ClinicalTrials.gov rosacea intervention records, and Medicare Part D reimbursement databases. Bottom-up patient volume estimates triangulated with top-down pharmaceutical revenue disclosures.
Segment-level outputs across topical medications, laser treatments, oral antibiotics, and light therapy modalities were generated through the projection horizon, with patient population sizing by severity subtype and treatment line informing adoption curves. CAGRs were derived from epidemiological prevalence trends, regulatory approval velocity assumptions, and reimbursement pathway evolution across United States, German, and Japanese markets.
Forecast precision tightens around the base case; tail outcomes carry wider variance under API export restriction scenarios or accelerated antibiotic stewardship implementation in Germany and Japan. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dermatology
Acne Vulgaris Market
Dermatology
Dermal Facial Fillers Market
Dermatology
Inflammatory Skin Diseases Treatment Market
Dermatology
Dermatology Software Market
Dermatology
Derma Rollers Market
Dermatology
Dermabrasion and Micro Needling Market
Dermatology
UK Scar Treatment Market
Dermatology
Global Veterinary Dermatology Drugs Market
Dermatology
Saudi Arabia Hair Transplant Market
Dermatology
Pigmented Lesion Treatment Market
Dermatology
Global Ozone Therapy in Dermatology Market
Dermatology
Radiation Dermatitis Market
Dermatology
Dermatology Drugs Market
Dermatology
Hyperpigmentation Treatment Market
Dermatology
Japan Scar Treatment Market
Dermatology
Global Dermatology Cro Market