
 Derma Rollers Market | 2026-2036
Derma Rollers Market Size, Share, and Industry Trends Forecast 2026-2036
Derma Rollers Market Analysis
Buyer concentration across dermatology clinics and medical spa chains is restructuring procurement patterns for professional-grade devices. Linduray Skincare leverages direct-to-consumer channels to sustain brand visibility among home users. BeautyBio anchors its position through premium positioning in specialty retail. SRI Professional competes on manufacturing scale for salon and clinic supply contracts.
A derma roller is a handheld cylindrical device embedded with fine metal or polymer microneedles, typically ranging from 0.2 to 3.0 millimeters in length, designed to create controlled micro-injuries that stimulate collagen induction and enhance topical product absorption. Stainless steel and titanium variants dominate clinical settings due to durability and biocompatibility requirements, while plastic and glass configurations serve lower-cost cosmetic segments. Medical rollers command the highest margin pools through dermatologist-prescribed protocols, whereas cosmetic rollers reach volume through supermarket and online retail placement. Home users represent the fastest-expanding end-user category as social media education reduces treatment intimidation.
The FDA oversees medical device classification for microneedling instruments in the United States, while the EU Medical Device Regulation imposes conformity assessment burdens on European market entrants. REACH compliance affects titanium and stainless steel sourcing for manufacturers distributing in Europe. Stakeholders must monitor evolving classification boundaries between cosmetic and medical-grade devices, as regulatory reclassification would reshape channel access and labeling requirements across major markets.
Market Dynamics
Medical device reclassification pressure from the FDA is compressing commercial timelines for cosmetic-grade manufacturers while elevating quality thresholds across all distribution tiers.
Growth Catalysts
- EU Medical Device Regulation (MDR):Conformity assessment requirements for microneedling instruments are filtering out low-quality imports and consolidating shelf space for certified suppliers in European dermatology clinics.
- Collagen induction therapy protocols:Dermatology residency programs are expanding hands-on microneedling training, embedding device literacy into the next generation of practitioners.
- Social media education:Video tutorials on proper at-home technique are demystifying derma roller use and expanding the addressable consumer base beyond early adopters.
Market Restraints
- Titanium sourcing concentration:Biocompatible needle-grade titanium supply chains cluster in select East Asian smelters, exposing manufacturers to input volatility and geopolitical friction.
- FDA Class II medical device thresholds:Quality system regulation compliance costs block smaller cosmetic brands from entering professional channels, segmenting the vendor base by capital access.
- Topical retinoid substitution:Prescription tretinoin formulations compete for the same collagen-stimulation indication with lower upfront patient commitment and no device purchase requirement.
Strategic Opportunities
- Underpenetrated Indian aesthetic medicine:Rising disposable income in tier-2 cities and CDSCO regulatory harmonization efforts are opening professional microneedling service deployment outside Mumbai and Delhi.
- Combination therapy protocols:Device manufacturers bundling derma rollers with peptide-infused serums are capturing higher per-treatment revenue in medical spa channels.
- Direct-to-clinic subscription models:Monthly replenishment programs for disposable roller heads are locking in recurring revenue and reducing customer acquisition costs for professional-grade suppliers.
Industry Challenges
- Cross-contamination protocol training:Clinic staff turnover accelerates retraining cycles for sterilization and single-use head disposal, elevating operational risk in high-volume practices.
- ISO 13485 certification timelines:Medical device quality management system audits stretch 12-18 months, delaying product launches and compressing first-mover advantage windows for innovations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Derma Rollers Market |
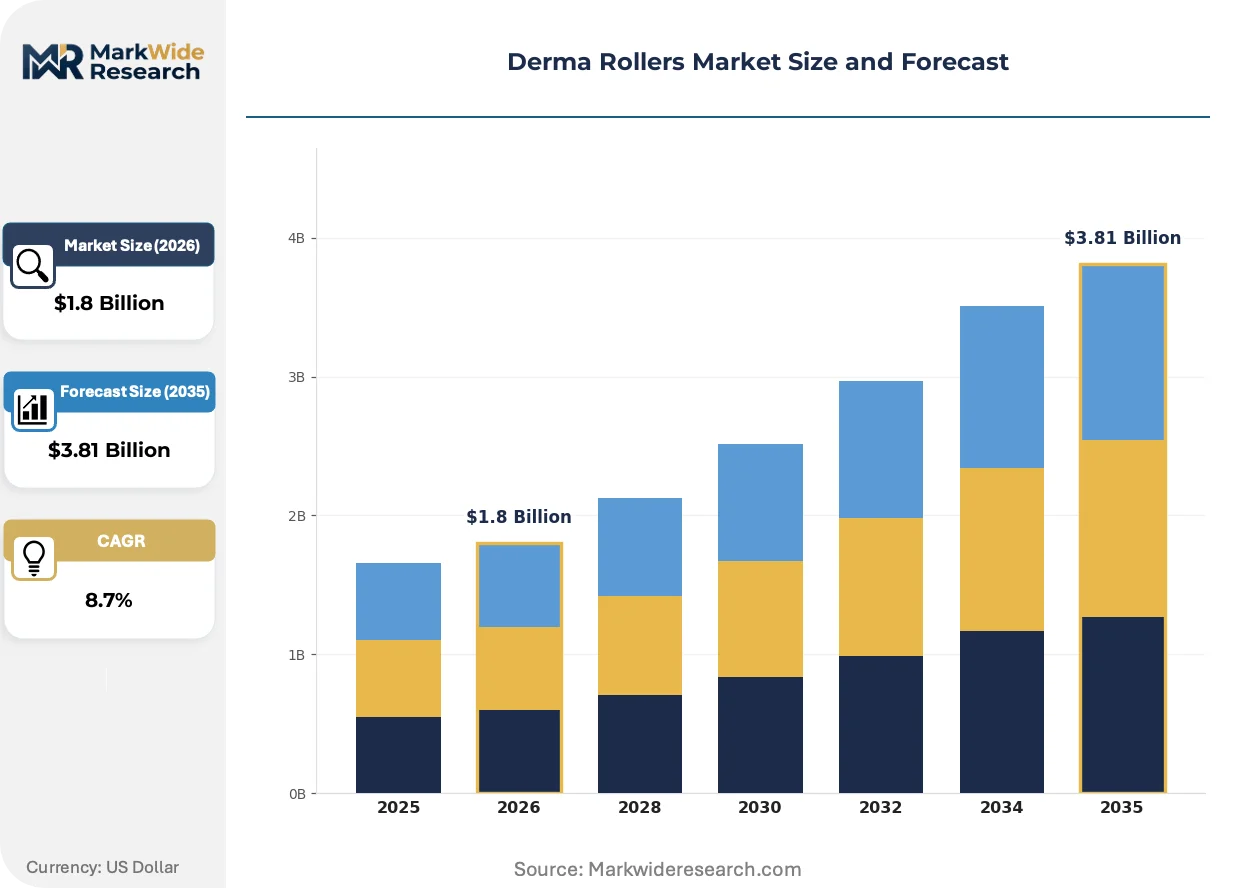
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microneedle Rollers, Medical Rollers, Cosmetic Rollers, Dermarollers Material: Stainless Steel, Titanium, Plastic, Glass End User: Clinics, Dermatologists, Home Users, Salons Distribution Channel: Online Retail, Specialty Stores, Pharmacies, Supermarkets |
| Companies Covered | Linduray Skincare, ORA, SRI Professional, Alphaluxy, Stacked Skincare, GRO+, BeautyBio, Vitalysse, Sdara Skincare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Derma Rollers Market Emerging Trajectories
Automation and connected-device architectures are penetrating the handheld aesthetic device category, shifting competitive differentiation from needle geometry alone to data-enabled treatment protocols.
Electroporation-enhanced derma rollers are electrifying the professional segment by combining microneedling with electrical pulse delivery to amplify transdermal serum penetration. Medical spa chains in California and Florida are piloting these hybrid devices for premium service tiers. The technology is electrifying margin structures by justifying per-treatment surcharges that offset capital equipment amortization.
REACH substance restrictions on nickel alloy compositions are forcing European manufacturers to reformulate needle substrates and document supply chain provenance for ECHA compliance. The regulatory burden falls heaviest on mid-tier cosmetic brands lacking in-house toxicology testing capabilities. German and French distributors are responding by consolidating supplier relationships to reduce audit complexity.
Home users are bypassing traditional retail entirely through TikTok Shop and Instagram Checkout, collapsing the multi-layer distribution model that historically separated manufacturers from end consumers. Direct-to-consumer brands are capturing first-party usage data to refine needle length recommendations and serum pairing algorithms. This channel compression is most advanced in the United States, where medical influencer partnerships drive conversion rates exceeding conventional e-commerce benchmarks.
Derma Rollers Market Segmentation
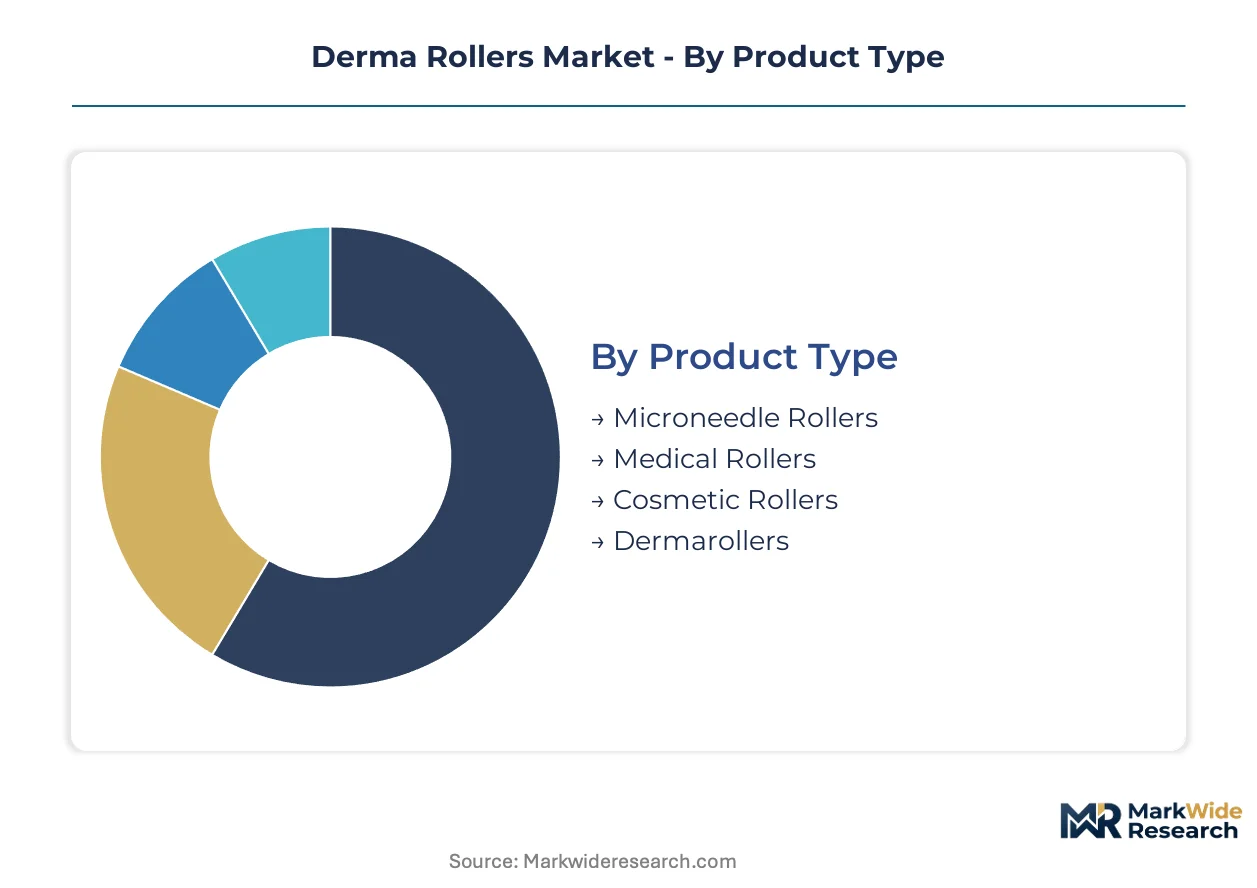
Derma roller segmentation reveals divergent margin architectures across medical and cosmetic tiers. Material specifications and distribution channel access determine which manufacturers capture professional-grade premiums versus high-volume consumer sales.
Product Type:
Medical rollers command premium pricing through FDA Class II certification burdens, while cosmetic variants drive volume through mass retail placement.
- Microneedle Rollers:Devices feature cylindrical drums embedded with 192-540 surgical-grade needles calibrated to 0.2-3.0mm penetration depths. Demand concentrates in California and Florida medical spa chains where combination therapy protocols justify per-treatment surcharges.
- Medical Rollers:ISO 13485-certified instruments with sterilized packaging and single-use head protocols dominate dermatology clinic procurement. FDA quality system regulation compliance blocks smaller brands from professional channels, segmenting the vendor base by capital access.
- Cosmetic Rollers:Lower-cost configurations with plastic needle substrates reach consumers through supermarket and online retail placement. TikTok Shop and Instagram Checkout are collapsing traditional distribution layers for this tier.
- Dermarollers:Branded handheld devices with proprietary needle geometries target home users seeking clinic-mimicking results. Social media education is demystifying at-home technique and expanding this addressable base beyond early adopters.
Mature deployment sits with Medical Rollers. Newer deployment is concentrated in Dermarollers.
Material:
Biocompatibility requirements split procurement between clinical durability standards and cosmetic cost optimization.
- Stainless Steel:Surgical-grade 316L compositions dominate professional settings due to corrosion resistance and autoclave sterilization compatibility. REACH nickel alloy restrictions are forcing European manufacturers to reformulate substrates and document supply chain provenance for ECHA compliance.
- Titanium:Needle-grade titanium supply chains cluster in select East Asian smelters, exposing manufacturers to input volatility. German and French distributors are consolidating supplier relationships to reduce audit complexity under tightened substance regulations.
- Plastic:Polymer microneedles serve entry-level cosmetic segments where disposable economics outweigh durability requirements.
- Glass:Specialty configurations for sensitive skin protocols occupy niche positioning in Korean and Japanese aesthetic medicine markets.
Stainless steel anchors clinical procurement. Titanium is gaining share fastest in premium device architectures.
End User:
Professional training requirements create procurement friction that home users bypass entirely through direct-to-consumer channels.
- Clinics:Multi-station practices with high patient throughput prioritize disposable head subscription models to lock in recurring revenue and reduce retraining cycles for sterilization protocols.
- Dermatologists:Board-certified practitioners prescribe medical-grade rollers as part of collagen induction therapy protocols, embedding device literacy through expanded residency training programs.
- Home Users:Video tutorials on proper technique are expanding this fastest-expanding category as treatment intimidation fades. First-party usage data from direct-to-consumer brands is refining needle length recommendations and serum pairing algorithms.
- Salons:Beauty service providers source mid-tier devices for add-on facial treatments, competing with medical spa chains on accessibility rather than clinical outcomes.
Dermatologists anchor premium positioning. Home users represent the steepest expansion trajectory.
Distribution Channel:
Channel compression is restructuring how manufacturers reach end consumers versus professional purchasers.
- Online Retail:Direct-to-consumer brands capture first-party data through proprietary e-commerce platforms, with medical influencer partnerships driving conversion rates exceeding conventional benchmarks in the United States.
- Specialty Stores:Premium positioning in beauty retailers like Sephora and Ulta anchors brand visibility for cosmetic-tier devices with serum bundling opportunities.
- Pharmacies:CVS and Walgreens placement reaches consumers seeking dermatologist-adjacent credibility without prescription requirements.
- Supermarkets:Mass retail penetration drives volume for entry-level plastic and glass configurations with minimal educational packaging.
Pharmacies anchor mid-tier credibility. Online retail is climbing the fastest as TikTok Shop collapses distribution layers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Patient inquiries for microneedling services concentrate in the United States, where medical spa chains and direct-to-consumer brands drive procurement volume. Dermatology clinics in Florida and California are expanding service menus fastest. Regulatory divergence across major economies is fragmenting commercial entry pathways for device manufacturers.
United States
Medical spa chains in Los Angeles and Miami are piloting electroporation-enhanced rollers for premium service tiers. The FDA Class II medical device classification tightens quality thresholds and blocks smaller cosmetic brands from professional channels. TikTok Shop and Instagram Checkout are collapsing distribution layers for home-use devices, with medical influencer partnerships driving conversion rates above conventional e-commerce benchmarks.
Germany
Dermatology clinics in Berlin and Munich prioritize ISO 13485-certified instruments with single-use head protocols. REACH substance restrictions on nickel alloy compositions force manufacturers to reformulate needle substrates and document supply chain provenance for ECHA compliance. German distributors are consolidating supplier relationships to reduce audit complexity under tightened substance regulations.
India
Rising disposable income in tier-2 cities outside Mumbai and Delhi is opening professional microneedling service deployment. CDSCO regulatory harmonization efforts are streamlining device registration pathways for international manufacturers. Clinics in Bangalore and Hyderabad are expanding combination therapy protocols that bundle rollers with peptide-infused serums.
United Kingdom
Specialty beauty retailers in London anchor premium positioning for cosmetic-tier devices with serum bundling opportunities. The EU Medical Device Regulation imposes conformity assessment burdens on European market entrants, filtering out low-quality imports. Harley Street dermatology practices are embedding device literacy through expanded residency training programs.
South Korea
Glass microneedle configurations for sensitive skin protocols occupy niche positioning in Seoul aesthetic medicine markets. MFDS oversight of medical device registration shapes commercial timelines for professional-grade manufacturers. Gangnam district clinics are driving demand for titanium-needle devices in premium collagen induction therapy protocols.
Derma Rollers Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue direct-to-consumer channel compression and serum-bundling strategies. The vendor base stratifies across three tiers: ISO-certified medical device specialists serving dermatology clinics, mid-tier suppliers targeting salon channels, and digitally native brands capturing home users through social commerce. Three archetypes dominate: certification-heavy incumbents defending professional procurement relationships, vertically integrated manufacturers controlling titanium supply chains, and influencer-backed startups optimizing for first-party data capture. Competitive moves concentrate on M&A for regulatory certifications and geographic expansion into underpenetrated Indian tier-2 cities.
Within the direct-to-consumer archetype, Linduray Skincare and BeautyBio exemplify contrasting positioning strategies. Linduray Skincare leverages proprietary e-commerce platforms to sustain brand visibility among home users, capturing first-party usage data to refine needle length recommendations. BeautyBio anchors premium positioning in specialty retail through Sephora and Ulta placement, occupying the serum-bundling vector that medical spa chains are replicating. SRI Professional represents the manufacturing-scale archetype, competing for salon and clinic supply contracts through production capacity rather than brand equity.
| Leading Market Players |
|---|
| Linduray Skincare |
| ORA |
| SRI Professional |
| Alphaluxy |
| Stacked Skincare |
| GRO+ |
| BeautyBio |
| Vitalysse |
| Sdara Skincare |
| Others |
Supply Flow & Price Mechanics
Needle-grade titanium metallurgists concentrated in East Asian smelting corridors create labor-cost differentials that widen pricing-tier spreads between FDA-certified medical rollers and mass-market cosmetic variants. REACH compliance burdens and ISO 13485 certification timelines further stratify cost structures, entrenching three distinct procurement economics across professional dermatology, medical spa, and direct-to-consumer channels.
Pricing Analysis
The volume-versus-margin split separates cosmetic-grade plastic rollers commanding supermarket placement economics from titanium-needle medical devices capturing per-treatment surcharges in California and Florida medical spas. Price differentiation rests on FDA Class II certification grade and sterilization protocol complexity, with dermatologist-prescribed ISO 13485 instruments carrying the widest premiums. Cost compression in the cosmetic tier intensifies as TikTok Shop disintermediation collapses distributor markups, while home users demonstrate highest price sensitivity and clinic procurement committees exhibit lowest.
Supply Chain Analysis
Biocompatible needle-grade titanium supply rests on smelting capacity clustered in China, Japan, and South Korea, with surgical-grade 316L stainless steel drawing from German and Indian specialty steel producers. Raw material dependencies center on titanium sponge, nickel alloy substrates, and polymer feedstocks for disposable cosmetic configurations. Single-source vulnerability concentrates in East Asian titanium processing, where geopolitical friction threatens input continuity. Distribution runs through layered wholesale structures for professional channels and direct-to-consumer platforms for home-use segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where FDA Class II medical device thresholds erect barrier-to-entry moats favoring capitalized incumbents with quality system regulation infrastructure already deployed.
For Market Incumbents: Acquire ISO 13485 certification assets and sterilization facility capacity to consolidate professional channel access before emerging direct-to-consumer brands achieve regulatory parity. Threats from electroporation-enhanced hybrid devices and peptide-serum bundling strategies demand defensive R&D investment in combination therapy protocols. Backward integration into titanium supply contracts with named East Asian smelters anchors input cost control. For New Entrants and Emerging Players: Electroporation-enhanced roller architectures offer technology-first positioning against legacy needle-geometry competitors. White-space concentration sits with tier-2 Indian cities where CDSCO harmonization is streamlining device registration and disposable income trajectories support premium service deployment. Social commerce conversion optimization through medical influencer partnerships provides the most penetrable go-to-market angle for home-use market capture. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated manufacturers controlling titanium supply chains given REACH substance restriction enforcement tightening audit burdens on mid-tier competitors. Long-term viability favors archetypes with captive needle-grade material sourcing and multi-regulatory certification portfolios. The signal to watch is FDA reclassification pressure expanding Class II device boundaries, which would accelerate vendor base consolidation toward compliance-heavy specialists.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Pathway | Class II medical device clearance unlocks dermatology clinic procurement and prescription-channel access. |
| CE Marking Under EU MDR | Conformity assessment filters low-quality imports and consolidates European shelf space for certified suppliers. |
| Hospital System Partnership | Multi-station dermatology practices prioritize disposable head subscription models with sterilization protocol training. |
| Software Companion Development | Connected-device architectures shift differentiation from needle geometry to data-enabled treatment protocols. |
| Reimbursement Strategy | Collagen induction therapy coding alignment with commercial and Medicare Advantage plans expands addressable patient base. |
Methodological Framework
Document review covered FDA 510(k) filings, EU MDR technical documentation, and CDSCO registration databases, complemented by interviews with dermatology clinic procurement managers, medical spa chain operations directors, biomedical engineers at ISO 13485-certified manufacturers, and GPO contracts specialists. Secondary validation drew from customs trade data, REACH substance restriction updates, and hospital purchasing committee records. Bottom-up demand modeling across end-user segments triangulated against top-down market sizing from device shipment and import-export flows.
Historical shipment and pricing trajectories cross-referenced against expert panel input on regulatory timeline expectations and technology adoption curves. Segmentation dimensions modeled include product certification tier, needle material composition, end-user category, and distribution channel architecture across the projection horizon. CAGRs derived from curve-fitting approaches applied to professional service deployment rates and direct-to-consumer conversion benchmarks, with electroporation-enhanced device penetration and Indian tier-2 city expansion serving as key industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including unforeseen FDA reclassification actions, titanium supply disruptions from geopolitical events, and alternative collagen-stimulation technology breakthroughs. Forecasts reflect assumptions around regulatory stability and material cost continuity that external shocks could revise. A small set of named triggers warrants ongoing watch: EU MDR enforcement intensity, TikTok Shop policy changes affecting medical device advertising, and CDSCO harmonization pace for international manufacturers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dermatology
Prescription Dermatology Therapeutics Market
Dermatology
Dermatology Software Market
Dermatology
UK Scar Treatment Market
Dermatology
Lentigo Maligna Melanoma Therapeutic Market
Dermatology
Seborrheic Dermatitis Treatment Market
Dermatology
Europe Scar Treatment Market
Dermatology
Lichen Sclerosus Treatment Market
Dermatology
Dermabrasion and Micro Needling Market
Dermatology
Global Dermatitis Herpetiformis Market
Dermatology
Cutaneous Squamous Cell Carcinoma Market
Dermatology
Folliculitis Treatment Market
Dermatology
Immunodermatology Market
Dermatology
Keloid Treatment Market
Dermatology
Atopic Dermatitis Treatment Market
Dermatology
Telogen Effluvium Treatment Market
Dermatology
Pigmented Lesion Treatment Market