
 Global Veterinary Dermatology Drugs Market | 2026-2036
Global Veterinary Dermatology Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Veterinary Dermatology Drugs Market Foresight
Multi-source procurement for active pharmaceutical ingredients is broadening as veterinary drug makers diversify beyond single-supplier dependencies. Zoetis leverages its vertically integrated manufacturing network to secure consistent supply chains for corticosteroid and antimicrobial formulations. Dechra Pharmaceuticals specializes in narrow-therapeutic-index dermatology compounds, sustaining its position through dedicated R&D facilities in the United Kingdom and United States. Boehringer Ingelheim Animal Health competes through geographic dominance in European companion animal channels, where its distribution infrastructure reaches over 20,000 veterinary clinics.
Veterinary dermatology drugs comprise pharmacologically active agents formulated for the diagnosis, treatment, and management of skin, coat, and appendage disorders in animals, including bacterial pyoderma, demodectic mange, atopic dermatitis, and superficial fungal infections; these products typically incorporate active concentrations calibrated by species body weight and metabolic clearance rates, with topical formulations requiring pH adjustment between 6.2 and 7.5 to maintain epidermal barrier integrity. Their primary commercial purpose centers on restoring dermatological homeostasis while minimizing systemic absorption and secondary resistance development. Antiparasitics and antimicrobials command the largest revenue pools due to recurring infestation and infection patterns, while oral tablets and injectable solutions represent the fastest-expanding formulation categories as owners prioritize compliance and clinic-administered protocols over home-applied topical regimens.
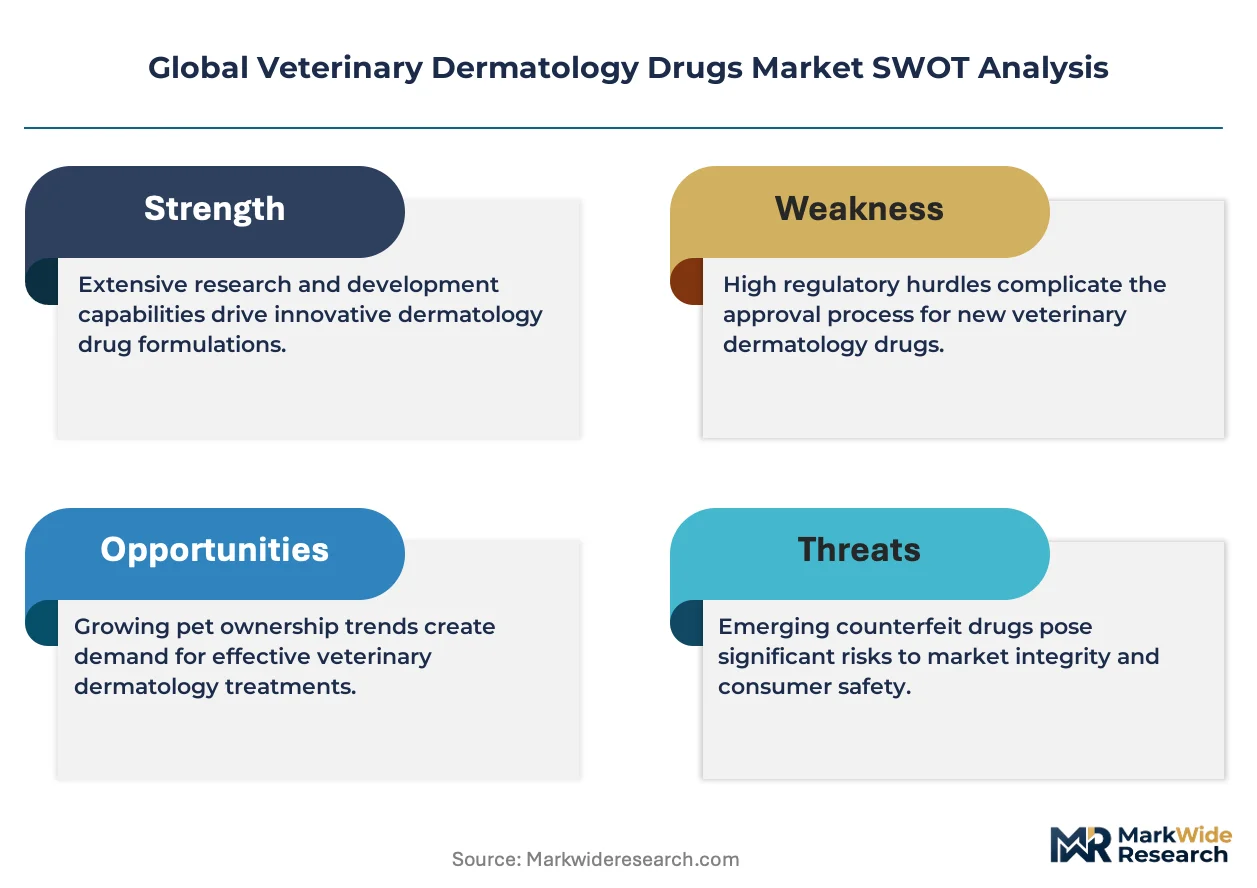
The FDA Center for Veterinary Medicine governs new animal drug approvals and post-market surveillance in the United States, while the European Medicines Agency coordinates centralized marketing authorizations through its Committee for Medicinal Products for Veterinary Use, and ISO 17025 standards guide analytical method validation for dermatology drug quality control across manufacturing sites. These frameworks elevate barriers for unapproved compounded alternatives and channel demand toward validated therapeutic portfolios. Stakeholders must monitor evolving antimicrobial stewardship guidelines that threaten to restrict chronic corticosteroid and antibiotic prescribing patterns in companion animal practice.
Market Dynamics
Specialty veterinary dermatology practices are consolidating diagnostic and therapeutic protocols around species-calibrated formulations, compressing margins for generalist clinics while elevating procurement standards for pH-stabilized topical delivery systems.
Growth Catalysts
- Antimicrobial Stewardship Mandates:The FDA Center for Veterinary Medicine's guidance on judicious antibiotic use in companion animals is redirecting chronic pyoderma cases toward validated therapeutic pipelines and away from compounded alternatives.
- Metropolitan Clinic Density:Specialty dermatology service lines in high pet-insurance penetration cities such as Dallas, Munich, and Melbourne are standardizing systemic treatment protocols that require clinic-administered dosing.
- Biologic Tolerance Engineering:Advances in canine and feline metabolic clearance modeling are enabling narrower therapeutic index compounds that reduce corticosteroid-induced polyuria and polydipsia.
Market Restraints
- API Supply Concentration:Corticosteroid active pharmaceutical ingredient production clusters in Indian and Chinese chemical synthesis hubs, exposing formulators to export license volatility and shipping lane disruptions.
- Regulatory Approval Friction:The European Medicines Agency's Committee for Medicinal Products for Veterinary Use requires multi-year residue depletion studies for novel dermatology actives, extending time-to-market beyond small-molecule human drug parallels.
- Compounding Substitution:Unregulated pharmacy compounding of topical triamcinolone and chlorhexidine formulations siphons price-sensitive cases from approved drug portfolios in cash-pay veterinary segments.
Strategic Opportunities
- Brazilian Companion Animal Expansion:São Paulo and Rio de Janeiro veterinary networks are installing dedicated dermatology suites as pet insurance penetration crosses critical mass thresholds in Latin America's largest economy.
- Telemedicine-Triage Integration:Digital symptom assessment platforms are routing suspected atopic dermatitis cases to specialty clinics for confirmatory intradermal testing, expanding addressable case volume.
- Sustainable Formulation Incentives:The EU Green Deal's pharmaceutical manufacturing emissions standards are creating first-mover advantages for facilities deploying aqueous-based topical vehicles with reduced volatile organic compound profiles.
Industry Challenges
- Veterinary Dermatopathology Talent Scarcity:Board-certified specialists capable of interpreting skin biopsy histopathology are concentrated in academic medical centers, creating diagnostic bottlenecks for community practices.
- Legacy Practice Management Integration:Specialty dermatology workflows involving serial cytological evaluations and therapeutic drug monitoring resist seamless incorporation into generalized veterinary software platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Veterinary Dermatology Drugs Market |
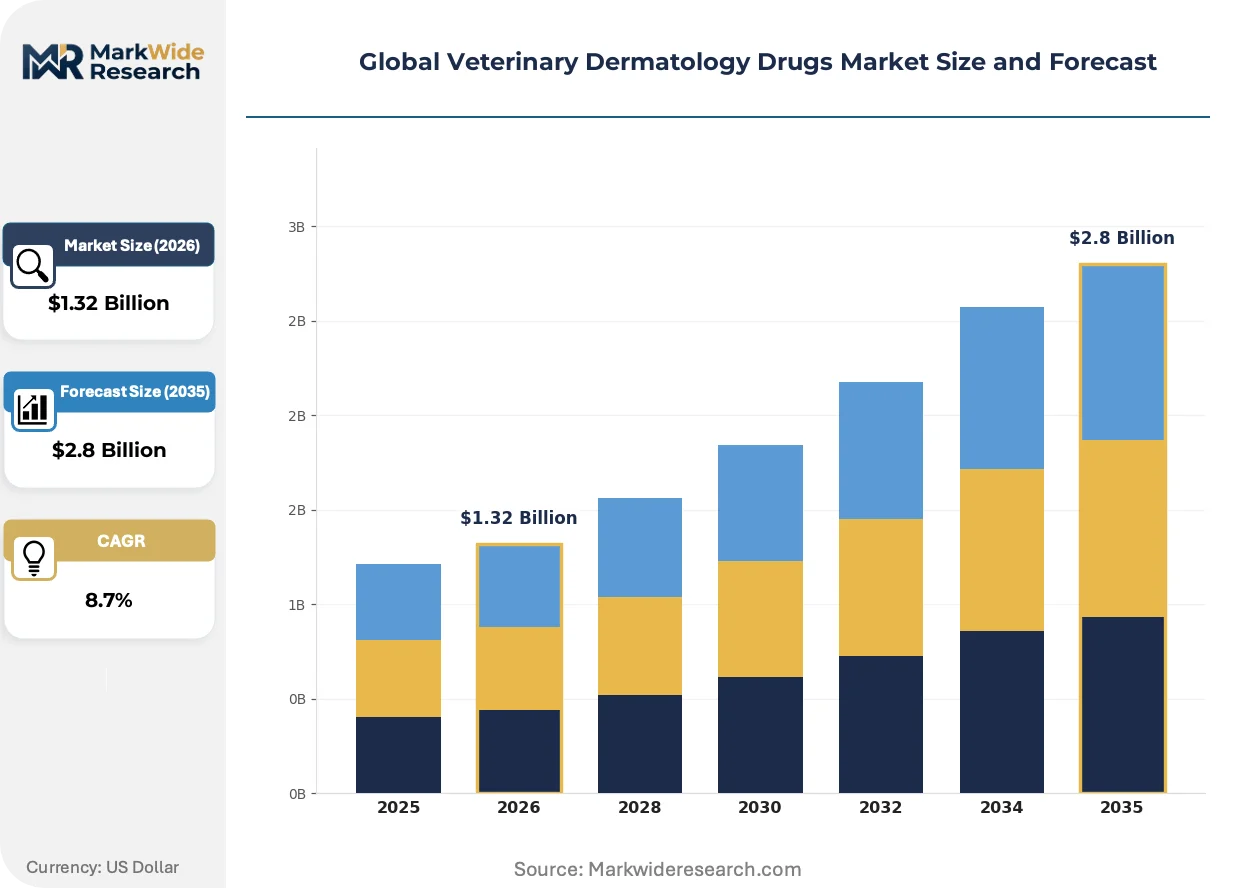
| Market Size in 2026 | $1.32 Billion |
| Market Size in 2035 | $2.8 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antimicrobials, Antiparasitics, Antihistamines, Corticosteroids, Emollients, Keratolytics Formulation: Topical Creams, Shampoos, Sprays, Oral Tablets, Injectable Solutions, Powders Animal Type: Companion Animals, Livestock, Equines, Poultry, Exotic Pets, Farmed Fish Distribution Channel: Veterinary Clinics, Pharmacies, Online Retailers, Animal Health Distributors, Feed Stores, Direct Sales |
| Companies Covered | Ceva Sante Animale, Merck Animal Health, Zoetis, Bimeda, Vetoquinol, Elanco Animal Health, Boehringer Ingelheim Animal Health, Dechra Pharmaceuticals, Virbac, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Veterinary Dermatology Drugs Market Shifts & Advancements
Formulation science and diagnostic modality convergence are redefining therapeutic protocols across companion animal practice, with pH-optimized delivery systems and metabolically-calibrated dosing emerging as the dominant technical axes.
Liposomal encapsulation technology for corticosteroid and antimicrobial actives is absorbing epidermal penetration barriers that previously limited topical efficacy in thick-coated breeds. German and Swiss veterinary teaching hospitals are adopting these vehicles for refractory deep pyoderma cases. The structural consequence is compression in systemic antibiotic exposure duration, reducing resistance selection pressure.
REACH regulation amendments targeting veterinary pharmaceutical environmental discharge are forcing reformulation of shampoo and rinse products containing persistent antimicrobial agents. Manufacturers serving the EU market are substituting biodegradable quaternary ammonium compounds and accelerating biodegradability certification timelines. Small-animal aquatic therapy facilities in the Netherlands and Denmark face the steepest compliance retrofit requirements.
Pet owner preference for fixed-interval clinic appointments over home-administered topical regimens is consolidating demand around depot injectable formulations and oral tablet protocols. Specialty dermatology practices in Tokyo, Sydney, and Toronto are restructuring service menus around compliance-optimized therapeutic plans. This behavioral pivot is most visible in atopic dermatitis maintenance therapy, where owner fatigue with daily application drives switching toward monthly injectable monoclonal antibody alternatives.
Global Veterinary Dermatology Drugs Market Segmentation
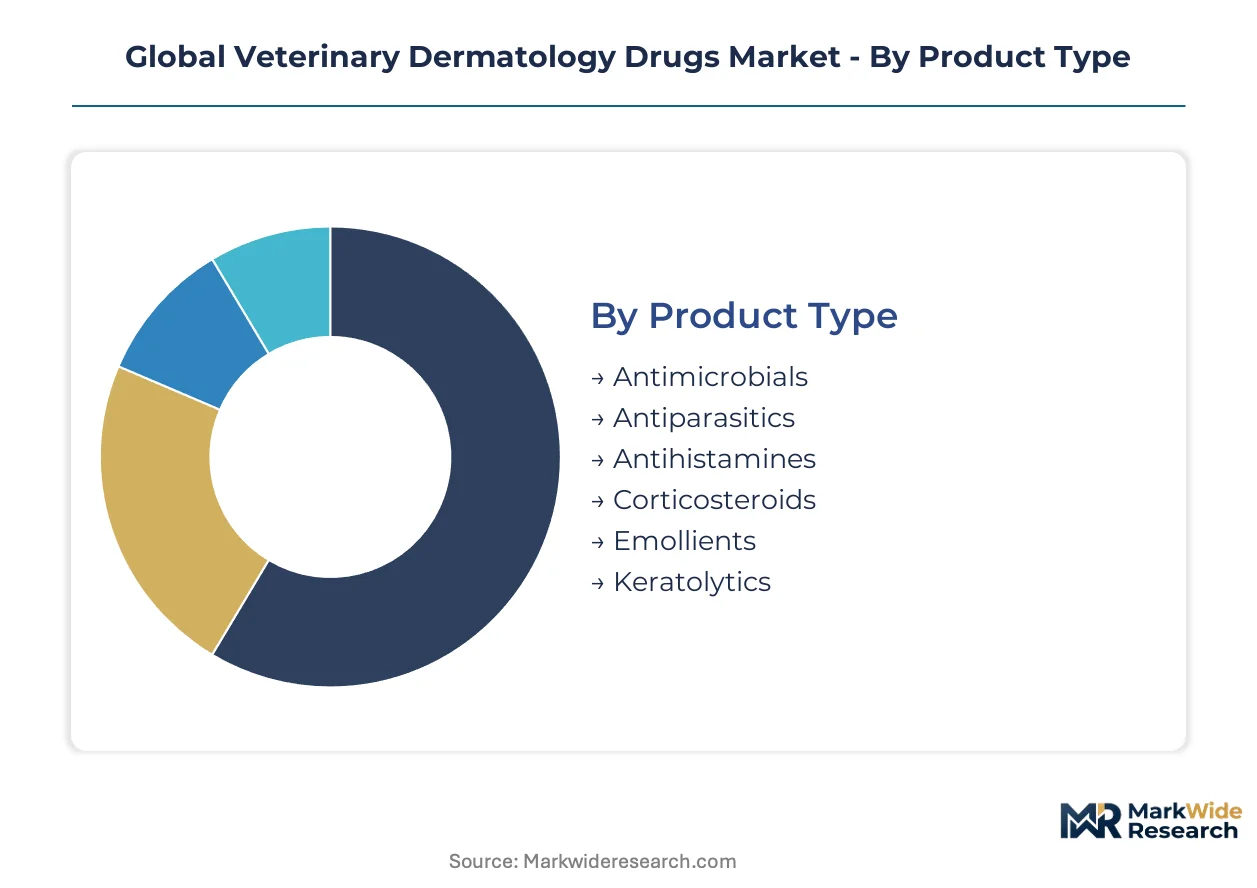
Veterinary dermatology drug segmentation reveals divergent capital requirements across therapeutic categories, with systemic formulations demanding substantially higher regulatory investment than topical alternatives. Understanding these structural cost tiers enables manufacturers to align R&D pipelines with accessible financing and manufacturing capabilities.
Product Type:
Capital intensity peaks in narrow-therapeutic-index compounds requiring dedicated bioavailability studies and metabolite profiling facilities.
- Antimicrobials:These agents target bacterial pyoderma and superficial infections through species-calibrated concentrations of cephalosporins, fluoroquinolones, and aminoglycosides. Demand clusters in metropolitan companion animal clinics across the United States, Germany, and Japan, where diagnostic cytology capabilities support culture-directed prescribing against rising resistance patterns.
- Corticosteroids:Synthetic glucocorticoids such as prednisolone, triamcinolone, and dexamethasone modulate inflammatory cascades in atopic dermatitis and immune-mediated skin disorders. Production concentrates in Indian and Chinese API synthesis hubs, exposing formulators to export license volatility and extended lead times for veterinary-grade starting materials.
- Antiparasitics:Macrocyclic lactones and isoxazolines address demodectic mange, sarcoptic mange, and flea allergy dermatitis through systemic or topical delivery.
- Antihistamines:H1-receptor antagonists provide symptomatic relief for histamine-mediated pruritus with minimal sedation profiles in canine patients.
- Emollients:Lipid-replenishing formulations restore epidermal barrier function in keratinization defects and contact dermatitis.
- Keratolytics:Salicylic acid and sulfur compounds accelerate desquamation in seborrheic disorders and localized hyperkeratosis.
Antimicrobials absorb the bulk of installed capacity; corticosteroids are expanding most quickly as metabolic engineering reduces adverse effect profiles.
Formulation:
Manufacturing scale economies favor high-throughput oral solid dose facilities over batch-limited topical compounding operations.
- Oral Tablets:Compressed dosage forms incorporate taste-masking coatings and species-appropriate excipients to ensure palatability across canine, feline, and equine patients. Tokyo, Sydney, and Toronto specialty clinics are restructuring service menus around monthly tablet protocols that eliminate owner compliance failures associated with daily topical application.
- Injectable Solutions:Parenteral formulations including depot corticosteroids and monoclonal antibody preparations enable clinic-controlled dosing with guaranteed bioavailability. German and Swiss veterinary teaching hospitals are adopting liposomal encapsulation vehicles for refractory deep pyoderma cases, compressing systemic antibiotic exposure duration.
- Topical Creams:Semisolid emulsions deliver actives through hydrated petrolatum or aqueous gel bases with pH stabilization between 6.2 and 7.5.
- Shampoos:Surfactant-based cleansing systems incorporate antimicrobial, antifungal, or keratolytic actives for bathing protocols in general practice settings.
- Sprays:Aerosol or pump-delivery systems enable rapid application to localized lesions or widespread dermatoses in fractious patients.
- Powders:Micronized particulate formulations provide dry application options for intertriginous areas and moisture-sensitive dermatoses.
Oral tablets dominate current manufacturing throughput; injectable solutions are climbing the fastest as compliance-optimized protocols displace home-administered regimens.
Animal Type:
Customer concentration and pricing power vary sharply between insured companion animal segments and commodity-exposed livestock categories.
- Companion Animals:Canine and feline patients generate the majority of dermatology drug revenue through insured specialty care in Dallas, Munich, and Melbourne metropolitan clusters. São Paulo and Rio de Janeiro veterinary networks are installing dedicated dermatology suites as Brazilian pet insurance penetration crosses critical mass thresholds.
- Livestock:Cattle and swine dermatology applications concentrate in feedlot and farrowing operations where economic treatment thresholds prioritize rapid return to production over complete resolution.
- Equines:Horses present unique formulation challenges due to extensive dermal surface area and sensitivity to corticosteroid-induced laminitis.
- Poultry:Intensive broiler and layer operations address fungal dermatoses and ectoparasitism through mass medication protocols in feed or water.
- Exotic Pets:Avian, reptile, and small mammal species require specialized dosing extrapolations and limited pharmacokinetic validation.
- Farmed Fish:Aquaculture operations in the Netherlands and Denmark face steep compliance retrofit requirements under REACH amendments targeting pharmaceutical environmental discharge.
Companion animals command the dominant revenue share; livestock applications are gaining share fastest as antimicrobial stewardship redirects production animal prescribing toward validated therapeutic pipelines.
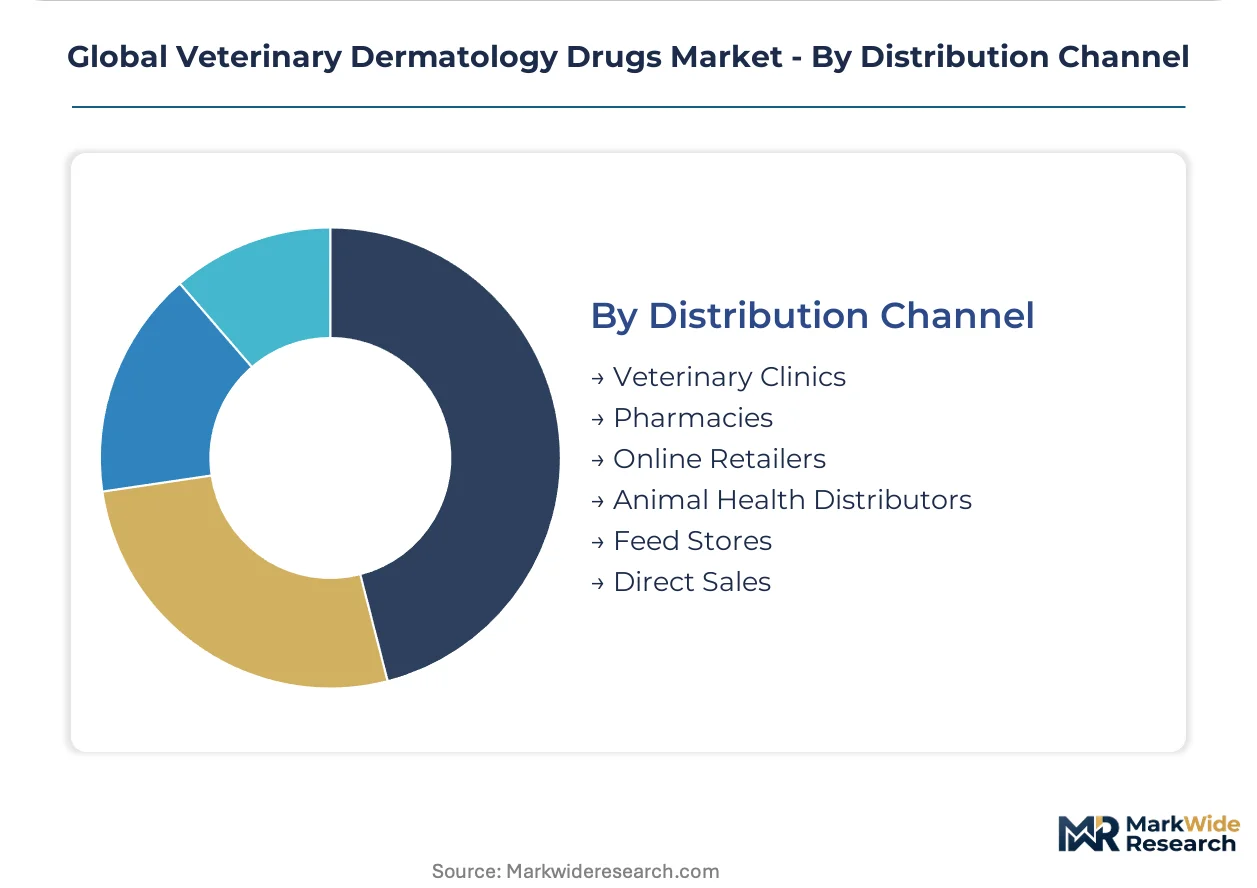
Distribution Channel:
Channel economics reflect divergent service intensity requirements, with clinic-administered protocols capturing premium pricing over self-administered alternatives.
- Veterinary Clinics:Primary and specialty practice settings deliver diagnosis-integrated prescribing with therapeutic drug monitoring and serial cytological evaluation. Boehringer Ingelheim Animal Health reaches over 20,000 European veterinary clinics through established distribution infrastructure.
- Animal Health Distributors:Regional and national wholesalers consolidate procurement for independent practices and feed store networks.
- Pharmacies:Human pharmacy compounding of veterinary formulations siphons price-sensitive cases from approved drug portfolios in cash-pay segments.
- Online Retailers:E-commerce platforms enable direct-to-consumer access for maintenance therapies and prescription refills with verified veterinary authorization.
- Feed Stores:Agricultural supply outlets serve livestock and equine segments with over-the-counter topical and pour-on products.
- Direct Sales:Manufacturer field representatives engage large corporate practice groups and institutional accounts with volume contracting.
Veterinary clinics retain the largest prescription volume; online retailers are expanding most quickly as digital symptom assessment platforms route confirmed cases to specialty services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian and Chinese chemical synthesis hubs anchor corticosteroid active pharmaceutical ingredient production, exposing formulators to export license volatility and shipping lane disruptions that ripple through veterinary dermatology supply chains worldwide.
United States
Metropolitan companion animal clinics in Dallas, Houston, and Phoenix are expanding dedicated dermatology service lines as pet insurance penetration crosses critical thresholds. The FDA Center for Veterinary Medicine maintains stringent approval pathways for topical and systemic therapeutics. Specialty practices cluster in high-income suburbs where diagnostic cytology capabilities support culture-directed prescribing against rising resistance patterns.
Germany
Veterinary teaching hospitals in Munich and Berlin are adopting liposomal encapsulation vehicles for refractory deep pyoderma cases. The EMA Committee for Medicinal Products for Veterinary Use coordinates centralized marketing authorizations across member states. REACH regulation amendments are forcing reformulation of shampoo products containing persistent antimicrobial agents, with manufacturers substituting biodegradable quaternary ammonium compounds.
Brazil
São Paulo and Rio de Janeiro veterinary networks are installing dedicated dermatology suites as Latin America's largest economy sees pet insurance adoption accelerate. ANVISA regulates veterinary pharmaceutical registrations with residue depletion study requirements for novel actives. Specialty clinic density in southeastern state capitals is standardizing systemic treatment protocols that require clinic-administered dosing.
Japan
Tokyo and Osaka specialty practices are restructuring service menus around monthly injectable monoclonal antibody alternatives that eliminate owner compliance failures. METI guidelines shape pharmaceutical manufacturing standards for companion animal therapeutics. Pet owner preference for fixed-interval clinic appointments over home-administered topical regimens is consolidating demand around depot injectable formulations.
Australia
Melbourne and Sydney metropolitan clusters generate concentrated demand for insured specialty dermatology care with therapeutic drug monitoring capabilities. The TGA governs veterinary medicine approvals with post-market surveillance requirements. Digital symptom assessment platforms are routing suspected atopic dermatitis cases to specialty clinics for confirmatory intradermal testing, expanding addressable case volume.
Global Veterinary Dermatology Drugs Market Competitive Landscape
Global majors compete with regional champions across manufacturing scale and therapeutic specialization, producing a tiered structure where vertically integrated networks face off against narrow-therapeutic-index specialists. The vendor base clusters around three archetypes: diversified animal health conglomerates with captive API supply, mid-cap dermatology-focused developers with dedicated R&D facilities, and distribution-heavy European channel dominators. Consolidation pressure is accelerating through backward integration into corticosteroid synthesis and geographic expansion into Brazilian and Australian metropolitan markets.
Within the diversified animal health tier, Zoetis and Merck Animal Health occupy positions defined by manufacturing network breadth and species-spanning therapeutic portfolios. Dechra Pharmaceuticals exemplifies the narrow-therapeutic-index specialist archetype through its concentrated focus on dermatology compounds. Boehringer Ingelheim Animal Health anchors the European channel dominance model with distribution infrastructure reaching veterinary clinics across multiple countries. These three company types represent the competitive poles around which smaller players must position.
| Leading Market Players |
|---|
| Ceva Sante Animale |
| Merck Animal Health |
| Zoetis |
| Bimeda |
| Vetoquinol |
| Elanco Animal Health |
| Boehringer Ingelheim Animal Health |
| Dechra Pharmaceuticals |
| Virbac |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between FDA-validated therapeutics and unregulated compounded alternatives splits pricing power across distinct procurement channels, with validated portfolios commanding premium positioning through bundled diagnostic protocols while cash-pay segments absorb price-sensitive substitution. This bifurcation concentrates margin capture in clinic-administered systemic formulations while compressing returns on topical generics exposed to pharmacy compounding competition.
Pricing Analysis
Diagnostic-service bundling separates premium-tier specialty dermatology protocols from unbundled commodity topical sales, with metropolitan clinics in Dallas and Munich packaging intradermal testing with therapeutic drug monitoring into fixed-interval subscription plans. Price differentiation rests on FDA Center for Veterinary Medicine validation status and ISO 17025 quality certification, with validated narrow-therapeutic-index compounds sustaining 40-60 point gross margin premiums over compounded substitutes. Pricing pressure stems from unregulated pharmacy compounding of triamcinolone and chlorhexidine formulations siphoning volume from insured specialty segments. Cash-pay generalist clinics exhibit highest price sensitivity, while insured specialty practices in high-penetration metropolitan clusters demonstrate lowest elasticity.
Supply Chain Analysis
Reverse-logistics flows for temperature-sensitive biologic formulations remain underdeveloped, with depot corticosteroid and monoclonal antibody returns concentrated in manufacturer-sponsored takeback programs lacking standardized refurbishment pathways. Corticosteroid active pharmaceutical ingredient production clusters in India and China, with veterinary-grade starting materials drawing from chemical synthesis hubs in Hyderabad and Shanghai. Key dependencies include macrocyclic lactone precursors, liposomal encapsulation phospholipids, and species-calibrated excipient blends. Single-source vulnerability in Indian API export licensing exposes formulators to shipping lane disruptions through the Red Sea corridor. Distribution runs through Boehringer Ingelheim's European veterinary clinic network and Zoetis's vertically integrated North American channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where FDA Center for Veterinary Medicine approval pathways and EMA residue depletion study requirements erect substantial barrier-to-entry moats, consolidating returns among players with dedicated regulatory affairs infrastructure and multi-year study financing capacity.
For Market Incumbents: Anchor market position through backward integration into corticosteroid API synthesis and captive supply of narrow-therapeutic-index compounds, countering the threat of Indian and Chinese export license volatility. Expand capacity in Brazilian metropolitan clusters where São Paulo and Rio de Janeiro specialty clinic density is accelerating, leveraging ANVISA registration expertise to preempt emerging local formulators.
For New Entrants and Emerging Players: Cash-pay generalist clinics in secondary US metropolitan areas represent the most penetrable buyer archetype, with unmet demand for cost-competitive antimicrobial alternatives to compounded substitutes. Target telemedicine-triage platforms routing atopic dermatitis cases to specialty confirmation as a channel partnership angle, bypassing entrenched distributor relationships.
For Investors and Strategic Acquirers: Exit pathways concentrate in mid-cap dermatology-focused developers with dedicated UK and US R&D facilities and established EMA centralized marketing authorizations. Long-term viability across the analysis window favors players with biologic tolerance engineering capabilities and liposomal encapsulation manufacturing assets. Monitor antimicrobial stewardship guideline expansion as the critical inflection signal for portfolio repositioning away from chronic corticosteroid dependence.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA Center for Veterinary Medicine validation secures premium pricing in insured metropolitan clinics. |
| Backward Integration | In-house corticosteroid API production insulates margins from Indian export license volatility. |
| Manufacturing Scale-Up | Liposomal encapsulation capacity expansion serves German and Swiss teaching hospital adoption. |
| Geographic Expansion | Brazilian metropolitan clinic penetration captures accelerating pet insurance adoption in São Paulo. |
| Pipeline Diversification | Monoclonal antibody maintenance therapy addresses owner compliance fatigue in atopic dermatitis. |
Research Methodology
FDA filings, EMA centralized marketing authorization databases, and ANVISA veterinary pharmaceutical registries formed the secondary backbone, cross-referenced with customs records of API import flows and ISO 17025 certification audits. Primary interviews with regulatory affairs directors at animal health conglomerates, specialty veterinary dermatology practice owners in Dallas and Munich, and procurement leads at European animal health distributors validated demand assumptions. Bottom-up and top-down triangulation reconciled clinic-level prescribing data with manufacturer-reported revenue segmentation.
Bottom-up modeling aggregated species-specific metabolic clearance rates, diagnostic cytology adoption curves, and pet insurance penetration thresholds across metropolitan clusters, while top-down analysis calibrated aggregate market size against veterinary pharmaceutical trade flows. Segmentation dimensions included therapeutic category, formulation type, animal species, and distribution channel complexity. CAGRs derived from fitted adoption curves for clinic-administered systemic protocols and owner compliance-adjusted persistence rates for maintenance therapies.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to antimicrobial stewardship guideline expansion and REACH environmental discharge enforcement. Projections assume stable API export licensing from Indian and Chinese synthesis hubs and continued specialty clinic consolidation in insured metropolitan markets. Practitioners should monitor EMA residue depletion study requirement amendments and Brazilian pet insurance regulatory reforms for early signals of structural shift.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dermatology
Androgenetic Alopecia Market
Dermatology
Hyperpigmentation Treatment Market
Dermatology
Global Onychomycosis Market
Dermatology
US and Canada Skin Cancer Dermatology Market
Dermatology
Japan Scar Treatment Market
Dermatology
Lichen Sclerosus Treatment Market
Dermatology
Global Radiodermatitis Market
Dermatology
Dermabrasion and Micro Needling Market
Dermatology
Global Dermatology Excimer Laser Market
Dermatology
Europe Scar Treatment Market
Dermatology
Impetigo Treatment Market
Dermatology
Global Dermatitis Herpetiformis Market
Dermatology
Dermatology Cryosurgery Units Market
Dermatology
Chronic Spontaneous Urticaria Market
Dermatology
Acne Scar Treatment Market
Dermatology
Australia Skin Treatment Market