
 Global Ozone Therapy in Dermatology Market | 2026-2036
Global Ozone Therapy in Dermatology Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ozone Therapy in Dermatology Market Foresight
The distinction between medical dermatology clinics and wellness-oriented beauty spas is collapsing as both segments invest in certified ozone delivery infrastructure. MEDOZONS Ltd. leverages its concentration on clinical-grade ozone generators to anchor the professional dermatology channel across Eastern Europe. Zotzmann + Stahl GmbH + Co. KG sustains German engineering credibility through precision gas concentration controls that dominate hospital procurement protocols. Promolife differentiates via direct-to-practice distribution models that bypass traditional medical device wholesalers in North American markets.
Ozone therapy in dermatology deploys medical-grade ozone gas or ozonated derivatives to modulate oxidative stress, enhance tissue oxygenation, and accelerate cutaneous repair through controlled redox signaling. Concentrations typically range from 10 to 80 micrograms per milliliter depending on indication, with topical ozonated oils serving chronic wound management and autohemotherapy addressing systemic inflammatory dermatoses. Ozonated oils command the deepest margin pools among product types due to formulation complexity and shelf-stability requirements. Autohemotherapy devices represent the fastest-growing delivery mode segment as clinicians seek systemic alternatives to topical limitations in severe psoriasis and refractory acne protocols.
FDA clearance pathways for ozone dermatology devices intersect with EPA regulations on medical gas generation equipment, creating dual compliance burdens for manufacturers targeting US market entry. The EU Medical Device Regulation and REACH chemical safety standards collectively shape formulation and labeling requirements for ozonated topical products sold across European dermatology practices. Stakeholders must monitor evolving reimbursement decisions by Germany's Federal Joint Committee and comparable national health technology assessment bodies, as these determinations will dictate whether clinical ozone expands from alternative therapy niches into mainstream dermatological protocols.
Market Dynamics
The dermatology ozone market pivots on Germany's Federal Joint Committee reimbursement decisions, which determine whether clinical protocols graduate from alternative niches into standard-of-care coverage across European practice networks.
Growth Catalysts
- EU Medical Device Regulation harmonization:MDR quality thresholds for topical ozone delivery systems create certification moats that filter out low-grade competitors and elevate compliant manufacturers into hospital procurement channels.
- Autohemotherapy device innovation:Systemic delivery modes address refractory psoriasis and severe acne cases where topical ozone reaches physiological limits, expanding addressable patient populations.
- German reimbursement pathway maturity:Established medical ozone coverage in Germany provides a template for neighboring health technology assessment bodies evaluating clinical evidence thresholds.
Market Restraints
- Dual compliance architecture:FDA clearance intersecting with EPA medical gas generation rules imposes overlapping validation burdens on US market entrants, extending time-to-revenue timelines.
- Formulation stability constraints:Ozonated oil shelf-life requirements demand cold-chain infrastructure and antioxidant stabilization chemistry that elevates unit economics above commodity topical alternatives.
- Concentration standardization gaps:Absence of unified ISO protocols for ozone dosing in dermatological indications forces clinicians to navigate conflicting national guidelines.
Strategic Opportunities
- Eastern European practice consolidation:Poland and Czech Republic dermatology clinic chains lack certified ozone infrastructure, creating first-mover positioning for equipment suppliers with CE-marked systems.
- REACH-compliant topical formulations:Chemical safety registration pathways for ozonated derivatives open premium positioning for manufacturers investing in toxicological dossiers.
- Direct-to-practice distribution:Bypassing traditional medical device wholesalers in North American markets compresses channel margins and accelerates clinical adoption velocity.
Industry Challenges
- Redox biology expertise scarcity:Dermatology practices lack personnel trained in oxidative stress modulation protocols, constraining protocol adherence and outcome consistency.
- Capital equipment intensity:Clinical-grade ozone generators require dedicated ventilation infrastructure and gas monitoring systems that inflate facility upgrade costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ozone Therapy in Dermatology Market |
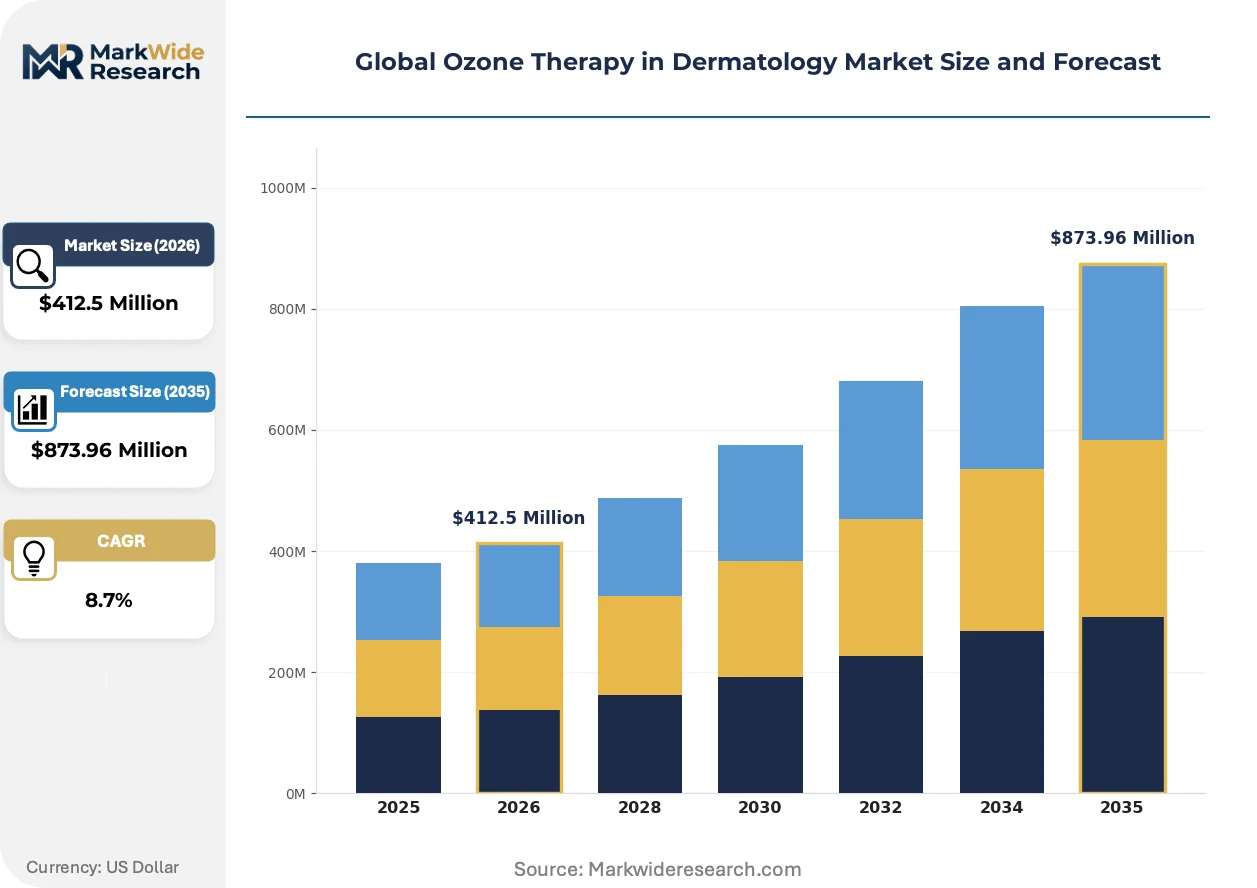
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $873.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ozone Gas Generators, Ozonated Oils, Ozonated Water, Ozone Autohemotherapy Devices, Ozone Creams, Ozone Injectors Application: Acne Treatment, Psoriasis Relief, Wound Healing, Anti-Aging Therapy, Skin Whitening, Hair Regrowth Stimulation End User: Dermatology Clinics, Beauty Spas, Cosmetic Surgery Centers, Medical Research Institutes, Alternative Therapy Centers, Wellness Clinics Delivery Mode: Topical Application, Autohemotherapy, Injection, Insufflation, Bagging Technique, Ozonated Water Rinses |
| Companies Covered | MEDOZONS Ltd., Zotzmann + Stahl GmbH + Co. KG, The Ozone Company, Promolife, Ozolabs, LLC, O3organics, Humares GmbH, Dr. J. Hänsler GmbH, Apoza Enterprise Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ozone Therapy in Dermatology Market Shifts & Advancements
Ozone delivery technology is fragmenting across precision-controlled medical devices and wellness-oriented spa equipment, with regulatory compliance becoming the decisive wedge between segments.
Closed-loop ozone concentration control systems now enable real-time gas dosing adjustments based on tissue oxygenation feedback. Hospital dermatology departments in Germany and Switzerland are adopting these platforms for chronic wound protocols. The technology is bifurcating the market into precision-medical tier and unregulated wellness tier, compressing margins for mid-grade equipment lacking clinical certification.
REACH chemical safety standards are tightening labeling and formulation requirements for ozonated topical products sold across European dermatology practices. Manufacturers must submit expanded toxicological dossiers for ozonated oil derivatives, elevating compliance costs for smaller formulators. German and French regulators are coordinating enforcement priorities, with ANSM and BfArM issuing joint guidance on stability testing protocols.
Beauty spas and medical dermatology clinics are converging on identical ozone delivery infrastructure, though certification requirements diverge sharply. Spas purchase uncertified equipment through aesthetic supply channels, while clinics demand MDR-compliant systems with traceable calibration records. This channel compression is most visible in Spain and Italy, where wellness chains are acquiring clinical-grade systems to differentiate against unregulated competitors.
Global Ozone Therapy in Dermatology Market Segmentation
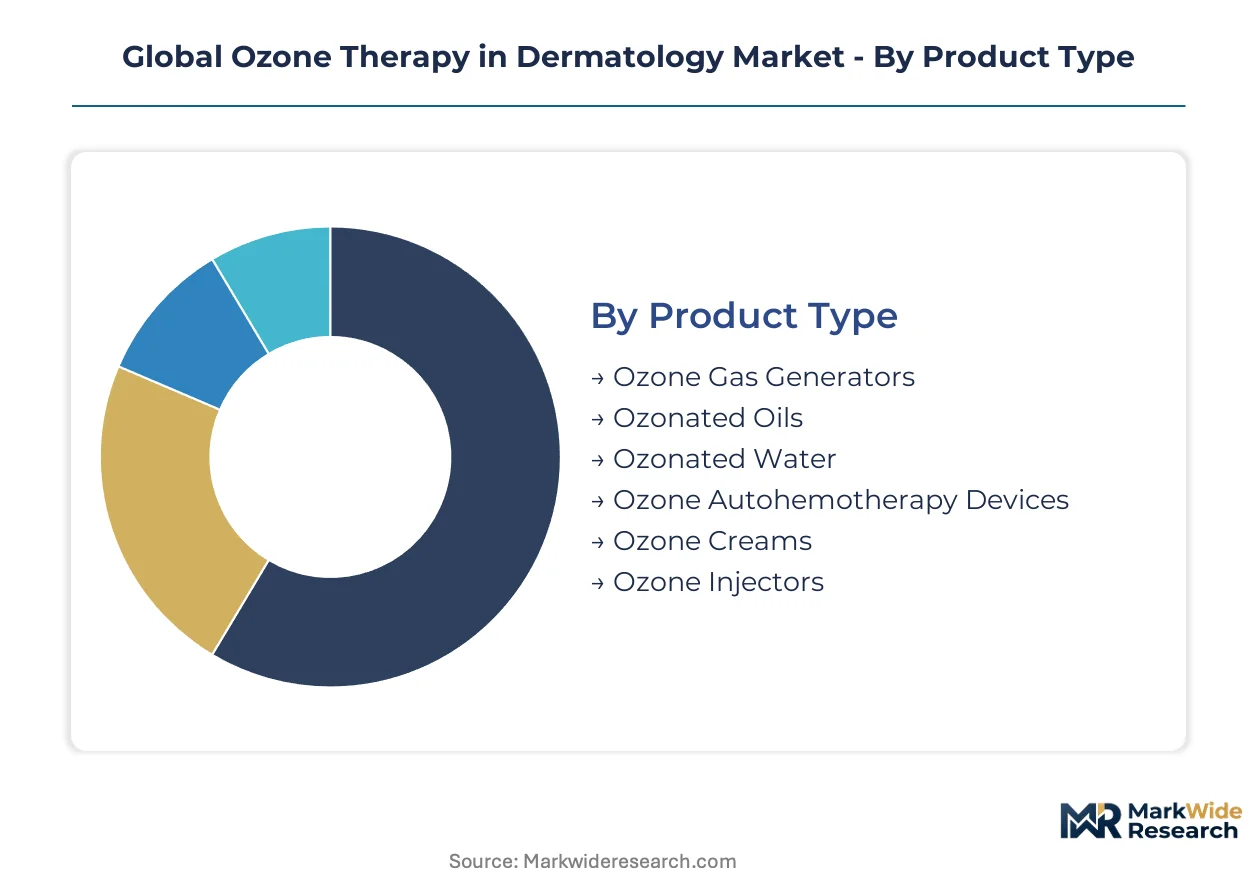
Ozone therapy's dermatological deployment fragments across equipment, consumables, and delivery methodologies that each carry distinct regulatory burdens and margin profiles. Understanding where value concentrates within these taxonomies clarifies capital allocation priorities for manufacturers and clinical procurement strategies for practice networks.
Product Type:
Margin pools concentrate in formulation-intensive consumables where shelf-stability chemistry and cold-chain infrastructure create defensible premium positioning against commodity alternatives.
- Ozonated Oils:Lipid-based carriers infused with ozone gas at 10-80 micrograms per milliliter concentrations, requiring antioxidant stabilization and refrigerated logistics to maintain therapeutic potency. Demand clusters in German wound care protocols where reimbursement codes support premium pricing for chronic ulcer management. Formulation complexity elevates unit economics above aqueous alternatives.
- Ozone Autohemotherapy Devices:Closed-loop systems enabling extracorporeal blood ozonation and reinfusion for systemic inflammatory dermatoses. Clinicians in Switzerland and Austria are deploying these platforms for refractory psoriasis cases where topical delivery reaches physiological limits. Device innovation here is climbing the fastest share trajectory as systemic protocols expand addressable patient populations.
- Ozone Gas Generators:Medical-grade electrochemical or corona discharge units producing precise ozone concentrations for clinical deployment.
- Ozonated Water:Aqueous ozone solutions for rinsing protocols and superficial antimicrobial applications.
- Ozone Creams:Emulsion-based topical formulations combining ozone with dermatological excipients.
- Ozone Injectors:Precision delivery instruments for subcutaneous and intradermal ozone administration.
Ozonated oils hold installed capacity in European wound care networks. Autohemotherapy devices are rotating up the share rankings as systemic protocols gain clinical validation.
Application:
Volume concentration tracks reimbursement pathway maturity, with covered indications commanding procurement priority over cosmetic adjacencies lacking insurance support.
- Wound Healing:Chronic ulcer and diabetic foot protocols utilizing ozonated dressings and topical gas application to modulate oxidative stress and accelerate granulation tissue formation. German hospital dermatology departments have integrated these protocols into standard order sets, creating predictable demand cadences for consumable suppliers.
- Psoriasis Relief:Systemic autohemotherapy and topical ozone combinations addressing plaque severity and inflammation biomarkers. Swiss clinics are reporting protocol adherence improvements when ozone complements biologic tapering strategies. This application is expanding most quickly as clinicians seek steroid-sparing alternatives.
- Acne Treatment:Antimicrobial and seboregulatory ozone protocols for inflammatory and cystic presentations.
- Anti-Aging Therapy:Cosmetic ozone applications targeting dermal collagen remodeling and oxidative stress modulation.
- Skin Whitening:Melanin-inhibiting ozone protocols primarily deployed in Asian aesthetic markets.
- Hair Regrowth Stimulation:Scalp ozone application for androgenetic alopecia and alopecia areata protocols.
Wound healing anchors reimbursement-supported demand. Psoriasis relief is rotating up the share rankings as evidence accumulates for systemic ozone efficacy.
End User:
Customer type stratification reflects certification divergence between medical-grade and wellness-oriented deployment, with procurement authority concentrating in clinically credentialed settings.
- Dermatology Clinics:Physician-supervised practices demanding MDR-compliant equipment with traceable calibration records and outcome documentation protocols. These facilities in Germany and France drive premium equipment adoption and establish protocol templates that diffuse to neighboring markets.
- Beauty Spas:Wellness-oriented establishments purchasing uncertified equipment through aesthetic supply channels, converging on identical physical infrastructure but lacking clinical validation requirements. Spanish and Italian spa chains are upgrading to clinical-grade systems to differentiate against unregulated competitors.
- Cosmetic Surgery Centers:Hybrid facilities bridging medical and aesthetic ozone applications.
- Medical Research Institutes:Academic dermatology departments conducting clinical trials and protocol development.
- Alternative Therapy Centers:Naturopathic and integrative medicine practices deploying ozone outside conventional dermatology.
- Wellness Clinics:Preventive health facilities incorporating ozone into broader metabolic optimization protocols.
Dermatology clinics hold installed capacity in certified equipment networks. Beauty spas are rotating up the share rankings as wellness-medical boundaries blur.
Delivery Mode:
Technical sophistication and regulatory classification intensity vary sharply across administration routes, with invasive modalities facing steeper validation burdens.
- Topical Application:Direct gas exposure or ozonated product application to cutaneous surfaces, dominating procedure volume due to minimal training requirements and broad indication coverage. German outpatient clinics have standardized concentration protocols for eczema and superficial infection management.
- Autohemotherapy:Extracorporeal blood treatment requiring specialized devices and phlebotomy protocols, representing the steepest expansion trajectory among delivery modes as systemic dermatoses demand alternatives to topical physiological limits.
- Injection:Subcutaneous and intradermal ozone administration for localized inflammatory conditions.
- Insufflation:Body cavity ozone delivery with limited dermatological relevance.
- Bagging Technique:Limb enclosure with ozone gas for localized extremity conditions.
- Ozonated Water Rinses:Aqueous ozone application for superficial antimicrobial and cleansing protocols.
Topical application holds installed capacity across practice types. Autohemotherapy is rotating up the share rankings as device innovation reduces procedural complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment manufacturing clusters in Germany and Switzerland supply precision ozone generators to dermatology networks across Europe, while regulatory divergence between FDA and EPA frameworks fragments US market entry pathways.
Germany
Federal Joint Committee reimbursement decisions for medical ozone protocols drive hospital procurement cycles in Berlin and Munich. The BfArM coordinates with ANSM on stability testing standards for ozonated topicals. North Rhine-Westphalia hosts the densest concentration of clinical-grade generator production facilities serving EU hospital networks.
United States
Dermatology practices in Florida and California navigate dual FDA device clearance and EPA medical gas generation compliance for ozone equipment deployment. The EPA's overlapping jurisdiction on ozone-generating equipment extends validation timelines for manufacturers targeting outpatient clinic channels. Greater Boston research hospitals pilot closed-loop concentration control systems for chronic wound protocols.
Switzerland
Swissmedic certification requirements for autohemotherapy devices position Zurich and Geneva clinics as early adopters of systemic ozone protocols for refractory psoriasis. The country's precision engineering heritage translates into demand for traceable calibration records in hospital procurement specifications. Basel-area manufacturers supply MDR-compliant systems to neighboring EU markets.
Spain
Beauty spa chains in Madrid and Barcelona are acquiring clinical-grade ozone infrastructure to differentiate against unregulated wellness competitors. The Spanish Agency for Medicines and Health Products enforces MDR compliance thresholds that filter equipment into certified versus aesthetic supply channels. Catalonia leads practice consolidation among dermatology clinic networks seeking CE-marked systems.
Poland
Dermatology clinic chains in Warsaw and Krakow lack certified ozone infrastructure, creating positioning opportunities for CE-marked equipment suppliers. The country's national pharmaceutical regulator evaluates German reimbursement templates for potential protocol adoption. Silesian manufacturing zones host emerging distributors serving Eastern European practice networks.
Global Ozone Therapy in Dermatology Market Competitive Landscape
Concentration sits with precision-engineering specialists and clinical-grade equipment fabricators that have secured MDR certification moats. The vendor base stratifies across German-engineered hospital systems, Eastern European value-positioned platforms, and North American direct-distribution challengers. Two dominant archetypes define competitive positioning: engineering-credibility anchors with traceable calibration protocols, and channel-bypass specialists compressing margin structures through direct-to-practice logistics. Competitive moves center on MDR dossier completion for EU hospital procurement eligibility and geographic expansion into undercertified Eastern European markets.
Among German-engineered specialists, Zotzmann + Stahl GmbH + Co. KG and Dr. J. Hänsler GmbH exemplify the precision-control archetype that dominates hospital procurement protocols through traceable gas concentration systems. MEDOZONS Ltd. represents the Eastern European value-positioned tier, anchoring professional dermatology channels across Poland and Czech Republic markets with CE-marked platforms. Promolife occupies the North American direct-distribution position, bypassing traditional medical device wholesalers to accelerate clinical adoption velocity in outpatient practice networks.
| Leading Market Players |
|---|
| MEDOZONS Ltd. |
| Zotzmann + Stahl GmbH + Co. KG |
| The Ozone Company |
| Promolife |
| Ozolabs, LLC |
| O3organics |
| Humares GmbH |
| Dr. J. Hänsler GmbH |
| Apoza Enterprise Co., Ltd. |
| Others |
Supply & Pricing Matrix
Antioxidant stabilization chemistry replacing cold-chain dependence as the primary shelf-life preservation method simultaneously relocates formulation capacity toward chemical processing clusters in Germany and Switzerland while compressing premium pricing power for ozonated oil producers.
Pricing Analysis
EU Medical Device Regulation dictates the pricing tier structure across ozone dermatology equipment, separating MDR-certified clinical systems from uncertified wellness-tier alternatives. Pricing stratifies across premium hospital-grade generators with traceable calibration records, mid-tier outpatient clinic platforms, and economy spa-oriented equipment lacking clinical validation. Cost compression in the wellness tier is intensifying as Spanish and Italian spa chains upgrade to certified systems, eroding margin pools for non-compliant manufacturers. Hospital procurement committees in Berlin and Munich exhibit the lowest price sensitivity due to reimbursement coverage, while independent dermatology practices in Eastern Europe prioritize capital efficiency over certification premiums.
Supply Chain Analysis
Germany and Switzerland anchor precision ozone generator manufacturing, with North Rhine-Westphalia and Basel-area facilities supplying MDR-compliant systems to EU hospital networks. Electrochemical cell components and medical-grade gas monitoring sensors draw from specialized semiconductor fabrication in the Netherlands and Austria. Single-source vulnerability concentrates in corona discharge electrode supply, where a limited qualified supplier base creates procurement bottlenecks during demand surges. Distribution runs through medical device wholesalers in continental Europe, while North American channels increasingly favor direct-to-practice logistics that bypass traditional distributor markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
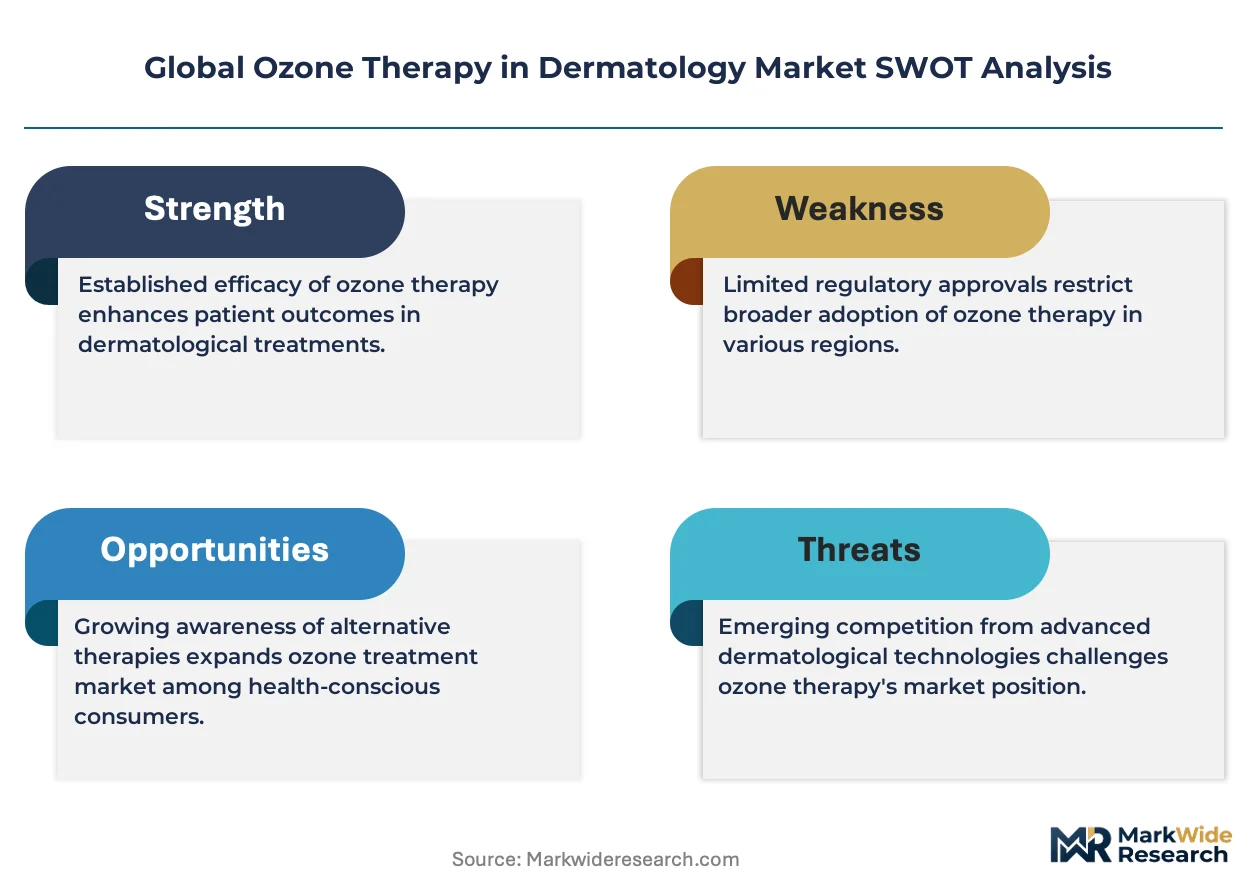
Incumbents must defend against photobiomodulation and low-level laser therapy as substitute modalities encroach on wound healing and anti-inflammatory indications, eroding ozone's procedural volume in reimbursed dermatology protocols.
For Market Incumbents: Fortify certification moats by accelerating MDR dossier completion for next-generation autohemotherapy platforms before REACH chemical safety standards tighten further. Secure backward integration into ozonated oil formulation capacity to capture margin pools currently diverted to third-party chemical processors. Counter the photobiomodulation substitution threat by embedding closed-loop tissue oxygenation feedback as a differentiable clinical outcome metric in hospital procurement specifications. For New Entrants and Emerging Players: CE marking fast-track through notified body partnerships in Poland and Czech Republic opens positioning in undercertified Eastern European dermatology clinic chains lacking ozone infrastructure. Target Warsaw and Krakow practice networks where German reimbursement templates are under regulatory evaluation. Penetrate via equipment-leasing models that reduce capital barriers for clinic chains consolidating multi-site procurement. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed German engineering specialists holding hospital procurement relationships but requiring refresh capital for autohemotherapy device innovation. Five-to-ten year viability hinges on systemic delivery modes displacing topical limitations in severe psoriasis protocols. Monitor Federal Joint Committee reimbursement expansion decisions as the inflection signal for mainstream protocol adoption beyond alternative therapy niches.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Certification Pathway Completion | Unlocks hospital procurement channels in Germany and France under BfArM and ANSM coordination. |
| Autohemotherapy Device Innovation | Addresses refractory psoriasis cases where topical ozone reaches physiological limits in Swiss clinics. |
| Eastern European Geographic Expansion | Captures first-mover positioning in Polish and Czech dermatology clinic consolidation waves. |
| REACH-Compliant Formulation Investment | Secures premium positioning for ozonated oil derivatives under tightening ECHA chemical safety standards. |
| Direct-to-Practice Distribution Buildout | Compresses channel margins and accelerates adoption velocity in North American outpatient networks. |
Research Methodology
The analysis maps ozonated oil formulations, autohemotherapy devices, and gas generator systems, each validated through hospital procurement managers, dermatology clinic directors, and biomedical engineering specialists. Primary interviews with GPO contracts managers and regulatory affairs leads at MDR-notified bodies combined with secondary validation against EMA device registrations, BfArM safety notifications, and hospital procurement database extracts. Bottom-up equipment shipment tracking and top-down reimbursement code analysis triangulate market sizing across the projection horizon.
Consistency checks against external benchmarks validated volume and value outputs across product type, application, end user, and delivery mode segmentation dimensions. CAGRs derive from procedure volume elasticity to reimbursement coverage expansion and equipment replacement cycles in hospital dermatology departments. Forecast inputs incorporate autohemotherapy protocol adoption curves in Swiss and Austrian clinics and REACH compliance cost trajectories for ozonated topical manufacturers.
Underlying assumptions cover reimbursement pathway maturation in Germany and stability testing protocol harmonization between ANSM and BfArM, with deviation risk concentrated in Federal Joint Committee coverage decisions and EPA-FDA jurisdictional friction for US market entrants. Recalibration cycles align with material shifts in MDR enforcement priorities and systemic ozone clinical evidence publication.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dermatology
Skin Hyperpigmentation Treatment Market
Dermatology
Global Dermatological OTC Drugs Market
Dermatology
Porokeratosis Treatment Market
Dermatology
Pigmented Lesion Treatment Market
Dermatology
Derma Rollers Market
Dermatology
Erythema Treatment Market
Dermatology
Seborrheic Keratosis Market
Dermatology
Dermatology Devices Market
Dermatology
Global Radiodermatitis Market
Dermatology
Scleroderma Treatment Market
Dermatology
Dermabrasion Market
Dermatology
Inflammatory Skin Diseases Treatment Market
Dermatology
Alopecia Treatment (Hair Loss) Market
Dermatology
Seborrheic Keratosis Treatment Market
Dermatology
Immunodermatology Market
Dermatology
Global Dermatological Therapeutics Market