
 Dermatology Software Market | 2026-2036
Dermatology Software Market Size, Share, and Industry Trends Forecast 2026-2036
Dermatology Software Market Intelligence
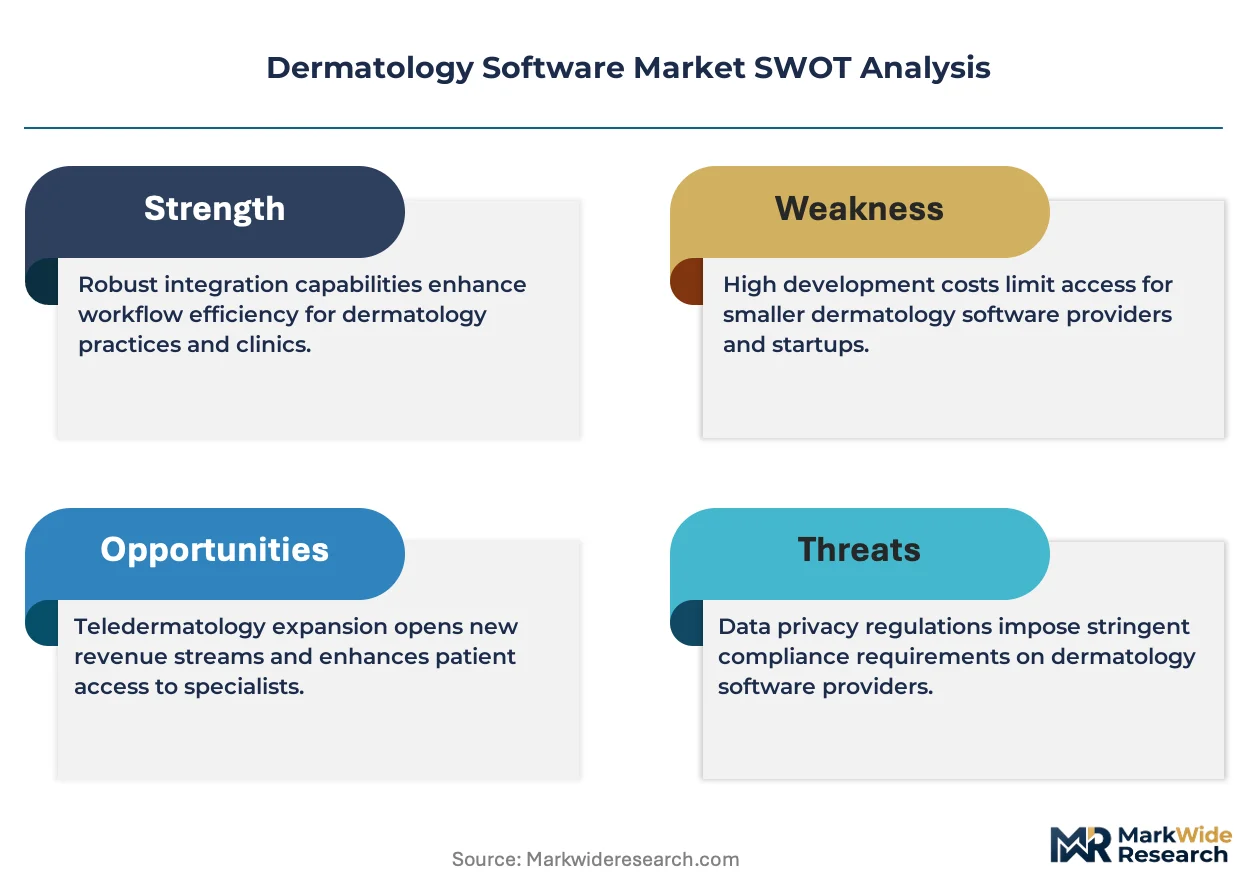
The growing fragmentation of end-users, from large hospital networks to specialized aesthetic centers, is decoupling software procurement from traditional enterprise-wide IT purchasing cycles. Epic Systems sustains its position within large integrated delivery networks that prioritize system-wide data consistency. In contrast, ModMed specializes in cloud-based solutions tailored for dermatology-specific workflows in independent practices. PatientNow competes by offering integrated practice management and marketing tools designed for smaller, growth-oriented clinics.
Dermatology software comprises specialized healthcare information technology designed for dermatological practices. These platforms often integrate high-resolution imaging capabilities, adhering to standards like DICOM for medical image handling, to aid in diagnosis and treatment planning. Teledermatology platforms represent the fastest-growing product segment, driven by the shift towards remote consultations. Within deployment models, cloud-based SaaS solutions are displacing legacy on-premise systems due to lower upfront costs and easier scalability for clinics of all sizes.
Regulatory oversight from bodies like the US FDA and Europe's MDR framework classifies certain AI-powered diagnostic tools as medical devices. This classification mandates rigorous clinical validation and quality management systems, influencing development costs and market entry timelines for vendors. Vendor success will hinge on navigating the complex compliance landscape while delivering a user experience that justifies a specialized solution over a generic electronic health record system.
Market Dynamics
The market's central dynamic is the tension between demand for highly specialized clinical workflows and the need for interoperability with generalist hospital information systems. This conflict drives purchasing decisions, forcing vendors to balance niche feature development against broad enterprise compatibility to capture value from both independent clinics and large health networks.
Growth Catalysts
- National Digitalization Policies:Government-led healthcare digitalization initiatives, such as those in Germany, create direct incentives and mandates for practices to adopt certified electronic health record and practice management software, accelerating market penetration.
- Teledermatology Adoption:The expansion of telehealth services provides a powerful catalyst for teledermatology platforms, which enable remote consultations, image sharing, and follow-up care, meeting patient demand for convenient access.
- Aesthetic Medicine Expansion:The growth of specialized aesthetic centers and medspas creates a distinct end-user segment seeking software with integrated marketing, patient relationship management, and cosmetic procedure tracking features.
Market Restraints
- High Implementation Costs:The significant upfront investment and ongoing subscription fees for specialized dermatology software can be a substantial barrier for solo practitioners and small, independent clinics with limited IT budgets.
- Interoperability with Legacy EHRs:Poor integration between specialized dermatology platforms and incumbent, hospital-wide Electronic Health Record (EHR) systems creates data silos and workflow inefficiencies, discouraging adoption in large healthcare organizations.
- Stringent Regulatory Hurdles:The classification of AI-powered diagnostic aids as medical devices by bodies like the US FDA and under Europe's MDR framework imposes long and costly clinical validation requirements, slowing innovation.
Strategic Opportunities
- Emerging Market Penetration:Developing healthcare markets, particularly in countries like Brazil and India with growing private healthcare sectors, represent significant untapped opportunities for vendors offering scalable, cloud-based solutions.
- Predictive Analytics Integration:An opportunity exists to move beyond diagnostics and incorporate AI for predicting patient response to specific treatments or forecasting disease progression based on clinical and genetic data.
- Augmented Reality for Training:The convergence of high-resolution imaging with augmented reality (AR) offers a new frontier for surgical planning and resident training, especially in complex cosmetic and reconstructive procedures.
Industry Challenges
- Maintaining Data Security Compliance:Vendors face the constant operational challenge of ensuring their platforms remain compliant with evolving data privacy regulations like HIPAA and GDPR, particularly concerning cloud storage and cross-border data transfers.
- Clinician Training and Change Management:Overcoming user resistance and ensuring effective adoption requires significant investment in training and support to transition dermatologists from established paper-based or generic software workflows.
- Legacy System Integration Complexity:The technical difficulty of creating seamless, bidirectional data exchange between modern SaaS dermatology software and older, on-premise hospital information systems remains a primary implementation hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dermatology Software Market |
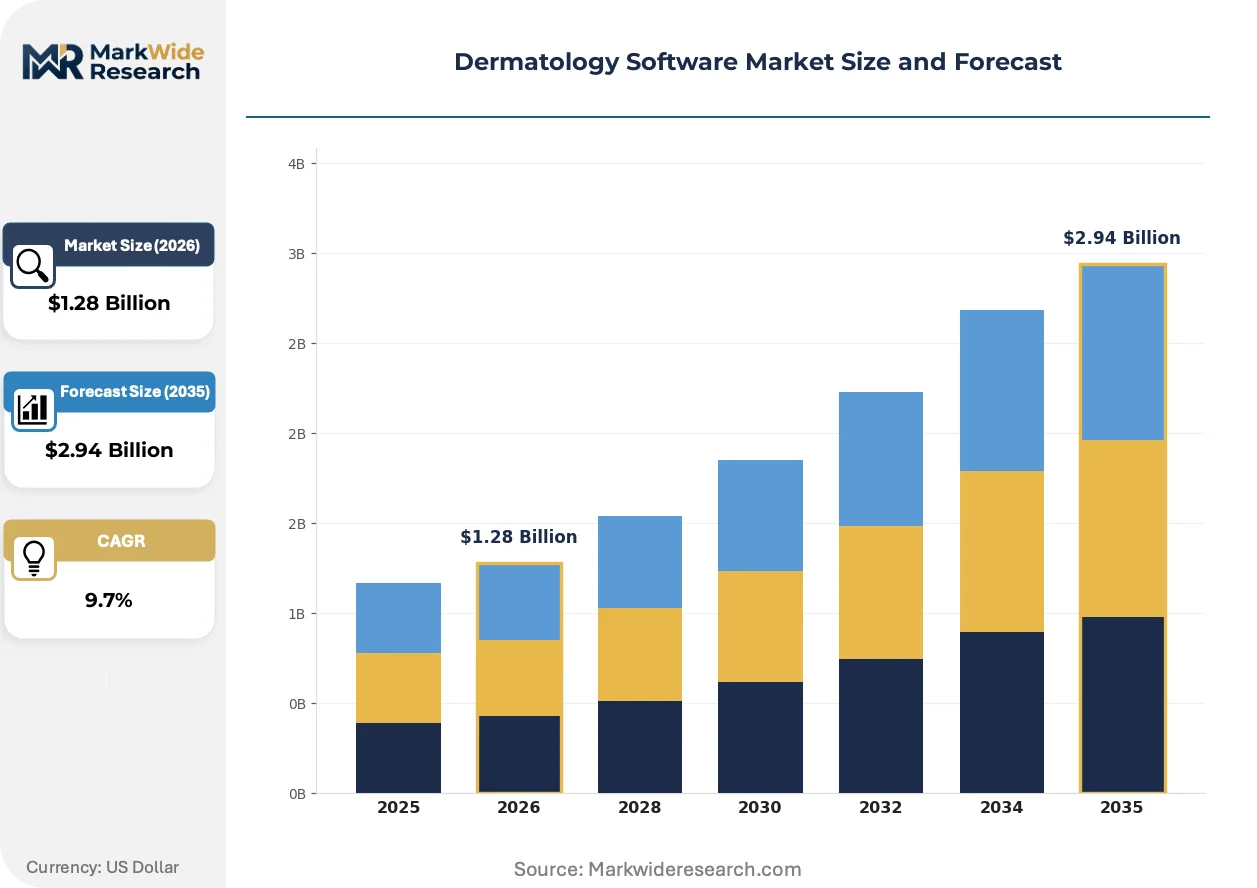
| Market Size in 2026 | $1.28 Billion |
| Market Size in 2035 | $2.94 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clinical Decision Support, Teledermatology Platforms, Imaging & Analysis, Patient Management, Practice Management Application: Skin Cancer Detection, Psoriasis Monitoring, Acne Treatment, Eczema Management, Cosmetic Dermatology End User: Dermatology Clinics, Telehealth Providers, Research Laboratories, Ambulatory Surgery Centers, Aesthetic Centers Deployment: Cloud-Based, On-Premise, Hybrid, SaaS, Mobile Applications |
| Companies Covered | athenahealth, PatientNow, Edvak, CharmHealth, Epic Systems, ModMed, Ezderm, PracticeSuite, Nextech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dermatology Software Market Strategic Shifts & Innovations
The market's evolution is defined by the infusion of artificial intelligence into clinical workflows and a decisive shift toward patient-centric engagement tools. Software is moving beyond simple data repositories to become an active participant in diagnosis, treatment planning, and patient communication, reshaping the value proposition for specialized platforms.
Artificial intelligence, particularly through machine learning algorithms, enables automated analysis of dermatoscopic images for lesion classification and change detection. Specialized dermatology practices and academic research centers are adopting these tools to enhance diagnostic accuracy and streamline screening processes. This technology is integrating decision support directly into the clinical encounter, augmenting the dermatologist's expertise rather than attempting to replace it.
Strict data privacy regulations, including the US Health Insurance Portability and Accountability Act (HIPAA), are fundamentally shaping software architecture. This compliance pressure compels vendors to engineer platforms with end-to-end encryption, granular user access controls, and comprehensive audit logging capabilities. Cloud-based teledermatology providers are most impacted, as they must prove and maintain compliance for patient data that is transmitted and stored across networks.
A significant demand-side shift is the unbundling of software purchasing from enterprise-wide IT procurement cycles, particularly within the aesthetic and cosmetic sub-specialties. These independent clinics prioritize platforms with tailored features for marketing and patient management, choosing best-of-breed solutions over integrated hospital systems. This trend is most visible in markets with a high concentration of private practices, such as the United States.
Dermatology Software Market Segmentation
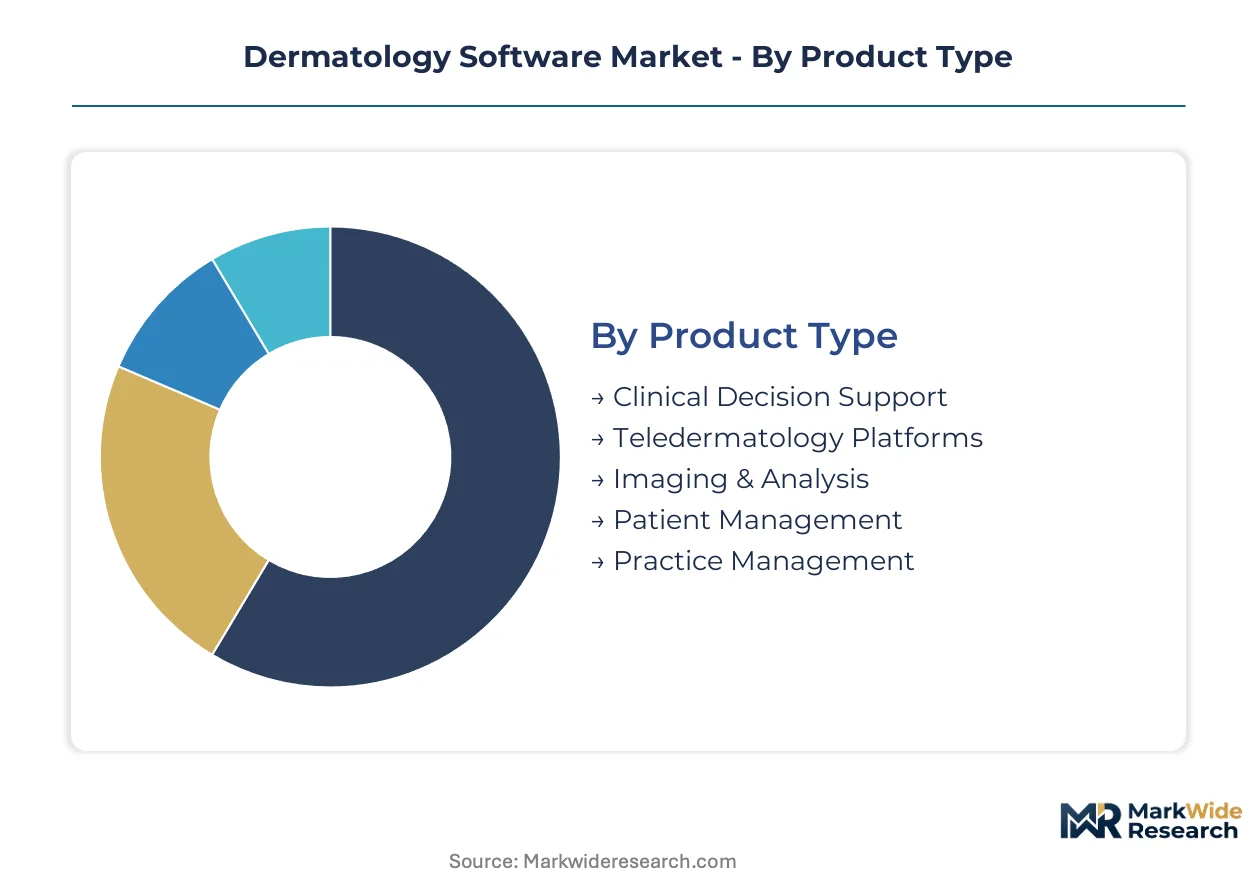
The Dermatology Software Market is segmented to provide a granular understanding of the diverse technological offerings and end-user needs. This segmentation helps identify specific growth pockets and areas where innovation is most impactful, guiding strategic development and market penetration efforts across various clinical settings.
Product Type:
The upgrade and replacement cycle in dermatology software is driven by the need for more specialized tools that integrate advanced clinical capabilities.
- Clinical Decision Support:These tools integrate evidence-based guidelines and patient data to assist dermatologists in diagnostic accuracy and treatment selection.
- Teledermatology Platforms:These solutions facilitate remote consultations, image sharing, and virtual follow-up care. Demand is accelerating among telehealth providers seeking to offer convenient access to dermatological expertise.
- Imaging & Analysis:This segment includes software for capturing, storing, and processing high-resolution dermatoscopic images, often adhering to DICOM standards. Clinical practices use these tools for precise diagnosis and treatment planning.
- Patient Management:Software in this category streamlines appointment scheduling, billing, and electronic health record management for dermatology practices.
- Practice Management:These platforms offer comprehensive administrative features, including financial reporting, staff scheduling, and inventory control for clinics.
Volume placements concentrate in Practice Management; the faster expansion belongs to Teledermatology Platforms.
Application:
The clinical utility of dermatology software varies significantly across different applications, reflecting the diverse diagnostic and treatment needs of patients.
- Skin Cancer Detection:This application utilizes AI and image analysis to identify suspicious lesions and track changes over time. Specialized dermatology practices employ these tools to enhance diagnostic accuracy for patients.
- Psoriasis Monitoring:Software supports tracking disease progression, treatment efficacy, and patient outcomes for chronic psoriasis conditions.
- Acne Treatment:These applications assist in managing patient records, treatment protocols, and follow-up for acne-related dermatological care.
- Eczema Management:Tools in this area help dermatologists monitor eczema severity, treatment responses, and patient education.
- Cosmetic Dermatology:This segment focuses on managing aesthetic procedures, including patient consultations, treatment planning, and before/after image documentation. Aesthetic centers prioritize features for marketing and patient relationship management.
The market focus is increasingly shifting towards advanced diagnostic applications and specialized cosmetic procedures.
End User:
End-user procurement patterns are diversifying, with specialized clinics and telehealth providers seeking solutions tailored to their specific operational models.
- Dermatology Clinics:These are specialized medical facilities providing comprehensive skin care services, from diagnosis to treatment. Independent practices and smaller clinics drive demand for tailored cloud-based solutions.
- Telehealth Providers:Organizations offering remote healthcare services utilize dermatology software to facilitate virtual consultations and secure image transfers. Adoption is accelerating to meet patient demand for convenient access.
- Research Laboratories:These institutions use specialized software for data collection, image analysis, and clinical trial management in dermatological studies.
- Ambulatory Surgery Centers:These facilities employ dermatology software for scheduling, patient tracking, and managing minor surgical procedures.
- Aesthetic Centers:Medspas and cosmetic clinics leverage software for patient management, marketing, and tracking aesthetic treatments.
Investment priorities among end-users are increasingly directed towards solutions that support remote care and specialized aesthetic services.
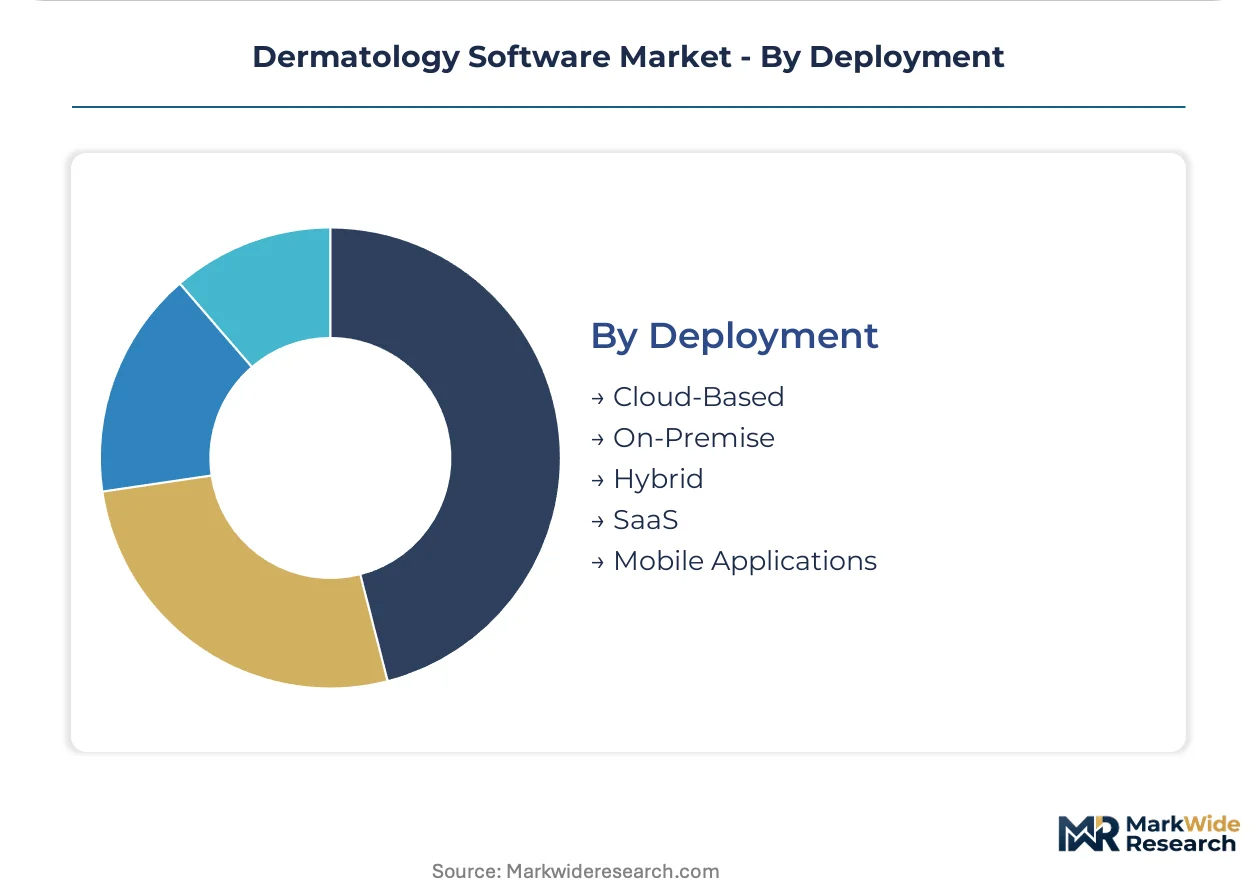
Deployment:
A significant technology shift is underway in deployment models, moving away from traditional setups towards more flexible and cost-effective solutions.
- Cloud-Based:These solutions are hosted on remote servers and accessed via the internet, offering lower upfront costs and flexible scalability. Independent practices and new clinics prefer cloud solutions for ease of deployment.
- On-Premise:Legacy systems installed directly on a clinic's local servers require significant upfront investment and ongoing IT maintenance.
- Hybrid:These deployments combine elements of both on-premise and cloud solutions, balancing data control with remote accessibility.
- SaaS:Software-as-a-Service models provide subscription-based access to dermatology platforms, reducing the need for local IT infrastructure. Small to medium-sized practices find SaaS appealing for cost-efficiency.
- Mobile Applications:These tools extend dermatology software functionality to smartphones and tablets, supporting remote access and patient engagement.
Cloud-based models are becoming the preferred deployment option due to their scalability and reduced infrastructure requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany, with its strong national healthcare digitalization initiatives, anchors the European demand for dermatology software. This market expansion is driven by both regulatory mandates and a growing emphasis on efficient patient care. Other nations are also advancing, with diverse regional demands shaping product development and deployment.
Germany
Demand for certified electronic health record and practice management software is high in Germany. National digitalization policies, such as those promoting e-health solutions, create direct incentives for adoption. The cities of Berlin and Munich serve as significant hubs for health tech innovation, fostering development of specialized platforms.
United States
Independent practices and specialized aesthetic centers drive substantial demand for tailored dermatology software in the United States. HIPAA regulations profoundly influence software architecture, mandating robust data protection features. Silicon Valley and Boston remain key centers for health-tech innovation, attracting significant investment in new solutions.
India
The growing private healthcare sector in India presents a significant opportunity for scalable, cloud-based dermatology solutions. The country's national pharmaceutical regulator, CDSCO, oversees medical device and software approvals. Bengaluru and Hyderabad are major IT services hubs, supporting the development and deployment of new platforms.
Brazil
Expanding private healthcare services and a focus on teledermatology are fueling software adoption in Brazil. ANVISA, the national health surveillance agency, regulates health technology products. São Paulo functions as a vital center for medical technology and digital health startups.
Japan
High demand for advanced diagnostic imaging capabilities and patient management tools characterizes the Japanese market. The Pharmaceuticals and Medical Devices Agency (PMDA) regulates medical software and AI-powered diagnostic aids. Tokyo's vibrant technology sector supports research and development in health-tech applications.
Dermatology Software Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue specialized cloud-based solutions tailored for dermatology workflows. The market structure is tiered, featuring large enterprise EHR providers alongside agile, cloud-native dermatology software specialists. Strategic archetypes include comprehensive enterprise solutions, niche practice management tools, and AI-driven diagnostic platforms. Dominant competitive moves involve strategic partnerships for enhanced interoperability and portfolio diversification into advanced analytics.
Within the diverse market landscape, Epic Systems exemplifies the enterprise-level EHR provider, maintaining a strong position within large integrated delivery networks. ModMed represents a cloud-native dermatology specialist, focusing on tailored solutions for independent practices. PatientNow occupies a position as a provider of integrated practice management and marketing tools, specifically designed for smaller, growth-oriented clinics.
| Leading Market Players |
|---|
| athenahealth |
| PatientNow |
| Edvak |
| CharmHealth |
| Epic Systems |
| ModMed |
| Ezderm |
| PracticeSuite |
| Nextech |
| Others |
Cost & Logistics Intelligence
Dermatology Clinics and Aesthetic Centers, as concentrated buyer archetypes, influence pricing structures for specialized software. Their varied operational scales drive a tiered subscription model.
Pricing Analysis
Volume-driven segments, like basic patient management software, operate on lower per-user margins. Premium solutions, such as AI-powered diagnostics, command higher margins due to specialized capabilities. A SaaS subscription-tiered model dominates, offering different feature sets at varying price points. Customization level for specific workflows and the level of regulatory compliance (e.g., FDA-cleared AI tools) are key differentiators. Pricing pressure stems from the proliferation of cloud-based solutions offering competitive entry points. Solo practitioners exhibit higher price sensitivity compared to large hospital networks.
Supply Chain Analysis
Workforce availability in software development hubs like Bengaluru, India, and Silicon Valley, United States, impacts the supply of skilled developers for dermatology software. Software development concentrates in the United States, India, and Germany. The supply chain relies on cloud infrastructure services (e.g., AWS, Azure) and specialized AI/ML libraries. Single-source vulnerability for specific cloud providers represents a structural risk. Distribution runs through direct sales teams and channel partners targeting specific practice sizes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Dermatology Software Market presents as a consolidation play, driven by the increasing technical demands of regulatory compliance. Smaller vendors struggle to maintain the necessary data security and interoperability standards.
For Market Incumbents:Anticipate evolving interoperability demands from large hospital networks. Integrate with generalist EHRs like Epic Systems to counter the threat of data silos. Pursue strategic partnerships for advanced AI development, particularly in image analysis, to maintain a competitive edge. Invest in rigorous clinical validation pathways to meet US FDA and Europe's MDR requirements for AI tools.
For New Entrants and Emerging Players:Begin with specialized cloud-based solutions targeting aesthetic centers in the United States. This segment is less integrated with legacy EHRs and prioritizes marketing features. Focus on intuitive user experience and robust patient relationship management tools. A freemium model for basic practice management features can attract growth-oriented clinics.
For Investors and Strategic Acquirers:The window for entry favors mid-sized software firms with established cloud infrastructure and specialized AI capabilities. Long-term viability hinges on platforms that can seamlessly integrate teledermatology and advanced diagnostics. Target acquisition archetypes include niche AI diagnostic startups with strong clinical validation. The signal to watch is successful large-scale deployments of AI-powered screening tools in major health systems.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Enhance seamless data exchange with major EHR systems like Epic Systems. |
| AI Clinical Validation | Secure regulatory approvals (e.g., FDA, MDR) for AI diagnostic tools. |
| Teledermatology Expansion | Extend remote consultation capabilities to underserved geographic markets. |
| Cloud Infrastructure Upgrade | Ensure scalability and robust data security for SaaS offerings. |
| Patient Engagement Tools | Develop advanced features for patient self-service and communication. |
Research Approach
Multi-period observation of software adoption rates and regulatory changes anchored the trend analysis, supplemented by interviews with industry stakeholders. Primary research involved discussions with CTOs, IT procurement officers, dermatologists, and telehealth providers. Secondary validation utilized data from government health digitalization reports, medical device registries (e.g., FDA, PMDA), and academic research on teledermatology. This approach ensured robust bottom-up and top-down triangulation of market insights.
Segment-weighting across product types, applications, end-users, and deployment models formed the core analytical framework over the projection horizon. Quantitative models incorporated historical growth trends and future adoption drivers. Compound annual growth rates were derived from a synthesis of primary insights and macroeconomic indicators. Key forecast inputs included healthcare IT spending trends and teledermatology consultation volumes.
Underlying measurement precision varies by segment; established practice management software carries tighter precision than emerging AI diagnostic tools. Forecasts reflect assumptions regarding regulatory stability and technological advancements. Geopolitical shifts or unforeseen changes in healthcare funding models could revise projections. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dermatology
Global Veterinary Dermatology Drugs Market
Dermatology
Dermatology Devices Market
Dermatology
Hyperpigmentation Treatment Market
Dermatology
Australia Skin Laser Market
Dermatology
Dermatology Diagnostic Devices and Therapeutics Market
Dermatology
Global Dermatology Excimer Laser Market
Dermatology
Erythema Treatment Market
Dermatology
Seborrheic Keratosis Market
Dermatology
Global Ozone Therapy in Dermatology Market
Dermatology
Porokeratosis Treatment Market
Dermatology
Acne Vulgaris Treatment Market
Dermatology
Australia Skin Treatment Market
Dermatology
Dermabrasion and Micro Needling Market
Dermatology
Global Dermatological OTC Drugs Market
Dermatology
Global Hirsutism Market
Dermatology
China Scar Treatment Market