
 Vaginitis Therapeutics Market | 2026-2036
Vaginitis Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Vaginitis Therapeutics Market Outlook
ISO 13485 certification for medical device-drug combination products is redrawing qualification thresholds for intravaginal delivery system manufacturers. Pfizer Inc. leverages its antifungal manufacturing scale to supply hospital formularies across North America. Bayer AG anchors its position through sustained R&D investment in hormonal therapeutic platforms. Teva Pharmaceutical Industries Ltd differentiates via generic antibiotic portfolios that compete on cost in pharmacy channels.
Vaginitis therapeutics comprise pharmaceutical agents formulated to restore vaginal microbiome balance, eliminate infectious pathogens, or modulate estrogen-dependent mucosal integrity, typically delivered through pH-optimized vehicles achieving local tissue concentrations with minimal systemic absorption. Their primary purpose centers on resolving infectious, atrophic, or inflammatory vaginal conditions while minimizing recurrence rates and antimicrobial resistance selection. Antifungals occupy the largest revenue pool given recurrent vulvovaginal candidiasis prevalence, yet probiotics represent the fastest-expanding segment as live biotherapeutic products gain formulary acceptance. Among treatment modalities, intravaginal delivery commands premium pricing due to manufacturing complexity, while oral tablets sustain volume leadership through patient convenience and pharmacy accessibility.
FDA bioequivalence standards for topical antifungals and EMA guidance on live biotherapeutic products jointly shape clinical trial requirements and approval timelines across developed markets. The EPA's evolving framework for antimicrobial environmental discharge additionally constrains manufacturing process design for antibiotic actives. Stakeholders must monitor regulatory divergence between FDA and EMA on probiotic quality standards, as this will determine which platforms achieve transatlantic commercialization without reformulation.
Market Dynamics
FDA's streamlined bioequivalence pathways for complex topical generics are compressing competitive entry timelines while hospital pharmacy procurement committees prioritize intravaginal formulations with ISO 13485-certified manufacturing.
Growth Catalysts
- Live Biotherapeutic Product Pathways:EMA guidance on microbiome-derived therapies accelerates probiotic formulary acceptance in European gynecology clinics.
- Specialty Clinic Concentration:United States-based gynecology practices drive prescription volume for combination antifungal-hormonal regimens through direct-to-patient sampling programs.
- pH-Optimized Vehicle Innovation:Advanced intravaginal delivery systems achieve targeted tissue concentrations with minimal systemic absorption, expanding therapeutic indices.
Market Restraints
- Antimicrobial Environmental Discharge:EPA manufacturing constraints on antibiotic active pharmaceutical ingredients raise compliance costs for bulk producers.
- Active Pharmaceutical Ingredient Concentration:Three contract manufacturers supply the majority of azole antifungal raw materials, creating supply vulnerability.
- Recurrence Rate Limitations:Existing antifungal therapies demonstrate suboptimal long-term efficacy in recurrent vulvovaginal candidiasis populations.
Strategic Opportunities
- Underpenetrated Latin American Markets:Brazil and Mexico present expansion potential where diagnostic access lags prevalence rates.
- Telehealth Distribution Channels:Direct-to-consumer platforms bypass traditional pharmacy intermediaries for maintenance therapy refills.
- IRA Drug Pricing Negotiation Exclusions:Complex generic topical formulations fall outside Medicare price-setting mechanisms, preserving margin structures.
Industry Challenges
- ISO 13485 Certification Timelines:Medical device-drug combination product qualification requires 18-24 month validation cycles.
- Microbiome Characterization Skill Gaps:Live biotherapeutic manufacturing demands specialized quality control personnel scarce in contract development organizations.
- Legacy Formulation Integration:New intravaginal delivery platforms face compatibility testing burdens against established excipient libraries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vaginitis Therapeutics Market |
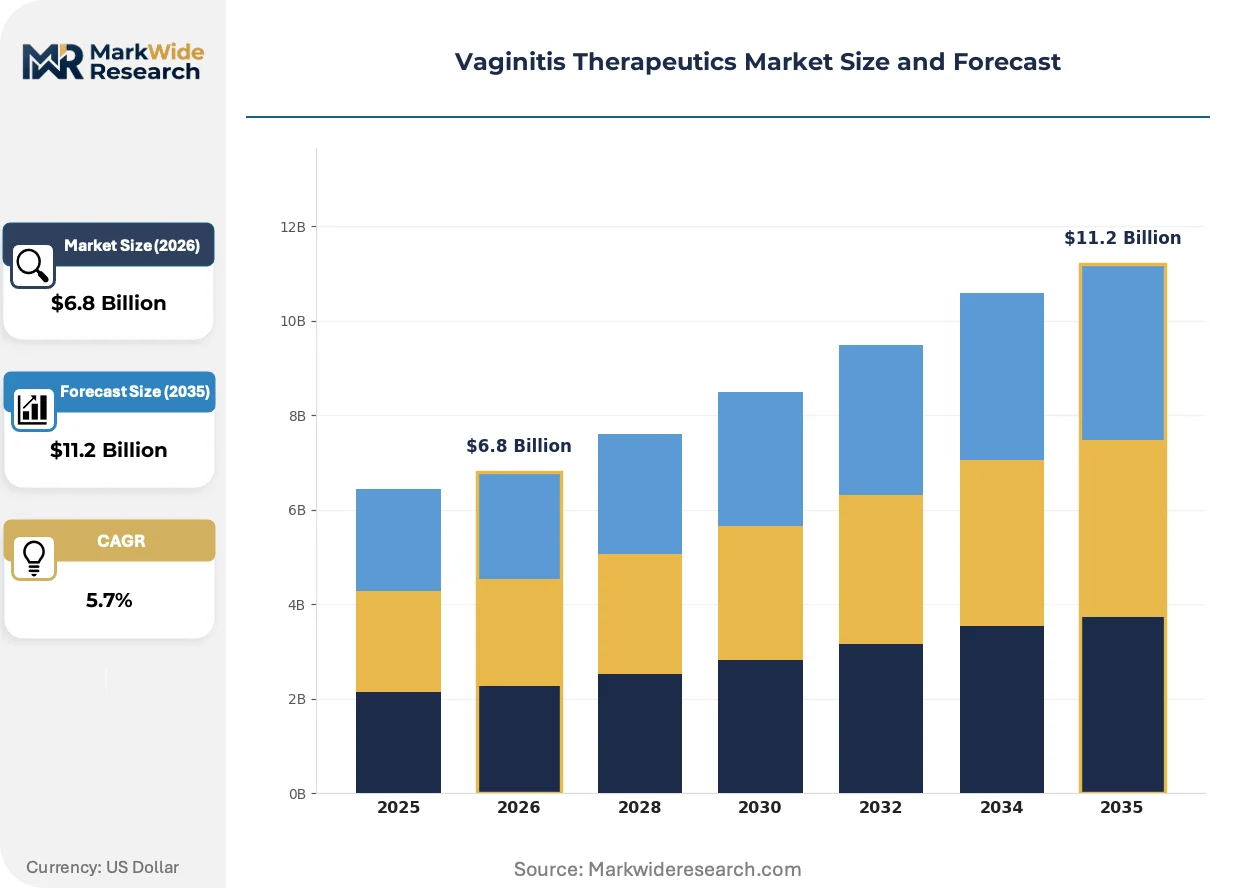
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antifungals, Antibiotics, Hormonal Treatments, Probiotics End User: Hospitals, Clinics, Home Care, Pharmacies Treatment Type: Topical, Oral, Intravaginal, Combination Therapy Formulation: Creams, Tablets, Gels, Suppositories |
| Companies Covered | Pfizer Inc., Merck & Co., Inc., Novartis AG, Bayer AG, GlaxoSmithKline plc, Teva Pharmaceutical Industries Ltd, Sanofi, Johnson & Johnson, Lupin Pharmaceuticals, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vaginitis Therapeutics Market Strategic Shifts
Intravaginal therapeutic delivery is converging with precision microbiome engineering and digital health monitoring, reshaping how clinicians manage recurrent conditions and how patients adhere to maintenance protocols.
Microneedle-array intravaginal patches are miniaturizing drug reservoirs into dissolvable microprojections that breach the mucosal barrier without applicator devices. Specialty gynecology clinics in the United States are piloting these systems for localized hormonal delivery. This form factor is miniaturizing patient-administered therapy into discrete, portable formats that eliminate cold-chain requirements and bathroom privacy concerns.
EMA's evolving framework for live biotherapeutic product quality standards is forcing reformulation investments for probiotic candidates seeking transatlantic approval. Manufacturers must duplicate stability testing under divergent temperature and humidity specifications. European formulation development teams are responding by designing platform technologies adaptable to both FDA and EMA release specifications without process changes.
Subscription-based maintenance therapy programs are replacing episodic prescription models for recurrent vulvovaginal candidiasis patients. Direct-to-consumer platforms disintermediate traditional pharmacy fulfillment with automated refill algorithms tied to symptom-tracking applications. This shift concentrates most visibly in United States metropolitan markets where employer-sponsored telehealth benefits cover gynecologic consultations.
Vaginitis Therapeutics Market Segmentation
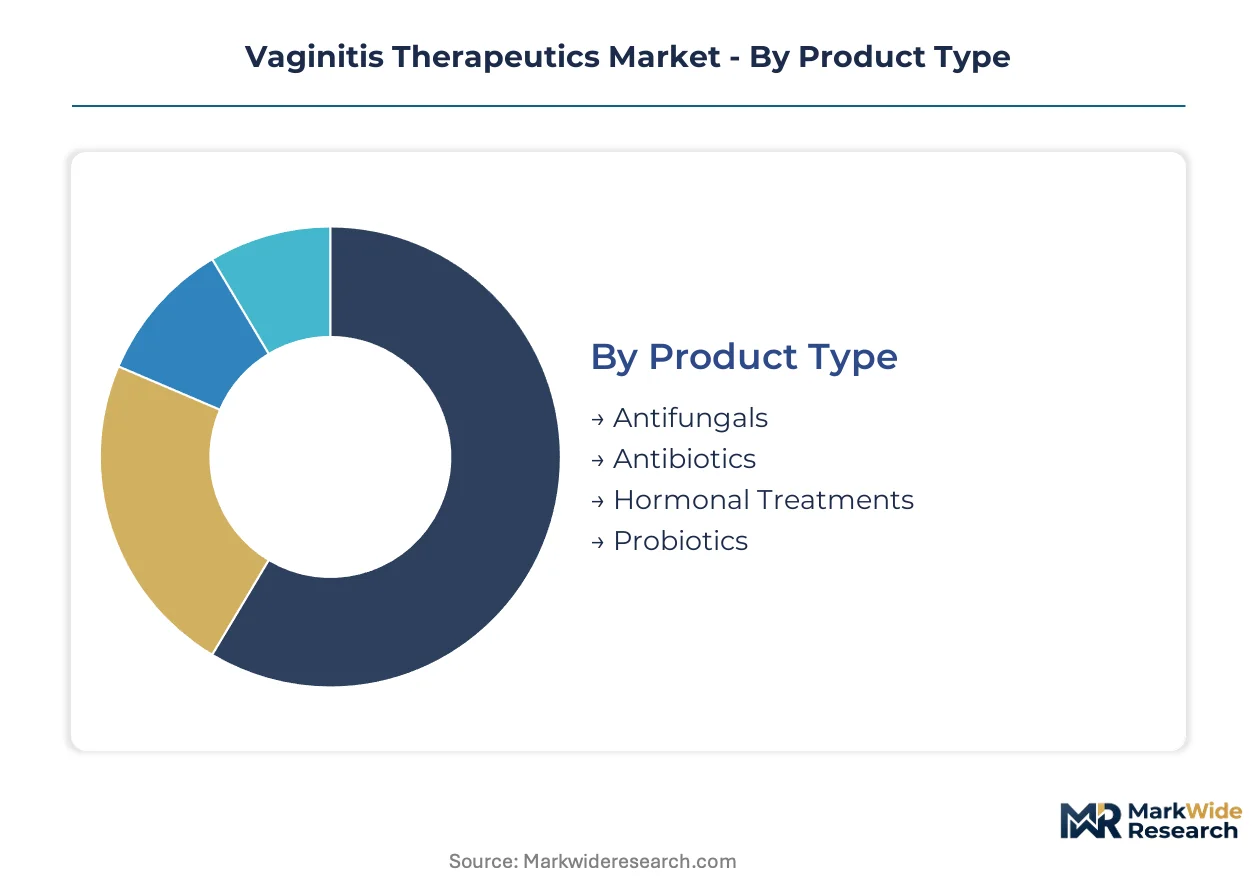
Segmentation in vaginitis therapeutics reveals how formulation complexity, delivery precision, and care setting access determine commercial viability. Each dimension carries distinct regulatory burdens and reimbursement profiles that reshape competitive positioning across patient populations.
Product Type:
Substitution pressure from live biotherapeutics and hormonal alternatives is reshaping competitive dynamics most acutely among infectious disease agents.
- Antifungals:Azole and polyazole compounds dominate hospital formularies for vulvovaginal candidiasis management. United States specialty gynecology clinics drive prescription volume through direct-to-patient sampling programs for recurrent cases.
- Antibiotics:Metronidazole and clindamycin formulations address bacterial vaginosis with established efficacy profiles. EPA manufacturing constraints on active pharmaceutical ingredients raise compliance costs for bulk producers supplying North American markets.
- Hormonal Treatments:Localized estrogen therapies restore mucosal integrity in atrophic vaginitis populations.
- Probiotics:Live biotherapeutic products gain formulary acceptance under EMA guidance.
Antifungals anchor the volume base while probiotics gain share at the steepest rate.
End User:
Cost tier stratification separates acute intervention sites from maintenance therapy channels with divergent procurement authority.
- Hospitals:Inpatient and emergency departments manage severe infectious presentations requiring intravenous escalation pathways. Pharmacy procurement committees prioritize ISO 13485-certified intravaginal formulations for formulary inclusion.
- Clinics:Outpatient gynecology practices concentrate prescription authority for combination antifungal-hormonal regimens. United States metropolitan markets show highest telehealth integration for follow-up consultations.
- Home Care:Self-administered maintenance protocols reduce recurrence through patient-controlled dosing.
- Pharmacies:Retail and hospital pharmacy channels compete on generic antibiotic cost positioning.
Hospitals capture the premium intervention tier while home care expands most quickly through direct-to-consumer platform integration.
Treatment Type:
Application-specific efficacy requirements drive divergence between systemic exposure tolerance and localized delivery precision.
- Intravaginal:pH-optimized vehicles achieve targeted tissue concentrations with minimal systemic absorption, commanding premium pricing due to manufacturing complexity. FDA bioequivalence standards for complex topical generics compress competitive entry timelines.
- Oral:Systemic fluconazole and metronidazole tablets sustain volume leadership through patient convenience and broad pharmacy accessibility. Recurrence rate limitations in resistant candidiasis populations constrain long-term efficacy.
- Topical:External vulvar applications address symptomatic relief without mucosal penetration.
- Combination Therapy:Simultaneous antifungal-hormonal or antibiotic-probiotic protocols target polymicrobial presentations.
Oral administration retains the volume base while intravaginal systems climb the fastest on precision delivery advantages.
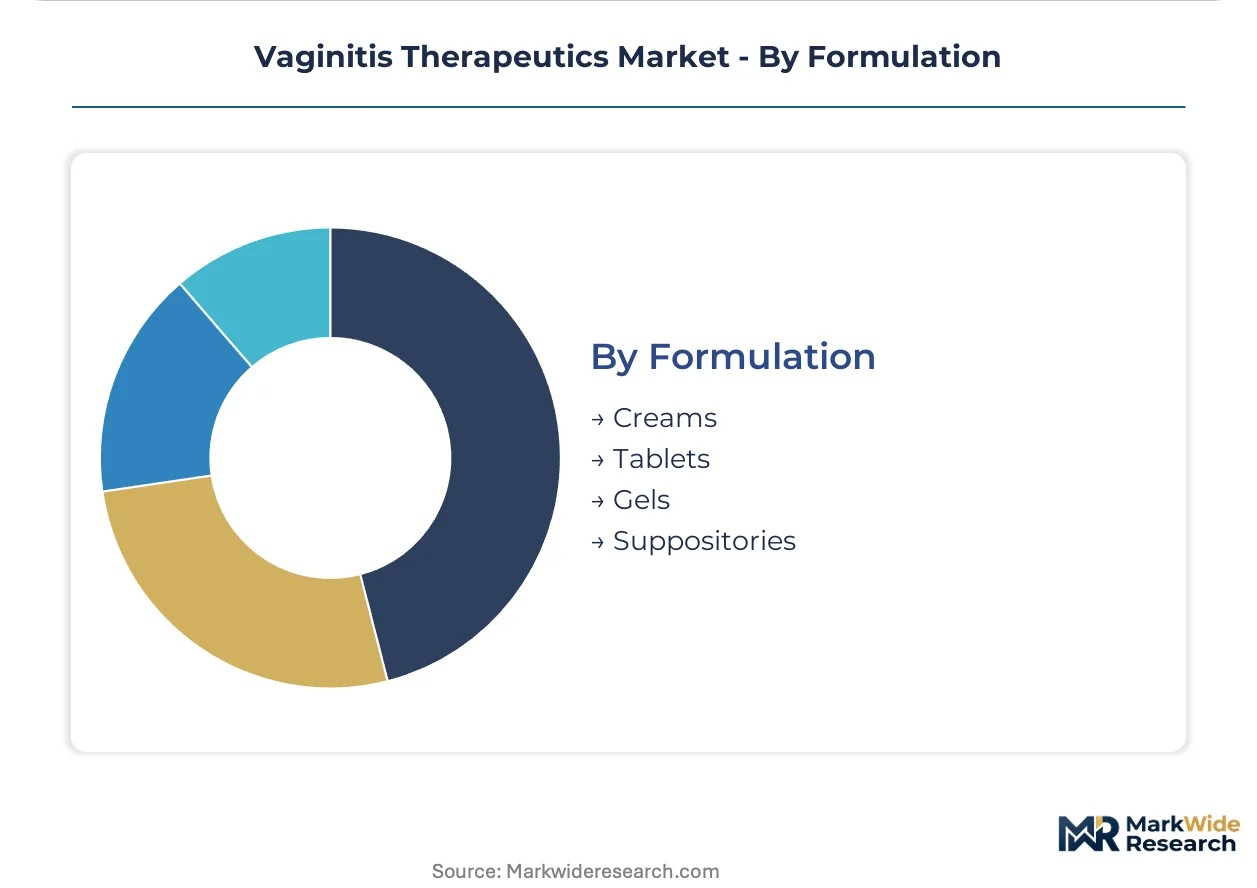
Formulation:
Supply concentration among contract manufacturers for semisolid excipients shapes margin structures across physical form factors.
- Creams:Semisolid emulsions with established excipient compatibility dominate legacy prescription volumes. Three contract manufacturers supply the majority of azole-compatible base materials, creating supply vulnerability.
- Tablets:Oral solid dosage forms leverage existing high-speed production infrastructure for cost-competitive supply. Microneedle-array innovations are miniaturizing drug reservoirs into dissolvable microprojections for localized delivery.
- Gels:Aqueous polymer networks enable rapid mucosal spreading and patient-administered application.
- Suppositories:Lipid-based or polyethylene glycol vehicles provide prolonged intravaginal residence time.
Creams sustain the installed volume base while tablets diversify most rapidly through delivery technology convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA's streamlined bioequivalence pathways and EMA's live biotherapeutic guidance are accelerating product registrations across developed markets while hospital procurement committees prioritize ISO 13485-certified manufacturing. Specialty gynecology clinics in the United States and Germany drive prescription volumes for combination antifungal-hormonal regimens through direct-to-patient sampling programs.
United States
Specialty gynecology clinics in metropolitan markets concentrate prescription authority for intravaginal formulations with pH-optimized vehicles. The FDA's bioequivalence standards for complex topical generics compress competitive entry timelines for azole antifungal manufacturers. Boston and San Francisco medical device clusters host development teams engineering microneedle-array intravaginal patches for localized hormonal delivery.
Germany
EMA guidance on live biotherapeutic products accelerates probiotic formulary acceptance in European gynecology clinics. The country's national pharmaceutical regulator enforces stability testing under divergent temperature specifications for transatlantic approval pathways. Frankfurt and Munich pharmaceutical hubs house formulation development teams designing platform technologies adaptable to both FDA and EMA release specifications.
Japan
PMDA review pathways for medical device-drug combination products shape qualification timelines for intravaginal delivery system manufacturers. METI industrial policy supports domestic production of antibiotic active pharmaceutical ingredients amid EPA-constrained global supply chains. Tokyo and Osaka medical technology corridors concentrate contract development organizations specializing in mucosal drug delivery characterization.
Brazil
Diagnostic access gaps relative to vulvovaginal candidiasis prevalence rates create expansion potential for telehealth distribution channels. ANVISA registration requirements for imported probiotic formulations extend commercialization timelines compared to developed markets. São Paulo and Rio de Janeiro metropolitan areas concentrate private gynecology practices piloting subscription-based maintenance therapy programs.
India
CDSCO approval pathways for generic antibiotic formulations sustain cost-competitive supply to pharmacy channels across emerging markets. The country's national pharmaceutical regulator aligns with WHO prequalification standards for intravaginal product exports. Hyderabad and Mumbai pharmaceutical clusters host contract manufacturers supplying azole antifungal raw materials to North American hospital formularies.
Vaginitis Therapeutics Market Competitive Environment
Player mix skews toward multinational pharmaceutical conglomerates with established antifungal manufacturing scale and generic specialists competing on cost positioning. Market structure concentrates around three operational tiers: integrated innovators with hormonal therapeutic platforms, scale-driven generic houses with antibiotic portfolios, and emerging live biotherapeutic developers. Dominant competitive moves include strategic partnerships for microbiome-derived therapy commercialization and backward integration into active pharmaceutical ingredient production to secure azole supply chains.
Among integrated pharmaceutical conglomerates, Pfizer Inc. and Bayer AG exemplify archetypes anchored in manufacturing scale and sustained R&D investment respectively. Teva Pharmaceutical Industries Ltd occupies a position within the generic specialist tier where cost positioning in pharmacy channels determines competitive viability. These three entities represent the structural fault lines between innovation-driven premium pricing and volume-driven generic penetration across hospital and retail pharmacy procurement committees.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Merck & Co., Inc. |
| Novartis AG |
| Bayer AG |
| GlaxoSmithKline plc |
| Teva Pharmaceutical Industries Ltd |
| Sanofi |
| Johnson & Johnson |
| Lupin Pharmaceuticals, Inc. |
| Others |
Value Chain & Pricing Dynamics
Eighteen-to-twenty-four month ISO 13485 validation cycles compress procurement flexibility for hospital formularies while concentrating pricing power among certified intravaginal delivery system manufacturers. This lead-time band forces buyers into long-term offtake commitments with qualified suppliers, embedding certification grade as the dominant price stratifier across generic and branded portfolios.
Pricing Analysis
Certification level creates the primary spread between ISO 13485-certified intravaginal formulations and standard topical generics. Three-tier pricing structure across premium certified, validated standard, and uncertified economy levels reflects manufacturing complexity and regulatory burden. Cost compression in the economy tier is intensifying because EPA manufacturing constraints on antibiotic actives raise compliance costs for bulk producers. Hospital pharmacy procurement committees show lowest price sensitivity due to formulary inclusion requirements, while retail pharmacy channels compete aggressively on generic antibiotic cost positioning.
Supply Chain Analysis
India and China anchor azole antifungal active pharmaceutical ingredient production for North American and European hospital formularies. Hyderabad and Mumbai pharmaceutical clusters supply raw materials that draw from concentrated petrochemical feedstocks and specialized fermentation capacity. Single-source vulnerability concentrates among three contract manufacturers providing azole-compatible semisolid base materials. Distribution runs through hospital pharmacy procurement committees and direct-to-consumer telehealth platforms for maintenance therapy refills.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Live biotherapeutic products threaten to displace conventional antifungal and antibiotic regimens as EMA guidance accelerates probiotic formulary acceptance, forcing incumbents to defend against microbiome-derived substitution.
For Market Incumbents: Fortify azole supply chain security through backward integration into active pharmaceutical ingredient production or captive supply agreements with Indian contract manufacturers. Secure ISO 13485 certification renewal timelines well ahead of formulary review cycles to defend against complex generic entrants leveraging FDA streamlined bioequivalence pathways. For New Entrants and Emerging Players: Differentiate on live biotherapeutic platform technologies adaptable to both FDA and EMA quality specifications without reformulation. Target underpenetrated Latin American markets where diagnostic access gaps relative to vulvovaginal candidiasis prevalence create white-space opportunity. Deploy subscription-based direct-to-consumer distribution to bypass entrenched pharmacy intermediaries. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because manufacturing scale and regulatory qualification create durable moats against commodity competition. Acquisition targets should display ISO 13485-certified intravaginal delivery capabilities combined with microbiome characterization expertise. Watch EMA-FDA probiotic quality standard convergence as the signal for transatlantic commercialization viability.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Renewal | Hospital formulary inclusion requires current certification status for intravaginal combination products. |
| Live Biotherapeutic Platform Development | EMA guidance accelerates probiotic acceptance against conventional antifungal regimens. |
| Backward Integration into API Production | Captive azole supply secures margins against EPA-constrained global raw material markets. |
| Telehealth Distribution Partnership | Direct-to-consumer platforms bypass pharmacy intermediaries for maintenance therapy refills. |
| Dual Regulatory Pathway Design | Platform technologies adaptable to FDA and EMA specifications enable transatlantic commercialization. |
Study Parameters
A spread of perspectives from drug development executives, regulatory affairs leads, hospital procurement managers, and formulary directors converged on the working assumptions driving this analysis. Primary interview data combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up prescription volume modeling and top-down pharmaceutical market sizing were triangulated to establish market boundaries.
Segmentation dimensions modeled include product type, treatment modality, formulation, end-user channel, and regional regulatory cluster across the analysis window. CAGRs were derived from patient population prevalence trajectories, formulary inclusion timelines, and generic entry assumptions. Forecast inputs incorporated EPA manufacturing constraint impacts on antibiotic active pharmaceutical ingredient supply and EMA live biotherapeutic guidance adoption curves.
Material uncertainties — regulatory divergence between FDA and EMA probiotic standards, azole raw material supply disruptions, and telehealth reimbursement policy shifts — sit outside the modeled envelope. Forecasts reflect assumptions about certification timeline stability and hospital procurement committee prioritization patterns. Recalibration cycles align with material shifts in regulatory guidance and supply chain concentration events.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Riociguat Tablets Market
Pharmaceuticals
PDE Inhibitors Market
Pharmaceuticals
Intravenous Solution Compounders Market
Pharmaceuticals
Oral & Topical Anaesthetics Market
Pharmaceuticals
Global Anorexiants Market
Pharmaceuticals
Daratumumab Market
Pharmaceuticals
Mtor Inhibitors Market
Pharmaceuticals
GCC Generic Injectables Market
Pharmaceuticals
G Protein Coupled Receptors (Gpcrs) Market
Pharmaceuticals
Global Histone Deacetylase Inhibitors Market
Pharmaceuticals
Global Chemotherapy-Induced Nausea and Vomiting (CINV) Market
Pharmaceuticals
Pharmacovigilance (PV) Market
Pharmaceuticals
Middle East and Africa Gastrointestinal Drugs Market
Pharmaceuticals
Global Treatment-Resistant Depression Market
Pharmaceuticals
Global Loperamide Hcl Market
Pharmaceuticals
Veterinary Insulin Drugs Market