
 Dermatology Drugs Market | 2026-2036
Dermatology Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Dermatology Drugs Market Intelligence
Specialized manufacturing capacity for monoclonal antibodies and other complex biologics is hardening, creating high barriers to entry for new competitors. AbbVie Inc. leverages its established immunology portfolio to maintain a significant market presence in inflammatory skin conditions. Novartis AG competes through a diversified pipeline targeting a wide range of dermatological diseases. Eli Lilly and Company differentiates with its focus on developing novel biologic therapies for conditions like atopic dermatitis and psoriasis, positioning itself at the forefront of innovation.
Dermatology drugs are pharmaceutical agents formulated to diagnose, treat, or prevent diseases affecting the skin, hair, and nails. These compounds range from topical corticosteroids and retinoids to systemic small molecules and large-molecule biologics, which often modulate specific immune pathways. The primary purpose is to manage chronic inflammatory conditions, combat infections, or address aesthetic concerns. The biologics segment represents the fastest-growing product type, driven by its efficacy in treating severe psoriasis and eczema where other therapies have failed.
Regulatory frameworks from the United States' FDA and Europe's EMA dictate stringent requirements for clinical trial design, safety, and efficacy data for new drug approvals. In Japan, the PMDA establishes parallel standards that influence market access and reimbursement policies. These agencies' guidelines for drug development directly impact R&D costs and timelines for pharmaceutical companies. A critical decision for manufacturers involves allocating resources between developing treatments for prevalent conditions versus niche, orphan dermatological diseases.
Market Dynamics
The central force shaping the dermatology drugs market is the paradigm shift from broad-spectrum topical agents to highly targeted, high-cost biologic therapies. This transition fundamentally alters research priorities, manufacturing requirements, and reimbursement negotiations for chronic inflammatory skin diseases.
Growth Catalysts
- Novel Mechanisms of Action:The development of new therapeutic classes, such as Janus kinase (JAK) inhibitors and tyrosine kinase 2 (TYK2) inhibitors, provides new options for patients who are unresponsive to existing biologics, expanding the addressable patient population.
- Rising Disease Prevalence:An increasing incidence of chronic, immune-mediated skin conditions like psoriasis and atopic dermatitis in industrialized nations creates a sustained demand for more effective and long-term treatment solutions.
- Regulatory Incentives:Programs like the FDA's Orphan Drug Designation and the EMA's PRIME scheme encourage investment in treatments for rare dermatological diseases by offering market exclusivity and accelerated review pathways.
Market Restraints
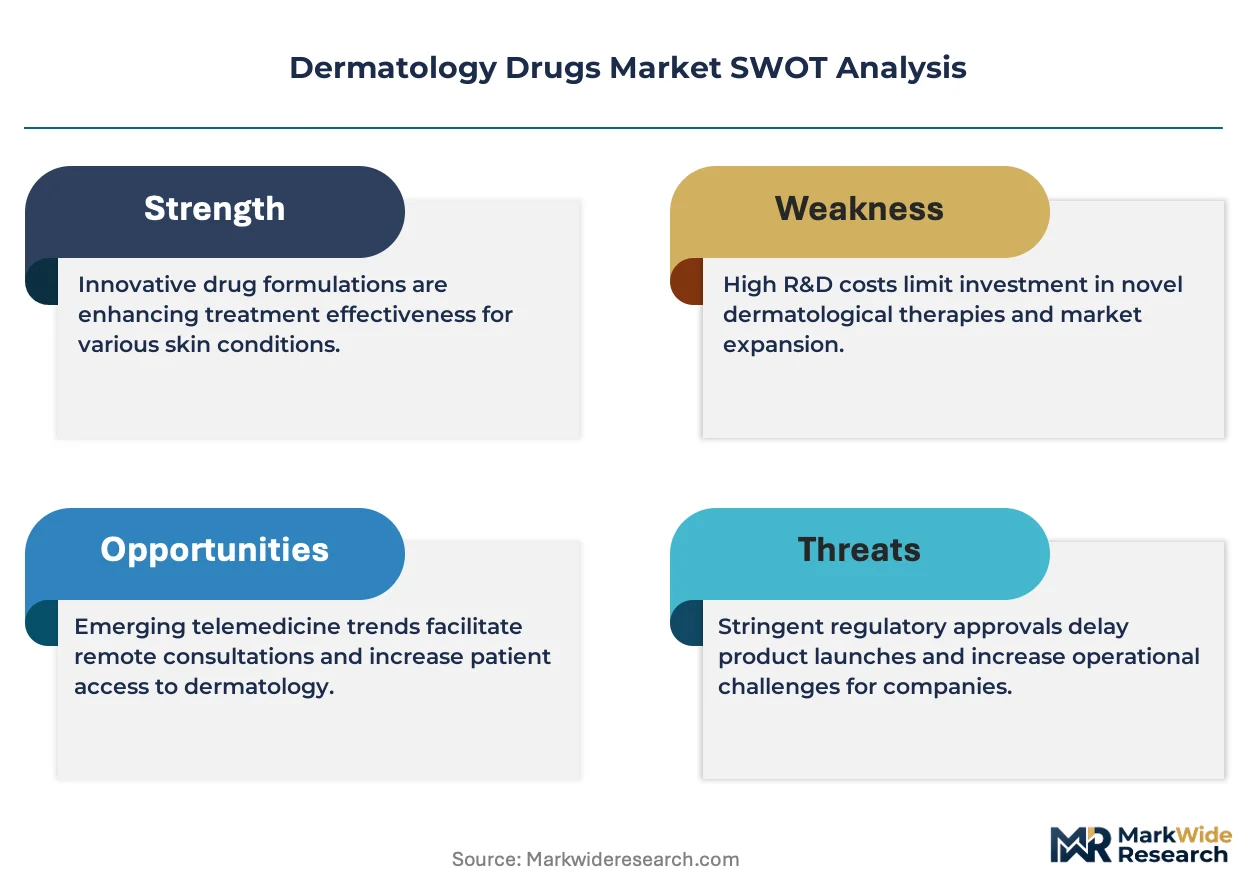
- High Cost of Biologics:The significant expense of monoclonal antibody therapies creates substantial access barriers, with stringent reimbursement criteria from payors in the United States and Europe limiting patient uptake.
- Manufacturing Complexity:Production of large-molecule biologics requires specialized facilities and expertise, creating a manufacturing bottleneck that increases costs and limits the entry of new competitors.
- Patent Expiration and Biosimilars:The looming patent cliffs for several blockbuster dermatology biologics expose originator products to competition from lower-cost biosimilars, putting pressure on revenue streams for established therapies.
Strategic Opportunities
- Topical Drug Innovation:There is a significant opportunity to develop novel topical formulations with biologic-like efficacy but with improved safety profiles and lower costs, addressing mild-to-moderate disease segments.
- Emerging Market Penetration:Expanding access to advanced dermatological treatments in large, underserved markets like China and Brazil presents a major growth vector, contingent on navigating local regulatory and reimbursement landscapes.
- Personalized Medicine:The use of genetic biomarkers to identify patient subpopulations most likely to respond to a specific therapy can improve clinical trial success rates and support value-based pricing arguments with payors.
Industry Challenges
- Complex Clinical Trial Requirements:Demonstrating superiority over an expanding field of effective incumbents requires larger, more expensive, and longer clinical trials, increasing R&D risk for companies developing next-generation therapies.
- Payer Resistance to Stacking:Health insurers and national health systems are pushing back against the use of multiple high-cost specialty drugs, challenging combination therapy strategies for complex skin diseases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dermatology Drugs Market |
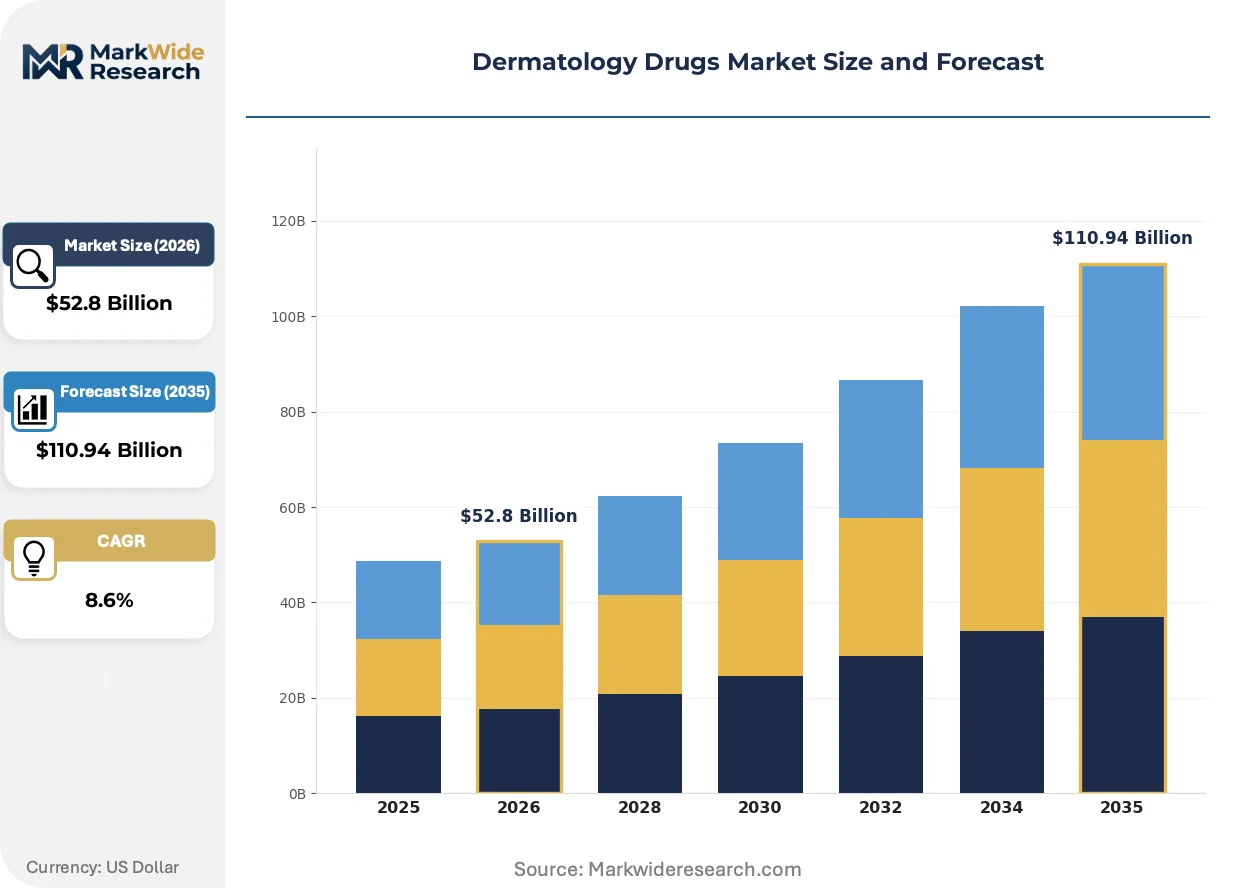
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $110.94 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Agents, Systemic Treatments, Biologics, Phototherapy Agents, Combination Therapies Therapy Area: Psoriasis, Eczema, Acne, Fungal Infections, Vitiligo End User: Dermatology Clinics, Hospitals, Specialty Pharmacies, Ambulatory Care Centers Delivery Mode: Creams, Lotions, Tablets, Injections, Transdermal Patches |
| Companies Covered | AbbVie Inc., Novartis AG, Pfizer Inc., Johnson & Johnson Services, Inc., Eli Lilly and Company, Sanofi, Amgen Inc., LEO Pharma A/S, Galderma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dermatology Drugs Market Strategic Shifts & Innovations
The convergence of advanced immunology and data analytics is personalizing treatment for dermatological conditions. This evolution moves the market away from standardized protocols toward patient-specific interventions that target the underlying molecular drivers of disease, improving outcomes in chronic conditions.
Topical drug delivery systems are evolving to enhance the penetration of active pharmaceutical ingredients through the skin barrier. Advanced formulations, including nanoemulsions, liposomes, and microneedle patches, are being developed to improve efficacy and reduce systemic side effects. The primary adopters are companies focused on reformulating existing molecules for psoriasis and acne, and this innovation is unifying drug delivery science with material science to create more effective, patient-friendly treatments.
Regulatory bodies are adapting to the pace of innovation with new frameworks. The PMDA in Japan, for example, has established a "sakigake" designation system to promote the research and development of innovative new medicines, including those for dermatological use. This policy accelerates the review and approval timeline for drugs that offer significant benefits over existing therapies. The orphan drug segment for rare skin diseases is most affected, as it allows for quicker market access in a key pharmaceutical market.
A notable behavioral shift is occurring in how treatment success is measured and valued. Patient-reported outcome measures, which capture the impact of a disease and its treatment on a patient's quality of life, are becoming critical endpoints in clinical trials and key factors in prescribing decisions. This disrupts the traditional focus on physician-assessed clinical signs alone. This trend is most visible in the management of atopic dermatitis and hidradenitis suppurativa, particularly within the United States.
Dermatology Drugs Market Segmentation
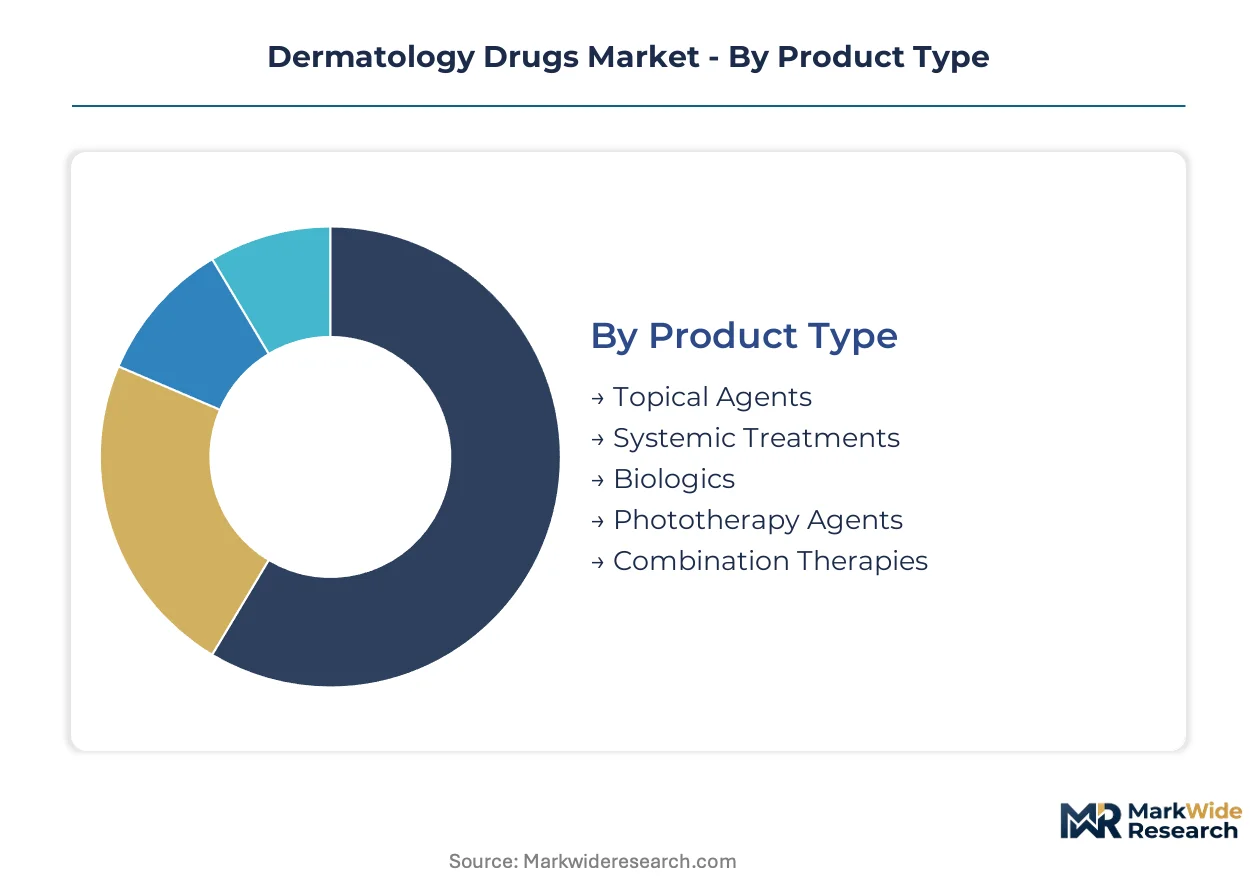
The dermatology drugs market segmentation reveals diverse therapeutic approaches and patient needs across skin, hair, and nail conditions. Understanding these segments is crucial for pharmaceutical companies to tailor research, development, and commercial strategies.
Product Type:
Buyer differentiation in this segment primarily stems from the severity and nature of the dermatological condition, dictating the required mechanism of action.
- Biologics:These large-molecule drugs target specific immune pathways in chronic inflammatory skin diseases. Demand concentrates in developed economies like the United States, driven by high healthcare expenditure.
- Systemic Treatments:Administered orally or via injection, these agents act throughout the body for widespread or severe dermatological conditions. Demand is stable across geographies due to established efficacy.
- Topical Agents:Applied directly to the skin, these formulations offer localized treatment for mild to moderate conditions like eczema and acne.
- Phototherapy Agents:These drugs enhance skin sensitivity to light, used with specific light wavelengths to treat conditions such as psoriasis and vitiligo.
- Combination Therapies:These treatments involve simultaneous use of two or more active ingredients to achieve synergistic effects or address multiple disease pathways.
Topical Agents lead volumes today; Biologics are gaining share fastest.
Therapy Area:
The clinical focus for dermatological treatments directly shapes the therapeutic approach, managing chronic inflammatory conditions or combating specific infections.
- Psoriasis:This chronic autoimmune condition manifests as scaly skin patches, often treated with biologics and systemic therapies. Demand for advanced treatments is high in industrialized nations due to increasing incidence and desire for remission.
- Eczema:Characterized by inflamed, itchy skin, eczema often requires a multi-faceted approach involving topical and novel biologics. The expanding patient population drives demand for effective symptom control.
- Acne:This common skin condition involves clogged pores and inflammation, primarily treated with topical retinoids, antibiotics, and hormonal therapies.
- Fungal Infections:Managed with topical and oral antifungal agents, these conditions target specific fungal pathogens like athlete's foot or ringworm.
- Vitiligo:This autoimmune disease causes skin depigmentation, with treatments focusing on repigmentation through phototherapy, topical agents, and emerging systemic options.
Psoriasis treatments currently command significant market value; Eczema therapies exhibit the steepest expansion trajectory.
End User:
Customer type defines the point of care and drug procurement scale, influencing distribution channels and patient access to specialized dermatological therapies.
- Dermatology Clinics:These specialized outpatient facilities are primary prescribers and administrators of a wide range of dermatological drugs, including advanced biologics. Their role is critical in patient diagnosis and management.
- Specialty Pharmacies:These pharmacies manage and dispense high-cost, complex biologics, often requiring specific handling and patient education. They are crucial for advanced dermatology drug supply.
- Hospitals:These institutions primarily handle acute dermatological emergencies, inpatient care for severe conditions, and surgical interventions, utilizing various drugs.
- Ambulatory Care Centers:These facilities provide outpatient medical services, including minor dermatological procedures and follow-up care, often dispensing less complex medications.
Dermatology Clinics represent the largest end-user segment for prescriptions; Specialty Pharmacies are climbing the fastest in dispensing high-value treatments.
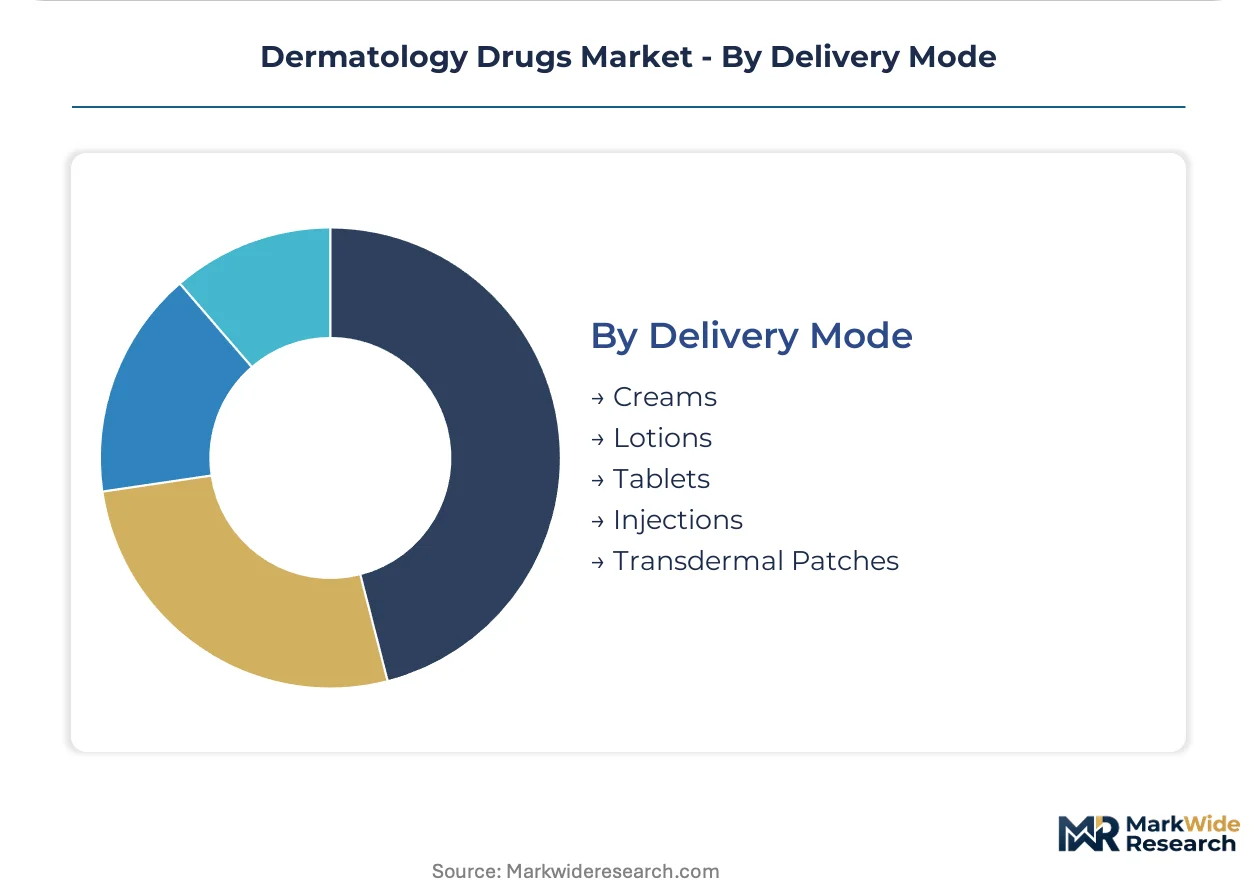
Delivery Mode:
The technology and maturity of drug delivery systems directly impact patient convenience, adherence, and active ingredient penetration to target sites.
- Injections:This mode, including subcutaneous and intravenous routes, is essential for biologics and systemic treatments requiring precise dosing and high bioavailability. Its prevalence is driven by the need for systemic action.
- Tablets:Oral tablets represent a convenient and widely accepted delivery method for systemic small-molecule drugs, offering ease of administration for many dermatological conditions. Patient preference drives strong demand.
- Creams:These semi-solid emulsions are common topical formulations, providing localized drug delivery for conditions like eczema, acne, and fungal infections.
- Lotions:Liquid-based topical preparations offer easier spreadability over large skin areas, suitable for widespread conditions or sensitive skin.
- Transdermal Patches:These adhesive patches deliver drugs through the skin into the bloodstream, offering sustained systemic release and bypassing first-pass metabolism.
Creams and Lotions maintain a foundational position in topical treatments; Injections are expanding most quickly for advanced systemic therapies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage influences the global dermatology drugs market, with production often shifting to regions offering favorable compliance costs and streamlined approval processes. This dynamic impacts pharmaceutical companies' investment decisions and market entry strategies across various geographies. Advanced healthcare systems and high patient awareness also drive demand for novel therapies.
United States
United States demand for advanced biologics is driven by a high prevalence of chronic skin conditions and robust healthcare expenditure. The FDA's stringent yet clear regulatory pathways for novel drugs provide market predictability for manufacturers. Major biopharmaceutical clusters in Boston and San Francisco continue to innovate in dermatological drug discovery, attracting significant investment.
Germany
Germany exhibits strong demand for specialty dermatology drugs, supported by its comprehensive healthcare system and patient access to innovative treatments. The EMA's centralized approval process, headquartered in Amsterdam, streamlines market access across the European Union. Pharmaceutical research hubs in cities like Berlin and Munich are actively developing new therapeutic agents for skin conditions.
Japan
Japanese patients increasingly seek targeted therapies for conditions like psoriasis and atopic dermatitis, reflecting rising awareness and disposable income. The PMDA's "sakigake" designation system accelerates review timelines for promising dermatological innovations, fostering local R&D. Research institutions in Tokyo and Osaka are at the forefront of advanced drug delivery system development.
China
China's dermatology drug market is expanding due to a large patient population and increasing healthcare infrastructure investment. The NMPA's reforms aim to expedite drug approvals, especially for new and innovative treatments from both domestic and international companies. Pharmaceutical manufacturing centers in Shanghai and Guangzhou are scaling up production capabilities for dermatological products.
India
India's market for dermatology drugs is growing, fueled by a large population, improving access to healthcare, and a rising burden of skin diseases. The CDSCO regulates drug manufacturing and approvals, balancing accessibility with quality standards for both generics and novel therapies. Hyderabad and Ahmedabad are significant pharmaceutical production hubs, supporting both domestic and export markets.
Dermatology Drugs Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue niche orphan indications and novel topical formulations. The market structure exhibits a tiered consolidation, with large pharmaceutical companies dominating high-value biologic segments. Strategic archetypes include diversified portfolios, immunology specialists, and innovation-focused biotech firms. Dominant competitive moves involve strategic partnerships for pipeline development and portfolio diversification into new therapeutic areas.
Specialists in immunology and chronic inflammatory conditions, such as AbbVie Inc., exemplify the market's focus on high-value biologics and maintaining significant market presence. Novartis AG, with its diversified pipeline, represents a broader approach to dermatological diseases, encompassing both novel and established therapies across various segments. Eli Lilly and Company occupies a position at the forefront of innovation, particularly in developing novel biologic therapies for atopic dermatitis and psoriasis, positioning itself as a key innovator in the advanced treatment space.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Novartis AG |
| Pfizer Inc. |
| Johnson & Johnson Services, Inc. |
| Eli Lilly and Company |
| Sanofi |
| Amgen Inc. |
| LEO Pharma A/S |
| Galderma |
| Others |
Cost & Logistics Intelligence
Specialized biopharmaceutical manufacturing talent in regions like the United States and Europe drives significant labor-cost differentials, directly influencing the pricing tiers of complex dermatology drugs.
Pricing Analysis
Distributor margins for specialty dermatology drugs reflect the complex logistics and patient support required for high-value biologics. Value-based pricing models dominate for novel biologics, with differentiation driven by clinical efficacy, regulatory approval status from agencies like the FDA, and bundled patient support programs. Pricing pressure stems from stringent reimbursement criteria imposed by national health systems and private payors. While patients with severe, chronic conditions exhibit low price sensitivity for effective treatments, healthcare systems are highly sensitive to the overall cost burden.
Supply Chain Analysis
FDA and EMA qualification gating for biologics manufacturing facilities creates significant entry barriers and dictates the global supply footprint for dermatology drugs. Production capability concentrates in advanced pharmaceutical hubs like the United States, Germany, and Japan. The supply chain draws from highly specialized inputs such as cell culture media and purification resins, posing a structural risk due to manufacturing bottlenecks in limited specialized facilities. Distribution runs through specialty pharmacies and direct-to-dermatology clinics for advanced therapies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dermatology drugs market is a late-cycle quality story, driven by a pronounced demand-shift toward premium biologic therapies for chronic inflammatory conditions.
For Market Incumbents:Anchor established market share by continuously diversifying immunology pipelines to counter biosimilar competition and payer resistance. Strategic partnerships for novel mechanism of action R&D, such as JAK and TYK2 inhibitors, are crucial. Invest in robust patient support programs and deepen channel control.
For New Entrants and Emerging Players:Patients with rare dermatological diseases represent an underserved buyer archetype, offering white-space opportunities for new entrants. Target orphan indications with accelerated regulatory pathways, like Japan's PMDA "sakigake" system. Develop novel topical formulations with biologic-like efficacy for mild-to-moderate conditions, emphasizing patient-friendly delivery.
For Investors and Strategic Acquirers:Large pharmaceutical companies are the most active acquirers in this space, seeking to bolster immunology portfolios for sustained long-term viability. The market indicates continued demand for advanced therapies over the next five to ten years. Focus on innovation-focused biotech firms with late-stage pipeline assets. Clinical trial success rates for novel biologics serve as a key signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Advancing late-stage trials for novel biologics, such as JAK inhibitors, secures future market leadership against incumbents. |
| Regulatory Approval Pathway | Leveraging accelerated pathways like Japan's "sakigake" designation grants quicker market access for innovative dermatology drugs. |
| Manufacturing Scale-Up | Investing in specialized biologics manufacturing capacity addresses production bottlenecks and meets rising global demand. |
| Pipeline Diversification | Expanding therapeutic portfolios into new indications like vitiligo or hidradenitis suppurativa mitigates revenue risks from patent cliffs. |
| Strategic Partnership | Collaborating with academic institutions or biotech firms accelerates the discovery of next-generation dermatological therapies. |
Research Approach
Bottom-up patient population modeling reconciled against top-down pharmaceutical manufacturer tracking forms the analytical core of this study. Primary interviews with drug development executives, regulatory affairs leads, and dermatology clinic managers provided qualitative insights. Secondary validation drew from FDA filings, EMA submissions, and ClinicalTrials.gov databases. This triangulated approach ensured robust data integrity and market understanding.
Historical trendline analysis across the past five years established a foundational understanding of market dynamics and growth patterns. The forecast framework modeled segmentation dimensions including product type, therapy area, end user, delivery mode, and regional regulatory cluster across the analysis window. Compound Annual Growth Rates (CAGRs) were derived from projected shifts in disease prevalence rates and biologic therapy uptake rates. Quantitative projections integrated these factors for comprehensive market sizing.
Underlying measurement precision varies by segment; established therapy areas like psoriasis carry tighter precision than emerging orphan dermatological diseases. Forecasts reflect assumptions concerning future major drug approvals and significant reimbursement policy shifts. A model refresh is warranted upon material change in regulatory frameworks or clinical trial outcomes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dermatology
Dermatology Cryosurgery Units Market
Dermatology
Australia Skin Laser Market
Dermatology
US and Canada Skin Cancer Dermatology Market
Dermatology
Global Ozone Therapy in Dermatology Market
Dermatology
Global Radiodermatitis Market
Dermatology
Radiation Dermatitis Market
Dermatology
Global Dermatitis Herpetiformis Market
Dermatology
Telogen Effluvium Treatment Market
Dermatology
Dermabrasion and Micro Needling Market
Dermatology
Dermatology Devices Market
Dermatology
Seborrheic Keratosis Market
Dermatology
Keloid Treatment Market
Dermatology
Global Dermatological Therapeutics Market
Dermatology
China Scar Treatment Market
Dermatology
Dermatology Diagnostic Devices and Therapeutics Market
Dermatology
Androgenetic Alopecia Market