
 UK Scar Treatment Market | 2026-2036
UK Scar Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
UK Scar Treatment Market Insights
CE marking under the UKCA transition timeline is redrawing competitive access for scar treatment devices and topical products. Smith & Nephew plc leverages its wound care heritage to anchor hospital procurement channels for silicone-based therapies. Mölnlycke Health Care AB specializes in advanced wound management and competes aggressively in dermatology clinic supply chains. Lumenis Ltd. dominates laser and energy-based scar revision technology, extending its installed base across private aesthetic centres.
Scar treatment encompasses topical formulations, mechanical sheeting, and energy-based interventions designed to modulate collagen remodelling and improve functional or cosmetic outcomes following dermal injury. Silicone gel and silicone sheets form the backbone of first-line conservative management, typically applied for 12–24 hour daily cycles over 8–12 week protocols to flatten and soften raised scar tissue. Keloid and hypertrophic scar categories command the deepest clinical engagement due to their recurrence-prone pathology and higher intervention thresholds. Home care end users represent the fastest-expanding consumption node, though margin pools remain thicker in plastic surgery centres where combination protocols bundle multiple modalities.
The Medicines and Healthcare products Regulatory Agency enforces UKCA marking requirements that now gate device market entry, while the General Pharmaceutical Council shapes dispensing standards for pharmacy-distributed topical therapies. NHS England referral criteria for scar revision procedures influence which patients enter private payment channels versus reimbursed care pathways. Stakeholders must monitor whether MHRA aligns future medical device regulations with evolving EU MDR equivalence agreements or pursues independent divergence that fragments certification burdens.
Market Dynamics
The UKCA marking transition post-Brexit is fragmenting device certification pathways, forcing manufacturers to duplicate compliance investments and reshaping which suppliers can access NHS procurement channels versus private aesthetic networks.
Growth Catalysts
- Rising dermatology clinic volumes:Patient throughput at private skin clinics in London and the South East accelerates demand for combination therapy protocols bundling silicone sheeting with energy-based devices.
- MHRA regulatory clarity:The Medicines and Healthcare products Regulatory Agency's finalized UKCA timelines provide investment certainty for domestic manufacturers of Class IIa scar treatment devices.
- Home care protocol expansion:Extended daily wear silicone gel protocols shift treatment completion from clinical settings to patient-managed environments, expanding addressable volume.
Market Restraints
- Medical-grade silicone supply concentration:Raw material sourcing clusters in German and US chemical producers, exposing UK formulators to euro-dollar volatility and bulk order minimums.
- Energy-based device capex thresholds:Fractional laser and radiofrequency platforms require six-figure capital commitments, limiting independent clinic participation.
- Keloid recurrence biology:Pathological scar categories exhibit high retreatment rates, compressing per-patient lifetime value and straining reimbursement logic.
Strategic Opportunities
- Underpenetrated NHS referral pathways:NHS England's scar revision criteria create a backlog of functional impairment cases eligible for private conversion in Northern England and the Midlands.
- Telemedicine-guided home protocols:Remote monitoring platforms enable dermatologists to supervise silicone adherence and compression therapy without face-to-face visits.
- Combination device-topical bundling:Aesthetic chains are piloting subscription models pairing laser pretreatment with take-home silicone regimens.
Industry Challenges
- Laser operator certification bottlenecks:Energy-based scar revision requires specialized training pathways that NHS trusts and private clinics struggle to staff at scale.
- UKCA-MDR divergence uncertainty:Manufacturers face parallel certification burdens if MHRA device rules drift from EU MDR equivalence, stretching compliance timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Scar Treatment Market |
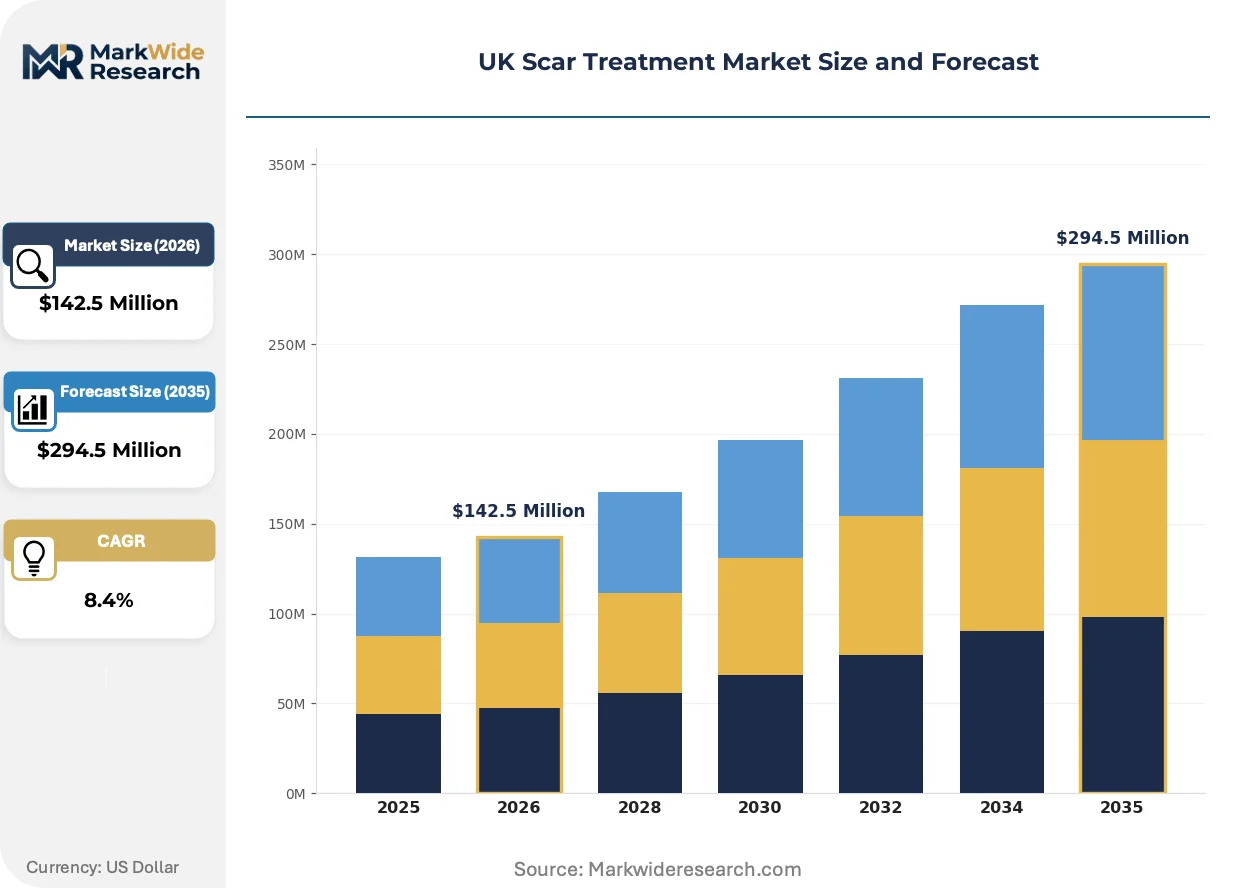
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $294.5 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone Gel, Silicone Sheets, Ointments, Creams, Spray Therapy Area: Keloid Scars, Hypertrophic Scars, Atrophic Scars, Contracture Scars End User: Dermatology Clinics, Plastic Surgery Centers, Medical Spas, Home Care Distribution Channel: Pharmacies, Online Retail, Hospitals, Specialty Stores |
| Companies Covered | Merz Pharmaceuticals GmbH, Sonoma Pharmaceuticals Inc., Smith & Nephew plc, CCA Industries Inc., Cynosure LLC, Mölnlycke Health Care AB, Perrigo Company plc, Suneva Medical Inc., Lumenis Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Scar Treatment Market Trends and Innovations
Silicone-based conservative management is converging with energy-based modalities, creating hybrid protocol standards that redefine first-line versus specialist intervention boundaries across UK care settings.
Needle-free radiofrequency microneedling is supplanting traditional ablative laser for hypertrophic scar revision in private London clinics. The technology delivers controlled thermal injury without epidermal disruption, shortening recovery windows from weeks to days. Dermatology groups report faster patient throughput and reduced post-treatment complication management, compressing total cost-per-outcome against legacy CO2 laser platforms.
The Medicines and Healthcare products Regulatory Agency's phased UKCA enforcement is bifurcating the device landscape between grandfathered CE-marked inventory and new UK-specific certifications. Manufacturers with existing notified body relationships in Germany or Ireland face expedited transition pathways, while smaller device importers confront extended market access freezes. Private aesthetic chains are consolidating supplier relationships around dual-certified portfolios to hedge regulatory friction.
Patient-initiated purchasing through pharmacy and direct-to-consumer channels is displacing clinician-gatekept silicone dispensing. Boots and Superdrug shelf placement of medical-grade scar gels captures post-surgical patients before specialist referral, shifting brand selection authority from plastic surgeons to retail pharmacists. This pattern concentrates in Greater London and Manchester, where pharmacy density supports impulse replenishment of 8–12 week treatment cycles.
UK Scar Treatment Market Segmentation
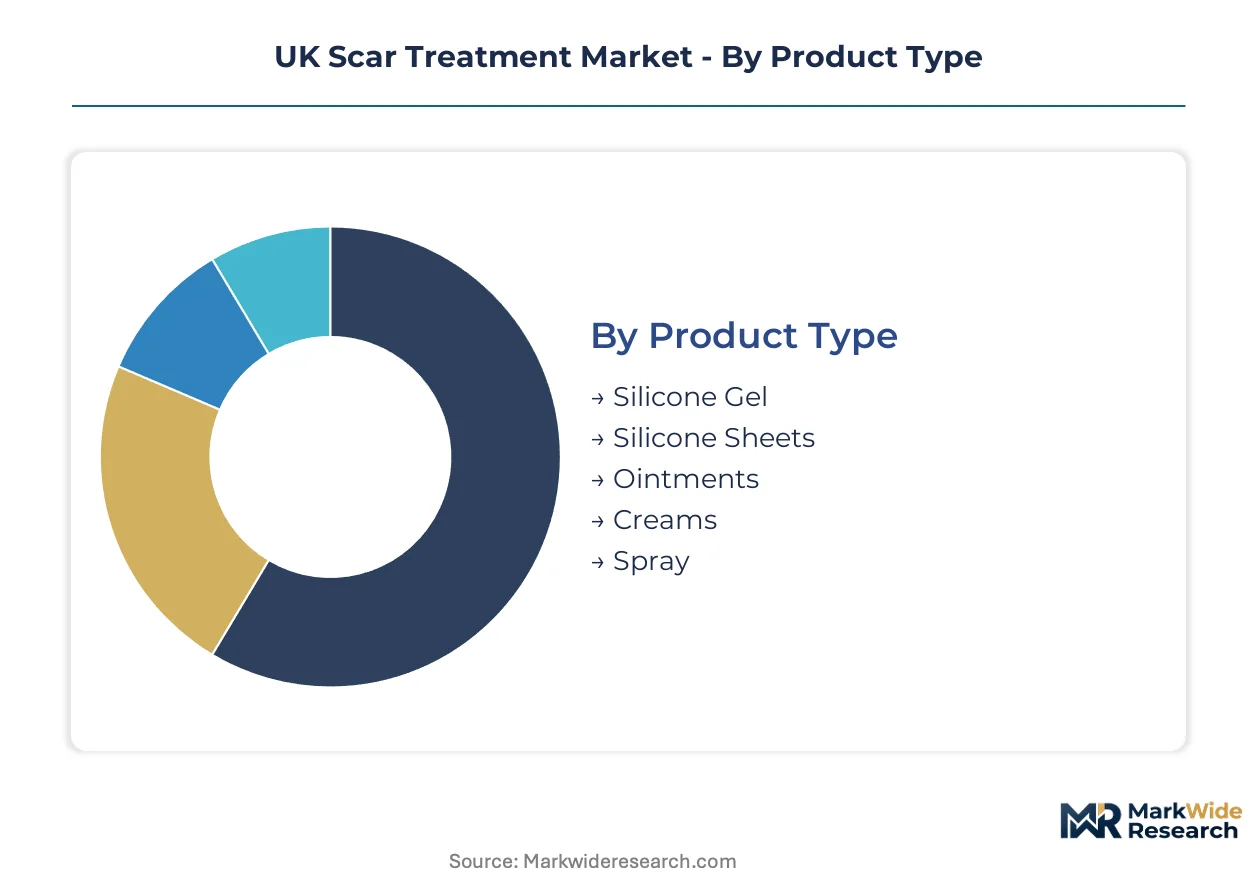
Scar treatment revenue flows unevenly across product formats and care settings. Manufacturers align R&D and distribution investments around margin concentration points rather than volume alone.
Product Type:
Silicone-based formats command the thickest margin pools due to clinical validation and repeat purchase cycles.
- Silicone Gel:Transparent, self-drying polymer formulation enables discreet application under clothing and cosmetics. London dermatology clinics prescribe 15–20 gram tubes as standard discharge protocol following Mohs surgery or cesarean section. Boots pharmacy placement captures patient-initiated replenishment without specialist gatekeeping.
- Silicone Sheets:Medical-grade elastomer sheeting delivers sustained occlusion and hydration through 12–24 hour daily wear cycles. NHS procurement channels favor adhesive-backed formats for burn unit discharge kits, though patient compliance drops with visible facial placement.
- Ointments:Petroleum-based carriers with onion extract or vitamin E derivatives occupy pharmacy value tiers.
- Creams:Water-in-oil emulsions target the post-laser recovery window in private aesthetic chains.
- Spray:Aerosolized silicone delivery suits large surface area burns and pediatric applications where tactile sensitivity complicates gel application.
The dominant share belongs to Silicone Gel, while Silicone Sheets is closing the gap fastest through expanded NHS formulary inclusion.
Therapy Area:
Pathological scar categories drive intervention intensity and reimbursement complexity.
- Keloid Scars:Benign fibroproliferative growths extending beyond original wound margins with recurrence rates exceeding 50% post-excision. Birmingham and Manchester tertiary referral centers combine intralesional corticosteroid injection with silicone compression as first-line protocol.
- Hypertrophic Scars:Raised collagen deposits remaining within wound boundaries, frequently resolving spontaneously over 12–18 months. Private London clinics bundle fractional radiofrequency pretreatment with home silicone regimens to accelerate maturation timelines.
- Atrophic Scars:Depressed fibrotic tissue from acne or varicella, addressed through dermal filler or subcision rather than topical silicone.
- Contracture Scars:Functional impairment from burn-induced skin tightening, concentrated in regional NHS burn units with limited private conversion.
Keloid Scars anchors specialist revenue through retreatment cycles, though Hypertrophic Scars is expanding most quickly via aesthetic channel protocol bundling.
End User:
Care setting determines price realization and purchase authority.
- Home Care:Patient-directed purchasing through pharmacy and e-commerce channels, expanding fastest as telemedicine supervision replaces clinic-based follow-up.
- Dermatology Clinics:Combination protocol gatekeepers linking energy-based devices with take-home silicone regimens.
- Plastic Surgery Centers:High-margin bundled care with procedure-linked product dispensing.
- Medical Spas:Aesthetic-focused delivery with lighter clinical oversight and premium positioning.
Home Care captures volume leadership, while Dermatology Clinics retains the steepest margin expansion trajectory through protocol control.
Distribution Channel:
Channel selection shapes brand authority and replenishment economics.
- Pharmacies:Boots and Superdrug shelf placement intercepts post-surgical patients before specialist referral, shifting selection authority to retail pharmacists in Greater London and Manchester.
- Online Retail:Amazon and clinic-branded e-commerce platforms enable subscription replenishment of 8–12 week treatment cycles.
- Hospitals:NHS procurement frameworks and private discharge kit assembly.
- Specialty Stores:Aesthetic supply distributors serving independent clinic networks.
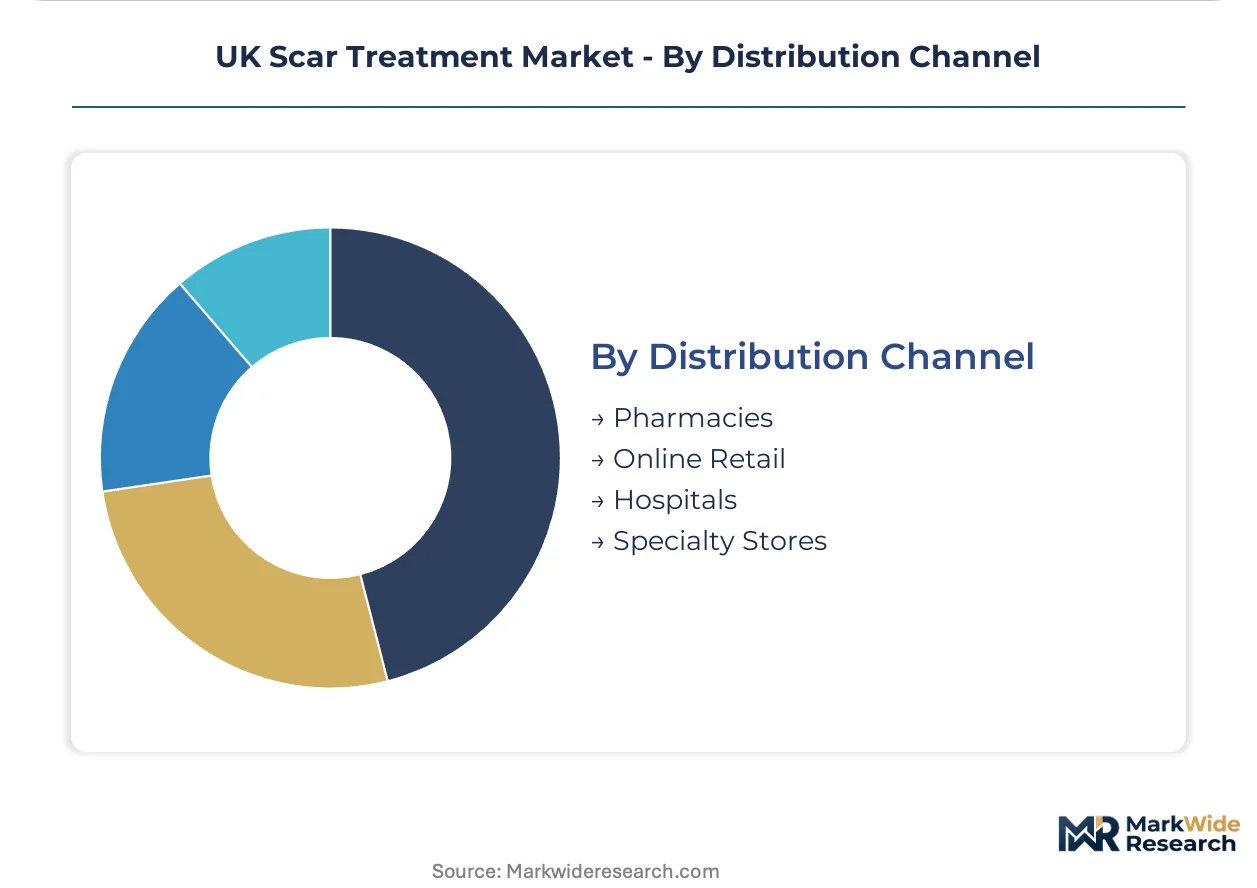
Pharmacies holds the established position, while Online Retail is gaining share fastest through subscription model adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The M1 motorway corridor and West Coast Main Line rail link concentrate scar treatment distribution infrastructure across England's economic spine. Private aesthetic chains cluster along these transport arteries to access London's procurement networks and Manchester's manufacturing base.
London and the South East
Private dermatology clinic density in Harley Street and Canary Wharf drives combination therapy adoption. NHS England's specialized commissioning framework restricts scar revision referrals, pushing functional cases into private payment channels. The Thames Valley corridor hosts medical-grade silicone gel manufacturing for pharmacy distribution.
Midlands
Birmingham's Queen Elizabeth Hospital burn unit anchors regional keloid research and tertiary referrals. MHRA's UKCA marking enforcement creates compliance bottlenecks for device importers based in the West Midlands logistics hubs. Leicester's pharmaceutical packaging sector supplies NHS discharge kit assembly.
North England
Manchester's private aesthetic market expands through telemedicine-linked home care protocols. Underpenetrated NHS scar revision pathways in Yorkshire create conversion opportunities for functional impairment cases. The Liverpool-Manchester rail corridor enables same-day silicone gel replenishment from central distribution.
Scotland
NHS Scotland's integrated health boards centralize scar treatment procurement through Glasgow and Edinburgh teaching hospitals. Scottish Medicines Consortium assessments influence formulary inclusion for silicone-based therapies. Aberdeen's oil economy sustains private cosmetic surgery demand independent of English referral patterns.
Wales
Cardiff's regional burns unit serves sparse population centers through mobile outreach. Welsh Government procurement frameworks favor domestic silicone gel manufacturers over English suppliers. Swansea's medical device cluster experiments with needle-free radiofrequency platforms for hypertrophic scar revision.
UK Scar Treatment Market Competitive Landscape
Listed leaders compete with private specialists across regulatory certification capacity, forcing divergence in UKCA transition strategies. The vendor base splits between multinational wound care conglomerates with dedicated notified body relationships and independent device importers facing extended market access freezes. Three archetypes dominate: hospital procurement anchors leveraging NHS framework contracts, aesthetic chain suppliers bundling energy-based devices with take-home protocols, and pharmacy-focused formulators capturing patient-initiated replenishment. M&A activity concentrates on dual-certified device portfolios, while capacity expansion targets silicone gel manufacturing for direct-to-consumer channels.
Among UK-headquartered wound care specialists, Smith & Nephew plc represents the hospital procurement anchor archetype through its heritage in surgical discharge protocols. Mölnlycke Health Care AB exemplifies the aesthetic chain supplier model with advanced wound management positioning across dermatology clinic supply chains. Lumenis Ltd. occupies the energy-based technology tier, anchoring laser and radiofrequency scar revision platforms in private aesthetic centers. These three companies illustrate how regulatory transition timelines are redrawing competitive access rather than market share alone.
| Leading Market Players |
|---|
| Merz Pharmaceuticals GmbH |
| Sonoma Pharmaceuticals Inc. |
| Smith & Nephew plc |
| CCA Industries Inc. |
| Cynosure LLC |
| Mölnlycke Health Care AB |
| Perrigo Company plc |
| Suneva Medical Inc. |
| Lumenis Ltd. |
| Others |
Pricing and Supply Chain Analysis
Needle-free radiofrequency microneedling displacing traditional CO2 laser platforms redraws procurement economics across London aesthetic chains while compressing capital recovery timelines for clinic operators investing in scar revision capacity.
Pricing Analysis
Volume-discount tiering structures separate NHS procurement frameworks from private aesthetic channel pricing. Three-tier pricing stratifies across premium laser-device bundles, standard silicone gel protocols, and economy pharmacy-grade sheeting. Price differentiation centers on UKCA certification grade and clinical supervision depth. Pricing pressure stems from Boots and Superdrug shelf placement capturing patient-initiated purchasing before specialist gatekeeping. NHS trusts exhibit highest price sensitivity, while Harley Street cosmetic surgery centers tolerate premium positioning for combination therapy protocols.
Supply Chain Analysis
Strategic stockpiling of medical-grade silicone polymer dominates inventory strategy among UK formulators facing German and US chemical producer minimum order thresholds. Raw material sourcing draws from German elastomer specialists and US silicone polymer manufacturers. Supply chain risk concentrates in euro-dollar volatility exposure on bulk chemical imports. Distribution runs through M1 corridor logistics hubs serving London procurement networks and Manchester packaging operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
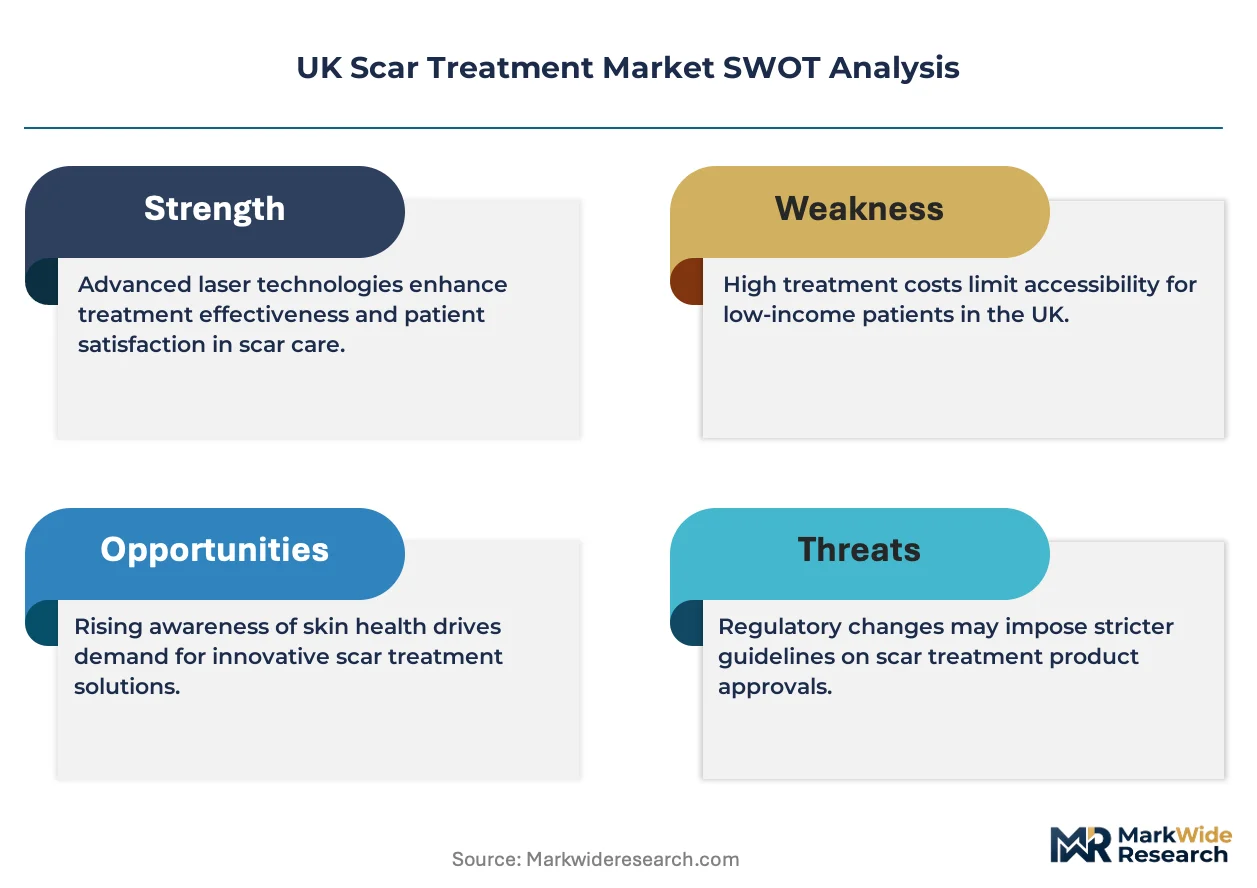
The UK scar treatment market constitutes a defensive-moat opportunity anchored in MHRA regulatory entrenchment, where UKCA certification timelines create switching costs that freeze out uncertified competitors.
For Market Incumbents: Fortify hospital procurement channel control through dual-certified device portfolios hedging UKCA-MDR divergence risk. Deepen silicone gel manufacturing capacity in Thames Valley corridors to capture pharmacy-directed replenishment cycles. Vertical integration into medical-grade polymer compounding reduces euro-denominated raw material exposure. For New Entrants and Emerging Players: Anchor in Northern England NHS referral backlogs where functional scar revision cases convert to private payment channels. Target telemedicine-guided home care protocols as the most penetrable segment, leveraging remote monitoring platforms to supervise silicone adherence without London clinic infrastructure. Pursue pharmacy e-commerce partnerships for patient-initiated replenishment capture. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed aesthetic clinic roll-ups consolidating around dual-certified energy-based device suppliers. Long-term viability frames around 5-10 year UKCA regulatory stability enabling platform standardization across combined silicone-topical and laser-device offerings. Monitor MHRA equivalence agreement negotiations with EU MDR as the critical inflection signal for certification burden fragmentation or harmonization.| Strategic Initiative | Industry Significance |
|---|---|
| UKCA Dual Certification Investment | Secures parallel NHS and private aesthetic channel access under diverging regulatory frameworks. |
| Silicone Gel Manufacturing Scale-Up | Captures pharmacy-directed replenishment economics in Greater London and Manchester distribution clusters. |
| Telemedicine Platform Integration | Enables remote supervision of home care protocols without Harley Street clinic infrastructure investment. |
| Needle-Free RF Device Deployment | Compresses patient recovery windows from weeks to days against legacy CO2 laser platforms. |
| Pharmacy E-Commerce Partnership | Intercepts post-surgical patients before specialist referral through Boots and Superdrug shelf placement. |
Research Methodology
Desk research of MHRA regulatory filings, NHS procurement databases, and GPO contract disclosures preceded structured interviews with dermatology clinic operators, biomedical device engineers, hospital purchasing committee members, and pharmacy category buyers. Secondary validation drew from UKCA certification timelines, EU MDR equivalence documentation, and silicone polymer trade flow records. Bottom-up demand modeling triangulated against top-down market sizing across therapy area and end-user segments.
Variance decomposition across product type, therapy area, end-user setting, and distribution channel dimensions shaped the analytical framework. CAGRs derived from patient volume trajectories at dermatology clinics, NHS referral pattern shifts, and home care protocol expansion rates. Forecast inputs incorporated MHRA regulatory timeline certainty, pharmacy channel penetration curves, and energy-based device replacement cycles throughout the projection horizon.
Material uncertainties — MHRA-MDR divergence decisions, keloid recurrence rate variability, and medical-grade silicone supply disruptions — sit outside the modeled envelope. Forecasts reflect assumptions of stable UKCA enforcement timelines and continued NHS referral restriction patterns. Revision becomes warranted when regulatory equivalence negotiations cross divergence thresholds or pharmacy channel capture accelerates beyond modeled replenishment cycles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dermatology
Global Ozone Therapy in Dermatology Market
Dermatology
Pigmented Lesion Treatment Market
Dermatology
Global Rosacea Market
Dermatology
Global Dermatology Cro Market
Dermatology
Skin Cancer Market
Dermatology
Telogen Effluvium Treatment Market
Dermatology
Dermatology Software Market
Dermatology
Chronic Spontaneous Urticaria Market
Dermatology
Japan Scar Treatment Market
Dermatology
Dermatology Cryosurgery Units Market
Dermatology
Saudi Arabia Hair Transplant Market
Dermatology
Global Dermatological OTC Drugs Market
Dermatology
Scar Treatment Market
Dermatology
Folliculitis Market
Dermatology
Skin Excision Market
Dermatology
Global Hirsutism Market