
 Aldosteronism Treatment Market | 2026-2036
Aldosteronism Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Aldosteronism Treatment Market Outlook
The EU Medical Device Regulation is shifting the cost-of-entry calculus for aldosteronism diagnostic and treatment platforms across European markets. Pfizer Inc. leverages its established cardiovascular portfolio to sustain leadership in mineralocorticoid receptor antagonist supply chains. Novartis AG anchors its position through specialized R&D programs targeting resistant hypertension endpoints. Bayer AG differentiates via manufacturing scale that supports consistent API availability for spironolactone formulations.
Aldosteronism treatment encompasses pharmacological interventions targeting pathological aldosterone excess, primarily employing mineralocorticoid receptor antagonists such as spironolactone and eplerenone that competitively inhibit aldosterone binding at receptor sites in renal tubular epithelium. These therapies restore potassium homeostasis, reduce sodium retention, and lower blood pressure in patients with primary or secondary aldosteronism. Among therapy areas, hypertension commands the largest patient volume while heart failure represents the fastest-expanding application as cardiologists adopt earlier mineralocorticoid antagonism. Oral delivery mode dominates prescribing patterns due to patient compliance advantages, though intravenous formulations capture critical margin pools in acute hospital settings.
The FDA oversees new drug approvals and label expansions for aldosteronism therapies in the United States, while the EMA coordinates centralized marketing authorization across European member states and the PMDA evaluates cardiovascular drug submissions in Japan. These regulators shape demand through bioequivalence requirements for generic entrants and cardiovascular outcome trial mandates for novel agents. Stakeholders must monitor evolving pharmacovigilance obligations and real-world evidence requirements that will determine competitive positioning in mineralocorticoid receptor antagonist markets.
Market Dynamics
The FDA's accelerated approval pathways for cardiovascular therapies are compressing clinical trial timelines and forcing sponsors to front-load real-world evidence collection for mineralocorticoid receptor antagonist label expansions.
Growth Catalysts
- Resistant hypertension protocols:Endocrinology clinics across the United States are expanding mineralocorticoid receptor antagonist prescribing for patients failing first-line antihypertensive regimens, creating sustained demand pull for spironolactone and eplerenone formulations.
- EU MDR diagnostic platform harmonization:The EU Medical Device Regulation is standardizing aldosteronism diagnostic requirements across European member states, reducing fragmentation in adrenal disorder screening workflows and enabling cross-border patient referral networks.
- Adrenal venous sampling automation:Interventional radiology suites in tertiary hospitals are adopting computed tomography-guided catheter placement systems that reduce operator-dependent variability in lateralization procedures for surgical candidate selection.
Market Restraints
- Active pharmaceutical ingredient concentration:Spirulactone API manufacturing clusters heavily in Chinese chemical synthesis facilities, exposing formulation sponsors to import tariff volatility and geopolitical supply interruptions.
- Hyperkalemia monitoring burden:Serum potassium surveillance requirements for mineralocorticoid receptor antagonist therapy impose recurring laboratory costs and specialist follow-up obligations that limit primary care prescribing autonomy.
- Endocrine surgeon scarcity:Adrenalectomy-capable surgical subspecialists concentrate in academic medical centers, creating geographic access barriers for unilateral aldosterone-producing adenoma patients outside major metropolitan corridors.
Strategic Opportunities
- Underpenetrated Japanese screening:The PMDA's evolving hypertension guideline alignment with primary aldosteronism detection protocols creates whitespace for diagnostic platform vendors and referral network builders in prefectural hospital systems.
- Non-steroidal antagonist development:Selective mineralocorticoid receptor modulators without progesterone receptor cross-activity are advancing through cardiovascular outcome trials, targeting the gynecomastia-limited patient segment that discontinues spironolactone.
- Telemedicine endocrinology channels:Virtual specialist consultation platforms are penetrating rural and underserved U.S. markets, extending adrenal disorder expertise to patients distant from tertiary adrenal centers.
Industry Challenges
- Interventional radiology training pipelines:Adrenal venous sampling proficiency requires specialized fellowship exposure that U.S. residency programs are contracting, narrowing the specialist pool for confirmatory diagnostic procedures.
- Liquid chromatography-mass spectrometry validation:Plasma aldosterone and renin assay standardization across hospital laboratories remains inconsistent, generating diagnostic discordance that complicates multi-site clinical trial enrollment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aldosteronism Treatment Market |
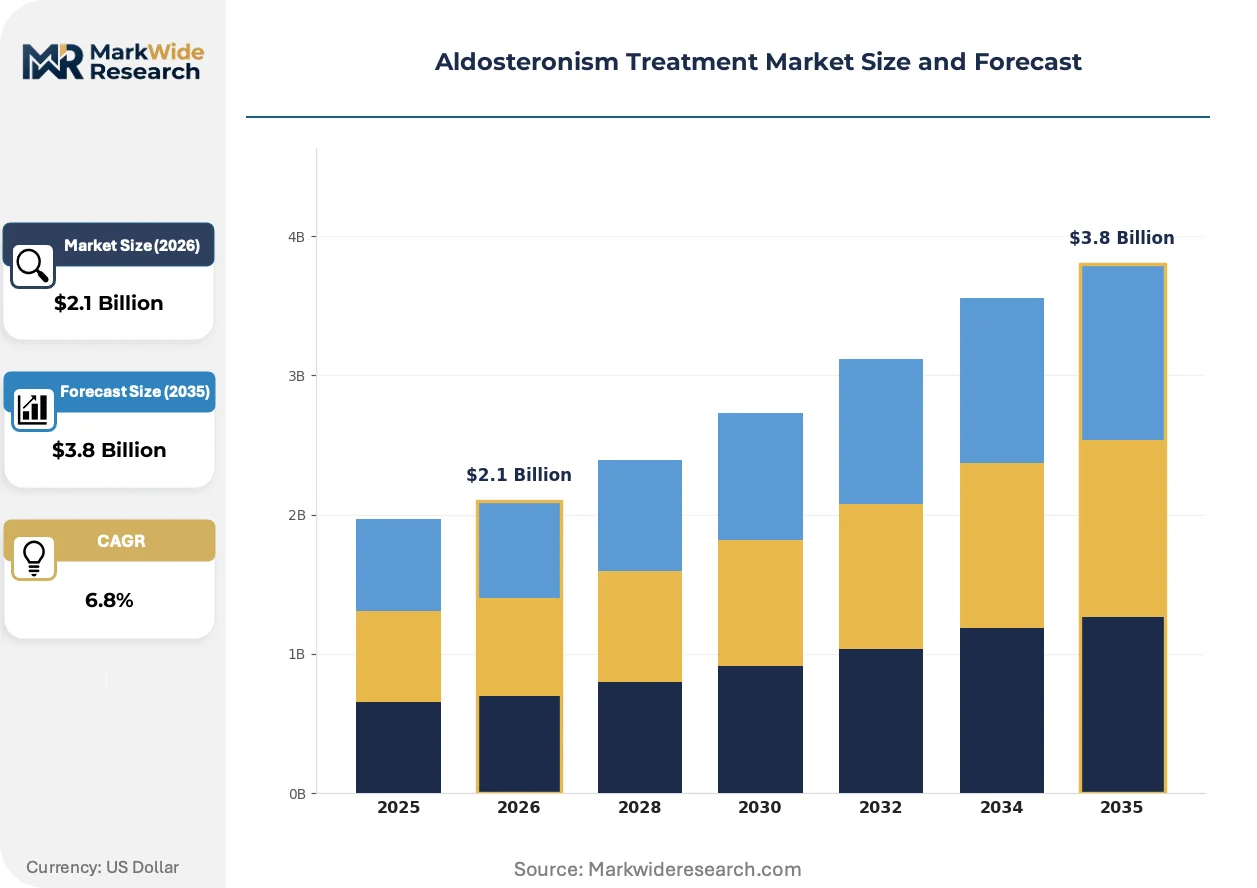
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antihypertensives, Diuretics, Beta Blockers, ACE Inhibitors Therapy Area: Hypertension, Heart Failure, Organ Transplant, Hypokalaemia Delivery Mode: Oral, Intravenous, Subcutaneous, Transdermal End User: Hospitals, Clinics, Home Care, Specialty Pharmacies |
| Companies Covered | Pfizer Inc., Novartis AG, Teva Pharmaceutical Industries Ltd., Viatris Inc., Accord Healthcare, Bayer AG, CMP Pharma, Sun Pharmaceutical Industries Ltd., Merck & Co., Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aldosteronism Treatment Market Strategic Shifts
Mineralocorticoid receptor antagonist development is pivoting toward tissue-selective compounds that preserve renal protection while dissociating from electrolyte disturbance liabilities.
Biomarker-guided patient stratification is unifying aldosterone-to-renin ratio thresholds with machine learning-derived cardiovascular risk scores in hypertensive screening protocols. Kaiser Permanente and Mayo Clinic systems are piloting automated laboratory reflex algorithms that trigger endocrinology referral without primary care gatekeeping. This convergence is compressing the diagnostic interval from suspicion to confirmation and accelerating surgical candidacy identification.
The EU Medical Device Regulation's post-market surveillance requirements are mandating extended follow-up for adrenal vein catheterization devices used in lateralization procedures. Manufacturers must now submit periodic safety update reports and real-world performance data to notified bodies. Interventional radiology device sponsors are responding by embedding radio-opaque marker technologies that enable procedural outcome tracking across European hospital networks.
Accountable care organizations in the United States are bundling hypertension management payments that reward aldosteronism case-finding in resistant populations. Cleveland Clinic and Geisinger Health are restructuring specialist referral incentives to prioritize confirmatory testing over empiric spironolactone initiation. This payment model rotation is most visible in Medicare Advantage contracts where capitated budgets align diagnostic expenditure with downstream cardiovascular event avoidance.
Aldosteronism Treatment Market Segmentation
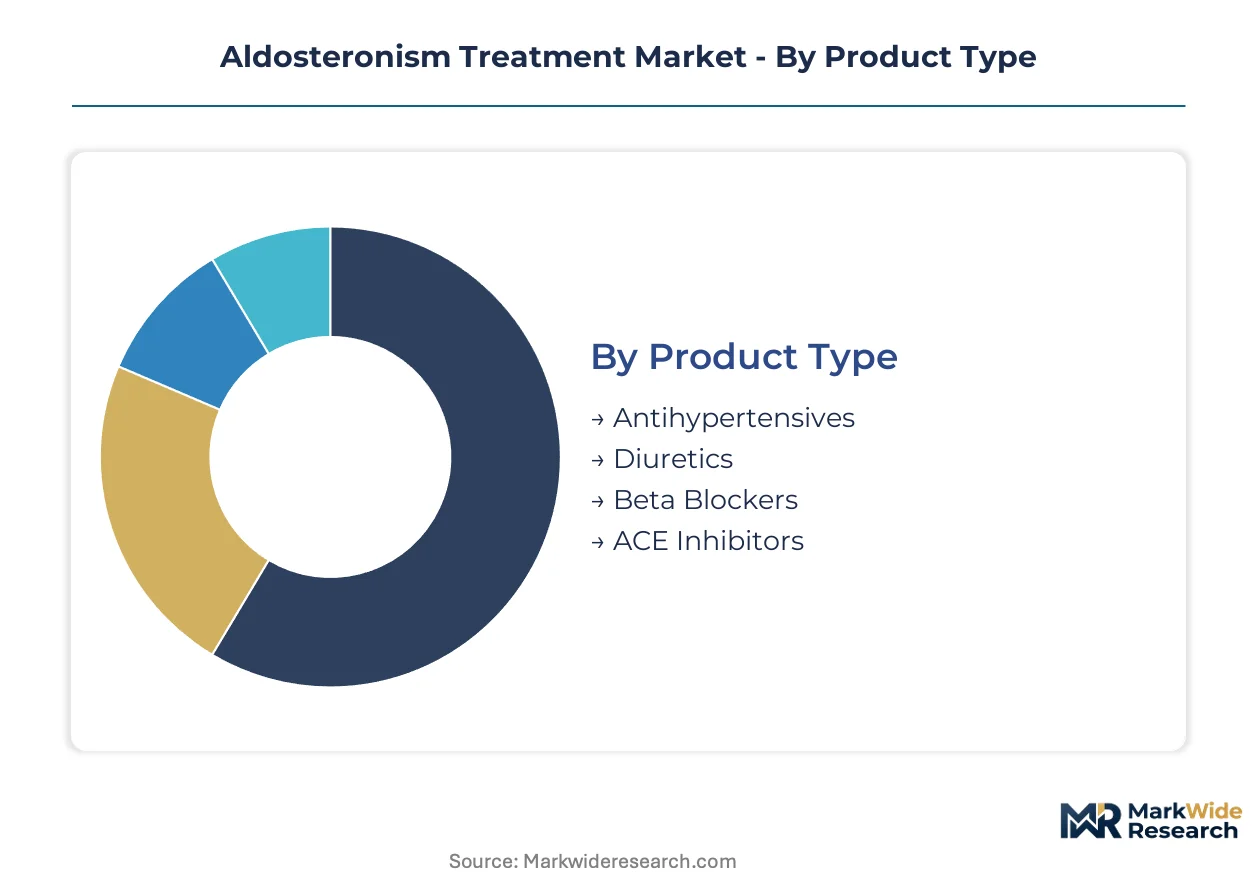
Segmentation in aldosteronism treatment reveals how prescribing authority, reimbursement pathways, and patient acuity reshape competitive access. Manufacturers must align formulation strategies with institutional procurement hierarchies and ambulatory care expansion.
Product Type:
Supply concentration in active pharmaceutical ingredient synthesis determines which therapeutic classes achieve consistent availability across hospital formularies.
- Antihypertensives:Mineralocorticoid receptor antagonists such as spironolactone and eplerenone constitute the pharmacological backbone of aldosteronism management. Tertiary care hospitals in the United States and Germany concentrate demand as resistant hypertension protocols mandate first-line antagonist therapy before surgical referral.
- Diuretics:Potassium-sparing diuretics complement mineralocorticoid blockade in patients with pronounced sodium retention. Japanese prefectural hospital systems are expanding diuretic co-prescription as the PMDA aligns hypertension guidelines with primary aldosteronism detection protocols.
- Beta Blockers:Cardioselective agents manage reflex tachycardia in patients initiating mineralocorticoid antagonist therapy.
- ACE Inhibitors:Renin-angiotensin system modulators address concurrent essential hypertension in secondary aldosteronism presentations.
Today's leader: Antihypertensives. Tomorrow's challenger: Diuretics.
Therapy Area:
Application-specific outcome requirements are fragmenting clinical trial investment and label expansion priorities across cardiovascular subspecialties.
- Hypertension:Resistant hypertension commands the largest patient volume as endocrinology clinics expand screening for primary aldosteronism in patients failing three-drug regimens. Kaiser Permanente and Mayo Clinic systems are piloting automated laboratory reflex algorithms that compress diagnostic intervals.
- Heart Failure:Cardiologists are adopting earlier mineralocorticoid antagonism in reduced ejection fraction populations. Cleveland Clinic and Geisinger Health are restructuring specialist referral incentives to prioritize confirmatory testing over empiric initiation in this segment.
- Organ Transplant:Immunosuppression-induced hypertension in renal transplant recipients creates specialized demand for potassium-sparing regimens.
- Hypokalaemia:Severe potassium depletion secondary to aldosterone excess requires urgent mineralocorticoid blockade in acute hospital settings.
Hypertension retains volume dominance. Heart failure is climbing the fastest as outcome-based contracts reward cardiovascular event avoidance.
Delivery Mode:
Margin capture varies sharply by administration setting, with acute care formulations commanding premium pricing against commoditized oral generics.
- Oral:Tablet and suspension formulations dominate prescribing patterns due to patient compliance advantages in chronic management. Primary care networks across the United States favor oral initiation before specialty referral.
- Intravenous:Hospital-only formulations capture critical margin pools in acute decompensated heart failure and severe hypokalemia. Tertiary care centers with dedicated adrenal disorder centers concentrate demand.
- Subcutaneous:Emerging depot formulations target non-adherent populations in longitudinal hypertension management.
- Transdermal:Patch-based delivery remains investigational for mineralocorticoid receptor antagonists with limited commercial penetration.
Oral formulations anchor volume. Intravenous delivery holds the steepest expansion trajectory as hospital bundling incentives align.
End User:
Procurement authority is shifting toward integrated delivery networks that centralize formulary decisions across previously autonomous care sites.
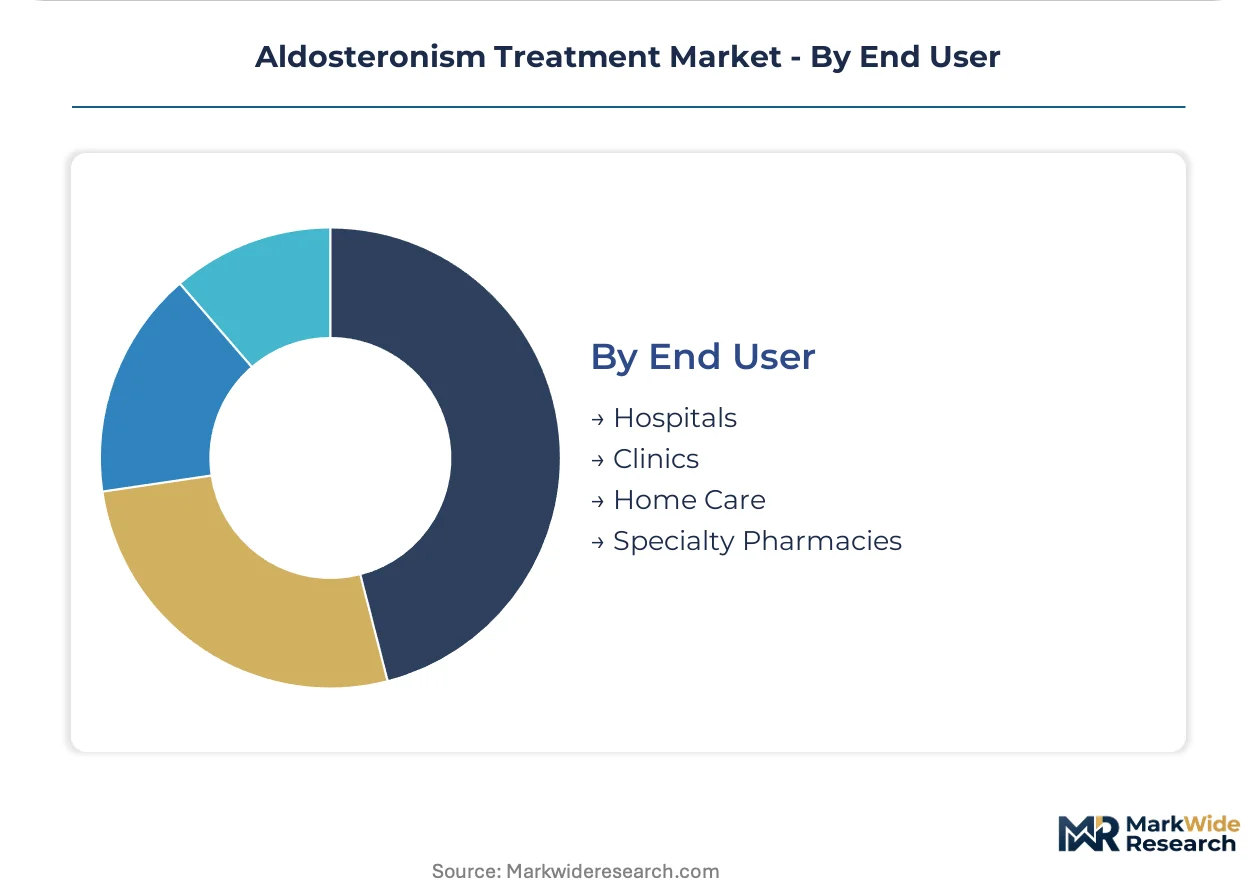
- Hospitals:Tertiary centers with interventional radiology capabilities and endocrine surgery programs control the diagnostic and surgical pathway for unilateral aldosterone-producing adenoma. Academic medical centers in the United States, Germany, and Japan concentrate adrenalectomy-capable subspecialists.
- Clinics:Endocrinology clinics are expanding mineralocorticoid receptor antagonist protocols as resistant hypertension screening intensifies. EU MDR harmonization is standardizing diagnostic requirements across European member states.
- Home Care:Post-surgical monitoring and chronic oral therapy management are migrating to home-based nursing services.
- Specialty Pharmacies:Limited distribution networks handle high-cost mineralocorticoid receptor modulators in development pipelines.
Hospitals control the high-acuity pathway. Clinics are gaining share fastest as telemedicine endocrinology extends specialist reach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Endocrine surgeon density and interventional radiology training capacity anchor geographic demand distribution for aldosteronism treatment pathways.
United States
Tertiary care hospitals with dedicated adrenal disorder centers concentrate diagnostic and surgical capacity for unilateral aldosterone-producing adenoma. The FDA's accelerated approval pathways for cardiovascular therapies compress mineralocorticoid receptor antagonist label expansion timelines. Mayo Clinic and Cleveland Clinic systems pilot automated laboratory reflex algorithms that trigger endocrinology referral without primary care gatekeeping.
Germany
Academic medical centers in Bavaria and North Rhine-Westphalia anchor adrenalectomy-capable surgical subspecialist pools. The EU Medical Device Regulation standardizes adrenal venous sampling device requirements across member states, reducing diagnostic workflow fragmentation. Heidelberg and Munich hospital networks are expanding mineralocorticoid receptor antagonist protocols for resistant hypertension populations.
Japan
Prefectural hospital systems concentrate demand as the PMDA aligns hypertension guidelines with primary aldosteronism detection protocols. The PMDA evaluates cardiovascular drug submissions with evolving bioequivalence requirements for generic mineralocorticoid receptor antagonists. Tokyo and Osaka metropolitan corridors host the interventional radiology suites adopting computed tomography-guided catheter placement systems.
United Kingdom
NHS England's specialized commissioning frameworks concentrate adrenal disorder referrals to designated tertiary centers. The EMA coordinates centralized marketing authorization for novel mineralocorticoid receptor modulators across European member states. London and Manchester academic medical centers are restructuring specialist referral incentives to prioritize confirmatory testing over empiric spironolactone initiation.
India
Growing endocrinology clinic networks in Maharashtra and Karnataka expand resistant hypertension screening capacity. The CDSCO oversees new drug approvals for mineralocorticoid receptor antagonist formulations with pharmacovigilance obligations shaping competitive positioning. Mumbai and Bangalore hospital systems are piloting telemedicine endocrinology channels that extend specialist reach to underserved patient populations.
Aldosteronism Treatment Market Competitive Environment
The competitive structure tilts toward diversified pharmaceutical conglomerates with established cardiovascular portfolios. Market concentration reflects regulatory barrier height for generic mineralocorticoid receptor antagonist entry and API manufacturing scale requirements. Three archetypes dominate: research-intensive innovators with specialized R&D programs, manufacturing-scale incumbents with captive API supply, and generic formulation specialists with distribution breadth. Capacity expansion and strategic portfolio diversification represent the dominant competitive moves as sponsors front-load real-world evidence collection for label expansions.
Among research-intensive innovators, Pfizer Inc. and Novartis AG exemplify archetypes anchored in cardiovascular outcome trial investment and resistant hypertension endpoint targeting. Bayer AG occupies a position representing manufacturing-scale incumbency with consistent API availability for spironolactone formulations. These three entities collectively illustrate how regulatory compliance burden and therapeutic specialization stratify competitive positioning in mineralocorticoid receptor antagonist markets.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Novartis AG |
| Teva Pharmaceutical Industries Ltd. |
| Viatris Inc. |
| Accord Healthcare |
| Bayer AG |
| CMP Pharma |
| Sun Pharmaceutical Industries Ltd. |
| Merck & Co., Inc. |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap API manufacturers in India and China anchor spironolactone supply, translating concentrated ownership into pricing discipline that resists commoditization despite generic formulation saturation in Western markets. Their captive control over key synthetic intermediates creates asymmetric bargaining power against multinational formulation sponsors seeking volume commitments.
Pricing Analysis
Bundled diagnostic-therapeutic pathways command premium capture in tertiary adrenal centers, while unbundled oral generic prescribing competes on procurement efficiency. Three-tier pricing structure across premium intravenous hospital formulations, standard oral tablets, and economy generic spironolactone segments stratifies buyer access. Pricing pressure stems from Medicare Advantage capitation models that compress diagnostic reimbursement margins. Primary care networks exhibit highest price sensitivity, whereas academic medical centers prioritize clinical outcome guarantees over unit cost.
Supply Chain Analysis
EMA and FDA bioequivalence certifications gate API supplier qualification, filtering active pharmaceutical ingredient access to a narrow tier of audited manufacturers. Spironolactone API synthesis concentrates in Chinese chemical clusters and Indian pharmaceutical zones, with potassium canrenoate intermediates sourced from specialized European facilities. Supply chain risk centers on tariff exposure from US-China trade policy volatility affecting import chemistry. Distribution runs through hospital GPO contracts and specialty pharmacy limited networks for investigational mineralocorticoid receptor modulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage opportunities concentrate in Japanese prefectural systems, where PMDA guideline evolution lags US and European diagnostic penetration by several cost-adjusted years, enabling platform vendors to replicate proven referral network architectures at lower regulatory compliance burden.
For Market Incumbents: Acquire interventional radiology training program assets to secure adrenal venous sampling specialist pipelines against contracting US fellowship exposure. Consolidate backward integration into potassium canrenoate intermediate production to buffer Chinese API tariff volatility. Pfizer and Novaritis archetypes should lock long-term offtake agreements with Indian family-owned API houses before generic formulation sponsors bid up capacity.
For New Entrants and Emerging Players: Non-steroidal mineralocorticoid receptor modulator platforms offer technology-first wedge into the gynecomastia-limited patient segment that discontinues spironolactone therapy. Target Japanese prefectural hospital systems as the most penetrable geography, where PMDA hypertension guideline alignment creates whitespace for diagnostic platform vendors. Deploy telemedicine endocrinology channels as the go-to-market angle to bypass specialist scarcity barriers in rural US corridors.
For Investors and Strategic Acquirers: Valuations sit cheapest among EU MDR-compliant diagnostic device manufacturers facing extended post-market surveillance cost burdens that strain mid-cap balance sheets. Five-to-ten year viability favors sponsors with cardiovascular outcome trial data packages that satisfy EMA and FDA label expansion requirements. Watch PMDA diagnostic reimbursement decisions as the inflection signal for Japanese market entry timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Adrenal Venous Sampling Automation | CT-guided catheter placement systems reduce operator variability in Heidelberg and Munich hospital networks. |
| Non-Steroidal Antagonist Development | Selective mineralocorticoid receptor modulators target the discontinuation-prone gynecomastia patient segment. |
| Telemedicine Endocrinology Expansion | Virtual specialist platforms penetrate rural US markets distant from tertiary adrenal centers. |
| EU MDR Diagnostic Harmonization | Standardized adrenal disorder screening workflows enable cross-border patient referral networks. |
| Real-World Evidence Collection | Front-loaded pharmacovigilance data satisfies FDA accelerated approval pathway requirements. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with endocrinology clinic directors, interventional radiologists, hospital formulary managers, and pharmaceutical regulatory affairs leads with secondary validation against FDA filings, EMA centralized marketing authorization records, ClinicalTrials.gov cardiovascular outcome trial databases, and Japanese PMDA hypertension guideline documentation. Bottom-up patient volume modeling and top-down pharmaceutical market sizing triangulated segment-level demand estimates.
Segment-weighting approaches distributed value across antihypertensive, diuretic, beta-blocker, and ACE inhibitor product categories, with therapy area splits between hypertension, heart failure, organ transplant, and hypokalaemia applications further refined by delivery mode and end-user channel. CAGRs derived from regression analysis of historical prescription volume trends and regulatory approval timelines across the projection horizon, incorporating mineralocorticoid receptor antagonist label expansion scenarios and adrenal venous sampling procedural growth curves as industry-specific forecast inputs.
The model holds under stable FDA and EMA regulatory frameworks; deviation in PMDA reimbursement policy or EU MDR enforcement intensity would shift Japanese and European demand trajectories. Forecasts reflect documented assumptions regarding resistant hypertension screening protocol adoption and generic formulation sponsor entry timing. A model refresh is warranted upon material change in interventional radiology fellowship training pipeline output or API import tariff regime structure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Primary Sclerosing Cholangitis (PSC) Market
Specialty Medicine
Bronchiectasis Market
Specialty Medicine
Hypersensitivity Pneumonitis Market
Specialty Medicine
Paronychia Treatment Market
Specialty Medicine
Psychedelic Medicine Market
Specialty Medicine
Genital Warts (Condyloma Acuminatum) Market
Specialty Medicine
Hashimoto's Thyroiditis Therapeutics Market
Specialty Medicine
Global Amyotrophic Lateral Sclerosis (ALS) Treatment Market
Specialty Medicine
Acute Intermittent Porphyria Market
Specialty Medicine
Ulcerative Colitis Therapeutics Market
Specialty Medicine
Epidermal Nevus Syndrome Market
Specialty Medicine
Rhabdomyosarcoma Treatment Market
Specialty Medicine
Gallbladder Cancer Therapeutics Market
Specialty Medicine
Malabsorption Syndrome Market
Specialty Medicine
Lateral Epicondylitis (Tennis Elbow) Treatment Market
Specialty Medicine
Necrotizing Fasciitis Market